
 Electric Tuk-Tuks Market | 2026-2036
Electric Tuk-Tuks Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Tuk-Tuks Market Analysis
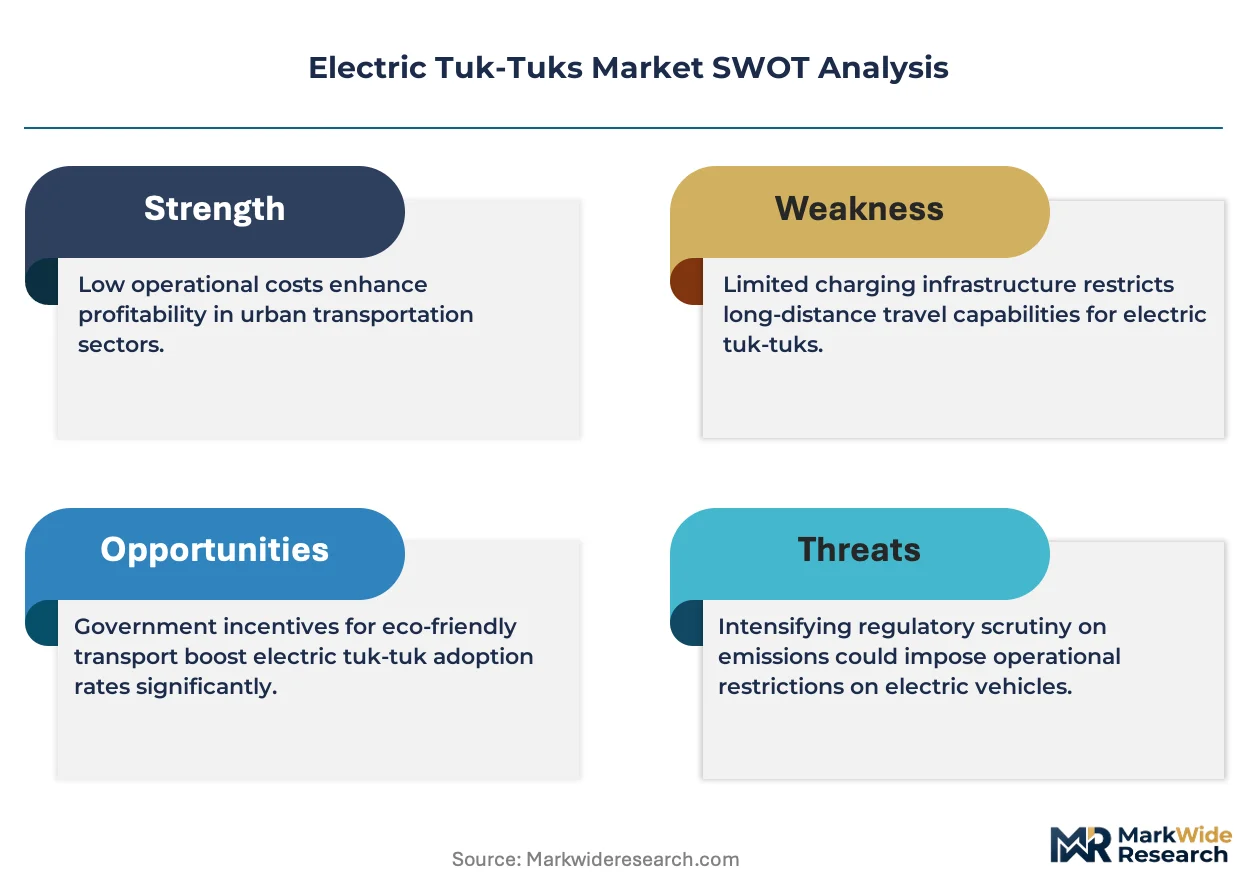
High-voltage lithium-ion configurations is reorganizing competitive dynamics across the electric tuk-tuk sector. Kinetic Green Vehicles Ltd leverages in-house battery pack assembly to control cost curves in the Indian market. Mahindra Electric Mobility Ltd anchors its position through captive motor manufacturing and extensive dealership networks. Piaggio & C. SpA competes on European design standards, exporting premium chassis architectures to Southeast Asian assemblers.
An electric tuk-tuk is a three-wheeled battery-powered vehicle with a typical 48V to 72V drivetrain, hub-mounted or mid-drive motor, and steel-tube chassis designed for 4-6 passenger capacity or 500kg cargo loads in dense urban environments. Battery electric technology dominates unit shipments while hybrid configurations retain share in charging-infrastructure-deficient zones. Cargo variants capture expanding margin pools as e-commerce last-mile operators specify reinforced suspensions and modular load beds. Luxury configurations with enclosed cabins and HVAC systems command premium pricing in tourist applications across Thai and Sri Lankan resort corridors.
India's Ministry of Road Transport and Highways enforces AIS-154 safety standards for electric three-wheelers, while Bangladesh's BRTA mandates type-approval for imported powertrains, shaping product homologation strategies. The EU's F-Gas Regulation indirectly pressures thermal management system choices for exported European units. Stakeholders must monitor how India's PLI scheme phase transitions affect component localization requirements versus import dependency for lithium cells.
Market Dynamics
High-voltage lithium-ion architectures are compressing cost curves faster than incumbent lead-acid systems can respond, forcing a platform reset across vehicle assemblers and battery suppliers alike.
Growth Catalysts
- India's PLI scheme:Production-linked incentives for electric mobility are accelerating domestic cell-to-pack manufacturing capacity, reducing import dependency for lithium-ion configurations.
- Last-mile delivery electrification:E-commerce logistics operators in Bangladesh's Dhaka-Chittagong corridor are specifying reinforced cargo variants with modular load beds for fleet standardization.
- Hub-mounted motor adoption:Simplified drivetrain architectures eliminate transmission losses and reduce maintenance intervals for high-utilization commercial operators.
Market Restraints
- Lithium cell supply concentration:Cathode active material processing capacity clusters in China, exposing assemblers to export control volatility and freight cost spikes.
- Charging infrastructure gaps:Grid reinforcement lags vehicle deployment in peri-urban Sri Lankan and Nepalese corridors, constraining range confidence for inter-city routes.
- Lead-acid residual economics:Lower upfront acquisition costs for flooded battery configurations sustain demand in informal financing environments with high discount rates.
Strategic Opportunities
- Battery swapping networks:Station-based exchange infrastructure addresses dwell-time constraints for commercial fleets operating on fixed routes in dense Indian urban cores.
- Tourism luxury configurations:Enclosed cabins with HVAC systems command premium pricing in Thai and Sri Lankan resort corridors where visitor experience differentiation drives selection.
- EU F-Gas Regulation alignment:Thermal management system redesign for exported European units opens compliance-driven premium segments with stricter refrigerant protocols.
Industry Challenges
- AIS-154 homologation timelines:India's safety certification process for electric three-wheelers creates product launch delays for new market entrants lacking established testing relationships.
- Power electronics skill scarcity:Motor controller calibration and battery management system programming expertise concentrates in Tier-1 automotive hubs, constraining regional assembler technical autonomy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Tuk-Tuks Market |
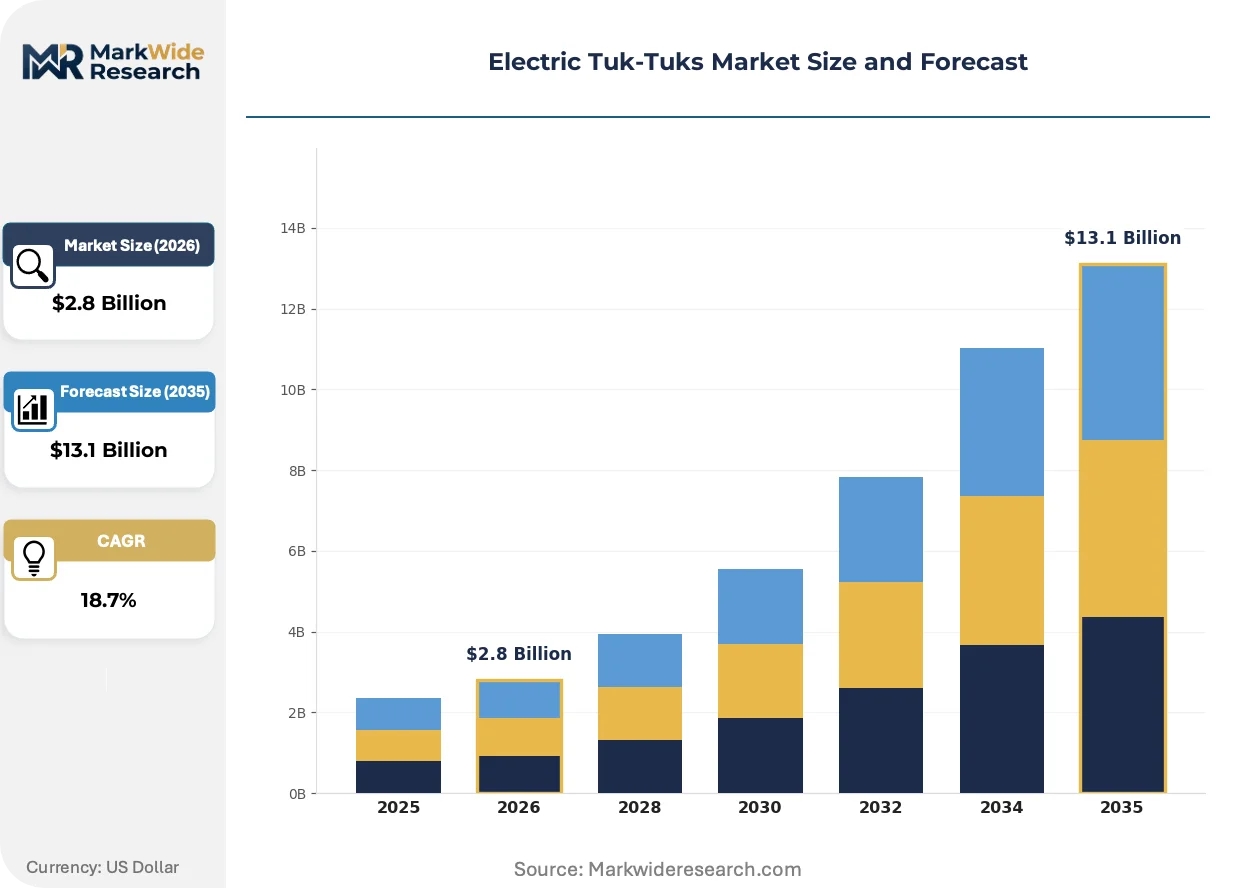
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13.1 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard, Luxury, Cargo, Convertible End User: Tourists, Local Transport, E-Commerce, Delivery Services Technology: Battery Electric, Hybrid, Fuel Cell, Solar Distribution Channel: Online, Dealerships, Direct Sales, Exporters |
| Companies Covered | Kinetic Green Vehicles Ltd, Daehan Auto Rickshaw, Mahindra Electric Mobility Ltd, E-Tuk Factory, Lohia Auto Industries Ltd, eTuk USA, Piaggio & C. SpA, Henan Niegui Import and Export Trade Co., Ltd, Ampere Vehicles, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Tuk-Tuks Market Emerging Trajectories
Electrification is forcing a component architecture reset across the three-wheeler value chain, with implications for thermal management, chassis design, and service infrastructure.
Silicon carbide power modules are replacing IGBT-based motor controllers in high-voltage drivetrains. Fleet operators in Bangladesh and India are specifying SiC-equipped variants for improved efficiency at sustained high loads. The technology is miniaturizing inverter packaging, freeing chassis space for battery volume expansion or cargo bay enlargement.
India's Ministry of Road Transport and Highways is tightening enforcement of AIS-154 crashworthiness and electromagnetic compatibility standards. Component suppliers must redesign battery enclosures and wiring harnesses to meet penetration resistance thresholds. Passenger-carrying variants face the steepest compliance cost increases, accelerating segmentation between certified and informal market vehicles.
Commercial fleet procurement is consolidating around total-cost-of-ownership models that internalize battery degradation and residual value risk. Aggregator platforms in Indian metro corridors are displacing individual owner-operator acquisition with lease-to-own structures bundled with maintenance and charging access. This shift concentrates purchasing power among logistics intermediaries and reduces price sensitivity to upfront vehicle cost.
Electric Tuk-Tuks Market Segmentation
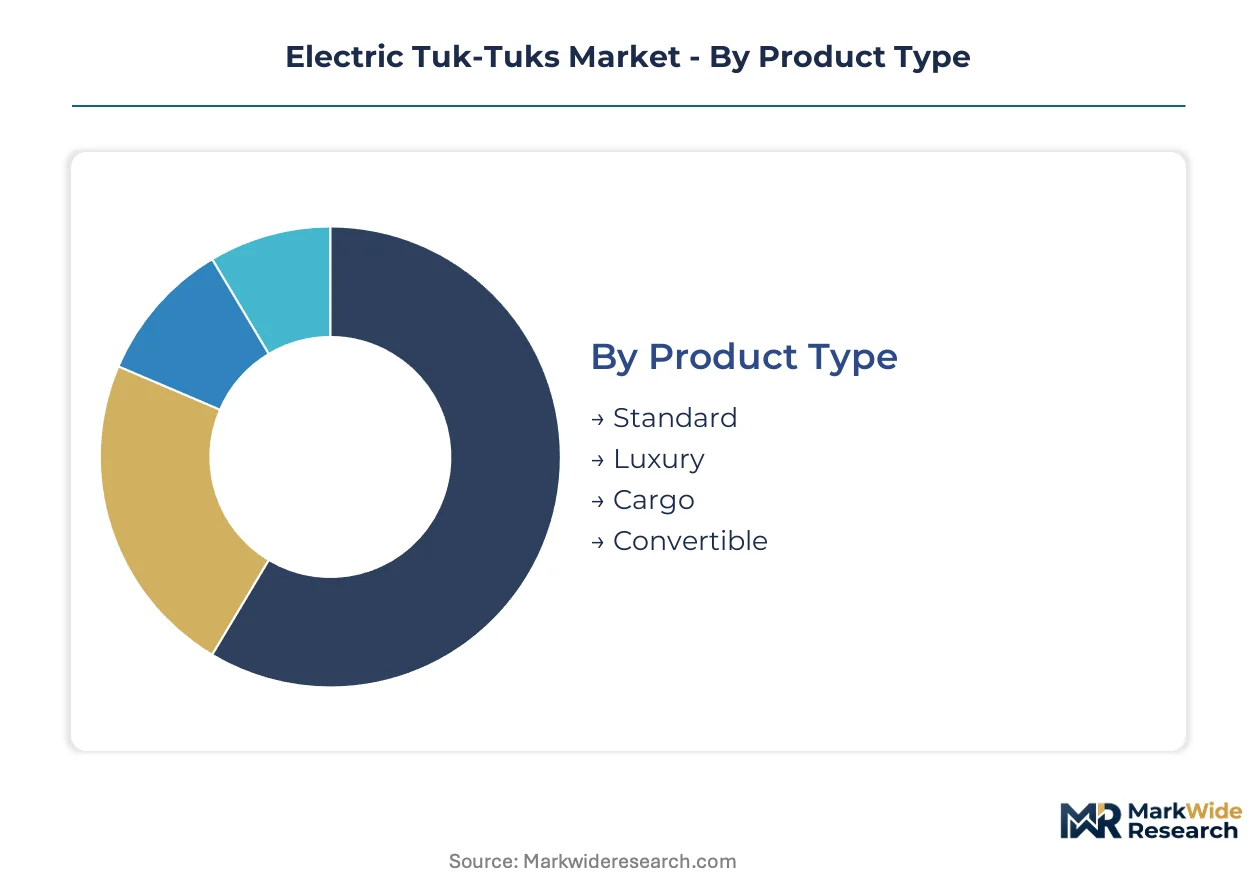
Segmentation in the electric tuk-tuk sector separates vehicles with fundamentally different regulatory footprints, cost structures, and operational economics. Product type and technology choices determine which safety standards apply, while end-user concentration shapes fleet procurement patterns across South Asian corridors.
Product Type:
India's AIS-154 safety standards create tiered compliance burdens that segment the market by structural reinforcement requirements and crashworthiness testing intensity.
- Standard:Open-frame steel-tube chassis with basic weather protection and 48V drivetrains dominate owner-operator acquisition in Bangladesh's informal transport sector. Dhaka-Chittagong corridor fleet aggregators specify these units for maximum passenger throughput on fixed urban routes.
- Cargo:Reinforced suspensions and modular load beds with 500kg rated capacity address last-mile delivery electrification. E-commerce logistics operators in Indian metro corridors prioritize these variants for total-cost-of-ownership optimization across high-utilization duty cycles.
- Luxury:Enclosed cabins with HVAC systems and upgraded seating configurations target tourist applications in Thai and Sri Lankan resort corridors.
- Convertible:Removable roof panels and configurable seating arrangements serve seasonal demand fluctuations in coastal Indian states.
Standard configurations handle the majority of throughput; Cargo is the fastest mover on share.
End User:
Procurement patterns diverge sharply between individual owner-operators with high discount rates and institutional fleet managers optimizing for residual value.
- E-Commerce:Logistics aggregators in Bangladesh and India deploy lease-to-own structures bundling maintenance and charging access. These operators specify reinforced cargo variants with telematics integration for route optimization and battery health monitoring.
- Local Transport:Owner-operators in peri-urban Sri Lankan and Nepalese corridors favor lead-acid configurations for lower upfront acquisition costs despite shorter cycle life.
- Tourists:Resort operators in Thai and Sri Lankan coastal zones specify luxury enclosed cabins with premium finishing and air conditioning.
- Delivery Services:Quick-commerce platforms in Indian urban cores prioritize battery-swappable variants for minimized dwell time.
E-Commerce channels concentrate the highest per-unit procurement volumes; Delivery Services is climbing the fastest on share.
Technology:
Powertrain architecture determines thermal management complexity and supply chain exposure to lithium cell processing concentration.
- Battery Electric:High-voltage lithium-ion configurations with 48V to 72V drivetrains and hub-mounted motors dominate unit shipments. Fleet operators specify silicon carbide power modules for efficiency gains at sustained high loads.
- Hybrid:Range-extender configurations with small displacement generators retain share in charging-infrastructure-deficient zones across peri-urban Nepal and Sri Lanka.
- Fuel Cell:Proton exchange membrane systems with compressed hydrogen storage remain pre-commercial for three-wheeler duty cycles.
- Solar:Roof-integrated photovoltaic panels supplement auxiliary loads in extended-idle tourist applications.
Battery Electric carries the dominant technology share; Hybrid is gaining share fastest where grid reinforcement lags deployment.
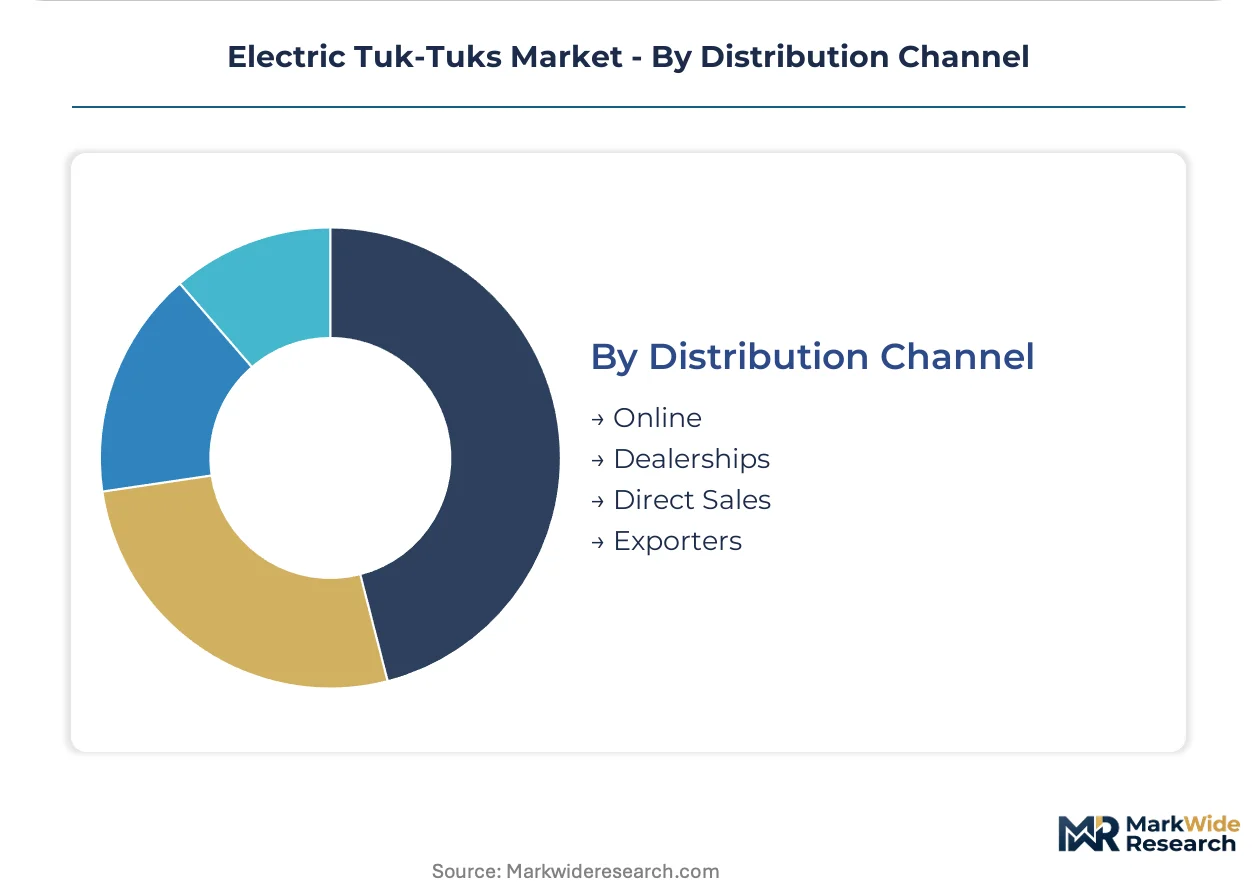
Distribution Channel:
Channel selection reflects customer financing sophistication and service infrastructure requirements for battery maintenance and thermal system calibration.
- Dealerships:Mahindra Electric Mobility Ltd and Kinetic Green Vehicles Ltd anchor extensive physical networks across Indian states for test-ride access and post-sale service.
- Direct Sales:Fleet aggregators in Bangladesh's Dhaka-Chittagong corridor negotiate volume contracts with assemblers for standardized cargo variants.
- Online:Digital platforms with financing integration serve first-time buyers in Tier-2 and Tier-3 Indian cities.
- Exporters:Piaggio & C. SpA channels European-designed chassis architectures to Southeast Asian assemblers for local powertrain integration.
Dealerships handle the majority of unit throughput; Direct Sales is expanding most quickly on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across South Asian corridors. Bangladesh's informal transport sector prioritizes lowest acquisition cost, while Indian fleet aggregators optimize total-cost-of-ownership over multi-year horizons. Thai resort operators demonstrate least price elasticity, specifying premium configurations for tourist experience differentiation.
India
Fleet aggregators in Mumbai, Bangalore, and Delhi-NCR corridors are consolidating procurement around lease-to-own structures bundled with maintenance and charging access. The Ministry of Road Transport and Highways enforces AIS-154 safety standards for electric three-wheelers, tightening crashworthiness and electromagnetic compatibility requirements. Manufacturing clusters in Maharashtra and Gujarat are scaling domestic cell-to-pack assembly capacity under the PLI scheme for electric mobility.
Bangladesh
Informal transport electrification is scaling fastest in the Dhaka-Chittagong corridor where owner-operators convert diesel fleets to electric variants for fuel cost arbitrage. The Bangladesh Road Transport Authority mandates type-approval for imported powertrains, shaping product homologation strategies for regional assemblers. Fleet standardization is concentrating demand in Dhaka's urban core where e-commerce logistics operators specify reinforced cargo variants with modular load beds.
Thailand
Resort operators in Phuket, Pattaya, and Chiang Mai corridors specify luxury enclosed cabins with HVAC systems for tourist transport applications. The country's national automotive regulator enforces safety certification for commercial passenger vehicles, differentiating certified units from informal market alternatives. Manufacturing activity clusters in Bangkok's peripheral industrial zones where assemblers integrate European-designed chassis architectures with local powertrain specifications.
Sri Lanka
Peri-urban corridors around Colombo and Kandy face charging infrastructure gaps that constrain range confidence for inter-city routes. The national transport authority oversees vehicle registration and safety compliance, though enforcement intensity varies across provincial jurisdictions. Grid reinforcement lags vehicle deployment in Galle and Jaffna sub-regions, sustaining hybrid configuration demand where battery electric range proves insufficient.
Nepal
High-discount-rate financing environments in Kathmandu and Pokhara corridors sustain lead-acid residual economics despite shorter cycle life. The national transport management authority regulates vehicle imports and safety standards, though informal assembly persists in border-adjacent zones. Charging infrastructure deficits across peri-urban Bagmati Province are forcing range-extender configurations for commercial operators serving inter-city routes.
Electric Tuk-Tuks Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the electric tuk-tuk sector. The vendor base separates into three tiers: integrated manufacturers with captive battery assembly, regional assemblers sourcing modular powertrains, and specialty exporters of premium chassis architectures. Consolidation is accelerating around production-linked incentive compliance in India, while fragmentation persists in Bangladesh's informal conversion market. Dominant competitive moves include backward integration into cell-to-pack manufacturing and geographic expansion through distributor network densification.
Among Indian integrated manufacturers, Kinetic Green Vehicles Ltd and Mahindra Electric Mobility Ltd exemplify the captive supply chain archetype, leveraging in-house component production to control cost curves and accelerate AIS-154 certification timelines. Piaggio & C. SpA occupies a position as the European design standard-bearer, exporting premium chassis architectures to Southeast Asian assemblers for local powertrain integration. These three anchors illustrate the strategic divergence between cost-optimized domestic production and compliance-driven premium export positioning.
| Leading Market Players |
|---|
| Kinetic Green Vehicles Ltd |
| Daehan Auto Rickshaw |
| Mahindra Electric Mobility Ltd |
| E-Tuk Factory |
| Lohia Auto Industries Ltd |
| eTuk USA |
| Piaggio & C. SpA |
| Henan Niegui Import and Export Trade Co., Ltd |
| Ampere Vehicles |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day lithium cell lead times from cathode active material processors compress pricing power for Indian assemblers lacking captive battery pack assembly, while Bangladeshi informal converters exploit spot-market lead-acid economics to undercut certified variants on upfront acquisition cost.
Pricing Analysis
After-sales service contracts and battery replacement subscriptions generate lifetime value multiples exceeding the original vehicle transaction. Three-tier pricing structure across premium, standard, and economy levels separates AIS-154-certified cargo variants from informal market open-frame units and luxury enclosed-cabin configurations. Cost compression in standard-tier configurations intensifies because fleet aggregators internalize total-cost-of-ownership calculations that discount residual value risk. Owner-operators in Bangladesh's Dhaka-Chittagong corridor exhibit highest price sensitivity, while Thai resort operators demonstrate least elasticity for HVAC-equipped tourist variants.
Supply Chain Analysis
Inventory cycles stretching across monsoon shipping windows concentrate cathode precursor exposure for assemblers without localized cell-to-pack capacity. Lithium cell processing clusters in China, cathode active material refining concentrates in Indonesia, and steel-tube chassis fabrication anchors in India. Raw material dependencies span lithium carbonate, nickel-manganese-cobalt cathode formulations, and electrical-grade silicon steel. Single-source vulnerability in hub-mounted motor controllers exposes assemblers to export control volatility. Distribution runs through Maharashtra and Gujarat manufacturing clusters into dealership networks and direct fleet contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery swapping platform interoperability is reshaping competitive boundaries, as aggregator-led fleet standardization creates winner-take-most dynamics across Indian metro corridors where charging access determines operational viability.
For Market Incumbents: Compound captive battery pack assembly advantages through PLI scheme compliance acceleration, while densifying service networks to capture aftermarket revenue streams threatened by third-party battery swapping operators. Anchor position through exclusive charging infrastructure partnerships that lock in fleet aggregator procurement decisions across Delhi-NCR and Mumbai logistics corridors. For New Entrants and Emerging Players: Battery management system calibration services represent an under-served technical layer where incumbent assemblers lack dedicated software engineering depth. Penetrate peri-urban Sri Lankan and Nepalese corridors where hybrid range-extender configurations retain operational relevance against charging infrastructure gaps. Deploy mobile service units bundled with financing to displace informal lead-acid conversion workshops. For Investors and Strategic Acquirers: Long-term, this sits as a platform-aggregation play because fleet procurement consolidation concentrates purchasing power among logistics intermediaries rather than fragmented owner-operators. Target cell-to-pack manufacturing specialists with AIS-154 certification relationships and established assembler offtake agreements. Monitor PLI scheme phase transition announcements as inflection indicators for domestic manufacturing capacity deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Swapping Network Deployment | Station-based exchange infrastructure addresses dwell-time constraints for quick-commerce operators in dense Indian urban cores. |
| Silicon Carbide Power Module Integration | SiC-equipped drivetrains improve efficiency at sustained high loads for Bangladeshi cargo fleet operators. |
| AIS-154 Certification Acceleration | Crashworthiness compliance separates certified passenger variants from informal market alternatives in Indian regulatory enforcement zones. |
| Hub-Mounted Motor Manufacturing | Simplified drivetrain architectures reduce maintenance intervals for high-utilization commercial operators across South Asian corridors. |
| Tourism Luxury Configuration Development | Enclosed cabins with HVAC systems capture premium pricing in Thai and Sri Lankan resort corridors. |
Methodological Framework
Operator-level perspectives from fleet aggregation platform executives, battery pack assembly plant managers, and informal conversion workshop proprietors anchored the qualitative base, cross-referenced with AIS-154 homologation filings, Bangladesh Road Transport Authority type-approval records, and PLI scheme beneficiary disclosures. Secondary validation drew from customs trade data on lithium cell imports, vehicle registration databases across Indian states, and e-commerce logistics operator procurement disclosures. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction across product type, technology, and end-user segmentation dimensions.
Sensitivity analysis around lithium cell price trajectories and charging infrastructure deployment rates framed the projection horizon. Segmentation modeling incorporated product type, technology architecture, end-user procurement pattern, and regional regulatory cluster dimensions. CAGRs derived from fitted growth curves calibrated to historical penetration rates and policy incentive intensity. Forecast inputs included fleet aggregator lease-to-own adoption curves and battery degradation cost internalization behaviors.
Underlying assumptions cover PLI scheme continuity, lithium cell import tariff stability, and grid reinforcement pacing, with deviation risk concentrated in export control measures affecting cathode precursor supply and informal market enforcement intensity variations. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Central and Eastern Europe E-Bike Market
Electric Vehicles
Electric Delivery Vans Market
Electric Vehicles
Oman EV Market
Electric Vehicles
Europe Electric Light Commercial Vehicles Market
Electric Vehicles
Electric Two-Wheeler Market
Electric Vehicles
Middle East and Africa Electric Vehicle Thermal Management System Market
Electric Vehicles
Electric Vehicle Power Control Unit Market
Electric Vehicles
Embedded System for Electric Vehicle Market
Electric Vehicles
North America Electric Vehicle Market
Electric Vehicles
ASEAN Countries Plug-In Hybrid Electric Vehicle Battery Market
Electric Vehicles
Commercial Vehicle Electric Propulsion System Market
Electric Vehicles
Global Smart Electric Drive Market
Electric Vehicles
Electric Vehicle Skateboard Chassis Market
Electric Vehicles
India E-Bike Market
Electric Vehicles
Automotive Battery Powered Propulsion System Market
Electric Vehicles
EV Condenser Market