
 Global Taxi Market | 2026-2036
Global Taxi Market Size, Share, and Industry Trends Forecast 2026-2036
Global Taxi Market Outlook
Driver supply shortages across major metropolitan zones are reorganizing fleet economics and accelerating platform investment in recruitment automation. Uber Technologies Inc. leverages its global network density to sustain pricing power in high-frequency corridors. DiDi Global Inc. anchors its operational model on AI-driven dispatch optimization. Grab Holdings Inc. differentiates through super-app integration spanning transport, delivery, and financial services.
A taxi constitutes a licensed, metered vehicle-for-hire service transporting passengers between defined points for regulated fares, typically operating through street hails, dispatch centers, or digital platforms with GPS-enabled routing and integrated payment systems. The service type segment reveals ride-sharing and taxi aggregator models capturing dominant volume share as traditional street-hail operations contract in mature markets. Technology segmentation shows mobile app-based booking and payment integration commanding the fastest expansion, while autonomous vehicles represent a nascent but capital-intensive frontier with concentrated testing in select North American and Chinese urban corridors.
The US Department of Transportation enforces vehicle safety standards through NHTSA while the EU F-Gas Regulation and GDPR constrain fleet composition and passenger data handling protocols across member states. India's Ministry of Road Transport and Highways governs city-specific permit regimes that determine platform market access in metropolitan jurisdictions. Stakeholders must monitor regulatory divergence between permissive and restrictive licensing frameworks as this tension determines where platform capital deploys most efficiently.
Market Dynamics
Fleet operators confront a structural pivot as driver supply constraints force capital reallocation toward autonomous vehicle development and recruitment automation infrastructure.
Growth Catalysts
- EU F-Gas Regulation:Stringent vehicle emission standards in member states accelerate corporate fleet electrification and aggregator platform adoption for compliant commuter services.
- AI-driven dispatch systems:Machine learning algorithms optimize vehicle positioning and reduce passenger wait times in high-density urban corridors.
- Urban India concentration:Metropolitan jurisdictions witness rapid displacement of street-hail services by app-based booking platforms with integrated payment systems.
Market Restraints
- Driver supply volatility:Labor pool contraction in major metropolitan zones elevates recruitment costs and compresses fleet utilization rates.
- Permit regime fragmentation:India's city-specific licensing frameworks create market access barriers and operational complexity for platform expansion.
- Autonomous vehicle capex intensity:Concentrated testing corridors in North America and China demand sustained R&D investment without near-term revenue offset.
Strategic Opportunities
- Super-app convergence:Integration of transport, delivery, and financial services creates sticky user ecosystems and cross-subsidization potential.
- GDPR-compliant data monetization:Passenger routing and payment data streams enable targeted advertising and insurance product distribution under regulated frameworks.
- Brazil urban corridors:Underpenetrated metropolitan markets present first-mover advantages for platform operators with localized payment and routing solutions.
Industry Challenges
- Legacy dispatch system integration:Traditional taxi cooperatives resist platform interoperability, fragmenting supply coordination and passenger experience.
- Certification timeline compression:Autonomous vehicle safety validation under NHTSA protocols extends deployment schedules and capital lock-up periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Taxi Market |
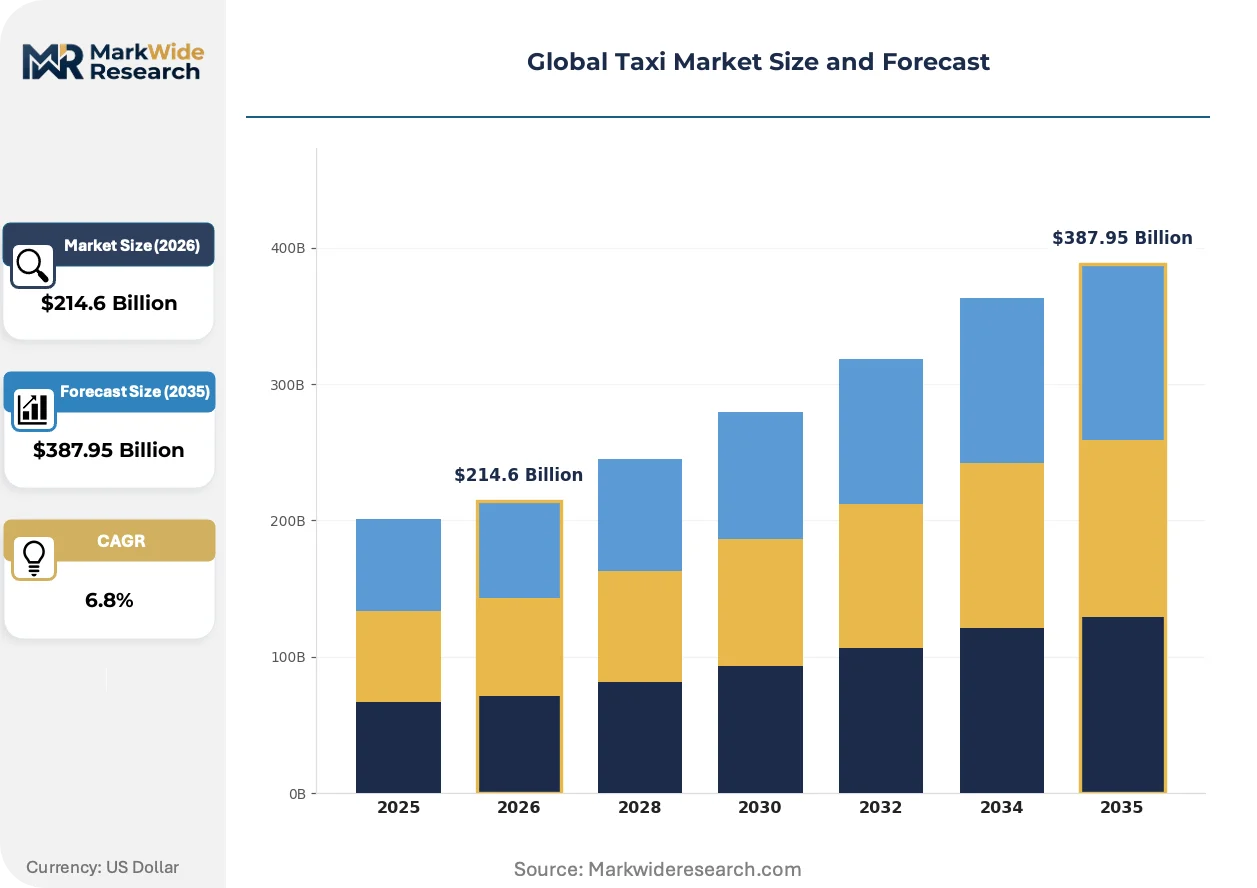
| Market Size in 2026 | $214.6 Billion |
| Market Size in 2035 | $387.95 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Traditional Taxi, Ride-Sharing, Taxi Aggregator, Luxury Taxi Technology: Mobile App-Based, GPS Tracking, Payment Integration, Autonomous Vehicles End User: Corporate, Individual, Tourist, Emergency Services Vehicle Type: Compact Cars, SUVs, Vans, Electric Vehicles |
| Companies Covered | Uber Technologies Inc., DiDi Global Inc., Grab Holdings Inc., Gojek, Ola Cabs, Bolt Technology, Lyft Inc., Yandex Go, FREE NOW, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Taxi Market Strategic Shifts
Digital infrastructure is fundamentally restructuring how vehicles are summoned, routed, and monetized across regulatory environments with divergent data governance standards.
Electric drivetrain technology is supplanting internal combustion engines in fleet procurement decisions. Municipal procurement officers and corporate travel managers specify zero-emission vehicle quotas in service contracts. This transition compresses total cost of ownership calculations and redirects maintenance revenue toward battery lifecycle management services.
REACH compliance requirements and EU AI Act provisions constrain algorithmic decision-making in passenger matching and dynamic pricing. Fleet operators must document automated system logic for regulatory audit trails. European platform subsidiaries face heightened compliance expenditure relative to permissive licensing jurisdictions.
Subscription-based mobility packages displace per-ride transactions among enterprise accounts. Human resources departments consolidate vendor relationships through annual committed spend agreements with guaranteed service levels. This pattern concentrates procurement leverage in Germany and the United Kingdom where corporate travel budgets centralize under fleet management departments.
Global Taxi Market Segmentation
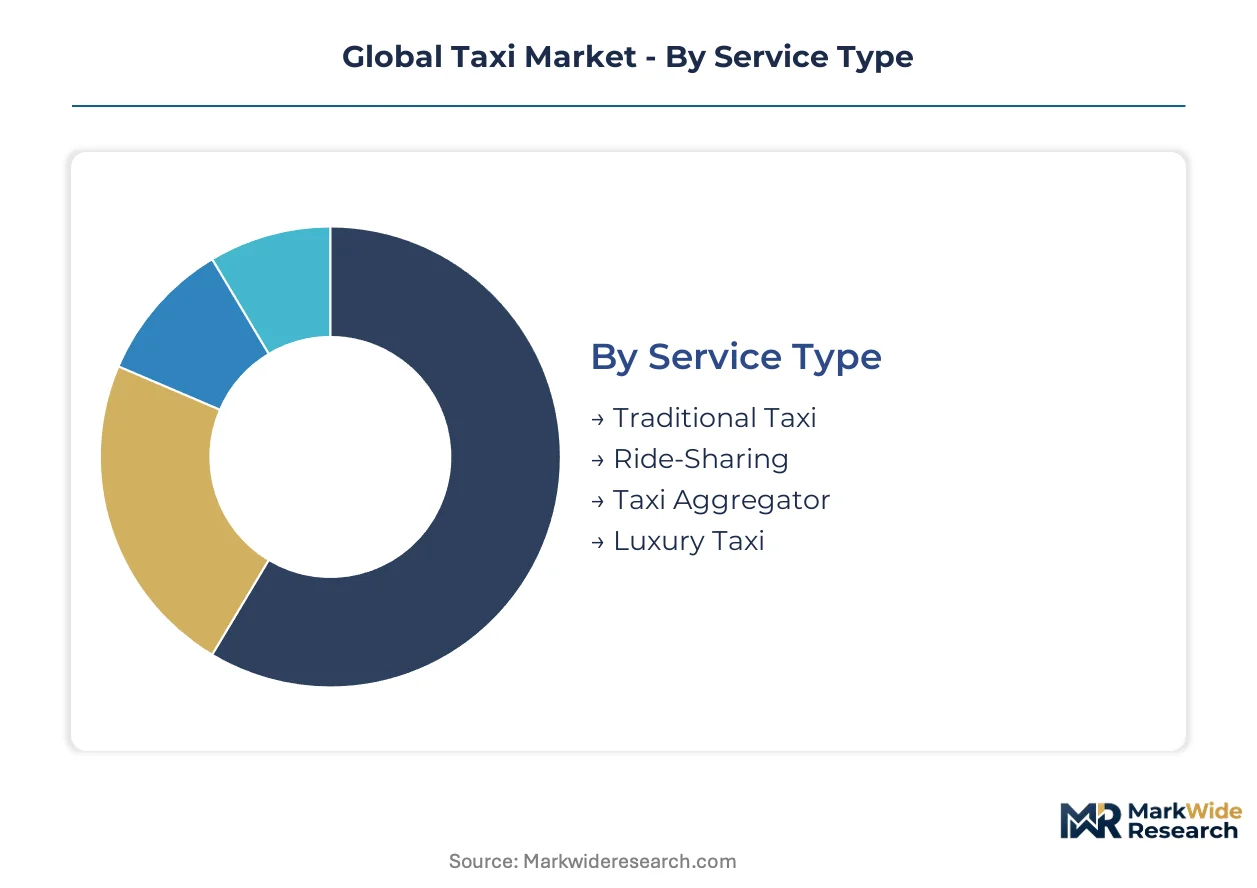
Segmentation reveals how capital and regulatory pressure distribute across operational models in the global taxi market. Fleet operators calibrate vehicle procurement and platform investment against distinct service tiers and technology readiness levels.
Service Type:
Ride-sharing and taxi aggregator models dominate cross-border platform expansion, while traditional street-hail services retain localized permit advantages in restrictive licensing jurisdictions.
- Traditional Taxi:Metered, licensed vehicles operating through street hails or dispatch centers with regulated fare structures. Demand concentrates in German and Japanese cities where cooperative licensing frameworks resist platform displacement and preserve driver income floors.
- Ride-Sharing:Peer-to-peer vehicle utilization connecting private drivers with passengers via digital platforms. Volume concentrates in Brazilian and Indonesian urban corridors where vehicle ownership costs and traffic congestion elevate driver supply elasticity.
- Taxi Aggregator:Platform-mediated access to licensed taxi fleets with centralized booking and payment systems. India's metropolitan permit regimes favor this hybrid model for regulatory compliance.
- Luxury Taxi:Premium vehicle specifications with trained chauffeurs targeting corporate travel and airport transfers. Corporate procurement departments in the United Kingdom and Switzerland specify these services under annual mobility contracts.
Taxi aggregator models hold the largest share; momentum sits with ride-sharing platforms expanding in underpenetrated metropolitan markets.
Technology:
Technology adoption stratifies by capital intensity, with software-layer investments scaling faster than hardware-dependent autonomous systems.
- Mobile App-Based:Smartphone interfaces for ride booking, driver tracking, and fare estimation. Indian and Southeast Asian platforms deploy lightweight applications optimized for variable network connectivity and prepaid payment instruments.
- GPS Tracking:Real-time vehicle positioning enabling route optimization and passenger safety monitoring. EU GDPR compliance requirements constrain data retention periods and cross-border transfer protocols for location histories.
- Payment Integration:In-app digital wallets, card tokenization, and split-fare functionality. Brazilian platforms prioritize PIX instant payment integration to reduce cash handling costs.
- Autonomous Vehicles:Self-driving taxi prototypes undergoing safety validation under NHTSA protocols in the United States and MIIT certification in China. Capital deployment concentrates in Phoenix, San Francisco, and Shanghai testing corridors without near-term revenue contribution.
Mobile app-based systems anchor current fleet economics; autonomous vehicles carry the steepest expansion trajectory contingent on regulatory clearance timelines.
End User:
User segments diverge by procurement channel, with corporate accounts consolidating through annual contracts and individual users driving per-ride platform liquidity.
- Corporate:Enterprise mobility budgets covering employee commuter services and business travel. German and British fleet management departments negotiate committed spend agreements with guaranteed service level metrics.
- Individual:Discrete consumer purchases for daily commuting and discretionary trips. Urban Indian demand concentrates here as smartphone penetration displaces street-hail habits.
- Tourist:Airport transfers and city sightseeing services with multilingual driver requirements. Dubai and Singapore operators target this segment through hotel concierge integrations.
- Emergency Services:Medical transport and priority dispatch for healthcare facility transfers. Japan's aging demographics expand non-urgent medical taxi specifications under municipal subsidy programs.
Individual users generate highest trip frequency; corporate accounts deliver superior unit economics through subscription bundling.
Vehicle Type:
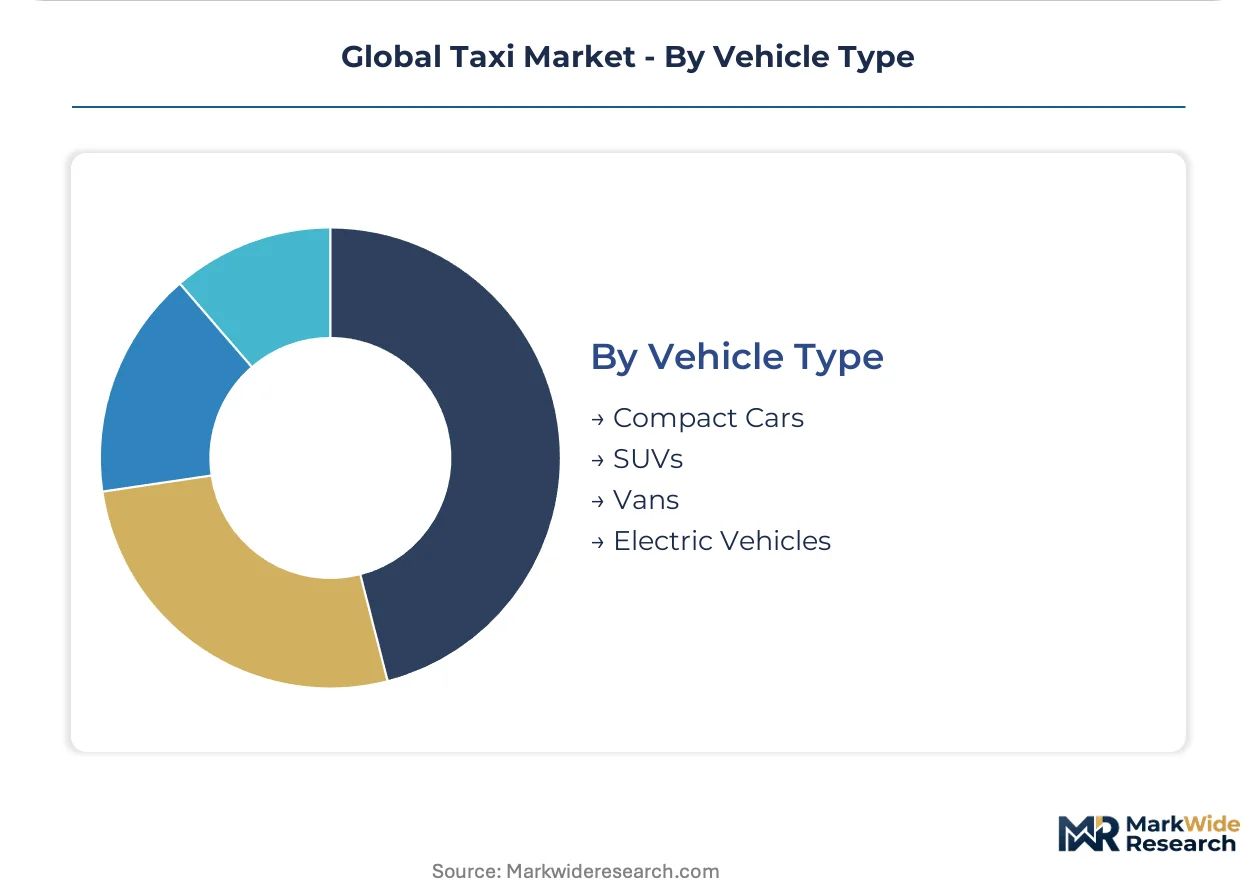
Fleet composition pivots toward electrification as total cost of ownership calculations incorporate carbon pricing and municipal zero-emission mandates.
- Compact Cars:Fuel-efficient sedans and hatchbacks optimized for urban density and parking constraints. European fleet operators favor these for EU F-Gas Regulation compliance in corporate commuter contracts.
- SUVs:Higher-capacity vehicles serving airport routes and premium service tiers. United States platform supply concentrates here in suburban corridors with lower passenger density.
- Vans:Multi-passenger configurations for group transport and accessibility requirements. Dutch and Belgian operators deploy these under municipal public service obligations.
- Electric Vehicles:Battery-electric drivetrains with dedicated charging infrastructure requirements. Chinese fleet procurement leads volume here driven by MIIT new energy vehicle mandates and Shenzhen's full electrification targets.
Compact cars retain dominant fleet share; electric vehicles are gaining share fastest as battery lifecycle management services mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHTSA vehicle safety standards anchor operational requirements in the United States while divergent regulatory frameworks across Germany, India, China, and Brazil determine platform capital deployment efficiency.
United States
Corporate commuter contracts and airport transfer services drive demand concentration in metropolitan corridors. NHTSA autonomous vehicle testing protocols govern safety validation timelines in Phoenix and San Francisco. Fleet operators prioritize electric vehicle procurement to meet municipal zero-emission mandates in California and New York.
Germany
Corporate travel management departments consolidate annual mobility spend agreements with guaranteed service levels. EU F-Gas Regulation and REACH compliance requirements elevate fleet procurement standards. Berlin and Munich retain traditional cooperative licensing structures that resist full platform displacement.
India
Smartphone penetration and app-based payment integration displace street-hail habits in metropolitan jurisdictions. Ministry of Road Transport and Highways city-specific permit regimes create market access barriers. Bangalore and Mumbai concentrate aggregator platform expansion as regulatory arbitrage opportunities.
China
MIIT new energy vehicle mandates accelerate electric fleet procurement decisions. Dual carbon goals redirect capital toward battery lifecycle management services. Shanghai and Shenzhen testing corridors concentrate autonomous vehicle R&D expenditure without near-term revenue contribution.
Brazil
PIX instant payment integration reduces cash handling costs and elevates driver supply elasticity. ANVISA data governance frameworks constrain passenger information monetization. São Paulo and Rio de Janeiro present first-mover advantages for localized routing and payment solutions.
Global Taxi Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with global network density separating premium-platform operators from regional specialists. The vendor base stratifies across three tiers: integrated super-app conglomerates, single-market aggregators, and legacy dispatch cooperatives. Platform operators defend position through AI-driven dispatch optimization and recruitment automation infrastructure. Geographic expansion and super-app convergence represent the dominant competitive vectors.
Among North American platform operators, Uber Technologies Inc. and Lyft Inc. exemplify the global network density archetype, leveraging cross-border technology stacks to sustain pricing power. Within the Asia-Pacific super-app tier, Grab Holdings Inc. and Gojek occupy positions defined by transport-delivery-financial service integration. DiDi Global Inc. anchors the AI-optimization specialist segment with concentrated operational depth in Chinese urban corridors. Regional specialists including Ola Cabs, Bolt Technology, Yandex Go, and FREE NOW represent market-specific licensing arbitrage strategies.
| Leading Market Players |
|---|
| Uber Technologies Inc. |
| DiDi Global Inc. |
| Grab Holdings Inc. |
| Gojek |
| Ola Cabs |
| Bolt Technology |
| Lyft Inc. |
| Yandex Go |
| FREE NOW |
| Others |
Value Chain & Pricing Dynamics
EU F-Gas Regulation compliance gates both vehicle fleet qualification and price differentiation across corporate commuter contracts, forcing operators to absorb electrification capex or pass through premiums to enterprise procurement departments. This regulatory threshold simultaneously constrains supplier eligibility and segments pricing power by certification tier.
Pricing Analysis
Metropolitan corridors in Germany and Switzerland sustain 40-60% fare premiums over Brazilian and Indonesian urban markets due to cooperative licensing density and corporate contract concentration. Three-tier pricing structure across premium, standard, and economy levels separates luxury chauffeur services from aggregator platforms and street-hail cooperatives. Cost compression in the ride-sharing tier is intensifying because driver supply volatility elevates recruitment subsidies. Individual commuters in urban India exhibit highest price sensitivity; corporate travel managers in the United Kingdom demonstrate lowest elasticity through annual committed spend agreements.
Supply Chain Analysis
Semiconductor chip fabrication for dispatch hardware and autonomous sensor arrays creates a chokepoint that underwrites fleet technology procurement timelines and platform R&D pacing. Vehicle assembly concentrates in China, Germany, and Mexico for platform fleet procurement. Battery cell production draws from South Korea, China, and Japan. Lithium carbonate and nickel sulfate feedstock sourcing rests on Indonesian and Chilean extraction capacity. Single-source vulnerability in AI training chip supply threatens dispatch optimization deployment schedules. Distribution runs through regional hub-and-spoke depot networks with last-mile driver onboarding nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
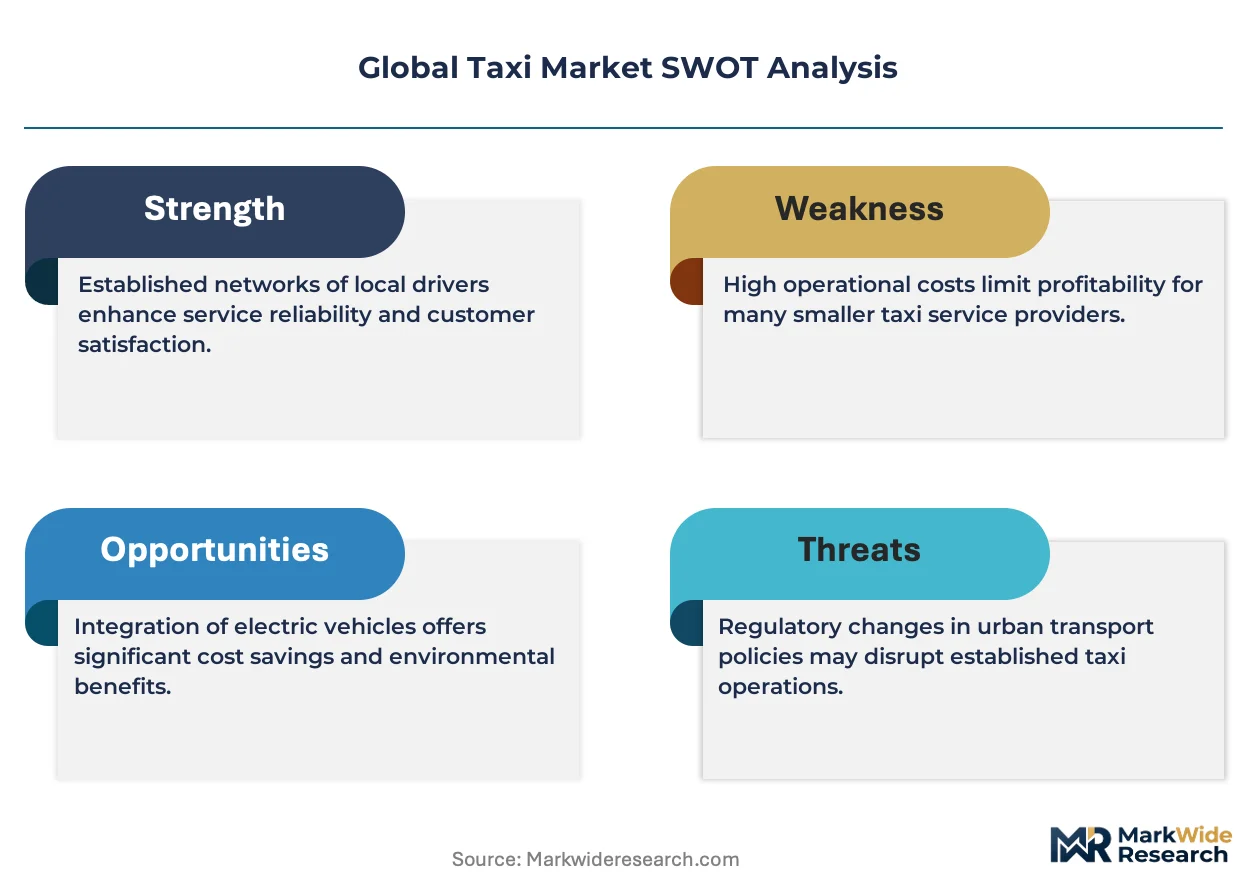
Platform fragmentation across city-specific permit regimes creates arbitrage niches for operators with localized compliance capabilities. Corporate procurement centralization in Germany and the United Kingdom fragments further as human resources departments disaggregate mobility budgets.
For Market Incumbents: Consolidate driver supply pools through recruitment automation infrastructure and captive training academy investments to offset labor pool contraction in major metropolitan zones. Deepen backward integration into electric vehicle procurement through direct OEM fleet purchase agreements, bypassing third-party leasing markups. Autonomous vehicle R&D capital lock-up periods represent the primary threat to near-term margin stability. For New Entrants and Emerging Players: Differentiate on PIX instant payment integration and Portuguese-language routing optimization to capture underpenetrated Brazilian metropolitan corridors before incumbent platform localization. Target India's tier-two municipal permit regimes where Ministry of Road Transport and Highways jurisdiction fragmentation creates temporary regulatory gaps. Deploy lightweight Android applications optimized for variable network connectivity as the primary go-to-market angle. For Investors and Strategic Acquirers: NHTSA autonomous vehicle certification timeline compression reshapes the acquisition landscape toward platform operators with demonstrated safety validation progress and capital endurance for extended R&D horizons. Long-term viability centers on super-app convergence capability spanning transport, delivery, and financial services integration. Acquisition target archetype: regional aggregators with city-specific permit holdings and localized payment infrastructure. Monitor MIIT new energy vehicle mandate enforcement intensity as the signal to watch for electric fleet transition inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Recruitment Automation Infrastructure | Reduces driver acquisition costs in supply-constrained metropolitan corridors like London and San Francisco. |
| Electric Fleet Procurement Agreement | Locks in battery lifecycle management services under EU F-Gas Regulation compliance timelines. |
| Super-App Integration | Creates cross-subsidization between Grab Holdings transport, delivery, and financial service verticals. |
| Autonomous Vehicle Testing Corridor | Concentrates R&D expenditure in Phoenix and Shanghai under NHTSA and MIIT validation protocols. |
| PIX Payment Localization | Eliminates cash handling friction for Brazilian drivers and elevates platform liquidity in São Paulo. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet procurement managers, platform dispatch engineers, municipal transport regulators, corporate travel management directors, and driver cooperative representatives. Secondary validation drew from NHTSA safety filing databases, EU F-Gas Regulation compliance registries, Ministry of Road Transport and Highways permit gazettes, SEC 10-K disclosures from listed platform operators, and vehicle registration data from metropolitan transport authorities. Bottom-up trip volume estimates and top-down fleet capacity assessments were triangulated against regulatory permit counts.
Across the analysis window, the forecasting framework modeled service type segmentation, technology adoption tiers, end-user procurement channels, and vehicle drivetrain specifications. CAGRs were derived from regression analysis against smartphone penetration curves, corporate travel budget indices, and electric vehicle cost parity thresholds. Driver supply elasticity coefficients and autonomous vehicle regulatory clearance probability weights informed scenario-weighted outputs.
The analysis sits within stated boundaries; outcomes outside sustained municipal zero-emission mandate enforcement or abrupt permit regime liberalization would require recalibration. Forecasts reflect documented assumptions regarding technology adoption S-curves and regulatory timeline stability. Practitioners should keep alternative scenarios live as EU AI Act algorithmic audit requirements and India city-specific permit fragmentation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Egypt Ride Hailing Service Market
Transportation Services
Equipment Relocation Service Market
Transportation Services
Ship Management Software Market
Transportation Services
Asia Pacific Tourism Vehicle Rental Market
Transportation Services
Enclosed Car Transportation Service Market
Transportation Services
Vacuum Truck Rentals Market
Transportation Services
Taxi and Ride-Hailing Services Market
Transportation Services
United States Car Rental Market
Transportation Services
Cross Docking Services Market
Transportation Services
Sanitation Vehicle Market
Transportation Services
On Street Vehicle Parking Meter Market
Transportation Services
United States White Glove Delivery Service Market
Transportation Services
Driving Vacation Market
Transportation Services
Germany Car Rental Market
Transportation Services
ASEAN Taxi Market
Transportation Services
Car Rental Market