
 North America Nuclear Medicine Equipment Market | 2026-2036
North America Nuclear Medicine Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
North America Nuclear Medicine Equipment Market Analytics
Academic medical centers is unwinding the traditional hospital-centric procurement model for nuclear medicine equipment in North America. GE HealthCare leverages its cyclotron manufacturing network to anchor supply security for radiotracer-dependent imaging systems. Siemens Healthineers differentiates through digital PET reconstruction algorithms that reduce scan times. Cardinal Health controls radiopharmaceutical distribution logistics across major metropolitan corridors.
Nuclear medicine equipment encompasses ionizing radiation-based diagnostic and therapeutic systems utilizing gamma-emitting or positron-emitting isotopes, with PET scanners achieving spatial resolution below 4 mm through lutetium-based crystal arrays and coincidence detection electronics. SPECT systems occupy the installed base majority across community hospitals, while PET modalities capture the fastest replacement cycle driven by oncology staging protocols. Delivery mode segmentation shows intravenous administration dominating radiopharmaceutical uptake, though oral routes expand in thyroid disorder applications.
The FDA regulates radiopharmaceutical manufacturing under current Good Manufacturing Practice standards, while the NRC governs reactor-produced isotope handling and waste protocols across imaging facilities. State-level Certificate of Need requirements in New York and Illinois constrain scanner deployment density, creating localized supply bottlenecks. Stakeholders must monitor CMS reimbursement rate deliberations for diagnostic radiopharmaceuticals, as payment policy shifts will determine capital recovery timelines for imaging center operators weighing system upgrades against extended utilization of existing PET and SPECT platforms.
Market Dynamics
FDA streamlining of radiopharmaceutical approval pathways is compressing the time between tracer development and clinical deployment, forcing imaging centers to accelerate capital planning cycles to capture reimbursement windows.
Growth Catalysts
- Oncology Staging Protocols:PET scanner replacement cycles accelerate as major cancer centers in the United States demand higher-resolution lutetium-based crystal arrays for precision tumor characterization.
- CMS Reimbursement Deliberations:Payment policy shifts for diagnostic radiopharmaceuticals are extending capital recovery timelines, incentivizing imaging center operators toward system upgrades.
- Academic Medical Center Expansion:Molecular imaging programs are proliferating across teaching hospitals, unwinding traditional hospital-centric procurement models for nuclear medicine equipment.
Market Restraints
- Molybdenum-99 Supply Concentration:Reactor-produced isotope handling bottlenecks in aging North American facilities constrain technetium-based SPECT tracer availability.
- Certificate of Need Requirements:New York and Illinois state regulations artificially limit scanner deployment density, creating localized supply constraints for PET and SPECT modalities.
- Capital Intensity Barriers:Cyclotron installation and shielding requirements exceed $10 million per site, excluding community hospitals from PET radiotracer production autonomy.
Strategic Opportunities
- Oral Route Expansion:Thyroid disorder applications are opening non-intravenous radiopharmaceutical delivery channels, diversifying administration modalities beyond oncology.
- Digital PET Reconstruction:Algorithm-driven scan time reduction is enabling higher patient throughput in outpatient imaging centers without hardware replacement.
- Radiopharmaceutical Distribution Logistics:Metropolitan corridor hub models are compressing tracer delivery windows, allowing same-day scheduling for time-sensitive cardiac and neuroimaging studies.
Industry Challenges
- Qualified Personnel Scarcity:Nuclear medicine technologist certification programs produce insufficient graduates to staff expanding PET scanner installations across the United States.
- NRC Waste Protocol Compliance:Radioactive material disposal regulations impose complex tracking and documentation burdens on imaging facilities with limited dedicated compliance staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Nuclear Medicine Equipment Market |
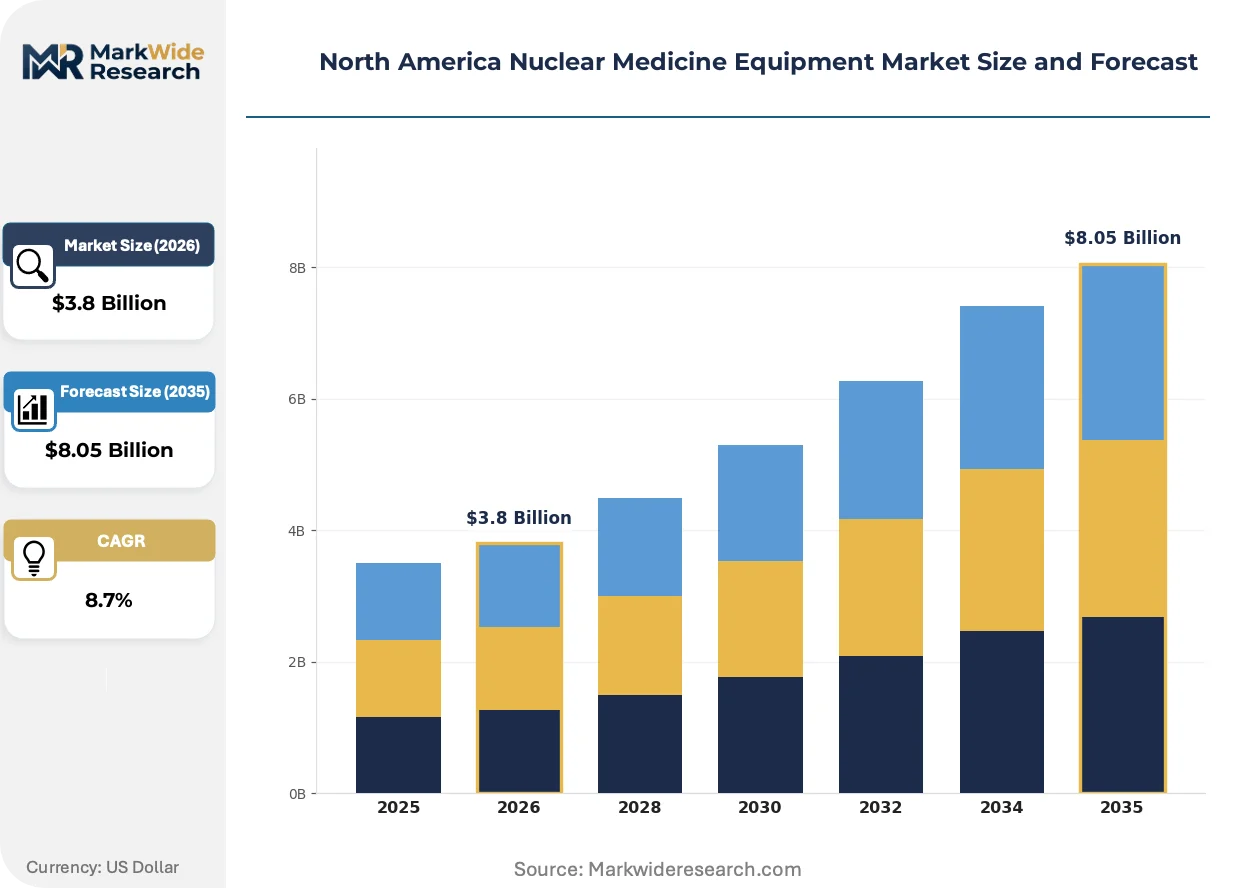
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SPECT, PET, Radionuclide Generators, Radiation Detectors Application: Oncology, Cardiology, Neurology, Thyroid Disorders Delivery Mode: Intravenous, Oral, Subcutaneous, Inhalation End User: Hospitals, Imaging Centers, Research Institutes, Diagnostics Labs |
| Companies Covered | GE HealthCare, Siemens Healthineers, Canon Medical Systems Corporation, Koninklijke Philips N.V., Cardinal Health, Mirion Technologies, Mediso Ltd., CMR Naviscan, Lantheus, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Nuclear Medicine Equipment Market Evolving Landscape
Digital reconstruction algorithms and detector crystal advances are compressing the performance gap between premium and mid-tier PET platforms, reshaping upgrade decisions across outpatient imaging networks.
Solid-state silicon photomultiplier detectors are replacing traditional photomultiplier tubes in next-generation PET scanners, enabling magnetic resonance compatibility and simultaneous PET-MR imaging. Academic medical centers in the United States are piloting these hybrid systems for neuro-oncology applications. The technology is miniaturizing detector footprints while maintaining sub-4 mm spatial resolution, allowing scanner deployment in previously space-constrained clinical environments.
The FDA's streamlined current Good Manufacturing Practice enforcement for novel radiopharmaceuticals is reducing investigational new drug application review timelines. This regulatory compression accelerates tracer commercialization, forcing imaging centers to validate new compound handling protocols ahead of reimbursement code establishment. PET scanner operators in major metropolitan corridors are investing in flexible dose calibration systems to accommodate rapid tracer portfolio expansion.
Academic medical centers are consolidating molecular imaging procurement decisions under centralized research administration, displacing traditional departmental capital allocation. This buyer concentration is compressing vendor negotiation cycles and demanding extended service bundling. The shift is most visible across National Cancer Institute-designated comprehensive cancer centers, where multi-site standardization is overriding local equipment preferences.
North America Nuclear Medicine Equipment Market Segmentation
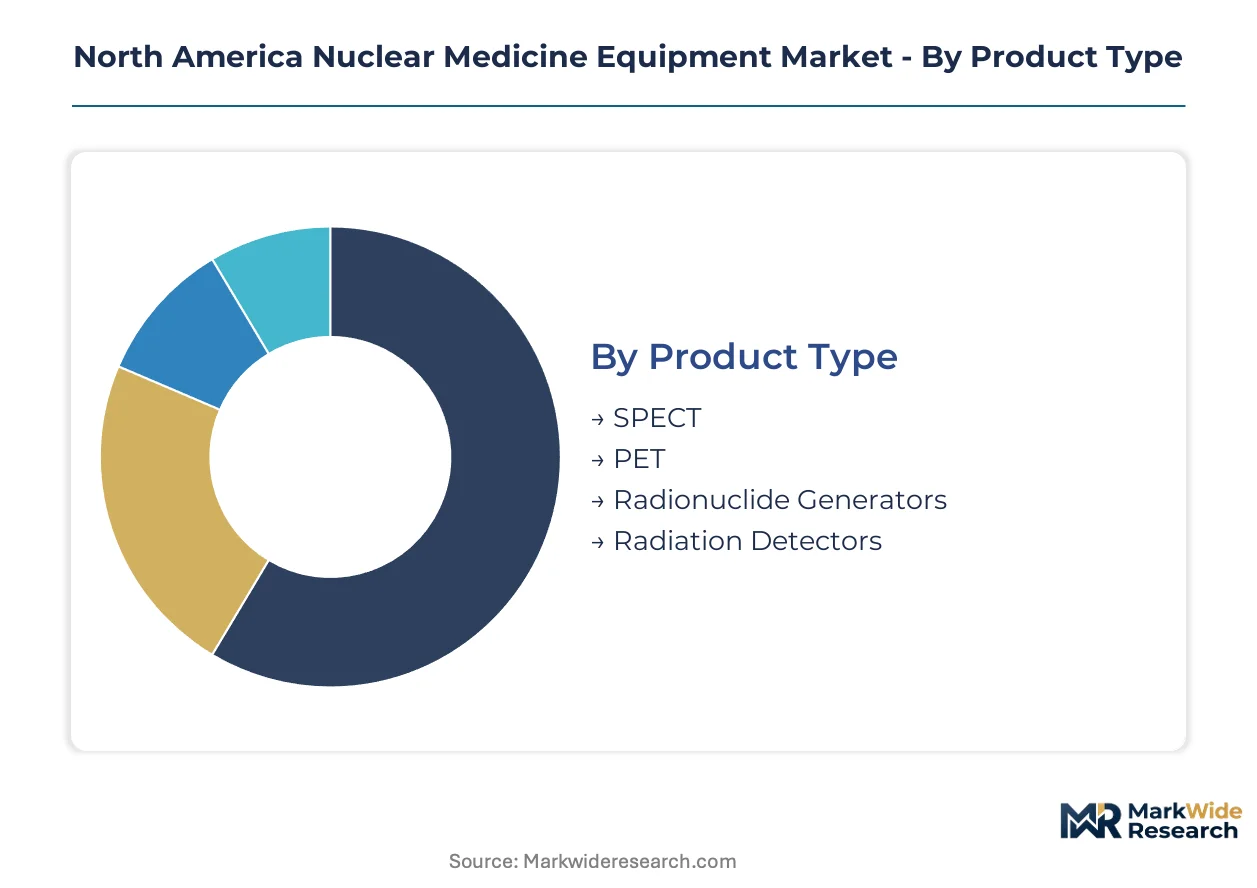
Equipment segmentation in North America nuclear medicine reveals divergent capital recovery profiles across modalities. Product type stratification determines cyclotron dependency and shielding investment thresholds, while application mix shapes radiotracer procurement contracts and CMS reimbursement exposure.
Product Type:
Premium margin pools concentrate in PET platforms where lutetium-based crystal arrays command pricing power through spatial resolution below 4 mm.
- PET:Positron emission tomography systems deploy lutetium oxyorthosilicate crystal arrays with coincidence detection electronics for sub-4 mm spatial resolution. Major cancer centers across the United States drive replacement cycles as oncology staging protocols demand precision tumor characterization.
- SPECT:Single photon emission computed tomography systems utilize sodium iodide or cadmium zinc telluride detectors for gamma-emitting isotope imaging. Community hospitals in Illinois and New York maintain the installed base majority despite Certificate of Need constraints on deployment density.
- Radionuclide Generators:Molybdenum-99/technetium-99m generator systems enable on-site tracer production for technetium-based SPECT studies. Aging reactor infrastructure across North American facilities creates supply vulnerability for this segment.
- Radiation Detectors:Handheld and fixed-position dose calibrators verify radiopharmaceutical activity prior to patient administration. Outpatient imaging centers in metropolitan corridors deploy these for same-day scheduling flexibility.
SPECT holds installed capacity. PET is rotating up the share rankings.
Application:
Oncology applications concentrate capital investment in academic medical centers with NCI-designated comprehensive cancer center status.
- Oncology:Tumor staging and treatment response monitoring utilize fluorodeoxyglucose and prostate-specific membrane antigen tracers. PET scanner installations accelerate across major United States cancer centers as precision characterization protocols proliferate.
- Cardiology:Myocardial perfusion imaging employs technetium-99m sestamibi or tetrofosmin tracers for coronary artery disease assessment. Metropolitan corridor distribution hubs enable same-day scheduling for time-sensitive cardiac studies.
- Neurology:Amyloid and tau imaging for Alzheimer's disease evaluation uses florbetapir and flortaucipir tracers. Academic medical centers pilot hybrid PET-MR systems for neuro-oncology applications requiring magnetic resonance compatibility.
- Thyroid Disorders:Iodine-131 uptake and ablation procedures treat hyperthyroidism and differentiated thyroid carcinoma. Oral route administration in this application diversifies delivery modalities beyond intravenous oncology protocols.
Cardiology maintains procedure volume. Oncology is climbing the fastest.
Delivery Mode:
Route selection determines shielding requirements, personnel exposure protocols, and patient throughput logistics.
- Intravenous:Direct bloodstream injection of technetium-99m, fluorine-18, and gallium-68 tracers dominates radiopharmaceutical uptake across oncology and cardiology applications. Imaging centers invest in flexible dose calibration systems to accommodate rapid tracer portfolio expansion.
- Oral:Iodine-131 capsule or liquid administration for thyroid disorders enables outpatient treatment without vascular access. This route expands administration modalities beyond hospital-based infusion capabilities.
- Subcutaneous:Lymphoscintigraphy for sentinel node biopsy utilizes filtered technetium-99m sulfur colloid injected beneath the skin. Breast cancer centers deploy this for surgical planning coordination.
- Inhalation:Xenon-133 ventilation studies assess pulmonary function in nuclear medicine departments with specialized gas handling infrastructure. Limited deployment reflects regulatory complexity of gaseous radioisotope management.
Intravenous commands procedure share. Oral is gaining share fastest.
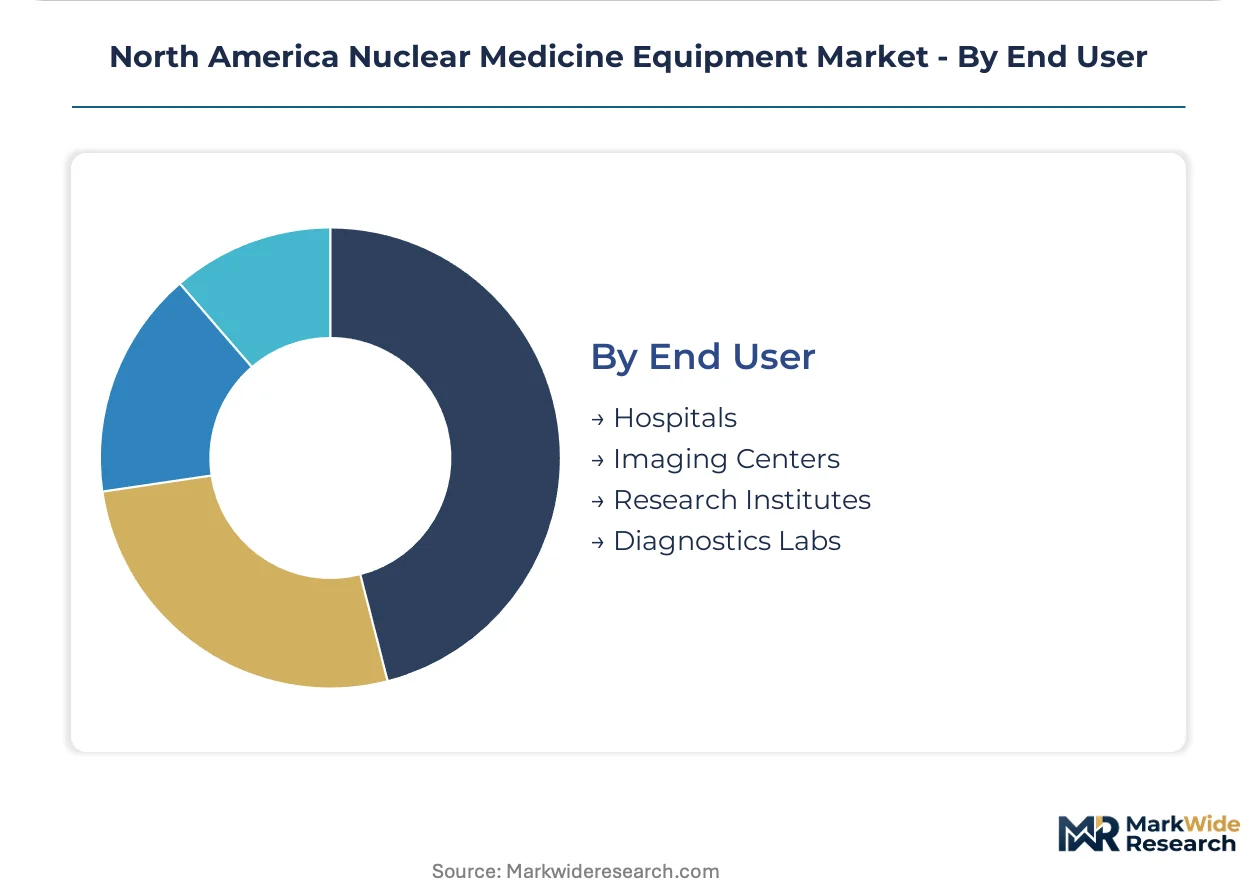
End User:
Procurement authority is consolidating under centralized research administration at academic medical centers.
- Hospitals:Integrated health systems deploy hybrid PET-CT and emerging PET-MR platforms across radiology and radiation oncology departments. Multi-site standardization is overriding local equipment preferences at NCI-designated centers.
- Imaging Centers:Freestanding outpatient facilities prioritize digital PET reconstruction algorithms to reduce scan times without hardware replacement. CMS reimbursement rate deliberations determine capital recovery timelines for these operators.
- Research Institutes:Preclinical imaging and translational radiochemistry programs require micro-PET and specialized cyclotron infrastructure. FDA streamlined approval pathways compress time between tracer development and clinical deployment.
- Diagnostics Labs:Reference laboratories process radioimmunoassay and molecular imaging biomarker validation. These facilities support clinical trial endpoints for novel radiopharmaceutical development.
Hospitals anchor installed base. Imaging centers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada exports molybdenum-99 and other reactor-produced isotopes to imaging centers across the United States, anchoring the North American radiopharmaceutical supply chain.
United States
Major cancer centers in Houston, Boston, and New York Metro drive PET scanner replacement cycles as oncology staging protocols demand sub-4 mm spatial resolution. The FDA streamlines current Good Manufacturing Practice enforcement for novel radiopharmaceuticals, compressing investigational new drug review timelines. National Cancer Institute-designated comprehensive cancer centers in the Midwest and Southeast are consolidating molecular imaging procurement under centralized research administration.
Canada
Chalk River Laboratories and aging reactor infrastructure supply technetium-99m generators to SPECT imaging facilities throughout the cross-border corridor. Health Canada regulates radiopharmaceutical manufacturing under standards harmonized with FDA protocols, facilitating seamless export certification. Ontario's Greater Toronto Area hosts cyclotron manufacturing networks that anchor supply security for fluorine-18 and gallium-68 tracers.
Mexico
Metropolitan Mexico City and Monterrey imaging centers expand PET-CT installations as private healthcare networks modernize diagnostic capabilities. COFEPRIS, the national pharmaceutical regulator, aligns radiopharmaceutical approval pathways with FDA benchmarks to accelerate tracer importation. Nuevo León's medical device distribution hubs serve as consolidation points for equipment entering the Central American corridor.
North America Nuclear Medicine Equipment Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity tiers, with publicly traded conglomerates commanding premium PET platform pricing while private firms dominate radiopharmaceutical logistics and cyclotron services. The vendor base stratifies into three tiers: integrated imaging system conglomerates, radiopharmaceutical distribution specialists, and regional cyclotron service operators. Consolidation pressures intensify as academic medical centers demand extended service bundling and multi-site standardization. Dominant competitive moves include strategic partnerships between equipment manufacturers and tracer producers, plus backward integration into cyclotron manufacturing networks.
Within the integrated imaging tier, GE HealthCare and Siemens Healthineers exemplify conglomerate-scale positioning through their cyclotron manufacturing and digital reconstruction algorithm portfolios. Cardinal Health occupies a distinct logistics-specialist position, controlling metropolitan corridor distribution for time-sensitive radiopharmaceutical delivery. These three entities represent the primary competitive anchors shaping procurement negotiations with NCI-designated cancer centers and hospital networks.
| Leading Market Players |
|---|
| GE HealthCare |
| Siemens Healthineers |
| Canon Medical Systems Corporation |
| Koninklijke Philips N.V. |
| Cardinal Health |
| Mirion Technologies |
| Mediso Ltd. |
| CMR Naviscan |
| Lantheus |
| Others |
Value Network & Pricing Analysis
Lutetium oxyorthosilicate crystal arrays replacing sodium iodide detectors simultaneously concentrates supply geography in Canadian and Belgian reactor zones and compresses pricing economics for mid-tier PET platforms. Equipment vendors now face margin pressure as digital reconstruction algorithms erode the performance premium historically commanded by lutetium-based hardware.
Pricing Analysis
Premium-tier PET scanners with sub-4 mm spatial resolution command substantial markups over prior-generation bismuth germanate systems, while next-generation silicon photomultiplier platforms are resetting price floors. Three-tier pricing structure across premium, standard, and economy levels stratifies by detector crystal grade and FDA 510(k) clearance tier. Pricing pressure stems from academic medical center consolidation under centralized research administration, which demands extended service bundling and compresses vendor negotiation cycles. Community hospitals exhibit highest price sensitivity due to Certificate of Need capital constraints, while NCI-designated comprehensive cancer centers prioritize performance specifications over unit economics.
Supply Chain Analysis
Chalk River reactor transit underwrites technetium-99m generator availability across the cross-border corridor, creating single-source vulnerability for SPECT tracer production. Geographic supply concentration centers on Canada for molybdenum-99, Belgium for enriched uranium processing, and the United States for fluorine-18 cyclotron networks. Raw material dependencies include reactor-grade uranium targets, high-purity lutetium ore, and specialized lead shielding alloys. Supply chain risk manifests in aging North American reactor infrastructure and NRC waste protocol compliance burdens. Distribution runs through Cardinal Health's metropolitan corridor hub model, compressing delivery windows for time-sensitive cardiac and neuroimaging studies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against MRI-based functional imaging and liquid biopsy diagnostics that threaten PET scanner utilization rates in oncology staging protocols.
For Market Incumbents: Shield installed base revenue by deepening cyclotron manufacturing networks to anchor radiotracer supply security for imaging center customers. Acquire or partner with digital PET reconstruction software specialists to differentiate service bundles beyond hardware specifications. Prioritize multi-site standardization contracts with consolidating academic medical centers to lock out emerging competitors before procurement authority centralizes completely. For New Entrants and Emerging Players: Differentiate on oral-route radiopharmaceutical delivery systems for thyroid disorder applications, where intravenous infrastructure requirements exclude traditional equipment vendors. Target imaging centers in Certificate of Need-constrained states like Illinois and New York, where scanner deployment density limits create localized supply bottlenecks and service gaps. Pursue GPO contracts with community hospital networks seeking PET-CT capability without academic medical center capital intensity. For Investors and Strategic Acquirers: FDA streamlined approval pathways for novel radiopharmaceuticals reshapes the acquisition landscape by compressing time-to-revenue for tracer development assets. Long-term viability favors vertically integrated platforms combining cyclotron manufacturing with imaging system deployment, as radiotracer supply security becomes the primary procurement criterion. Monitor CMS reimbursement rate deliberations for diagnostic radiopharmaceuticals as the critical inflection signal determining capital recovery timelines across outpatient imaging center operators.| Strategic Initiative | Industry Significance |
|---|---|
| Cyclotron Manufacturing Network Expansion | GE HealthCare's captive isotope production secures radiotracer supply for PET scanner customers. |
| Digital PET Reconstruction Algorithm Development | Siemens Healthineers reduces scan times without hardware replacement, enabling outpatient throughput gains. |
| Metropolitan Corridor Distribution Hub Consolidation | Cardinal Health compresses tracer delivery windows for same-day cardiac and neuroimaging scheduling. |
| Hybrid PET-MR Platform Commercialization | Academic medical centers pilot silicon photomultiplier systems for neuro-oncology magnetic resonance compatibility. |
| Oral Route Radiopharmaceutical Portfolio Expansion | Iodine-131 capsule administration diversifies delivery modalities beyond hospital-based intravenous capabilities. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with nuclear medicine technologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers; and secondary validation through FDA 510(k) filings, CMS reimbursement databases, NRC regulatory dockets, and hospital procurement records. Bottom-up equipment installation tracking triangulated against top-down radiopharmaceutical production and trade flow estimates to anchor market sizing.
Across the analysis window, the analytical framework modeled segmentation dimensions including product type, application mix, delivery mode, and end-user procurement authority concentration. CAGRs were derived from installed base replacement cycles, radiotracer approval velocity, and reimbursement policy trajectory. Industry-specific forecast inputs incorporated reactor infrastructure age profiles and academic medical center capital allocation centralization trends.
Material uncertainties — reactor shutdowns, CMS payment policy reversals, and qualified technologist supply constraints — sit outside the modeled envelope. Forecasts reflect documented assumptions about radiopharmaceutical approval pathway efficiency and Certificate of Need regulatory stability. Practitioners should keep alternative scenarios live as hybrid imaging substitution rates and liquid biopsy diagnostic accuracy evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Embryo Incubator Market
Medical Equipment
Medical Oxygen Gas Cylinder Market
Medical Equipment
Global Medical Equipment Calibration Market
Medical Equipment
Cryochambers Market
Medical Equipment
Electron Beam Linear Accelerators Market
Medical Equipment
Blood Bank Refrigerators Market
Medical Equipment
Medical Equipment Leasing Market
Medical Equipment
MRI Transport Market
Medical Equipment
Bench-Top Dental Autoclaves Market
Medical Equipment
Sanitary Napkin Equipment Market
Medical Equipment
India Massage Equipment Market
Medical Equipment
Medical Automation Market
Medical Equipment
Medical Linear Accelerators (MLA) Market
Medical Equipment
Global Cardiopulmonary Stress Testing Systems Market
Medical Equipment
Spinal Surgery Tables Market
Medical Equipment
Podiatry Equipment Market