
 Global Newborn Screening Market | 2026-2036
Global Newborn Screening Market Size, Share, and Industry Trends Forecast 2026-2036
Global Newborn Screening Market Foresight
A shift from outsourced reference-lab processing to in-house hospital-based screening is repositioning procurement patterns across the value chain. PerkinElmer leverages its installed base of tandem mass spectrometry systems to sustain long-term service contracts. Abbott competes through integrated immunoassay platforms that anchor neonatal care unit workflows. Bio-Rad Laboratories specializes in quality control materials that extend its influence beyond instrument sales into protocol standardization.
Newborn screening encompasses biochemical and molecular testing of blood, urine, or saliva specimens collected within 24–72 hours of birth to detect congenital disorders before clinical symptoms manifest; tandem mass spectrometry enables simultaneous detection of 30–50 metabolic analytes from a single dried blood spot, fundamentally expanding panel breadth while reducing per-sample cost. Molecular diagnostics represents the fastest-expanding product category as DNA sequencing costs decline and lysosomal storage disease panels gain reimbursement traction. Mass spectrometry occupies the mature core of metabolic disorder screening, where instrument refresh cycles and reagent volume commitments generate predictable margin pools.
The US FDA regulates in vitro diagnostic devices used in newborn screening under premarket notification pathways, while the EU MDR imposes stricter clinical evidence requirements on molecular diagnostic kits that reshape product development timelines for European market access. WHO newborn screening guidelines influence national program design in low- and middle-income countries, creating demand pull for simplified instrument platforms and dried blood spot logistics. Stakeholders must monitor how expanding panel recommendations from national health agencies interact with reimbursement bandwidth and laboratory capacity constraints.
Market Dynamics
Panel expansion toward lysosomal storage disorders is forcing laboratories to reconfigure workflows around molecular platforms while maintaining legacy mass spectrometry infrastructure for core metabolic screening.
Growth Catalysts
- WHO newborn screening guidelines:Standardized protocols are accelerating program adoption across low- and middle-income countries, creating demand for simplified dried blood spot logistics.
- Tandem mass spectrometry advances:Simultaneous detection of 30–50 metabolic analytes from single specimens is compressing per-sample costs and expanding reimbursable panel breadth.
- National program scaling in India, Brazil, and Nigeria:Public healthcare laboratories in these emerging economies are expanding panel adoption and building centralized screening infrastructure.
Market Restraints
- High capital intensity of molecular diagnostic platforms:Next-generation sequencing systems require substantial upfront investment, limiting adoption to tertiary referral centers and constraining rural access.
- Reimbursement bandwidth constraints:National health agencies face tension between expanding panel recommendations and fixed laboratory budget allocations, creating approval delays for novel assays.
- Supply concentration in specialized reagents:Isotope-labeled internal standards for mass spectrometry rely on a limited supplier base, exposing screening programs to price volatility and availability risk.
Strategic Opportunities
- Point-of-care screening in sub-Saharan Africa:Simplified instrument platforms and decentralized dried blood spot collection networks could bypass infrastructure gaps in national health systems.
- Integration of genomic sequencing with biochemical screening:Combined workflows for simultaneous metabolic and genetic disorder detection are opening reimbursement pathways for expanded panels.
- India's PLI scheme for medical devices:Domestic manufacturing incentives are attracting instrument and reagent production investment, reducing import dependency for national screening programs.
Industry Challenges
- Bioinformatics talent scarcity:Molecular diagnostic interpretation requires specialized computational biology expertise that outpaces current training pipeline output in emerging markets.
- EU MDR clinical evidence requirements:Stricter documentation demands for molecular diagnostic kits are extending product development timelines and raising regulatory submission costs for European market access.
- Legacy instrument integration complexity:Hospitals face workflow friction when connecting new molecular platforms with existing laboratory information systems and sample tracking infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Newborn Screening Market |
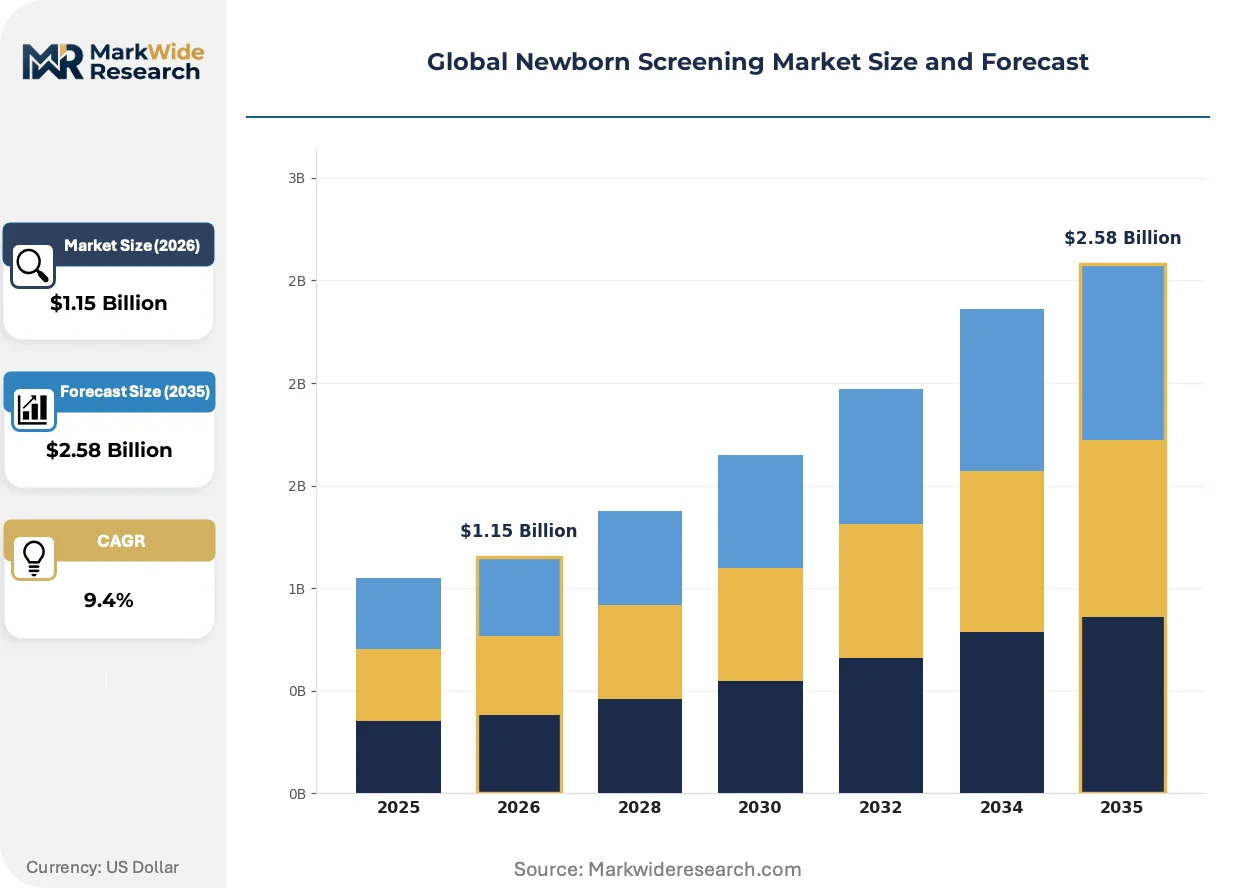
| Market Size in 2026 | $1.15 Billion |
| Market Size in 2035 | $2.58 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biochemical Assays, Molecular Diagnostics, Enzyme Assays, Immunoassays, Mass Spectrometry Screening Method: Heel Prick Test, Cord Blood Screening, Urine Analysis, Saliva Testing, DNA Analysis End User: Public Healthcare Laboratories, Private Diagnostic Centers, Research Institutes, Neonatal Care Units, Academic Hospitals Application: Metabolic Disorders, Endocrine Disorders, Hemoglobinopathies, Cystic Fibrosis, Lysosomal Storage Diseases |
| Companies Covered | PerkinElmer, Abbott, Roche, Bio-Rad Laboratories, Natus Medical, Danaher Corporation, Thermo Fisher Scientific, Agilent Technologies, Revvity, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Newborn Screening Market Shifts & Advancements
Next-generation sequencing is compressing the traditional separation between biochemical and genetic testing, enabling unified screening workflows that detect both metabolic and monogenic disorders from single specimens.
DNA sequencing is overtaking biochemical methods as the primary technology for expanded newborn screening panels in tertiary care centers across the United States and Western Europe. Academic medical centers and children's hospitals are adopting targeted gene panels and whole-exome sequencing for lysosomal storage disorders, spinal muscular atrophy, and severe combined immunodeficiency. This shift is compressing the addressable market for standalone biochemical assays while creating new service revenue pools around variant interpretation and genetic counseling.
The EU MDR imposes stricter clinical evidence requirements on molecular diagnostic kits, reshaping product development timelines for European market access. Manufacturers must now generate prospective clinical performance data for novel assays, extending regulatory submission cycles by 18–24 months compared to predecessor directives. In vitro diagnostic companies are responding by prioritizing CE-marked products with established clinical utility, delaying launches for exploratory biomarker panels until evidence thresholds stabilize.
Hospital-based laboratories are internalizing screening functions that previously flowed to outsourced reference labs, altering procurement patterns across the value chain. Integrated health systems in the United States and United Kingdom are consolidating neonatal testing within captive facilities to capture reimbursement margin and reduce turnaround times. This concentration is most visible in metropolitan hospital networks with sufficient birth volume to justify dedicated tandem mass spectrometry and molecular platform investments.
Global Newborn Screening Market Segmentation
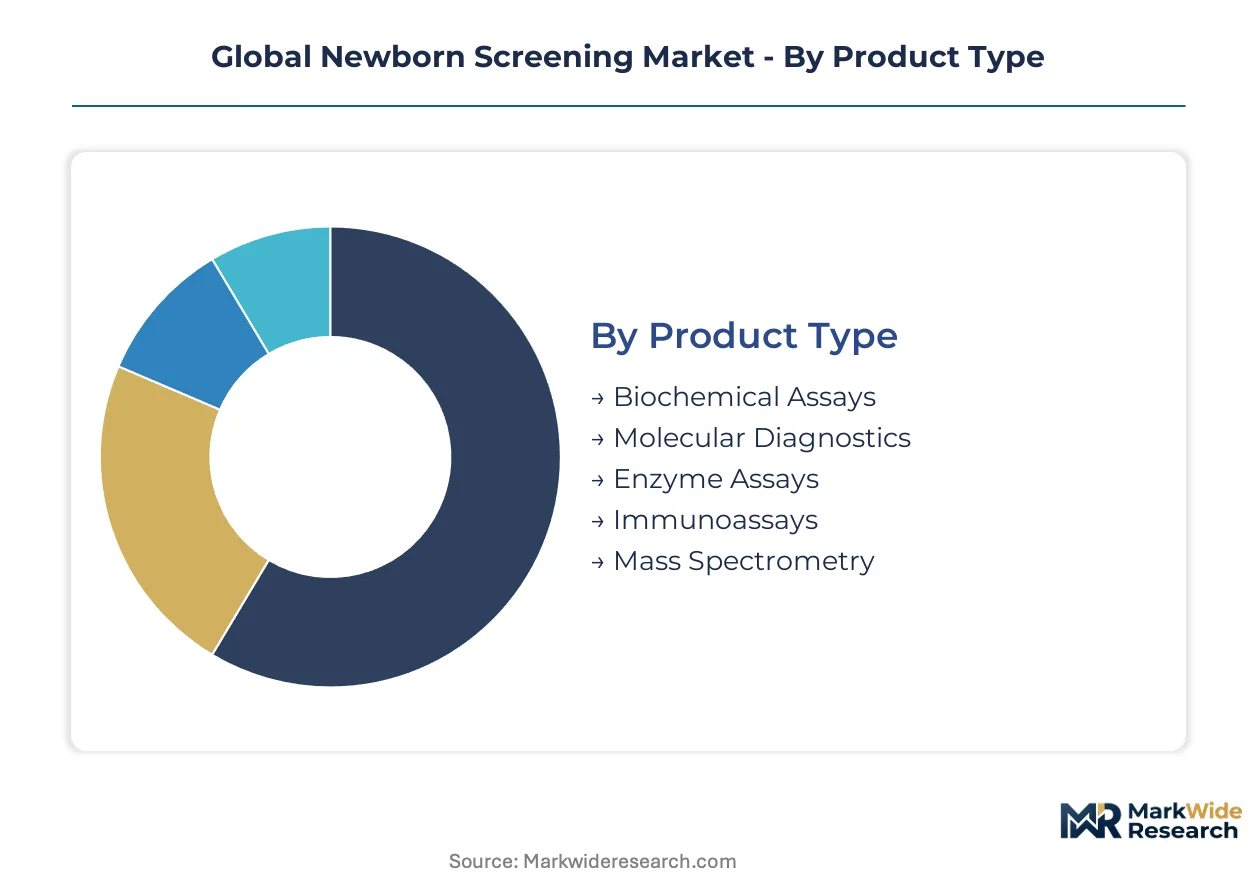
Segmentation in newborn screening reveals how capital allocation, reimbursement pathways, and infrastructure maturity diverge across testing modalities. Laboratories prioritize platforms based on birth volume, panel breadth requirements, and regulatory complexity in their jurisdiction.
Product Type:
Capital intensity varies sharply across product categories, with molecular platforms demanding the highest upfront investment while biochemical methods sustain volume economics.
- Mass Spectrometry:Tandem mass spectrometry systems detect 30–50 metabolic analytes from single dried blood spots, forming the backbone of national screening programs in Brazil and India. Public healthcare laboratories in these markets anchor procurement volume through centralized tenders.
- Molecular Diagnostics:Next-generation sequencing and targeted gene panels enable simultaneous detection of monogenic and metabolic disorders, requiring substantial bioinformatics infrastructure. Academic hospitals in the United States and Western Europe concentrate adoption where reimbursement supports expanded panels.
- Biochemical Assays:Conventional colorimetric and fluorometric methods serve as entry-level screening tools.
- Enzyme Assays:Quantitative enzyme activity measurements target specific metabolic deficiencies.
- Immunoassays:Antibody-based detection systems anchor thyroid and steroid disorder screening in neonatal care units.
Mass spectrometry absorbs the bulk of installed capacity; molecular diagnostics is expanding most quickly.
Screening Method:
Collection logistics and specimen stability determine geographic penetration, with dried blood spot methods dominating resource-limited settings.
- Heel Prick Test:The standard dried blood spot collection from infant heels enables centralized laboratory processing with minimal cold chain requirements. Nigeria's national program scales through decentralized heel prick collection networks feeding regional hubs.
- DNA Analysis:Saliva and buccal swab-based genetic testing bypasses metabolite degradation concerns but requires extraction infrastructure. Tertiary centers in Saudi Arabia and South Korea integrate DNA analysis with biochemical screening for comprehensive panels.
- Cord Blood Screening:Immediate post-delivery specimen collection supports rapid turnaround.
- Urine Analysis:Secondary confirmation testing for metabolic disorders.
- Saliva Testing:Non-invasive collection alternative gaining traction in home-based screening pilots.
Heel prick testing commands the highest specimen volume; DNA analysis shows the steepest expansion trajectory.
End User:
Procurement authority and reimbursement mechanisms fragment demand across public and institutional buyers.
- Public Healthcare Laboratories:Government-funded centralized screening facilities in India, Brazil, and Nigeria drive tender-based instrument procurement with multi-year reagent commitments. WHO guideline alignment shapes technical specifications and panel breadth.
- Neonatal Care Units:Hospital-embedded screening within academic medical centers in the United States and United Kingdom internalizes testing to capture margin and reduce turnaround. Integrated health systems justify dedicated platform investments through birth volume concentration.
- Private Diagnostic Centers:Commercial laboratories serving supplemental screening demand.
- Research Institutes:Pilot programs and expanded panel validation studies.
- Academic Hospitals:Hybrid research-clinical screening with protocol development authority.
Public healthcare laboratories dominate instrument placement; neonatal care units are gaining share fastest through vertical integration.
Application:
Disease prevalence and treatment availability determine panel composition across national programs.
- Metabolic Disorders:Phenylketonuria, galactosemia, and fatty acid oxidation defects constitute the core reimbursable panel in established programs. Tandem mass spectrometry cost compression has made 30+ analyte panels standard in the United States and European Union.
- Lysosomal Storage Diseases:Pompe disease, Fabry disease, and Gaucher disease screening requires molecular or enzyme activity confirmation, with enzyme replacement therapy availability driving inclusion decisions. Japan and Taiwan lead panel expansion here.
- Endocrine Disorders:Congenital hypothyroidism screening via TSH measurement.
- Hemoglobinopathies:Sickle cell disease and thalassemia detection prioritized in malaria-endemic regions.
- Cystic Fibrosis:Immunoreactive trypsinogen screening with DNA reflex testing.
Metabolic disorder screening captures the largest test volume; lysosomal storage disease detection is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dried blood spot collection networks in Nigeria, India, and Brazil anchor procurement volume for tandem mass spectrometry systems. National health agencies in these markets tender multi-year reagent contracts that shape instrument placement decisions across public healthcare laboratories.
United States
Academic medical centers in Boston and the San Francisco Bay Area drive adoption of expanded molecular panels for lysosomal storage disorders. FDA premarket notification pathways govern in vitro diagnostic device approval, creating predictable regulatory timelines for instrument manufacturers. Hospital networks in Texas and Florida internalize screening functions to capture reimbursement margin and reduce turnaround times.
India
Centralized public health laboratories in Maharashtra and Karnataka scale heel prick collection networks feeding regional screening hubs. The PLI scheme for medical devices attracts domestic manufacturing investment for instruments and reagents, reducing import dependency for national programs. Delhi-NCR and Tamil Nadu concentrate procurement authority for multi-year tandem mass spectrometry tenders.
Brazil
São Paulo and Minas Gerais anchor the national screening program's centralized laboratory infrastructure. ANVISA regulates in vitro diagnostics under risk-based classification pathways that align with WHO newborn screening guidelines. Public tenders in Rio de Janeiro and Rio Grande do Sul specify technical requirements for 30+ analyte metabolic panels.
Germany
Bavaria and Baden-Württemberg host reference laboratories that validate expanded panels for EU market access. The EU MDR imposes stricter clinical evidence requirements on molecular diagnostic kits, extending product development timelines by 18–24 months. Berlin-Brandenburg concentrates bioinformatics talent for variant interpretation services.
Nigeria
Lagos and Kano anchor decentralized dried blood spot collection networks that bypass cold chain infrastructure gaps. WHO guideline alignment shapes technical specifications for simplified instrument platforms in national program design. Abuja coordinates procurement for regional screening hubs serving northern and southern zones.
Global Newborn Screening Market Competitive Landscape
Strategic partnerships dominate the current landscape as instrument manufacturers secure long-term service contracts with public health laboratories. The vendor base clusters around three tiers: diversified life science conglomerates with full-platform portfolios, specialized diagnostic companies with mass spectrometry heritage, and emerging molecular players with sequencing expertise. Two archetypes define competitive positioning: installed-base defenders leveraging reagent lock-in, and workflow integrators capturing hospital-based screening migration. M&A activity and technology licensing agreements represent the primary competitive moves reshaping market structure.
Within the installed-base defender tier, PerkinElmer and Bio-Rad Laboratories exemplify archetypes built on tandem mass spectrometry heritage and quality control materials respectively. PerkinElmer occupies a position anchored to service contract renewals across public laboratory networks. Bio-Rad Laboratories sits within the protocol standardization layer, extending influence beyond instrument sales into reagent and control material supply. Abbott represents the workflow integration archetype, competing through immunoassay platforms that anchor neonatal care unit workflows.
| Leading Market Players |
|---|
| PerkinElmer |
| Abbott |
| Roche |
| Bio-Rad Laboratories |
| Natus Medical |
| Danaher Corporation |
| Thermo Fisher Scientific |
| Agilent Technologies |
| Revvity, Inc. |
| Others |
Supply & Pricing Matrix
Public healthcare laboratories in India, Brazil, and Nigeria anchor procurement volume through centralized multi-year tenders, locking instrument manufacturers into service-contract pricing models that bundle reagent supply with preventive maintenance.
Pricing Analysis
Warranty and service bundling separates full-platform contracts from unbundled instrument-only sales in this market. Three-tier pricing structure across premium, standard, and economy levels reflects instrument throughput capacity and bioinformatics module inclusion. Cost compression in emerging-market tenders is intensifying because domestic manufacturing incentives under India's PLI scheme reduce import dependency. Public healthcare laboratories exhibit the highest price sensitivity due to fixed national health budgets, while academic medical centers in the United States and Western Europe prioritize expanded panel capabilities over unit economics.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme and Brazil's local procurement preferences are reshaping sourcing patterns for instrument assembly and reagent production. Manufacturing concentration centers on the United States, Germany, and China for tandem mass spectrometry systems, with isotope-labeled internal standards drawing from a limited supplier base in North America and Europe. Single-source vulnerability in specialized reagent supply exposes screening programs to availability risk. Distribution runs through direct sales teams for hospital-based accounts and tender-based procurement for public laboratory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a technology-transition phase where next-generation sequencing platforms are displacing standalone biochemical assays for expanded lysosomal storage disease panels.
For Market Incumbents: Deepen service contract penetration in public laboratory networks to lock out molecular diagnostic entrants. Expand captive production of isotope-labeled internal standards to neutralize reagent supply risk. Prioritize bioinformatics talent acquisition in Berlin-Brandenburg and Boston to defend interpretation service revenue against emerging sequencing specialists. For New Entrants and Emerging Players: ANVISA's risk-based classification pathways in Brazil open a window for simplified instrument platforms targeting decentralized heel prick collection networks. Target sub-Saharan Africa's point-of-care screening gap with dried blood spot logistics partnerships. Pursue WHO guideline alignment as the primary go-to-market credential for national program tenders in Nigeria and India. For Investors and Strategic Acquirers: The window for entry favors molecular diagnostic platform developers with established variant interpretation pipelines. Long-term viability hinges on capturing hospital-based screening migration in integrated US and UK health systems. Watch EU MDR clinical evidence requirement evolution as the signal for European market access timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | Expanded panel inclusion in national health benefit catalogs unlocks molecular diagnostic volume in Japan and Taiwan. |
| Hospital System Partnership | Vertical integration with Texas and Florida hospital networks captures margin from reference lab displacement. |
| CE Marking Pathway | Prospective clinical performance data generation aligns with EU MDR evidence thresholds for lysosomal storage disease kits. |
| Software Companion Development | Bioinformatics modules for variant interpretation address talent scarcity in emerging-market screening programs. |
| Strategic Partnership | Dried blood spot logistics alliances with Nigeria's regional hub network bypass cold chain infrastructure gaps. |
Research Methodology
Multi-period observation of tandem mass spectrometry installation rates and molecular diagnostic reimbursement decisions anchored the trend analysis, supplemented by interviews with laboratory directors, neonatologists, procurement officers at public health agencies, and regulatory affairs specialists at in vitro diagnostic manufacturers. Secondary validation drew from FDA premarket notification databases, EU MDR technical documentation requirements, WHO newborn screening guideline editions, and national health program tender records. Bottom-up instrument placement tracking and top-down healthcare expenditure modeling were triangulated against reagent volume commitments in multi-year service contracts.
Segment-weighting across product type, screening method, end user, and application dimensions shaped the analytical framework. CAGRs were derived from birth cohort projections, panel expansion timelines, and instrument refresh cycle patterns. Modeling incorporated WHO guideline adoption trajectories in low- and middle-income countries, EU MDR transition impacts on molecular kit launch schedules, and PLI scheme manufacturing capacity buildouts in India.
The model assumes a particular technology adoption path; alternative pathways for next-generation sequencing cost compression would alter the outlook for biochemical assay market share. Forecasts reflect assumptions about national program scaling velocity, reimbursement bandwidth expansion, and bioinformatics infrastructure deployment. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global GMP Testing Service Market
Testing Services
Instrument Calibration Services Market
Testing Services
Pancreatic Stone Protein Testing Market
Testing Services
Retrovirus Testing Market
Testing Services
Hemotransmissive Infections Testing Market
Testing Services
Global Rapid Test Market
Testing Services
Global Thyroid Function Test Market
Testing Services
Lipase Testing Reagents Market
Testing Services
Global Direct-To-Consumer (DTC)Testing Market
Testing Services
Phenytoin Testing Market
Testing Services
Ige Allergy Blood Tests Market
Testing Services
Radiographic Testing Market
Testing Services
Genetic Toxicology Testing Market
Testing Services
Addison Disease Testing Market
Testing Services
India GMP Testing Service Market
Testing Services
Global Medical Device Testing and Certification Market