
 Sterilization Equipment Market | 2026-2036
Sterilization Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Sterilization Equipment Market Analysis
Low-temperature hydrogen peroxide vapor systems is reconfiguring central sterile processing workflows in acute care facilities. STERIS leverages its installed base of vaporized hydrogen peroxide platforms to sustain service revenue streams across North American hospital networks. Getinge anchors its competitive position through integrated washer-disinfector and sterilizer suites that dominate European operating theater supply chains.
Sterilization equipment encompasses thermal, chemical, and radiation-based systems engineered to achieve defined sterility assurance levels, typically SAL 10^-6, for medical devices, pharmaceutical products, and laboratory materials. Steam sterilizers operate at saturated steam conditions of 121°C to 134°C with corresponding pressure cycles, making them the backbone of hospital central sterile supply departments where heat-stable instrument reprocessing dominates throughput. Hydrogen peroxide sterilizers command premium positioning in temperature-sensitive endoscope and robotic surgery instrument reprocessing, while ethylene oxide sterilizers retain structural importance for single-use device manufacturers navigating complex polymer compatibility matrices. Physical sterilization techniques, including steam and dry heat modalities, occupy the mature volume tier, whereas radiation sterilization extends into pharmaceutical packaging and implantable device terminal sterilization where chemical residuals are prohibited.
FDA 510(k) clearance pathways and EPA emissions standards for ethylene oxide sterilization facilities shape equipment design specifications and site permitting requirements for sterilization service providers. EMA Medical Device Regulation compliance and ISO 17665 steam sterilization validation protocols create parallel conformity demands for vendors accessing European healthcare procurement frameworks. Stakeholders must monitor evolving EPA ethylene oxide ambient air limits and state-level facility moratoriums that could accelerate capital redeployment toward alternative low-temperature modalities.
Market Dynamics
Central sterile processing departments are consolidating reprocessing workflows around single-platform hydrogen peroxide vapor systems to reduce footprint and labor intensity in space-constrained surgical facilities.
Growth Catalysts
- FDA 510(k) pathway streamlining:Expedited clearances for low-temperature sterilizers with enhanced cycle monitoring accelerate hospital capital replacement cycles for aging steam infrastructure.
- Robotic surgery instrument proliferation:Temperature-sensitive electromechanical components in da Vinci and competitor platforms mandate vapor-phase sterilization, expanding addressable equipment base.
- China hospital infrastructure expansion:Tier-3 city surgical center construction under the 14th Five-Year Plan drives sterilizer procurement for newly commissioned operating theaters.
Market Restraints
- Ethylene oxide supply concentration:EPA facility moratoriums in Illinois and Georgia restrict sterilization service capacity, creating regional bottlenecks for device manufacturers dependent on EtO terminal sterilization.
- Stainless steel input cost volatility:Chamber fabrication for steam sterilizers faces nickel price fluctuation exposure, compressing margins for mid-tier equipment vendors without captive metal sourcing.
- Heat-labile polymer incompatibility:PEEK and certain fluoropolymers degrade under standard steam cycles, forcing dual-modalities investment that extends facility commissioning timelines.
Strategic Opportunities
- India pharmaceutical manufacturing expansion:CDSCO GMP compliance deadlines for sterile injectables create demand for isolator-integrated sterilization suites in Hyderabad and Ahmedabad clusters.
- Gamma-to-e-beam conversion:Electron beam sterilization offers dose uniformity advantages for high-density medical device packaging, displacing cobalt-60 dependency in contract sterilization networks.
- EU MDR traceability mandates:Unique Device Identification requirements for reprocessed instruments create software-integrated sterilizer upgrade cycles with automated load documentation.
Industry Challenges
- Biomedical equipment technician specialization gap:Vaporized hydrogen peroxide system maintenance requires vendor-certified training that outpaces community college program development, extending service response times.
- Legacy steam infrastructure integration:Hospital networks with 1980s-era sterilizers face building code and utility incompatibility when retrofitting automated loading systems, forcing greenfield construction decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sterilization Equipment Market |
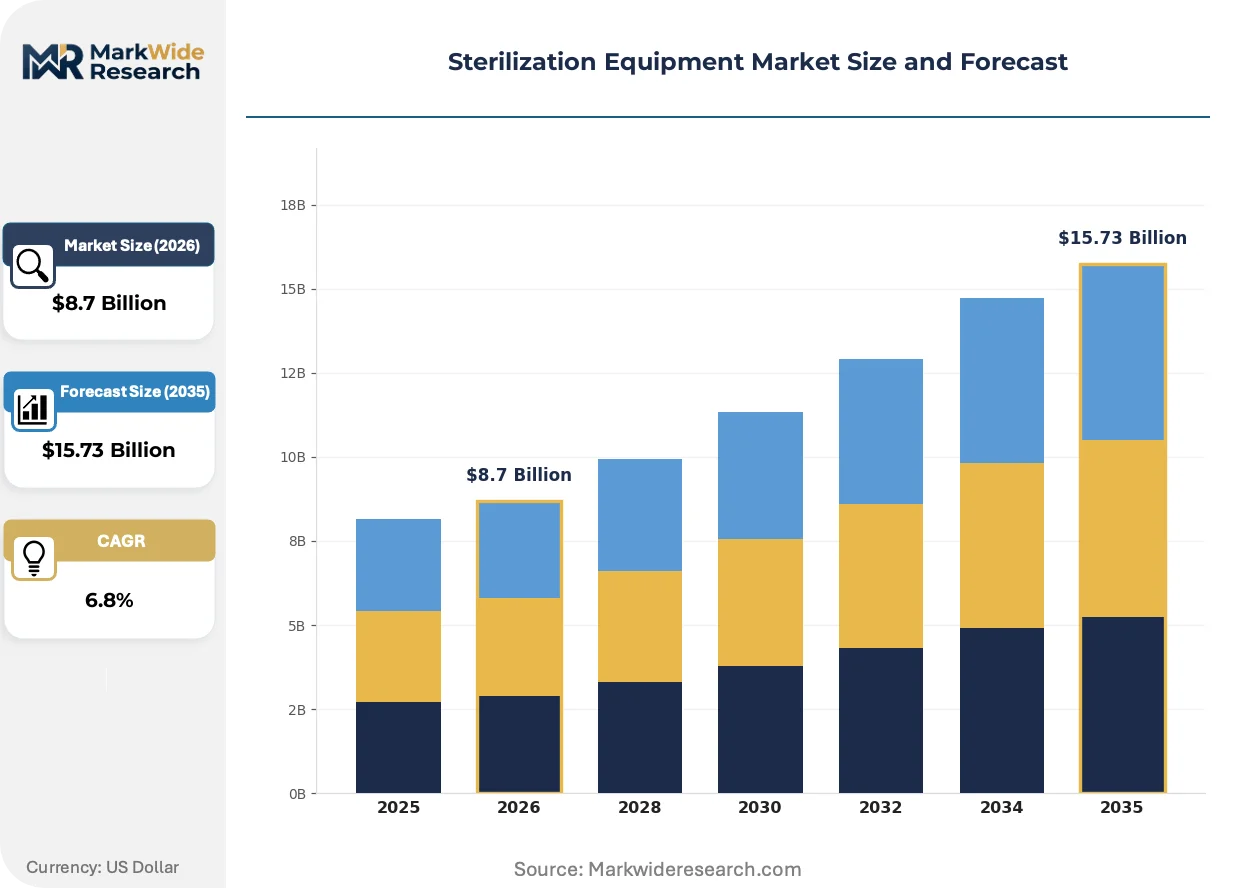
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steam Sterilizers, Ethylene Oxide Sterilizers, Hydrogen Peroxide Sterilizers, Dry Heat Sterilizers Technique: Physical Sterilization, Chemical Sterilization, Radiation Sterilization, Filtration Sterilization End User: Hospitals, Clinics, Pharmacies, Laboratories Application: Medical Instruments, Pharmaceuticals, Laboratory Equipment, Dental Instruments |
| Companies Covered | Fortive, Steelco S.p.A., STERIS, Belimed AG, MMM Group, Getinge, Sotera Health, MATACHANA, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sterilization Equipment Market Emerging Trajectories
Reprocessing workflows are converging around closed-loop systems that integrate cleaning, disinfection, and sterilization phases under unified control architectures rather than discrete equipment purchases.
Plasma-enhanced hydrogen peroxide sterilization is virtualizing traditional batch processing by enabling continuous-load architectures that eliminate chamber cooldown dead time. Ambulatory surgery centers in the United States are adopting these systems to match same-day discharge throughput requirements. The technology is virtualizing capital allocation patterns by compressing equipment-per-procedure ratios in high-volume outpatient settings.
EPA ethylene oxide emissions standards are tightening ambient air concentration limits for commercial sterilization facilities, forcing capital redeployment toward alternative modalities. Device manufacturers with EtO-dependent polymer portfolios face facility relocation or process revalidation costs. Single-use instrument producers in the United States are accelerating low-temperature vapor platform qualification to preempt supply continuity risk.
Hospital procurement committees are unbundling after-sales service contracts from equipment purchases, creating independent third-party maintenance markets. Original equipment manufacturers face margin compression as ISO 13485-certified service organizations capture multi-vendor maintenance contracts. German hospital purchasing cooperatives are pioneering this disaggregation, separating capital acquisition from decade-long service obligation structures.
Sterilization Equipment Market Segmentation
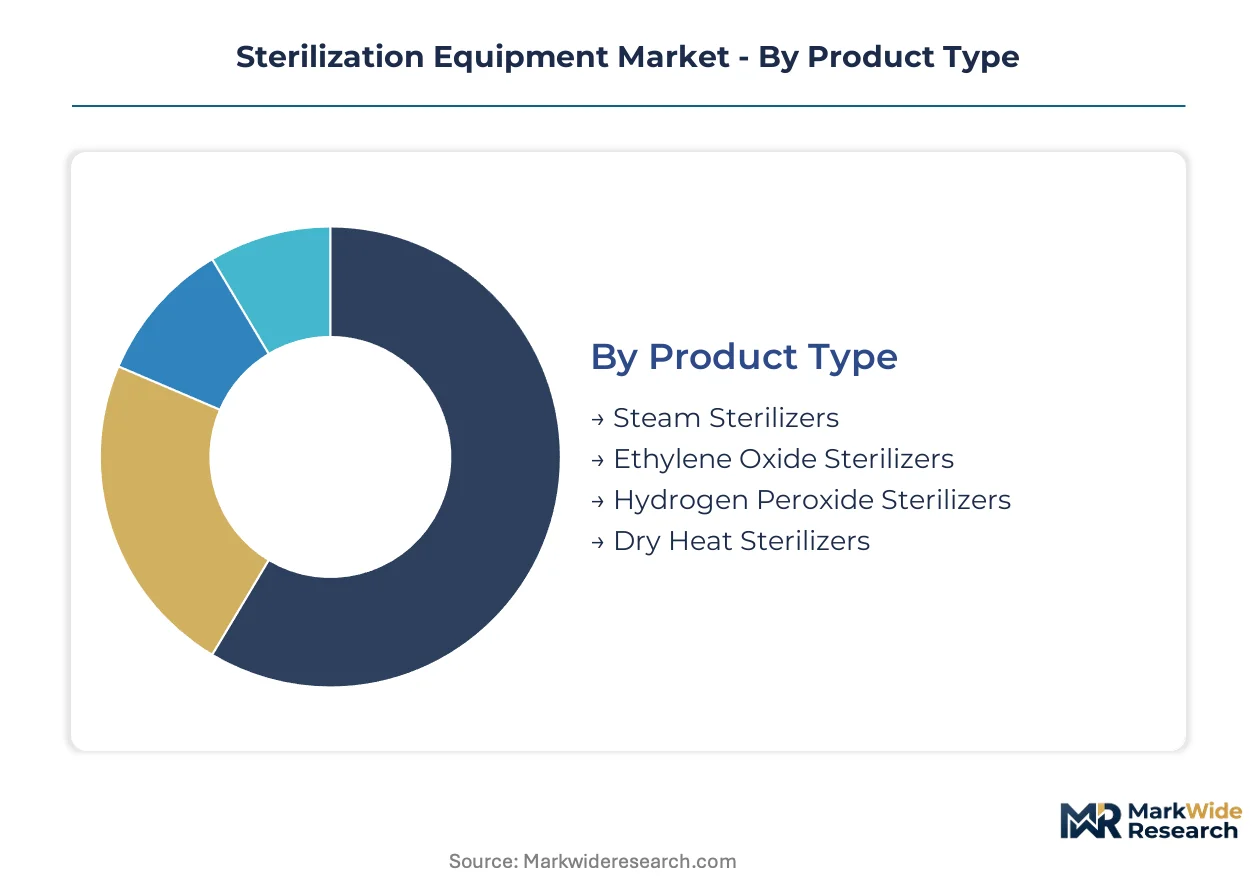
Sterilization equipment segmentation reveals divergent technology maturities and regulatory compliance burdens across healthcare and pharmaceutical value chains. Equipment specifications vary sharply between high-volume hospital central sterile processing and precision-driven pharmaceutical manufacturing environments.
Product Type:
Mature thermal platforms dominate installed base volumes while low-temperature chemical systems capture replacement cycles and capacity expansion.
- Steam Sterilizers:Saturated steam systems operating at 121°C to 134°C with pressure cycling remain the backbone of hospital central sterile supply departments. United States health systems deploy these for heat-stable surgical instrument reprocessing where throughput volume and operational simplicity outweigh temperature constraints.
- Ethylene Oxide Sterilizers:Gas-phase systems maintain structural importance for single-use medical device manufacturers navigating complex polymer compatibility matrices. EPA facility moratoriums in Illinois and Georgia restrict commercial sterilization capacity, forcing device producers toward alternative modalities or geographic relocation.
- Hydrogen Peroxide Sterilizers:Vapor-phase platforms command premium positioning for temperature-sensitive endoscope and robotic surgery instrument reprocessing.
- Dry Heat Sterilizers:Convection and conduction-based systems serve niche applications where moisture exposure risks instrument degradation.
Steam sterilizers retain volume leadership; hydrogen peroxide sterilizers hold the steepest expansion curve.
Technique:
Cost tier stratification separates capital-intensive radiation infrastructure from accessible thermal and chemical modalities.
- Physical Sterilization:Steam and dry heat modalities occupy the mature volume tier with established validation protocols and lower capital barriers. German hospital purchasing cooperatives prioritize these systems for standardized reprocessing workflows where regulatory compliance costs must be contained.
- Chemical Sterilization:Hydrogen peroxide vapor and ethylene oxide gas systems address heat-labile materials with higher operational complexity and regulatory scrutiny. FDA 510(k) pathway streamlining accelerates hospital capital replacement cycles for aging steam infrastructure.
- Radiation Sterilization:Gamma and electron beam systems extend into pharmaceutical packaging and implantable device terminal sterilization where chemical residuals are prohibited.
- Filtration Sterilization:Membrane-based systems serve biopharmaceutical aseptic processing for heat-sensitive liquid formulations.
Physical sterilization anchors the lowest cost tier; radiation sterilization commands the highest capital intensity per installed unit.
End User:
Customer type determines equipment specification complexity and service contract bundling preferences.
- Hospitals:Acute care facilities consolidate reprocessing workflows around automated sterilization systems to manage surgical throughput. China tier-3 city surgical center construction under infrastructure expansion plans drives sterilizer procurement for newly commissioned operating theaters.
- Clinics:Outpatient settings prioritize compact footprint and rapid cycle turnaround over batch volume capacity.
- Pharmacies:Compounding operations require isolator-integrated sterilization suites meeting CDSCO GMP compliance deadlines for sterile injectables in India.
- Laboratories:Research and diagnostic facilities demand flexible load configurations for diverse material types.
Hospitals concentrate the largest equipment procurement volumes; laboratories exhibit the most fragmented purchasing patterns.
Application:
Application-driven segmentation aligns with regulatory validation pathways and sterility assurance level requirements.
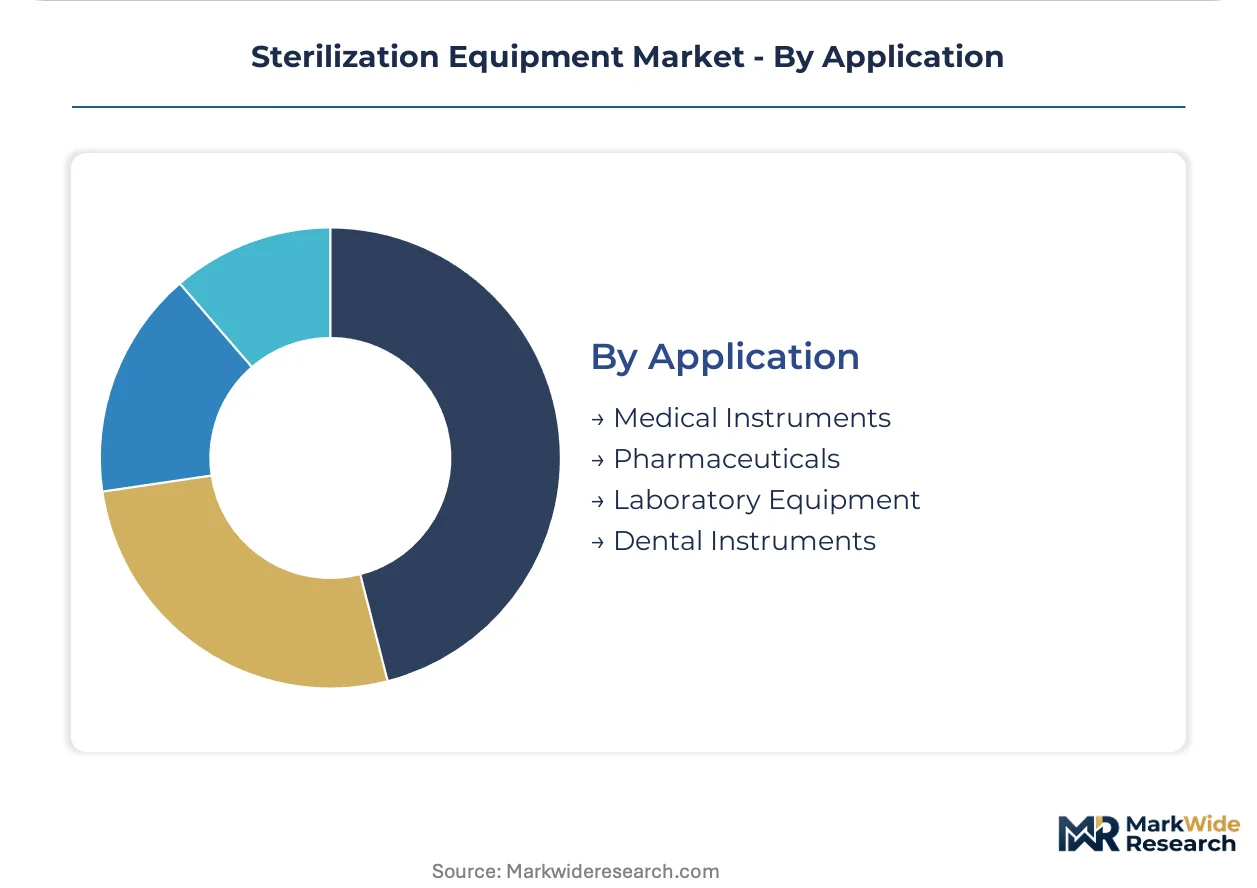
- Medical Instruments:Reusable surgical device reprocessing dominates equipment utilization rates with SAL 10^-6 validation mandates. Robotic surgery instrument proliferation with temperature-sensitive electromechanical components expands vapor-phase sterilization demand.
- Pharmaceuticals:Terminal sterilization of drug products and packaging materials requires modality selection matched to product stability profiles.
- Laboratory Equipment:Cell culture and analytical instrument sterilization demands precision cycle control.
- Dental Instruments:Smaller chamber volumes and accelerated cycles serve high-turnover outpatient oral surgery settings.
Medical instruments drive the highest equipment utilization intensity; pharmaceuticals impose the most stringent validation documentation burdens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German sterilization equipment manufacturers export vapor-phase systems to United States hospital networks expanding robotic surgery capacity. This transatlantic trade corridor reflects divergent infrastructure ages and regulatory compliance timelines.
United States
Hospital central sterile processing departments are automating reprocessing workflows to manage da Vinci surgical system throughput. EPA ethylene oxide emissions standards are tightening ambient air limits for commercial sterilization facilities in Illinois and Georgia. Chicago-area contract sterilizers face facility moratoriums that accelerate capital redeployment toward hydrogen peroxide vapor platforms.
Germany
Hospital purchasing cooperatives are unbundling after-sales service contracts from equipment acquisitions. EMA Medical Device Regulation compliance deadlines drive ISO 17665 steam sterilization validation protocol adoption. Baden-Württemberg manufacturing clusters supply washer-disinfector and sterilizer suites dominating European operating theater supply chains.
China
Tier-3 city surgical center construction under the 14th Five-Year Plan drives sterilizer procurement for newly commissioned operating theaters. NMPA medical device registration requirements are tightening equipment specifications for imported systems. Yangtze River Delta hospital infrastructure expansion concentrates demand for automated central sterile processing systems.
India
Pharmaceutical manufacturing clusters in Hyderabad and Ahmedabad are expanding isolator-integrated sterilization suites for sterile injectables production. CDSCO GMP compliance deadlines for active pharmaceutical ingredients create equipment procurement urgency. Maharashtra-based contract manufacturers are qualifying terminal sterilization capacity for export-oriented generic drug producers.
Japan
Aging hospital infrastructure replacement cycles are accelerating capital expenditure on low-temperature sterilization platforms. PMDA pharmaceutical manufacturing standards mandate validated sterilization processes for biologic drug packaging. Kansai-region medical device producers are qualifying electron beam alternatives to cobalt-60 gamma sterilization for implantable device terminal sterilization.
Sterilization Equipment Market Vendor Landscape
On the supply side, the industry is consolidating around integrated platform providers capable of delivering unified control architectures spanning cleaning through sterilization phases. Equipment vendors face procurement committee pressure to disaggregate hardware from decade-long service obligations. Two strategic archetypes dominate: diversified medical technology conglomerates with installed base leverage, and specialized sterilization equipment fabricators with validation expertise. Competitive intensity centers on M&A activity absorbing mid-tier regional players and strategic partnerships securing stainless steel supply chain access.
Among diversified medical technology conglomerates, Fortive and 3M occupy positions anchored by broad healthcare portfolio breadth. STERIS exemplifies the installed-base-leverage archetype through service revenue streams across North American hospital networks. Getinge represents the integrated-suite positioning dominating European procurement frameworks through washer-disinfector and sterilizer combinations.
| Leading Market Players |
|---|
| Fortive |
| Steelco S.p.A. |
| STERIS |
| Belimed AG |
| MMM Group |
| Getinge |
| Sotera Health |
| MATACHANA |
| 3M |
| Others |
Supply Flow & Price Mechanics
Overcapacity in European washer-disinfector fabrication is compressing margins for mid-tier vendors while concentrating pricing power among German manufacturers with captive stainless steel sourcing. This utilization asymmetry shapes procurement negotiations across hospital purchasing cooperatives and pharmaceutical manufacturing clusters.
Pricing Analysis
Current-generation hydrogen peroxide vapor platforms command substantial premiums over prior-generation steam sterilizers, while next-generation plasma-enhanced continuous-load systems are entering at premium-mid-economy pricing differentiation. The dominant structure is contract-based long-term offtake bundled with decade-long service obligations, though German hospital cooperatives are disaggregating these. Price differentiation rests on FDA 510(k) certification tier and after-sales service bundling. Cost compression in standard steam sterilizers is intensifying because nickel price volatility squeezes chamber fabrication margins. Ambulatory surgery centers exhibit highest price sensitivity due to capital constraints; pharmaceutical manufacturers show lowest sensitivity given GMP compliance imperatives.
Supply Chain Analysis
Upstream feedstock concentration in Swedish and Finnish stainless steel production anchors chamber fabrication costs for steam sterilizer manufacturers. Component sourcing draws from German precision valve suppliers, Chinese electronics assemblies, and Italian control system integrators. Supply chain risk centers on nickel price volatility from Indonesian ore processing concentration. Distribution runs through hospital GPO contracts in the United States, purchasing cooperatives in Germany, and direct government procurement in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is positioned for cyclical recovery as hospital infrastructure replacement cycles accelerate post-pandemic deferred capital expenditure. The 14th Five-Year Plan hospital construction in China provides the named cyclical driver.
For Market Incumbents: Entrench installed base leverage by extending vapor-phase platform service contracts into automated load documentation systems that satisfy EU MDR traceability mandates. Deepen backward integration into stainless steel supply through long-term offtake agreements with Nordic mills to neutralize nickel price volatility exposure. The threat is unbundling of service contracts by procurement committees; the lever is certification investment in ISO 13485 service capabilities. For New Entrants and Emerging Players: Build out isolator-integrated sterilization suites targeting Indian pharmaceutical manufacturing clusters in Hyderabad and Ahmedabad facing CDSCO GMP compliance deadlines. The most penetrable segment is contract sterilization services for generic drug exporters seeking terminal sterilization capacity qualification. The go-to-market angle is electron beam sterilization alternatives displacing cobalt-60 dependency. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among installed-base-leverage archetypes with multi-vendor service capabilities spanning steam, vapor-phase, and radiation modalities. Long-term viability favors platforms with unified control architectures integrating cleaning through sterilization phases. Target acquisition archetype: ISO 13485-certified service organizations capturing disaggregated maintenance contracts. The signal to watch is EPA ethylene oxide facility moratorium expansion accelerating capital redeployment toward low-temperature alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Service Contract Disaggregation | German purchasing cooperatives are separating capital acquisition from decade-long maintenance obligations. |
| Plasma-Enhanced Continuous-Load Qualification | Ambulatory surgery centers are adopting these systems to match same-day discharge throughput requirements. |
| Electron Beam Sterilization Conversion | Japanese medical device producers are qualifying e-beam alternatives to cobalt-60 gamma sterilization. |
| Isolator-Integrated Suite Expansion | Indian pharmaceutical clusters are expanding sterilization capacity for CDSCO GMP compliance deadlines. |
| Automated Load Documentation Integration | EU MDR traceability mandates are creating software-integrated sterilizer upgrade cycles. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EPA emissions compliance records, and hospital procurement databases. The research combined structured interviews with central sterile processing directors, biomedical equipment technicians, GPO contracts managers, and pharmaceutical manufacturing quality heads with validation against EMA Medical Device Regulation guidance documents, ISO 17665 sterilization standards, and customs trade data for equipment imports. Bottom-up equipment shipment analysis and top-down healthcare capital expenditure triangulation anchored market sizing.
Forecast inputs include surgical procedure volume trajectories, robotic surgery instrument proliferation rates, and regulatory compliance deadline schedules across the analysis window. The segmentation framework models product type, technique modality, end-user facility category, and application-specific sterility assurance level requirements. CAGRs were derived from equipment replacement cycle analysis and capacity expansion pipelines. Industry-specific inputs incorporate EPA ethylene oxide facility moratorium status and China 14th Five-Year Plan hospital construction targets.
The forecast holds incumbent behavior within observed patterns; aggressive moves by diversified medical technology conglomerates into third-party service markets would shift outcomes. Cross-checking against hospital capital expenditure surveys and pharmaceutical manufacturing capacity announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Medication Pouch Inspection Systems Market
Medical Equipment
Medical Air Sterilizer Market
Medical Equipment
Mercury Thermometer Market
Medical Equipment
Medical Ultrasonic Baths Market
Medical Equipment
Tissue Processing Systems Market
Medical Equipment
North America Medical Automation Market
Medical Equipment
Bone Marrow Processing Systems Market
Medical Equipment
Blood Bank Refrigerators Market
Medical Equipment
Global Ultra Low Temperature Freezers Market
Medical Equipment
Auditory Brainstem Response Analyzers Market
Medical Equipment
Equine Operating Tables Market
Medical Equipment
Medical Ethylene Oxide Sterilization Equipment Market
Medical Equipment
Biomedical Refrigerators and Freezers Market
Medical Equipment
ECG Equipment and Management Systems Market
Medical Equipment
US Radiotherapy Market
Medical Equipment
Global Blood Viscometer Market