
 Medical Automation Market | 2026-2036
Medical Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Automation Market Intelligence
Software-as-a-Service (SaaS) subscription models for clinical workflow automation is broadening the market's value proposition beyond initial hardware sales. Siemens Healthineers leverages its extensive diagnostic imaging portfolio to integrate automated analysis tools. Intuitive Surgical dominates the robotic surgery segment with its proprietary systems and training ecosystems. Medtronic competes across a diverse range of automated medical devices, from insulin pumps to surgical instruments, positioning itself in multiple end-user settings.
Medical automation applies robotics, artificial intelligence, and information technologies to streamline tasks in healthcare settings, enhancing efficiency and patient safety. These systems are designed to achieve high precision, such as reducing medication dispensing errors to near-zero levels. Within the product landscape, robotic surgery systems command high capital investment from hospitals. Laboratory automation, however, represents a more mature segment with wide adoption in high-volume diagnostic laboratories.
The regulatory environment is stringent, with the US FDA's 510(k) and PMA pathways governing device clearance. In Europe, the Medical Device Regulation (MDR) imposes strict requirements for clinical evidence and post-market surveillance. These frameworks shape product development cycles and data security protocols. Stakeholders must now decide whether to prioritize investments in on-premise hardware or scalable cloud-based platforms for future data integration needs.
Market Dynamics
The central force shaping the medical automation market is the acute pressure on healthcare systems to increase diagnostic throughput and accuracy. This demand is driven by global clinician shortages and the need for data integration between disparate laboratory and imaging systems to support value-based care models.
Growth Catalysts
- Artificial Intelligence in Diagnostics:The integration of AI and machine learning algorithms into pathology and radiology workflows enhances diagnostic precision and accelerates analysis, meeting demands from high-volume clinical laboratories for greater efficiency.
- Aging Demographics:An expanding elderly population in developed countries like Japan and Germany increases the prevalence of chronic diseases, spurring demand for automated systems in surgery, medication management, and patient monitoring.
- Focus on Lab Efficiency:Diagnostic laboratories are investing in total laboratory automation (TLA) systems to reduce manual errors, shorten turnaround times, and manage rising sample volumes with a limited workforce.
Market Restraints
- High Capital Investment:The substantial upfront cost of robotic surgical systems and comprehensive laboratory automation platforms remains a significant barrier for smaller hospitals and independent clinics with constrained capital budgets.
- Interoperability and Data Standards:A lack of universal communication protocols between automated devices from different manufacturers creates data silos, complicating efforts to build fully integrated and seamless clinical workflows.
- Stringent Regulatory Hurdles:The rigorous clinical validation and documentation required by regulatory bodies, such as the US FDA's PMA pathway and Europe's MDR, extend development timelines and increase costs.
Strategic Opportunities
- Decentralized Point-of-Care Automation:Developing smaller, automated diagnostic platforms for use in clinics, pharmacies, and physician offices presents an opportunity to move testing closer to the patient, beyond the central lab.
- Cloud-Based Analytics Platforms:The expansion of SaaS models for data management and workflow automation enables vendors to offer scalable solutions with lower upfront costs, broadening access for mid-sized healthcare facilities.
- Automation in Emerging Markets:Healthcare infrastructure modernization in countries like Brazil and India creates new growth avenues for vendors of diagnostic and therapeutic automation systems as facilities seek to improve care standards.
Industry Challenges
- Cybersecurity Risks in Connected Devices:The increasing network connectivity of medical automation systems exposes them to potential data breaches and operational disruptions, demanding robust security protocols compliant with rules like HIPAA.
- Specialized Talent Shortages:A deficit of technicians, engineers, and data scientists with the skills to operate, maintain, and interpret data from sophisticated automation systems can limit their effective deployment.
- Integrating with Legacy Infrastructure:Many hospitals face significant technical and financial challenges in integrating new automation technologies with existing, often outdated, information systems and physical layouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Automation Market |
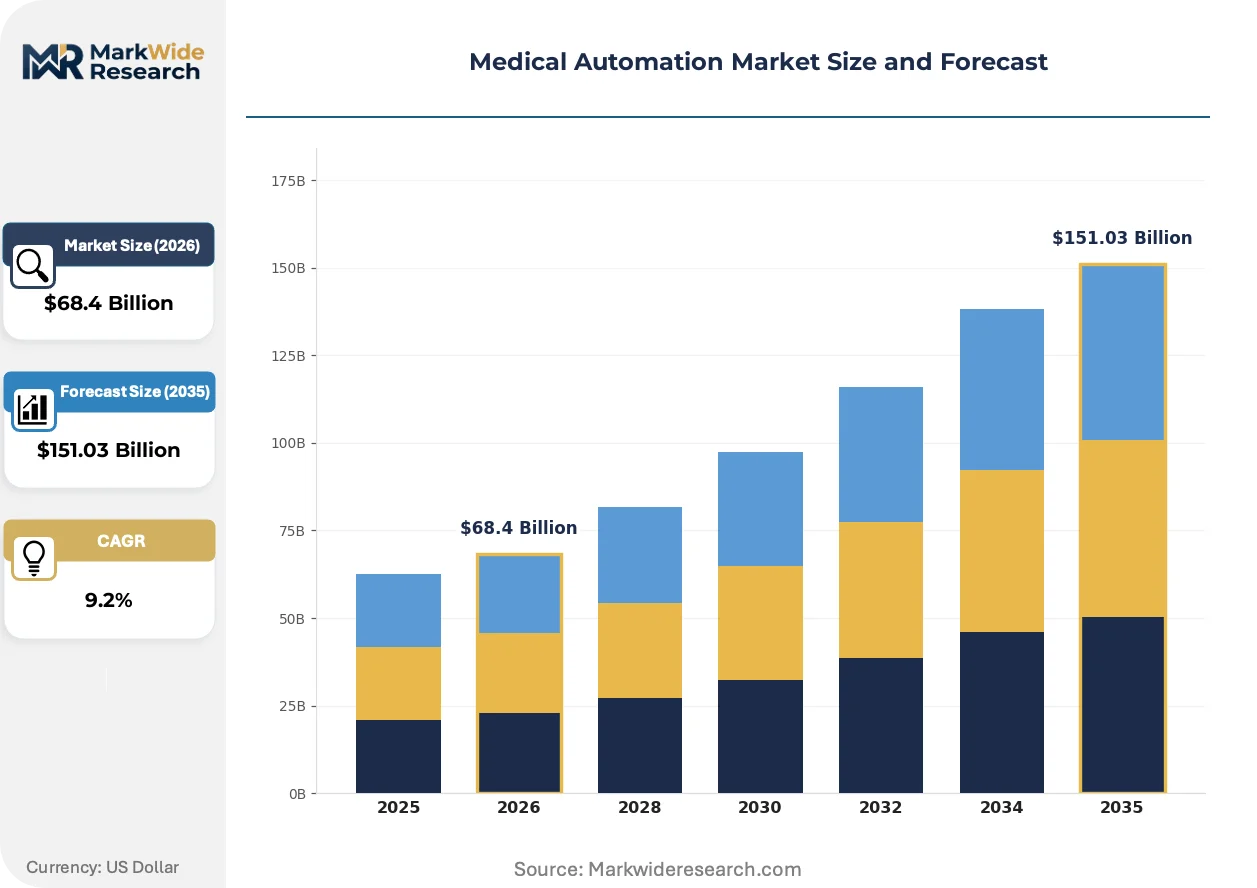
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $151.03 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Surgery Systems, Pharmacy Automation, Diagnostic Automation, Laboratory Automation, Clinical Workflow Automation Application: Surgical Procedures, Medication Dispensing, Sample Analysis, Patient Monitoring, Medical Imaging End User: Hospitals, Diagnostic Laboratories, Ambulatory Surgical Centers, Pharmaceutical Distributors, Rehabilitation Centers Deployment: Cloud-Based Platforms, On-Premise Systems, Hybrid Solutions, Edge Computing |
| Companies Covered | GE Healthcare, Labcorp Holdings, Medtronic, Teladoc Health, Agilent Technologies, Intuitive Surgical, Abbott Laboratories, Accenture, Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Automation Market Strategic Shifts & Innovations
The convergence of cloud platforms and artificial intelligence is fundamentally altering medical automation. This shift moves the focus from standalone hardware efficiency toward integrated, data-driven clinical decision support systems that enhance diagnostic and therapeutic pathways across the care continuum.
AI-powered analytics software provides advanced image interpretation and workflow optimization. Large hospital networks and diagnostic chains are adopting these tools to handle increasing test volumes with greater accuracy. This technology is consolidating previously siloed data from pathology, radiology, and laboratory instruments into unified platforms for analysis.
Europe's Medical Device Regulation (MDR) imposes stricter requirements for clinical evidence and continuous post-market surveillance. This framework compels manufacturers to invest more heavily in data collection and risk management throughout the product lifecycle. The regulation most acutely affects software-as-a-medical-device (SaMD) and high-risk robotic systems seeking CE marking.
A preference for operational expenditure (OpEx) models over large capital expenditure (CapEx) is altering procurement patterns. Healthcare providers are increasingly adopting subscription or pay-per-use contracts for automation systems, disrupting the traditional one-time sales model for capital equipment. This shift is most prominent in the United States and Germany where budget flexibility is prioritized.
Medical Automation Market Segmentation
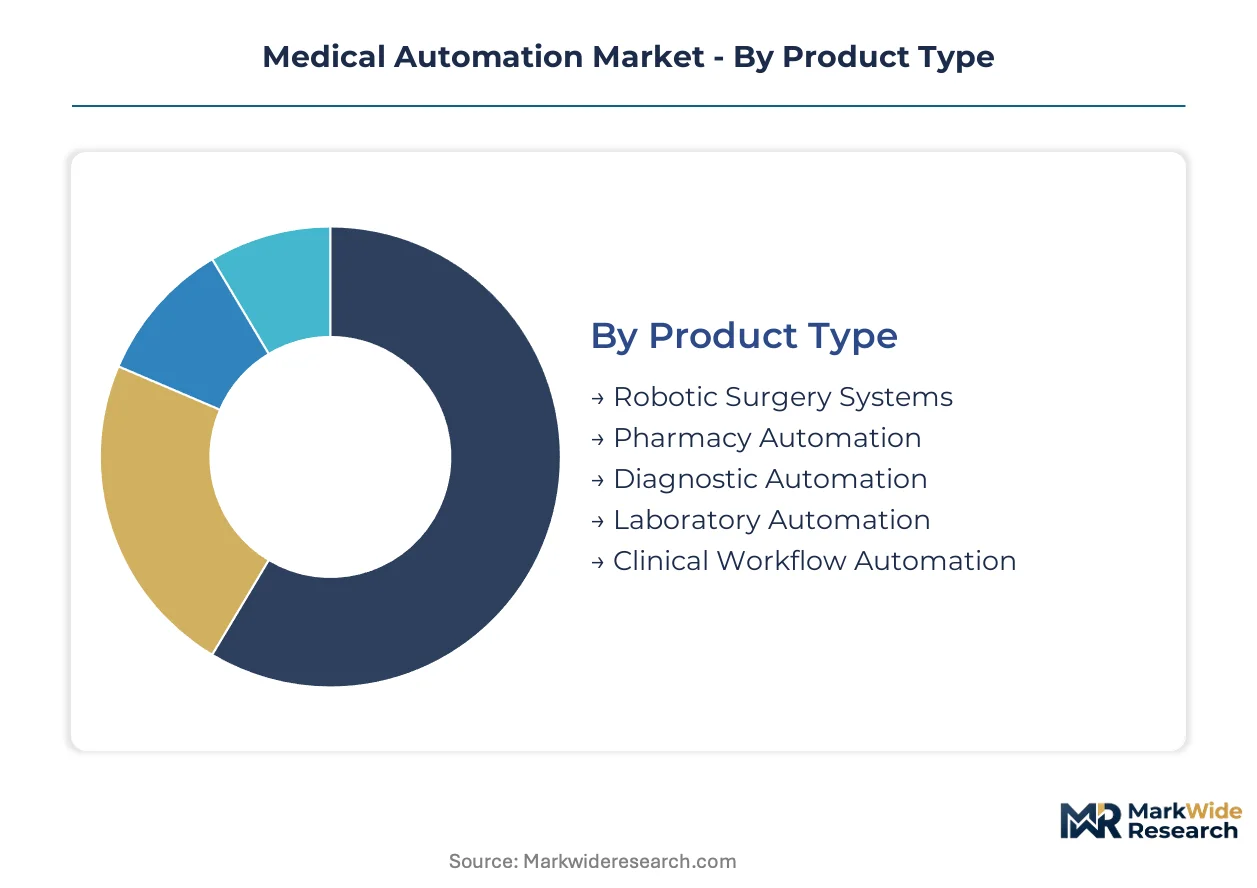
The medical automation market segmentation provides a granular view of how diverse technologies and solutions address specific needs across the healthcare continuum. This breakdown helps stakeholders understand where investment is concentrated and how different product types and deployment models serve various end-user requirements.
Product Type:
The segmentation by product type elucidates how medical automation solutions span from high-precision surgical tools to integrated laboratory systems, catering to diverse operational needs and investment capacities.
- Robotic Surgery Systems:These advanced platforms integrate robotic arms, specialized instruments, and 3D visualization for minimally invasive procedures. Demand concentrates in large hospital networks in the United States, driven by improved patient outcomes and reduced recovery times.
- Laboratory Automation:Comprehensive systems automate sample handling, preparation, and analysis across various diagnostic disciplines. High-volume diagnostic laboratories in Germany are adopting these solutions to manage increasing test throughput and reduce manual errors.
- Pharmacy Automation:Solutions for medication dispensing, inventory management, and compounding, enhancing safety and efficiency in hospital and retail pharmacies.
- Diagnostic Automation:Automated instruments and software for interpreting diagnostic tests, including pathology and radiology, supporting faster and more accurate diagnoses.
- Clinical Workflow Automation:Software-driven tools that streamline administrative and clinical processes, such as scheduling, patient intake, and documentation, across healthcare facilities.
Mature deployment sits with Laboratory Automation. Newer deployment is concentrated in Clinical Workflow Automation.
Application:
Application segmentation highlights the specific clinical processes where automation delivers efficiency and safety improvements across the patient journey.
- Surgical Procedures:This application involves the use of robotic systems and advanced imaging for precise interventions. Hospitals prioritize these solutions for complex cardiovascular and orthopedic surgeries, enhancing surgical accuracy.
- Sample Analysis:Automated platforms process biological samples for diagnostic testing, including pathology and clinical chemistry. Large reference laboratories leverage these systems to accelerate turnaround times for high-volume tests.
- Medication Dispensing:Automated systems manage the storage, preparation, and distribution of pharmaceuticals, minimizing errors in hospital and outpatient settings.
- Patient Monitoring:Automated devices and software continuously track vital signs and other physiological data, providing real-time insights for patient care and early intervention.
- Medical Imaging:AI-powered tools and automated workflows enhance the acquisition, processing, and interpretation of medical images like X-rays, CT scans, and MRIs.
Operational efficiency gains are most established in Medication Dispensing. Patient Monitoring represents an area of rapidly expanding automation.
End User:
End-user segmentation reveals distinct adoption patterns across healthcare facilities, influenced by their scale, service offerings, and capital expenditure capabilities.
- Hospitals:These institutions are primary users of diverse medical automation, from robotic surgery to pharmacy systems. Large hospital systems in Japan invest heavily to manage an aging population and clinician shortages.
- Diagnostic Laboratories:Centralized and decentralized labs utilize automation for high-throughput sample processing and analysis. European diagnostic chains adopt these systems to meet stringent regulatory requirements and improve diagnostic accuracy.
- Ambulatory Surgical Centers:Outpatient facilities performing surgical procedures, increasingly integrating automation for efficiency and precision in specific specialties.
- Pharmaceutical Distributors:Companies involved in the supply chain of medicines, using automation for warehousing, packaging, and logistics to ensure timely delivery.
- Rehabilitation Centers:Facilities focused on patient recovery and therapy, employing automated devices for physical therapy, mobility assistance, and continuous monitoring.
Hospitals remain the largest consumer segment. Ambulatory Surgical Centers are demonstrating a climbing adoption rate.
Deployment:
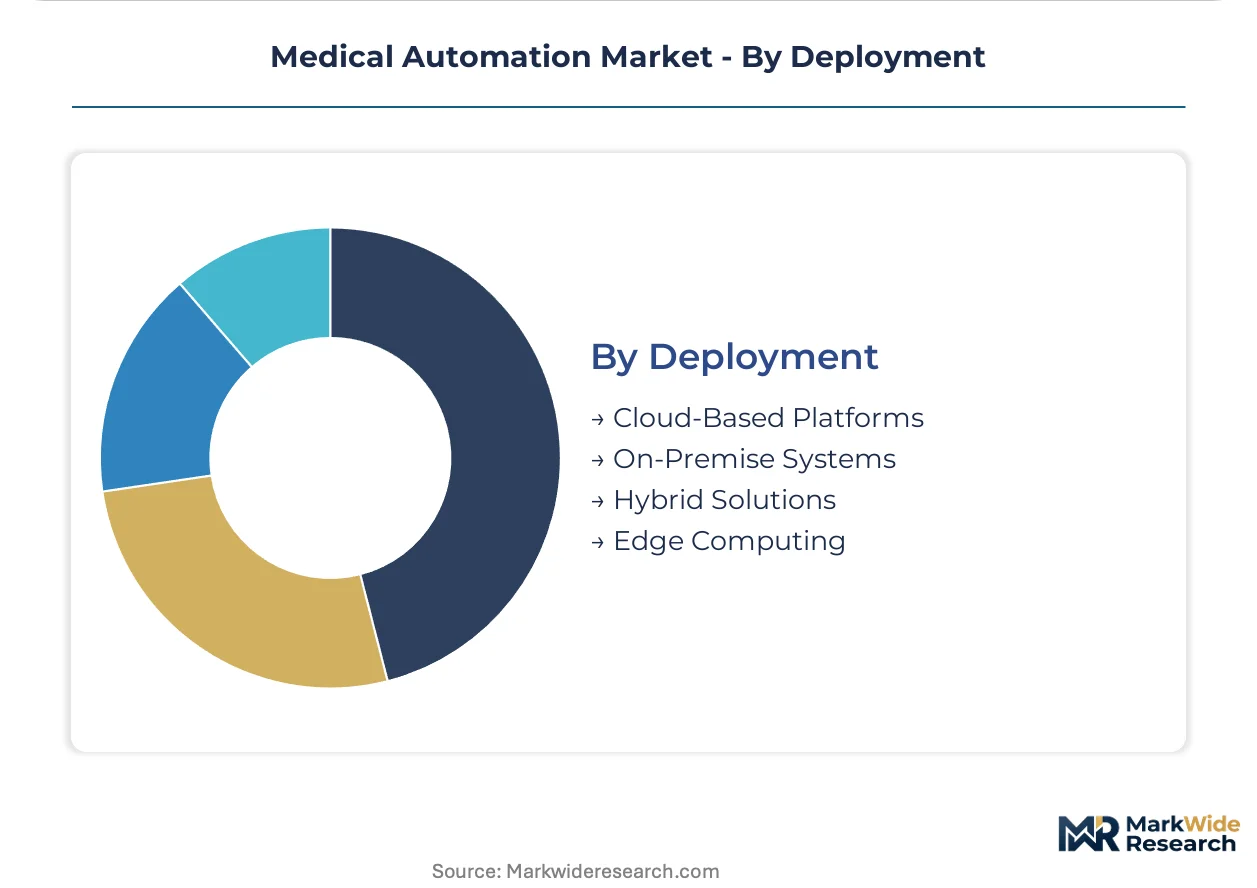
The deployment model segmentation distinguishes between infrastructure choices, reflecting varying preferences for data control, scalability, and operational expenditure across healthcare providers.
- Cloud-Based Platforms:These solutions offer scalable software and data analytics accessible via the internet, reducing upfront hardware costs. Mid-sized clinics in the United States increasingly adopt cloud solutions for workflow automation and data integration.
- On-Premise Systems:Automation hardware and software are installed directly within the healthcare facility, providing direct data control and security. Large university hospitals often prefer on-premise solutions for their existing IT infrastructure and sensitive patient data.
- Hybrid Solutions:A combination of cloud and on-premise components, offering flexibility to store sensitive data locally while leveraging cloud scalability for other functions.
- Edge Computing:Processing data closer to the source of generation, such as within a medical device, reducing latency and improving real-time decision-making for critical applications.
Traditional On-Premise Systems maintain significant market presence. Cloud-Based Platforms are experiencing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's vibrant biotech and medical device cluster drives significant innovation in medical automation, attracting substantial investment and talent. This region benefits from a strong research ecosystem and proximity to leading healthcare institutions. The demand for advanced diagnostic and surgical solutions concentrates here.
United States
Demand for increased diagnostic throughput and advanced surgical systems fuels medical automation in the United States. The US FDA's 510(k) and PMA pathways govern device clearance, shaping product development. California's Silicon Valley remains a hub for AI-powered diagnostic software and cloud-based platforms.
Germany
Germany's aging demographics and focus on lab efficiency accelerate the adoption of automated systems. Europe's Medical Device Regulation (MDR) imposes strict requirements for clinical evidence and post-market surveillance. Munich's medical technology sector sees significant investment in total laboratory automation.
Japan
An expanding elderly population in Japan creates sustained demand for automated medication management and patient monitoring solutions. The country's Ministry of Health, Labour and Welfare (MHLW) oversees medical device approvals, emphasizing patient safety. Tokyo's large hospital networks are integrating robotic surgery systems to address clinician shortages.
India
India's healthcare infrastructure modernization efforts open new growth avenues for diagnostic and therapeutic automation. The Central Drugs Standard Control Organization (CDSCO) regulates medical devices, supporting local manufacturing. Bengaluru's burgeoning tech industry facilitates the development of cloud-based analytics platforms for healthcare.
Medical Automation Market Key Industry Players
Capital-heavy producers compete with asset-light designers for market share in medical automation, creating a dynamic competitive environment. The market exhibits a tiered structure, with established conglomerates alongside specialized innovators. Strategic archetypes include integrated solution providers, niche technology developers, and platform-focused software companies that cater to specific healthcare needs. Portfolio diversification, geographic expansion, and strategic partnerships remain dominant competitive moves for market participants seeking sustained growth.
Integrated solution providers such as Siemens Healthineers, with its extensive diagnostic imaging portfolio, represent a significant market segment for automated analysis tools. Intuitive Surgical anchors the robotic surgery segment through its proprietary systems and comprehensive training ecosystems, maintaining a strong position in high-precision interventions. Medtronic exemplifies a diversified player, competing across a broad range of automated medical devices, from insulin pumps to surgical instruments, in various end-user settings. These companies illustrate the spectrum from specialized high-capital equipment to broad-based device portfolios.
| Leading Market Players |
|---|
| GE Healthcare |
| Labcorp Holdings |
| Medtronic |
| Teladoc Health |
| Agilent Technologies |
| Intuitive Surgical |
| Abbott Laboratories |
| Accenture |
| Siemens Healthineers |
| Others |
Cost & Logistics Intelligence
Large hospital networks' procurement patterns influence pricing models, increasingly favoring operational expenditure over upfront capital outlays for medical automation systems. This shift enables broader access and flexible budget management.
Pricing Analysis
Value-based pricing, linking system costs to improved patient outcomes or diagnostic throughput, increasingly defines medical automation procurement. SaaS subscription models offer flexibility, while differentiation stems from advanced feature sets and comprehensive after-sales support. Pricing softness affects mature laboratory automation, driven by competition, but novel robotic surgery systems command premium pricing. Smaller clinics demonstrate higher price sensitivity compared to large hospital networks.
Supply Chain Analysis
Dual-sourcing requirements for critical components mitigate risks in the medical automation supply chain, which concentrates manufacturing expertise in the United States, Germany, and Japan. The industry relies on specialized sensors, precision robotics components, and high-performance computing chips. Single-source vulnerability for proprietary technologies presents a structural risk. Distribution runs through direct sales teams and specialized medical device distributors reaching healthcare facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The medical automation market presents a supply-constrained growth story, with a persistent shortage of specialized technical talent acting as a key capacity bottleneck. This talent scarcity props up service pricing and limits deployment speed for complex systems.
For Market Incumbents: Lock in existing customer bases through comprehensive training ecosystems and integrated service contracts. Acquire specialized AI software firms to counter the threat from agile SaMD entrants. Invest in R&D for next-generation AI integration to maintain technological leadership. Strengthen channel control by offering full-suite solutions, making competitive displacement more challenging.
For New Entrants and Emerging Players: Enter via niche segments like decentralized point-of-care automation, targeting underpenetrated clinics and pharmacies. Focus on cloud-based analytics platforms for mid-sized healthcare facilities in the United States, offering scalable solutions. Leverage SaaS models with lower upfront costs as a compelling go-to-market strategy. Address specific workflow gaps within existing legacy infrastructure for rapid adoption.
For Investors and Strategic Acquirers: The window for entry favors strategic acquirers seeking long-term growth driven by aging demographics and persistent healthcare efficiency demands over the next decade. Target specialized AI/ML firms or SaMD developers with validated clinical evidence and strong intellectual property. Watch for accelerated FDA or Europe's MDR clearance of novel AI-powered diagnostic tools as a key inflection indicator. Prioritize companies demonstrating strong interoperability with existing hospital systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Secures long-term deployment channels for robotic surgery and laboratory automation systems. |
| SaaS Companion Development | Expands recurring revenue streams by integrating cloud-based analytics with hardware sales. |
| CE Marking Pathway Acceleration | Facilitates market entry and broader adoption across European diagnostic chains under MDR. |
| AI-Powered Diagnostic Software Launch | Enhances diagnostic accuracy and throughput, meeting demands from high-volume clinical laboratories. |
| Decentralized Point-of-Care Platform Development | Addresses market white-space by moving testing closer to patients in clinics and pharmacies. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, providing foundational market intelligence. Primary research involved structured interviews with clinicians, hospital purchasing committees, biomedical engineers, and diagnostic lab managers. This approach combined insights from industry experts with quantitative data for bottom-up and top-down triangulation. Academic research databases and GPO contracts further validated initial findings.
Market sizing and forecast models were built at the granular level across product type, application, end user, deployment, and regional regulatory clusters. Compound annual growth rates were derived from historical trends and projected growth drivers over the analysis window. Key forecast inputs included technological advancements in artificial intelligence and evolving healthcare expenditure patterns. This framework ensured a comprehensive market outlook.
Forecast precision tightens around the base case; tail outcomes carry wider variance under significant regulatory shifts or unforeseen technological disruptions. The projections reflect assumptions about healthcare policy stability and continued investment in automation. Deviation in major cybersecurity incidents or FDA/MDR pathway changes would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Minor Surgical Lights Market
Medical Equipment
Global Oxygen Flow Meters Market
Medical Equipment
Medication Pouch Inspection Systems Market
Medical Equipment
Dialyzer Reprocessing Machines and Concentrates Market
Medical Equipment
Global Indirect Calorimeter Market
Medical Equipment
Dialysis Equipment Market
Medical Equipment
US ECG Equipment Market
Medical Equipment
Durable Medical Equipment Rental Market
Medical Equipment
Cryopreservation Systems Market
Medical Equipment
Europe Medical Equipment Maintenance Market
Medical Equipment
Medical Pediatric Bed Market
Medical Equipment
Europe Nuclear Medicine Equipment Market
Medical Equipment
Nuclear Medicine Equipment Market
Medical Equipment
Global Medical Refrigerators Market
Medical Equipment
Autoclaves Market
Medical Equipment
CO2 Medical Laser Systems Market