
 MRI-Guided Cardiac Ablation Market | 2026-2036
MRI-Guided Cardiac Ablation Market Size, Share, and Industry Trends Forecast 2026-2036
MRI-Guided Cardiac Ablation Market Foresight
A shift from outsourced imaging partnerships toward in-house MRI suite integration is recalibrating capital deployment across electrophysiology departments. Medtronic leverages its integrated hardware-software ecosystem to anchor premium system placements in North American academic medical centers. Siemens Healthineers competes through proprietary magnet technology that sustains image resolution during radiofrequency energy delivery. Boston Scientific differentiates via catheter compatibility breadth that spans multiple imaging platform architectures.
MRI-guided cardiac ablation denotes a therapeutic intervention wherein real-time magnetic resonance imaging visualizes myocardial tissue during energy delivery, enabling lesion assessment at magnetic field strengths of 1.5 or 3.0 Tesla with active catheter tracking. The procedure's primary purpose is to treat drug-refractory arrhythmias through thermally mediated tissue destruction while avoiding esophageal injury and pulmonary vein stenosis. Catheters command the dominant product revenue share due to disposable recurring consumption, while ablation platforms represent the fastest-growing capital segment as hospitals replace legacy electroanatomic mapping systems. Radiofrequency technology leads procedural volume globally, though cryoablation gains traction in centers prioritizing contiguous lesion sets for paroxysmal atrial fibrillation.
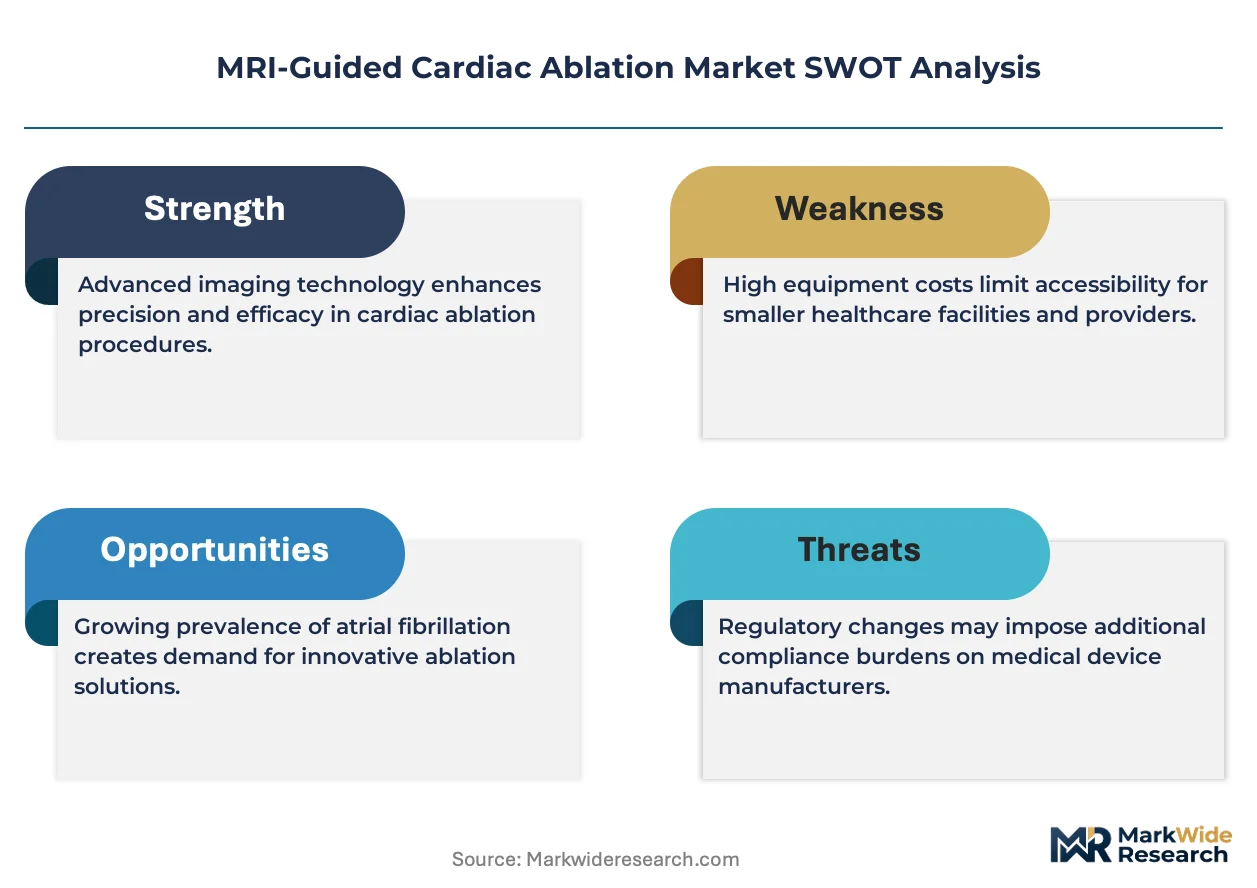
FDA premarket notification pathways and EU MDR conformity assessments shape product development timelines and clinical evidence requirements for device manufacturers seeking commercial access. ISO 13485 quality management standards and IEC 60601-1-2 electromagnetic compatibility specifications govern design controls for MRI-conditional ablation instruments. Stakeholders must monitor evolving reimbursement coding for real-time MRI-guided procedures versus conventional electroanatomic mapping to determine capital allocation priorities.
Market Dynamics
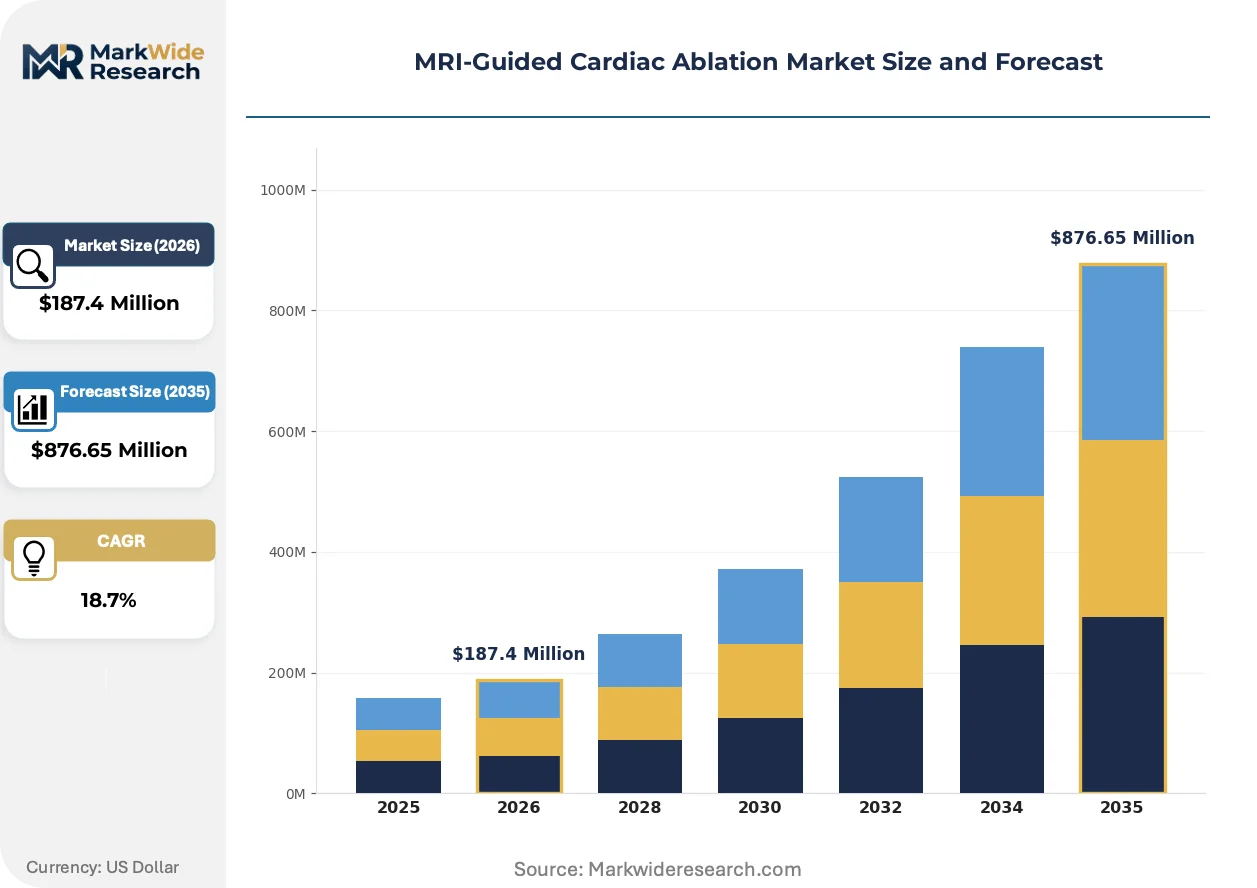
The transition from electroanatomic mapping to real-time MRI visualization is restructuring capital allocation across electrophysiology departments, with hospitals consolidating imaging infrastructure to capture procedural margins previously lost to radiology outsourcing.
Growth Catalysts
- EU MDR CE marking pathways:Streamlined conformity assessments for breakthrough devices accelerate commercial access timelines for MRI-conditional ablation systems in European tertiary hospitals.
- Radiofrequency energy delivery:Mature thermometry feedback loops enable precise lesion control, driving procedural adoption in academic medical centers seeking reproducible outcomes.
- Japan's reimbursement frameworks:Mature coverage policies for advanced cardiac interventions reduce patient out-of-pocket burdens and expand addressable procedure volumes.
Market Restraints
- Superconducting magnet supply concentration:Cryogen-dependent magnet manufacturing clusters in Germany and Japan create vulnerability to helium price volatility and export license delays.
- FDA premarket notification friction:510(k) pathways for novel catheter designs require extensive electromagnetic compatibility testing, extending development cycles by 12-18 months.
- Cryoablation substitution pressure:Balloon-based cryothermal systems offer contiguous lesion sets with simpler workflow, threatening RF catheter volumes in paroxysmal atrial fibrillation cases.
Strategic Opportunities
- India's tertiary hospital expansion:Greenfield electrophysiology lab construction in Mumbai and Delhi creates first-mover positioning for integrated MRI-ablation suite vendors.
- Active catheter tracking convergence:Fusion of microcoil localization with machine learning-based motion compensation enables sub-millimeter precision during respiratory cycle variation.
- US Medicare add-on payment codes:Emerging reimbursement distinctions for real-time MRI-guided procedures versus conventional mapping reward technology differentiation.
Industry Challenges
- Electrophysiologist MRI safety certification:Scarcity of clinicians dual-trained in cardiac ablation and Zone IV magnetic field management limits procedural throughput expansion.
- Legacy EP recorder integration:Proprietary data formats from established mapping systems resist interoperability with MRI console architectures, forcing costly middleware development.
- IEC 60601-1-2 electromagnetic compliance:Evolving immunity test levels for 3.0 Tesla environments require iterative hardware redesigns that compress margin structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MRI-Guided Cardiac Ablation Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $876.65 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Catheters, Ablation Platforms, Imaging Systems, Accessories Technology: Radiofrequency, Cryoablation, Microwave, Laser Application: Arrhythmia Treatment, Cardiac Mapping, Postoperative Monitoring, Imaging End User: Hospitals, Cardiac Clinics, Research Institutions, Outpatient Facilities |
| Companies Covered | Medtronic, Johnson & Johnson MedTech, Boston Scientific, Abbott Laboratories, AtriCure, Imricor Medical Systems, Stereotaxis, Philips, Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MRI-Guided Cardiac Ablation Market Shifts & Advancements
Real-time thermometry and active catheter tracking are converging to enable closed-loop ablation control, eliminating the latency between energy delivery and tissue response assessment that constrains conventional electrophysiology workflows.
Artificial intelligence-based respiratory motion prediction is expanding into cardiac MRI sequences, compensating for myocardial displacement during radiofrequency delivery. Tertiary hospitals in Germany and the United States are deploying these algorithms to reduce gating artifacts and shorten procedure times. The compression of imaging-procedure integration cycles is forcing legacy electroanatomic mapping vendors to accelerate MRI compatibility roadmaps.
FDA breakthrough device designations are creating regulatory fast lanes for thermally-mediated arrhythmia interventions, compressing premarket review timelines for systems demonstrating superior esophageal safety profiles. Manufacturers are prioritizing clinical evidence packages that isolate pulmonary vein isolation durability metrics. Academic medical centers in the United States are responding by expanding investigator-initiated trial infrastructure to capture real-world performance data.
Hospital purchasing committees are unbundling catheter procurement from capital platform agreements, demanding compatibility certifications across multiple magnet manufacturers. This fragmentation of sourcing decisions is visible most acutely in United States integrated delivery networks seeking to avoid single-vendor lock-in. Electrophysiology departments are responding by establishing technical evaluation working groups that span cardiology, radiology, and biomedical engineering functions.
MRI-Guided Cardiac Ablation Market Segmentation
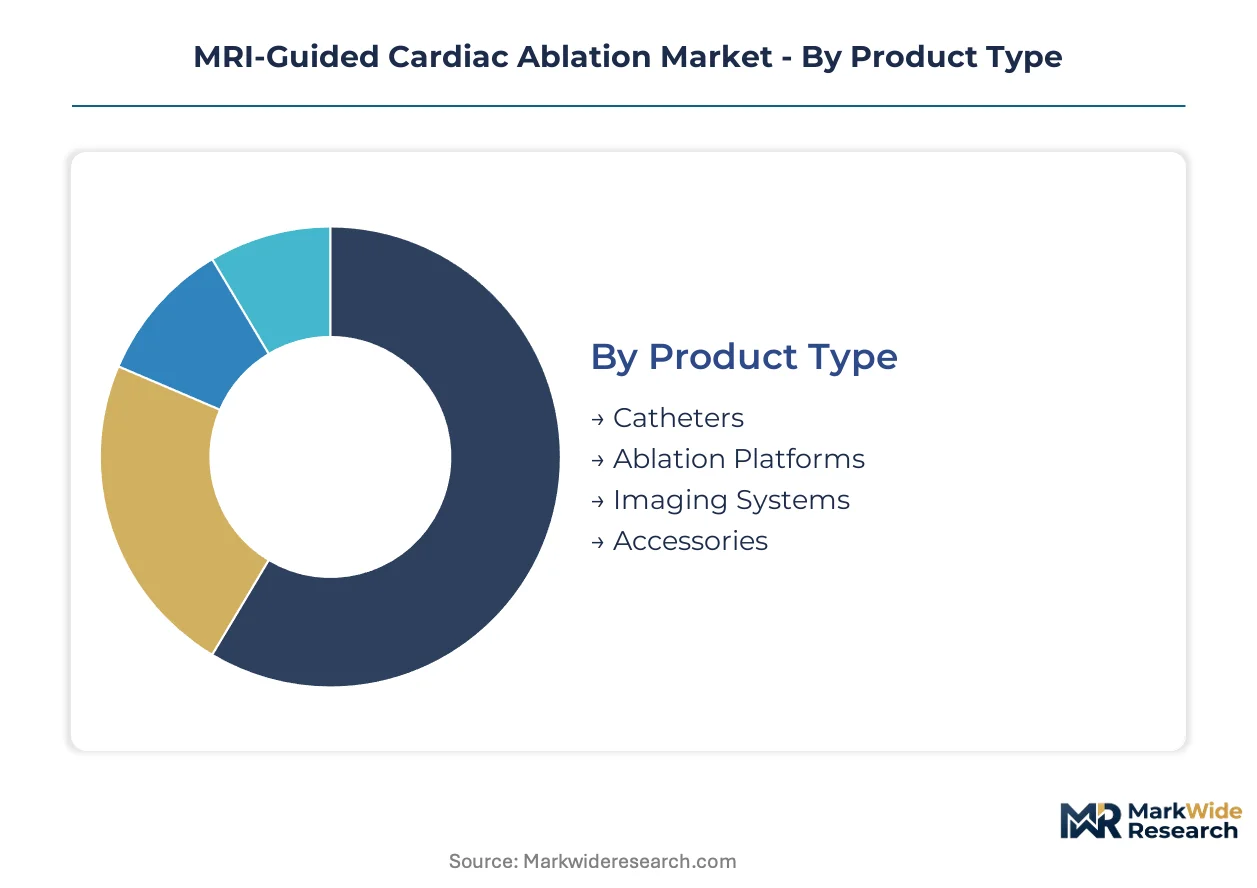
Procurement committees in electrophysiology departments weigh capital intensity against recurring revenue streams when structuring vendor contracts. The segmentation below maps how purchasing power distributes across product categories, energy modalities, clinical applications, and facility types.
Product Type:
Hospital capital committees prioritize total cost of ownership calculations that balance upfront magnet investment against disposable catheter replenishment schedules.
- Catheters:MRI-conditional ablation catheters incorporate microcoil tracking elements and thermocouple arrays compatible with 1.5 and 3.0 Tesla fields. Demand clusters in United States academic medical centers where high procedure volumes justify premium disposable pricing. Recurring procurement contracts dominate vendor negotiations.
- Ablation Platforms:Integrated hardware-software systems combine radiofrequency generators with real-time MRI console interfaces. German and Japanese tertiary hospitals lead replacement cycles as legacy electroanatomic mapping systems age out. Capital budgeting cycles extend 5-7 years, slowing penetration relative to disposables.
- Imaging Systems:Dedicated cardiac MRI scanners with EP-conditional magnet configurations.
- Accessories:Patient coils, surface electrodes, and sterile draping systems.
Volume sits with Catheters; growth tilts toward Ablation Platforms.
Technology:
Energy modality selection follows lesion geometry requirements and operator training pathways rather than equipment cost alone.
- Radiofrequency:Resistive heating through unipolar or bipolar electrode configurations enables point-by-point lesion creation with real-time impedance feedback. United States procedural volume concentrates in academic centers seeking durable pulmonary vein isolation outcomes. Thermometry integration with MRI sequences drives adoption.
- Cryoablation:Balloon-based cryothermal delivery produces contiguous circumferential lesions through phase-change cooling. Japanese reimbursement frameworks favor simplified workflows for paroxysmal atrial fibrillation cases. Single-shot efficiency appeals to centers with constrained electrophysiologist availability.
- Microwave:Electromagnetic field heating at 915 MHz or 2.45 GHz frequencies.
- Laser:Optical energy delivery through fiberoptic catheter channels.
Radiofrequency commands installed base; Cryoablation gains share fastest in streamlined workflow environments.
Application:
Clinical utility expands from therapeutic intervention toward diagnostic mapping and post-procedural surveillance.
- Arrhythmia Treatment:Therapeutic ablation for drug-refractory atrial fibrillation, atrial flutter, and ventricular tachycardia. United States hospital systems prioritize pulmonary vein isolation durability metrics for value-based contracting. Real-time lesion visualization reduces redo procedure rates.
- Cardiac Mapping:Anatomical and electrophysiological substrate characterization prior to energy delivery. German electrophysiology labs integrate MRI mapping with conventional electroanatomic systems for complex substrate cases. Pre-procedural planning shortens fluoroscopy exposure.
- Postoperative Monitoring:Follow-up imaging to assess lesion maturation and detect pulmonary vein reconnection.
- Imaging:Diagnostic cardiac MRI without concurrent ablation intervention.
Arrhythmia Treatment absorbs majority utilization; Cardiac Mapping climbs the fastest as pre-procedural planning protocols standardize.
End User:
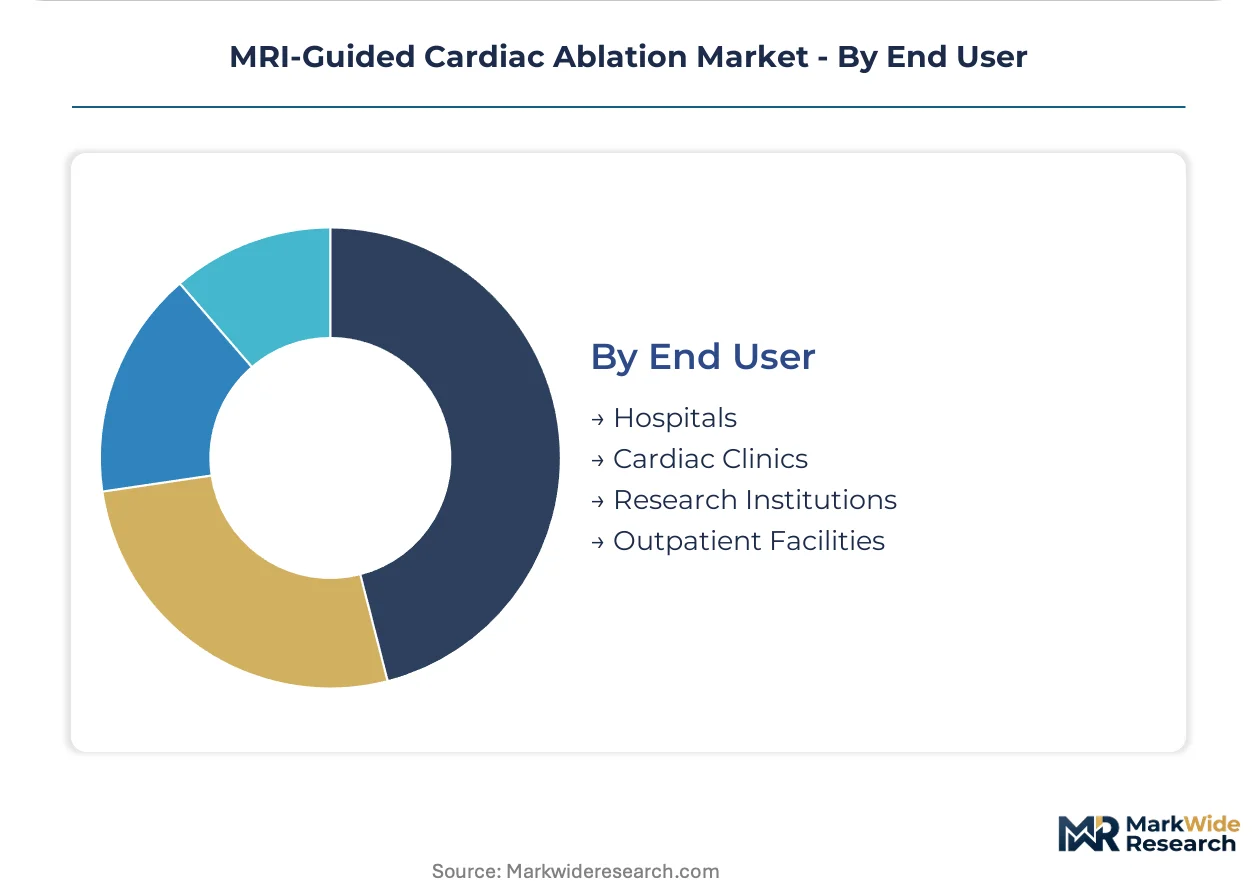
Facility type determines reimbursement capture, capital availability, and regulatory compliance burden.
- Hospitals:Tertiary and academic medical centers with on-site MRI suites and 24-hour electrophysiology coverage. United States integrated delivery networks consolidate advanced ablation services to capture add-on reimbursement codes. Infrastructure requirements exclude smaller community facilities.
- Cardiac Clinics:Specialized ambulatory surgical centers with focused electrophysiology programs. German outpatient cardiac centers expand MRI-guided service lines under DRG reimbursement incentives. Partnership arrangements with radiology providers enable magnet access without capital ownership.
- Research Institutions:Investigator-initiated trial sites and device development programs.
- Outpatient Facilities:Freestanding surgical centers with limited overnight capacity.
Hospitals anchor revenue concentration; Cardiac Clinics represent the steepest expansion trajectory as ambulatory migration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Helium refining capacity in Qatar and the United States underpins superconducting magnet supply chains for MRI-guided ablation platforms. Cryogen logistics networks radiate from Doha and Kansas to manufacturing clusters in Germany and Japan. Regional demand patterns reflect tertiary hospital infrastructure maturity and reimbursement sophistication.
United States
Medicare add-on payment codes for real-time MRI-guided procedures drive hospital capital allocation toward integrated EP-MRI suites. FDA breakthrough device designations compress premarket review timelines for thermally-mediated arrhythmia systems. The Cleveland Clinic and Mayo Clinic anchor investigator-initiated trial networks capturing real-world durability metrics.
Germany
EU MDR conformity assessments under streamlined pathways accelerate CE marking for MRI-conditional ablation catheters. DRG reimbursement incentives favor outpatient cardiac center expansion of MRI-guided service lines. Munich and Heidelberg host electrophysiology research consortia advancing active catheter tracking algorithms.
Japan
METI procurement standards for advanced medical equipment subsidize 3.0 Tesla magnet installations in prefectural hospitals. PMDA consultation programs reduce regulatory uncertainty for novel thermometry-integrated systems. Tokyo and Osaka academic medical centers lead cryoablation adoption for paroxysmal atrial fibrillation workflows.
India
CDSCO medical device registration reforms shorten import approval timelines for MRI-conditional EP instruments. PLI scheme incentives for domestic manufacturing attract joint ventures for catheter assembly. Mumbai and Delhi greenfield electrophysiology lab construction creates first-mover positioning for integrated suite vendors.
MRI-Guided Cardiac Ablation Market Competitive Landscape
Strategic partnerships dominate the current landscape as hardware manufacturers align with imaging platform vendors to secure catheter compatibility certifications. The vendor base stratifies across integrated system architects, specialized catheter developers, and magnet technology suppliers. Three archetypes prevail: diversified medtech conglomerates with EP recorder legacy positions; pure-play MRI-conditional device specialists; and imaging OEMs extending into therapeutic integration. Portfolio diversification and technology licensing represent the primary competitive vectors, with geographic expansion into India's tertiary hospital sector accelerating.
Within the diversified medtech tier, Medtronic and Johnson & Johnson MedTech exemplify integrated hardware-software ecosystem strategies anchoring premium placements in North American academic centers. Boston Scientific occupies a position spanning catheter compatibility breadth across multiple magnet architectures. Siemens Healthineers represents the imaging OEM archetype, leveraging proprietary magnet technology to sustain resolution during radiofrequency delivery. These three anchors illustrate the competitive tension between disposable recurring revenue capture and capital platform control.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson MedTech |
| Boston Scientific |
| Abbott Laboratories |
| AtriCure |
| Imricor Medical Systems |
| Stereotaxis |
| Philips |
| Siemens Healthineers |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up catheter specialists have consolidated manufacturing footprints across Minnesota and Massachusetts, tightening working capital discipline while anchoring premium pricing through exclusive service contracts with United States academic medical centers.
Pricing Analysis
Warranty and service-bundling unbundling distinguishes capital platform transactions from disposable catheter procurement. Three-tier pricing structure across premium, standard, and economy levels segments buyers by procedure volume and magnet field strength requirements. Price differentiation hinges on ISO 13485 certification tier and active catheter tracking compatibility breadth. Cost compression in mid-tier ablation platforms is intensifying because hospital purchasing committees demand cross-manufacturer interoperability certifications. Community hospitals with constrained electrophysiology volumes exhibit highest price sensitivity; tertiary academic centers with bundled GPO contracts demonstrate lowest.
Supply Chain Analysis
Single-source vulnerability sits with niobium-titanium superconducting wire suppliers concentrated in Germany and Japan. Cryogen logistics networks draw from Qatar and Kansas helium refining capacity to feed magnet manufacturing clusters in Erlangen and Tokyo. Raw material dependencies encompass liquid helium, rare-earth magnetic alloys, and biocompatible catheter polymers. Tariff exposure on Chinese-sourced thermocouple arrays threatens margin structures for disposable component suppliers. Distribution runs through radiology equipment distributors with EP-specific technical service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is accelerating as FDA electromagnetic compatibility testing requirements extend development cycles beyond 18 months, forcing subscale catheter developers toward strategic exits.
For Market Incumbents: Acquire active catheter tracking algorithm portfolios to neutralize machine-learning-based respiratory motion compensation threats from imaging OEMs. Backward integration into niobium-titanium wire supply through offtake agreements with German and Japanese superconductor manufacturers secures magnet cost visibility. Lock in 5-7 year exclusive catheter supply contracts with United States integrated delivery networks before reimbursement coding distinctions mature. For New Entrants and Emerging Players: CDSCO registration reforms in India open a window for greenfield electrophysiology lab partnerships in Mumbai and Delhi without legacy electroanatomic mapping baggage. Target cardiac clinic ambulatory surgical centers in Germany seeking radiology partnership arrangements rather than capital-intensive magnet ownership. Lead with cryoablation catheter compatibility certifications for simplified paroxysmal atrial fibrillation workflows. For Investors and Strategic Acquirers: FDA breakthrough device designation announcements are the leading indicator that premarket review timelines have compressed sufficiently to justify premium valuations. Position for 5-10 year holding periods centered on reimbursement distinction durability between real-time MRI-guided and conventional electroanatomic mapping procedures. Monitor electrophysiologist dual-training certification expansion rates as throughput ceiling signal.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR streamlined conformity assessments accelerate commercial access timelines for MRI-conditional systems. |
| Hospital System Partnership | United States integrated delivery network exclusive supply contracts lock out competing catheter vendors. |
| Software Companion Development | Machine learning-based respiratory motion prediction algorithms shorten procedure times in German tertiary centers. |
| Reimbursement Strategy | Medicare add-on payment code distinctions reward technology differentiation for real-time MRI-guided procedures. |
| Backward Integration | Captive niobium-titanium wire supply from German and Japanese sources insulates against helium price volatility. |
Research Methodology
FDA 510(k) filings, EU MDR technical documentation, and CMS Medicare reimbursement coding databases formed the secondary backbone, cross-referenced against primary interviews with electrophysiologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers. Bottom-up procedure volume estimates from United States, German, and Japanese tertiary hospitals were triangulated against top-down capital equipment shipment data from magnet manufacturers.
Historical trendline analysis of electroanatomic mapping system replacement cycles informed platform penetration assumptions across the analysis window. Segmentation modeling incorporated product type, energy modality, clinical application, and facility tier dimensions. CAGRs were derived from weighted average procedure growth projections and capital budgeting cycle patterns, with specific inputs from PMDA consultation program timelines and METI procurement standard revisions.
Caveats apply where helium export license delays or electrophysiologist certification bottlenecks could materially shift the outlook for procedural throughput expansion. Forecasts reflect documented assumptions regarding reimbursement coding stability and EU MDR conformity assessment pathway continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Implantable Drug Infusion Pumps Market
Cardiovascular Devices
Arterial Stabilization Device Market
Cardiovascular Devices
Cardiac Assist Devices Market
Cardiovascular Devices
Global Angio Suites Market
Cardiovascular Devices
Heart Valves Market
Cardiovascular Devices
Cardiovascular Stents Market
Cardiovascular Devices
Global Sclerotherapy Market
Cardiovascular Devices
Global Advanced Balloon Catheter Market
Cardiovascular Devices
Infusion System Market
Cardiovascular Devices
Endovascular Aneurysm Repair Market
Cardiovascular Devices
Single-Use Hemoperfusion Device Market
Cardiovascular Devices
Europe Heart Valve Repair and Replacement Market
Cardiovascular Devices
3D Cardiac Mapping Systems Market
Cardiovascular Devices
Centrifugal Blood Pumps Market
Cardiovascular Devices
Umbilical Vessel Catheters Market
Cardiovascular Devices
Saphenous Vein Grafts Market