
 Chemotherapy-Induced Nausea and Vomiting Therapeutics Market | 2026-2036
Chemotherapy-Induced Nausea and Vomiting Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Chemotherapy-Induced Nausea and Vomiting Therapeutics Market Outlook
Oncology outpatient centers is shifting toward same-day infusion models that require more reliable delayed-phase nausea control. Merck & Co., Inc. leverages its long-standing 5-HT3 franchise to sustain hospital formulary presence across North American cancer centers. Helsinn Group specializes in NK1 receptor antagonist innovation and dominates the premium prophylactic segment in European markets. Heron Therapeutics, Inc. differentiates through extended-release delivery platforms that reduce rescue medication dependence in high-emetic-risk chemotherapy cycles.
Chemotherapy-induced nausea and vomiting therapeutics comprise pharmaceutical agents that antagonize serotonin, substance P, or corticosteroid pathways to prevent or treat emesis following cytotoxic drug administration, with formulations requiring precise pharmacokinetic matching to acute-phase onset (0-24 hours) versus delayed-phase persistence (24-120 hours) after cisplatin or anthracycline-based regimens. The primary commercial purpose centers on enabling complete chemotherapy dose delivery while preserving patient nutritional status and treatment adherence. NK1 receptor antagonists now anchor the highest-margin pool in the product type dimension as combination regimens with palonsetron become standard-of-care for highly emetogenic protocols. Oral delivery mode leads volume share due to homecare expansion, though subcutaneous formulations are capturing the fastest growth trajectory among patients with swallowing difficulties or severe breakthrough episodes. Breakthrough nausea indication segments command premium pricing due to rescue-therapy failure rates and the clinical urgency of maintaining chemotherapy schedules.
FDA, EMA, and NMPA each enforce distinct bioequivalence and safety surveillance standards that shape clinical trial design costs and post-market pharmacovigilance obligations for antiemetic developers seeking multi-region approval. The EU MDR and FDA's oncology supportive care guidance documents increasingly demand head-to-head non-inferiority data against established three-drug combinations, raising barriers for novel mechanism entrants. Stakeholders must monitor evolving payer evidence requirements for prophylactic versus rescue therapy positioning as value-based oncology contracts expand.
Market Dynamics
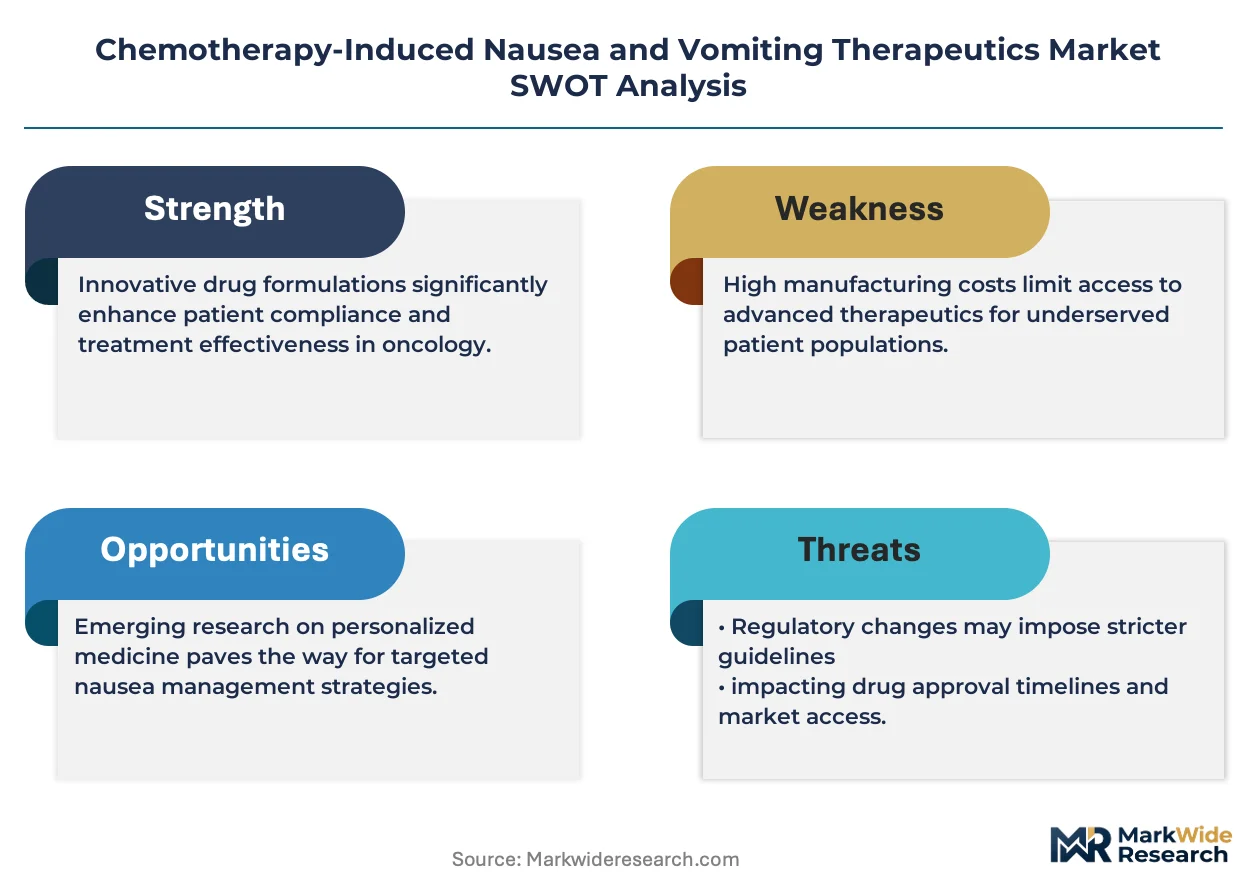
The shift toward same-day chemotherapy infusion models is compressing the window for effective antiemetic intervention, forcing pharmacokinetic redesign of delayed-phase formulations to prevent rescue medication dependency.
Growth Catalysts
- EMA oncology supportive care guidance:Tightened efficacy thresholds for three-drug combination approvals are accelerating head-to-head clinical trial investment, elevating standard-of-care benchmarks across European cancer centers.
- Homecare administration expansion:Oral antiemetic formulations are capturing volume share as outpatient chemotherapy protocols reduce hospital bed utilization, particularly in United States and Japanese markets.
- Subcutaneous delivery platforms:Needle-based administration is addressing swallowing difficulties in high-emetic-risk patients, opening access for geriatric and head-and-neck cancer populations previously excluded from oral prophylaxis.
Market Restraints
- API supply concentration:Palonosetron and aprepitant active pharmaceutical ingredients rely on concentrated Chinese and Indian manufacturing, exposing formulators to import tariff volatility and geopolitical disruption.
- Non-inferiority trial costs:FDA and EMA requirements for head-to-head comparison against established three-drug regimens inflate clinical development budgets, discouraging novel mechanism entrants.
- Generic 5-HT3 antagonist substitution:Patent-expired ondansetron continues to displace premium prophylactic regimens in cost-constrained payer environments, compressing margin pools for branded innovators.
Strategic Opportunities
- German ambulatory oncology networks:Underpenetrated same-day infusion centers present white-space demand for extended-release antiemetic platforms that reduce nursing intervention frequency.
- NMPA regulatory harmonization:China's alignment with ICH efficacy standards creates accelerated approval pathways for NK1 receptor antagonist combinations previously validated in Western markets.
- Digital adherence monitoring:Integration of wearable nausea severity tracking with automated rescue medication dispensing addresses the 40% underreporting rate of breakthrough symptoms in homecare settings.
Industry Challenges
- Pharmacokinetic matching complexity:Cisplatin-based regimens require precise acute-phase versus delayed-phase coverage, forcing formulators to maintain dual inventory SKUs with distinct stability profiles.
- Reimbursement evidence generation:Payer value-based oncology contracts demand real-world data on chemotherapy completion rates, requiring costly post-market surveillance infrastructure beyond traditional safety monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemotherapy-Induced Nausea and Vomiting Therapeutics Market |
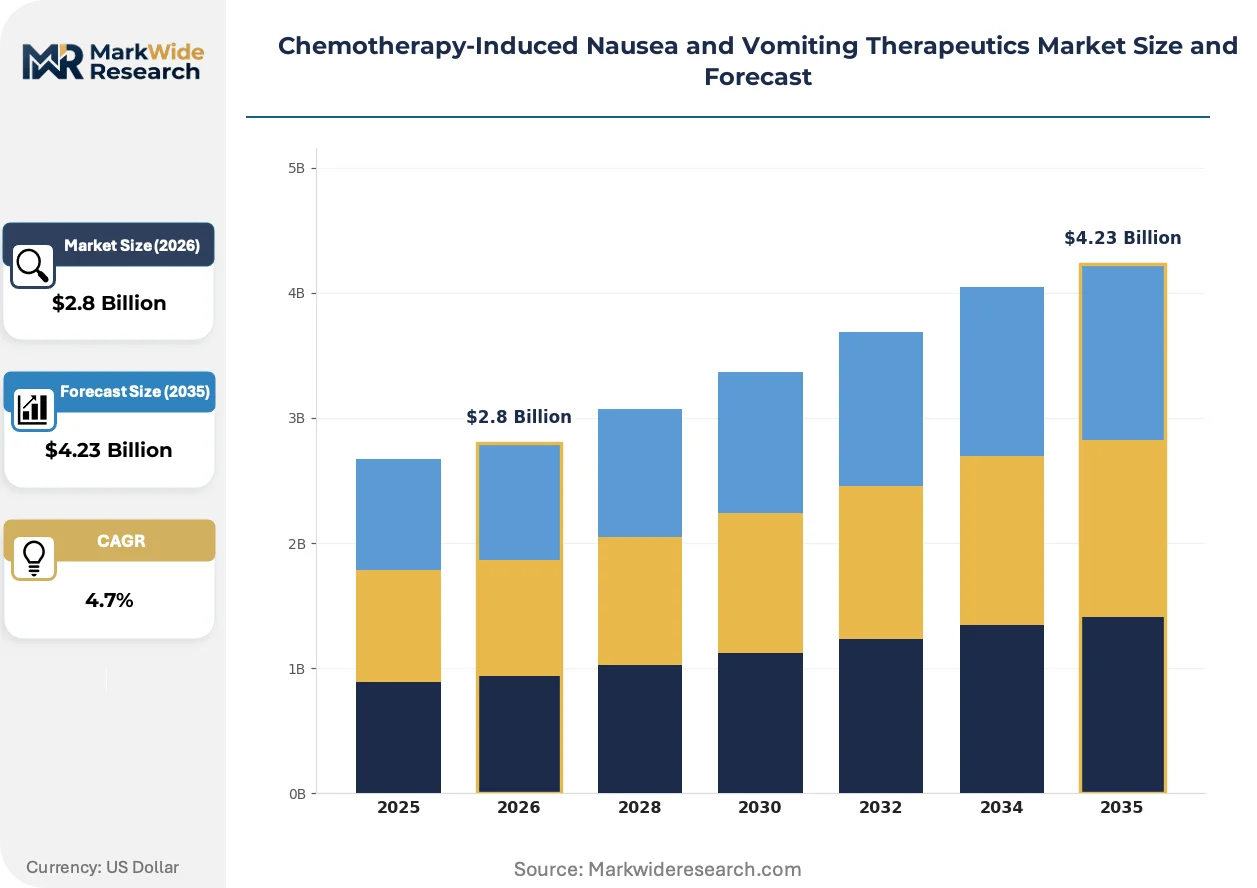
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 5-HT3 Receptor Antagonists, NK1 Receptor Antagonists, Corticosteroids, Antidepressants Delivery Mode: Oral, Intravenous, Subcutaneous, Transdermal Indication: Acute Nausea, Delayed Nausea, Breakthrough Nausea, Anticipatory Nausea End User: Hospitals, Clinics, Homecare, Outpatient Centers |
| Companies Covered | Merck & Co., Inc., GlaxoSmithKline plc, Novartis AG, Helsinn Group, Heron Therapeutics, Inc., Teva Pharmaceutical Industries, F. Hoffmann-La Roche Ltd, Baxter International Inc., Cipla Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemotherapy-Induced Nausea and Vomiting Therapeutics Market Strategic Shifts
Antiemetic development is pivoting from receptor antagonism optimization toward delivery system innovation that compresses dosing frequency and improves homecare reliability.
Extended-release injectable suspensions are absorbing the technical risk of delayed-phase nausea control previously managed through oral corticosteroid tapering. Oncology outpatient centers in the United States and Germany are adopting these platforms for high-emetic-risk anthracycline regimens, reducing same-day rescue medication calls by enabling 72-hour pharmacokinetic coverage from single administration.
EU MDR post-market surveillance requirements are forcing antiemetic manufacturers to maintain active implantable-grade vigilance systems for previously passive supportive care drugs. The regulation mandates systematic collection of real-world efficacy data across all member states, compelling Helsinn Group and Merck & Co. to deploy centralized European pharmacovigilance hubs that track breakthrough emesis rates by chemotherapy protocol.
Hospital purchasing consortia are consolidating antiemetic procurement across multi-site cancer networks, displacing individual pharmacy-and-therapeutics committee autonomy with standardized formulary mandates. This concentration is visible most acutely in United States academic medical centers, where 12-hospital systems now negotiate exclusive supply contracts for NK1 receptor antagonist combinations, compressing vendor diversity to two or three approved suppliers per network.
Chemotherapy-Induced Nausea and Vomiting Therapeutics Market Segmentation
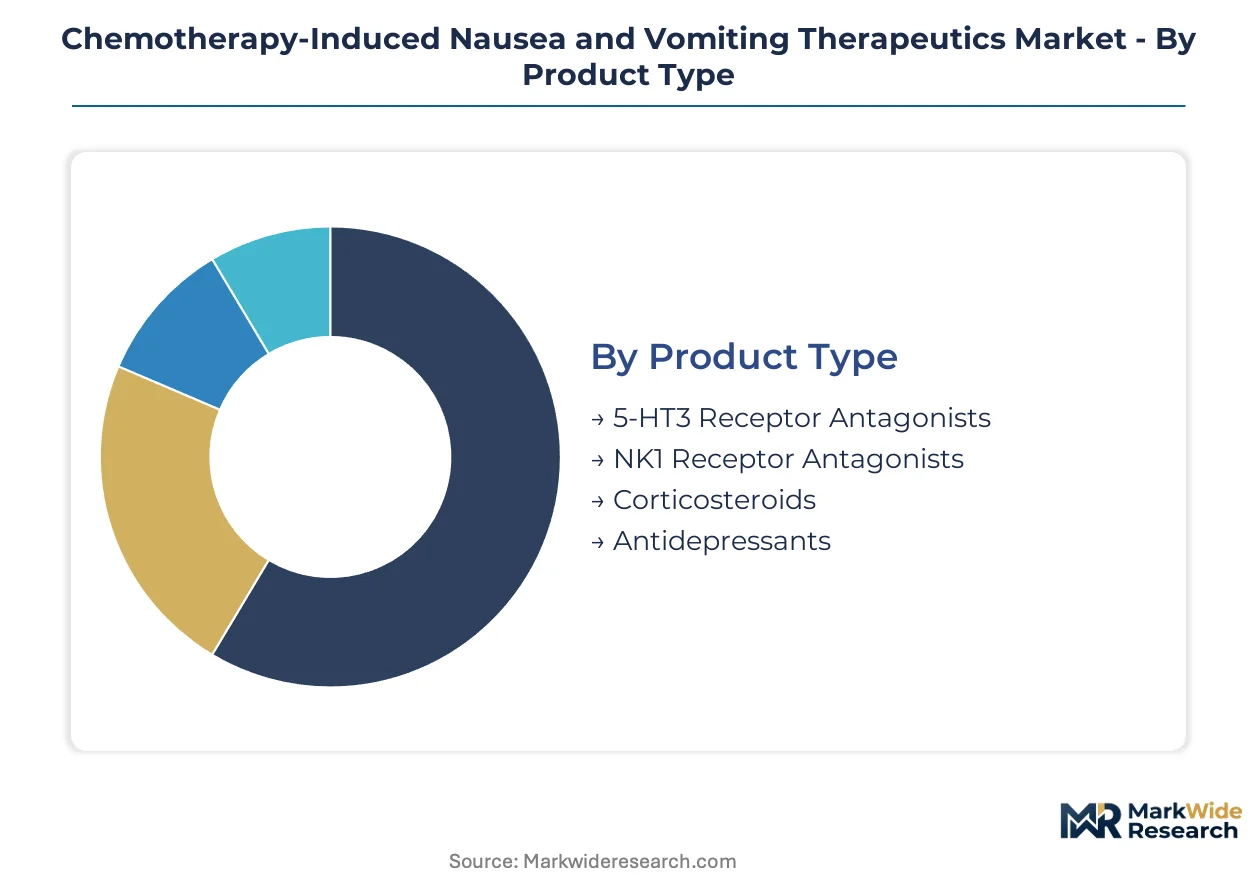
Segmentation in the chemotherapy-induced nausea and vomiting therapeutics market reflects the pharmacokinetic complexity of matching drug delivery to distinct emetic phases. Each dimension—product mechanism, administration route, clinical indication, and care setting—carries distinct margin profiles and regulatory requirements that shape competitive positioning.
Product Type:
Upgrade cycles in antiemetic therapy follow the evolution from single-agent 5-HT3 blockade to triple-combination regimens anchored by NK1 receptor antagonists.
- NK1 Receptor Antagonists:These agents block substance P signaling in the brainstem emetic center, delivering superior delayed-phase control when combined with 5-HT3 antagonists and dexamethasone. Demand concentrates in United States academic medical centers where MASCC/ESMO guidelines for highly emetogenic chemotherapy mandate their inclusion in prophylactic protocols.
- 5-HT3 Receptor Antagonists:First-generation agents like ondansetron and the second-generation palonosetron antagonize serotonin receptors in the gastrointestinal tract and central nervous system. German ambulatory oncology networks favor palonosetron for its extended half-life that reduces same-day rescue calls in anthracycline-based regimens.
- Corticosteroids:Dexamethasone remains the backbone of acute and delayed-phase prophylaxis through anti-inflammatory mechanisms in the solitary tract nucleus.
- Antidepressants:Mirtazapine and olanzapine address refractory cases through histamine H1 and 5-HT2A receptor blockade.
NK1 receptor antagonists sit at the top of the volume ranking, with corticosteroid combinations climbing the fastest as value-based oncology contracts emphasize complete emesis protection.
Delivery Mode:
Cost tier differentiation separates premium extended-release injectables from commoditized oral generics, with reimbursement density determining uptake patterns.
- Oral:Tablet and capsule formulations dominate homecare administration where patient self-management reduces hospital bed utilization. Japanese health technology assessment frameworks favor oral NK1 antagonist combinations for outpatient reimbursement.
- Subcutaneous:Needle-based delivery platforms bypass gastrointestinal absorption variability in patients with mucositis or post-surgical anatomy alterations. United States head-and-neck cancer centers adopt these formulations for patients with swallowing dysfunction.
- Intravenous:Bolus and infusion administration remains standard for same-day chemotherapy suites requiring immediate pharmacokinetic onset.
- Transdermal:Patch-based delivery remains investigational for chronic nausea applications outside acute chemotherapy cycles.
Oral formulations command the highest volume share, though subcutaneous platforms are gaining share fastest among geriatric and high-emetic-risk populations.
Indication:
Application urgency varies dramatically across the emetic timeline, with breakthrough episodes demanding rescue-therapy pricing premiums.
- Delayed Nausea:Occurring 24-120 hours post-chemotherapy, this phase drives the most complex pharmacokinetic engineering as 5-HT3 antagonist coverage wanes. Cisplatin-based regimens in United States oncology clinics require sustained corticosteroid tapering or NK1 combination therapy.
- Breakthrough Nausea:Rescue-therapy failure after prophylaxis commands premium pricing due to the clinical urgency of maintaining chemotherapy schedules and preventing dose reduction.
- Acute Nausea:The initial 0-24 hour window responds reliably to 5-HT3 antagonist monotherapy in moderately emetogenic protocols.
- Anticipatory Nausea:Conditioned responses before chemotherapy administration require behavioral intervention adjuncts to pharmacotherapy.
Delayed nausea sits at the top of the volume ranking, with breakthrough nausea climbing the fastest as same-day infusion models compress intervention windows.
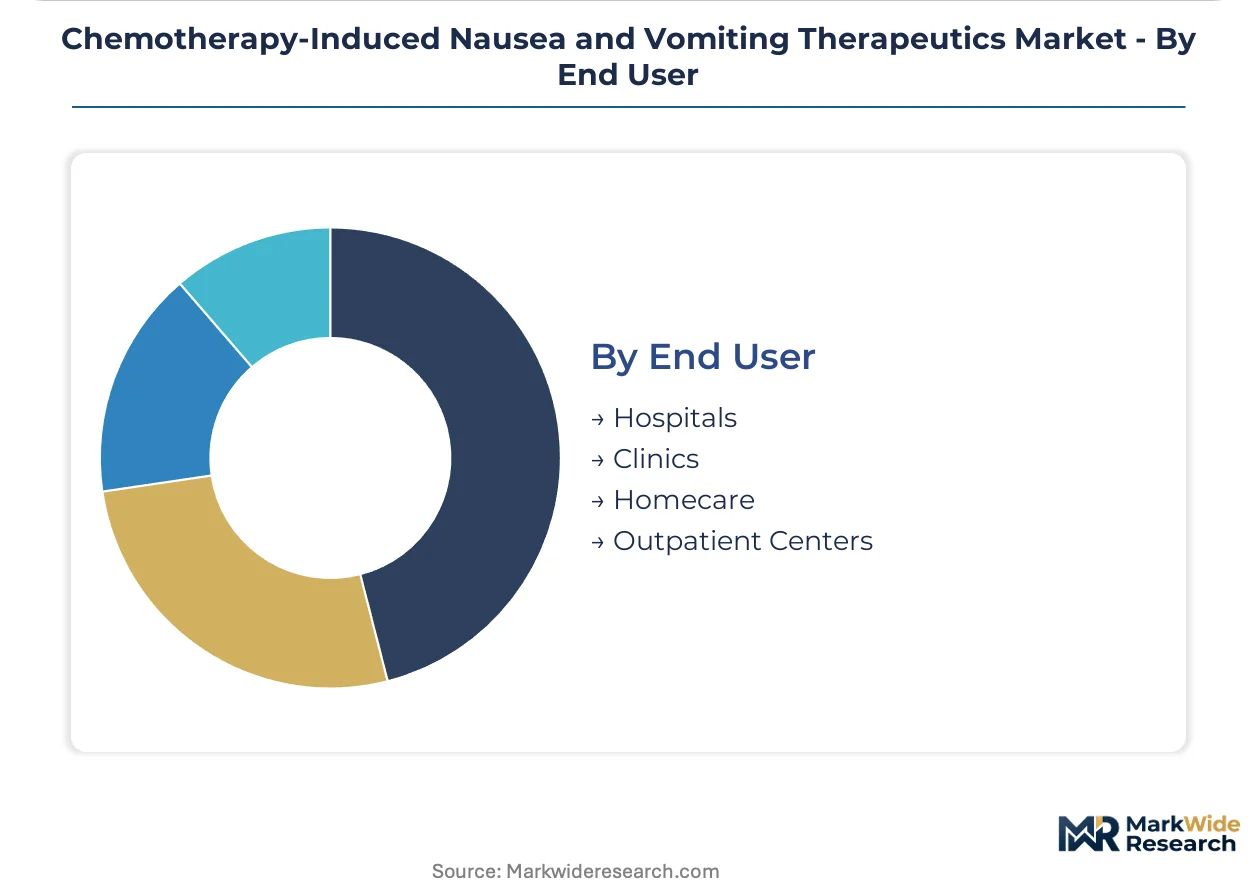
End User:
Customer type concentration reflects the structural shift from inpatient oncology wards to ambulatory infusion networks.
- Outpatient Centers:Same-day chemotherapy infusion suites in United States and Germany require reliable delayed-phase control to prevent emergency department transfers. These facilities negotiate consolidated procurement contracts across multi-site networks.
- Homecare:Oral antiemetic dispensing for self-administered regimens is expanding in Japanese and United States markets where reimbursement supports remote patient monitoring.
- Hospitals:Inpatient oncology units retain high-emetic-risk protocols requiring intravenous rescue capabilities.
- Clinics:Community-based practices balance formulary cost constraints with guideline adherence.
Outpatient centers sit at the top of the volume ranking, with homecare climbing the fastest as value-based contracts incentivize reduced hospital utilization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping clinical trial placement as developers relocate Phase III antiemetic studies from high-cost FDA jurisdictions to EMA-aligned markets with streamlined oncology supportive care pathways. Manufacturing of active pharmaceutical ingredients concentrates in Asian contract facilities serving both Western innovator firms and emerging biosimilar producers.
United States
Academic medical centers in Boston and Houston drive premium NK1 antagonist uptake through MASCC guideline adherence. FDA oncology supportive care guidance mandates head-to-head non-inferiority data against three-drug combinations. The Research Triangle Park cluster in North Carolina anchors pharmacovigilance infrastructure for post-market surveillance of extended-release formulations.
Germany
Ambulatory oncology networks in Bavaria and North Rhine-Westphalia generate concentrated demand for same-day infusion antiemetics. EMA tightened efficacy thresholds accelerate clinical trial investment across European cancer centers. The Heidelberg-Mannheim corridor hosts specialized early-phase units testing subcutaneous delivery platforms for high-emetic-risk regimens.
Japan
Metropolitan Tokyo and Osaka cancer centers sustain premium reimbursement for oral NK1 combination therapies under PMDA-aligned health technology assessment frameworks. METI industrial policy supports domestic formulation capabilities for extended-release injectables. Yokohama biotech clusters coordinate real-world data collection for breakthrough nausea rescue protocols.
China
NMPA regulatory harmonization with ICH standards creates accelerated approval pathways for NK1 antagonists validated in Western markets. Yangtze River Delta manufacturing hubs concentrate palonosetron API production for global supply chains. Shanghai oncology centers pilot digital adherence monitoring integrated with automated rescue medication dispensing.
India
CDSCO streamlined oncology drug approval processes attract contract manufacturing of generic 5-HT3 antagonists for cost-constrained emerging markets. Hyderabad and Ahmedabad clusters specialize in palonosetron and aprepitant API synthesis. Mumbai-based hospital networks expand outpatient chemotherapy capacity requiring prophylactic antiemetic standardization.
Chemotherapy-Induced Nausea and Vomiting Therapeutics Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with innovator firms commanding premium positioning in NK1 receptor antagonist combinations while generic producers capture volume in patent-expired 5-HT3 blockades. The market structure concentrates around three archetypes: large-cap pharmaceutical conglomerates with hospital formulary leverage, mid-cap oncology-focused developers with delivery platform specialization, and emerging-market manufacturers with API cost advantages. Dominant competitive moves include strategic partnerships for subcutaneous formulation technology and geographic licensing agreements for NMPA pathway access.
Among large-cap developers, Merck & Co., Inc. and Novartis AG occupy positions sustained by long-standing hospital relationships and oncology portfolio breadth. Helsinn Group and Heron Therapeutics, Inc. exemplify the delivery-innovation archetype, with the former anchoring European premium prophylactic segments and the latter representing extended-release platform specialization. Teva Pharmaceutical Industries and Cipla Inc. sit within the generic-access tier, serving cost-sensitive markets with commoditized 5-HT3 antagonist supply.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| GlaxoSmithKline plc |
| Novartis AG |
| Helsinn Group |
| Heron Therapeutics, Inc. |
| Teva Pharmaceutical Industries |
| F. Hoffmann-La Roche Ltd |
| Baxter International Inc. |
| Cipla Inc. |
| Others |
Value Chain & Pricing Dynamics
Palonosetron and aprepitant active pharmaceutical ingredients move from concentrated Yangtze River Delta and Hyderabad manufacturing through formulation facilities in Germany and the United States, with procurement managers at hospital consortia negotiating volume discounts that compress margins for branded NK1 antagonist combinations while generic 5-HT3 blockades capture cost-sensitive community clinic demand.
Pricing Analysis
Distributor margins for hospital purchasing consortia now determine effective net pricing across United States academic medical centers, where three-tier pricing structure across premium, standard, and economy levels separates patent-protected NK1 combinations from palonosetron generics and rescue-therapy rescue medications. Quality grade differentiation through FDA oncology supportive care guidance compliance and EMA bioequivalence certification creates pricing premiums for guideline-adherent triple-combination regimens. Cost compression in the generic 5-HT3 segment intensifies because of Indian API oversupply, with community oncology clinics exhibiting highest price sensitivity versus academic centers prioritizing complete emesis protection.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore coordinate hub-and-spoke patterns for temperature-sensitive injectable formulations, with API synthesis concentrating in China, India, and Switzerland for critical antiemetic precursors. Finished dose manufacturing draws from Italian and Irish sterile fill-finish facilities, with formulation development resting on Chinese heparinoid excipients and Indian corticosteroid intermediates. Single-source vulnerability in palonosetron API exposes formulators to import tariff volatility from concentrated Zhejiang province production. Distribution runs through oncology-focused specialty distributors serving hospital consortia rather than broad-line pharmaceutical wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as outpatient infusion expansion shifts procurement criteria toward pharmacokinetic reliability and reduced rescue-therapy dependency.
For Market Incumbents: Acquire subcutaneous delivery platform specialists to anchor formulary position as same-day infusion models compress intervention windows. Defensive consolidation through backward integration into aprepitant API production mitigates tariff exposure from concentrated Chinese supply. Capacity addition in German ambulatory oncology networks captures white-space demand for extended-release platforms. For New Entrants and Emerging Players: Geriatric patients with swallowing dysfunction represent the most penetrable entry point for needle-based formulations excluded from oral prophylaxis protocols. Homecare administration expansion in Japanese and United States markets offers second white-space target for digital adherence monitoring integration. Go-to-market angle should emphasize automated rescue medication dispensing partnerships with wearable nausea severity tracking vendors. For Investors and Strategic Acquirers: Consolidation pressure builds where EMA and FDA tightened efficacy thresholds raise clinical development barriers for novel mechanism entrants. Long-term viability favors delivery-platform specialists with validated pharmacokinetic profiles over receptor-antagonism innovators facing head-to-head non-inferiority trial cost inflation. Acquisition target archetype: mid-cap developers with extended-release injectable suspensions and NMPA regulatory pathway access. Signal to watch is NMPA harmonization velocity with ICH standards accelerating Western-market validation transfers.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Head-to-head non-inferiority studies against three-drug combinations satisfy FDA oncology supportive care guidance requirements. |
| Regulatory Approval Pathway | NMPA alignment with ICH efficacy standards creates accelerated entry for NK1 antagonist combinations. |
| Licensing Agreement | Subcutaneous formulation technology partnerships expand access for head-and-neck cancer populations. |
| Manufacturing Scale-Up | Extended-release injectable suspension capacity addresses German ambulatory oncology network demand. |
| Pipeline Diversification | Digital adherence monitoring integration targets 40% underreporting rate in homecare settings. |
Study Parameters
Multiple input streams — formulary database analysis, clinical trial registry monitoring, and procurement contract review — were reconciled against primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital GPO contract databases. Bottom-up patient-flow modeling and top-down pharmaceutical expenditure tracking were cross-referenced for triangulation.
Historical prescription volume trends were cross-referenced against panel input from oncology pharmacy directors to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include product mechanism, administration route, clinical indication, and care setting, with regional regulatory cluster effects incorporated. CAGRs were derived from patent expiry impact analysis and guideline adoption curve modeling, with chemotherapy protocol mix and reimbursement density serving as primary forecast inputs.
Underlying measurement precision varies by segment; NK1 receptor antagonist combinations and subcutaneous delivery platforms carry tighter precision than generic 5-HT3 blockades due to concentrated manufacturer disclosure. Forecasts reflect documented assumptions regarding EMA guidance implementation velocity and NMPA harmonization timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Acetazolamide Market
Pharmaceuticals
Critical Care Drugs Market
Pharmaceuticals
Peptide Therapeutics Market
Pharmaceuticals
Global BHK Rabies Vaccine Market
Pharmaceuticals
Novel Drug Delivery Systems in Cancer Therapy Market
Pharmaceuticals
Mexico Dimenhydrinate Market
Pharmaceuticals
Tumor Necrosis Factor Alpha Inhibitors Market
Pharmaceuticals
Hepatitis B Treatment Market
Pharmaceuticals
Anti-Inflammatory Analgesic and Antipyretic Drugs Market
Pharmaceuticals
Global Fondaparinux Market
Pharmaceuticals
Asia-Pacific Contraceptive Drugs and Devices Market
Pharmaceuticals
Decongestants Market
Pharmaceuticals
Hydroxycarbamide Market
Pharmaceuticals
Osteoarthritis Drugs Market
Pharmaceuticals
Nasal Vaccines Market
Pharmaceuticals
Long-Acting Insulin Market