
 Neurodiagnostic and Monitoring Devices Market | 2026-2036
Neurodiagnostic and Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Neurodiagnostic and Monitoring Devices Market Analysis
Modular device bundling is recalibrating procurement patterns across hospital systems and research institutions. Medtronic leverages its integrated care pathways to anchor high-value contracts in epilepsy monitoring centers. Natus Medical Incorporated specializes in newborn and pediatric neurodiagnostic systems, occupying a defensible niche with dedicated clinical workflows.
Neurodiagnostic and monitoring devices comprise electrophysiological recording systems, implantable sensors, and software analytics platforms that detect, quantify, and transmit neural electrical activity with microvolt-level sensitivity. These systems serve to diagnose epilepsy, sleep architecture disorders, neuromuscular degeneration, and cognitive impairment in clinical and ambulatory settings. Electroencephalography systems dominate installed base value due to their ubiquity in seizure monitoring and surgical planning, while wearable devices represent the fastest-expanding technology segment as ambulatory reimbursement frameworks mature. Sleep monitoring applications command premium pricing in diagnostic labs, whereas homecare settings drive volume growth through remote patient monitoring protocols.
FDA 510(k) and premarket approval pathways govern device commercialization in the United States, while EU MDR and CE marking requirements impose strengthened clinical evidence standards across European markets. Japan's PMDA enforces QMS conformity assessments that filter market entry for foreign manufacturers. Stakeholders must monitor evolving software-as-a-medical-device classifications and cybersecurity guidance documents that will determine which analytics capabilities require separate regulatory submission.
Market Dynamics
EU MDR recertification timelines and FDA premarket clearance pathways are compressing product development cycles while forcing manufacturers to consolidate software analytics capabilities under single regulatory submissions.
Growth Catalysts
- Ambulatory reimbursement frameworks:United States CMS coverage expansions for home-based EEG monitoring are redirecting capital toward wearable device platforms and remote patient monitoring protocols.
- Japan's PMDA QMS conformity assessments:Foreign manufacturers meeting these standards gain preferential market access, concentrating high-value epilepsy monitoring contracts in Tokyo and Osaka medical centers.
- Electrode miniaturization:Dry electrode arrays eliminate conductive gel requirements, reducing per-procedure costs for sleep labs and expanding deployment in pediatric populations.
Market Restraints
- Neodymium supply concentration:Rare earth magnet dependencies for high-sensitivity sensors concentrate in Chinese processing facilities, exposing manufacturers to export quota volatility.
- EU MDR clinical evidence standards:Strengthened post-market surveillance requirements extend recertification timelines to 18-24 months, freezing product portfolios during transition periods.
- Optical imaging substitution:Functional near-infrared spectroscopy systems capture cortical hemodynamics without scalp preparation, displacing EEG in research institutions prioritizing participant comfort.
Strategic Opportunities
- Germany's DiGA fast-track pathway:Digital health applications for cognitive assessment qualify for statutory reimbursement, creating first-mover advantages for software-analytics platforms.
- Neonatal intensive care units:Amplitude-integrated EEG systems for hypoxic-ischemic encephalopathy monitoring remain underpenetrated in Indian tertiary hospitals.
- AI-assisted seizure detection:Machine learning classifiers embedded in ambulatory devices enable automated event marking, reducing neurologist review burden in high-volume epilepsy centers.
Industry Challenges
- Clinical neurophysiologist shortages:Fellowship-trained readers for ICU continuous EEG monitoring command premium compensation, constraining service expansion in community hospitals.
- Legacy EMR integration:Proprietary data formats from Nihon Kohden and Natus systems require middleware development for health information exchange compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neurodiagnostic and Monitoring Devices Market |
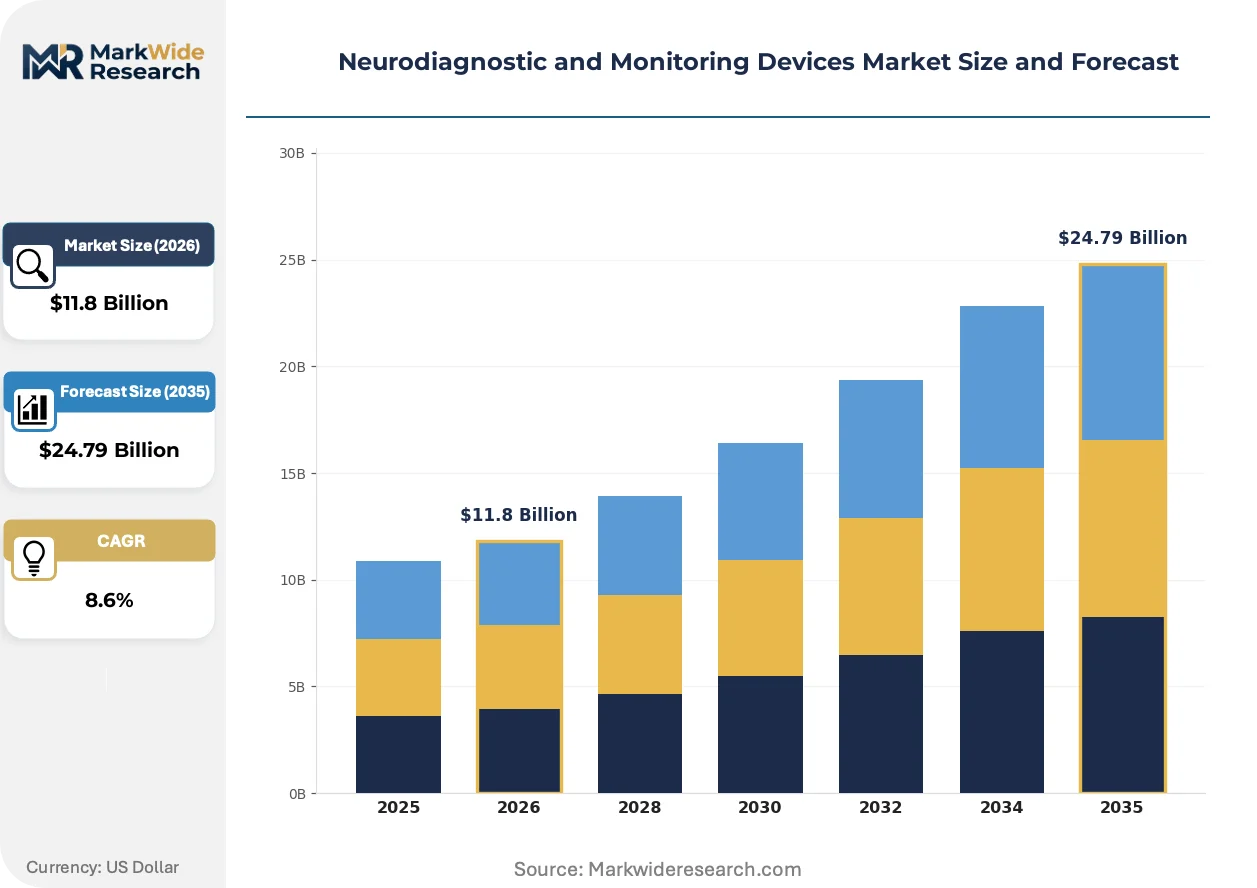
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $24.79 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electroencephalography, Electromyography, Sleep Monitoring, Brain Implants Technology: Wireless Monitoring, Software-based Systems, Wearable Devices, Invasive Techniques End User: Hospitals, Diagnostic Labs, Research Institutions, Homecare Settings Application: Seizure Detection, Sleep Disorders, Neuromuscular Assessment, Cognitive Function Monitoring |
| Companies Covered | Philips Healthcare, Koninklijke Philips N.V., Medtronic, Advanced Brain Monitoring Inc., Neurosoft, Natus Medical Incorporated, Compumedics Limited, Brain Products GmbH, Nihon Kohden Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neurodiagnostic and Monitoring Devices Market Emerging Trajectories
Device architectures are fragmenting into interoperable component ecosystems while regulatory frameworks force consolidation of software validation protocols across multiple jurisdictions.
Wireless amplifier headsets with integrated motion artifact rejection are modularizing traditional bedside EEG configurations. Epilepsy monitoring units in Germany and Japan are adopting these platforms for ambulatory transition protocols. The technology is modularizing capital deployment by separating hardware acquisition from software subscription licensing.
EU MDR Article 10 clinical evaluation requirements now mandate post-market performance follow-up for implantable neurostimulation recorders. Manufacturers must maintain technical documentation across product lifecycles exceeding fifteen years. Implantable sensor segments face the steepest compliance cost escalation, with Swissmedic and TGA aligning inspection protocols to EU standards.
Hospital systems are unbundling device procurement from technical service agreements. Academic medical centers in the United States now source electrophysiology amplifiers through group purchasing organizations while negotiating direct maintenance contracts with regional service providers. This bifurcation is most pronounced in California and Texas health systems managing multi-site neurology networks.
Neurodiagnostic and Monitoring Devices Market Segmentation
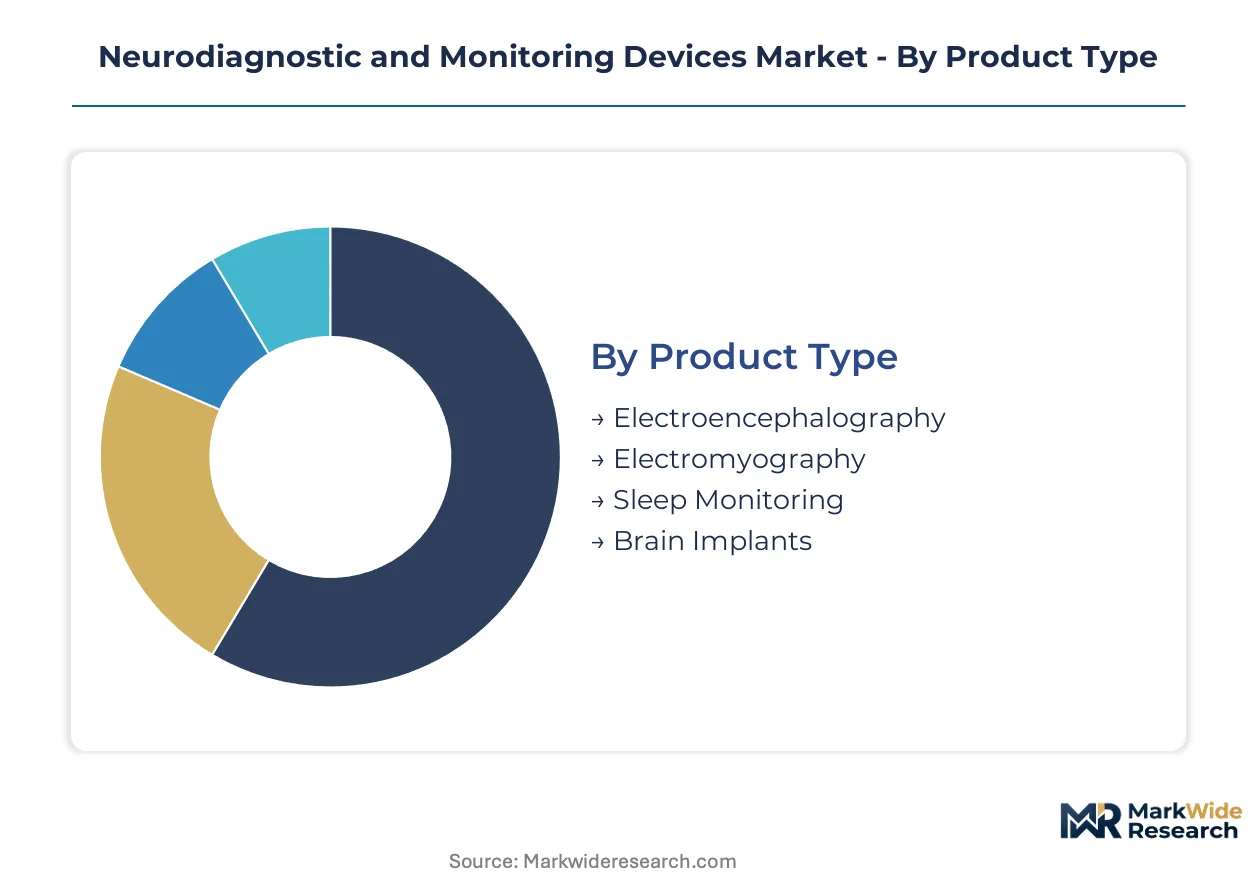
Device segmentation in neurodiagnostic markets reflects divergent capital deployment cycles across clinical settings. Upgrade timelines for electrophysiology platforms stretch 7-10 years in hospital neurology departments, while ambulatory monitoring systems turn over every 3-5 years as reimbursement codes expand.
Product Type:
Replacement cycles vary sharply across product categories, with installed base age and reimbursement velocity driving upgrade decisions differently in each segment.
- Electroencephalography:Scalp electrode arrays with 10-20 channel configurations remain the workhorse for seizure monitoring and pre-surgical mapping. Demand concentrates in United States epilepsy monitoring centers where CMS reimbursement for long-term video-EEG justifies capital outlays for high-density systems.
- Electromyography:Needle electrode and surface recording systems quantify neuromuscular electrical activity with microvolt precision. Germany's statutory health insurance funds now bundle EMG interpretation fees with device utilization, accelerating replacement of analog amplifier systems in outpatient neurology practices.
- Sleep Monitoring:Polysomnography systems integrate EEG, EOG, and respiratory sensors for diagnostic labs.
- Brain Implants:Subdural and depth electrode arrays for intracranial monitoring in epilepsy surgery candidates.
Electroencephalography sits at the top of the volume ranking, with Sleep Monitoring climbing the fastest as home-based diagnostic protocols expand.
Technology:
Technology tiers stratify by patient mobility requirements and data transmission architecture, with cost premiums attaching to seamless ambulatory integration.
- Wireless Monitoring:Bluetooth-enabled amplifier headsets eliminate tethered bedside configurations. United States academic medical centers in California and Massachusetts deploy these for epilepsy monitoring unit step-down protocols, reducing nursing labor for ambulatory transition.
- Software-based Systems:Cloud-native analytics platforms process raw electrophysiological data through FDA-cleared algorithms. Japan's PMDA software-as-a-medical-device guidance creates compliance bottlenecks for foreign developers seeking Tokyo hospital contracts.
- Wearable Devices:Dry electrode arrays and miniaturized amplifiers for home-based monitoring.
- Invasive Techniques:Intracranial depth and strip electrodes for pre-surgical localization.
Software-based Systems command the highest margin tier, while Wearable Devices gain share fastest as CMS expands remote patient monitoring reimbursement.
End User:
Customer type determines procurement channel and service bundling, with group purchasing organizations dominating high-volume hospital contracts.
- Hospitals:Integrated delivery networks in Texas and Florida negotiate multi-site electrophysiology contracts through regional GPOs. Neurology department expansion in these systems favors modular amplifier platforms with shared service agreements.
- Diagnostic Labs:Independent sleep centers in Germany operate under statutory reimbursement contracts that cap equipment depreciation schedules. These constraints favor refurbished polysomnography systems over new capital purchases.
- Research Institutions:Academic medical centers with NIH or DFG funding sources.
- Homecare Settings:Remote patient monitoring providers serving Medicare Advantage populations.
Hospitals absorb the largest capital share, with Homecare Settings expanding most quickly as payors shift site-of-service incentives.
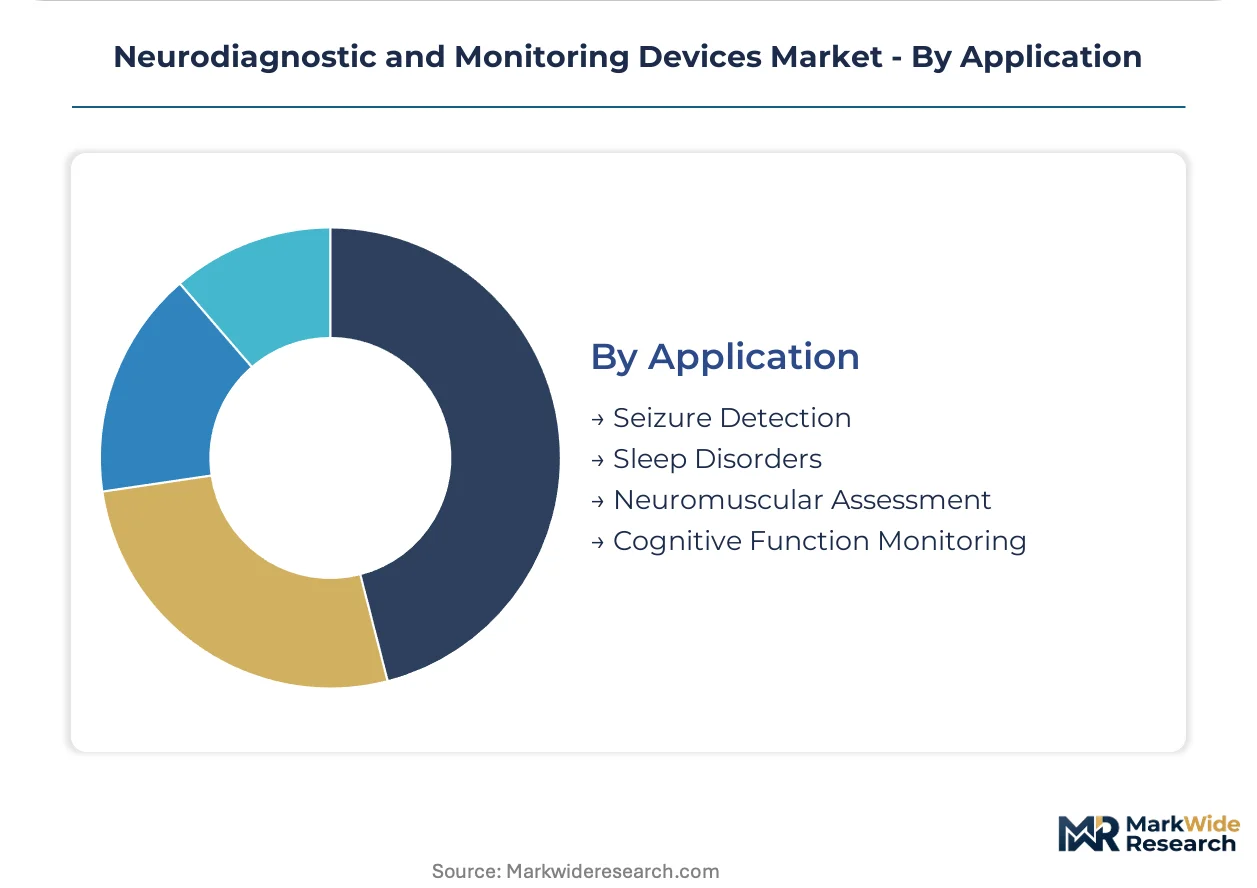
Application:
Clinical indication drives sensor configuration and reimbursement pathway, with procedure volume concentrated in diagnostic categories with established CPT or EBM codes.
- Seizure Detection:Continuous EEG monitoring in ICU and epilepsy monitoring unit settings requires 24-7 technical staffing. United States community hospitals face clinical neurophysiologist shortages that constrain service line expansion despite patient demand.
- Sleep Disorders:Polysomnography and home sleep apnea testing capture obstructive and central sleep pathologies. Japan's aging demographic concentrates demand in Osaka and Nagoya metropolitan areas where specialist interpretation capacity remains limited.
- Neuromuscular Assessment:EMG and nerve conduction studies for peripheral neuropathy and motor neuron disease.
- Cognitive Function Monitoring:Evoked potential and quantitative EEG for delirium and dementia assessment.
Seizure Detection anchors the revenue base, with Cognitive Function Monitoring gaining share fastest as aging populations expand addressable incidence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrophysiological diagnostics originated in European university hospitals during the mid-twentieth century before scaling through American academic medical centers. Japan's precision electronics industry subsequently miniaturized amplifier systems for clinical deployment. Contemporary demand concentrates in aging societies with established reimbursement frameworks for long-term neural monitoring.
United States
CMS coverage expansions for home-based EEG monitoring redirect capital toward wearable platforms and remote patient monitoring protocols. FDA 510(k) and premarket approval pathways govern device commercialization with evolving software-as-a-medical-device classifications. Epilepsy monitoring centers in California and Massachusetts deploy wireless amplifier headsets for ambulatory transition protocols, reducing nursing labor requirements.
Germany
Statutory health insurance funds bundle EMG interpretation fees with device utilization, accelerating replacement of analog amplifier systems in outpatient neurology practices. EU MDR and CE marking requirements impose strengthened clinical evidence standards with post-market surveillance extending recertification timelines. The DiGA fast-track pathway for digital health applications creates first-mover advantages for software-analytics platforms in Berlin and Munich medical centers.
Japan
PMDA QMS conformity assessments filter market entry for foreign manufacturers, concentrating high-value epilepsy monitoring contracts in Tokyo and Osaka medical centers. METI oversees industrial standards alignment with international electrophysiology protocols. Aging demographics in the Osaka and Nagoya metropolitan areas drive demand for sleep disorder diagnostics where specialist interpretation capacity remains limited.
India
Amplitude-integrated EEG systems for hypoxic-ischemic encephalopathy monitoring remain underpenetrated in tertiary hospitals despite rising neonatal intensive care unit investments. CDSCO regulates medical device imports with strengthening quality management system requirements for foreign manufacturers. Maharashtra and Karnataka host expanding private hospital networks negotiating group purchasing organization contracts for modular neurodiagnostic platforms.
Australia
TGA alignment with EU MDR inspection protocols elevates compliance costs for implantable sensor segments while streamlining market access for validated electrophysiology systems. Research institutions with NIH or DFG funding sources drive demand for high-density EEG configurations in Melbourne and Sydney academic medical centers. Remote patient monitoring providers serving Medicare Advantage populations expand deployment of ambulatory sleep monitoring devices across southeastern health networks.
Neurodiagnostic and Monitoring Devices Market Vendor Landscape
The competitive structure tilts toward integrated care pathway providers anchoring high-value hospital contracts through bundled service agreements. Three archetypes dominate: diversified medtech conglomerates leveraging cross-divisional synergies, specialized neurodiagnostic pure-plays occupying clinical workflow niches, and regional electronics manufacturers competing on component cost. Dominant competitive moves include modular device bundling to recalibrate procurement patterns and software subscription licensing to separate hardware acquisition from recurring revenue streams.
Within the diversified medtech tier, Medtronic leverages integrated care pathways to anchor contracts in epilepsy monitoring centers, while Koninklijke Philips N.V. occupies a position spanning hospital systems and diagnostic labs through electrophysiology platform breadth. Natus Medical Incorporated exemplifies the specialized pure-play archetype, concentrating on newborn and pediatric neurodiagnostic systems with dedicated clinical workflows that create defensible market positions against generalist competitors.
| Leading Market Players |
|---|
| Philips Healthcare |
| Koninklijke Philips N.V. |
| Medtronic |
| Advanced Brain Monitoring Inc. |
| Neurosoft |
| Natus Medical Incorporated |
| Compumedics Limited |
| Brain Products GmbH |
| Nihon Kohden Corporation |
| Others |
Supply Flow & Price Mechanics
EU MDR Article 10 clinical evidence mandates gate qualified supply access for implantable neurostimulation recorders while anchoring premium-tier pricing for manufacturers maintaining fifteen-year technical documentation lifecycles. Buyers in German statutory health insurance funds and United States academic medical centers face divergent procurement economics as compliance cost escalation stratifies vendor tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared software-analytics platforms from basic electrophysiology amplifiers and refurbished polysomnography systems. Price differentiation hinges on CE marking tier under EU MDR and bundled service agreement depth. Cost compression in standard-tier EMG systems is intensifying because Germany's statutory health insurance bundles interpretation fees with device utilization. Diagnostic labs operating under statutory reimbursement caps exhibit highest price sensitivity, while United States epilepsy monitoring centers demonstrate lowest sensitivity due to CMS coverage clarity for long-term video-EEG.
Supply Chain Analysis
Single-source vulnerability sits with Chinese rare earth processing facilities supplying neodymium-dependent high-sensitivity sensors for scalp electrode arrays and implantable depth electrodes. Manufacturing concentration spans China for magnet components, Japan for precision amplifier electronics, and Germany for polysomnography system assembly. Raw material dependencies encompass neodymium magnets, conductive gel polymers, and biocompatible electrode alloys. Tariff exposure runs through export quota volatility for rare earth elements. Distribution runs through regional group purchasing organizations in Texas and California health systems, with direct maintenance contracts increasingly unbundled from hardware acquisition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in neurodiagnostic devices rests on electrode miniaturization cost-down curves and software subscription revenue anchoring recurring revenue streams. The shift from capital-intensive bedside configurations to modular ambulatory platforms concentrates profitability in analytics capabilities.
For Market Incumbents: Lock in epilepsy monitoring center contracts through integrated care pathway bundling that combines wireless amplifier headsets with automated seizure detection algorithms. Consolidate software analytics capabilities under single regulatory submissions to compress EU MDR recertification timelines. Counter optical imaging substitution threats in research institutions by emphasizing microvolt-level sensitivity that functional near-infrared spectroscopy cannot replicate. Deepen backward integration into dry electrode array manufacturing to capture margin from pediatric population expansion.
For New Entrants and Emerging Players: Begin with amplitude-integrated EEG systems for neonatal intensive care units in Indian tertiary hospitals, where underpenetration meets rising NICU investment. Target homecare settings as CMS expands remote patient monitoring reimbursement codes, deploying wearable dry electrode platforms that eliminate conductive gel requirements. Pursue Germany's DiGA fast-track pathway for cognitive assessment software to secure statutory reimbursement before generalist competitors establish presence.
For Investors and Strategic Acquirers: Roll-up economics work for specialized neurodiagnostic pure-plays because clinical workflow niche concentration creates defensible positions against diversified medtech conglomerates. Five-to-ten year viability favors targets with FDA-cleared AI-assisted seizure detection algorithms and established GPO contracts in United States integrated delivery networks. Monitor clinical neurophysiologist shortage severity as inflection indicator for automated interpretation demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission | 510(k) pathway for wireless amplifier headsets accelerates ambulatory transition protocol adoption in California epilepsy centers. |
| CE Marking Pathway | EU MDR recertification consolidation reduces compliance cost escalation for implantable sensor portfolios. |
| Hospital System Partnership | Multi-site electrophysiology contracts through Texas GPOs anchor recurring software subscription revenue. |
| Software Companion Development | Cloud-native analytics platforms qualify for Germany's DiGA statutory reimbursement fast-track. |
| Reimbursement Strategy | CMS coverage expansion for home-based EEG monitoring redirects capital toward wearable device platforms. |
Methodological Framework
Direct dialogue with hospital purchasing committees, biomedical engineers, GPO contracts managers, and clinical neurophysiologists grounded qualitative findings in procurement workflow realities. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare reimbursement schedules, and hospital procurement contract registries. Bottom-up and top-down triangulation cross-checked electrophysiology platform installed base estimates against statutory health insurance utilization data.
Bottom-up modeling built from segment-level procedure volumes and device replacement cycles across the analysis window. Segmentation dimensions encompassed product type, technology tier, end-user procurement channel, and clinical application with reimbursement pathway specificity. CAGRs derived from weighted average of historical capital deployment patterns and regulatory velocity assumptions. Forecast inputs incorporated electrode miniaturization adoption curves and ambulatory reimbursement code expansion trajectories.
Several conditions sit outside the modeled scope, including geopolitical disruption to rare earth supply chains and unanticipated software-as-a-medical-device reclassification by Japan's PMDA. Forecasts reflect documented assumptions about clinical neurophysiologist supply elasticity and EU MDR inspection protocol alignment timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
At-Home Laser Hair Removal Devices Market
Medical Devices
Deep Brain Stimulator Market
Medical Devices
Neuromuscular Transmission Monitor Market
Medical Devices
Sinus Dilation Devices Market
Medical Devices
Global Medical Composite Market
Medical Devices
Asia-Pacific Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Bone Power Tools Market
Medical Devices
Asia-Pacific Respiratory Devices Market
Medical Devices
Brazil Artificial Organs and Bionic Implants Market
Medical Devices
Capsule Endoscope and Workstations Market
Medical Devices
Immunoadsorption Columns Market
Medical Devices
Digital Sphygmomanometer Market
Medical Devices
Catheter Coatings Market
Medical Devices
Digital Medical Thermometers Market
Medical Devices
Wearable Pulse Oximeters Market
Medical Devices
Skincare Devices Market