
 Wearable Pulse Oximeters Market | 2026-2036
Wearable Pulse Oximeters Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable Pulse Oximeters Market Analytics
The EU Medical Device Regulation is expanding compliance requirements for wearable diagnostic devices sold across European member states. Masimo Corporation leverages its hospital-grade signal processing heritage to compete in consumer-adjacent segments. Nonin Medical anchors its position through FDA-cleared clinical accuracy claims that differentiate premium offerings. Philips sustains channel control via integrated remote patient monitoring platforms that bundle pulse oximetry with broader vital sign tracking.
Wearable pulse oximeters are non-invasive photometric devices that estimate arterial oxygen saturation and pulse rate by transmitting red and infrared light through vascularized tissue and detecting differential light absorption. These devices serve continuous physiological monitoring in ambulatory, athletic, and home-based care settings where intermittent spot-checking proves inadequate. Smartwatch-integrated variants capture the fastest-growing demand segment as consumer electronics firms embed SpO2 algorithms into multipurpose wearables. Hospitals remain the most concentrated margin pool for clinically validated devices, while home care channels show the steepest volume trajectory driven by post-acute and chronic disease management programs.
FDA 510(k) premarket notification requirements enforce minimum accuracy thresholds for over-the-counter and prescription pulse oximeters distributed in the United States. ISO 80601-2-61 standards govern international electromagnetic compatibility and basic safety specifications for pulse oximeter equipment, shaping design priorities for export-oriented manufacturers. Stakeholders must monitor evolving FDA guidance on skin pigmentation bias in optical sensors, as emerging evidence on measurement disparities threatens to reshape product validation protocols and competitive rankings.
Market Dynamics
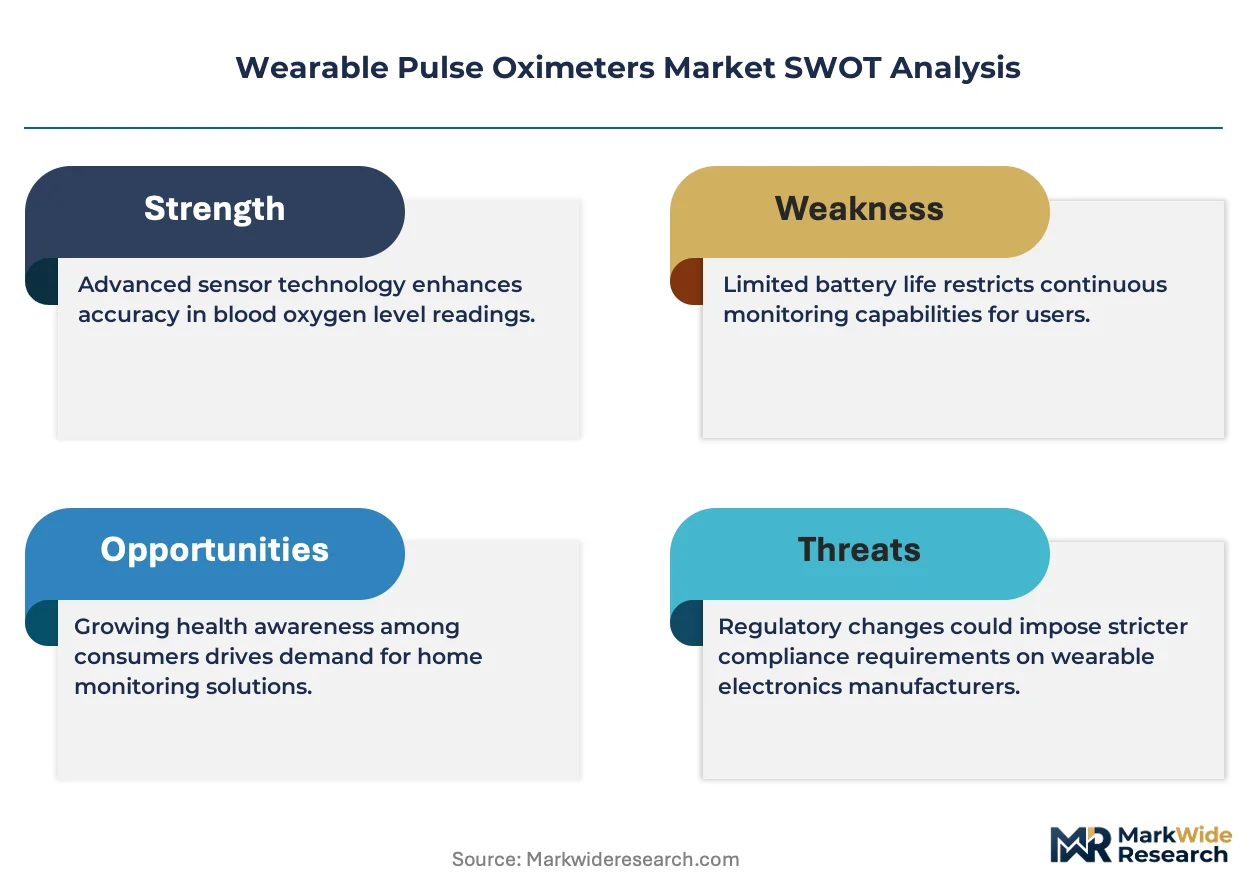
Smartwatch-integrated SpO2 sensing is compressing the addressable market for dedicated fingertip devices as consumer electronics firms embed clinical-grade algorithms into multipurpose wearables. This technology convergence forces incumbent pulse oximeter manufacturers to defend margin pools through regulatory differentiation and hospital channel control.
Growth Catalysts
- Post-acute monitoring programs:Medicare reimbursement expansion for remote patient monitoring in the United States drives institutional procurement of prescription-grade wearable oximeters for chronic obstructive pulmonary disease and heart failure cohorts.
- ISO 80601-2-61 harmonization:International electromagnetic compatibility standards reduce technical barriers for export-oriented manufacturers seeking multi-jurisdiction product registrations.
- Aging demographics in East Asia:Japan's super-aged population and China's pension system reforms generate sustained demand for home-based oxygen saturation tracking among cardiovascular and respiratory disease patients.
Market Restraints
- Optical sensor cost concentration:High-precision photodiode and LED supply chains concentrate in Taiwanese and South Korean component foundries, exposing manufacturers to input price volatility and allocation constraints.
- FDA 510(k) pathway friction:Pre-market notification requirements for over-the-counter pulse oximeters create multi-month approval timelines that delay product launches and compress revenue recognition windows.
- Smartwatch substitution pressure:Apple Watch and Samsung Galaxy Watch SpO2 capabilities satisfy casual wellness monitoring needs, eroding demand for single-purpose consumer oximeters in fitness and sleep tracking segments.
Strategic Opportunities
- Pediatric ambulatory monitoring:Underpenetrated neonatal and infant home care markets present whitespace for wearable oximeters with specialized probe designs and motion-tolerant signal processing algorithms.
- EU MDR compliance premium:Stricter European Medical Device Regulation clinical evidence requirements create tiered market segmentation where notified body-certified manufacturers command price premiums over uncertified imports.
- AI-ECG fusion devices:Convergence of photoplethysmography with machine learning arrhythmia detection enables next-generation wearables that bundle oxygen saturation with cardiac monitoring for atrial fibrillation screening.
Industry Challenges
- Skin pigmentation algorithm validation:FDA guidance on optical sensor bias across diverse melanin levels demands expanded clinical trials and retrospective algorithm retraining that extends development cycles by 12-18 months.
- Legacy hospital IT integration:Epic and Cerner electronic health record interoperability requirements force wearable oximeter vendors to maintain multiple data exchange protocols and API certification programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable Pulse Oximeters Market |
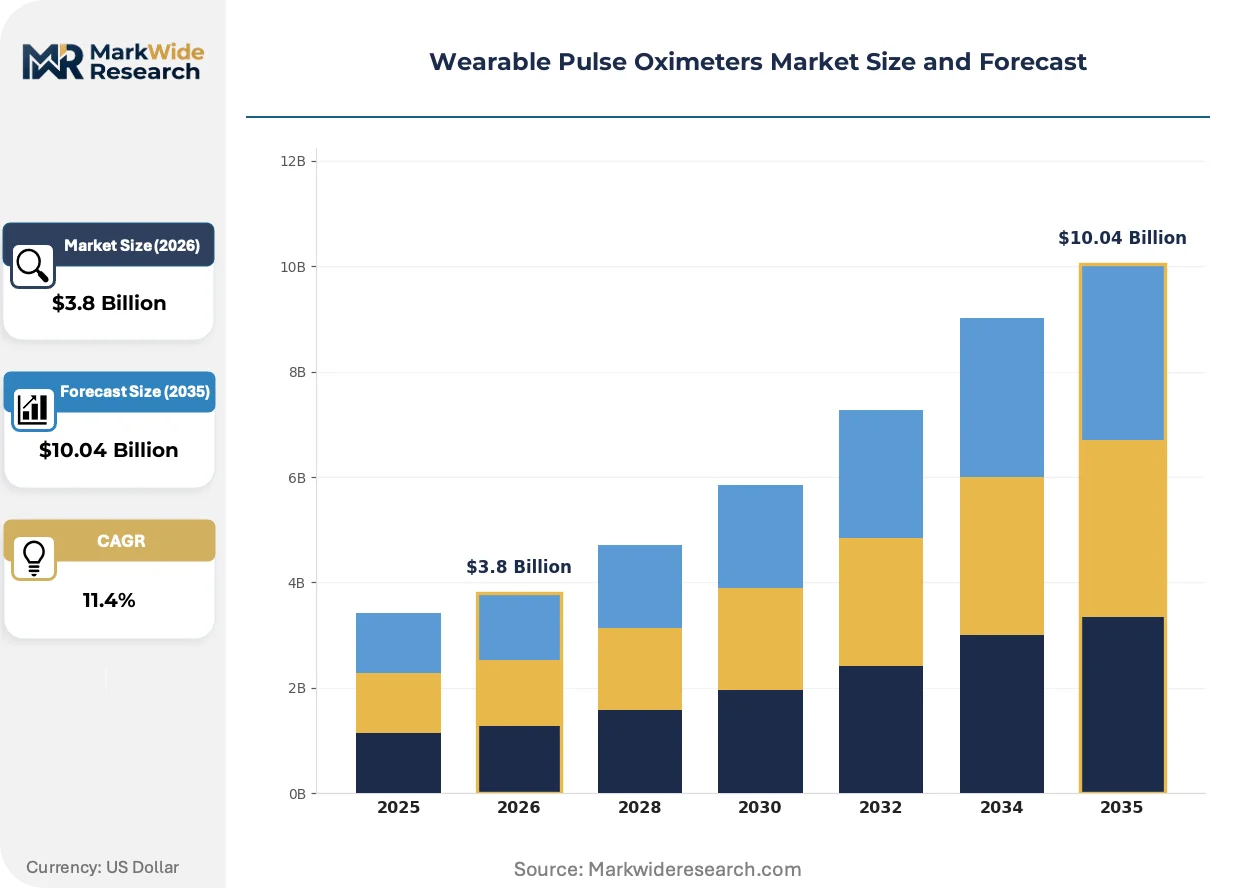
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wrist-Based, Finger Clip, Smartwatch-Integrated, Mobile Device-Compatible Technology: Plethysmography, Optical Sensors, Infrared Light, Wireless Connectivity End User: Home Care, Hospitals, Sports & Fitness, Remote Monitoring Distribution Channel: Online Retailers, Pharmacies, Direct Sales, Medical Supply Stores |
| Companies Covered | Masimo Corporation, Nonin Medical, Medtronic, GE Healthcare, Koninklijke Philips, Contec Medical Systems, Apple, Garmin, Alphabet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable Pulse Oximeters Market Evolving Landscape
Reflectance-mode photoplethysmography is displacing transmission-mode architectures as the dominant sensing paradigm, enabling continuous monitoring from wrist, ear, and forehead form factors previously incompatible with optical pulse oximetry.
Multi-wavelength pulse oximetry is decentralizing oxygen saturation measurement from clinical settings to athletic training facilities and residential environments. NCAA Division I programs and professional cycling teams now deploy wrist-worn SpO2 sensors for altitude acclimatization protocols. This technology diffusion compresses the addressable market for spot-check fingertip devices while expanding total monitoring hours per patient.
The EU Medical Device Regulation is tightening post-market surveillance requirements for wearable diagnostic devices sold across European member states. Manufacturers must now maintain systematic procedures to collect and review experience gained from devices in use, with notified bodies conducting unannounced audits. Class IIa pulse oximeter vendors face particular compliance burden as clinical investigation requirements expand beyond equivalence claims.
Hospital procurement committees are consolidating vendor relationships around integrated remote patient monitoring platforms rather than standalone pulse oximeter contracts. Health systems in Germany and the Netherlands now bundle SpO2 sensing with blood pressure, weight scale, and symptom survey tools under single-source agreements. This buyer concentration favors platform vendors with existing electronic health record integration over specialized oximeter manufacturers.
Wearable Pulse Oximeters Market Segmentation
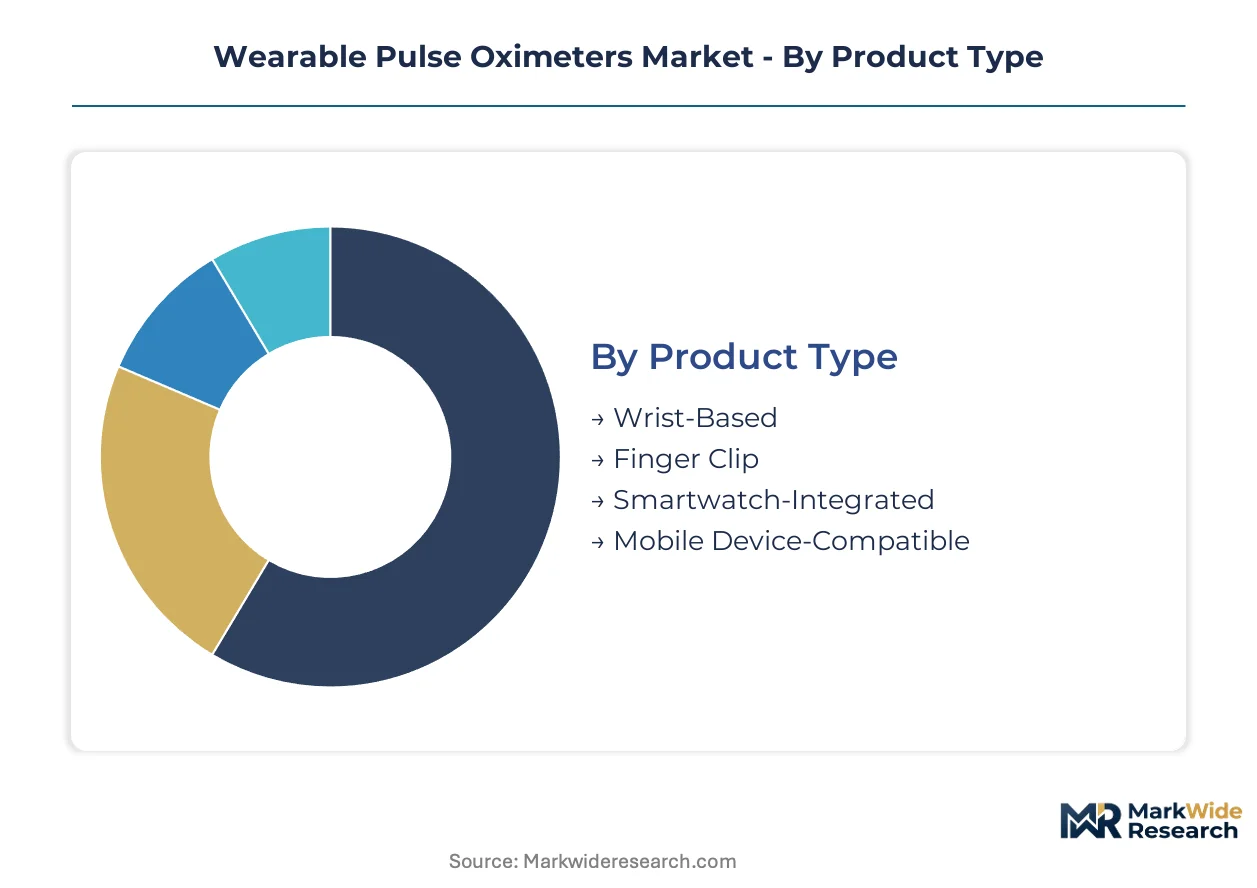
Device architecture and connectivity standards determine upgrade cycles across the wearable pulse oximeter landscape. Replacement timelines compress where smartwatch integration and wireless telemetry reduce standalone hardware dependency.
Product Type:
Upgrade cycles vary dramatically by form factor, with integrated solutions accelerating replacement through consumer electronics refresh patterns while clinical devices follow longer depreciation schedules.
- Smartwatch-Integrated:Embedded SpO2 algorithms leverage existing accelerometer and photoplethysmography hardware in multipurpose wearables from Apple and Samsung. Demand concentrates in United States consumer channels where fitness enthusiasts and sleep apnea suspects prioritize convenience over clinical-grade accuracy. Apple Watch Series upgrades drive 18-24 month replacement velocity that outpaces dedicated medical devices.
- Wrist-Based:Dedicated optical sensors in continuous-monitoring bracelets target post-acute patients requiring overnight oxygen saturation tracking without fingertip obstruction. Japan's super-aged population and Germany's statutory health insurance reimbursement for remote patient monitoring sustain volume leadership in clinical-adjacent segments. Refurbishment programs extend device life in hospital procurement frameworks.
- Finger Clip:Spot-check fingertip devices remain the lowest-cost entry point for intermittent oxygen saturation assessment in developing markets and emergency response kits.
- Mobile Device-Compatible:Smartphone-connected peripherals leverage computational power and display real estate from host devices, reducing onboard processing requirements and manufacturing cost.
Wrist-Based devices sit at the top of the volume ranking, with Smartwatch-Integrated climbing the fastest.
Technology:
Component cost tiers stratify sharply around photodiode precision and signal processing sophistication, with premium clinical specifications commanding manufacturing investment multiples over consumer-grade alternatives.
- Optical Sensors:High-precision photodiodes and LED arrays from Taiwanese and South Korean foundries constitute the dominant cost concentration in device bill-of-materials. FDA 510(k) clearance pathways for pulse oximeter accuracy enforce minimum performance thresholds that differentiate prescription-grade from wellness-oriented implementations. Supply allocation constraints from semiconductor foundries create procurement bottlenecks for manufacturers scaling production.
- Plethysmography:Photoplethysmography signal processing algorithms extract arterial oxygen saturation from pulsatile blood volume changes, with Masimo Corporation's proprietary motion-tolerant implementations setting clinical accuracy benchmarks. Hospital procurement committees in the Netherlands and Germany specify plethysmography performance in remote patient monitoring platform tenders.
- Infrared Light:Dual-wavelength near-infrared and red LED illumination enables differential hemoglobin absorption measurement across tissue penetration depths.
- Wireless Connectivity:Bluetooth Low Energy and proprietary radio protocols transmit continuous data streams to hub devices and electronic health record systems.
Optical Sensors command the highest component expenditure share, with Wireless Connectivity expanding most quickly through remote monitoring platform integration mandates.
End User:
Application-specific validation requirements and reimbursement pathways create distinct margin profiles across clinical, consumer, and institutional deployment contexts.
- Home Care:Continuous ambulatory monitoring for chronic obstructive pulmonary disease and heart failure patients drives the steepest volume trajectory as Medicare reimbursement expansion in the United States institutionalizes remote patient monitoring programs. Philips and Masimo compete through integrated platform offerings that bundle SpO2 with blood pressure and weight scale telemetry. Aging demographics in China and Japan sustain replacement demand as pension system reforms shift care burden to residential settings.
- Hospitals:Inpatient and emergency department applications demand FDA-cleared clinical accuracy claims that Nonin Medical and Masimo defend through 510(k) premarket notifications. Epic and Cerner electronic health record interoperability requirements force vendors to maintain multiple data exchange protocols. Procurement committees consolidate vendor relationships around single-source platform agreements rather than standalone device contracts.
- Sports & Fitness:Altitude acclimatization protocols at NCAA Division I programs and professional cycling teams deploy wrist-worn SpO2 sensors for training optimization.
- Remote Monitoring:Post-acute surveillance programs integrate oxygen saturation with symptom surveys and medication adherence tracking in bundled reimbursement models.
Home Care generates the highest absolute shipment volumes, with Remote Monitoring gaining share fastest through Medicare reimbursement expansion.
Distribution Channel:
Channel economics fragment around prescription requirements, reimbursement complexity, and consumer self-selection patterns that favor direct-to-patient or clinical-intermediated pathways.
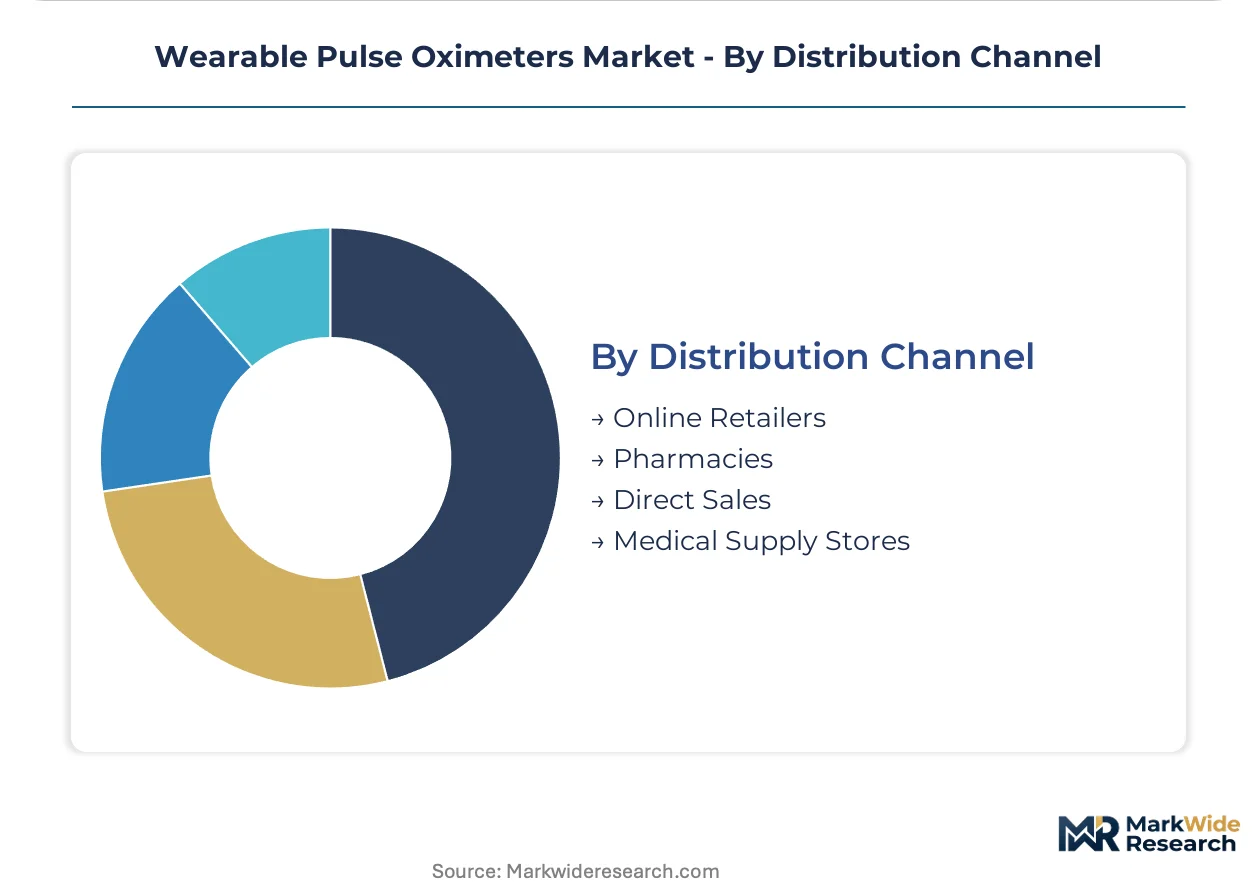
- Direct Sales:Hospital procurement committees and integrated delivery networks negotiate enterprise agreements with Masimo, Philips, and Nonin Medical for platform-level remote patient monitoring deployments. Germany's statutory health insurance system and Netherlands hospital procurement cooperatives consolidate purchasing power through multi-year framework contracts. Sales cycles extend 12-18 months but lock in recurring consumables and service revenue.
- Online Retailers:Amazon and specialized medical device marketplaces serve consumer-directed purchases of over-the-counter fingertip and wrist-based devices where FDA 510(k) clearance is not required. Price transparency and review aggregation accelerate commoditization in wellness-oriented segments.
- Pharmacies:Retail pharmacy chains provide clinical credibility and insurance reimbursement processing for prescription-grade devices.
- Medical Supply Stores:Durable medical equipment suppliers serve Medicare and Medicaid beneficiary populations with documentation-intensive procurement workflows.
Direct Sales captures the largest transaction value per unit, with Online Retailers expanding most quickly through consumer self-selection in wellness segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The wearable pulse oximeter industry traces its commercial origins to hospital-grade monitoring systems developed in the United States during the 1980s, with subsequent manufacturing scale-up shifting toward East Asian electronics clusters.
United States
Medicare reimbursement expansion for remote patient monitoring drives institutional procurement of prescription-grade devices for chronic respiratory disease cohorts. FDA 510(k) premarket notification requirements enforce minimum accuracy thresholds that differentiate clinical-grade from wellness-oriented implementations. Minneapolis anchors hospital procurement networks where integrated delivery networks consolidate vendor relationships around platform-level agreements.
China
Domestic manufacturers scale production of low-cost wearable sensors to serve aging populations under national pension system reforms. NMPA medical device registration requirements shape export-oriented design priorities for multi-jurisdiction product registrations. Shenzhen's electronics manufacturing clusters concentrate photodiode assembly and LED packaging operations for global supply chains.
Germany
Statutory health insurance reimbursement for remote patient monitoring sustains volume leadership in clinical-adjacent segments. EU Medical Device Regulation compliance requirements create tiered market segmentation where notified body-certified manufacturers command price premiums. Bavaria's medical technology corridor hosts procurement cooperatives that bundle SpO2 sensing with broader vital sign tracking platforms.
Japan
Super-aged population demographics generate sustained demand for home-based oxygen saturation tracking among cardiovascular patients. PMDA medical device approval pathways align with international electromagnetic compatibility standards to reduce technical barriers for product registration. Tokyo-Osaka metropolitan corridors concentrate distribution networks for refurbished hospital equipment programs.
Netherlands
Hospital procurement committees consolidate purchasing power through multi-year framework contracts for integrated remote patient monitoring platforms. EMA-aligned regulatory requirements enforce post-market surveillance procedures with unannounced notified body audits. Eindhoven's health technology cluster drives interoperability standards for electronic health record data exchange protocols.
Wearable Pulse Oximeters Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory certification and signal processing sophistication tiers. The vendor base stratifies into hospital-grade specialists defending clinical channel control, consumer electronics firms embedding SpO2 algorithms into multipurpose wearables, and contract manufacturers serving private-label distributors. Three archetypes dominate: FDA-cleared accuracy claimants, platform-integrated remote monitoring providers, and component-integrated smartwatch suppliers. Competitive moves concentrate on regulatory differentiation through 510(k) clearances and hospital IT interoperability certifications.
Within the clinical-accuracy tier, Masimo Corporation and Nonin Medical exemplify positioning around FDA-cleared performance claims. Koninklijke Philips occupies a platform-integrated position bundling pulse oximetry with broader vital sign telemetry. Among consumer electronics entrants, Apple represents the smartwatch-integrated archetype compressing demand for dedicated fingertip devices. These three anchors illustrate how regulatory heritage, platform breadth, and consumer reach define competitive separation in a market where technology convergence erodes single-purpose hardware margins.
| Leading Market Players |
|---|
| Masimo Corporation |
| Nonin Medical |
| Medtronic |
| GE Healthcare |
| Koninklijke Philips |
| Contec Medical Systems |
| Apple |
| Garmin |
| Alphabet |
| Others |
Value Network & Pricing Analysis
Captive integration into Taiwanese and South Korean photodiode foundries anchors both component supply security and pricing power for FDA-cleared device manufacturers, while consumer-grade assemblers in Shenzhen compete on outsourced procurement flexibility. This structural split between clinical-grade vertical control and wellness-tier modular sourcing generates divergent margin profiles across the wearable pulse oximeter landscape.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Masimo and Nonin Medical's FDA-cleared hospital contracts from wrist-based remote monitoring devices and commoditized fingertip spot-checkers. Price differentiation rests on 510(k) certification tier and signal processing sophistication, with clinical-grade algorithms commanding substantial premiums over wellness-oriented implementations. Cost compression in the consumer tier is intensifying because Apple Watch and Samsung Galaxy Watch SpO2 capabilities satisfy casual monitoring needs. Hospital procurement committees exhibit the lowest price sensitivity due to bundled platform contracts, while fitness enthusiasts drive the steepest discount pressure through direct online retail channels.
Supply Chain Analysis
Refurbishment flows from Netherlands and Germany hospital networks extend device life cycles and create secondary component recovery streams for wrist-based oximeter manufacturers. Photodiode and LED array production concentrates in Taiwan, South Korea, and China's Shenzhen electronics clusters, with high-precision clinical-grade components drawing from specialized Taiwanese foundries. Raw material dependencies span gallium arsenide substrates, epoxy molding compounds, and lithium-polymer battery cells. Single-source vulnerability in photodiode allocation from Taiwanese foundries creates procurement bottlenecks during semiconductor demand surges. Distribution runs through hospital procurement cooperatives in Germany and the Netherlands, direct enterprise sales for prescription-grade devices, and Amazon-mediated consumer channels for over-the-counter wellness segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in algorithm licensing and platform bundling as component costs compress through scale economies in optical sensor manufacturing. Premium-tier shift toward AI-ECG fusion devices enables value capture beyond standalone SpO2 measurement.
For Market Incumbents: Lock in hospital channel control through Epic and Cerner electronic health record interoperability certifications that raise switching costs for procurement committees. Deepen backward integration into photodiode specification design to secure allocation priority from Taiwanese foundries during supply constraints. Smartwatch substitution pressure demands defensive patent positioning around motion-tolerant signal processing algorithms. For New Entrants and Emerging Players: The price-point gap between FDA-cleared premium devices and uncertified wellness wearables creates entry space for mid-tier clinical-adjacent positioning. Pediatric ambulatory monitoring presents the most penetrable whitespace, with specialized probe designs for neonatal applications underserved by incumbent form factors. A direct-to-patient online retail go-to-market angle bypasses hospital procurement committee consolidation around platform vendors. For Investors and Strategic Acquirers: Roll-up economics work for remote patient monitoring platform specialists because hospital procurement consolidation favors integrated vital sign telemetry over standalone device vendors. Long-term viability over a multi-year horizon favors targets with existing Medicare reimbursement codes and statutory health insurance eligibility in Germany. Signal to watch: FDA guidance finalization on skin pigmentation bias validation protocols, which will reshape competitive rankings and create acquisition windows for algorithm-retrofitted challengers.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Epic and Cerner interoperability certifications lock in procurement committee vendor consolidation. |
| FDA Submission | 510(k) premarket notifications enforce accuracy thresholds that differentiate prescription-grade from wellness tiers. |
| Software Companion Development | AI-ECG fusion algorithms enable atrial fibrillation screening bundled with oxygen saturation monitoring. |
| Reimbursement Strategy | Medicare remote patient monitoring codes institutionalize chronic disease cohort device procurement. |
| CE Marking Pathway | EU MDR notified body certification commands price premiums over uncertified imports in European markets. |
Research Methodology
Multiple input streams — primary interviews with hospital procurement managers, biomedical engineers, and GPO contracts specialists; secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, and hospital procurement records; and trade data from customs authorities — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured institutional purchasing patterns across integrated delivery networks in Minneapolis, Bavaria's medical technology corridor, and Netherlands hospital cooperatives. Secondary sources included ISO 80601-2-61 standard documentation, PMDA medical device approval records, and NMPA registration filings from Chinese manufacturers.
Historical shipment trajectories were cross-referenced against panel input from component suppliers and contract manufacturers to anchor growth assumptions across the projection horizon. The analytical framework modeled segmentation dimensions including device architecture (smartwatch-integrated, wrist-based, finger clip), technology tier (optical sensor precision, plethysmography sophistication), end-user application (home care, hospital, sports), and distribution channel structure. CAGRs were derived from reconciling top-down market sizing with bottom-up segment build-ups, incorporating Medicare reimbursement expansion rates and statutory health insurance coverage decisions as demand-side inputs.
Caveats apply where FDA guidance finalization on skin pigmentation algorithm validation, photodiode allocation constraints from Taiwanese foundries, or smartwatch SpO2 accuracy improvements could materially shift the outlook. Forecasts embed assumptions regarding reimbursement code stability and EU MDR compliance cost trajectories. Practitioners should monitor FDA 510(k) clearance timelines, semiconductor foundry capacity announcements, and hospital procurement platform consolidation signals for early indicators of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
EEG Amplifiers Market
Medical Devices
Bandage Contact Lenses Market
Medical Devices
Contact Lenses Market
Medical Devices
Syndesmosis Repair System Market
Medical Devices
Canada Varicose Vein Treatment Devices Market
Medical Devices
Interlaminar Device Market
Medical Devices
Cheek Implants Market
Medical Devices
Thyroid Ablation Devices Market
Medical Devices
Ablation Devices Market
Medical Devices
Microneedle Flu Vaccine Market
Medical Devices
Global Medical Devices Market
Medical Devices
Global Mobile ECG Devices Market
Medical Devices
Global Implantable Cardioverter Defibrillators (ICD) Market
Medical Devices
Middle-East and Africa Cardiac Arrhythmia Monitoring Devices Market
Medical Devices
Prescription Goggles Market
Medical Devices
Conduction Vaporizers Market