
 Skincare Devices Market | 2026-2036
Skincare Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Skincare Devices Market Intelligence
CE marking under the EU Medical Device Regulation is redrawing competitive boundaries for professional-grade equipment. L'Oréal leverages its dermatological science subsidiary to navigate clinical validation requirements across European notified bodies. Koninklijke Philips anchors its position through in-house semiconductor fabrication for LED arrays, while Cynosure specializes in dual-wavelength laser platforms that dominate North American medspa procurement.
Skincare devices encompass electromechanical and photonic instruments engineered to deliver controlled thermal, acoustic, or electromagnetic energy to epidermal and dermal tissues, typically operating at wavelengths between 400 nm and 1,064 nm or frequencies from 1 MHz to 40 MHz for ultrasound modalities. Radiofrequency devices command premium placement in professional settings due to their collagen remodeling efficacy at 0.5–8 MHz, while LED devices penetrate the consumer channel through lower power thresholds and simplified safety profiles. Electroporation technology represents the fastest-expanding segment as it enables transdermal delivery of topical actives without microneedle trauma, though ultrasound platforms retain margin concentration in clinic-based fat reduction protocols.
FDA 510(k) premarket notification requirements govern device clearance in the United States, while the EU MDR and CE marking framework enforce post-market surveillance and clinical evidence standards across European Economic Area states. Japan's PMDA imposes additional quality management system audits that extend lead times for Asian manufacturers seeking multi-regional approval. Stakeholders must monitor evolving software-as-medical-device classifications as AI-driven skin analysis modules trigger new regulatory scrutiny in both North American and European jurisdictions.
Market Dynamics
Radiofrequency and LED modalities are displacing legacy laser platforms in professional dermatology settings, while EU MDR recertification timelines concentrate procurement power among manufacturers with dedicated regulatory affairs infrastructure.
Growth Catalysts
- EU MDR Clinical Evidence Mandate:Post-market surveillance requirements under the Medical Device Regulation are filtering smaller competitors from the professional channel, concentrating demand among validated suppliers with notified body relationships.
- Electroporation Technology:Transdermal active delivery without microneedle trauma is expanding addressable patient populations beyond traditional aesthetic candidates into therapeutic dermatology applications.
- Gangnam Medical District Density:Seoul's clinic concentration per capita exceeds any metropolitan cluster globally, creating localized demand pull for multi-modality device fleets with rapid treatment throughput.
Market Restraints
- Semiconductor Component Concentration:LED array fabrication depends on specialized foundry capacity concentrated in East Asian supply chains, exposing manufacturers to input volatility.
- FDA 510(k) Timeline Compression:Pre-market notification review periods for software-as-medical-device classifications are extending lead times for AI-integrated skin analysis modules.
- Ultrasound Platform Substitution:Radiofrequency devices at 0.5–8 MHz are compressing margin concentration previously held by ultrasound modalities in clinic-based fat reduction protocols.
Strategic Opportunities
- Consumer Channel LED Penetration:Lower power thresholds and simplified safety profiles enable direct-to-consumer distribution bypassing professional procurement gatekeepers entirely.
- Japan PMDA Quality Management:Extended audit timelines for Asian manufacturers create first-mover advantage for Western suppliers with established QMS documentation.
- AI-Driven Skin Analysis Convergence:Integration of diagnostic imaging with treatment delivery platforms creates service unbundling opportunities in medspa and clinic settings.
Industry Challenges
- Software-as-Medical-Device Classification:Evolving FDA and EU regulatory scrutiny of AI modules requires dedicated compliance personnel and documentation infrastructure absent from legacy hardware manufacturers.
- Multi-Regional Certification Coordination:Simultaneous navigation of FDA 510(k), EU MDR, and Japan PMDA approval pathways demands specialized regulatory expertise with extended timeline management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skincare Devices Market |
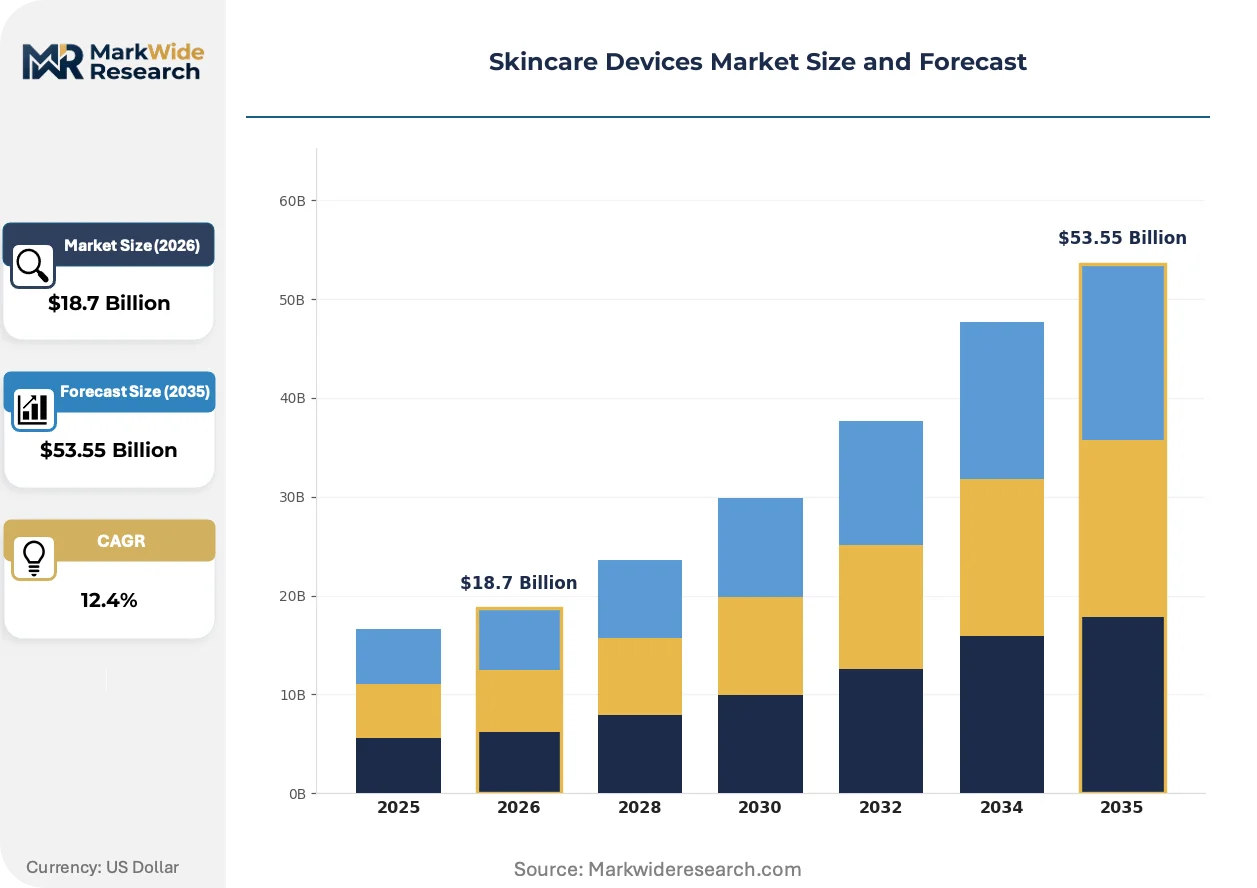
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $53.55 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Devices, Microdermabrasion Tools, Radiofrequency Devices, Light Therapy Devices Technology: Ultrasound, Laser, Electroporation, Cryotherapy End User: Professionals, Consumers, Dermatologists, Clinics Distribution Channel: Online Retail, Specialty Stores, Department Stores, Direct Sales |
| Companies Covered | Panasonic Holdings Corporation, Nu Skin Enterprises, Procter & Gamble, Cynosure, FOREO, Koninklijke Philips, Johnson & Johnson, Conair Corporation, L'Oréal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skincare Devices Market Strategic Shifts & Innovations
Device architecture is fragmenting between high-power professional platforms and simplified consumer-grade instruments, with regulatory classification boundaries determining competitive positioning across both segments.
Radiofrequency technology is bifurcating treatment protocols across professional and consumer channels. Professional devices operating at 0.5–8 MHz deliver controlled thermal injury for collagen remodeling in dermatology clinics. Medspa procurement teams are prioritizing dual-modality platforms combining RF with LED arrays. The technology is bifurcating market structure between premium clinic-based systems and simplified home-use devices with capped energy output.
EU MDR post-market surveillance requirements are extending clinical evidence obligations for existing device portfolios. Manufacturers must maintain systematic data collection on safety and performance across European Economic Area states. Professional-grade equipment with legacy CE marks under the Medical Devices Directive faces recertification deadlines that favor organizations with dedicated clinical affairs infrastructure.
Clinic procurement patterns are compressing replacement cycles for aesthetic equipment. Seoul's Gangnam district and Tokyo's Shibuya medical clusters are consolidating vendor relationships with manufacturers offering comprehensive service contracts. South Korean dermatology groups are demanding integrated training and maintenance packages alongside hardware acquisition, shifting supplier selection criteria beyond device specifications toward operational partnership depth.
Skincare Devices Market Segmentation
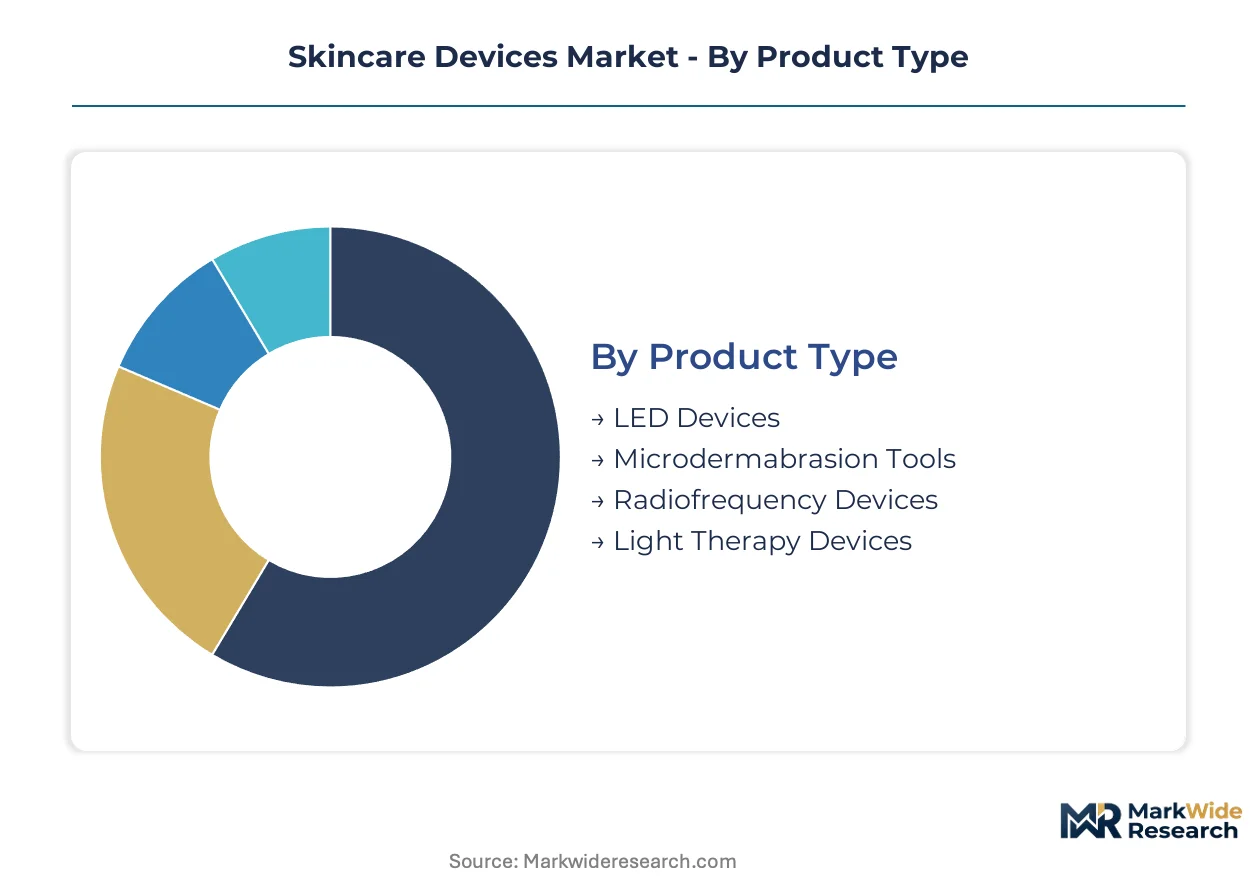
Segmentation in skincare devices reveals how regulatory classification boundaries, power thresholds, and channel access requirements partition manufacturers into distinct competitive arenas. Each dimension exposes different margin structures and capital intensity profiles.
Product Type:
Radiofrequency and LED modalities command premium positioning in professional procurement, while microdermabrasion tools concentrate volume in direct-to-consumer channels.
- LED Devices:Photonic instruments operating at 400-700 nm wavelengths deliver controlled light energy for collagen stimulation and acne management. Seoul's Gangnam medical district drives fleet expansion as clinics replace legacy laser platforms with multi-wavelength LED arrays for shorter treatment cycles.
- Radiofrequency Devices:Electromagnetic systems at 0.5-8 MHz generate controlled thermal injury for dermal collagen remodeling. North American medspa procurement prioritizes dual-modality platforms combining RF with complementary technologies, though EU MDR recertification timelines filter smaller suppliers from this premium segment.
- Microdermabrasion Tools:Mechanical exfoliation systems dominate entry-level consumer pricing tiers through simplified safety profiles and minimal regulatory burden.
- Light Therapy Devices:Broadband and narrow-spectrum instruments span professional and home-use classifications depending on power output thresholds.
Radiofrequency devices hold installed capacity. LED devices are rotating up the share rankings.
Technology:
Electroporation systems are climbing fastest as transdermal delivery applications expand beyond aesthetic into therapeutic dermatology.
- Electroporation:Pulsed electrical field technology creates transient micropores in stratum corneum for active ingredient penetration without physical trauma. The fastest-expanding segment enables topical biologic delivery for conditions previously requiring injection, drawing investment from Korean device manufacturers targeting clinic-based therapeutic protocols.
- Ultrasound:Acoustic energy platforms at 1-40 MHz frequencies support both diagnostic imaging and therapeutic fat reduction applications. Margin concentration in clinic-based body contouring protocols faces compression as radiofrequency devices capture collagen-focused treatment share.
- Laser:Coherent light systems at 400-1064 nm wavelengths retain position in pigmentation and vascular lesion treatment despite displacement pressure from LED alternatives.
- Cryotherapy:Controlled cooling platforms address localized fat reduction and skin tightening through apoptotic induction in adipose tissue.
Ultrasound platforms hold installed capacity. Electroporation systems are rotating up the share rankings.
End User:
Professional channel concentration favors manufacturers with dedicated regulatory affairs infrastructure and service contract capabilities.
- Professionals:Licensed aesthetic practitioners and medical spas operating FDA 510(k) cleared or CE marked equipment demand comprehensive training and maintenance packages. Tokyo's Shibuya medical cluster exemplifies vendor consolidation around suppliers offering operational partnership depth beyond hardware specifications.
- Clinics:Dermatology and plastic surgery practices prioritize multi-modality device fleets with rapid treatment throughput to maximize per-square-meter revenue in high-rent districts.
- Dermatologists:Board-certified specialists drive clinical validation requirements and influence procurement standards across affiliated medical groups.
- Consumers:Home-use purchasers prioritize simplified safety profiles and capped energy outputs that bypass professional gatekeeper channels entirely.
Professional end users hold installed capacity. Consumer-directed sales are rotating up the share rankings.
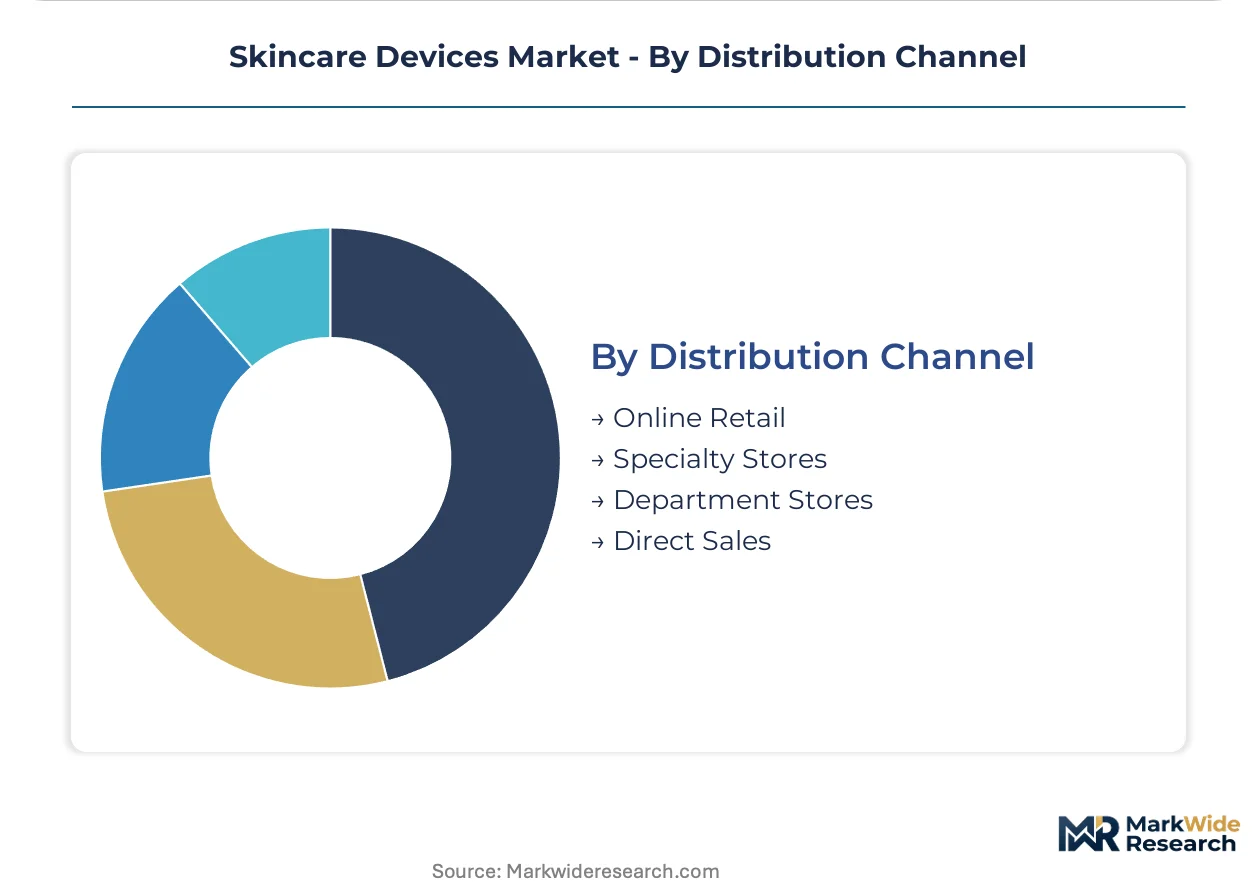
Distribution Channel:
Channel selection determines regulatory classification burden and margin retention simultaneously.
- Direct Sales:Manufacturer-to-clinic relationships dominate professional-grade equipment procurement in Seoul and Tokyo medical districts, enabling bundled service contracts and training programs that lock in replacement cycles.
- Online Retail:E-commerce platforms capture consumer-channel LED and microdermabrasion volume through simplified safety profiles that minimize regulatory friction.
- Specialty Stores:Beauty retailers and medical supply distributors intermediate between manufacturers and smaller clinic operators lacking direct procurement scale.
- Department Stores:Premium positioning venues for consumer-grade devices with elevated price points and brand recognition requirements.
Direct sales channels hold installed capacity. Online retail is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MFDS reimbursement pathways for clinic-based aesthetic procedures are accelerating device fleet turnover across Seoul's medical districts. National regulators in Japan and the United States are tightening software-as-medical-device classifications for AI-integrated skin analysis modules.
United States
FDA 510(k) premarket notification timelines are extending for electroporation and radiofrequency platforms with embedded diagnostic algorithms. The agency's Center for Devices and Radiological Health issued draft guidance on AI-enabled dermatological tools in 2023. Medspa procurement concentrates in Florida, California, and Texas, where clinic chains negotiate multi-unit service contracts with manufacturers.
South Korea
MFDS fast-track approval for therapeutic dermatology applications is redirecting electroporation investment from cosmetic toward medical indications. The regulator's post-market surveillance database tracks adverse events across Gangnam district clinics. Device manufacturers cluster in Seongnam and Suwon, supplying LED arrays and RF platforms to the densest aesthetic clinic network per capita globally.
Japan
PMDA quality management system audits add six to nine months to approval timelines for Asian manufacturers without established QMS documentation. METI subsidies for domestic medical device production are expanding cleanroom fabrication capacity in Osaka and Nagoya. Tokyo's Shibuya medical cluster demands integrated training and maintenance packages alongside hardware procurement.
Germany
CE marking under EU MDR recertification deadlines is filtering smaller manufacturers from professional channel access. Germany's notified bodies handle disproportionate volumes of class IIa and IIb aesthetic device applications. Industrial concentration in Baden-Württemberg and Bavaria supports precision manufacturing for LED semiconductor arrays and RF electrode assemblies.
China
NMPA innovation pathway designations for electroporation devices are accelerating domestic manufacturer market entry. The regulator's technical review center published guidance on transdermal delivery system biocompatibility testing in 2023. Manufacturing gravity concentrates in Shenzhen and Suzhou, where LED foundry capacity serves both consumer and professional device tiers.
Skincare Devices Market Key Industry Players
Listed leaders compete with private specialists across regulatory certification capacity and service contract depth. The professional channel concentrates procurement among manufacturers with dedicated clinical affairs infrastructure capable of navigating simultaneous FDA 510(k), EU MDR, and Japan PMDA pathways. Three archetypes dominate: diversified conglomerates with dermatological science subsidiaries, semiconductor-integrated device fabricators, and specialized laser platform developers. Competitive moves center on M&A for regulatory approval portfolios and backward integration into LED foundry capacity.
Among diversified conglomerates, L'Oréal and Johnson & Johnson exemplify archetypes leveraging dermatological science subsidiaries to navigate clinical validation requirements. Koninklijke Philips anchors the semiconductor-integrated tier through captive LED array fabrication. Cynosure occupies a specialist position in dual-wavelength laser platforms dominating North American medspa procurement.
| Leading Market Players |
|---|
| Panasonic Holdings Corporation |
| Nu Skin Enterprises |
| Procter & Gamble |
| Cynosure |
| FOREO |
| Koninklijke Philips |
| Johnson & Johnson |
| Conair Corporation |
| L'Oréal |
| Others |
Cost & Logistics Intelligence
FDA 510(k) clearance tiers and EU MDR certification grades operate as simultaneous gates on supplier qualification and price positioning across professional and consumer channels. Manufacturers lacking notified body relationships face exclusion from premium procurement tiers in Seoul's Gangnam district and Tokyo's Shibuya medical clusters, compressing their addressable market to price-sensitive consumer segments with minimal regulatory burden.
Pricing Analysis
Certification level (FDA 510(k)/CE MDR-grade) creates the primary spread between professional clinic systems and direct-to-consumer devices. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales bundling intensity and training contract depth rather than hardware specifications alone. Pricing pressure stems from LED array commoditization in consumer channels, where simplified safety profiles enable e-commerce bypass of professional gatekeepers. Hospital purchasing committees and medspa procurement teams demonstrate lowest price sensitivity, prioritizing service contract reliability over per-unit cost.
Supply Chain Analysis
South Korea and Taiwan anchor LED semiconductor foundry capacity for photonic device arrays, while Germany and Japan concentrate precision RF electrode fabrication. Raw material flows draw from gallium arsenide substrates, sapphire wafers, and medical-grade aluminum for handheld housings. Single-source vulnerability runs through East Asian foundry concentration, exposing manufacturers to input volatility from geopolitical friction or cleanroom capacity constraints. Distribution runs through direct manufacturer-to-clinic relationships in dense medical districts, with e-commerce platforms capturing consumer-tier volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electroporation technology expansion and AI-driven skin analysis modules are disrupting legacy competitive boundaries, creating first-mover windows for regulatory-fast manufacturers and specialist acquirers.
For Market Incumbents: Compound regulatory affairs infrastructure through dedicated clinical validation teams capable of simultaneous FDA 510(k), EU MDR, and Japan PMDA navigation. Deepen backward integration into LED foundry capacity to defend margin position against semiconductor input volatility. Cynosure and Koninklijke Philips exemplify archetypes leveraging captive fabrication and dual-modality platforms to lock in medspa procurement cycles. For New Entrants and Emerging Players: MFDS fast-track approval for therapeutic dermatology applications opens white-space penetration beyond cosmetic aesthetic candidates into clinic-based medical protocols. Target consumer-channel LED devices with simplified safety profiles that bypass professional procurement gatekeepers entirely. Pursue direct-to-e-commerce distribution with capped energy outputs and minimal certification burden to compress time-to-revenue. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed dermatology device specialists lacking AI-integrated diagnostic modules or electroporation portfolios. Five-to-ten year viability hinges on regulatory approval velocity and software-as-medical-device classification readiness. Watch FDA draft guidance finalization on AI-enabled dermatological tools as inflection signal for valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR recertification deadlines filter smaller competitors from professional channel access. |
| LED Foundry Backward Integration | Captive semiconductor fabrication defends margin position against East Asian supply volatility. |
| Software Companion Development | AI-driven skin analysis modules trigger new FDA scrutiny and service unbundling opportunities. |
| Hospital System Partnership | Integrated training and maintenance packages lock in replacement cycles in Gangnam and Shibuya districts. |
| Reimbursement Strategy | MFDS therapeutic pathway designation redirects electroporation investment toward medical indications. |
Research Approach
Operator-level perspectives from dermatology clinic directors, medspa procurement managers, biomedical engineers, and GPO contracts managers anchored the qualitative base. Primary interview data combined with secondary validation from FDA 510(k) filings, EU MDR notified body databases, MFDS approval registries, and hospital procurement contract disclosures. Bottom-up device shipment modeling and top-down market sizing triangulated across professional and consumer channel estimates.
Sensitivity analysis tested forecast robustness across regulatory timeline scenarios and semiconductor input cost assumptions. Segmentation dimensions spanned product type, technology modality, end-user channel, and geographic regulatory cluster. CAGRs derived from installed base rotation rates and replacement cycle compression in dense medical districts. Electroporation adoption curves and AI module integration timelines served as industry-specific demand inputs.
Decision-makers should treat outputs as directional under stable regulatory clearance timelines and intact East Asian foundry capacity; material deviation would warrant model refresh. Recalibration cycles align with material shifts in FDA software-as-medical-device classifications and EU MDR recertification deadlines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Cannula Market
Medical Devices
United Kingdom Drug Delivery Devices Market
Medical Devices
Global Interspinous Spacers Market
Medical Devices
Graft Delivery Devices Market
Medical Devices
Global Limb Prosthetics Market
Medical Devices
Asia-Pacific Interventional Cardiology and Peripheral Vascular Devices Market
Medical Devices
Carpal Tunnel Release Systems Market
Medical Devices
Knee Walkers Market
Medical Devices
Medical Smart Glasses Market
Medical Devices
Global Advanced Bipolar Direct Energy Device Market
Medical Devices
Global Thermoelectric Devices in Medical and Laboratory Offering Market
Medical Devices
Muscle Stimulator Market
Medical Devices
Peripheral Vascular Guide Wire Market
Medical Devices
Chest Drainage System Market
Medical Devices
Global Angiography Devices Market
Medical Devices
Laparoscopic Devices Market