
 Immunoadsorption Columns Market | 2026-2036
Immunoadsorption Columns Market Size, Share, and Industry Trends Forecast 2026-2036
Immunoadsorption Columns Market Outlook
Specialized bioprocessing engineering talent is rotating toward immunoadsorption manufacturing hubs, tightening labor pools for smaller competitors while concentrating expertise at established operations. Fresenius Medical Care Adsorber Tec leverages its vertically integrated dialysis-apheresis platform to dominate European hospital procurement. Asahi Kasei Corporation sustains membrane-separation R&D intensity across its medical materials division. Miltenyi Biotec GmbH specializes in magnetic cell separation architectures that extend into column-based purification workflows.
Immunoadsorption columns are sterile, single-use devices packed with ligand-activated matrices—typically protein A, synthetic peptides, or immobilized antigens—that selectively bind pathogenic antibodies or immune complexes from plasma during extracorporeal circulation. The primary purpose centers on treating autoimmune disorders, transplant rejection, and specific hematological conditions by removing disease-mediating immunoglobulins without depleting beneficial plasma components. Plasma purification applications occupy the most mature margin pool, while autoimmune disease treatment segments attract fastest-growing clinical adoption. Resin-based systems lead technology deployments, though membrane filtration alternatives compete in acute care settings where setup speed determines utilization.
FDA blood purification device regulations and EU MDR conformity requirements shape product development timelines and clinical evidence thresholds for market access. Japan's PMDA enforces additional post-market surveillance protocols that filter non-compliant suppliers from reimbursement lists. Stakeholders must monitor evolving CMS coding decisions for therapeutic apheresis procedures and anticipate how biosimilar pipeline expansion redirects antibody-removal demand across therapeutic and manufacturing applications.
Market Dynamics
Hospital procurement consolidation is compressing vendor margins while elevating clinical evidence requirements for immunoadsorption column suppliers seeking formulary inclusion.
Growth Catalysts
- EU MDR compliance deadlines:Stricter conformity assessment protocols are filtering out marginal suppliers and concentrating procurement among validated manufacturers with robust quality management systems.
- Therapeutic apheresis program expansion:Academic medical centers in Germany and Japan are scaling dedicated autoimmune disease treatment units, driving column consumption for plasma purification protocols.
- Synthetic peptide ligand advancement:Next-generation affinity matrices reduce protein A dependency and enable broader autoimmune indication coverage with improved batch consistency.
Market Restraints
- Specialized resin input concentration:Agarose and cellulose matrix supply chains cluster among a handful of European chemical processors, exposing manufacturers to raw material bottlenecks.
- FDA 510(k) pathway complexity:Blood purification device submissions face elongated review timelines as the agency tightens substantial equivalence thresholds for novel ligand chemistries.
- Membrane filtration substitution:Hollow-fiber plasma separators compete for acute care applications where rapid setup outweighs adsorption specificity.
Strategic Opportunities
- Japan's post-market surveillance differentiation:PMDA-compliant suppliers gain preferential reimbursement positioning as the agency strengthens adverse event reporting requirements.
- Cell therapy manufacturing adjacency:Magnetic separation expertise transfers into GMP-grade column production for ex vivo cell processing workflows.
- Outpatient apheresis center proliferation:Ambulatory treatment models in the United States create demand for compact, single-operator column systems outside traditional hospital infrastructure.
Industry Challenges
- Bioprocessing engineering scarcity:Talent pools for sterile device manufacturing and affinity chromatography process development remain shallow relative to expansion targets.
- EU MDR technical documentation burden:Clinical evaluation report requirements for legacy column products demand retrospective data aggregation that strains smaller operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Immunoadsorption Columns Market |
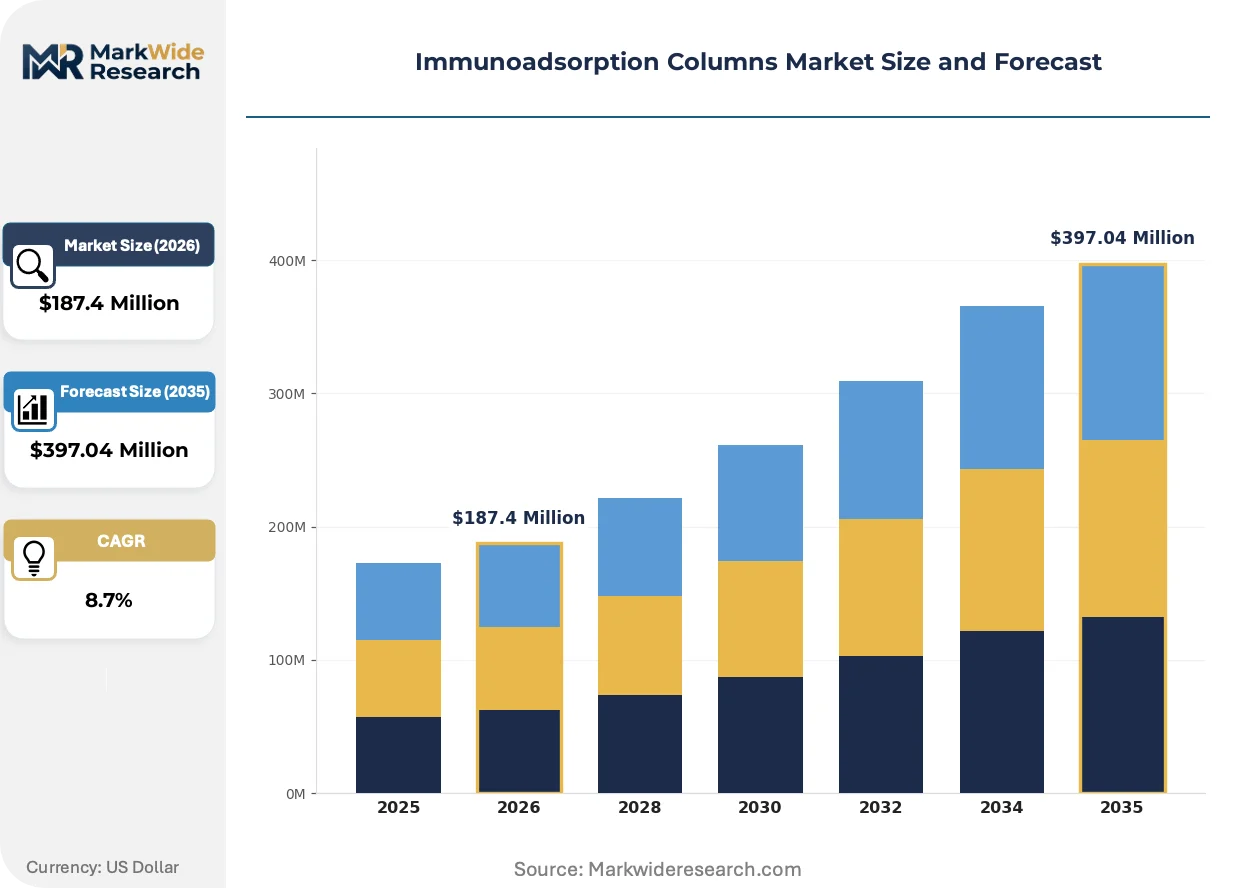
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plasma Purification, Autoimmune Disease Treatment, Antibody Removal, Affinity Chromatography End User: Hospitals, Research Laboratories, Blood Banks, Diagnostic Centers Technology: Column Chromatography, Membrane Filtration, Magnetic Separation, Resin-Based Systems Application: Therapeutic Apheresis, Drug Development, Clinical Research, Bioprocessing |
| Companies Covered | Fresenius Medical Care Adsorber Tec, Asahi Kasei Corporation, Miltenyi Biotec GmbH, POCARD Ltd, Jafron Biomedical Co Ltd, Guangzhou Kangsheng Biotechnology Co Ltd, Baxter International Inc, Kaneka Corporation, Terumo Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Immunoadsorption Columns Market Strategic Shifts
Affinity ligand engineering and regulatory data requirements are redefining competitive boundaries between resin-based and membrane-based plasma purification approaches.
Multi-modal synthetic peptide ligands are decomposing the traditional protein A monopoly in immunoadsorption applications. German hospital apheresis units are piloting these matrices for mixed immunoglobulin subclass removal. The technology is decomposing incumbent supplier lock-in by enabling indication-specific column customization without biological sourcing constraints.
Japan's PMDA has intensified post-market surveillance obligations for blood purification devices through enhanced adverse event reporting mandates. Manufacturers now face mandatory periodic safety update reports that extend beyond initial approval timelines. Transplant centers and autoimmune treatment facilities are prioritizing suppliers with established Japanese pharmacovigilance infrastructure.
Consolidated procurement by integrated delivery networks is compressing vendor rosters and elevating total-cost-of-ownership analytics over unit pricing. Group purchasing organizations in the United States are bundling column supply with apheresis service contracts. This concentration is most pronounced in multi-hospital health systems operating centralized therapeutic apheresis programs.
Immunoadsorption Columns Market Segmentation
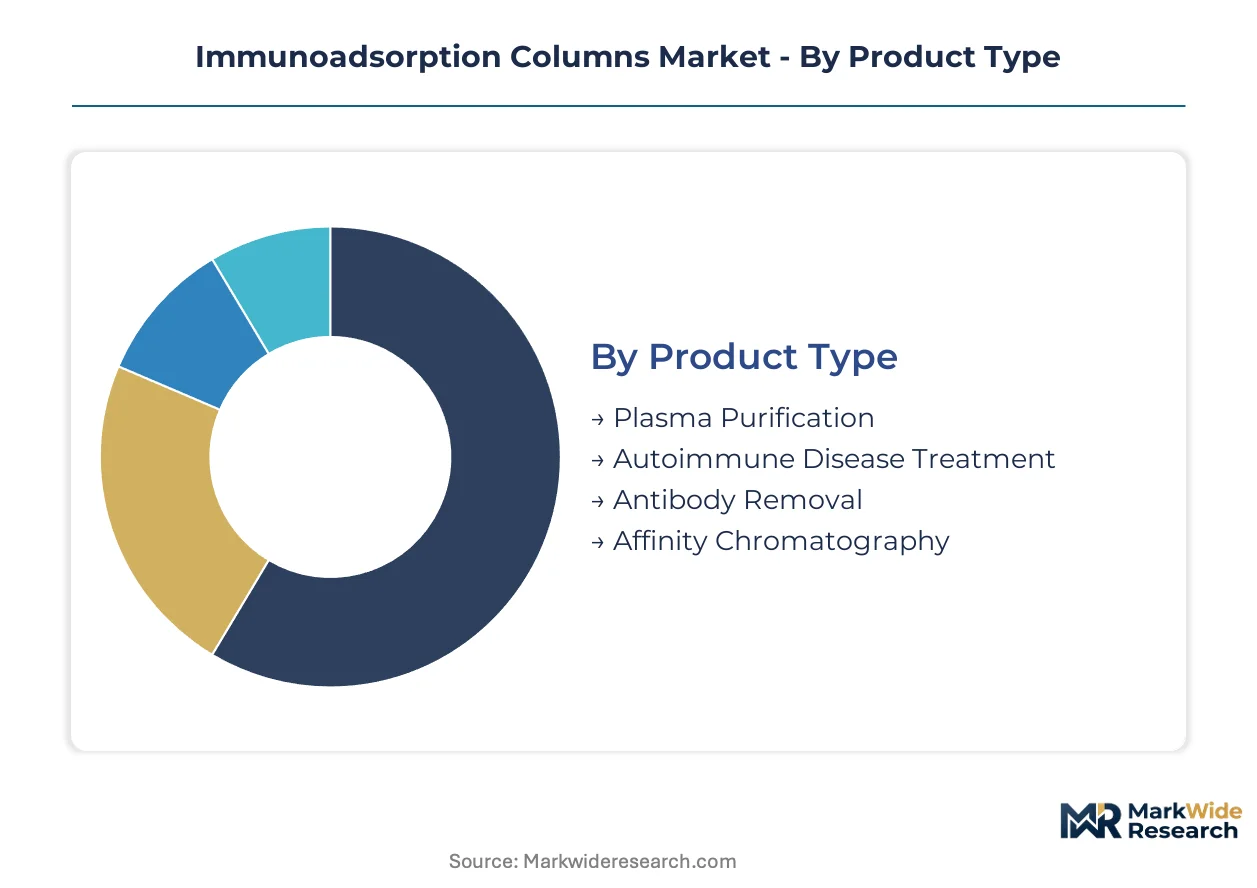
Segmentation in immunoadsorption columns determines manufacturing scale, regulatory pathway intensity, and procurement contract structures. Product type and application boundaries are blurring as multi-indication columns gain formulary traction.
Product Type:
FDA 510(k) and EU MDR submission requirements diverge sharply across indication-specific versus general-purpose column designs.
- Plasma Purification:Mature resin-based columns with protein A or synthetic peptide ligands dominate hospital apheresis programs. German and Japanese transplant centers drive procurement volume through standardized therapeutic protocols.
- Autoimmune Disease Treatment:Indication-specific ligand engineering enables selective immunoglobulin subclass removal. Academic medical centers in the United States and Germany are expanding dedicated treatment units, accelerating column consumption for conditions including myasthenia gravis and Guillain-Barré syndrome.
- Antibody Removal:Pre-transplant desensitization protocols utilize high-capacity matrices.
- Affinity Chromatography:GMP-grade production scales support cell therapy manufacturing workflows.
Established volume favors Plasma Purification; emerging adoption favors Autoimmune Disease Treatment.
End User:
Procurement authority and clinical evidence requirements create distinct margin tiers across customer categories.
- Hospitals:Integrated delivery networks consolidate purchasing through centralized therapeutic apheresis programs. Group purchasing organizations bundle column supply with service contracts, compressing vendor rosters toward manufacturers with vertically integrated dialysis-apheresis platforms.
- Research Laboratories:Academic and contract research organizations drive demand for customizable ligand chemistries and smaller batch sizes. Funding volatility constrains multi-year supply agreements.
- Blood Banks:National health service procurement frameworks govern volume.
- Diagnostic Centers:Limited therapeutic application scope restricts column utilization.
Margin concentration sits with Hospitals; flexibility requirements favor Research Laboratories.
Technology:
Setup speed versus binding specificity defines competitive positioning between physical separation modalities.
- Column Chromatography:Ligand-activated matrices packed in sterile single-use housings enable precise antibody subclass targeting. Resin-based deployments lead installed base across European hospital apheresis units.
- Membrane Filtration:Hollow-fiber plasma separators compete for acute care settings where rapid deployment outweighs adsorption specificity. Japanese emergency departments favor membrane systems for time-critical interventions.
- Magnetic Separation:Cell therapy manufacturing applications leverage paramagnetic bead architectures.
- Resin-Based Systems:Agarose and cellulose matrix supply chains cluster among European chemical processors.
Clinical precision favors Column Chromatography; speed-to-treatment favors Membrane Filtration.
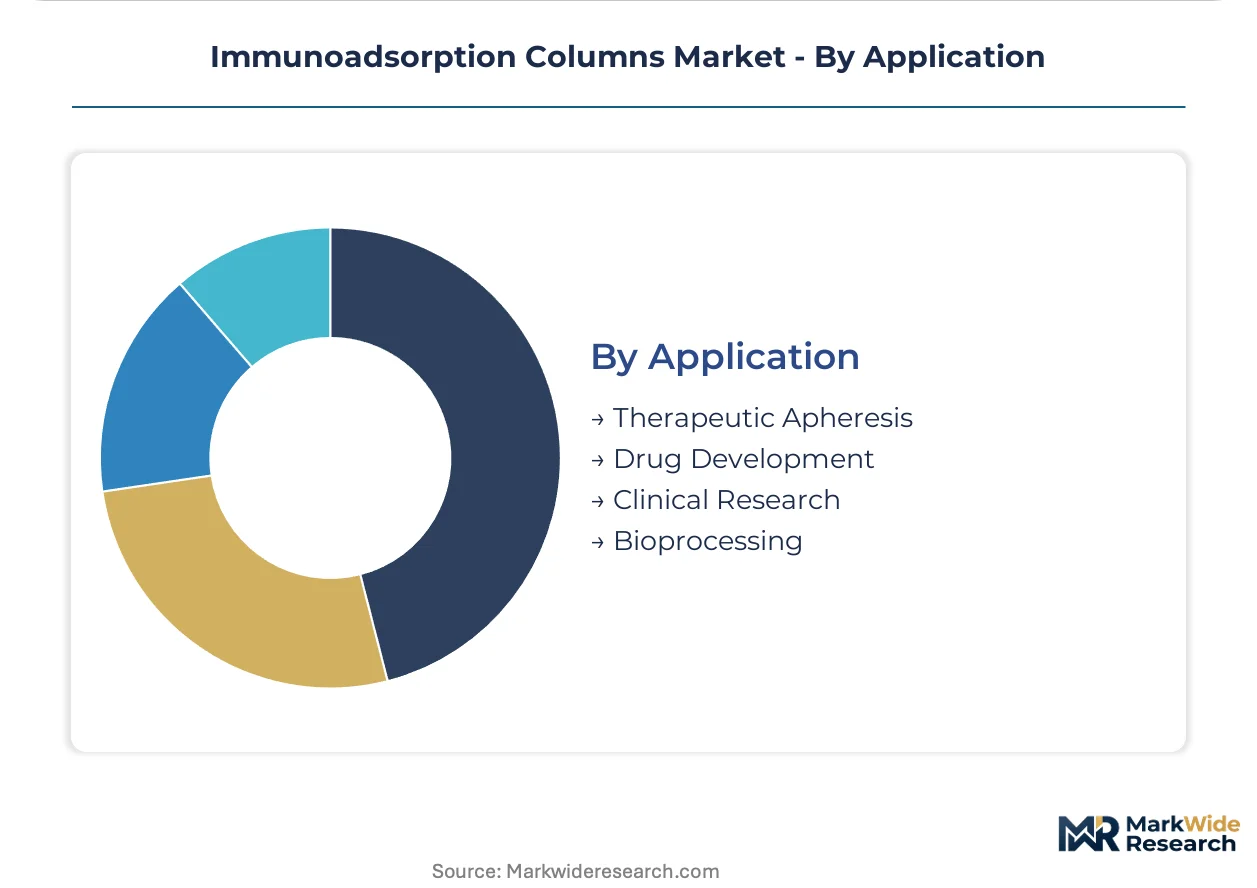
Application:
Reimbursement coding and evidence generation intensity vary across clinical versus non-clinical use cases.
- Therapeutic Apheresis:CMS coding decisions and DRG classifications directly shape hospital procurement economics. Outpatient center proliferation in the United States creates demand for compact, single-operator column systems.
- Drug Development:Biosimilar pipeline expansion redirects antibody-removal demand toward manufacturing-scale purification workflows. Contract development organizations prioritize suppliers with established GMP documentation packages.
- Clinical Research:Investigator-sponsored trials require flexible supply arrangements.
- Bioprocessing:Cell therapy manufacturing adjacency transfers magnetic separation expertise into GMP-grade production.
Reimbursement stability favors Therapeutic Apheresis; pipeline expansion favors Drug Development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA blood purification device regulations anchor the United States procurement environment, while EU MDR conformity deadlines reshape European competitive boundaries. Japan's PMDA post-market surveillance protocols filter supplier eligibility across Asia-Pacific reimbursement lists.
United States
Academic medical centers in Boston and Houston are expanding dedicated therapeutic apheresis programs for autoimmune disease treatment. CMS coding decisions for outpatient procedures directly shape hospital procurement economics. Integrated delivery networks in the Southeast are consolidating column supply contracts through group purchasing organization bundles.
Germany
Transplant centers in Berlin and Munich drive standardized plasma purification protocol adoption through hospital-based therapeutic apheresis programs. EU MDR technical documentation requirements for legacy column products strain smaller domestic operations. The Rhine-Ruhr cluster concentrates resin-based system manufacturing expertise among established chemical processors.
Japan
Emergency departments in Tokyo and Osaka favor membrane filtration systems for time-critical interventions where rapid deployment outweighs adsorption specificity. PMDA enhanced adverse event reporting mandates extend beyond initial approval timelines. The Kansai region anchors magnetic separation R&D intensity across medical materials divisions.
China
Domestic bioprocessing engineering talent is rotating toward immunoadsorption manufacturing hubs in Shanghai and Shenzhen. The country's national pharmaceutical regulator tightens quality benchmarks for blood purification devices entering reimbursement lists. Guangzhou-based operations specialize in compact single-operator column systems for ambulatory treatment models.
Switzerland
Swissmedic conformity assessment protocols for sterile single-use devices elevate clinical evidence thresholds for market access. Basel-area research laboratories drive demand for customizable ligand chemistries in investigator-sponsored trials. The country's precision manufacturing heritage supports GMP-grade column production for cell therapy manufacturing workflows.
Immunoadsorption Columns Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in immunoadsorption column supply. Fresenius Medical Care Adsorber Tec leverages vertically integrated dialysis-apheresis platforms to dominate European hospital procurement, while Asahi Kasei Corporation sustains membrane-separation R&D intensity. Three archetypes define competitive positioning: diversified medical technology conglomerates with captive apheresis platforms, specialized bioprocessing equipment fabricators with magnetic separation expertise, and regional column manufacturers serving domestic reimbursement systems. Capacity expansion in resin-based matrix production and strategic partnerships for synthetic peptide ligand development represent the dominant competitive moves.
Among diversified medical technology conglomerates, Fresenius Medical Care Adsorber Tec and Baxter International Inc exemplify the integrated-platform archetype through their vertically structured dialysis-apheresis operations. Asahi Kasei Corporation and Terumo Corporation occupy positions within the membrane-separation specialist tier, with the former representing sustained R&D intensity across medical materials divisions. Kaneka Corporation sits within the synthetic ligand engineering segment, exemplifying the transition from protein A dependency toward next-generation affinity matrices.
| Leading Market Players |
|---|
| Fresenius Medical Care Adsorber Tec |
| Asahi Kasei Corporation |
| Miltenyi Biotec GmbH |
| POCARD Ltd |
| Jafron Biomedical Co Ltd |
| Guangzhou Kangsheng Biotechnology Co Ltd |
| Baxter International Inc |
| Kaneka Corporation |
| Terumo Corporation |
| Others |
Value Chain & Pricing Dynamics
Synthetic peptide ligands displacing protein A dependency are redrawing procurement geography toward German chemical processors while compressing margin pools for legacy biological-sourced matrices. This substitution dynamic simultaneously elevates pricing power for synthetic ligand patent holders and exposes resin-based column manufacturers to agarose supply bottlenecks from concentrated European suppliers.
Pricing Analysis
German-manufactured resin-based columns command 15-25% premiums over Asian-produced alternatives in Japanese procurement tenders. Three-tier pricing structure across premium synthetic peptide, standard protein A, and economy cellulose matrices reflects certification grade and ligand engineering complexity. Pricing pressure stems from integrated delivery network bundling of column supply with apheresis service contracts. Academic medical centers exhibit lowest price sensitivity due to clinical evidence requirements, while outpatient apheresis centers prioritize total-cost-of-ownership over unit pricing.
Supply Chain Analysis
Container availability constraints on Rotterdam-Shanghai lanes have elevated inbound logistics costs for agarose matrix imports by European column manufacturers. Agarose and cellulose raw materials draw from German, Dutch, and Spanish chemical processors with limited alternative sourcing. Single-source vulnerability concentrates in protein A biological production from Danish and Irish suppliers. Distribution runs through hospital group purchasing organizations in the United States and national health service frameworks in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The immunoadsorption column market sits at a platform-economics inflection where vertically integrated dialysis-apheresis ecosystems are displacing standalone column vendors through service-contract bundling and interoperability lock-in.
For Market Incumbents: Secure synthetic peptide ligand patent positions ahead of EU MDR technical documentation deadlines for legacy product transitions. Deepen backward integration into agarose matrix production through Rhine-Ruhr chemical processor partnerships to defend against raw material bottlenecks. Prioritize PMDA pharmacovigilance infrastructure investment to maintain Japanese reimbursement list eligibility against emerging membrane filtration substitutes. For New Entrants and Emerging Players: Anchor in United States outpatient apheresis center proliferation where compact single-operator system demand outpaces established vendor coverage. Target ambulatory treatment models in the Southeast and Southwest regions with GMP-grade magnetic separation architectures transferable from cell therapy manufacturing workflows. Pursue investigator-sponsored trial partnerships with Boston and Houston academic medical centers to generate clinical evidence without hospital formulary barriers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized bioprocessing equipment fabricators with magnetic separation expertise and established Japanese regulatory infrastructure. Long-term viability hinges on synthetic ligand engineering capabilities and GMP-grade production scalability rather than commodity resin packing. Monitor EU MDR conformity assessment bottlenecks as an inflection signal for distressed acquisition opportunities among legacy column manufacturers facing retrospective data aggregation costs.| Strategic Initiative | Industry Significance |
|---|---|
| Synthetic Peptide Ligand Patent Expansion | Enables indication-specific column customization without biological sourcing constraints from Danish suppliers. |
| PMDA Pharmacovigilance Infrastructure Buildout | Secures preferential reimbursement positioning as Japanese adverse event reporting mandates intensify. |
| Backward Integration into Agarose Production | Reduces exposure to Rhine-Ruhr chemical processor concentration and raw material bottlenecks. |
| Outpatient Apheresis Center Partnership | Captures ambulatory treatment demand outside traditional hospital procurement consolidation. |
| EU MDR Technical Documentation Outsourcing | Addresses clinical evaluation report burdens straining smaller legacy column operations. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with hospital apheresis program directors, GPO contracts managers, biomedical engineers, and regulatory affairs specialists; and secondary validation against FDA 510(k) filings, EMA MDR technical documentation, Japanese PMDA adverse event databases, and hospital procurement contract records. Bottom-up demand modeling from therapeutic apheresis procedure volumes triangulated with top-down market sizing from manufacturer capacity disclosures.
Across the analysis window, forecasts employed segment-specific growth coefficients calibrated by technology type, application, and end-user procurement authority. Modeled dimensions included resin-based versus membrane filtration versus magnetic separation architectures, therapeutic apheresis versus drug development versus bioprocessing applications, and hospital versus outpatient center versus research laboratory end users. CAGRs derived from procedure volume elasticity to autoimmune disease prevalence, transplant waitlist dynamics, and cell therapy manufacturing pipeline expansion.
Decision-makers should treat outputs as directional under assumptions of stable EU MDR enforcement timelines and continued Japanese PMDA post-market surveillance intensification; material deviation in regulatory pacing or biosimilar pipeline redirection would warrant model refresh. Recalibration cycles align with material shifts in CMS coding decisions, synthetic peptide ligand patent expiries, and hospital procurement consolidation waves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Patient-Controlled Analgesic Pumps Market
Medical Devices
High Frequency Ventilators Market
Medical Devices
Concentrator O2 Devices Market
Medical Devices
Epilepsy Devices Market
Medical Devices
Organ Preservation & Perfusion Products Market
Medical Devices
Catheter Securement Devices Market
Medical Devices
Intraosseous Infusion Device Market
Medical Devices
Cystic Fibrosis Devices Market
Medical Devices
Thermal Ablation Devices Market
Medical Devices
Direct-Skin Wearable Medical Devices Market
Medical Devices
Point-Of-Care Ultrasound (Pocus) Device Market
Medical Devices
Global Intravenous (IV) Equipment Market
Medical Devices
3D Printed Hip and Knee Implants Market
Medical Devices
Global Pneumatic Tourniquets Market
Medical Devices
Brazil Angioplasty Devices Market
Medical Devices
Direct Energy Medical Devices Market