
 Stuttering Therapeutics Market | 2026-2036
Stuttering Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Stuttering Therapeutics Market Analytics
The EU Green Deal's emphasis on sustainable healthcare procurement is recalibrating how pharmaceutical suppliers approach environmental accountability in neurology-focused drug manufacturing. Johnson & Johnson leverages its broad therapeutic portfolio to sustain diversified R&D pipelines across speech and motor disorders. Pfizer anchors its presence through established central nervous system research capabilities, while Novartis differentiates via targeted investments in rare and orphan neurological conditions.
Stuttering therapeutics encompass pharmacological agents, behavioral interventions, assistive technologies, and speech therapy protocols designed to reduce disfluency frequency and severity through modulation of dopaminergic pathways, operant conditioning, or real-time auditory feedback. These interventions serve pediatric and adult patients whose communication impairment limits educational attainment, employment advancement, and social participation. Speech therapy retains the largest patient volume share, though pharmacotherapy commands higher per-patient revenue due to ongoing prescription requirements. Hybrid delivery models are expanding fastest as telehealth reimbursement stabilizes and mobile app integration improves adherence monitoring.
The US FDA oversees investigational new drug applications for stuttering pharmacotherapies, while the EMA shapes parallel development pathways in Europe through its centralized pediatric investigation plans. HIPAA compliance requirements in the United States and GDPR data handling rules in Europe directly constrain how digital therapy platforms collect and process patient speech biometric data. Stakeholders must monitor regulatory divergence between jurisdictions as artificial intelligence-enabled diagnostic tools enter clinical validation, since fragmented approval standards will determine which platforms achieve scalable market access.
Market Dynamics
Telehealth reimbursement stabilization in the United States is compressing patient acquisition costs for speech-language pathology networks while fragmenting service delivery across hybrid platforms. This structural shift is redistributing volume toward digital-native providers and forcing traditional clinic operators to reconfigure their physical footprints.
Growth Catalysts
- HIPAA-compliant telehealth infrastructure:Reimbursement parity laws in multiple US states now cover synchronous video-based speech therapy, expanding addressable patient populations beyond metropolitan clinic catchments.
- Pediatric investigation plans:The EMA's centralized pediatric investigation plan framework accelerates approval timelines for dopaminergic modulators targeting developmental stuttering in European markets.
- Mobile application integration:Real-time auditory feedback algorithms embedded in consumer smartphones are converging with clinical protocols, enabling between-session practice monitoring that improves adherence metrics.
Market Restraints
- Specialized clinician scarcity:Board-certified fluency specialists concentrate in coastal US metropolitan areas, creating access deserts in rural counties and secondary cities.
- Pharmacotherapy development risk:Central nervous system drug candidates face elevated FDA safety scrutiny due to off-target dopaminergic effects, extending Phase II timelines.
- Behavioral intervention substitution:Unlicensed mobile applications offering delayed auditory feedback compete directly with reimbursed clinical services at price points below insurance copays.
Strategic Opportunities
- School-based Medicaid expansion:US states with expanded Medicaid coverage now reimburse telehealth services delivered in K-12 settings, opening institutional procurement channels.
- AI-enabled diagnostic validation:Speech biometric classification algorithms are converging with electronic health record integration, creating workflow efficiencies for large health system contracts.
- Employer-sponsored wellness programs:Communication coaching for client-facing professionals represents an emerging self-pay segment with premium pricing tolerance.
Industry Challenges
- Cross-border credentialing complexity:Speech-language pathologists licensed in one US state face inconsistent reciprocity agreements, complicating multi-state telehealth platform staffing.
- Digital therapeutic classification uncertainty:FDA software-as-medical-device determinations for stuttering applications remain case-specific, delaying commercialization roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stuttering Therapeutics Market |
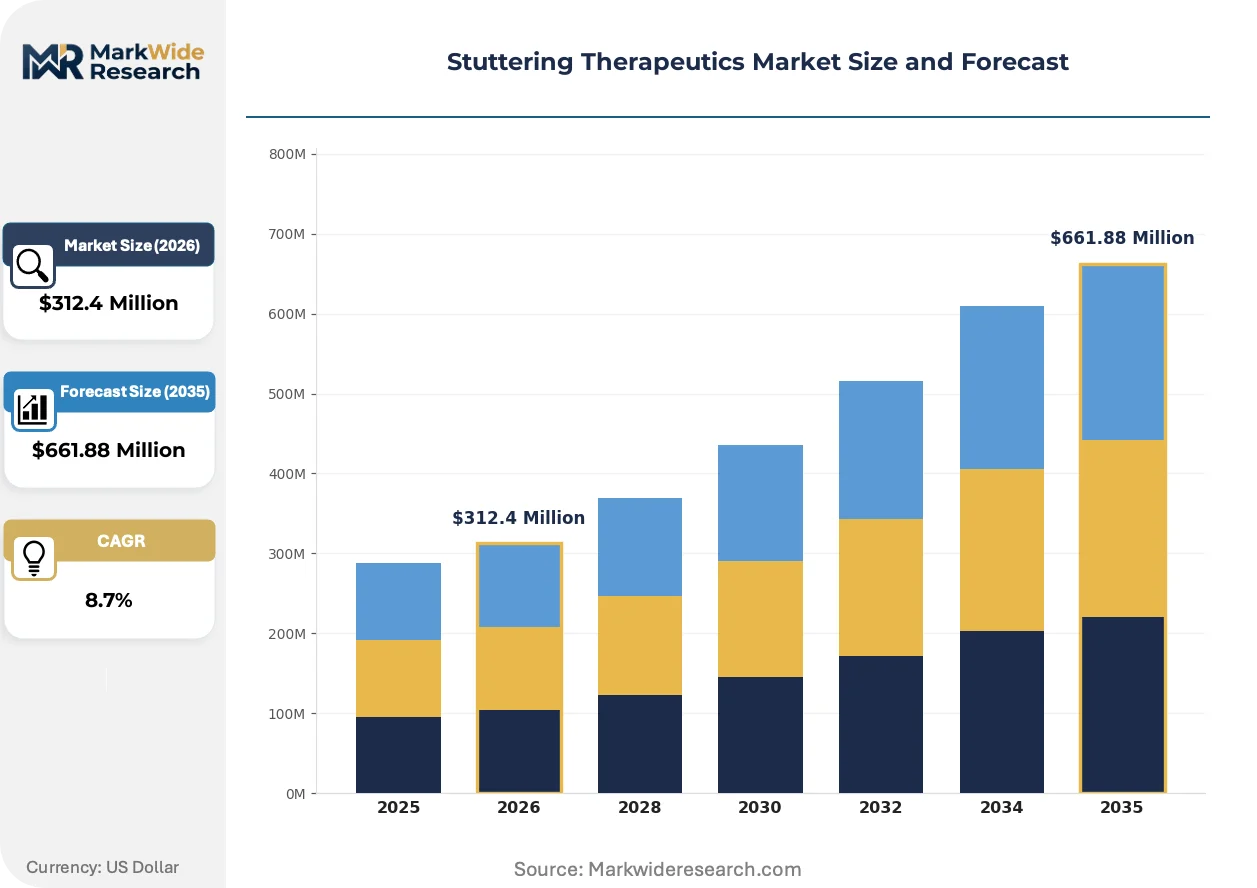
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Speech Therapy, Pharmacotherapy, Behavioral Interventions, Assistive Devices Delivery Mode: In-Person, Online, Mobile Apps, Hybrid End User: Pediatric Patients, Adult Patients, Clinicians, Educators Therapy Approach: Cognitive Behavioral Therapy, Fluency Shaping, Desensitization, Support Groups |
| Companies Covered | Auspex Pharmaceuticals, GlaxoSmithKline, Johnson & Johnson, Merck, Pfizer, Novartis, AstraZeneca, AbbVie, Signum Biosciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stuttering Therapeutics Market Evolving Landscape
Artificial intelligence is penetrating diagnostic and therapeutic workflows through speech signal processing advances that enable real-time disfluency classification. These capabilities are compressing the traditional assessment-to-treatment interval while generating novel data assets for outcome validation.
Machine learning-based acoustic analysis is converging with cloud-based therapy platforms. Pediatric clinics in the United States are adopting these tools at accelerating rates to standardize severity scoring across remote sessions. The technology is converging with traditional face-to-face protocols, enabling hybrid models that retain reimbursement eligibility while reducing per-patient facility costs.
The EU AI Act's risk classification framework for biometric identification systems is reshaping development priorities for European digital therapy vendors. Speech pattern recognition algorithms now face conformity assessment requirements before market placement. Developers targeting European health systems are restructuring their technical documentation to satisfy notified body scrutiny, prioritizing explainability features that satisfy clinical validation standards.
Large employers in the United States are unbundling communication coaching from comprehensive disability coverage, creating direct contracting opportunities for specialized stuttering programs. Financial services and legal sectors with high client-interaction demands are sourcing these services through employee assistance program administrators. This procurement evolution is most visible in Manhattan and London, where professional services firms compete for talent through differentiated wellness offerings.
Stuttering Therapeutics Market Segmentation
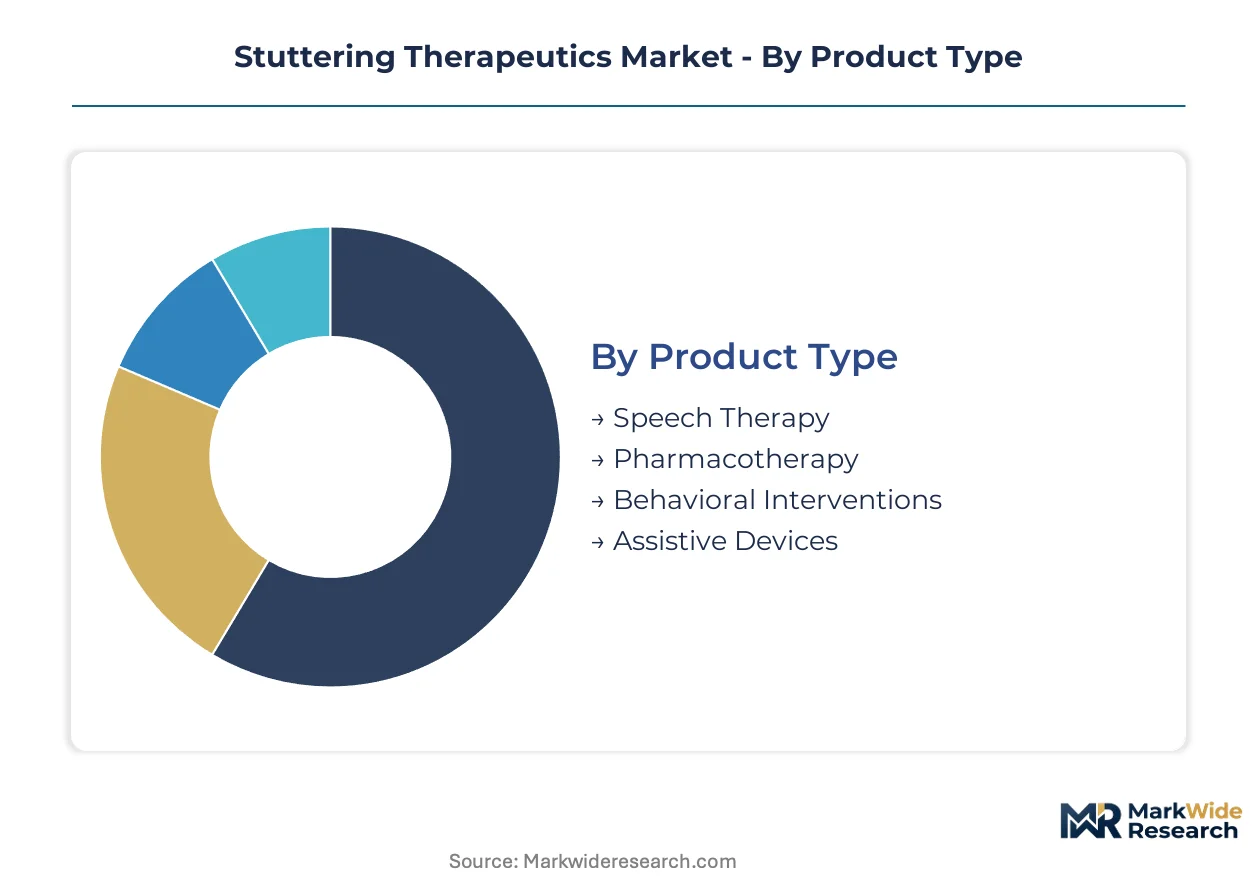
Stuttering therapeutics fragment across intervention modalities that differ fundamentally in reimbursement eligibility, clinician involvement, and patient adherence mechanics. Segmentation reveals where capital is concentrating versus where volume expansion is occurring.
Product Type:
Speech therapy operates as the standalone foundation of clinical practice, while pharmacotherapy and assistive technologies increasingly embed within hybrid care protocols.
- Speech Therapy:Face-to-face or telehealth-delivered protocols administered by licensed speech-language pathologists using fluency shaping and stuttering modification techniques. Demand concentrates in US pediatric clinics where Medicaid reimbursement for telehealth services has stabilized, though clinician scarcity in rural counties constrains expansion.
- Pharmacotherapy:Dopaminergic modulators and other central nervous system agents targeting neurotransmitter pathways implicated in stuttering pathophysiology. Development pipelines face elevated FDA safety scrutiny due to off-target effects, extending Phase II timelines and elevating per-patient revenue through ongoing prescription requirements.
- Behavioral Interventions:Operant conditioning protocols and self-managed practice regimens.
- Assistive Devices:Delayed auditory feedback hardware and wearable speech processors.
Speech therapy leads volumes today; pharmacotherapy is gaining share fastest.
Delivery Mode:
Cost tier separation distinguishes reimbursed clinical encounters from self-pay digital alternatives, with hybrid models capturing margin expansion.
- In-Person:Traditional clinic-based sessions with direct clinician supervision. Concentrates in coastal US metropolitan areas where board-certified fluency specialists cluster, creating access deserts in secondary cities and rural regions.
- Hybrid:Synchronous video sessions supplemented by between-session mobile app practice. Expanding most quickly as US states implement reimbursement parity laws and pediatric clinics reconfigure physical footprints to reduce per-patient facility costs.
- Online:Fully remote synchronous platforms.
- Mobile Apps:Consumer-grade delayed auditory feedback applications.
Hybrid delivery climbs the fastest; in-person retains the highest reimbursement rates.
End User:
Application context separates institutional procurement through schools and health systems from individual patient self-selection.
- Pediatric Patients:Children and adolescents undergoing developmental stuttering intervention. US states with expanded Medicaid coverage now reimburse telehealth services delivered in K-12 settings, opening institutional procurement channels beyond traditional clinic networks.
- Adult Patients:Persistent developmental stuttering or acquired neurogenic stuttering cases. Employer-sponsored wellness programs in financial and legal sectors create direct contracting opportunities for communication coaching with premium pricing tolerance.
- Clinicians:Speech-language pathologists and fluency specialists.
- Educators:School-based intervention coordinators and special education staff.
Pediatric patients dominate volume; adult patients through employer channels show steepest expansion trajectory.
Therapy Approach:
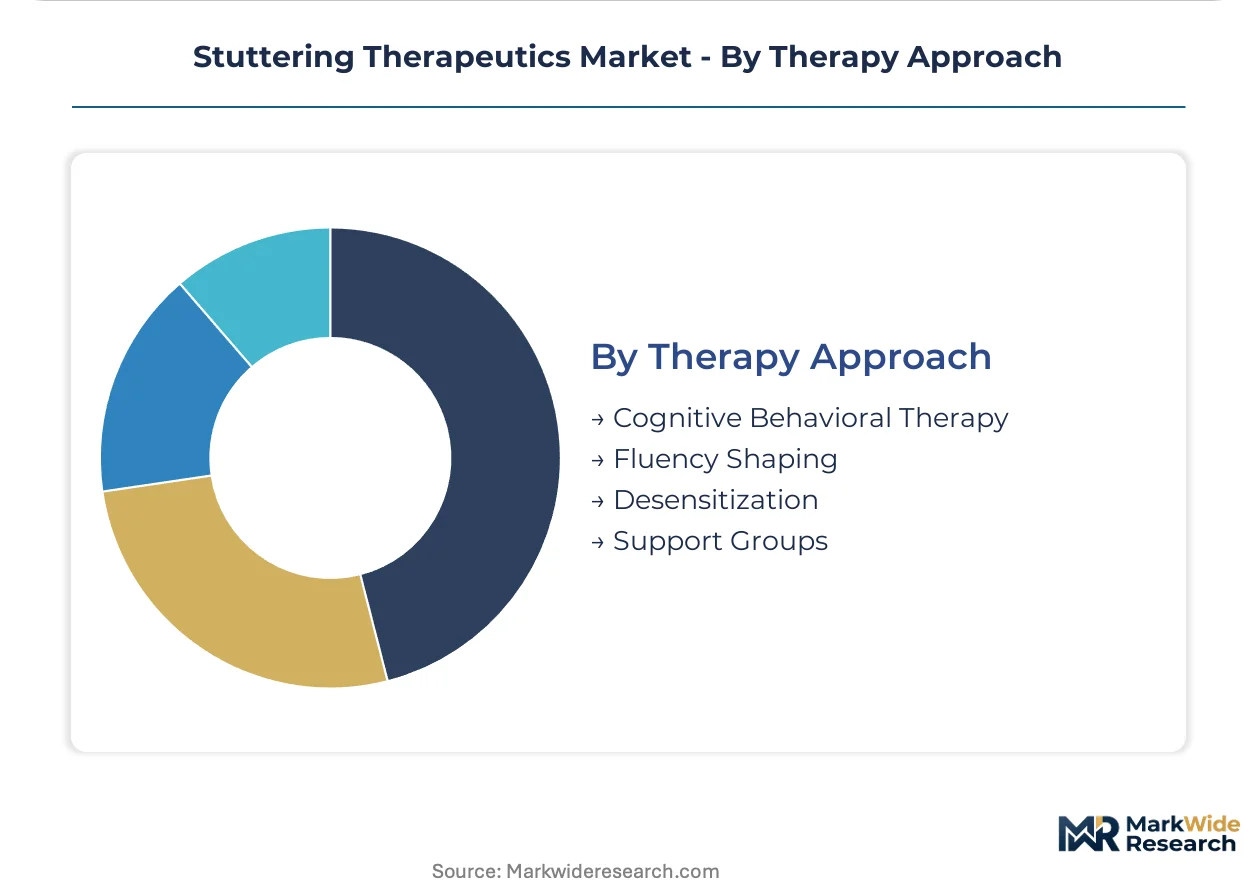
Maturity differentiation separates established evidence-based protocols from emerging integrative modalities.
- Fluency Shaping:Structured protocols targeting speech rate, breathing patterns, and phonation onset. Remains the reimbursement standard in US commercial insurance and Medicare Advantage plans, with AI-enabled acoustic analysis now standardizing severity scoring across remote sessions.
- Cognitive Behavioral Therapy:Anxiety and avoidance reduction protocols addressing the psychological sequelae of stuttering. Integrating with speech biometric classification algorithms for outcome validation, creating workflow efficiencies for large health system contracts.
- Desensitization:Graduated exposure to feared speaking situations.
- Support Groups:Peer-led maintenance and community reinforcement.
Fluency shaping holds established share; cognitive behavioral therapy is expanding most quickly through digital platform integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Speech-language pathology as a clinical discipline traces its modern therapeutic foundations to mid-20th century university research programs in the United States and United Kingdom, where fluency shaping protocols were first systematized for developmental stuttering intervention. These academic medical centers established the credentialing frameworks and evidence standards that now govern reimbursement eligibility across developed healthcare systems.
United States
Specialized speech-language pathology networks and reimbursed telehealth infrastructure create favorable access conditions for stuttering intervention. HIPAA compliance requirements constrain how digital therapy platforms collect patient speech biometric data, while FDA oversight shapes investigational new drug applications for dopaminergic modulators. Board-certified fluency specialists concentrate in coastal metropolitan areas like Boston, New York, and San Francisco, leaving access deserts in rural counties.
United Kingdom
The National Health Service funds speech and language therapy through integrated care boards, with demand concentrating in England's urban centers. GDPR data handling rules directly constrain digital therapy platform operations, while the EMA's centralized pediatric investigation plans accelerate approval timelines for pharmacotherapies targeting developmental stuttering. London's academic medical centers anchor clinical research activity and specialist training programs.
Germany
Statutory health insurance covers speech therapy with physician referral, creating stable reimbursement pathways for fluency intervention. The EU AI Act's risk classification framework for biometric identification systems is reshaping development priorities for domestic digital therapy vendors. Munich and Berlin host concentrated clusters of university-affiliated speech clinics and health technology startups.
Canada
Provincial health plans reimburse speech-language pathology services with varying eligibility criteria across Ontario, British Columbia, and Quebec. Health Canada regulates medical device software classifications for stuttering applications, creating case-specific approval pathways. Toronto's hospital-affiliated research institutes drive pediatric stuttering outcome studies and telehealth protocol validation.
Australia
Medicare provides limited reimbursement for speech pathology services, with private health insurance filling coverage gaps for adult stuttering intervention. The Therapeutic Goods Administration oversees software-as-medical-device determinations for digital therapy platforms. Sydney and Melbourne concentrate specialist clinician networks and university-based fluency research programs.
Stuttering Therapeutics Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the pharmacotherapy-digital therapy divide, with central nervous system drug developers commanding higher per-patient revenue through ongoing prescription requirements while telehealth platforms compete on patient acquisition efficiency. The vendor base stratifies into three tiers: diversified pharmaceutical conglomerates with established neuroscience pipelines, specialized biotechnology firms targeting orphan neurological indications, and digital health startups integrating mobile applications with synchronous clinical delivery. Consolidation pressure is building as reimbursement stabilization favors scaled telehealth networks, while FDA software-as-medical-device determinations remain case-specific and delay commercialization timelines for emerging platforms.
Among diversified pharmaceutical conglomerates, Johnson & Johnson, Pfizer, and Novartis occupy positions that exemplify contrasting strategic archetypes within the central nervous system therapeutic space. Johnson & Johnson represents the broad therapeutic portfolio approach that sustains diversified research and development pipelines across speech and motor disorders. Pfizer anchors its presence through established neuroscience research capabilities that span multiple neurological conditions. Novartis differentiates via targeted investments in rare and orphan neurological conditions, a positioning that aligns with the specialized nature of persistent developmental stuttering populations. These three entities collectively illustrate how incumbent pharmaceutical firms navigate the intersection of behavioral intervention substitution risk and pharmacotherapy development complexity.
| Leading Market Players |
|---|
| Auspex Pharmaceuticals |
| GlaxoSmithKline |
| Johnson & Johnson |
| Merck |
| Pfizer |
| Novartis |
| AstraZeneca |
| AbbVie |
| Signum Biosciences |
| Others |
Value Network & Pricing Analysis
Board-certified fluency specialists clustering in coastal US metropolitan areas create labor-cost differentials that widen pricing-tier spreads between premium in-person clinical services and economy digital alternatives. Speech-language pathology networks in Boston, New York, and San Francisco command reimbursement rates that rural telehealth platforms cannot match, fragmenting the market across credential-based price bands.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates reimbursed face-to-face sessions from hybrid telehealth bundles and consumer-grade mobile applications. Quality grade tied to clinician certification level and HIPAA-compliant platform infrastructure drives price differentiation, while cost compression in the economy tier intensifies because unlicensed delayed auditory feedback apps undercut insurance copays. Employer-sponsored wellness programs in financial and legal sectors show the least price sensitivity, whereas Medicaid-dependent pediatric families concentrate in the most price-sensitive segment.
Supply Chain Analysis
Domestic-content mandates in US federal procurement are reshaping sourcing for school-based Medicaid telehealth infrastructure, pushing vendors toward American-built HIPAA-compliant platforms. Hardware supply for assistive devices draws from Taiwan, South Korea, and China, while dopaminergic modulator APIs rest on Indian and Chinese pharmaceutical manufacturing. Single-source vulnerability in FDA-approved central nervous system drug ingredients creates supply chain risk. Distribution runs through specialized speech-language pathology networks, health system GPOs, and direct-to-consumer digital storefronts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as demand shifts toward AI-enabled diagnostic validation and hybrid care protocols that command premium reimbursement. Pediatric clinics and employer wellness programs now specify outcome-monitoring capabilities as table stakes for vendor selection.
For Market Incumbents: Hedge against behavioral intervention substitution by acquiring digital therapy platforms with validated speech biometric algorithms. Consolidate backward integration into AI-enabled acoustic analysis tools to defend margin position against unlicensed mobile app competitors. Lock in multi-year hospital system contracts before FDA software-as-medical-device determinations clarify competitive boundaries.
For New Entrants and Emerging Players: Begin with school-based Medicaid expansion in US states with telehealth reimbursement parity, the most penetrable channel for institutional procurement. Target rural access deserts where board-certified fluency specialist scarcity creates unmet demand. Pursue direct contracting with employee assistance program administrators as the go-to-market angle for adult communication coaching services.
For Investors and Strategic Acquirers: Diversified pharmaceutical conglomerates with central nervous system pipelines are the most active acquirers in this space, seeking digital therapeutic assets to complement pharmacotherapy development. Long-term viability hinges on reimbursement stabilization for hybrid delivery models. Watch for FDA software-as-medical-device determinations for stuttering applications as the inflection signal indicating which platforms achieve scalable market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | FDA Phase II studies for dopaminergic modulators face elevated safety scrutiny extending timelines. |
| Regulatory Approval Pathway | EMA centralized pediatric investigation plans accelerate European market entry for developmental stuttering pharmacotherapies. |
| Platform Integration | Mobile app convergence with synchronous telehealth protocols enables between-session adherence monitoring for pediatric clinics. |
| Strategic Partnership | Health system GPO contracts with AI-enabled diagnostic vendors compress assessment-to-treatment intervals. |
| Reimbursement Strategy | Medicaid telehealth parity laws in multiple US states expand addressable patient populations beyond metropolitan catchments. |
Research Methodology
Bottom-up patient-volume modeling reconciled against top-down pharmaceutical pipeline tracking forms the analytical core of this study. Primary interviews with speech-language pathology clinic directors, health system GPO contracts managers, FDA regulatory affairs consultants, and pediatric Medicaid program administrators combined with secondary validation against FDA investigational new drug filings, ClinicalTrials.gov registries, CMS Medicare reimbursement databases, and state-level telehealth parity legislation. Triangulation across these sources anchors market sizing and growth projections.
Historical trendline analysis of speech therapy service volumes, pharmacotherapy development timelines, and digital health platform adoption patterns informed the analytical framework across the projection horizon. Segmentation dimensions modeled include intervention modality, delivery mode, end-user population, and therapy approach, with regional regulatory clusters capturing FDA, EMA, and Health Canada pathway differences. CAGRs derive from fitted growth curves applied to validated baseline estimates, with AI-enabled diagnostic penetration and telehealth reimbursement stability as key forecast inputs.
Several conditions sit outside the modeled scope, including off-label pharmaceutical use, non-reimbursed wellness coaching outside employer channels, and experimental neurostimulation devices lacking regulatory validation. Forecasts reflect documented assumptions about reimbursement policy continuity and regulatory approval timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Enzyme Replacement Therapy Market
Specialty Medicine
Global Prurigo Nodularis Treatment Market
Specialty Medicine
Global Restless Legs Syndrome Market
Specialty Medicine
Biliary Atresia Treatment Market
Specialty Medicine
Global Overactive Bladder Treatment Market
Specialty Medicine
Acute Intermittent Porphyria Market
Specialty Medicine
Folliculotropic Mycosis Fungoides Treatment Market
Specialty Medicine
Inflammatory Diseases Market
Specialty Medicine
Bronchiectasis Therapeutic Market
Specialty Medicine
Leukemia Inhibitory Factor (LIF) Market
Specialty Medicine
Global Chondrosarcoma Market
Specialty Medicine
Chronic Myelogenous Leukemia Treatment Market
Specialty Medicine
Bartter Syndrome Treatment Market
Specialty Medicine
Peptide-Based Metabolic Disorders Therapeutics Market
Specialty Medicine
Allergic Conjunctivitis Market
Specialty Medicine
Global Chronic Lymphocytic Leukemia Therapeutics Market