
 Dural Arteriovenous Fistulas Treatment Market | 2026-2036
Dural Arteriovenous Fistulas Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Dural Arteriovenous Fistulas Treatment Market Analysis
Image-guided catheter navigation is narrowing the gap between diagnostic precision and therapeutic delivery in dural arteriovenous fistula interventions. Medtronic leverages its integrated neurovascular platform to sustain leadership in embolization coil and flow diversion technologies. Boston Scientific anchors its position through specialized liquid embolic systems designed for high-flow fistula occlusions. Stryker competes across the surgical resection segment with advanced visualization tools that complement endovascular approaches.
Dural arteriovenous fistulas represent abnormal direct connections between dural arteries and venous sinuses or cortical veins, typically classified by Cognard or Borden grading systems based on venous drainage patterns and hemorrhage risk; these lesions require intervention when cortical venous reflux or venous hypertension threatens neurological function. Endovascular embolization dominates procedural volume due to its minimally invasive profile and expanding liquid embolic options, while stereotactic radiosurgery occupies a niche for surgically inaccessible lesions with favorable angioarchitecture. Hospitals capture the largest share of treatment site revenue through comprehensive neurovascular teams, though ambulatory surgical centers are gaining traction for select low-complexity diagnostic and follow-up procedures.
FDA 510(k) clearance pathways and EU MDR conformity assessment shape device commercialization timelines and clinical evidence requirements for neurovascular manufacturers. Japan's PMDA enforces stringent post-market surveillance for embolic agents, influencing R&D prioritization across Asia-Pacific regulatory submissions. Stakeholders must monitor evolving reimbursement thresholds for liquid embolics and flow diverters as health technology assessment bodies tighten value demonstration standards.
Market Dynamics
Image-guided catheter navigation systems are compressing the gap between diagnostic angiography and therapeutic embolization, forcing device manufacturers to integrate navigation hardware with liquid embolic delivery platforms rather than selling standalone coils or detachable balloons.
Growth Catalysts
- Liquid embolic material innovation:Onyx and n-BCA formulations with controlled polymerization rates enable precise fistula occlusion without proximal flow arrest, expanding treatable lesion complexity in neurovascular centers across Germany, Japan, and the United States.
- FDA 510(k) premarket notification streamlining:Expedited clearance pathways for neurovascular embolization devices with predicate equivalence claims accelerate commercialization timelines for next-generation flow diverters and detachable coil systems.
- Specialized fellowship training expansion:Endovascular neurosurgery residency programs at tertiary hospitals in Boston, Tokyo, and Heidelberg are producing operators capable of managing high-grade Cognard Type IV and V fistulas previously relegated to open surgery.
Market Restraints
- Platinum and iridium alloy cost volatility:Embolization coil manufacturing depends on precious metal feedstocks subject to commodity price swings and concentrated mining output from South Africa and Russia.
- Single-source dependency for ethylene-vinyl alcohol copolymers:Liquid embolic precursor supply concentrates with two specialty chemical manufacturers, creating vulnerability for Boston Scientific and Medtronic formulation pipelines.
- EU MDR clinical evidence escalation:Conformity assessment for Class III neurovascular devices now requires prospective registry data, extending time-to-market by 18-24 months versus the prior Medical Device Directive framework.
Strategic Opportunities
- Ambulatory surgical center penetration:Low-complexity diagnostic cerebral angiography and follow-up DSA procedures are migrating to ASCs in Florida, Texas, and Arizona where state-level CON reforms enable outpatient neurovascular service lines.
- Artificial intelligence angiographic analysis:Machine learning algorithms for automated fistula classification and venous drainage pattern quantification are converging with PACS infrastructure to reduce inter-observer variability in treatment planning.
- Japan PMDA post-market surveillance data monetization:Longitudinal safety databases for embolic agents create competitive differentiation for manufacturers with decade-plus Japanese commercial presence versus recent market entrants.
Industry Challenges
- Dual-trained operator scarcity:The intersection of open cerebrovascular surgery skill and endovascular catheter proficiency remains rare, limiting case volume expansion at community hospitals without academic affiliation.
- EMR-PACS integration complexity:Angiographic workflow tools from Stryker, Siemens, and GE require custom HL7 FHIR interfaces with Epic and Cerner deployments, extending implementation timelines and IT capital requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dural Arteriovenous Fistulas Treatment Market |
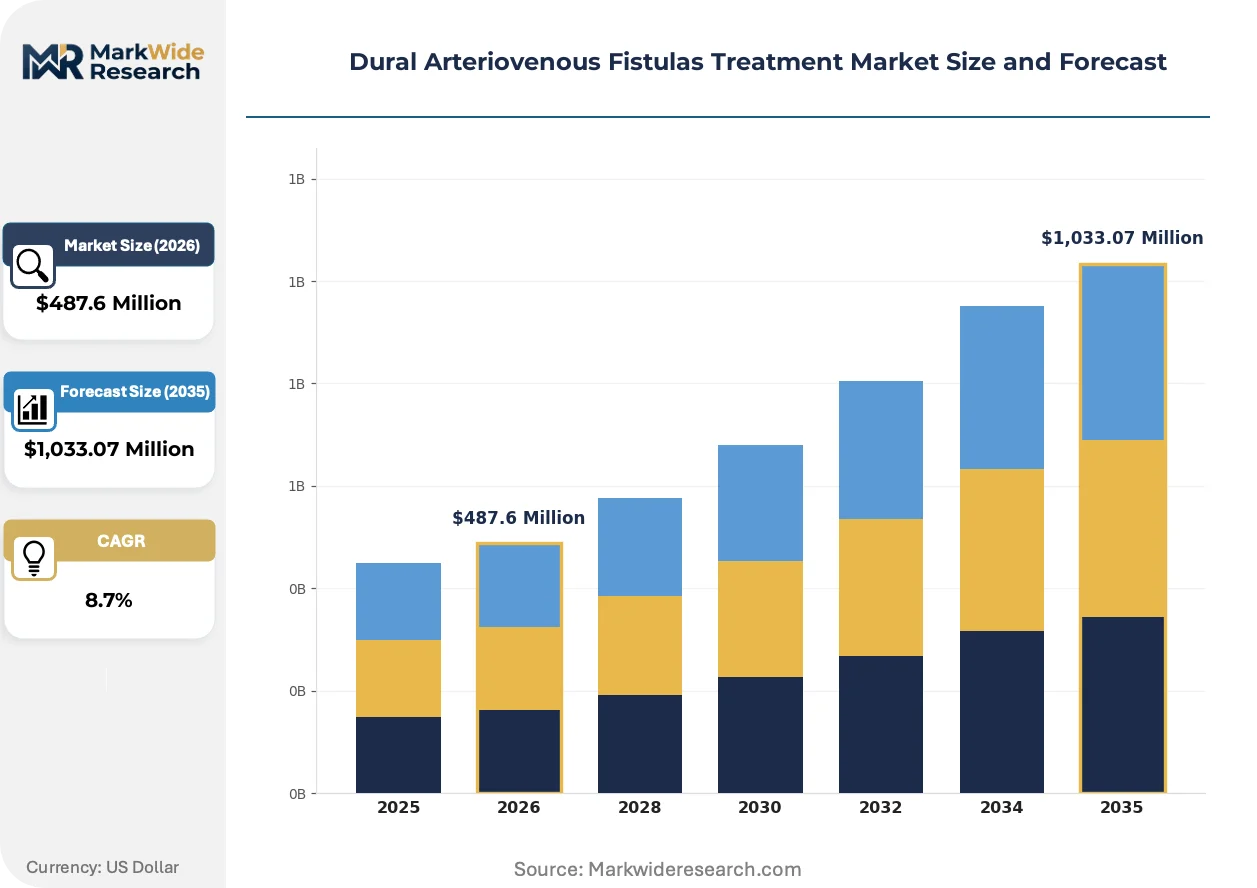
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endovascular Embolization, Surgical Resection, Stereotactic Radiosurgery, Microvascular Decompression Technology: Cerebral Angiography, MRI, CT Scanning, Ultrasound End User: Hospitals, Specialty Clinics, Ambulatory Surgical Centers, Research Institutions Treatment Method: Conservative Management, Surgical Intervention, Interventional Radiology, Follow-Up Care |
| Companies Covered | Medtronic, Boston Scientific Corporation, Johnson & Johnson, Stryker Corporation, Penumbra Inc, Terumo Corporation, MicroVention Inc, Cook Medical, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dural Arteriovenous Fistulas Treatment Market Emerging Trajectories
Device convergence is collapsing the traditional separation between diagnostic imaging platforms and therapeutic delivery systems, with navigation accuracy becoming the primary axis of vendor differentiation rather than embolic material chemistry alone.
Flow diversion technology is migrating from intracranial aneurysm indications toward dural arteriovenous fistula applications, with Silk Vista and Pipeline Flex devices now deployed off-label for high-flow transverse-sigmoid fistulas at centers in Paris, Seoul, and New York. Neurointerventionalists at Mount Sinai and Asan Medical Center are accumulating case series demonstrating feasibility, while device manufacturers pursue formal labeling expansion through FDA breakthrough pathway submissions. This migration is compressing the addressable market for standalone embolization coils in complex fistula anatomy.
EU MDR Article 10 post-market clinical follow-up requirements are mandating prospective safety registries for liquid embolic agents, with notified bodies in Germany and the Netherlands rejecting conformity assessments without five-year follow-up protocols. Manufacturers must now fund physician-sponsored registry infrastructure or sponsor formal post-approval studies, shifting cost structures from pre-market clinical trials toward longitudinal surveillance obligations. High-flow fistula subpopulations with cortical venous reflux face heightened scrutiny given hemorrhage risk profiles.
Hospital procurement committees are consolidating neurovascular device purchasing under value-analysis frameworks that bundle embolization coils, liquid embolics, and microcatheters into single-source contracts with tiered volume rebates. This behavioral shift favors integrated platform vendors with full procedure portfolios over specialty coil or catheter pure-plays. The transition is most visible in United States IDN consolidation markets where CommonSpirit and HCA system-level agreements override individual physician preference items.
Dural Arteriovenous Fistulas Treatment Market Segmentation
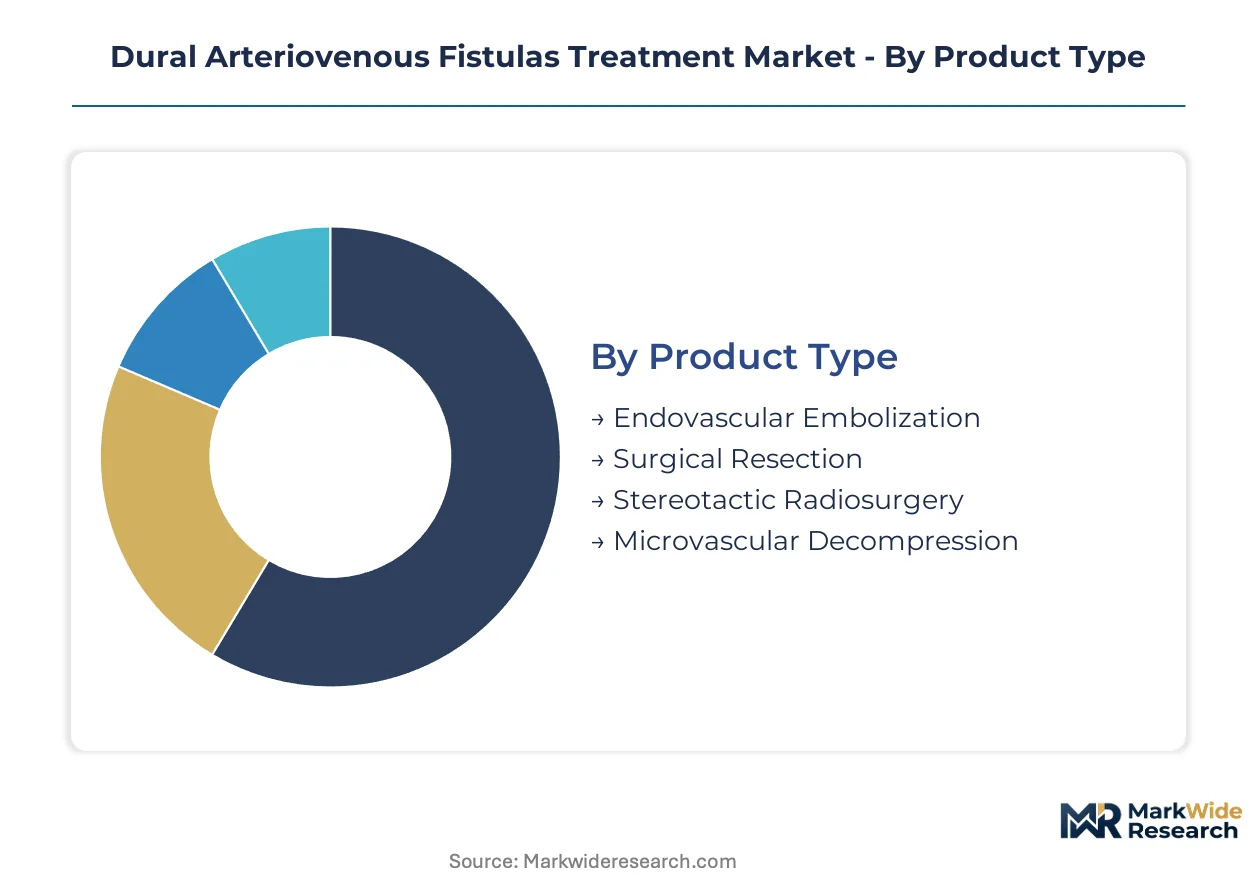
Treatment modality selection in dural arteriovenous fistulas hinges on lesion angioarchitecture, venous drainage pattern, and operator expertise availability. Segmentation reveals how procedural economics and reimbursement frameworks reshape competitive positioning across intervention types and care settings.
Product Type:
Cost tier stratification separates high-complexity endovascular procedures from capital-intensive surgical alternatives, with reimbursement differentials driving site-of-service decisions.
- Endovascular Embolization:Catheter-based delivery of liquid embolics or coils via transarterial or transvenous routes achieves fistula occlusion without craniotomy. Demand concentrates at tertiary neurovascular centers in the United States, Germany, and Japan where specialized fellowship training and comprehensive angiography suites support complex Cognard Type IV-V interventions.
- Surgical Resection:Open craniotomy with direct fistula disconnection or sinus packing remains indicated for lesions with extensive cortical venous reflux inaccessible to endovascular approaches. Volume is rotating toward hybrid operating rooms integrating intraoperative angiography at academic medical centers in Boston, Paris, and Heidelberg.
- Stereotactic Radiosurgery:Gamma Knife or CyberKnife delivery of focused radiation for slow-flow fistulas with favorable angioarchitecture.
- Microvascular Decompression:Cranial nerve decompression procedures occasionally indicated for associated neurovascular compression syndromes.
Endovascular Embolization holds installed capacity. Surgical Resection is rotating up the share rankings.
Technology:
Diagnostic precision requirements dictate imaging modality selection, with spatial resolution and temporal dynamics trading off against throughput economics.
- Cerebral Angiography:Digital subtraction angiography remains the gold standard for fistula characterization, venous drainage classification, and procedural navigation. Adoption clusters at high-volume stroke centers in Florida, Texas, and Arizona where CON reforms enable outpatient diagnostic service lines.
- MRI:Time-of-flight and contrast-enhanced MR angiography provide non-invasive screening and follow-up surveillance. Demand is climbing fastest in Germany and Japan where EU MDR and PMDA post-market surveillance requirements emphasize longitudinal safety monitoring without repeated radiation exposure.
- CT Scanning:CT angiography offers rapid hemorrhage assessment and bone-venous sinus anatomical mapping.
- Ultrasound:Transcranial Doppler provides hemodynamic monitoring and shunt flow quantification.
Cerebral Angiography anchors diagnostic revenue. MRI is expanding most quickly as surveillance protocols lengthen.
End User:
Customer type fragmentation reflects procedure complexity gradients and reimbursement site-of-service differentials.
- Hospitals:Comprehensive neurovascular teams at tertiary academic centers manage high-grade fistulas requiring multidisciplinary coordination. Volume concentrates in integrated delivery networks like CommonSpirit and HCA where value-analysis frameworks bundle device purchasing across embolization platforms.
- Ambulatory Surgical Centers:Low-complexity diagnostic angiography and established patient follow-up are migrating to outpatient settings. Share is rotating upward in Texas and Florida where state-level CON reforms and commercial payer site-of-service incentives align.
- Specialty Clinics:Dedicated cerebrovascular referral centers focusing on second-opinion consultation and longitudinal care coordination.
- Research Institutions:Academic sites conducting prospective registries and device trials under FDA breakthrough and EU MDR Article 10 post-market clinical follow-up mandates.
Hospitals retain complex case volume. Ambulatory Surgical Centers are gaining share fastest in diagnostic and surveillance segments.
Treatment Method:
Application urgency separates emergent hemorrhage management from elective fistula obliteration and chronic surveillance protocols.
- Interventional Radiology:Endovascular embolization and angiographic intervention dominate definitive treatment volume. Demand concentrates where specialized operator training pipelines at Mount Sinai, Asan Medical Center, and Heidelberg produce dual-trained neurointerventionalists capable of high-grade fistula management.
- Conservative Management:Observation with serial imaging for low-risk Borden Type I fistulas without cortical venous reflux. Utilization patterns vary with health technology assessment thresholds in Germany and Japan.
- Surgical Intervention:Open resection for failed endovascular attempts or anatomically unfavorable lesions.
- Follow-Up Care:Long-term angiographic surveillance and neurological monitoring post-obliteration.
Interventional Radiology commands definitive treatment volume. Conservative Management is rotating up as incidental detection increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized neurovascular centers concentrate purchasing power for dAVF treatment devices, with reimbursement density and fellowship training pipelines determining geographic demand clusters.
United States
Tertiary hospitals in Boston, New York, and Houston anchor complex case volume through integrated neurovascular teams. FDA 510(k) premarket notification pathways expedite device approvals for liquid embolic systems and flow diverters. Mount Sinai and Barrow Neurological Institute accumulate high-grade Cognard Type IV-V fistula case series that shape operator training standards.
Germany
Academic medical centers in Heidelberg and Berlin drive adoption of hybrid operating room configurations combining intraoperative angiography with open surgical capability. EU MDR Article 10 post-market clinical follow-up mandates require prospective safety registries for embolic agents, extending conformity assessment timelines. The Heidelberg neurovascular cluster produces dual-trained operators capable of managing lesions previously relegated to conservative management.
Japan
Endovascular fellowship programs at Tokyo and Osaka university hospitals generate specialized operators for high-flow fistula interventions. PMDA post-market surveillance databases for embolic agents create competitive differentiation for manufacturers with decade-plus commercial presence. Asan Medical Center case series influence regional treatment protocols for transverse-sigmoid fistula management.
United Kingdom
NHS England specialized commissioning frameworks concentrate dAVF procedures at designated neurovascular centers in London, Oxford, and Cambridge. MHRA conformity assessment alignment with EU MDR clinical evidence requirements shapes device commercialization timelines for UK market entry. The Oxford neurovascular unit accumulates stereotactic radiosurgery experience for surgically inaccessible lesions.
France
Public hospital neurovascular departments in Paris and Lyon manage high-volume fistula caseloads through academic-practice integration. ANSM post-market vigilance requirements for liquid embolic agents parallel EU MDR surveillance obligations. The Rothschild Foundation Hospital in Paris deploys flow diversion technology off-label for complex fistula anatomy, contributing to European case registries.
Dural Arteriovenous Fistulas Treatment Market Vendor Landscape
Channel-controlling players compete with product-specialist players across integrated platform versus standalone device positioning. The market structure tilts toward consolidated purchasing power at integrated delivery networks, with tiered vendor relationships stratifying between full-procedure portfolio suppliers and component specialists. Three archetypes dominate: diversified medical technology conglomerates with neurovascular divisions, pure-play neurointerventional device manufacturers, and surgical visualization platform vendors extending into endovascular adjacencies. M&A activity concentrates on liquid embolic formulation capabilities and navigation system integration, while geographic expansion targets Japanese and German regulatory approval portfolios.
Within the diversified conglomerate tier, Medtronic, Boston Scientific Corporation, and Stryker Corporation occupy positions defined by integrated platform breadth rather than single-product dominance. Medtronic exemplifies the navigation-integrated delivery system archetype through its neurovascular platform architecture. Boston Scientific represents liquid embolic specialization scaled through controlled polymerization chemistry. Stryker anchors the surgical visualization extension strategy, complementing endovascular approaches with intraoperative imaging infrastructure. These three entities collectively shape procurement committee value-analysis frameworks that bundle coils, liquid embolics, and microcatheters into single-source contracts.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| Johnson & Johnson |
| Stryker Corporation |
| Penumbra Inc |
| Terumo Corporation |
| MicroVention Inc |
| Cook Medical |
| Abbott Laboratories |
| Others |
Supply Flow & Price Mechanics
Ethylene-vinyl alcohol copolymer feedstock concentration with two specialty chemical manufacturers in Germany and Japan anchors margin capture at the liquid embolic formulation tier, forcing device vendors to absorb precursor cost volatility or renegotiate hospital procurement contracts.
Pricing Analysis
Cost-plus contracts with precious metal indexation govern embolization coil supply agreements between manufacturers and tertiary hospital GPOs. Pricing stratifies across premium flow-diverter, standard detachable-coil, and economy bare-platinum tiers based on venous drainage complexity and operator certification requirements. Cost compression in the standard tier is intensifying because EU MDR clinical evidence requirements extend development timelines without commensurate reimbursement expansion. Community hospitals with limited case volumes exhibit highest price sensitivity, while academic neurovascular centers prioritize navigation integration over unit economics.
Supply Chain Analysis
Extended payment terms from supply-chain finance facilities at major device vendors are compressing working capital cycles for microcatheter and guidewire suppliers. Manufacturing draws from precision polymer extrusion clusters in Ireland, nitinol processing facilities in California, and platinum-iridium alloy foundries in South Africa. Single-source vulnerability for EVOH copolymer precursors creates concentration risk amplified by PMDA batch-release protocols. Distribution runs through direct sales forces to hospital value-analysis committees, with IDN consolidation favoring platform vendors over component specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive outcomes as navigation-integrated delivery systems displace standalone embolic devices, with interoperability between angiography suites and EMR infrastructure determining hospital procurement decisions.
For Market Incumbents: Build installed-base moats through navigation-hardware bundling with liquid embolic delivery platforms. Deepen backward integration into EVOH copolymer supply to neutralize single-source precursor risk. Secure exclusive GPO contracts with CommonSpirit and HCA systems before emerging entrants achieve FDA 510(k) clearance for competing flow diverters. For New Entrants and Emerging Players: Ambulatory surgical center penetration in Texas and Florida represents the most penetrable expansion vector for diagnostic angiography and follow-up surveillance services. Target state-level CON reform corridors where outpatient neurovascular service lines face limited incumbent saturation. Pursue AI angiographic analysis partnerships with PACS vendors to circumvent direct coil and catheter competition. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed liquid embolic pure-plays lacking navigation integration capabilities. Five-to-ten year viability hinges on FDA breakthrough pathway submissions for flow diversion labeling expansion in dAVF indications. Monitor PMDA post-market surveillance database depth as differentiation signal for Japanese market positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Navigation-Delivery Integration | Medtronic's neurovascular platform collapses diagnostic-therapeutic workflow gaps for high-grade fistula interventions. |
| Liquid Embolic Formulation Expansion | Boston Scientific's controlled polymerization chemistry enables transvenous approaches previously requiring surgical resection. |
| Hybrid Operating Room Deployment | Stryker's intraoperative angiography infrastructure captures surgical resection volume rotating toward academic centers. |
| AI Angiographic Analysis Development | Machine learning algorithms for automated Cognard classification reduce inter-observer variability in treatment planning protocols. |
| PMDA Surveillance Database Investment | Longitudinal safety data monetization creates competitive moats for manufacturers with decade-plus Japanese commercial presence. |
Methodological Framework
Cross-validation between primary interviews with neurointerventionalists, hospital purchasing committee members, and biomedical engineers anchors the qualitative findings against secondary sources including FDA 510(k) filings, EU MDR notified body assessments, and hospital procurement database extracts. Bottom-up procedure volume estimates triangulate with top-down device shipment data from GPO contract disclosures.
Calibration against historical adoption curves for flow diversion technology in intracranial aneurysm indications informs penetration assumptions across the projection horizon. Segmentation models incorporate treatment modality, lesion angioarchitecture complexity, venous drainage pattern, and site-of-service economics. CAGRs derive from procedure volume elasticity to fellowship training pipeline expansion and reimbursement threshold evolution.
Practitioners should monitor EU MDR Article 10 registry completion rates and PMDA precursor batch-release delays for early signals of supply constraint or evidence requirement escalation. Forecasts reflect modeling assumptions about operator training expansion and IDN consolidation velocity; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Nonalcoholic Steatohepatitis Market
Specialty Medicine
Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Chronic Myelogenous Leukemia Treatment Market
Specialty Medicine
Cutaneous B-Cell Lymphoma Treatment Market
Specialty Medicine
Chromoblastomycosis Treatment Market
Specialty Medicine
Borderline Personality Disorder Market
Specialty Medicine
Iron Deficiency Anemia Therapy Market
Specialty Medicine
Sjogrens Syndrome Market
Specialty Medicine
Cholangiocarcinoma Market
Specialty Medicine
Congenital Neutropenia Treatment Market
Specialty Medicine
Non-Alcoholic Fatty Liver Disease (NAFLD) Market
Specialty Medicine
Global Gastrointestinal Stromal Tumors Market
Specialty Medicine
Latin America Liver Cancer Treatment Market
Specialty Medicine
Intramedullary Osteosarcoma Treatment Market
Specialty Medicine
Global Fungal Keratitis Treatment Market
Specialty Medicine
Hypertrophic Cardiomyopathy (HCM) Therapeutics Market