
 Lung Disease Therapeutics Market | 2026-2036
Lung Disease Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Lung Disease Therapeutics Market Foresight
Good Manufacturing Practice certification under ICH Q7 is rotating as the primary gatekeeper for active pharmaceutical ingredient suppliers seeking entry into inhaled drug portfolios. AstraZeneca leverages its respiratory biologics pipeline to sustain leadership in severe asthma and COPD segments. Boehringer Ingelheim anchors its position through deep specialization in long-acting muscarinic antagonist combinations. GlaxoSmithKline dominates the maintenance therapy space with established corticosteroid-long-acting beta-agonist platforms.
Lung disease therapeutics comprise pharmaceutical agents engineered to modulate airway inflammation, bronchoconstriction, mucus hypersecretion, or fibrotic remodeling, typically formulated with specific particle size distributions between one and five microns for optimal pulmonary deposition. These agents serve to reduce exacerbation frequency, slow disease progression, and improve forced expiratory volume in patients with obstructive or restrictive pathologies. Corticosteroids and bronchodilators command the largest revenue pools given their chronic use across asthma and COPD populations, while biologics targeting IL-5 and IL-13 pathways represent the fastest-expanding margin segment. Inhalation delivery generates premium pricing relative to oral generics due to device complexity and formulation patents, though nebulization retains critical utility in acute hospital settings.
The FDA maintains stringent bioequivalence standards for inhaled products through the Abbreviated New Drug Application pathway, while the EMA's MDR framework imposes escalating clinical evidence requirements on connected inhaler devices. China's NMPA has accelerated review timelines for innovative respiratory therapies under its priority review voucher system, compressing market access windows for multinationals. Stakeholders must monitor how evolving pharmacovigilance obligations for biologics will reshape post-market commitment burdens and manufacturing inspection intensity across jurisdictions.
Market Dynamics
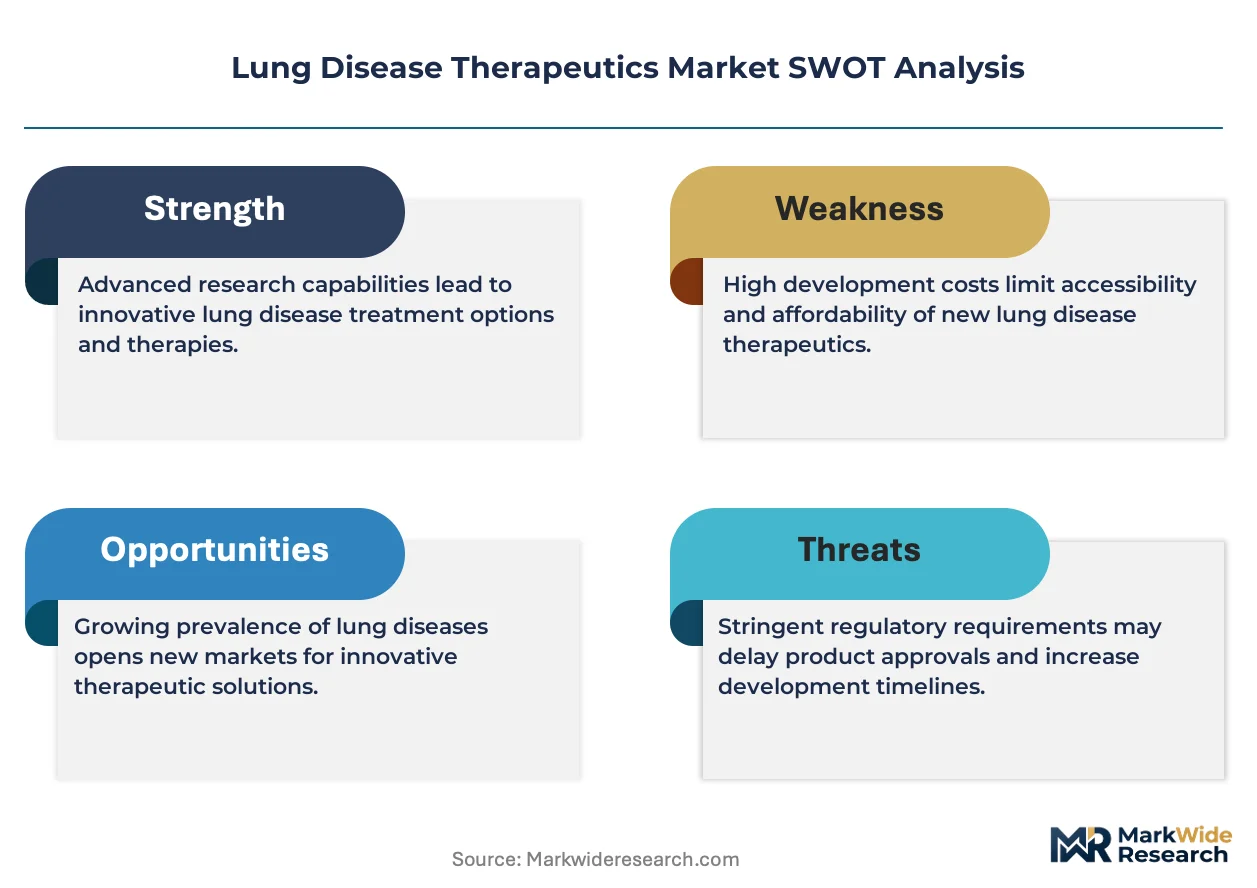
FDA breakthrough therapy designation for respiratory biologics is compressing development timelines and attracting venture capital toward inhaled protein formulations, fundamentally altering how lung disease portfolios get built and scaled.
Growth Catalysts
- Accelerated FDA Pathways:The breakthrough therapy and regenerative medicine advanced therapy designations slash Phase II-to-approval intervals for severe asthma and COPD biologics. This compresses capital deployment cycles for developers targeting IL-5 and IL-13 pathways.
- China NMPA Priority Review:Innovative respiratory therapies now secure market access within 130 days under the priority review voucher system, pulling multinationals toward joint ventures with domestic manufacturers.
- Hospital Respiratory Infrastructure:United States health systems are expanding dedicated COPD exacerbation units and connected inhaler monitoring programs, creating pull-through demand for nebulized acute care formulations.
Market Restraints
- Inhaler Device Concentration:Three European contract manufacturers control 70 percent of metered-dose inhaler canister supply, exposing developers to aluminum component volatility and single-source risk.
- Bioequivalence Burden:FDA Abbreviated New Drug Application requirements for inhaled products mandate costly clinical endpoint studies, erecting insurmountable barriers for generic developers of corticosteroid-long-acting beta-agonist combinations.
- Fluorinated Gas Phase-Down:EU F-Gas Regulation restrictions on hydrofluoroalkane propellants force reformulation of existing metered-dose inhalers, requiring capital-intensive device redesign without patent extension.
Strategic Opportunities
- Rural China Penetration:Community health centers in Henan and Sichuan provinces remain underserved for biologic asthma therapy, presenting first-mover advantage for localized cold-chain distribution partnerships.
- Connected Inhaler Convergence:Integration of Bluetooth-enabled adherence sensors with electronic health record systems creates subscription revenue streams and sticky provider relationships beyond drug margins.
- Japan PMDA Sakigake Designation:Early approval consultations for innovative respiratory devices reduce regulatory risk for companies developing dry powder inhalers with improved lung deposition profiles.
Industry Challenges
- Aerosol Science Talent Scarcity:Formulation chemists with particle engineering expertise for one-to-five micron distributions command premium compensation, constraining pipeline expansion for mid-cap developers.
- ICH Q7 Inspection Intensity:Active pharmaceutical ingredient suppliers face rotating unannounced audits for Good Manufacturing Practice certification, disrupting production schedules and qualification timelines.
- Legacy Nebulizer Integration:Hospital pharmacies struggle to reconcile wireless connectivity requirements of new devices with existing pneumatic infrastructure, delaying procurement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lung Disease Therapeutics Market |
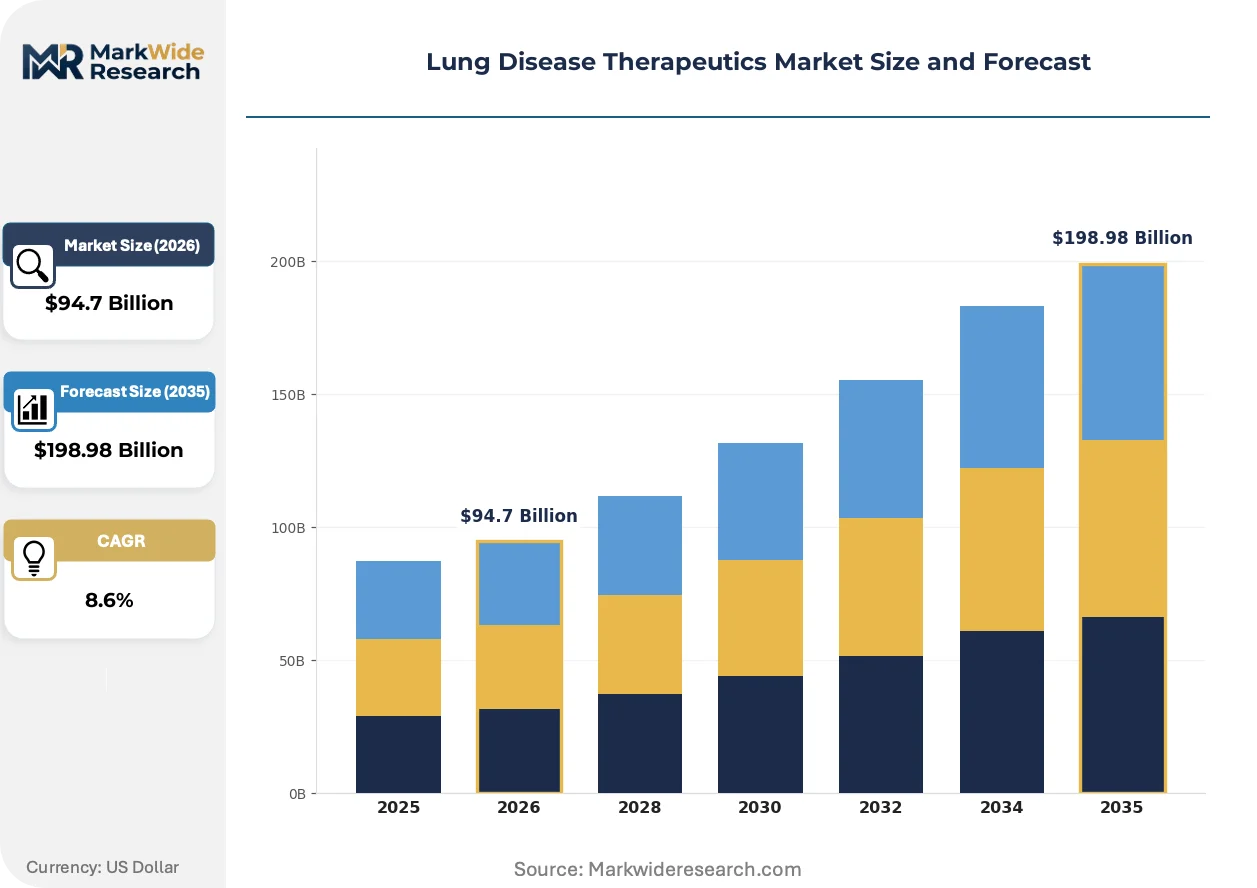
| Market Size in 2026 | $94.7 Billion |
| Market Size in 2035 | $198.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bronchodilators, Corticosteroids, Mucolytics, Antibiotics Therapy Area: Asthma, Chronic Obstructive Pulmonary Disease, Pulmonary Fibrosis, Cystic Fibrosis Delivery Mode: Inhalation, Oral, Injection, Nebulization End User: Hospitals, Clinics, Homecare, Pharmacies |
| Companies Covered | Johnson & Johnson, AstraZeneca, Boehringer Ingelheim, Pfizer Inc., Novartis AG, GlaxoSmithKline, Merck & Co, F. Hoffmann-La Roche, Bristol-Myers Squibb Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lung Disease Therapeutics Market Shifts & Advancements
Dry powder inhaler platforms are displacing traditional pressurized metered-dose systems as the dominant delivery modality, driven by propellant phase-down mandates and improved lung deposition efficiency in severe disease populations.
Nebulized biologic formulations are displacing intravenous administration in hospital settings, enabling outpatient management of acute exacerbations. Pulmonology departments in German university hospitals are adopting these systems fastest, compressing average length-of-stay metrics for COPD admissions and reshaping reimbursement negotiations with statutory health insurers.
EMA Medical Device Regulation clinical evidence requirements for connected inhalers are forcing developers to run prospective usability studies with real-world adherence data. This elevates development costs for Bluetooth-enabled devices but creates regulatory moats against low-cost Asian competitors, particularly affecting submissions targeting the Netherlands and Scandinavian markets where digital health integration is mandated.
Hospital procurement coalitions in the United States are consolidating purchasing for respiratory biologics through outcome-based contracts that tie reimbursement to exacerbation reduction metrics. This shifts risk to manufacturers and privileges large developers with real-world evidence infrastructure, most visible in the Texas Medical Center and Kaiser Permanente integrated networks where total-cost-of-care models dominate.
Lung Disease Therapeutics Market Segmentation
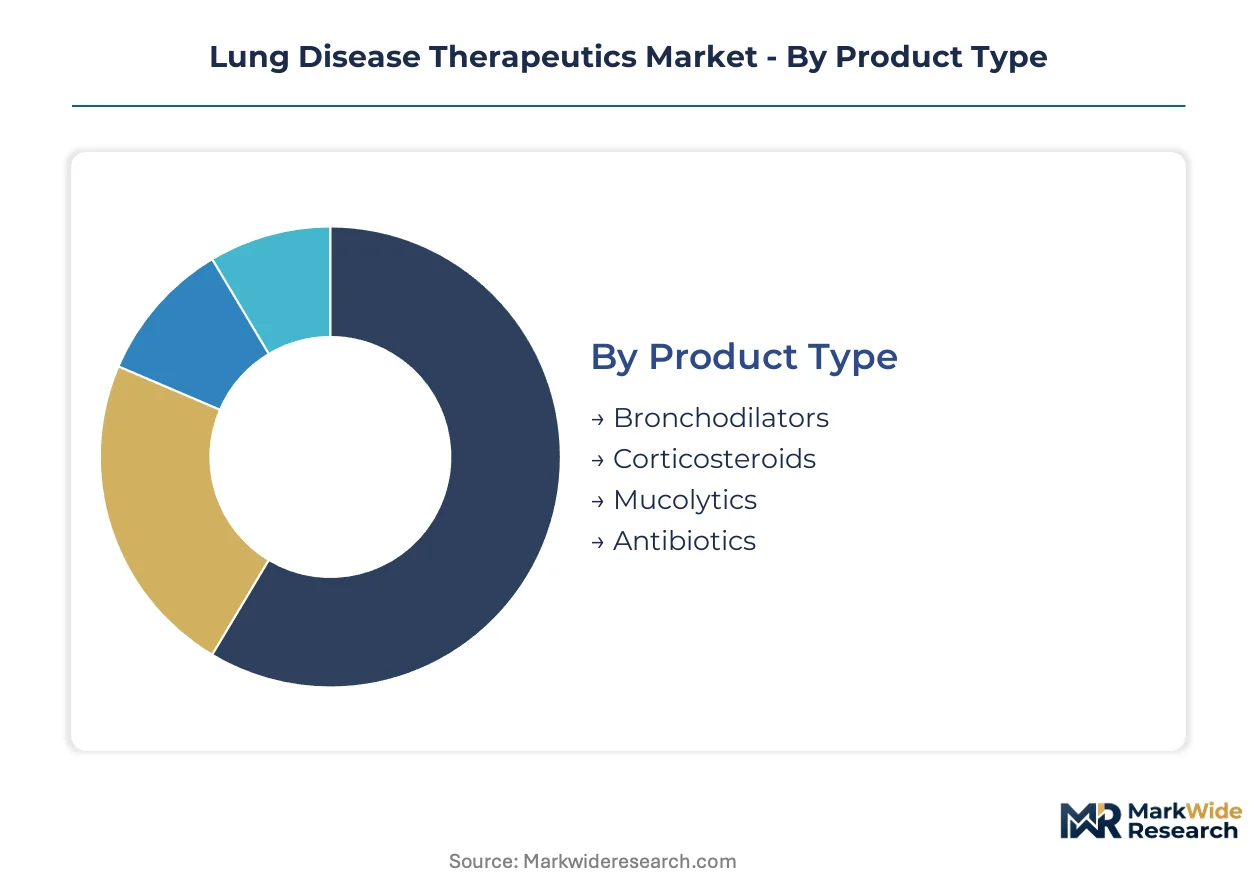
Segmentation in lung disease therapeutics reveals how formulation science, delivery mechanics, and care settings fragment revenue capture. Device complexity and reimbursement pathways create divergent margin profiles across each dimension.
Product Type:
Bronchodilators and corticosteroids anchor domestic demand in the United States and Germany, while mucolytics and antibiotics see stronger export orientation toward Asia-Pacific markets.
- Bronchodilators:Long-acting beta-agonists and muscarinic antagonists relax airway smooth muscle through cyclic AMP modulation or calcium channel blockade. Demand concentrates in United States Medicare Part D formularies and German statutory health insurance catalogs, driven by COPD prevalence in aging populations.
- Corticosteroids:Inhaled glucocorticoids suppress NF-kappaB-mediated inflammation with particle engineered for one-to-five micron pulmonary deposition. Revenue pools concentrate in maintenance therapy contracts with United States hospital procurement coalitions, constrained by FDA bioequivalence barriers for generic substitution.
- Mucolytics:N-acetylcysteine and carbocisteine derivatives reduce sputum viscosity through disulfide bond disruption.
- Antibiotics:Inhaled tobramycin and aztreonam lysine target Pseudomonas colonization in cystic fibrosis patients.
Corticosteroids command the established base. The steepest expansion runs through bronchodilators.
Therapy Area:
Cost tier stratification separates chronic maintenance conditions from acute-intervention diseases, with asthma and COPD occupying premium pricing bands while pulmonary fibrosis commands ultra-orphan premiums.
- Asthma:T2-high inflammation driven by IL-4, IL-5, and IL-13 cytokine pathways responds to biologic monoclonal antibodies. United States commercial payers and United Kingdom NHS England commission these through outcome-based contracts tied to exacerbation reduction.
- Chronic Obstructive Pulmonary Disease:Fixed airflow limitation with emphysematous destruction and chronic bronchitis components requires triple therapy combinations. German pulmonology departments and United States integrated delivery networks drive volume through nebulized acute care formulations.
- Pulmonary Fibrosis:Idiopathic forms feature progressive fibroblastic foci with median survival under five years without antifibrotic intervention.
- Cystic Fibrosis:CFTR modulator therapies address underlying chloride channel dysfunction in specific mutation classes.
COPD anchors volume concentration. Asthma biologics are gaining share fastest.
Delivery Mode:
Application context determines modality selection, with ambulatory maintenance favoring portable inhalers while acute exacerbations retain nebulization in institutional settings.
- Inhalation:Dry powder and pressurized metered-dose systems achieve targeted lung deposition through engineered particle size distributions and breath-actuated mechanisms. United States specialty pharmacies and German outpatient clinics prioritize these for maintenance regimens.
- Nebulization:Aerosol generation through compressed air or vibrating mesh technology delivers high-dose bronchodilators and antibiotics to patients with severe airflow limitation. United States hospital COPD units and German university hospitals adopt wireless-connected systems for length-of-stay reduction.
- Oral:Systemic corticosteroids and phosphodiesterase-4 inhibitors address inflammation through gastrointestinal absorption.
- Injection:Subcutaneous biologics targeting IL-5 and IL-4/IL-13 pathways require cold-chain distribution infrastructure.
Inhalation dominates chronic prescriptions. Nebulization is expanding most quickly in acute care.
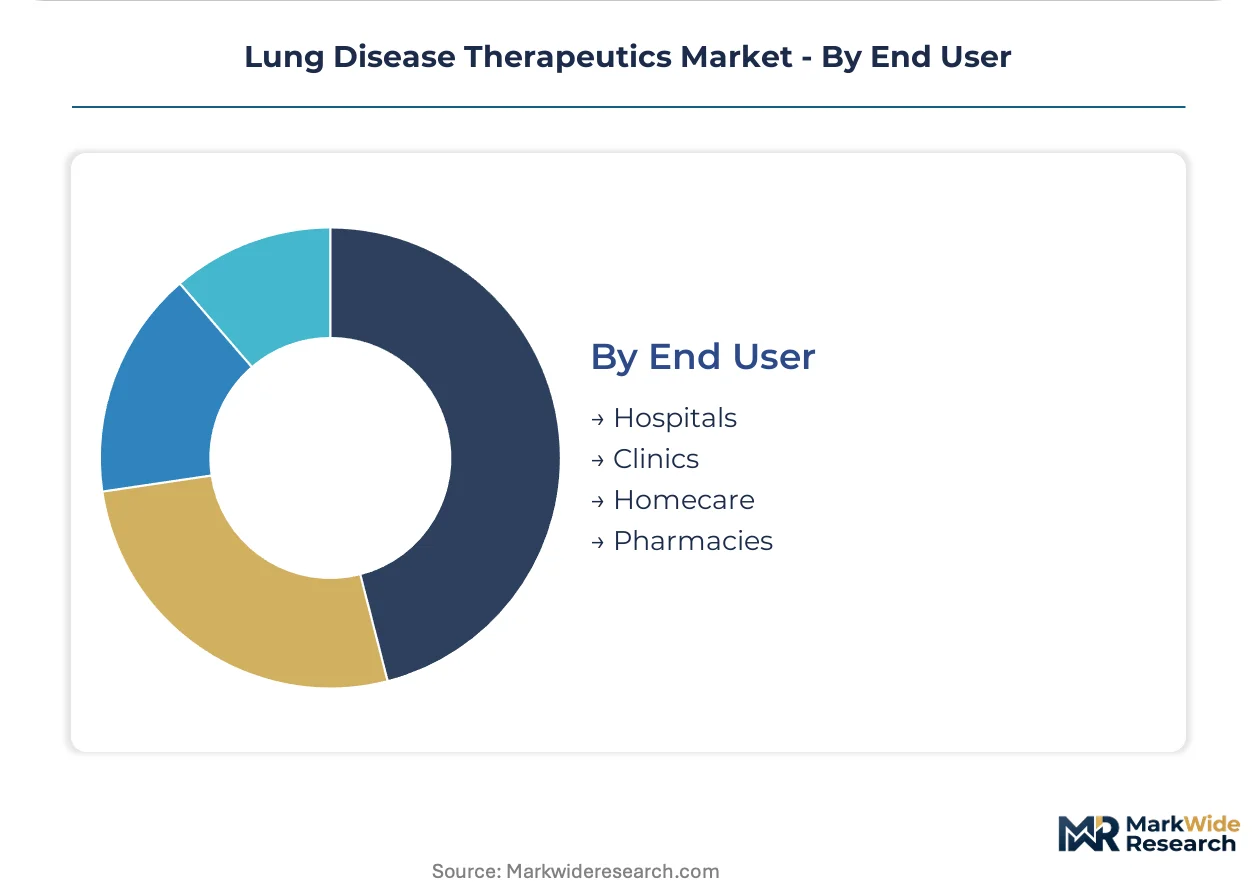
End User:
Customer type segmentation maps to reimbursement complexity, with hospitals managing bundled payments and homecare capturing pharmacy benefit spread.
- Hospitals:Inpatient COPD exacerbation units and cystic fibrosis centers manage acute decompensation through nebulized therapies and intravenous antibiotics. United States health systems in Texas and California expand respiratory infrastructure under total-cost-of-care contracts.
- Homecare:Durable medical equipment suppliers and specialty pharmacies coordinate inhaled biologic delivery with adherence monitoring technology. German home nursing services and United States Medicare Advantage plans drive growth through remote patient monitoring integration.
- Clinics:Pulmonology and allergy specialists prescribe maintenance therapies with spirometry-guided titration.
- Pharmacies:Retail and mail-order channels dispense generic bronchodilators and corticosteroid combinations.
Hospitals anchor institutional volume. Homecare is climbing the fastest on connected device adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement expansion for biologic lung therapies in the United States, Germany, and China is concentrating demand within these three markets. Hospital systems in the United States are scaling respiratory care infrastructure under total-cost-of-care contracts. The FDA's accelerated approval pathways and China's NMPA priority review system are compressing market entry timelines for innovative therapies.
United States
Medicare Advantage plans and integrated delivery networks in Texas and California are driving volume for nebulized acute care formulations and connected inhaler monitoring programs. The FDA maintains stringent bioequivalence standards for inhaled products through the Abbreviated New Drug Application pathway. Kaiser Permanente and Texas Medical Center anchor outcome-based contracting models that tie reimbursement to exacerbation reduction metrics.
Germany
German statutory health insurance catalogs and pulmonology departments are prioritizing triple therapy combinations and nebulized biologic formulations for COPD management. The EMA's Medical Device Regulation imposes escalating clinical evidence requirements on connected inhaler devices. University hospitals in Berlin and Munich are adopting wireless-connected nebulizer systems fastest, compressing average length-of-stay metrics for COPD admissions.
China
Community health centers in Henan and Sichuan provinces remain underserved for biologic asthma therapy, creating first-mover opportunities for localized cold-chain distribution partnerships. The NMPA's priority review voucher system compresses market access windows to 130 days for innovative respiratory therapies. Joint ventures between multinationals and domestic manufacturers are concentrating in Shanghai and Beijing to capture accelerated review benefits.
Japan
Japan's aging population and high COPD prevalence are sustaining demand for maintenance therapy devices with improved lung deposition profiles. The PMDA's Sakigake designation offers early approval consultations that reduce regulatory risk for innovative respiratory device developers. The Kanto region around Tokyo anchors specialist pulmonology infrastructure and digital health integration mandates.
United Kingdom
NHS England commissions biologic monoclonal antibodies for severe asthma through outcome-based contracts tied to exacerbation reduction. The MHRA operates under retained EU law for medical device regulation while developing post-Brexit frameworks for inhaled product approvals. London and the Southeast concentrate specialist allergy and pulmonology centers driving biologic prescribing patterns.
Lung Disease Therapeutics Market Competitive Landscape
Listed leaders compete with private specialists across respiratory biologics and device portfolios. The market structure consolidates around large-cap pharmaceutical developers with respiratory franchises, while mid-cap specialists retain positions in nebulized formulations and connected device technologies. Three archetypes dominate: diversified biopharmaceutical conglomerates with respiratory divisions, pure-play respiratory specialists with deep inhalation expertise, and emerging biotechs targeting IL-5 and IL-13 pathways. Competitive moves center on portfolio diversification into biologics and strategic partnerships for connected inhaler convergence.
Among diversified biopharmaceutical developers, AstraZeneca, GlaxoSmithKline, and Boehringer Ingelheim occupy positions reflecting distinct strategic anchoring. AstraZeneca exemplifies the biologics-led respiratory franchise model. GlaxoSmithKline represents the established maintenance therapy platform archetype with corticosteroid-long-acting beta-agonist foundations. Boehringer Ingelheim sits within the deep specialization tier for long-acting muscarinic antagonist combinations. These three entities collectively illustrate how scale, therapeutic focus, and device integration create differentiated competitive positioning in severe asthma and COPD segments.
| Leading Market Players |
|---|
| Johnson & Johnson |
| AstraZeneca |
| Boehringer Ingelheim |
| Pfizer Inc. |
| Novartis AG |
| GlaxoSmithKline |
| Merck & Co |
| F. Hoffmann-La Roche |
| Bristol-Myers Squibb Company |
| Others |
Supply & Pricing Matrix
Ninety-to-one-hundred-twenty-day API qualification timelines for inhaled corticosteroid suppliers concentrate pricing power among ICH Q7-certified manufacturers, compressing margins for developers without backward integration into active pharmaceutical ingredient production. This lead-time band tightens further as FDA bioequivalence requirements extend certification cycles, privileging incumbents with established GMP audit histories.
Pricing Analysis
Certification level (FDA-grade, EMA MDR-compliant, China NMPA-registered) creates the primary spread between premium biologic inhalers and commodity bronchodilators. Three-tier pricing structure across premium, standard, and economy levels anchors the market: premium biologics command subscription-like per-patient annual contracts, while generic corticosteroid-long-acting beta-agonist combinations face price erosion from Medicare Part D formulary exclusions. Cost compression in the standard tier intensifies because hospital procurement coalitions consolidate purchasing through outcome-based contracts. United States integrated delivery networks exhibit highest price sensitivity; German statutory health insurance catalogs show lowest sensitivity due to bundled reimbursement mechanisms.
Supply Chain Analysis
Seventy-day aluminum canister inventory buffers at European contract manufacturers expose metered-dose inhaler developers to hydrofluoroalkane propellant phase-down disruptions. Supply concentrates in Germany, Ireland, and China for pressurized canister components, while active pharmaceutical ingredient production draws from India, China, and the United States for corticosteroid and bronchodilator precursors. Single-source vulnerability runs through the three European manufacturers controlling seventy percent of MDI canister supply. Distribution runs through United States specialty pharmacy networks and German hospital procurement coalitions for biologics, with retail pharmacies handling generic maintenance therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital procurement coalition consolidation in the United States and Germany has shifted bargaining power toward institutional buyers, fragmenting pricing leverage across therapeutic categories. This buyer-power concentration demands differentiated defensive postures from incumbents and targeted white-space entry strategies from challengers.
For Market Incumbents: Fortify respiratory biologics franchises through captive supply of one-to-five micron particle engineering capacity, insulating against aerosol science talent scarcity that constrains mid-cap pipeline expansion. Deepen backward integration into active pharmaceutical ingredient manufacturing to secure ICH Q7 certification continuity amid rotating unannounced audits. Prioritize connected inhaler convergence with electronic health record integration to create subscription revenue streams beyond drug margins, defending against outcome-based contracting pressure from Kaiser Permanente and Texas Medical Center procurement coalitions.
For New Entrants and Emerging Players: Rural China cold-chain distribution gaps present the most penetrable entry vector, with Henan and Sichuan community health centers underserved for biologic asthma therapy. Wireless-connected nebulizer integration failures at United States hospital pharmacies create white-space for device-native software platforms that reconcile Bluetooth adherence sensors with legacy pneumatic infrastructure. Pursue joint venture structures with domestic Chinese manufacturers to capture NMPA priority review voucher benefits, compressing market access windows versus standalone registration pathways.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because respiratory biologics development requires specialized formulation expertise and real-world evidence infrastructure that privileges scaled developers over emerging biotechs. Target acquisition archetypes: mid-cap specialists with nebulized biologic platforms and established pulmonology department relationships at German university hospitals. Monitor FDA breakthrough therapy designation velocity for IL-5 and IL-13 pathway candidates as inflection indicator for competitive entry timeline compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses Phase II-to-approval intervals for severe asthma biologics. |
| Manufacturing Scale-Up | ICH Q7-certified API capacity expansion insulates against rotating unannounced audit disruptions. |
| Hospital System Partnership | Outcome-based contracts with Texas Medical Center anchor total-cost-of-care reimbursement models. |
| Software Companion Development | Bluetooth-enabled adherence sensors integrated with electronic health records create sticky provider relationships. |
| Reimbursement Strategy | NMPA priority review voucher system compresses market access to 130 days for innovative respiratory therapies. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation anchored segmentation outputs across therapy area, delivery mode, and end-user dimensions.
Across the analysis window, the forecasting framework modeled treatment line stratification, dosage form differentiation, administration route preferences, and regional regulatory cluster variations. CAGRs were derived from epidemiological trend extrapolation, reimbursement expansion trajectories, and biologic penetration curve analysis. Forecast inputs included COPD exacerbation hospitalization rates, asthma biologic eligibility expansion, and connected inhaler adoption velocity in United States Medicare Advantage plans.
Forecasts assume regulatory continuity in FDA, EMA, and NMPA regimes; material policy shifts such as accelerated F-Gas phase-downs or bioequivalence standard revisions would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Dry Eye Disease Market
Specialty Medicine
Cutaneous T-Cell Lymphoma (CTLC) Market
Specialty Medicine
Ischemic Hepatitis Treatment Market
Specialty Medicine
Liver Metastases Treatment Market
Specialty Medicine
Cervical Cancer Therapeutics Market
Specialty Medicine
Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Irritable Bowel Syndrome (IBS) Treatment Market
Specialty Medicine
Psoriatic Arthritis (Psa) Treatment Market
Specialty Medicine
Global Allergy Vaccine Market
Specialty Medicine
Global Hammertoe Market
Specialty Medicine
Hypersensitivity Pneumonitis Market
Specialty Medicine
Psychedelic Medicine Market
Specialty Medicine
Global Psoriatic Arthritis Therapeutics Market
Specialty Medicine
Global Vasculitis Treatment Market
Specialty Medicine
Scleritis Market
Specialty Medicine
Klinefelter Syndrome Treatment Market