
 Self-Healing Networks Market | 2026-2036
Self-Healing Networks Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Healing Networks Market Analytics
The EU AI Act is consolidating compliance requirements for autonomous decision-making systems across network infrastructure, compelling vendors to embed auditable recovery logic. Cisco Systems leverages its installed base of routing hardware to extend self-healing software modules into enterprise campuses. IBM Corporation anchors its offering in hybrid cloud orchestration, competing with Hewlett Packard Enterprise's GreenLake-integrated network automation stack.
Self-healing networks are telecommunications and IT infrastructure systems that autonomously detect faults, reroute traffic, and restore service without human intervention, typically employing closed-loop automation with sub-second detection thresholds and policy-driven remediation engines. Their primary purpose is to eliminate mean-time-to-repair in mission-critical connectivity environments. AI and machine learning segments dominate current procurement as carriers prioritize predictive failure models over rules-based automation, while the IoT application category represents the fastest-expanding structural opportunity due to edge device proliferation outpacing manual management capacity. Network management services capture the largest margin pool because recurring platform licenses command higher retention than discrete troubleshooting engagements.
The Federal Communications Commission in the United States imposes outage reporting mandates that steepen the cost of manual recovery, while the European Union's Cybersecurity Act establishes certification requirements for network resilience products seeking CE marking. The International Organization for Standardization and the International Electrotechnical Commission jointly maintain IEC 62443 standards for industrial network security that increasingly reference autonomous response capabilities. Stakeholders must weigh the trade-off between black-box AI performance and regulatorily mandated algorithmic transparency when selecting platform architectures for multi-jurisdiction deployments.
Market Dynamics
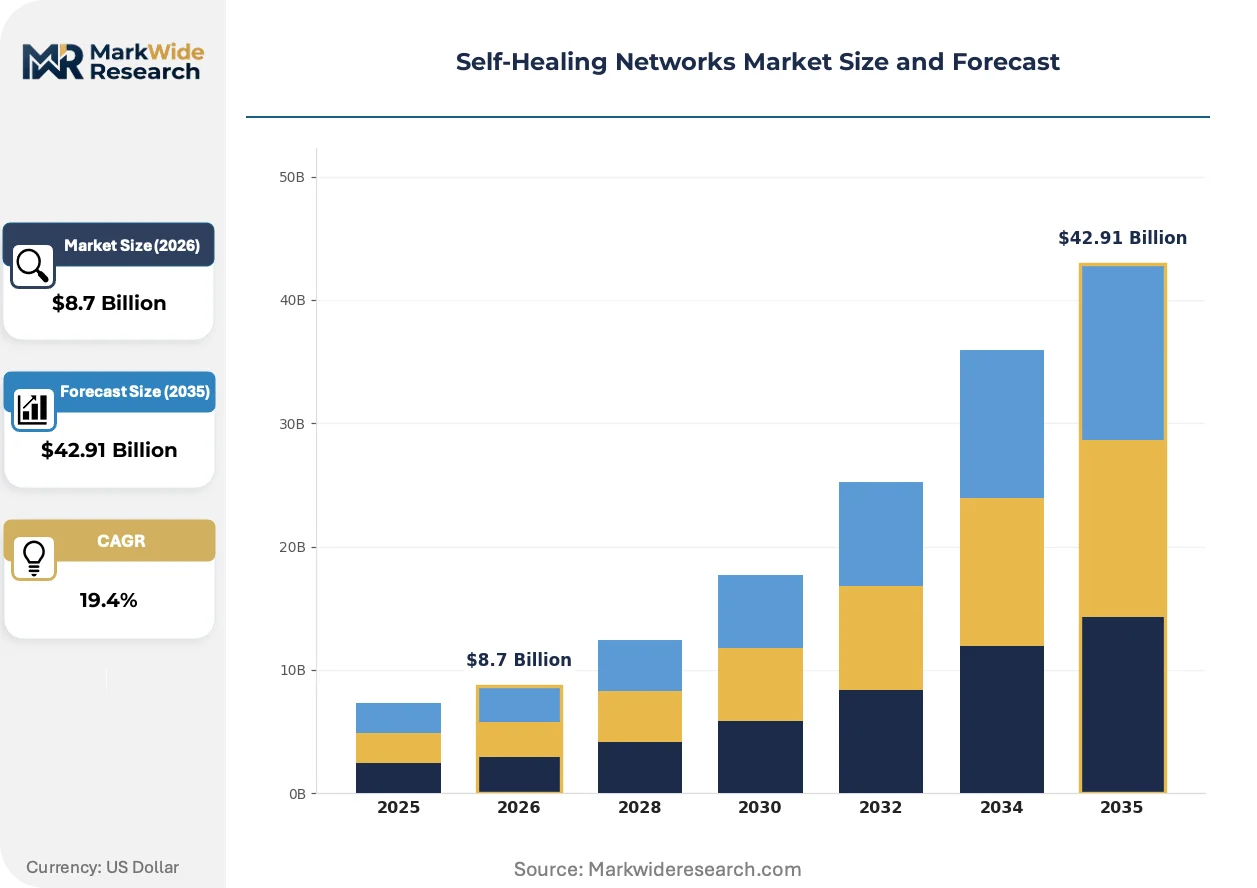
Autonomous network recovery systems are reshaping telecommunications infrastructure economics by compressing outage windows from hours to milliseconds, forcing carriers to reallocate capital from manual operations toward closed-loop automation platforms that embed explainable AI under emerging algorithmic accountability mandates.
Growth Catalysts
- EU AI Act compliance pressure:The European Union's algorithmic accountability framework mandates auditable decision logic in autonomous systems, compelling infrastructure vendors to embed transparent recovery engines that accelerate carrier procurement cycles.
- Edge device proliferation:IoT endpoint density in industrial and smart city deployments now exceeds manual management capacity, creating structural pull for self-healing orchestration that operates without human intervention at the network periphery.
- FCC outage reporting mandates:The Federal Communications Commission's steep penalty structure for service interruptions converts downtime into quantifiable regulatory liability, making autonomous recovery systems a risk-mitigation priority for US operators.
Market Restraints
- Specialized talent scarcity:The intersection of network engineering and machine learning operations requires hybrid skill sets that command premium compensation, constraining deployment velocity for mid-tier carriers.
- Semiconductor supply concentration:AI inference accelerators and programmable network processors depend on fabrication capacity concentrated in East Asian foundries, exposing infrastructure timelines to geopolitical supply disruptions.
- Legacy protocol fragmentation:Decades of accumulated network hardware running diverse management interfaces creates integration friction that extends self-healing deployment cycles and inflates professional services costs.
Strategic Opportunities
- India's smart grid expansion:The country's national power distribution modernization program under the Ministry of Power creates demand for autonomous fault isolation in electrical utility networks that mirror telecommunications self-healing architectures.
- Hybrid cloud orchestration convergence:The merging of on-premises network automation with public cloud control planes enables unified policy enforcement across distributed enterprise infrastructure, opening multi-environment management contracts.
- EU Cybersecurity Act certification:The European Union's resilience product marking scheme creates a regulatory tailwind for vendors that achieve Common Criteria evaluation, differentiating compliant platforms in procurement evaluations.
Industry Challenges
- Explainable AI engineering:Translating black-box neural network decisions into human-interpretable recovery rationales requires specialized interpretability tooling that extends development timelines and complicates validation.
- Cross-vendor interoperability:Multi-supplier network environments demand standardized intent-based interfaces that remain immature, forcing custom integration work that erodes margin on platform deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Healing Networks Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $42.91 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: AI, Machine Learning, Deep Learning, Automation Application: Telecommunications, Data Centers, IoT, Cybersecurity Service Type: Network Management, Monitoring, Troubleshooting, Analysis End User: Enterprises, Service Providers, Cloud Providers, Government |
| Companies Covered | Cisco Systems, Inc., Fortra LLC, IBM Corporation, CommScope Holding Company, Inc., Hewlett Packard Enterprise, Ericsson, SolarWinds Corporation, Juniper Networks, Inc., BMC Software, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Healing Networks Market Evolving Landscape
Intent-based networking is displacing imperative configuration models across carrier and enterprise infrastructure, compressing the gap between business policy statements and autonomous execution while embedding compliance verification into the automation loop itself.
Reinforcement learning for network control is converging with real-time telemetry pipelines to enable predictive failure remediation that anticipates congestion and hardware degradation before service impact occurs. Tier-one carriers in North America and Western Europe are deploying these systems in production core networks, replacing rules-based threshold alerting with continuous policy optimization that autonomously adjusts routing and capacity allocation.
The EU AI Act's risk classification framework for autonomous decision systems is compelling vendors to rearchitect remediation engines around auditable decision trees rather than opaque neural networks. Infrastructure providers seeking CE marking for network resilience products must now document algorithmic logic in machine-readable formats, accelerating investment in interpretable automation that satisfies both performance and compliance requirements. European telecommunications operators are prioritizing certified platforms in procurement specifications.
Carrier procurement departments are consolidating vendor relationships around integrated platform stacks that bundle hardware, software, and managed services into single accountability structures. This behavior shift displaces point-solution purchasing for discrete troubleshooting tools, favoring vendors with end-to-end automation portfolios. The pattern is most visible in United States federal infrastructure contracts and Japanese carrier modernization programs, where procurement teams seek simplified supplier management over best-of-breed component assembly.
Self-Healing Networks Market Segmentation
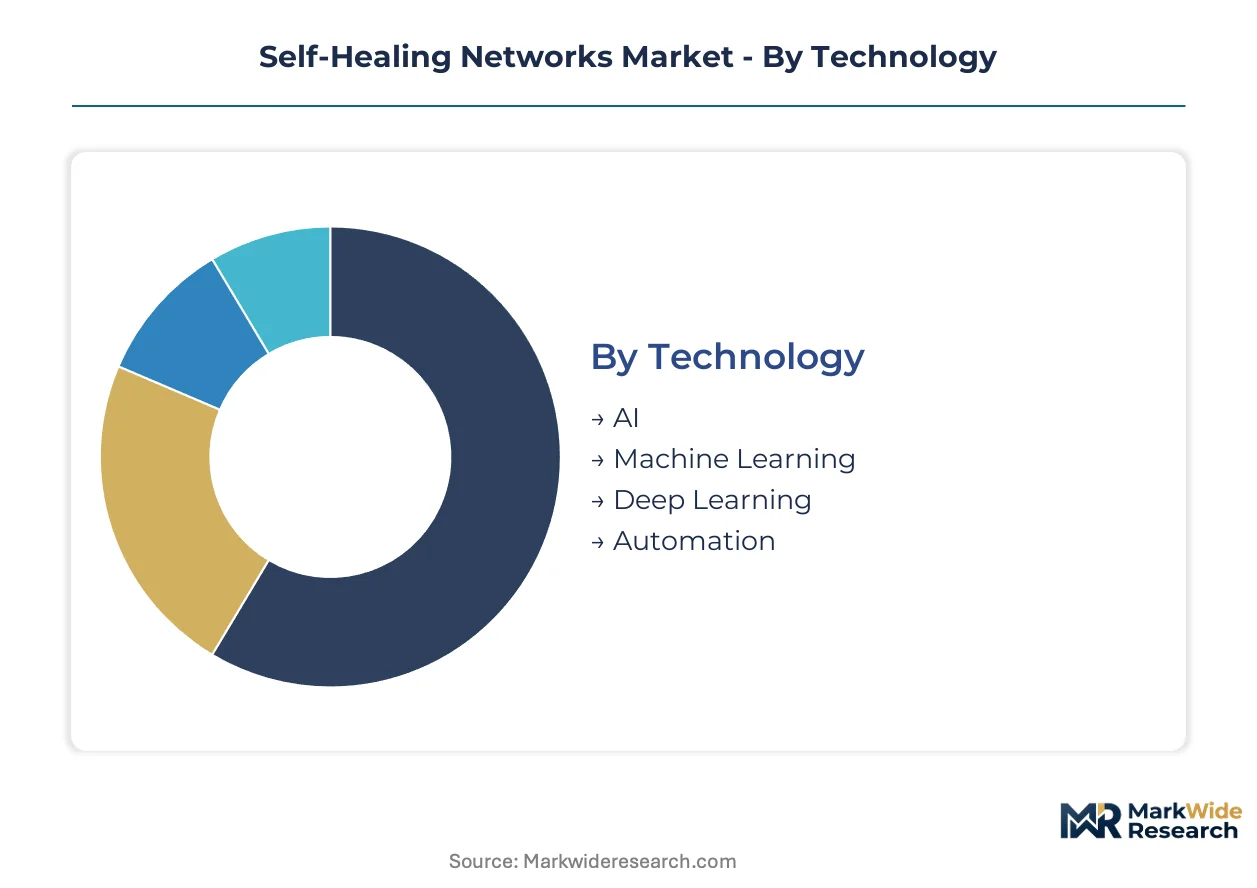
Segmentation in self-healing networks reflects divergent automation maturity across infrastructure layers. Procurement patterns cluster around predictive intelligence capabilities versus operational support functions.
Technology:
Standardization dominates inference engines while customization persists in training pipelines and edge deployment architectures.
- AI:Broad predictive systems integrating fault detection with automated remediation workflows. United States federal infrastructure mandates accelerate carrier procurement of auditable AI platforms that satisfy FCC reporting requirements. Demand concentrates among tier-one telecommunications operators seeking to compress mean-time-to-repair below regulatory thresholds.
- Machine Learning:Statistical models trained on historical failure patterns to anticipate congestion and hardware degradation. European operators under EU AI Act compliance pressure prioritize interpretable ML architectures that document decision logic for regulator examination.
- Deep Learning:Neural network architectures processing high-dimensional telemetry streams for anomaly detection.
- Automation:Rules-based orchestration engines executing predefined remediation policies without adaptive learning.
Most installed capacity flows through AI platforms. Expansion is steepest in Deep Learning where real-time inference at network edge gains traction.
Application:
Volume concentrates in legacy infrastructure while margin accumulates at the periphery where device density outstrips manual management capacity.
- Telecommunications:Core network automation spanning routing, switching, and optical transport layers. United States carriers facing FCC outage penalty structures deploy autonomous recovery to convert downtime liability into capital efficiency. This segment anchors current procurement volume.
- IoT:Edge orchestration managing sensor networks and distributed actuators without centralized human oversight. Smart city deployments in India and industrial automation in Germany create structural demand that outpaces available engineering talent.
- Data Centers:Hyperscale facility automation for power, cooling, and interconnect failure isolation.
- Cybersecurity:Autonomous threat containment and segmented network isolation responding to intrusion events.
Telecommunications retains the largest installed base. IoT climbs the fastest as endpoint proliferation exceeds operational scaling limits.
Service Type:
Recurring platform licenses command premium retention against discrete professional services engagements.
- Network Management:Comprehensive automation platforms embedding policy orchestration, configuration management, and closed-loop remediation. Cloud providers in the United States consolidate procurement around integrated stacks that bundle management software with underlying infrastructure.
- Monitoring:Real-time telemetry collection and visualization systems feeding downstream automation engines. European operators under Cybersecurity Act certification requirements prioritize monitored platforms that generate audit trails for resilience product marking.
- Troubleshooting:Reactive diagnostic services identifying root cause after service impact occurs.
- Analysis:Post-incident forensic and capacity planning assessments.
Network Management captures the dominant revenue share. Monitoring gains share fastest as observability becomes prerequisite for autonomous operation.
End User:
Procurement sophistication separates hyperscale operators from mid-market enterprises constrained by integration complexity.
- Service Providers:Telecommunications carriers operating national and regional infrastructure with stringent uptime commitments. Japanese carrier modernization programs demonstrate consolidated vendor relationships favoring end-to-end platform accountability over component assembly.
- Cloud Providers:Hyperscale operators orchestrating global backbone and metropolitan edge networks. United States federal contracts drive demand for certified autonomous systems that satisfy critical infrastructure protection directives.
- Enterprises:Corporate networks spanning campus, branch, and hybrid cloud connectivity.
- Government:Public sector infrastructure subject to national security and resilience procurement standards.
Service Providers deploy the greatest installed capacity. Cloud Providers show the steepest expansion trajectory as distributed workload architectures multiply failure domains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Self-healing networks originated in United States telecommunications infrastructure during the 1990s optical transport revolution, then migrated to European carrier networks under early automation mandates, and now diffuse through Asia-Pacific industrial corridors as edge device density overwhelms manual operations.
United States
FCC outage reporting mandates and critical infrastructure protection directives drive carrier procurement of autonomous recovery systems. Federal procurement specifications under the Cybersecurity and Infrastructure Security Agency favor certified platforms with auditable decision logic. Hyperscale cloud clusters in Northern Virginia and Dallas-Fort Worth anchor deployment velocity for multi-tenant network automation.
Germany
Industrial automation density and smart manufacturing proliferation create structural demand for edge-orchestrated self-healing. The EU AI Act's risk classification framework compels vendors to rearchitect platforms around interpretable decision trees for CE marking eligibility. The Ruhr industrial corridor and Stuttgart manufacturing belt concentrate pilot deployments in automotive and machinery networks.
Japan
Carrier modernization programs under METI guidance consolidate vendor relationships around end-to-end platform accountability. NTT and KDDI procurement specifications prioritize integrated automation stacks over component assembly. Tokyo-Osaka corridor deployments demonstrate sub-second fault isolation in converged fiber-wireless infrastructure.
India
Smart grid expansion under the Ministry of Power's national distribution modernization program mirrors telecommunications self-healing architectures for electrical utility networks. TRAI's quality-of-service mandates steepen penalties for outages in dense urban markets. Bengaluru and Hyderabad technology corridors host emerging vendor development centers for cost-optimized automation platforms.
United Kingdom
BT Group and Virgin Media O2 procurement specifications emphasize hybrid cloud orchestration converging on-premises automation with public cloud control planes. The UK National Cyber Security Centre's resilience guidelines shape vendor certification requirements for critical national infrastructure. London's financial services density drives premium-tier network management services procurement.
Self-Healing Networks Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the explainable AI certification divide, with algorithmic transparency becoming the pricing differentiator in regulated procurement environments. The vendor base stratifies into three tiers: integrated platform providers bundling hardware-software-services, specialized automation software vendors, and legacy network equipment suppliers extending installed base relationships. Dominant competitive moves include M&A to acquire machine learning operations capabilities and strategic partnerships to bridge legacy protocol fragmentation.
Within the integrated platform tier, Cisco Systems and IBM Corporation exemplify divergent architectural bets—Cisco leveraging routing hardware installed base for campus extension, IBM anchoring in hybrid cloud orchestration. Hewlett Packard Enterprise occupies a position between these vectors through GreenLake-integrated automation stacks. Among specialized networking vendors, Juniper Networks and Ericsson represent the telecommunications-native archetype competing for carrier core network modernization contracts.
| Leading Market Players |
|---|
| Cisco Systems, Inc. |
| Fortra LLC |
| IBM Corporation |
| CommScope Holding Company, Inc. |
| Hewlett Packard Enterprise |
| Ericsson |
| SolarWinds Corporation |
| Juniper Networks, Inc. |
| BMC Software, Inc. |
| Others |
Value Network & Pricing Analysis
AI inference accelerator procurement costs flow from Taiwan Semiconductor Manufacturing Company fabrication capacity through tiered platform pricing, with United States hyperscale cloud providers absorbing premium tiers while Indian utility operators negotiate economy-tier automation stacks under Ministry of Power procurement guidelines.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates certified explainable AI platforms from black-box automation and basic rules-based orchestration. Price differentiation hinges on EU Cybersecurity Act CE marking compliance and bundled managed service obligations. Pricing pressure stems from semiconductor supply concentration in East Asian foundries, compressing margins for mid-tier automation vendors. Cloud providers in Northern Virginia and Dallas-Fort Worth demonstrate lowest price sensitivity, while Indian state electricity boards operate under strict capital efficiency mandates.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for integrated hardware-software stacks, while systems integrators serve enterprise campus deployments. Geographic supply concentration centers on Taiwan, South Korea, and Japan for programmable network processors and AI inference accelerators. Raw material dependencies include advanced silicon wafers, specialized memory modules, and high-speed optical transceivers. Single-source vulnerability in extreme ultraviolet lithography equipment creates structural supply risk. Distribution runs through carrier procurement departments consolidating vendor relationships under end-to-end platform accountability frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story where carrier procurement departments now prioritize auditable decision logic over raw performance metrics, compressing pricing power for uncertified automation vendors.
For Market Incumbents: Lock in carrier relationships through EU AI Act compliance certification and embedded managed service contracts that extend replacement cycles. Defend against specialized machine learning operations vendors by acquiring interpretability tooling capabilities. Prioritize vertical integration into edge deployment architectures to capture IoT proliferation demand. For New Entrants and Emerging Players: Begin with India's smart grid modernization under the Ministry of Power, where cost-optimized automation platforms face limited incumbent saturation. Target electrical utility networks mirroring telecommunications self-healing architectures. Pursue channel partnerships with established systems integrators lacking native AI orchestration capabilities. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier automation vendors struggle to fund dual certification tracks for EU AI Act and FCC reporting mandates. Long-term viability favors platforms with interpretable ML architectures and recurring license revenue concentration. Acquisition target archetype: specialized network automation software vendors with carrier customer bases but limited hardware integration. Watch for inflection when European procurement specifications mandate Common Criteria evaluation as table stakes.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies on-premises orchestration with public cloud control planes for hybrid enterprise contracts. |
| Acquisition of Specialist Firm | Captures machine learning operations talent scarce at incumbent network equipment vendors. |
| Geographic Expansion | Establishes development centers in Bengaluru and Hyderabad for cost-optimized automation engineering. |
| Strategic Partnership | Bridges legacy protocol fragmentation through standardized intent-based networking interfaces. |
| Product Launch | Introduces auditable decision-tree architectures satisfying EU AI Act CE marking requirements. |
Research Methodology
Direct dialogue with carrier network architects, cloud infrastructure procurement officers, regulatory compliance leads at telecommunications operators, and systems integration specialists anchored qualitative findings. Secondary validation drew from FCC outage reporting databases, EU Cybersecurity Act certification registries, SEC 10-K filings of publicly traded network equipment vendors, and hyperscaler capital expenditure disclosures. Bottom-up and top-down triangulation cross-checked segment assumptions against aggregate infrastructure spending patterns.
Bottom-up modeling aggregated individual carrier deployment timelines and enterprise automation contract values, while top-down approaches calibrated against national infrastructure investment programs. Segmentation dimensions included technology layer, application environment, service delivery model, and end-user procurement sophistication. CAGRs were derived from regression analysis of historical automation adoption curves applied to regulatory mandate implementation schedules. Forecast inputs incorporated semiconductor supply lead times and carrier capital cycle phasing.
Several conditions sit outside the modeled scope, including geopolitical disruption to East Asian foundry operations, unanticipated regulatory fragmentation beyond EU AI Act and FCC frameworks, and breakthrough advances in quantum networking architectures. Forecasts reflect assumptions about sustained carrier investment in autonomous infrastructure and stable certification requirements. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Network Management Solutions Market
Network Technology
Wi-Fi 6E Router Market
Network Technology
Global 5G Smart Antenna Market
Network Technology
Germany Residential Gateway Market
Network Technology
DHCP and IP Address Management Market
Network Technology
UK Fixed Connectivity Market
Network Technology
Enterprise Routers Market
Network Technology
Global LWAN Market
Network Technology
Wi-Fi Network Equipment Market
Network Technology
Global Wi-Fi Range Extender Market
Network Technology
Middle East & Africa Video Conferencing Hardware Market
Network Technology
Power Over Ethernet (Poe) Solutions Market
Network Technology
Global Enterprise Session Border Controller (SBC) Market
Network Technology
Global Private 5G Network Market
Network Technology
Global Network Monitoring Market
Network Technology
Passive Optical Network Market