
 Wi-Fi Router Market | 2026-2036
Wi-Fi Router Market Size, Share, and Industry Trends Forecast 2026-2036
Wi-Fi Router Market Insights
Shortages of RF engineering talent is reorganizing how manufacturers allocate R&D budgets across product lines. TP-Link Technologies Co., Ltd. leverages its Shenzhen manufacturing base to sustain cost leadership in mass-market segments. Netgear Inc. anchors its premium positioning through specialized gaming and mesh router portfolios. Cisco Systems, Inc. competes primarily in enterprise channels where it controls security-integrated networking stacks.
A Wi-Fi router is a network device that forwards data packets between computer networks using radio frequency bands, typically operating at 2.4 GHz, 5 GHz, or 6 GHz with throughput rates measured in gigabits per second; its primary commercial purpose is to enable wireless internet connectivity for multiple client devices simultaneously. Mesh router systems now capture disproportionate margin pools as consumers prioritize whole-home coverage over single-unit hardware. Wi-Fi 6 and Wi-Fi 6E technology tiers are displacing Wi-Fi 5 in enterprise and gaming use cases where latency sensitivity and device density requirements are most acute.
The FCC governs unlicensed spectrum access in the United States, while ETSI coordinates harmonized standards across European member states and China's MIIT administers radio type approvals; together these bodies determine which frequency bands and power levels manufacturers can deploy, directly shaping regional product configurations and launch sequencing. Enterprise end users face procurement decisions around WPA3 security mandates and upcoming Wi-Fi 7 interoperability certifications that will determine hardware refresh cycles. Stakeholders should monitor spectrum auction outcomes and interoperability testing protocols as the primary variables affecting competitive positioning.
Market Dynamics
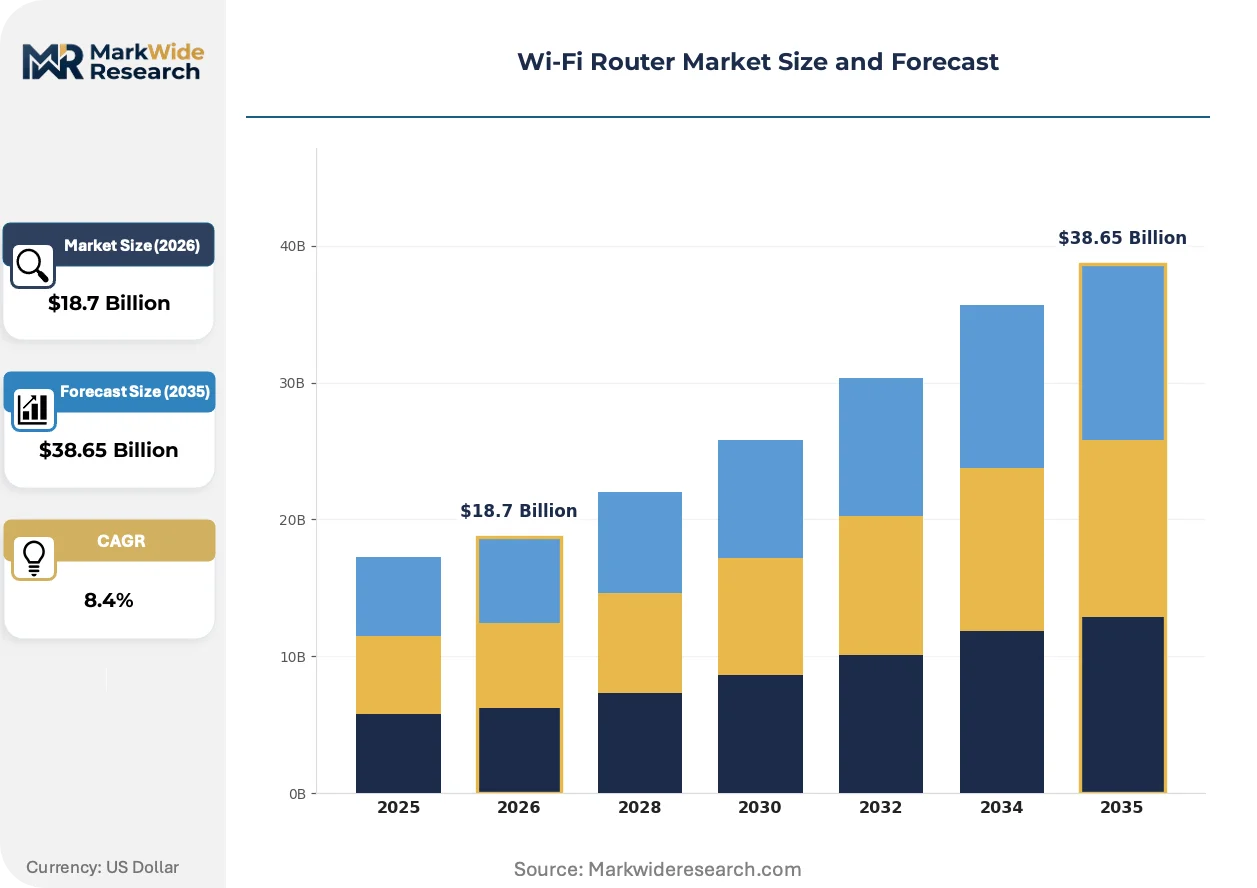
Enterprise IT departments are forcing infrastructure refresh cycles as hybrid work models permanently elevate concurrent device density requirements. Wi-Fi 6E spectrum allocations by the FCC and similar bodies are compressing product roadmaps and redistributing R&D budgets toward 6 GHz-capable architectures.
Growth Catalysts
- WPA3 Security Mandates:Enterprise procurement policies across the United States now require WPA3 encryption as a baseline qualification, accelerating hardware replacement in financial services and healthcare verticals.
- Smart Home Device Proliferation:Residential environments in Germany now average 25+ connected endpoints per household, creating sustained pull for mesh router systems with superior handoff protocols.
- 6 GHz Spectrum Liberalization:China's MIIT has authorized 6 GHz band access for unlicensed use, enabling domestic manufacturers to launch Wi-Fi 6E product lines previously restricted to North American and European markets.
Market Restraints
- RF Engineering Talent Scarcity:Design teams capable of optimizing antenna arrays for 6 GHz propagation remain concentrated in Shenzhen and Taipei, constraining new market entrants.
- Semiconductor Input Volatility:Wi-Fi 6E and Wi-Fi 7 chipsets depend on advanced process nodes where foundry allocation decisions in Taiwan directly constrain production scaling.
- Legacy 2.4 GHz Interference:Industrial IoT deployments in manufacturing facilities face persistent coexistence challenges with legacy automation equipment operating in overlapping spectrum.
Strategic Opportunities
- Rural Broadband Expansion:India's BharatNet initiative and similar fiber-to-the-home programs in secondary cities create first-time router demand outside traditional urban concentration zones.
- Converged Security-Networking Stacks:Integration of SASE architecture with wireless access points allows enterprise vendors to capture recurring software revenue alongside hardware sales.
- Direct-to-Consumer Channel Maturation:Brand-owned e-commerce platforms now bypass traditional retail distribution in the United States, capturing margin previously allocated to big-box electronics chains.
Industry Challenges
- Wi-Fi 7 Interoperability Certification Delays:The Wi-Fi Alliance's testing backlog is extending product launch timelines by 4-6 months for vendors seeking certified branding.
- Backward Compatibility Engineering Burden:Supporting 802.11a/b/g/n/ac/ax/be protocol stacks simultaneously consumes die area and power budgets that constrain industrial design flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wi-Fi Router Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Router, Range Extender, Mesh Router, Portable Router Technology: Wi-Fi 5, Wi-Fi 6, Wi-Fi 6E, Tri-Band Use Case: Home Networking, SMEs, Gaming, IoT Devices End User: Residential, Educational Institutions, Enterprises, Government |
| Companies Covered | TP-Link Technologies Co., Ltd., Netgear Inc., ASUS Computer International, Cisco Systems, Inc., D-Link Corporation, Huawei Technologies Co., Ltd., Xiaomi Corporation, Ubiquiti Inc., Belkin International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wi-Fi Router Market Trends and Innovations
Radio frequency architecture is decomposing into modular subsystems that separate baseband processing from RF front-end optimization. This structural shift enables faster technology iteration and opens supplier ecosystems beyond traditional integrated chipset vendors.
Wi-Fi 7's 320 MHz channel bonding and 4K-QAM modulation is decomposing the traditional single-router deployment model. Enterprise campuses and high-density residential complexes in South Korea are adopting distributed radio unit architectures that separate control plane intelligence from distributed antenna nodes. This topology compresses capital expenditure per square meter of coverage while elevating software-defined network management requirements.
ETSI's harmonized standards for 6 GHz power spectral density are reshaping European product configurations. The regulatory body's stricter out-of-band emission limits compared to FCC rules force hardware variants with modified RF filtering. German industrial automation buyers now face 8-12 week longer lead times for certified equipment versus North American equivalents.
Enterprise procurement teams are consolidating vendor relationships around full-stack networking suppliers. Financial services IT departments in the United States now issue single-source contracts covering switching, routing, wireless, and security infrastructure. This concentration displaces best-of-breed wireless specialists who previously competed on radio performance metrics alone.
Wi-Fi Router Market Segmentation
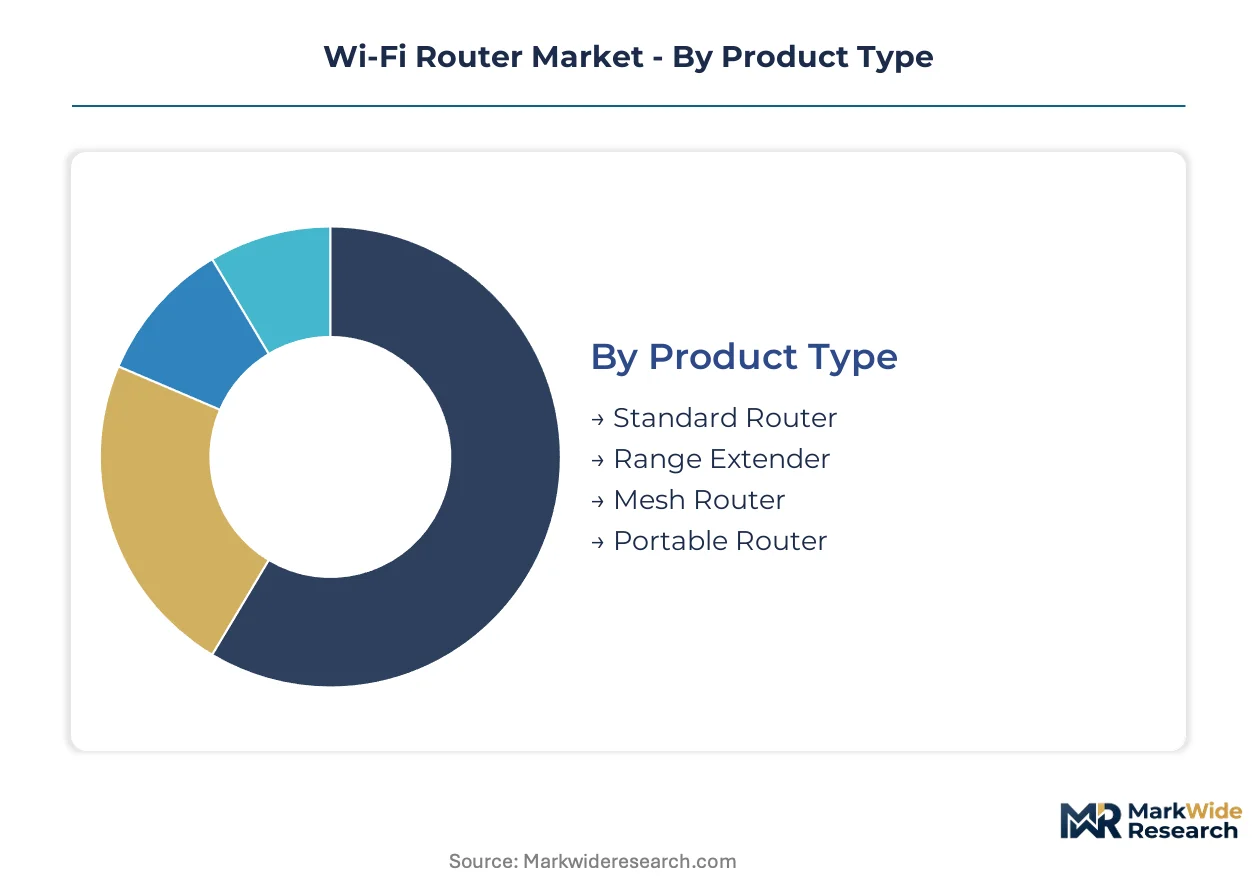
Wi-Fi router purchasing patterns diverge sharply across deployment contexts. Enterprise procurement teams prioritize security stack integration while residential buyers respond to coverage claims and subscription bundling. Channel economics favor different form factors in each vertical.
Product Type:
Mass-market retail channels in the United States and Germany move single-unit hardware at volume, while specialized distributors handle multi-node systems for commercial projects. Direct-to-consumer platforms now capture mesh system sales that previously flowed through big-box electronics chains.
- Standard Router:Single-unit hardware with integrated antennas serving 2.4 GHz and 5 GHz bands concurrently. Residential demand in Germany concentrates here for apartments under 100 square meters where one device suffices. Unit economics compress margins as Shenzhen manufacturing bases compete on cost.
- Mesh Router:Coordinated multi-node systems with dedicated backhaul channels enabling seamless client roaming. Premium positioning in the United States residential segment commands recurring software revenue through parental control subscriptions. Whole-home coverage requirements in larger dwellings drive replacement cycles.
- Range Extender:Signal amplification hardware rebroadcasting existing network coverage to dead zones.
- Portable Router:Battery-powered mobile hotspot devices utilizing cellular backhaul for temporary connectivity.
By volume, Standard Router leads. By growth pace, Mesh Router is expanding most quickly.
Technology:
Cost tiers separate clearly across protocol generations. Wi-Fi 5 inventory clears through discount channels while Wi-Fi 6E commands premium positioning where 6 GHz spectrum is available. Semiconductor allocation at advanced foundry nodes constrains supply of newer standards.
- Wi-Fi 6:OFDMA and MU-MIMO protocols enabling simultaneous service to dense device populations. Enterprise refresh cycles in the United States center here as WPA3 mandates force hardware replacement. Latency-sensitive applications in financial services trading floors specify this tier minimum.
- Wi-Fi 6E:Extended spectrum access adding 6 GHz channels with 160 MHz contiguous bandwidth. China's MIIT authorization unlocked domestic manufacturing for this tier previously restricted to FCC-regulated markets. Gaming peripheral ecosystems in South Korea adopt aggressively for low-latency competitive play.
- Wi-Fi 5:802.11ac protocol with 256-QAM modulation remaining viable for basic residential connectivity.
- Tri-Band:Dedicated backhaul channel architectures separating client service from inter-node communication.
By volume, Wi-Fi 5 still dominates installed base. By margin capture, Wi-Fi 6E is gaining share fastest.
Use Case:
Application requirements dictate performance thresholds. Gaming deployments prioritize latency under 20 milliseconds while IoT concentrators optimize for power efficiency across thousands of low-bandwidth endpoints.
- Home Networking:Residential coverage for streaming, teleconferencing, and smart device aggregation. German households averaging 25+ connected endpoints pull mesh configurations with superior handoff protocols. Service provider bundling in the United States subsidizes hardware costs against subscription lock-in.
- Gaming:Low-latency optimization with QoS prioritization and dedicated gaming LAN ports. Esports venues in South Korea specify sub-10 millisecond latency for tournament-grade infrastructure. Peripheral ecosystem compatibility drives brand loyalty in this segment.
- SMEs:Small and medium enterprise deployments balancing cost constraints against basic security requirements.
- IoT Devices:Industrial sensor networks and smart building automation requiring high endpoint density support.
By volume, Home Networking leads. By technology refresh urgency, Gaming is climbing the fastest.
End User:
Customer type determines procurement authority and decision criteria. Residential buyers respond to marketing claims while institutional purchasers issue formal RFPs with security certification requirements.
- Residential:Individual consumers purchasing through retail or direct channels for personal use. India's BharatNet fiber expansion creates first-time demand in secondary cities previously underserved by broadband infrastructure. Price sensitivity here favors Shenzhen manufacturing cost structures.
- Enterprises:Corporate IT departments consolidating vendor relationships around full-stack networking suppliers. Financial services in the United States now issue single-source contracts covering switching, routing, wireless, and security infrastructure. SASE integration requirements favor established networking vendors.
- Educational Institutions:Campus-wide deployments serving dormitory and classroom density requirements.
- Government:Public sector procurement with domestic content preferences and security clearance mandates.
By volume, Residential leads. By contract value concentration, Enterprises show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns split sharply across geographies. Enterprise buyers in the United States prioritize security-integrated stacks while residential markets in Germany and China drive mesh system adoption for high device-density households.
United States
FCC spectrum allocations for Wi-Fi 6E and emerging Wi-Fi 7 standards accelerate enterprise refresh cycles. Enterprise procurement policies now mandate WPA3 encryption, forcing replacement in financial services and healthcare verticals. Silicon Valley and Austin technology corridors concentrate vendor R&D operations for 6 GHz-capable architectures.
China
MIIT authorization of 6 GHz unlicensed access unlocked domestic manufacturing for Wi-Fi 6E product lines previously restricted to North American markets. The country's national telecommunications regulator coordinates radio type approvals that determine regional launch sequencing. Shenzhen manufacturing clusters sustain cost leadership in mass-market segments through integrated supply chains.
Germany
Residential environments average 25-plus connected endpoints per household, creating sustained demand for mesh router systems with superior handoff protocols. ETSI harmonized standards enforce stricter out-of-band emission limits than FCC rules, forcing hardware variants with modified RF filtering. Munich and Berlin industrial automation buyers face extended lead times for certified equipment versus North American equivalents.
South Korea
Esports venues and gaming peripheral ecosystems specify sub-10 millisecond latency requirements, driving aggressive adoption of Wi-Fi 6E and early Wi-Fi 7 infrastructure. The country's Ministry of Science and ICT coordinates spectrum policy for competitive gaming and high-density residential complexes. Seoul metropolitan area deployments adopt distributed radio unit architectures that separate control plane intelligence from antenna nodes.
India
BharatNet fiber-to-the-home expansion creates first-time router demand in secondary cities previously underserved by broadband infrastructure. TRAI regulatory frameworks govern service provider equipment standards and spectrum allocation for wireless broadband. Bangalore and Hyderabad technology hubs concentrate enterprise networking procurement as IT services firms upgrade hybrid work infrastructure.
Wi-Fi Router Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with full-stack networking vendors capturing enterprise consolidation contracts while cost-optimized manufacturers defend mass-market positions. The structure rewards scale in semiconductor procurement and RF engineering talent concentration. Three archetypes dominate: Shenzhen-based manufacturing specialists, premium-tier gaming and mesh specialists, and enterprise security-integrated stack providers. Competitive moves center on direct-to-consumer channel maturation and SASE architecture integration for recurring software revenue.
Within the manufacturing specialist tier, TP-Link Technologies Co., Ltd. and Xiaomi Corporation exemplify cost-leadership positioning anchored to Shenzhen production bases. Netgear Inc. occupies a position representing premium residential and gaming segmentation. Cisco Systems, Inc. anchors the enterprise-integrated tier where security-networking convergence determines procurement outcomes.
| Leading Market Players |
|---|
| TP-Link Technologies Co., Ltd. |
| Netgear Inc. |
| ASUS Computer International |
| Cisco Systems, Inc. |
| D-Link Corporation |
| Huawei Technologies Co., Ltd. |
| Xiaomi Corporation |
| Ubiquiti Inc. |
| Belkin International Inc. |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between Taiwanese foundries and chipset vendors lock in wafer allocation and cost visibility across Wi-Fi 6E and Wi-Fi 7 product generations. These arrangements bind Shenzhen manufacturing clusters to fixed input costs while insulating premium-tier vendors from spot-market volatility in advanced process nodes.
Pricing Analysis
Project-based pricing for enterprise deployments dominates North American channels, with WPA3 certification tiers separating premium security-integrated stacks from standard offerings. Price differentiation stems from certification grade and volume scale, with financial services buyers showing least sensitivity due to compliance mandates. Cost compression in mass-market segments intensifies as Shenzhen manufacturers compete on die-area optimization, while residential buyers in India and secondary Chinese cities exhibit highest price sensitivity.
Supply Chain Analysis
Strait of Malacca transit underwrites semiconductor logistics connecting Taiwanese foundries to Shenzhen assembly plants. Supply concentration centers on Taiwan for advanced Wi-Fi 6E/7 chipsets, China for PCB fabrication and final assembly, and South Korea for memory components. Raw material dependencies include silicon wafers, RF front-end gallium arsenide substrates, and copper-clad laminates. Single-source vulnerability in 6 GHz RF engineering talent constrains new entrant scaling. Distribution runs through brand-owned e-commerce platforms and enterprise direct sales, bypassing traditional retail margin capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as hybrid work models permanently elevate device density requirements, creating specialized niches for security-integrated and gaming-optimized architectures that incumbent generalists cannot serve uniformly.
For Market Incumbents: Compound defensive positioning through backward integration into RF front-end design capabilities and captive supply of 6 GHz-optimized antenna arrays. Threat from specialized mesh vendors with superior software-defined roaming protocols demands channel control reinforcement in enterprise procurement. Certification investment in Wi-Fi 7 interoperability serves as the priority lever to extend replacement cycle capture. For New Entrants and Emerging Players: FCC Part 15 certification fast-track enables rapid market entry for Wi-Fi 6E hardware targeting underserved rural broadband expansion in India and secondary U.S. markets. White-space concentrates in industrial IoT gateway applications where legacy 2.4 GHz interference creates demand for clean-spectrum 6 GHz solutions. Go-to-market through service provider bundling partnerships bypasses retail channel establishment costs. For Investors and Strategic Acquirers: RF engineering boutiques with proven 6 GHz antenna optimization track records represent acquisition targets with scarce, defensible capabilities. Long-term viability across the analysis window hinges on spectrum policy trajectory and foundry allocation stability. Signal to monitor: Wi-Fi Alliance certification backlog duration as inflection indicator for product launch velocity and working capital efficiency.| Strategic Initiative | Industry Significance |
|---|---|
| SASE Architecture Integration | Captures recurring software revenue alongside hardware sales through security-networking convergence. |
| Direct-to-Consumer Channel Maturation | Bypasses big-box retail margin capture in the United States residential segment. |
| 6 GHz RF Engineering Talent Acquisition | Secures scarce design capabilities concentrated in Shenzhen and Taipei clusters. |
| Wi-Fi 7 Interoperability Certification | Accelerates product launch timelines through Wi-Fi Alliance testing queue management. |
| Rural Broadband Partnership Programs | Accesses first-time router demand from India's BharatNet fiber expansion initiative. |
Research Methodology
A standing panel of enterprise IT procurement officers, RF engineering directors, semiconductor supply chain managers, and channel distribution heads provided ongoing calibration against market developments. Primary interviews with these stakeholders combined with secondary validation from FCC spectrum allocation filings, MIIT radio type approval databases, Wi-Fi Alliance certification records, and foundry capacity disclosure reports. Bottom-up unit economics modeling triangulated against top-down addressable market sizing across enterprise and residential deployment contexts.
Consistency checks validated volume and value outputs against external benchmarks including hyperscaler capex disclosures, service provider equipment procurement data, and retail channel inventory velocity indicators. The analytical framework segmented demand across technology tiers, product form factors, use case applications, and end-user archetypes throughout the projection horizon. CAGRs derived from installed base replacement cycle analysis, spectrum liberalization timelines, and semiconductor node transition curves.
Underlying assumptions cover WPA3 mandate enforcement timelines, foundry allocation continuity, and spectrum harmonization progress, with deviation risk concentrated in Wi-Fi 7 certification delays and geopolitical constraints on Taiwanese semiconductor logistics. Practitioners should keep alternative scenarios live as regulatory interoperability testing protocols and 6 GHz band authorization trajectories evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Digital Repeater Market
Network Technology
Europe Private 5G Network Market
Network Technology
MENA Wireless Routers Market
Network Technology
CPE Router Market
Network Technology
Cloud Managed Access Points Market
Network Technology
Sand Lane Systems Market
Network Technology
Router and Switch Market
Network Technology
Network Emulator Market
Network Technology
Unified Network Management Market
Network Technology
Global Home Networking Device Market
Network Technology
Global Private 5G Network Market
Network Technology
Global Active Network Management Market
Network Technology
IT Connector Market
Network Technology
Global Deep Packet Inspection and Processing Market
Network Technology
Virtual Customer Premises Equipment Market
Network Technology
Europe Video Conferencing Hardware Market