
 Global Network Monitoring Market | 2026-2036
Global Network Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Global Network Monitoring Market Foresight
Enterprise-grade telemetry resolution is bifurcating the competitive landscape between premium full-stack observability and cost-optimized point solutions. NETSCOUT Systems Inc. leverages its deep packet inspection heritage to dominate carrier-class deployments at scale. Datadog Inc. anchors its position through cloud-native integration density across multicloud estates. Cisco Systems Inc. extends its incumbent advantage by embedding monitoring intelligence directly into switching and routing hardware.
Network monitoring encompasses the continuous capture, analysis, and alerting of traffic flows, device states, and application performance across physical and virtual infrastructure, typically operating at millisecond granularity to detect anomalies before service degradation occurs. Its primary commercial purpose is ensuring operational continuity and security compliance for organizations whose revenue depends on uninterrupted digital service delivery. Cloud-based deployment is capturing the fastest expansion as enterprises retire legacy on-premises toolchains, while security monitoring solutions command premium pricing due to their integration with zero-trust architectures and threat intelligence pipelines. Managed services represents a maturing but sticky segment where multi-year contracts lock in recurring revenue through SLA-backed uptime guarantees.
The Federal Communications Commission shapes US market access through net neutrality enforcement and critical infrastructure designation, while the European Union Agency for Cybersecurity enforces NIS2 harmonized standards that mandate cross-border incident reporting and supply chain risk management. ISO 27001 and IEC 62443 certifications increasingly function as de facto procurement filters, particularly for vendors serving government agencies and regulated financial institutions. Stakeholders must weigh the capital efficiency of cloud-native delivery models against the data sovereignty requirements that still favor on-premises or sovereign-cloud deployments in defense and healthcare verticals.
Market Dynamics
The convergence of hyperscale data center buildouts and federal zero-trust mandates is compressing procurement cycles for network visibility tools, forcing vendors to embed analytics directly into infrastructure hardware rather than selling standalone software licenses.
Growth Catalysts
- EU AI Act enforcement:Critical digital service providers across European financial hubs must deploy continuous traffic monitoring to satisfy operational resilience mandates, accelerating replacement of legacy toolchains.
- Cloud-native telemetry:Financial institutions migrating core banking systems to distributed cloud architectures require millisecond-granularity observability to maintain SLA guarantees with retail customers.
- Federal zero-trust architecture:United States government agencies are mandating deep packet inspection at every network segment, creating sustained demand for carrier-grade monitoring infrastructure.
Market Restraints
- Specialized engineering talent scarcity:The shallow pool of professionals skilled in both network protocol analysis and cloud-native orchestration limits deployment velocity for complex multicloud estates.
- Silicon supply concentration:Dependence on advanced semiconductor fabrication concentrated in East Asian foundries creates procurement risk for hardware-embedded monitoring appliances.
- Data sovereignty fragmentation:Conflicting national data localization requirements between Germany, France, and emerging digital economies complicate cross-border SaaS delivery models.
Strategic Opportunities
- India's banking modernization:RBI-mandated digital payment infrastructure upgrades are creating first-mover advantage for vendors offering sovereign-cloud compliant monitoring solutions.
- 5G network slicing:Convergence of software-defined networking with edge computing architectures enables premium service tiering for industrial IoT monitoring contracts.
- Healthcare vertical expansion:HIPAA-compliant real-time monitoring for connected medical devices represents underpenetrated demand as hospital systems consolidate IT operations.
Industry Challenges
- ISO 27001 certification timelines:The 12-18 month audit cycle for information security management systems delays market entry for new vendors targeting government procurement channels.
- Legacy SNMP integration:Enterprise IT teams struggle to reconcile decades-old Simple Network Management Protocol investments with cloud-native API-driven observability platforms.
- Cross-functional skill gaps:Security operations centers lack personnel who can correlate network telemetry with application performance data, reducing tool utilization rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Network Monitoring Market |
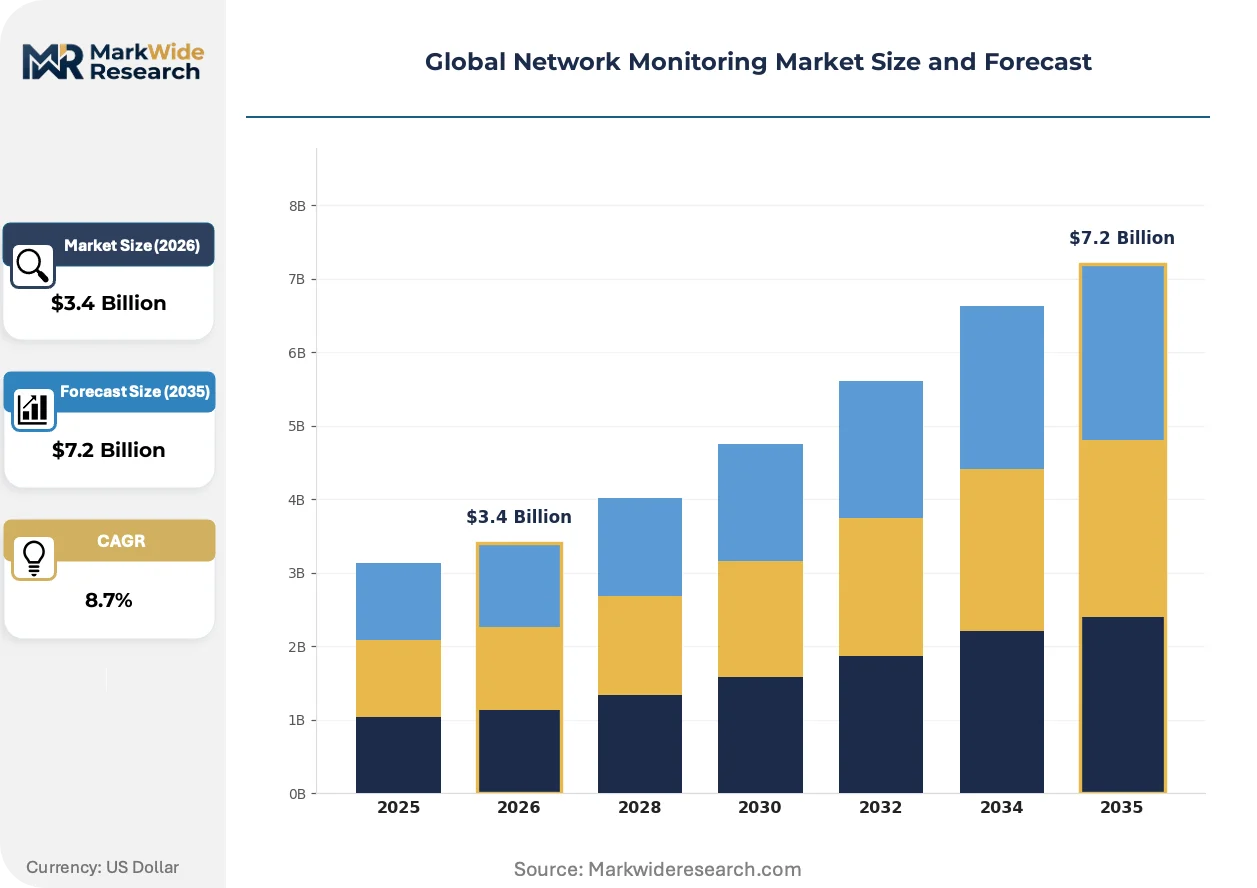
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $7.2 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Edge, Managed Services Solution: Bandwidth Monitoring, Fault Management, Performance Analysis, Security Monitoring, Configuration Management Application: Data Center Management, Enterprise Networks, Service Provider Networks, Cloud Infrastructure, Telecom Networks End User: Telecom Operators, Financial Institutions, Government Agencies, Educational Institutions, Manufacturing Firms |
| Companies Covered | NETSCOUT Systems Inc., Juniper Networks Inc., Cisco Systems Inc., Riverbed Technology Inc., Datadog Inc., SolarWinds Inc., Broadcom Inc., LogicMonitor Inc., IBM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Network Monitoring Market Shifts & Advancements
Telemetry processing architectures are migrating from centralized data lakes toward edge-native computation, compressing detection latency while complicating vendor consolidation strategies across the ecosystem.
eBPF kernel instrumentation is miniaturizing observability overhead by executing packet analysis within Linux kernel space rather than userspace agents. Cloud-native platform teams at hyperscale retailers are deploying eBPF-based tools across container fleets within single-quarter rollout cycles. This kernel-level execution model is compressing CPU resource consumption for monitoring workloads by an order of magnitude compared to traditional agent architectures.
NIS2 Directive harmonized standards are mandating cross-border incident reporting timelines for critical digital infrastructure operators. European network monitoring procurement now requires built-in automated threat intelligence pipelines that feed national Computer Security Incident Response Teams. Financial services providers in Germany and the Netherlands are prioritizing vendors with pre-certified compliance modules to accelerate security authorization timelines.
Consumption-based pricing models are displacing perpetual license structures across enterprise procurement negotiations. Mid-market technology firms are demanding metered billing tied to actual flow volume rather than port count or device limits. This behavioral shift is most visible in United States SaaS procurement, where infrastructure teams prefer operational expenditure treatment for monitoring tools aligned with cloud cost optimization mandates.
Global Network Monitoring Market Segmentation
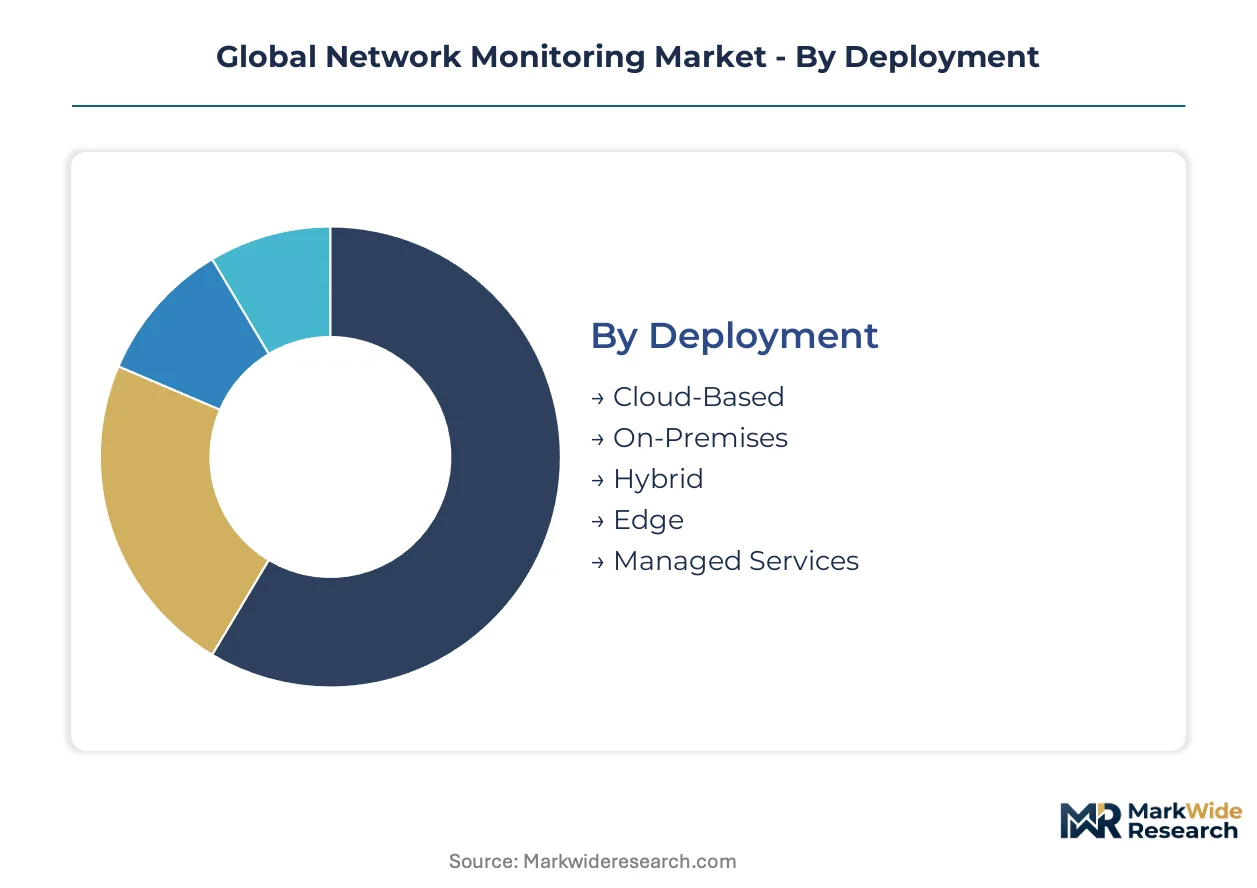
Network monitoring procurement diverges sharply across deployment models and end-user risk profiles. Buyers weigh sovereignty requirements against cloud-native agility when selecting solution architectures.
Deployment:
Cloud-based offerings face the most acute substitution pressure from edge-native alternatives as latency-sensitive workloads proliferate.
- Cloud-Based:SaaS delivery eliminates infrastructure overhead while enabling elastic scaling for multicloud estates. Financial institutions migrating core banking systems to distributed architectures drive concentrated demand in the United States and Germany.
- On-Premises:Hardware-embedded appliances retain dominance where data sovereignty mandates prohibit cross-border telemetry flows. Defense and healthcare verticals in France and Japan maintain rigid on-premises requirements.
- Hybrid:Split architectures reconcile legacy SNMP investments with cloud-native observability platforms.
- Edge:Kernel-level packet processing at network peripheries compresses detection latency for industrial IoT deployments.
- Managed Services:SLA-backed outsourcing locks in recurring revenue through multi-year operational contracts.
On-Premises anchors the volume base while Edge gains share at the steepest rate.
Solution:
Security monitoring commands the widest pricing spreads due to zero-trust integration complexity.
- Security Monitoring:Deep packet inspection pipelines feed threat intelligence systems with millisecond-granularity traffic analysis. United States federal agencies mandate this capability at every network segment under zero-trust architecture directives.
- Performance Analysis:Real-time telemetry correlation across application and infrastructure layers maintains SLA guarantees for cloud-native service delivery. Hyperscale retailers in the Netherlands and Singapore deploy these tools across container fleets.
- Bandwidth Monitoring:Flow volume measurement enables capacity planning and cost optimization.
- Fault Management:Automated root-cause analysis reduces mean-time-to-resolution for carrier-class networks.
- Configuration Management:Policy drift detection ensures compliance with IEC 62443 and ISO 27001 standards.
Bandwidth Monitoring anchors the volume base while Security Monitoring climbs the fastest.
Application:
Data center buildouts concentrate procurement volumes where hyperscale expansion intersects with regulatory density.
- Data Center Management:East-west traffic visibility within virtualized environments prevents lateral threat movement. Cloud infrastructure adoption among financial institutions in India and Brazil accelerates investment.
- Cloud Infrastructure:API-driven observability platforms reconcile Kubernetes orchestration with legacy network protocols. European banking hubs prioritize vendors with pre-certified NIS2 compliance modules.
- Enterprise Networks:Distributed branch office monitoring consolidates under single-pane-of-glass consoles.
- Service Provider Networks:Carrier-grade scale requires deep packet inspection at terabit-per-second throughput.
- Telecom Networks:5G network slicing enables premium service tiering for industrial IoT contracts.
Enterprise Networks anchors the volume base while Cloud Infrastructure expands most quickly.
End User:
Telecom operators sustain the deepest replacement cycles as network function virtualization displaces legacy probe architectures.
- Telecom Operators:5G standalone core deployments demand continuous subscriber-plane monitoring at unprecedented scale. RBI-mandated digital payment infrastructure upgrades in India create first-mover opportunities for compliant vendors.
- Financial Institutions:Operational resilience mandates under EU AI Act and NIS2 Directive accelerate toolchain replacement. German and Dutch banks prioritize automated cross-border incident reporting capabilities.
- Government Agencies:Federal zero-trust mandates in the United States reshape procurement priorities for network visibility tools.
- Educational Institutions:Campus network consolidation drives demand for unified wired and wireless monitoring.
- Manufacturing Firms:Connected device telemetry for predictive maintenance remains underpenetrated.
Telecom Operators anchors the volume base while Financial Institutions gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Israeli network monitoring vendors export specialized cybersecurity telemetry platforms to European financial hubs and United States federal agencies. This trade corridor channels innovation from Tel Aviv's dense startup cluster into regulated procurement pipelines.
United States
FCC net neutrality enforcement and critical infrastructure designation compress procurement cycles for hyperscale data centers in Northern Virginia and Dallas-Fort Worth. Federal zero-trust architecture mandates reshape visibility tool priorities across civilian and defense agencies. Palo Alto and Seattle clusters anchor cloud-native observability development for multicloud estates.
Germany
Industrial IoT deployments in automotive manufacturing drive edge-native monitoring demand across Baden-Württemberg and Bavaria. BSI and KBA enforce IEC 62443 certification requirements for connected vehicle infrastructure. Frankfurt's financial district concentrates operational resilience investment under NIS2 Directive timelines.
India
RBI-mandated digital payment infrastructure upgrades accelerate sovereign-cloud compliant solution procurement. TRAI spectrum allocation rules shape telecom operator monitoring requirements for 5G standalone core rollouts. Mumbai and Bangalore clusters lead banking modernization telemetry deployments.
Japan
METI operational technology security guidelines mandate continuous network visibility for critical manufacturing systems. Osaka and Nagoya industrial corridors deploy predictive maintenance monitoring across connected device fleets. Data localization requirements favor domestic vendors or joint ventures for sensitive infrastructure.
United Kingdom
NCSC cyber assessment framework shapes financial services procurement in London and Edinburgh. Post-Brexit data adequacy negotiations complicate cross-border SaaS delivery for EU-facing operations. Manchester and Bristol tech clusters specialize in healthcare-compliant monitoring for NHS digital transformation.
Global Network Monitoring Market Competitive Landscape
Listed leaders compete with private specialists across capital access and agile product development dimensions. The vendor base organizes around three tiers: incumbent infrastructure hardware vendors, cloud-native SaaS platforms, and specialized packet inspection engineers. Strategic moves concentrate on embedded analytics integration and consumption-based pricing model transitions.
Within the carrier-grade infrastructure tier, NETSCOUT Systems Inc. and Cisco Systems Inc. exemplify deep packet inspection heritage positions. Datadog Inc. occupies the cloud-native integration density archetype for multicloud estates. These three anchors represent divergent competitive vectors: hardware-embedded intelligence versus API-driven observability platforms versus kernel-level telemetry execution.
| Leading Market Players |
|---|
| NETSCOUT Systems Inc. |
| Juniper Networks Inc. |
| Cisco Systems Inc. |
| Riverbed Technology Inc. |
| Datadog Inc. |
| SolarWinds Inc. |
| Broadcom Inc. |
| LogicMonitor Inc. |
| IBM |
| Others |
Supply & Pricing Matrix
Multi-year managed service contracts with SLA-backed uptime guarantees lock in both supply access and price visibility for enterprise buyers, insulating procurement teams from spot-market volatility in semiconductor components while embedding telemetry infrastructure directly into operational expenditure frameworks across United States federal agencies and European financial institutions.
Pricing Analysis
Hardware-embedded monitoring appliances command substantial premiums over cloud-native SaaS tiers due to silicon scarcity and sovereign-cloud compliance requirements. Three-tier pricing structure across premium carrier-grade, standard enterprise, and economy point-solution levels stratifies by certification depth—ISO 27001 and IEC 62443 pre-certification accelerates authorization timelines and justifies 40-60% uplifts. Cost compression in the economy tier intensifies because eBPF kernel instrumentation eliminates agent licensing overhead. Mid-market technology firms exhibit highest price sensitivity, while defense and healthcare verticals prioritize data sovereignty over unit economics.
Supply Chain Analysis
Advanced semiconductor fabrication concentrated in Taiwan and South Korea creates single-source vulnerability for packet processing ASICs and high-throughput network interface controllers. Hardware-embedded monitoring appliances draw from specialized foundry capacity, FPGA programmable logic, and precision timing components. Tariff exposure on East Asian electronics imports compounds procurement risk for United States vendors. Distribution runs through authorized channel partners with certified integration capabilities rather than direct fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telemetry architecture fragmentation creates niche openings as edge-native computation displaces centralized data lakes, splintering procurement across kernel-level instrumentation, API-driven observability platforms, and hardware-embedded intelligence.
For Market Incumbents: Compound embedded analytics integration into switching and routing hardware to preempt standalone software displacement. Acquire eBPF-native tooling specialists before cloud-native challengers consolidate this layer. Deep packet inspection heritage positions NETSCOUT and Cisco to absorb carrier-class replacement cycles, but Datadog's API density threatens enterprise account erosion without rapid multicloud orchestration response. For New Entrants and Emerging Players: ISO 27001 fast-track partnerships with German BSI and Dutch NCSC accelerate security authorization timelines for NIS2-mandated procurement. Healthcare verticals remain underpenetrated—HIPAA-compliant real-time monitoring for connected medical devices offers first-mover positioning before hospital system IT consolidation matures. Lead with consumption-based pricing aligned to cloud cost optimization mandates rather than perpetual license displacement. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated specialists with kernel-level telemetry execution and pre-certified compliance modules. The 5-10 year viability window favors vendors bridging legacy SNMP investments with cloud-native API observability. Watch RBI-mandated Indian banking modernization as inflection indicator—sovereign-cloud compliant solution procurement there signals replication potential across Brazil and Southeast Asian financial hubs.| Strategic Initiative | Industry Significance |
|---|---|
| Kernel-Level Telemetry Integration | eBPF instrumentation compresses CPU overhead for hyperscale container deployments at Dutch retailers. |
| Sovereign-Cloud Compliance Certification | Pre-certified NIS2 modules accelerate German bank procurement under EU operational resilience mandates. |
| Consumption-Based Pricing Transition | Metered billing tied to flow volume aligns with United States cloud cost optimization directives. |
| Healthcare Vertical Expansion | HIPAA-compliant monitoring captures hospital system consolidation before incumbent platform lock-in. |
| Edge-Native Computation Architecture | Peripheral packet processing reduces detection latency for industrial IoT predictive maintenance contracts. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC infrastructure capex disclosures, hyperscaler procurement filings, and EU regulatory harmonization texts. Network operations directors, cloud platform engineers, federal IT procurement officers, and compliance leads at financial institutions provided qualitative input. Bottom-up triangulation against top-down macroeconomic indicators validates segment-level projections.
Deployment model, solution type, end-user vertical, and regional regulatory cluster dimensions structure the analytical framework. CAGRs derive from elasticity modeling across substitution scenarios between hardware-embedded and cloud-native architectures. Forecast inputs incorporate 5G standalone core rollout timelines and zero-trust mandate implementation phases across United States civilian agencies.
Decision-makers should treat outputs as directional under assumptions of sustained semiconductor supply normalization and stable cross-border data flow regimes; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as EU AI Act enforcement intensity and East Asian foundry capacity allocation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Global Network Probe Market
Network Technology
Netops Market
Network Technology
North America Network Management Solutions Market
Network Technology
Carrier Routing Equipment Market
Network Technology
Mobile Accelerator Market
Network Technology
Wi-Fi Network Equipment Market
Network Technology
United States and European Fiber Optic Cable Market
Network Technology
Lit Fiber Market
Network Technology
Wi-Fi As a Service (Waas) Market
Network Technology
Global Internet Transit Market
Network Technology
Global Intelligent Network Market
Network Technology
Gigabit Ethernet Market
Network Technology
Network Equipment Market
Network Technology
Router and Switch Market
Network Technology
North America Structured Cabling Market
Network Technology
US Private LTE and 5G Network Market