
 Residential Routers Market | 2026-2036
Residential Routers Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Routers Market Analytics
The EU Ecodesign Directive is realigning power efficiency benchmarks for residential networking hardware across member states. TP-Link Technologies Co. Ltd leverages its Shenzhen manufacturing base to sustain cost leadership in mesh router shipments. Huawei Technologies Co. Ltd anchors its position through vertical control over chip design and baseband integration. NETGEAR Inc. differentiates via premium gaming router sub-brands with firmware customization.
Residential routers are network gateway devices that route data packets between local area networks and wide area networks, typically incorporating dual-band or tri-band radios operating at 2.4 GHz and 5/6 GHz frequencies with throughput ratings from 1 Gbps to over 10 Gbps. Their primary purpose is to enable multiple wired and wireless client devices to share a single internet connection while providing firewall protection and quality-of-service management. Mesh routers now command the fastest expansion within product type segments as whole-home coverage replaces single-unit deployments in larger dwellings. Wi-Fi 6 and Wi-Fi 6E technology segments capture disproportionate margin pools where semiconductor scarcity and certification complexity limit vendor participation. Single-family homes remain the dominant end user category though remote workers represent the most volatile demand vector as hybrid work policies fluctuate.
The FCC governs unlicensed spectrum access and emission limits in the United States while ETSI harmonizes radio equipment standards across Europe through the Radio Equipment Directive. Both frameworks directly determine which frequency bands manufacturers can activate and which devices gain market entry. China's MIIT operates parallel certification for WLAN products that vendors must clear for domestic sales. Stakeholders must monitor spectrum reallocation proceedings and energy efficiency rulemakings as these will dictate next-generation hardware requirements and regional compliance costs.
Market Dynamics
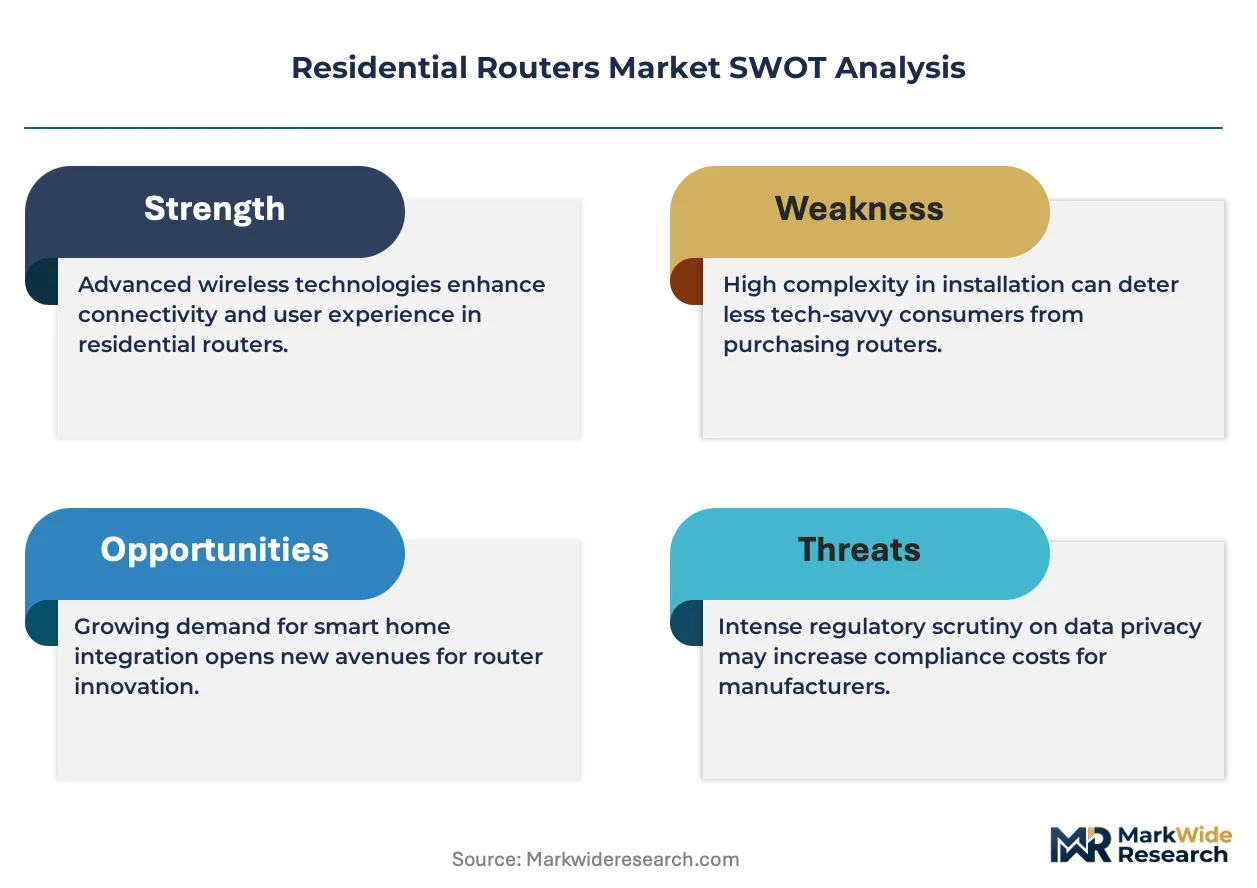
Wi-Fi 6E spectrum allocation by the FCC is compressing product lifecycles as manufacturers race to certify tri-band hardware before rival platforms capture retail shelf space. This single regulatory trigger is forcing simultaneous investments in radio frequency engineering, thermal design, and firmware architecture across the vendor base.
Growth Catalysts
- FCC 6 GHz Unlicensed Rules:The United States regulator opened 1,200 MHz of contiguous spectrum, enabling gigabit-class throughput that multi-device households now demand for 8K streaming and cloud gaming workloads.
- Multi-Device Household Density:Smart home ecosystems now average 20+ connected endpoints per dwelling, creating replacement pull for mesh systems that eliminate dead zones through distributed node architectures.
- Fiber-to-the-Home Rollouts:China's aggressive FTTH infrastructure buildout saturates urban markets with gigabit-capable backhaul, rendering legacy 802.11ac equipment obsolete and accelerating upgrade cycles.
Market Restraints
- Semiconductor Supply Concentration:Advanced Wi-Fi 6E system-on-chip production clusters at TSMC and Samsung foundries in Taiwan and South Korea, exposing vendors to geopolitical disruption and allocation rationing.
- Radio Certification Complexity:ETSI's Radio Equipment Directive and China's MIIT impose divergent test protocols for 6 GHz emissions, fragmenting engineering resources and delaying regional product launches.
- Copper and Rare Earth Input Volatility:PCB substrates and gallium arsenide power amplifiers face price swings tied to mining output in specific geographies, compressing hardware margins at the economy tier.
Strategic Opportunities
- EU Ecodesign Directive Alignment:The European Union's standby power limits create first-mover advantage for vendors with integrated power management silicon, locking out competitors dependent on discrete component architectures.
- Remote Worker Segment Specialization:Hybrid employment policies stabilize demand for quality-of-service prioritization features that enterprise-grade firmware previously reserved for commercial access points.
- Matter Protocol Convergence:The unified smart home standard collapses Zigbee and Z-Wave fragmentation, allowing router-integrated hub functionality to displace standalone bridge hardware in North American installations.
Industry Challenges
- RF Engineering Talent Scarcity:Millimeter-wave antenna design and beamforming algorithm development require specialized expertise concentrated at semiconductor firms and research universities, constraining in-house R&D scaling.
- Legacy IPv4 Address Translation:Carrier-grade NAT dependencies in older firmware complicate peer-to-peer gaming and IoT device discovery, forcing costly software rearchitecture without immediate revenue recovery.
- Interoperability Certification Backlogs:Wi-Fi Alliance and Broadband Forum test lab capacity limits create 4-6 month queues for final product approval, delaying seasonal retail placement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Residential Routers Market |
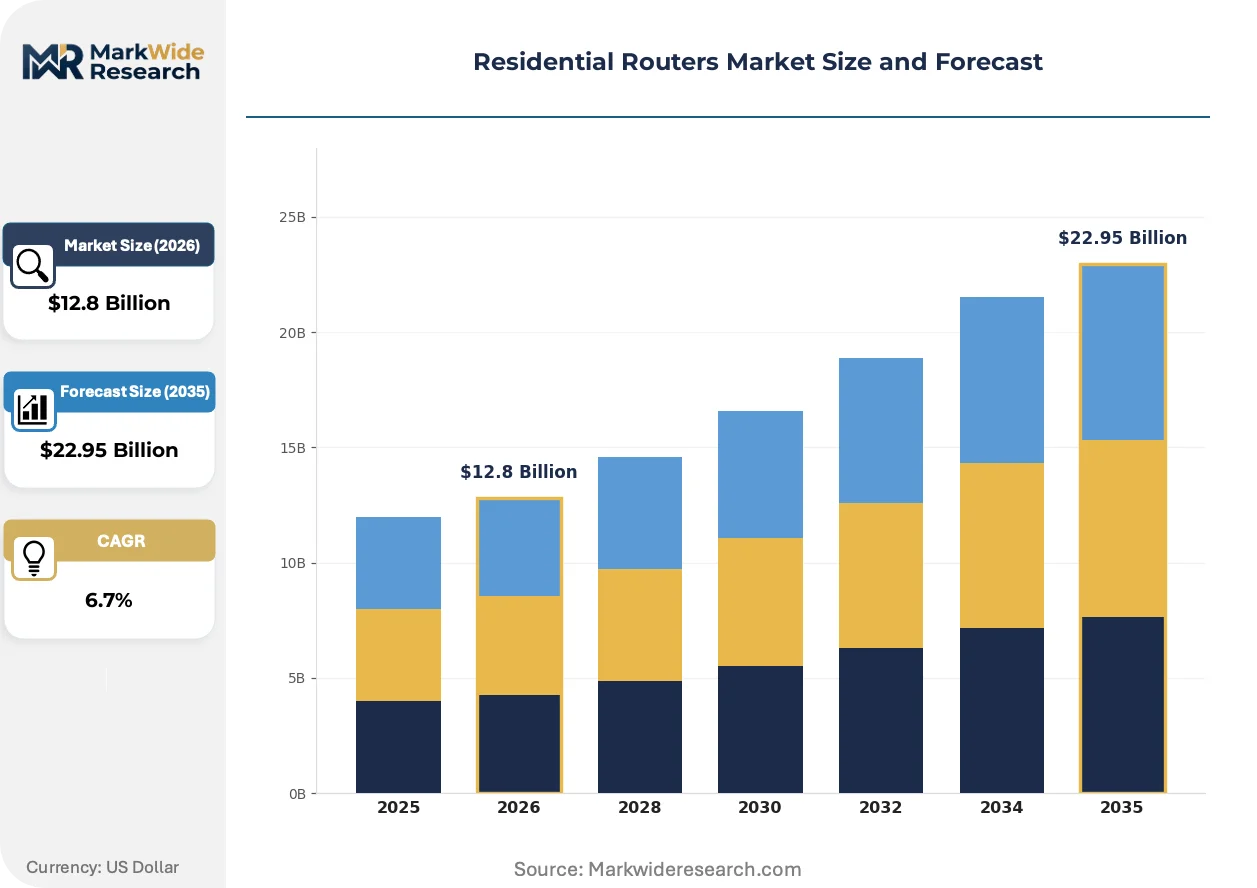
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Routers, Mesh Routers, Smart Routers, Gaming Routers Technology: Wi-Fi 5, Wi-Fi 6, Wi-Fi 6E, LTE End User: Single-Family Homes, Apartments, Small Offices, Remote Workers Deployment: Cloud-Based, On-Premises, Hybrid, Managed Services |
| Companies Covered | NETGEAR Inc., TP-Link Technologies Co. Ltd, ASUSTeK Computer Inc., D-Link Corporation, Belkin International, Inc., Huawei Technologies Co. Ltd, Linksys, Zyxel Communications Corp., Motorola, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Routers Market Evolving Landscape
Radio frequency architecture is absorbing the full impact of spectrum expansion, with thermal design and power amplifier efficiency now determining competitive differentiation more than raw throughput claims. Vendors must simultaneously optimize for 6 GHz coverage and sub-6 GHz backward compatibility.
Wi-Fi 7 (802.11be) is absorbing the engineering priorities of flagship product teams, with 320 MHz channel bonding and multi-link operation promising sub-5 millisecond latency for time-sensitive industrial and gaming applications. Early adopters in South Korea and Japan are stress-testing pre-certified silicon through internet service provider partnerships. The technology is absorbing margin from Wi-Fi 6E before that standard achieves mass-market cost parity, compressing the revenue window for intermediate-generation hardware.
The EU Ecodesign Directive is tightening standby power limits to 2.00 watts for networked equipment, forcing power supply redesigns and deep-sleep firmware states that complicate always-on IoT responsiveness. Manufacturers serving European Union member states must retest existing SKUs or withdraw from distribution channels. Mesh router systems with distributed node sleeping are absorbing compliance cost advantages over monolithic designs that cannot granularly power down radio chains.
Subscription-based security and parental control services are displacing perpetual-license firmware features as the primary post-purchase revenue stream. Retail channel buyers in the United States now expect 12-24 month trial bundles with hardware purchases, shifting margin capture from point-of-sale to recurring billing relationships. This model is concentrating customer lifetime value calculations among vendors with cloud infrastructure scale, disadvantaging hardware-only competitors.
Residential Routers Market Segmentation
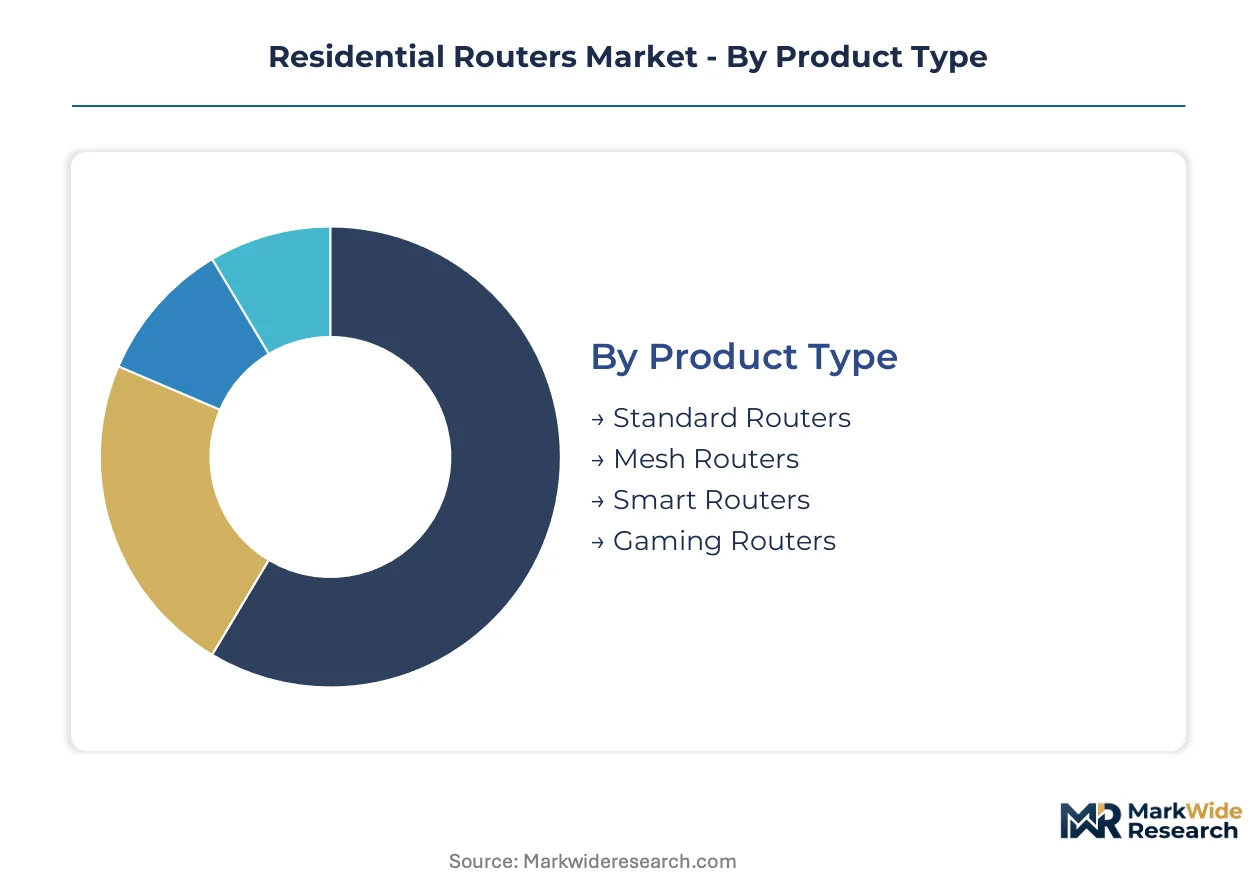
Residential router segmentation determines certification pathways, thermal design budgets, and firmware architecture investments. Vendors align product portfolios across four intersecting dimensions that dictate regional compliance costs and margin structures.
Product Type:
Certification burden varies sharply: mesh systems require multi-node RF coordination testing under FCC Part 15 and ETSI RED, while gaming routers face additional EMI scrutiny for high-power amplifiers.
- Standard Routers:Single-unit architectures with integrated 2.4 GHz and 5 GHz radios serving basic broadband termination. Demand concentrates in India's tier-2 cities where BSNL fiber expansion drives replacement of legacy DSL gateways, though price compression limits margin recovery.
- Mesh Routers:Distributed node systems employing dedicated backhaul channels for seamless roaming. Demand concentrates in US suburban single-family homes where 3,000+ square foot coverage requirements and 20+ device densities justify premium positioning.
- Smart Routers:Cloud-managed units with integrated voice assistants and IoT hub functionality. China's MIIT cybersecurity certification adds 8-12 weeks to domestic launch timelines.
- Gaming Routers:Prioritized traffic shaping firmware with hardware-accelerated NAT and QoS tagging. ETSI's stricter 5 GHz power limits in Germany and France force regional SKU fragmentation.
Leading the category by volume: Standard Routers. Growing fastest: Mesh Routers.
Technology:
Cost tier alignment separates premium silicon from economy chipsets, with foundry allocation rationing at TSMC and Samsung creating supply-side stratification.
- Wi-Fi 5:802.11ac wave-2 platforms with 80 MHz channel bonding and MU-MIMO support. Brazil's Anatel certification backlog delays entry for new Wi-Fi 5 economy models, preserving incumbent advantage.
- Wi-Fi 6:OFDMA-based 1024-QAM systems targeting 9.6 Gbps theoretical throughput. Remote worker households in Japan's Tokyo-Osaka corridor drive enterprise-grade feature adoption into residential price points.
- Wi-Fi 6E:Tri-band architectures accessing 6 GHz spectrum with 160 MHz contiguous channels. FCC unlicensed rules enable gigabit-class throughput for 8K streaming workloads in US multi-device households.
- LTE:Cellular-backup routers for rural broadband substitution. Australia's NBN satellite coverage gaps sustain demand in Queensland and Western Australia outback regions.
Volume leadership: Wi-Fi 5. Steepest expansion trajectory: Wi-Fi 6E.
End User:
Application context dictates antenna configuration, with small offices requiring external high-gain options and apartments demanding compact wall-mount designs.
- Single-Family Homes:Detached dwellings with basement-to-attic coverage requirements and outdoor smart device connectivity. Germany's KfW energy efficiency subsidies for smart home retrofits stimulate mesh system adoption in Bavaria and Baden-Württemberg.
- Apartments:High-density RF environments with channel congestion from neighboring networks. South Korea's apartment-dominant housing stock drives demand for DFS channel utilization and automatic band steering.
- Small Offices:SOHO deployments requiring VLAN segmentation and guest network isolation. India's GST registration threshold for small businesses creates a 20-50 employee sweet spot for prosumer-grade hardware.
- Remote Workers:Hybrid employment arrangements demanding enterprise-equivalent QoS and VPN throughput. Canada's Atlantic provinces see concentrated demand as federal remote-work mandates stabilize.
Single-Family Homes dominate unit shipments. Remote Workers segment climbing the fastest.
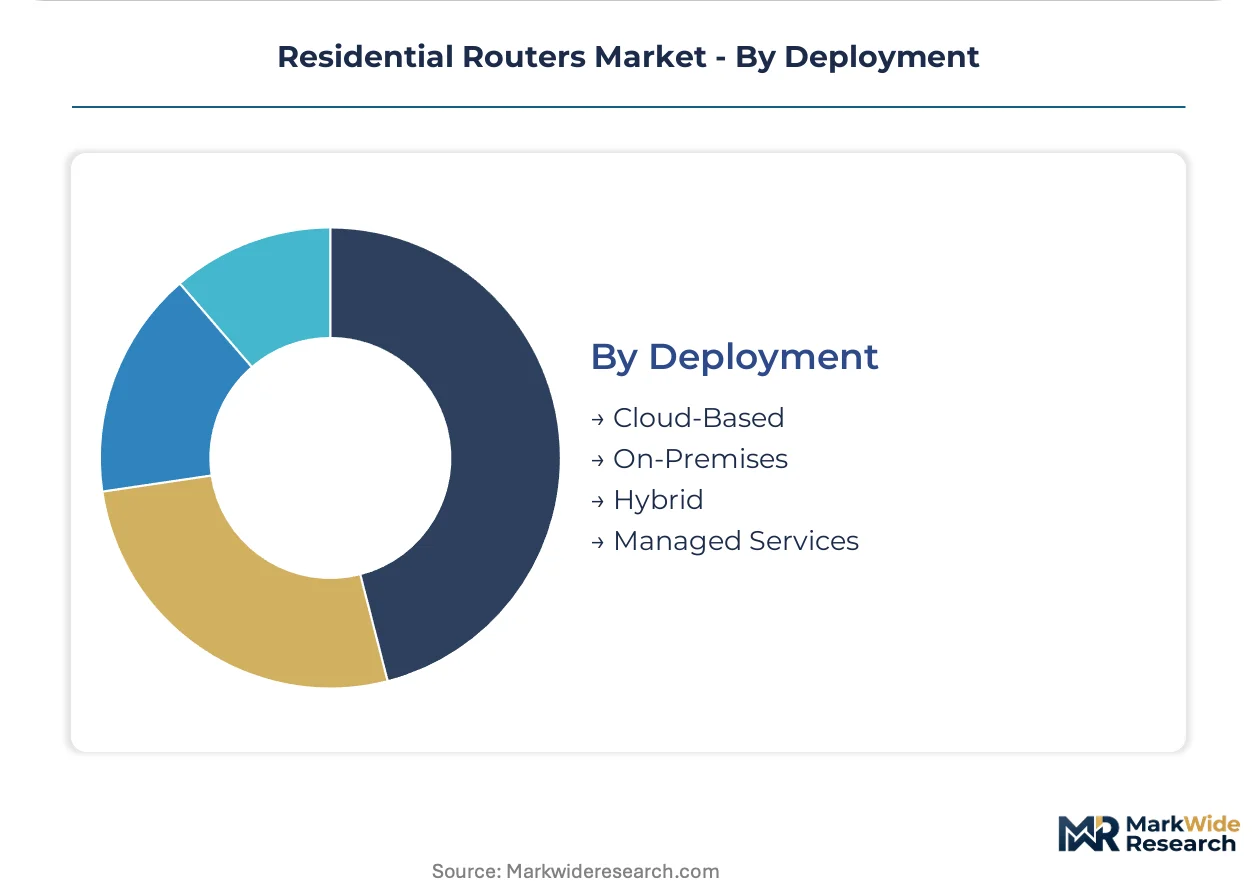
Deployment:
Customer type determines support infrastructure, with managed services requiring 24/7 NOC capabilities and on-premises demanding retail channel presence.
- Cloud-Based:Firmware-over-the-air management with traffic analytics dashboards. France's CNIL data localization requirements complicate cloud architecture for vendors serving GDPR-sensitive households.
- On-Premises:Local web interface administration without external data transmission. Germany's Federal Office for Information Security (BSI) baseline protection certification favors on-premises control for privacy-conscious consumers.
- Hybrid:Local processing with optional cloud enhancement for parental controls and security updates. UK ISP bundling strategies favor hybrid models enabling remote diagnostics without full cloud dependency.
- Managed Services:ISP-provisioned equipment with integrated support and automatic replacement. Japan's NTT East and NTT West fiber service bundles concentrate managed router penetration in Kanto and Kansai regions.
On-Premises deployment leads by installed base. Managed Services gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors manufacturing scale for residential networking hardware, with the Pearl River Delta corridor supplying component ecosystems that feed global distribution channels.
United States
FCC unlicensed spectrum rules for 6 GHz bandwidth drive tri-band router adoption across suburban households. The regulator's emission limits force thermal design investments that compress margins at the economy tier. Austin and Seattle tech corridors concentrate smart home ecosystem integration engineering.
China
MIIT cybersecurity certification for WLAN products adds 8-12 weeks to domestic launch timelines for cloud-managed units. The ministry's parallel standards regime fragments engineering resources versus FCC-aligned roadmaps. Shanghai and Beijing clusters dominate firmware development for fiber-to-the-home bundled equipment.
Germany
KfW energy efficiency subsidies for smart home retrofits stimulate mesh system adoption in Bavaria and Baden-Württemberg. The BSI baseline protection certification favors on-premises control architectures over cloud-dependent alternatives. Stuttgart automotive supplier networks supply precision RF component manufacturing.
Japan
NTT East and NTT West fiber service bundles concentrate managed router penetration in Kanto and Kansai regions. METI standards harmonization with Wi-Fi Alliance protocols accelerates certification timelines versus ETSI divergence. Osaka semiconductor packaging clusters support power amplifier module production.
South Korea
Apartment-dominant housing stock drives demand for DFS channel utilization and automatic band steering in Seoul Capital Area. The MFDS electromagnetic compatibility framework aligns with FCC protocols, enabling faster US export certification. Busan-Ulsan electronics manufacturing bases supply PCB substrate volume.
Residential Routers Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification complexity and silicon integration depth. The vendor base stratifies into three tiers: semiconductor-integrated specialists, firmware-differentiated brands, and contract-manufacturing assemblers. Strategic archetypes include vertical silicon controllers, cloud-service bundlers, and retail-channel optimizers. Dominant competitive moves span geographic certification pre-positioning and subscription revenue model migration.
Within the semiconductor-integrated tier, Huawei Technologies Co. Ltd and TP-Link Technologies Co. Ltd exemplify divergent approaches to supply chain control. Shenzhen-based TP-Link Technologies Co. Ltd occupies a position anchored by manufacturing scale advantages. Huawei Technologies Co. Ltd represents vertical silicon strategy through captive chip design capabilities. NETGEAR Inc. sits within the premium firmware-differentiated archetype, with San Jose headquarters signaling North American market prioritization.
| Leading Market Players |
|---|
| NETGEAR Inc. |
| TP-Link Technologies Co. Ltd |
| ASUSTeK Computer Inc. |
| D-Link Corporation |
| Belkin International, Inc. |
| Huawei Technologies Co. Ltd |
| Linksys |
| Zyxel Communications Corp. |
| Motorola |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap specialists across Taiwan and South Korea anchor advanced Wi-Fi silicon production, their concentrated ownership patterns enabling long-term foundry commitments that stabilize wafer pricing while limiting spot-market flexibility for smaller router vendors.
Pricing Analysis
Throughput-based value anchors dominate residential router pricing, with gigabit-class Wi-Fi 6E systems commanding substantial premiums over 802.11ac legacy units. Three-tier pricing structure across premium, standard, and economy levels separates gaming-optimized firmware SKUs from basic mesh configurations and entry-level single-band units. Cost compression in the economy tier is intensifying because TSMC allocation rationing forces smaller vendors toward costlier spot-market chip procurement. Remote worker households exhibit the least price sensitivity, prioritizing enterprise-grade QoS features, while India's tier-2 urban markets remain the most price-constrained.
Supply Chain Analysis
Single-source vulnerability sits with TSMC's N7 and N6 process nodes for Wi-Fi 6E system-on-chip production, where geopolitical disruption in the Taiwan Strait would halt flagship router launches across multiple vendor roadmaps. Manufacturing gravity draws from China's Pearl River Delta for PCB assembly, Vietnam for power supply modules, and Taiwan for RF front-end components. Gallium arsenide power amplifiers and high-frequency PCB substrates feed from concentrated mining and chemical processing operations in China and Germany. Tariff exposure on Chinese-assembled finished goods threatens margin structures for US-bound shipments. Distribution runs through Shenzhen-export logistics hubs feeding regional retail channel partners and ISP procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Residential routers occupy a forced-migration phase as Wi-Fi 6E spectrum allocation by the FCC renders 802.11ac inventory economically obsolete, compressing the revenue window for intermediate-generation hardware before Wi-Fi 7 achieves cost parity.
For Market Incumbents: Deepen captive silicon development or foundry partnership tiers to defend against allocation rationing at TSMC and Samsung, while accelerating ETSI RED and MIIT certification pre-positioning ahead of Wi-Fi 7 regional launches. Mesh system firmware differentiation and cloud-subscription bundling represent critical margin defense levers against hardware-only competitors. For New Entrants and Emerging Players: The mid-tier price-point gap between TP-Link's economy positioning and NETGEAR's premium gaming sub-brands creates entry space for firmware-differentiated specialists targeting remote worker QoS requirements. India's BSNL fiber expansion zones and Germany's KfW-subsidized smart home retrofits offer the most penetrable geographic white space, with direct-to-ISP bundling partnerships as the optimal go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor cloud-infrastructure-scaled vendors with recurring security subscription revenue in North American markets, where retail channel consolidation is accelerating. Acquisition targets should demonstrate firmware-over-the-air architecture and GDPR-compliant data handling. The signal to watch is FCC Wi-Fi 7 certification timelines, which will determine whether intermediate-generation inventory becomes stranded.| Strategic Initiative | Industry Significance |
|---|---|
| 6 GHz Tri-Band Certification | FCC Part 15 approval unlocks gigabit throughput positioning in US suburban retail channels. |
| Mesh Firmware Subscription Bundling | Recurring security revenue shifts margin capture from hardware point-of-sale to customer lifetime value. |
| EU Ecodesign Directive Alignment | Integrated power management silicon creates compliance cost advantage over discrete component architectures. |
| ISP Managed Services Partnership | NTT East and NTT West fiber bundles in Japan concentrate penetration in Kanto and Kansai regions. |
| Matter Protocol Hub Integration | Unified smart home standard collapses Zigbee fragmentation, displacing standalone bridge hardware. |
Research Methodology
Document review covered FCC Part 15 and ETSI RED regulatory filings, MIIT cybersecurity certification databases, and Wi-Fi Alliance interoperability test results, complemented by interviews with router vendor product managers, ISP procurement directors, RF engineering leads at semiconductor firms, and retail channel category buyers. Secondary validation drew from customs trade data for networking equipment, SEC 10-K filings for publicly traded vendors, and hyperscaler capex disclosures for cloud infrastructure scaling. Bottom-up unit shipment estimates by product type and technology tier were cross-referenced against top-down market value reconstructions.
Historical shipment trajectories were cross-referenced against panel input from component suppliers and foundry allocation managers across the analysis window. Segmentation modeling incorporated product type, technology generation, end-user dwelling category, and deployment architecture dimensions. CAGRs were derived from slope-intercept analysis of technology adoption curves and replacement cycle dynamics. Forecast inputs included fiber-to-the-home penetration rates by country, spectrum allocation proceedings, and energy efficiency rulemaking timelines.
Inputs from regulatory filing databases and primary stakeholder interviews were available through the study window; gaps in real-time foundry allocation data and pre-announcement Wi-Fi 7 certification schedules introduce uncertainty bands around vendor market share projections. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Managed Switches Market
Network Technology
GPON WIFI6 Home Gateway Market
Network Technology
Gigabit Ethernet Market
Network Technology
Home Wi-Fi Router and Extender Market
Network Technology
Multiservice Provisioning Platform Market
Network Technology
Radio Modem Market
Network Technology
Global Private 5G Network Market
Network Technology
Low-Power WAN Market
Network Technology
Global Passive Optical Network (PON) Equipment Market
Network Technology
5G Enterprise Private Network Market
Network Technology
WAN Optimization Controllers Market
Network Technology
Global Optical Transport Network (OTN) Market
Network Technology
Router and Switch Market
Network Technology
Power Over Ethernet (Poe) Solutions Market
Network Technology
Cloud Gateway Module Market
Network Technology
Enterprise Routers Market