
 Digital Process Automation Market | 2026-2036
Digital Process Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Process Automation Market Analysis
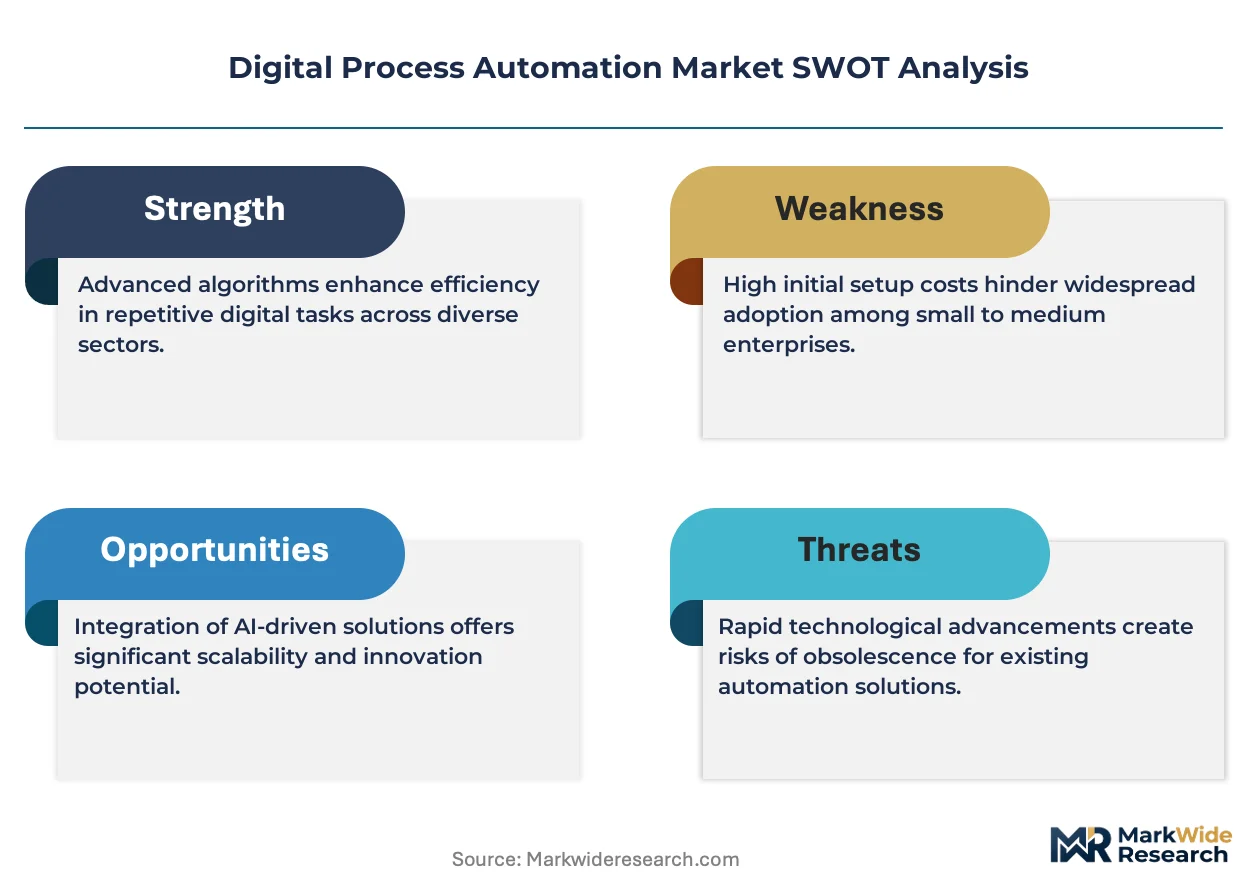
GDPR Article 22 is shifting the cost-of-entry calculus for vendors selling into European enterprises, forcing platforms to embed explainability layers and human-in-the-loop architectures by default. UiPath anchors its competitive position through extensive partner channel control across mid-market manufacturing verticals. IBM leverages its hybrid cloud footprint to sustain premium positioning in regulated industries requiring on-premises orchestration. Celonis specializes in process mining telemetry that maps operational bottlenecks before automation deployment, reducing implementation failure rates.
Digital Process Automation encompasses software platforms that orchestrate, execute, and optimize business workflows through robotic process automation, artificial intelligence, and business process management engines, typically operating via API-based integration with enterprise systems at sub-second response thresholds. These platforms eliminate manual handoffs in high-volume transactional environments such as invoice reconciliation, claims adjudication, and supply chain exception handling. Robotic Process Automation currently dominates deployment volumes due to its deterministic rule sets and rapid implementation cycles, though Artificial Intelligence segments capture disproportionate margin pools through natural language processing and intelligent document extraction capabilities. Cloud-Based deployment leads new bookings as CIOs prioritize elastic infrastructure over fixed on-premises licensing commitments.
The EU AI Act and GDPR collectively shape product roadmaps by mandating risk classification, audit trails, and human oversight for high-stakes automated decisions in credit, healthcare, and public administration. The SEC's disclosure requirements for material cybersecurity incidents further accelerate demand for automated compliance documentation and real-time control monitoring in publicly traded enterprises. Stakeholders must evaluate whether their automation portfolios can withstand concurrent regulatory audits across multiple jurisdictions without manual remediation overhead.
Market Dynamics
Algorithmic accountability mandates under the EU AI Act are forcing platform vendors to rearchitect core engines for explainability, embedding human-in-the-loop checkpoints that add latency but reduce regulatory exposure.
Growth Catalysts
- EU AI Act compliance deadlines:Banking and insurance enterprises in Germany, France, and Italy are accelerating procurement of audit-ready automation platforms ahead of enforcement milestones.
- Process mining telemetry:Industrial manufacturers deploy sensor-based operational mapping to identify bottlenecks before automation deployment, cutting implementation failure rates substantially.
- SEC cybersecurity disclosure rules:Publicly traded US enterprises demand automated control monitoring and real-time compliance documentation to satisfy incident reporting requirements.
Market Restraints
- Legacy ERP integration costs:On-premises orchestration requires substantial professional services expenditure to bridge SAP and Oracle systems with cloud-native automation layers.
- GDPR Article 22 friction:Automated decision systems in credit and healthcare face heightened scrutiny, forcing vendors to maintain parallel explainable architectures that inflate engineering overhead.
- Cloud concentration risk:Hyperscaler dependency for elastic infrastructure creates single-point-of-failure exposure for mid-market enterprises lacking multi-cloud failover capabilities.
Strategic Opportunities
- India's PLI scheme for manufacturing:Process automation vendors can capture subsidy-backed modernization programs across automotive and electronics assembly clusters in Tamil Nadu and Gujarat.
- Intelligent document processing convergence:Natural language extraction engines are merging with robotic process automation to displace manual invoice reconciliation in shared service centers.
- Japan's METI productivity mandates:Aging workforce demographics are driving public-sector procurement of workflow orchestration platforms for municipal administration and healthcare claims processing.
Industry Challenges
- Process mining specialist scarcity:Vendors struggle to recruit data scientists capable of translating operational telemetry into actionable automation roadmaps for manufacturing clients.
- Hybrid cloud certification timelines:Financial services buyers require FedRAMP and ISO 27001 attestations that extend sales cycles by six to nine months for on-premises orchestration deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Process Automation Market |
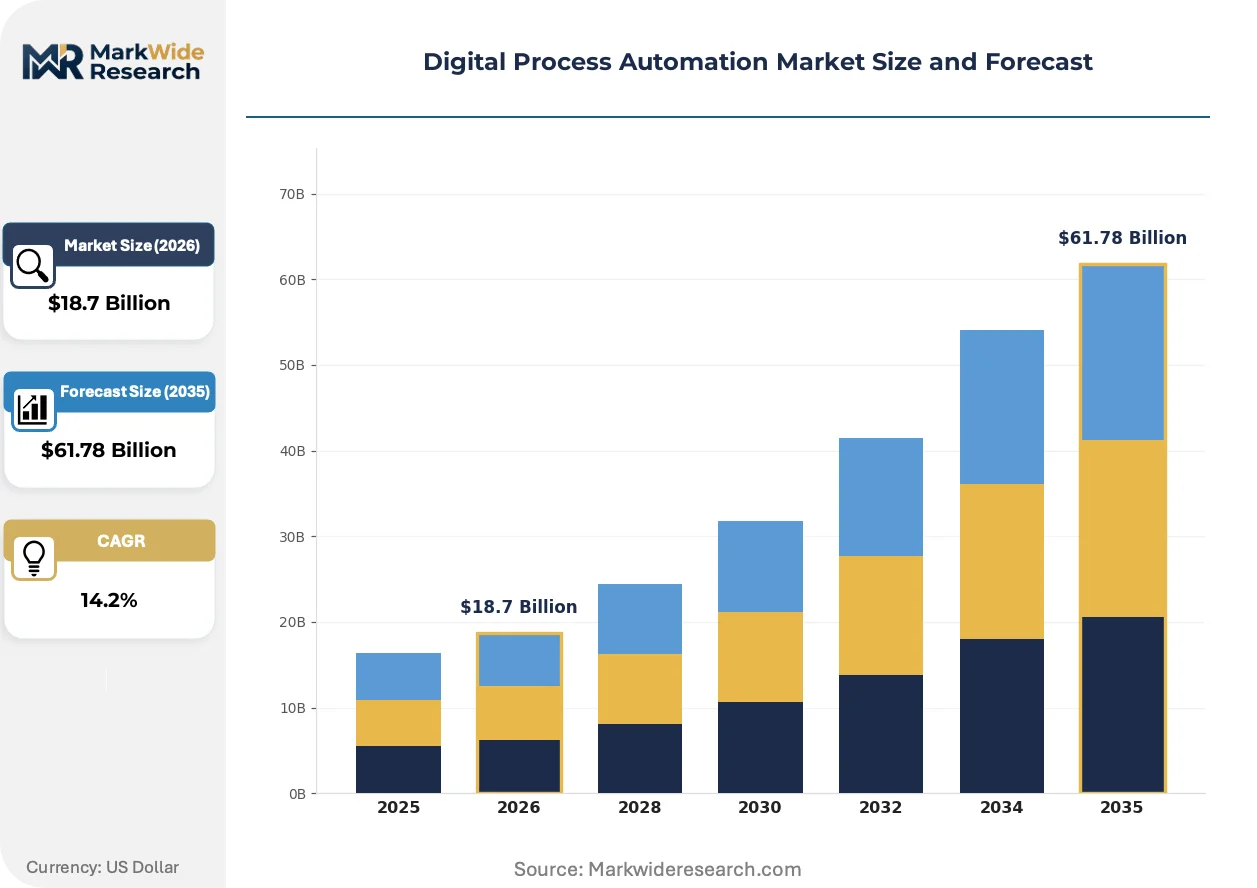
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Robotic Process Automation, Artificial Intelligence, Machine Learning, Business Process Management Deployment: Cloud-Based, On-Premises, Hybrid, Managed Services End User: IT Services, BFSI, Healthcare, Retail Application: Invoice Processing, Customer Service Automation, Workflow Automation, Compliance Management |
| Companies Covered | Pegasystems, SS&C Blue Prism, UiPath, IBM, Celonis, Automation Anywhere, Microsoft Power Automate, ServiceNow, Appian, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Process Automation Market Emerging Trajectories
Generative AI is compressing document extraction development cycles while regulators simultaneously tighten algorithmic oversight, creating a tension between automation velocity and compliance rigor.
Intelligent document processing engines are expanding into claims adjudication and contract analysis workflows. Property and casualty insurers in the US and Germany are deploying these systems at pilot scale, with full production rollouts accelerating through 2025. The technology is expanding into adjacent use cases faster than traditional robotic process automation, compressing the window for competitive differentiation.
REACH and RoHS compliance requirements in the European Union are forcing manufacturers to automate supply chain traceability documentation. Chemical and electronics producers must maintain batch-level material declarations across multi-tier supplier networks. German automotive OEMs are responding by mandating API-based data exchange standards that eliminate manual certificate collection.
Subscription pricing for automation platforms is displacing perpetual licensing in enterprise procurement. Chief information officers prioritize operational expenditure models that align costs with transaction volumes rather than fixed capacity. This shift is most pronounced in US healthcare and financial services verticals, where capital budget constraints favor elastic infrastructure commitments.
Digital Process Automation Market Segmentation
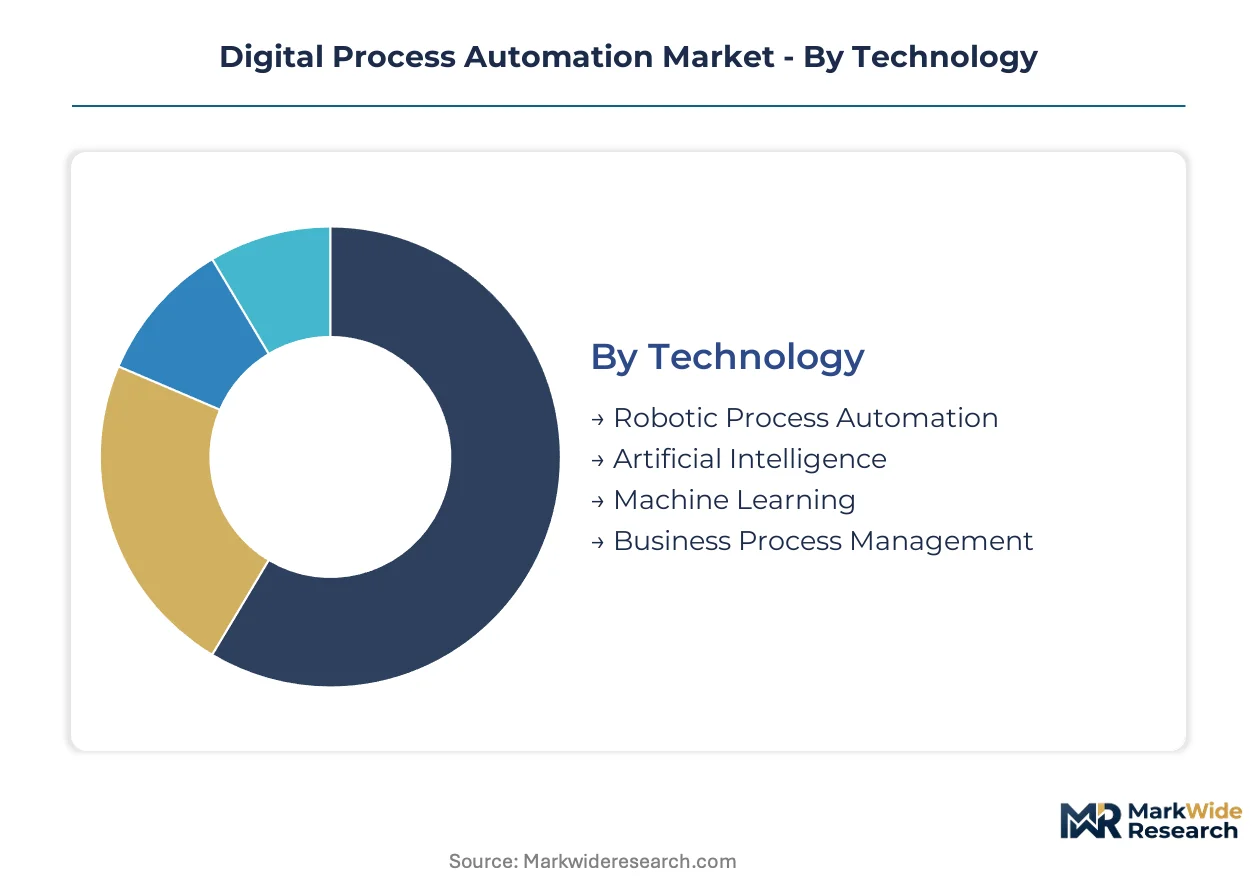
Segmentation in digital process automation determines which procurement pathways enterprises pursue based on regulatory exposure, infrastructure legacy, and transaction velocity requirements. Technology choices dictate certification burdens while deployment models shape total cost of ownership calculations across compliance-intensive verticals.
Technology:
Robotic Process Automation carries lighter certification overhead under GDPR Article 22 due to deterministic rule sets, whereas Artificial Intelligence and Machine Learning segments trigger EU AI Act high-risk system classifications requiring conformity assessments and audit trail architectures.
- Robotic Process Automation:Deterministic software bots execute repetitive, rules-based tasks through UI-layer interactions with legacy applications. German automotive suppliers and US healthcare payers deploy these for invoice reconciliation and claims data entry where predictability satisfies internal audit requirements.
- Artificial Intelligence:Cognitive engines process unstructured data via natural language processing and computer vision, embedding explainability layers to satisfy algorithmic accountability mandates. Credit decisioning and medical diagnosis workflows in France and Italy demand these capabilities despite implementation complexity.
- Machine Learning:Self-optimizing models identify pattern anomalies in operational telemetry, requiring continuous retraining pipelines and bias monitoring protocols under emerging regulatory frameworks.
- Business Process Management:Workflow orchestration engines coordinate human and automated tasks across enterprise boundaries, typically deployed with ISO 27001 attestation for financial services procurement.
Robotic Process Automation sits at the top of the volume ranking, with Artificial Intelligence climbing the fastest as explainability architectures mature.
Deployment:
Cost tier stratification separates elastic consumption models from fixed-capital commitments, with hybrid architectures commanding premium positioning due to dual-environment orchestration complexity.
- Cloud-Based:Multi-tenant SaaS platforms deliver API-native automation with subscription pricing aligned to transaction throughput. US healthcare systems and UK financial services firms prioritize these for rapid scaling without data center capital expenditure.
- On-Premises:Dedicated infrastructure installations satisfy FedRAMP and ISO 27001 requirements for classified or sensitive data processing. German banking regulators and US defense contractors mandate these deployments despite higher total cost of ownership.
- Hybrid:Split architectures route sensitive operations to private infrastructure while bursting transactional workloads to public cloud. Japanese manufacturers and Swiss pharmaceutical firms adopt these for supply chain automation spanning multiple jurisdictions.
- Managed Services:Third-party operated platforms transfer operational responsibility to specialized providers, common among mid-market enterprises lacking internal DevSecOps capabilities.
Cloud-Based deployments capture the broadest customer base, with Hybrid configurations expanding most quickly among regulated multinationals.
End User:
Application intensity varies sharply across verticals, with BFSI and Healthcare segments driving compliance-feature development while Retail and IT Services prioritize speed-to-deployment metrics.
- BFSI:Banking, insurance, and capital markets institutions deploy end-to-end automation for anti-money laundering screening, loan origination, and trade settlement. SEC disclosure rules and ECB stress testing requirements accelerate procurement of audit-ready platforms.
- Healthcare:Payers and providers automate claims adjudication, prior authorization, and clinical documentation while navigating HIPAA and FDA software-as-medical-device classifications. US health systems and German hospital networks lead implementation scale.
- IT Services:Managed service providers embed automation into client delivery models, white-labeling platforms for enterprise helpdesk and infrastructure monitoring.
- Retail:Omnichannel merchants deploy inventory reconciliation, returns processing, and customer service routing with lighter regulatory overhead than financial or medical applications.
BFSI generates the deepest feature requirements, with Healthcare gaining share fastest as reimbursement complexity intensifies.
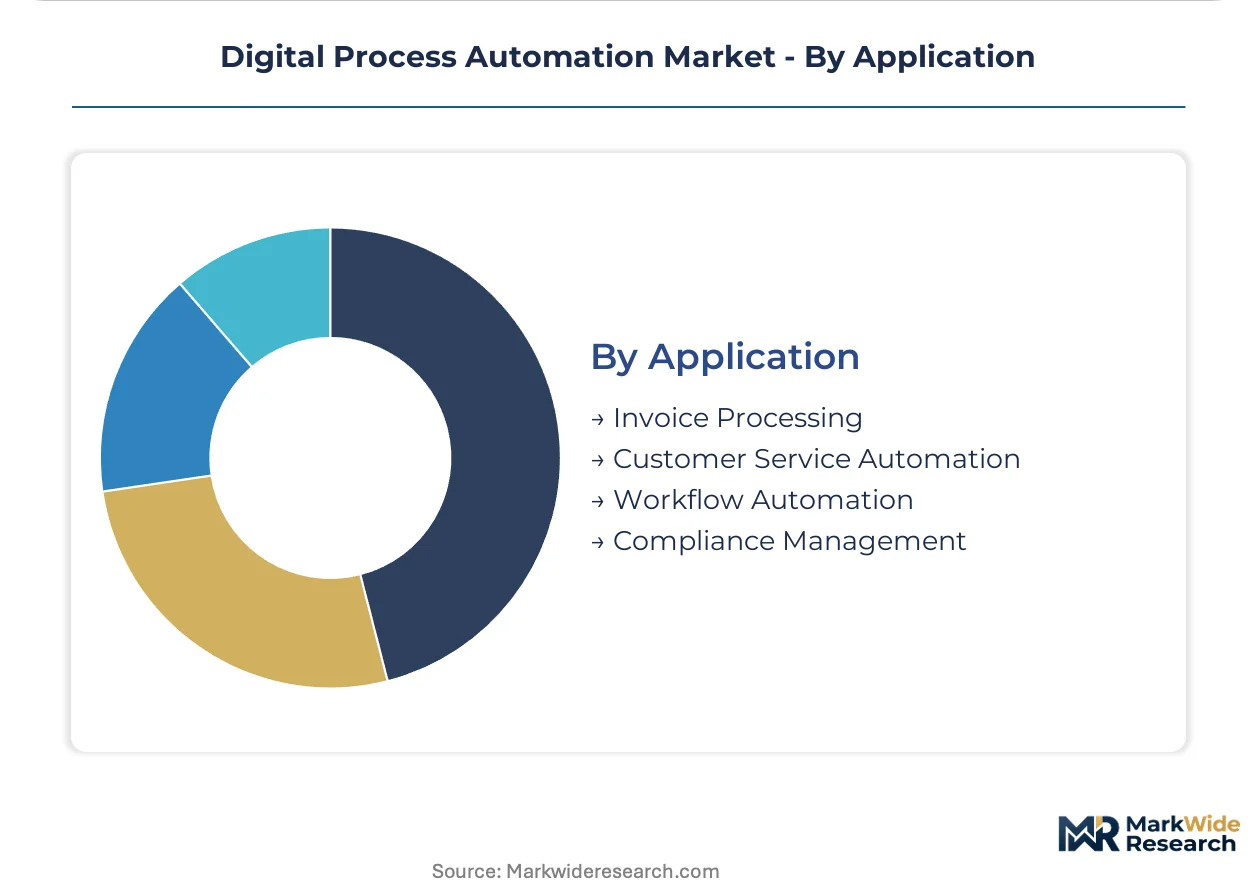
Application:
Maturity curves separate established use cases with proven ROI measurement from emerging workflows where success metrics remain contested.
- Invoice Processing:Intelligent document extraction engines automate accounts payable matching against purchase orders and receipts. Shared service centers in India and Poland deploy these at scale for European and North American parent companies.
- Compliance Management:Automated control monitoring, regulatory reporting, and audit documentation satisfy SEC, ECB, and FCA requirements. Publicly traded enterprises in the US and UK treat these as non-discretionary procurement.
- Customer Service Automation:Conversational AI and ticket routing systems reduce human agent headcount in telecommunications and utilities sectors.
- Workflow Automation:Cross-functional process orchestration connects HR onboarding, IT provisioning, and facilities management across enterprise boundaries.
Invoice Processing holds the largest installed base, with Compliance Management expanding most steeply as regulatory enforcement intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software engineering talent pools in Bangalore, Tel Aviv, and Berlin anchor platform development for digital process automation vendors serving enterprise clients worldwide.
United States
SEC cybersecurity disclosure rules and HIPAA compliance mandates drive procurement from healthcare payers and publicly traded enterprises. The FDA's software-as-medical-device guidance shapes clinical automation requirements. Greater Boston hosts specialized vendors developing audit-ready control monitoring systems for financial services clients.
Germany
Industrial manufacturers in automotive and chemicals verticals integrate process mining with SAP ERP infrastructure at scale. The EU AI Act and GDPR Article 22 impose algorithmic accountability requirements on automated credit and insurance decisioning. Bavaria's Munich-Stuttgart corridor concentrates vendor development centers for manufacturing-focused automation platforms.
India
PLI scheme subsidies for electronics and automotive assembly are accelerating modernization programs across Tamil Nadu and Gujarat manufacturing clusters. RBI guidelines on digital lending automation shape fintech procurement patterns. Bangalore's enterprise software ecosystem hosts development centers serving European and North American parent companies with shared service automation.
Japan
METI productivity mandates and aging workforce demographics drive municipal administration and healthcare claims processing automation. The country's national pharmaceutical regulator imposes documentation standards on clinical trial workflow platforms. Osaka-Kansai manufacturing belt enterprises deploy supply chain exception handling systems at pilot scale.
United Kingdom
FCA operational resilience requirements and FRC audit standards accelerate compliance management platform adoption among banking and insurance institutions. The Information Commissioner's Office enforces GDPR automated decision safeguards. London's financial services cluster generates concentrated demand for anti-money laundering screening automation.
Digital Process Automation Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Enterprise software incumbents leverage hybrid cloud footprints to sustain premium positioning in regulated industries requiring on-premises orchestration. Pure-play automation vendors anchor competitive positions through partner channel control and process mining telemetry specialization. Strategic moves concentrate on M&A for AI/ML capability expansion and strategic partnerships for multi-cloud deployment architectures.
Among platform specialists, UiPath and Celonis occupy distinct archetype positions within the competitive structure. UiPath exemplifies the volume-driven robotic process automation tier with extensive mid-market manufacturing penetration. Celonis represents the process intelligence vector, mapping operational bottlenecks before automation deployment to reduce implementation failure rates. IBM anchors the diversified technology conglomerate tier, leveraging hybrid cloud infrastructure for regulated industry procurement cycles requiring FedRAMP and ISO 27001 attestations.
| Leading Market Players |
|---|
| Pegasystems |
| SS&C Blue Prism |
| UiPath |
| IBM |
| Celonis |
| Automation Anywhere |
| Microsoft Power Automate |
| ServiceNow |
| Appian |
| Others |
Supply Flow & Price Mechanics
Cloud infrastructure spot pricing indices cascade through digital process automation supply chains, compressing margins for SaaS-native vendors while amplifying pricing power for hybrid-cloud orchestrators serving regulated German banking and US healthcare clients.
Pricing Analysis
The bundled-vs-unbundled service split separates subscription-based SaaS tiers from professional services-heavy on-premises deployments. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade—FedRAMP and ISO 27001 attestations command 40-60% premiums over uncertified alternatives. Pricing pressure stems from hyperscaler infrastructure commoditization, which erodes differentiation for cloud-native entrants. Mid-market manufacturing buyers in India and Poland exhibit highest price sensitivity, while US BFSI procurement teams prioritize audit-ready compliance features over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for SAP and Oracle integration services, while partner networks serve mid-market distributed procurement. Engineering talent concentrates in India, Germany, and the United States, with Bangalore and Berlin anchoring platform development centers. Raw material dependencies center on GPU compute capacity, API gateway infrastructure, and specialized process mining telemetry hardware. Single-source vulnerability runs through hyperscaler cloud concentration, where AWS, Azure, or GCP dependency creates failover risk for enterprises lacking multi-cloud architectures. Distribution runs through systems integrators and certified implementation partners with vertical-specific compliance expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act enforcement milestones compound regulatory demand across credit, healthcare, and public administration automation procurement, creating non-discretionary budget allocation for audit-ready platforms.
For Market Incumbents: To counter generative AI-native challengers compressing document extraction development cycles, incumbents must deepen explainability architecture R&D and secure FedRAMP Moderate certifications for federal healthcare automation contracts. Channel control through exclusive systems integrator partnerships in Germany's automotive corridor defends installed base erosion.
For New Entrants and Emerging Players: Cloud-native API marketplaces offer the lowest-friction entry vector for mid-market Indian manufacturing clusters under PLI scheme modernization programs. White-label intelligent document processing for US property and casualty insurance claims adjudication represents the most penetrable white-space target, with pilot-to-production conversion accelerating through 2025.
For Investors and Strategic Acquirers: Asymmetric upside sits with process mining specialists possessing operational telemetry translation capabilities for industrial manufacturing clients. Long-term viability hinges on multi-cloud orchestration architecture adoption rates across regulated European multinationals. The signal to watch is EU AI Act conformity assessment backlog clearing speed as an inflection indicator for platform vendor sales cycle compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firm | Process mining telemetry capabilities reduce implementation failure rates for German automotive ERP integrations. |
| Strategic Partnership | Multi-cloud deployment architectures address hyperscaler concentration risk for Japanese pharmaceutical supply chains. |
| Product Launch | Explainability-layer embedding satisfies GDPR Article 22 and EU AI Act algorithmic accountability mandates for French credit decisioning. |
| Platform Integration | SAP S/4HANA native connectors accelerate procurement cycles for Bavarian industrial manufacturers. |
| Geographic Expansion | Tamil Nadu and Gujarat manufacturing clusters under India's PLI scheme offer subsidy-backed modernization demand. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with CTOs, IT procurement officers, platform engineers, and channel partners against secondary validation through SEC filings, hyperscaler capex disclosures, and EU regulatory enforcement notices. Bottom-up deployment volume estimates triangulated with top-down enterprise software spending analysis across the analysis window.
Historical reference periods anchored the projection horizon to pre-pandemic automation adoption baselines and post-2022 regulatory acceleration phases. The analytical framework modeled deployment mode, organization size, vertical regulatory exposure, integration complexity, and regional adoption pattern dimensions. CAGRs derived from segment-level elasticity coefficients applied to compliance-driven procurement intensity curves, with EU AI Act enforcement timelines and SEC cybersecurity disclosure rules as primary demand shapers.
The model assumes a particular technology adoption path; alternative pathways for generative AI-native automation architectures would alter the outlook. Forecasts reflect base-case assumptions regarding regulatory enforcement consistency and hyperscaler infrastructure pricing stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
CNC Controller Market
Automation
North America Data Center Automation Market
Automation
Automation-As-A-Service Market
Automation
Global Cloud Automation Market
Automation
Global Warehouse Barcode System Market
Automation
Window Automation Market
Automation
Global Database Automation Systems Market
Automation
Self Bag Drop Machine Market
Automation
Automation Light Grids Market
Automation
Laboratory Benchtop Automation Market
Automation
Automation Testing Market
Automation
Workflow Automation Market
Automation
Global Sales Force Automation (SFA) Market
Automation
Global Zig-Bee Automation Market
Automation
Lab Automation Market
Automation
Global Smart Vending Machines Market