
 Global Automated Liquid Handlers Market | 2026-2036
Global Automated Liquid Handlers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automated Liquid Handlers Market Intelligence
The divergence between high-throughput modular systems for complex genomic workflows and simpler benchtop units for routine tasks is repositioning the competitive landscape. Tecan Group specializes in highly customized, large-scale automation platforms for pharmaceutical clients. In contrast, Agilent Technologies leverages its strength in analytical instruments to offer integrated solutions. Hamilton Company sustains its market position through a focus on precision engineering and robotic pipetting technology.
Automated liquid handlers are robotic systems designed for precise and repeatable dispensing of liquids in laboratory settings. These devices utilize robotic arms and advanced pipetting technology to aspirate and dispense volumes ranging from nanoliters to milliliters. High-throughput systems represent the fastest-growing product category, driven by large-scale screening requirements. Demand from genomics and clinical diagnostics applications commands the highest value, while environmental testing remains a smaller, niche segment.
Regulatory frameworks, including the U.S. FDA's guidelines for good laboratory practice (GLP) and the EMA's requirements for drug development, mandate stringent process control and data integrity. Conformance to ISO 9001 and ISO 13485 standards is critical for market access, especially for devices used in clinical diagnostics. Future system design will need to balance the push for greater throughput and modularity with the need for simplified user interfaces and enhanced data security.
Market Dynamics
The primary force shaping the market is the divergence between large, modular systems for complex genomics workflows and simpler benchtop units for routine assays. This bifurcation creates distinct development paths and competitive pressures across the vendor landscape.
Growth Catalysts
- Pharmaceutical R&D Investment:Demand from pharmaceutical companies for high-throughput screening in drug discovery and development is a primary catalyst for large-scale system adoption.
- Microfluidics Technology:Integration of microfluidics enables greater precision and miniaturization of assays, reducing reagent costs and supporting advanced applications like genomics.
- Data Integrity Mandates:Regulatory frameworks from the FDA and EMA requiring strict process control and data traceability under GLP guidelines push labs toward automation.
Market Restraints
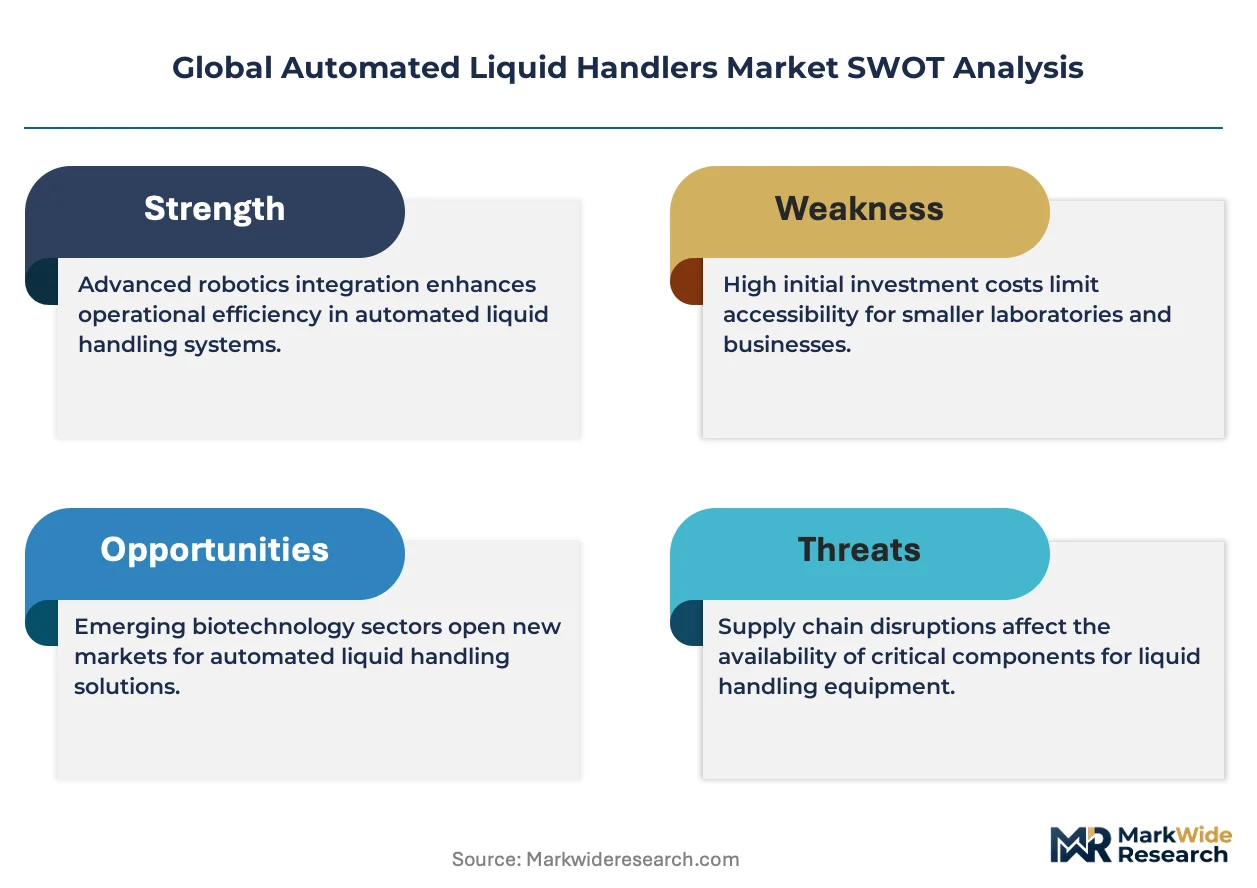
- High Capital Expenditure:The significant upfront investment required for large, fully automated platforms is a major barrier for smaller academic labs and startups.
- System Interoperability:Lack of standardization between instruments, software, and LIMS from different vendors creates complex and costly integration challenges for users.
- Specialized Component Dependency:Reliance on a limited number of suppliers for critical parts like high-precision robotic arms and proprietary tips creates supply chain vulnerability.
Strategic Opportunities
- Expansion into Cell Therapy:Developing automated, closed-system liquid handlers for sterile cell therapy manufacturing addresses a critical bottleneck in this emerging medical field.
- AI-Powered Protocol Optimization:Integrating machine learning algorithms allows systems to dynamically adjust protocols based on real-time sensor data, improving reproducibility and reducing errors.
- Clinical Diagnostics in Emerging Markets:Targeting mid-sized hospitals and diagnostic labs in rapidly developing regions of Asia-Pacific presents a significant growth vector for benchtop systems.
Industry Challenges
- Skilled Operator Shortage:A deficit of technicians and scientists trained in programming, validating, and maintaining complex robotic systems limits effective deployment and utilization.
- Data Standardization Hurdles:The absence of universal data formats across platforms hinders the aggregation and analysis of results from different systems in collaborative research.
- Legacy System Integration:Integrating modern liquid handlers with older Laboratory Information Management Systems often requires custom middleware, increasing project complexity and cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automated Liquid Handlers Market |
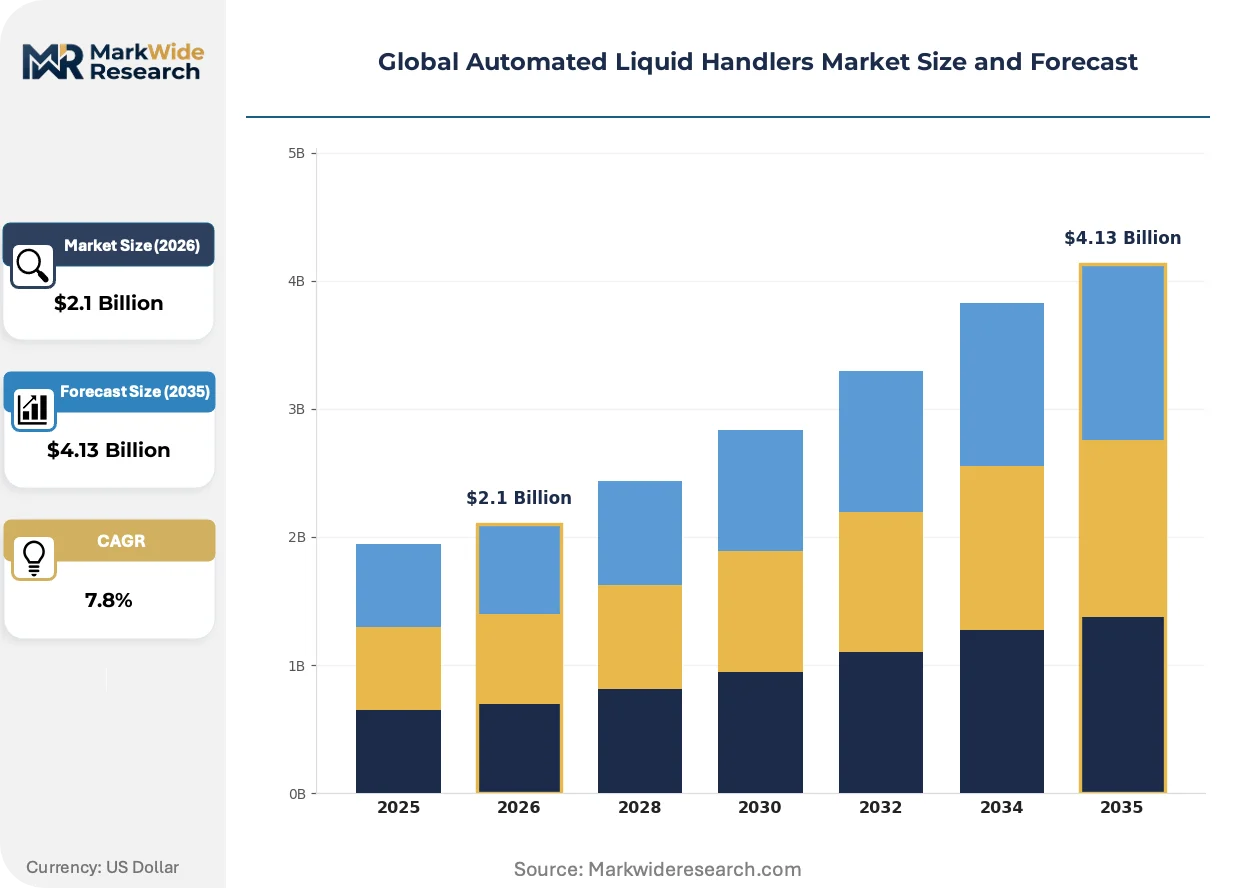
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.13 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benchtop Systems, Modular Systems, High-Throughput Systems, Disposable Tip Systems, Microplate Handlers Technology: Robotic Arms, Pipetting Technology, Liquid Dispensing, Microfluidics, Embedded Sensors Application: Drug Discovery, Genomics, Proteomics, Clinical Diagnostics, Environmental Testing End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutes, Clinical Laboratories, Food & Beverage Testing Labs |
| Companies Covered | Hamilton Company, Tecan Group, Agilent Technologies, Gilson, PerkinElmer, Beckman Coulter Lifesciences, Thermo Fisher Scientific, SPT Labtech, Eppendorf, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automated Liquid Handlers Market Strategic Shifts & Innovations
Miniaturization and intelligent data management are defining the next generation of automated liquid handling. The market is evolving from simple task automation toward integrated, data-rich workflow solutions that enhance reproducibility and accelerate scientific discovery.
Acoustic droplet ejection technology uses sound waves for non-contact liquid transfers in the nanoliter range. Genomics and proteomics research laboratories are rapidly adopting this method for ultra-high-throughput screening applications. This technology's precision is electrifying assay development by enabling experiments with previously unattainable low volumes and high densities.
The European Union's In Vitro Diagnostic Regulation (IVDR) imposes more stringent requirements on manufacturers. It mandates enhanced clinical evidence and post-market surveillance for all devices used in diagnostic workflows. Clinical diagnostic laboratories in the EU are therefore prioritizing liquid handlers from vendors who can provide comprehensive IVDR compliance documentation.
A shift from purchasing standalone instruments to procuring end-to-end, application-specific solutions is underway. This model displaces traditional capital equipment sales with bundled offerings of instruments, validated reagents, and software. This demand pattern is most visible within biopharmaceutical QC and clinical genomics labs across North America.
Global Automated Liquid Handlers Market Segmentation
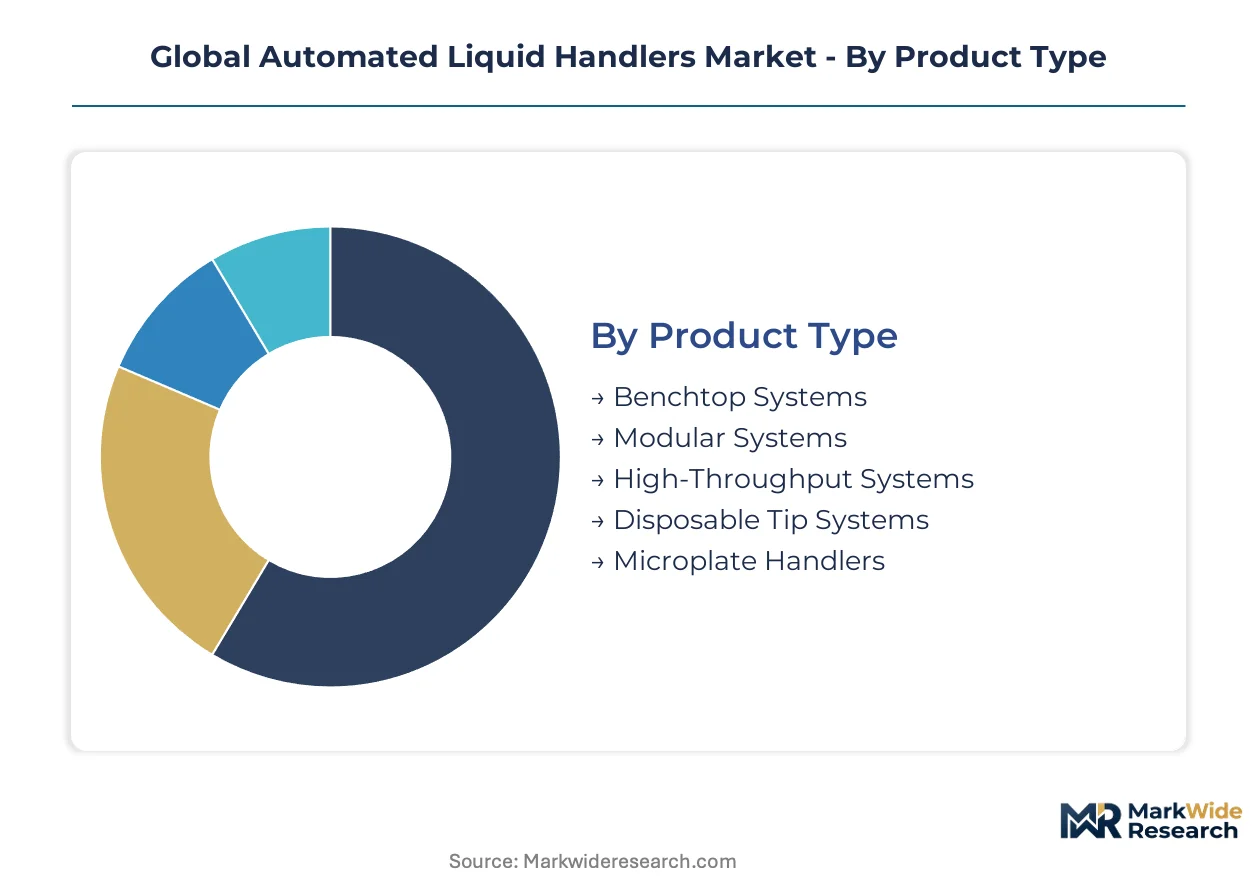
Understanding the market's segmentation by product type, technology, application, and end-user is critical for identifying specific growth pockets and competitive differentiators. This granular analysis reveals how diverse laboratory requirements shape demand for automated liquid handling solutions.
Product Type:
Laboratories frequently assess their existing liquid handling infrastructure, driving decisions on upgrades or new system acquisitions based on evolving throughput demands and assay complexity.
- High-Throughput Systems:These advanced robotic platforms manage large volumes of samples and reagents simultaneously, significantly accelerating screening processes. Pharmaceutical companies globally drive demand for high-throughput systems in drug discovery and lead optimization, requiring rapid processing of extensive compound libraries.
- Modular Systems:Modular systems offer flexible configurations, allowing laboratories to customize and expand their automation capabilities over time. Biotechnology firms in the United States increasingly adopt modular systems to adapt to dynamic research workflows, integrating various modules for specific genomic and proteomic applications.
- Benchtop Systems:These compact units provide automated liquid handling for routine tasks, offering cost-effective solutions for smaller academic and clinical labs.
- Disposable Tip Systems:These systems utilize single-use tips to prevent cross-contamination, essential for sensitive clinical diagnostic assays and sterile workflows.
- Microplate Handlers:Specialized devices automate the movement and manipulation of microplates, optimizing high-density assay formats and increasing experimental efficiency.
Benchtop Systems sits at the top of the volume ranking, with High-Throughput Systems climbing the fastest.
Technology:
The underlying technological sophistication directly influences the performance capabilities and cost structures of automated liquid handlers, enabling various levels of precision and automation.
- Microfluidics:This technology enables precise liquid handling at sub-microliter volumes, integrating multiple laboratory functions onto a single chip. Integration of microfluidics into automated systems reduces reagent consumption and enhances assay miniaturization for genomics research in Germany.
- Robotic Arms:Robotic arms provide the mechanical dexterity for aspirating, dispensing, and transferring liquids across various labware, forming the core of automated systems. Hamilton Company's market position relies on precision-engineered robotic arms, ensuring high accuracy and repeatability in complex workflows.
- Pipetting Technology:Advanced pipetting mechanisms ensure accurate and reproducible liquid transfers, critical for sensitive experimental results and regulatory compliance.
- Liquid Dispensing:Various dispensing methods, including acoustic droplet ejection, facilitate non-contact and ultra-low volume liquid delivery for specialized assays.
- Embedded Sensors:Integrated sensors monitor liquid levels, tip presence, and environmental conditions, enhancing system reliability and data integrity during operation.
Core robotic and pipetting technologies form the foundational layer, while microfluidics and embedded sensors represent advanced integration points for next-generation systems.
Application:
Specific laboratory applications dictate the required throughput, precision, and regulatory compliance for automated liquid handling systems.
- Drug Discovery:This application involves high-throughput screening of compound libraries to identify potential drug candidates, demanding rapid and precise liquid transfers. Pharmaceutical R&D investment in the United States drives the adoption of large-scale automated systems for lead identification and optimization.
- Clinical Diagnostics:Automated liquid handlers perform sample preparation and assay execution for patient diagnostics, requiring high accuracy and regulatory compliance. European clinical laboratories prioritize systems with comprehensive IVDR compliance documentation for diagnostic workflows.
- Genomics:Automated systems facilitate DNA/RNA extraction, library preparation, and sequencing setup, crucial for large-scale genomic studies and molecular diagnostics.
- Proteomics:Liquid handlers assist in protein purification, digestion, and mass spectrometry sample preparation, supporting protein analysis and biomarker discovery.
- Environmental Testing:This niche segment utilizes automated systems for preparing samples for contaminant analysis in water, soil, and air quality assessments.
Clinical Diagnostics and Drug Discovery command the highest value in this segment, while Environmental Testing remains a smaller niche application.
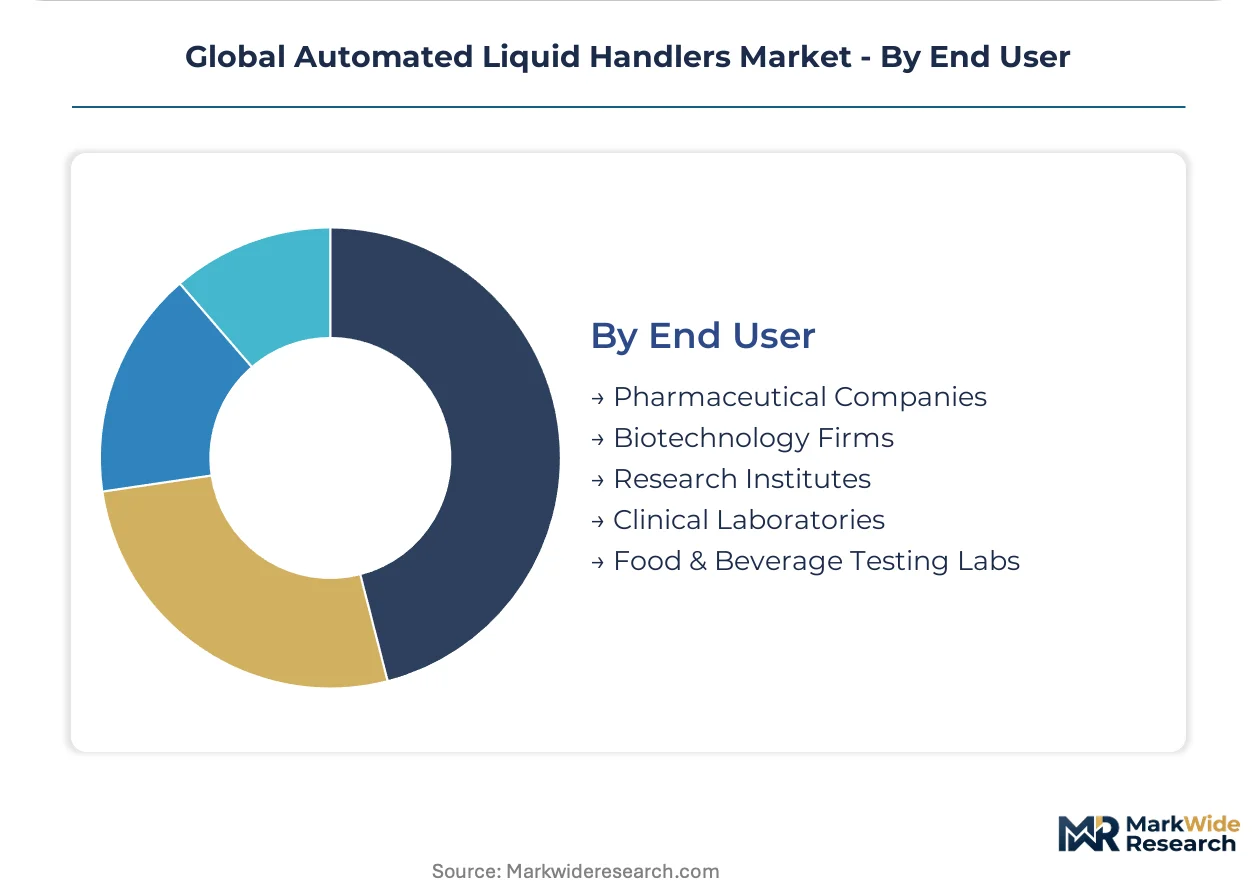
End User:
The operational scale and specific research focus of end-user institutions profoundly influence their investment in and utilization of automated liquid handling solutions.
- Pharmaceutical Companies:These entities leverage automated liquid handlers for high-throughput screening, drug formulation, and quality control processes. Demand from pharmaceutical companies for high-throughput screening in drug discovery is a primary catalyst across global markets.
- Clinical Laboratories:Clinical labs deploy automated systems for diagnostic testing, sample processing, and assay setup, requiring reliability and regulatory adherence. Mid-sized hospitals and diagnostic labs in rapidly developing regions of Asia-Pacific represent a significant growth vector for benchtop systems.
- Biotechnology Firms:Biotechnology firms utilize automated platforms for cell culture, genomics, and protein engineering applications, supporting innovative research and product development.
- Research Institutes:Academic and government research institutes employ liquid handlers for diverse scientific studies, from basic biology to applied sciences, often with grant-based funding.
- Food & Beverage Testing Labs:These labs use automated systems for quality control, pathogen detection, and nutritional analysis, ensuring product safety and regulatory compliance.
Pharmaceutical Companies and Clinical Laboratories represent the largest procurement entities, shaping product development and market trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled scientific workforces anchoring key research hubs drive demand for automated liquid handling solutions globally. These advanced systems support complex workflows in pharmaceutical R&D and clinical diagnostics. Regulatory mandates for data integrity further accelerate their adoption across various national markets.
United States
Pharmaceutical R&D investment and biotechnology innovation drive significant demand for high-throughput systems in the United States. The U.S. FDA's guidelines for good laboratory practice (GLP) mandate stringent process control, pushing labs towards automation. Boston's biotech cluster, along with research institutions in California, actively deploys these sophisticated platforms for drug discovery.
Germany
Precision engineering and a strong focus on genomics research propel the German market for automated liquid handlers. European Medicines Agency (EMA) requirements for drug development emphasize data integrity, influencing system procurement. Munich and Heidelberg's life science parks are centers for advanced microfluidics integration in automated assay development.
Japan
Aging demographics and a robust pharmaceutical industry fuel demand for automated clinical diagnostics and drug discovery applications in Japan. Japan's PMDA regulations for medical devices and pharmaceuticals encourage the use of highly reliable automated systems. Tokyo's research institutions and pharmaceutical companies are at the forefront of adopting advanced robotic pipetting technologies.
China
Expanding healthcare infrastructure and increasing investment in biopharmaceutical R&D stimulate the market for automated liquid handlers in China. The NMPA's stringent approval processes for medical devices and diagnostics promote quality-controlled automation. Shanghai's burgeoning biotech sector and Beijing's research institutes are rapidly integrating high-throughput screening platforms.
Global Automated Liquid Handlers Market Key Industry Players
Capital-heavy producers compete with asset-light designers for market share in automated liquid handling. The market exhibits a tiered structure, with established global players alongside specialized niche providers. Strategic archetypes include integrated solution providers, precision engineering specialists, and high-throughput automation experts. Companies primarily engage in portfolio diversification and strategic partnerships to expand their market reach.
Integrated solution providers like Agilent Technologies leverage their analytical instrument expertise to offer comprehensive laboratory platforms that span diverse applications, including genomics and clinical diagnostics. Hamilton Company sustains its market position as a precision engineering specialist, focusing on highly accurate robotic pipetting technology crucial for complex and sensitive workflows. Tecan Group exemplifies a high-throughput automation expert, specializing in highly customized, large-scale systems for pharmaceutical clients globally, addressing their demanding screening and drug discovery requirements.
| Leading Market Players |
|---|
| Hamilton Company |
| Tecan Group |
| Agilent Technologies |
| Gilson |
| PerkinElmer |
| Beckman Coulter Lifesciences |
| Thermo Fisher Scientific |
| SPT Labtech |
| Eppendorf |
| Others |
Cost & Logistics Intelligence
Pharmaceutical companies and clinical laboratories increasingly seek bundled solutions, shifting procurement from standalone instruments to comprehensive, application-specific offerings. This trend influences pricing towards value-based models encompassing instruments, reagents, and software.
Pricing Analysis
The market distinguishes between bundled, application-specific solutions and unbundled component sales. Value-based pricing dominates for integrated offerings, encompassing instruments, reagents, and software. Price differentiation stems from customization levels for complex systems and comprehensive regulatory compliance like IVDR documentation. Pricing softness affects benchtop systems due to increased competition, while large pharmaceutical companies show less price sensitivity than smaller academic labs.
Supply Chain Analysis
Reverse logistics for automated liquid handlers primarily involves component returns for repair and system refurbishment for upgrades. Supply concentration for critical components draws from Germany for precision engineering and the United States for advanced robotics. Key dependencies include high-precision robotic arms and proprietary pipetting tips. Single-source vulnerability for these specialized parts poses a structural risk. Distribution runs through direct sales channels for large systems and through specialized regional distributors for benchtop units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automated liquid handlers market presents a clear margin-expansion story. This growth stems from the ongoing shift towards integrated, data-rich workflow solutions demanding premium pricing and specialized services.
For Market Incumbents: Deepen existing client relationships by offering advanced data integration and AI-powered protocol optimization. This defends against emerging niche players leveraging specialized microfluidics. Invest in R&D for AI/ML capabilities to enhance system reproducibility and user experience, addressing the skilled operator shortage. Prioritize vertical integration into software platforms to mitigate data standardization hurdles.
For New Entrants and Emerging Players: Launch via application-specific bundles targeting underserved segments like cell therapy manufacturing. This addresses the critical bottleneck in sterile processing. Focus on mid-sized hospitals and diagnostic labs in rapidly developing regions of Asia-Pacific, a highly penetrable geography for benchtop systems. A go-to-market angle emphasizing cost-effectiveness and simplified user interfaces will resonate.
For Investors and Strategic Acquirers: Integrated life science platform providers are the most active acquirers in this space, seeking to consolidate specialized technologies. The market demonstrates strong long-term viability over the next 5-10 years, driven by R&D investment. Acquisition targets should be niche technology developers specializing in microfluidics or AI-driven automation. Investors should watch for increased venture capital funding into robotics and AI startups within the life sciences as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidates diverse analytical instruments into seamless workflows for pharmaceutical clients. |
| Strategic Partnership | Partnerships with LIMS providers address system interoperability challenges for clinical laboratories. |
| Product Launch | Introducing AI-powered protocol optimization enhances reproducibility for genomics research. |
| Geographic Expansion | Targeting mid-sized hospitals in Asia-Pacific expands market reach for benchtop systems. |
| Acquisition of Specialist Firm | Acquiring microfluidics developers strengthens precision capabilities for high-throughput screening. |
Research Approach
Bottom-up pharmaceutical R&D and clinical diagnostics modeling reconciled against top-down automated liquid handler manufacturer tracking forms the analytical core. This approach integrates primary interviews with R&D directors, lab managers, procurement officers, and regulatory affairs specialists. Secondary validation draws from FDA filings, EMA submissions, patent databases, and company annual reports. This ensures robust triangulation of market data.
An input-output matrix correlates technology adoption rates with end-user demand across the analysis window. The model segments across product type, technology, application, end-user, and regional regulatory compliance. Compound annual growth rates derive from historical trends and projected growth drivers. Pharmaceutical R&D investment and new IVD regulation impact serve as key forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under geopolitical instability or unforeseen technological breakthroughs. These forecasts reflect documented assumptions regarding market dynamics. Practitioners should monitor evolving regulatory frameworks and critical component supply chain disruptions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Global Form Automation Software Market
Automation
Voice Picking Solutions Market
Automation
Europe Laboratory Automation Market
Automation
Global Automated Sample Storage Systems Market
Automation
Middle East and Africa Workforce Management Market
Automation
Automation Testing Market
Automation
Global Cloud Automation Market
Automation
Global Remote Monitoring and Control Market
Automation
Computer Numerical Control Market
Automation
Italy Process Orchestration Market
Automation
RFID Kanban Systems Market
Automation
CNC Controller Market
Automation
Automation Light Grids Market
Automation
Asia-Pacific Micro Fulfillment Market
Automation
Global Database Automation Systems Market
Automation
Smart Home Automation Market