
 United States Laboratory Automation Market | 2026-2036
United States Laboratory Automation Market Size, Share, and Industry Trends Forecast 2026-2036
United States Laboratory Automation Market Intelligence
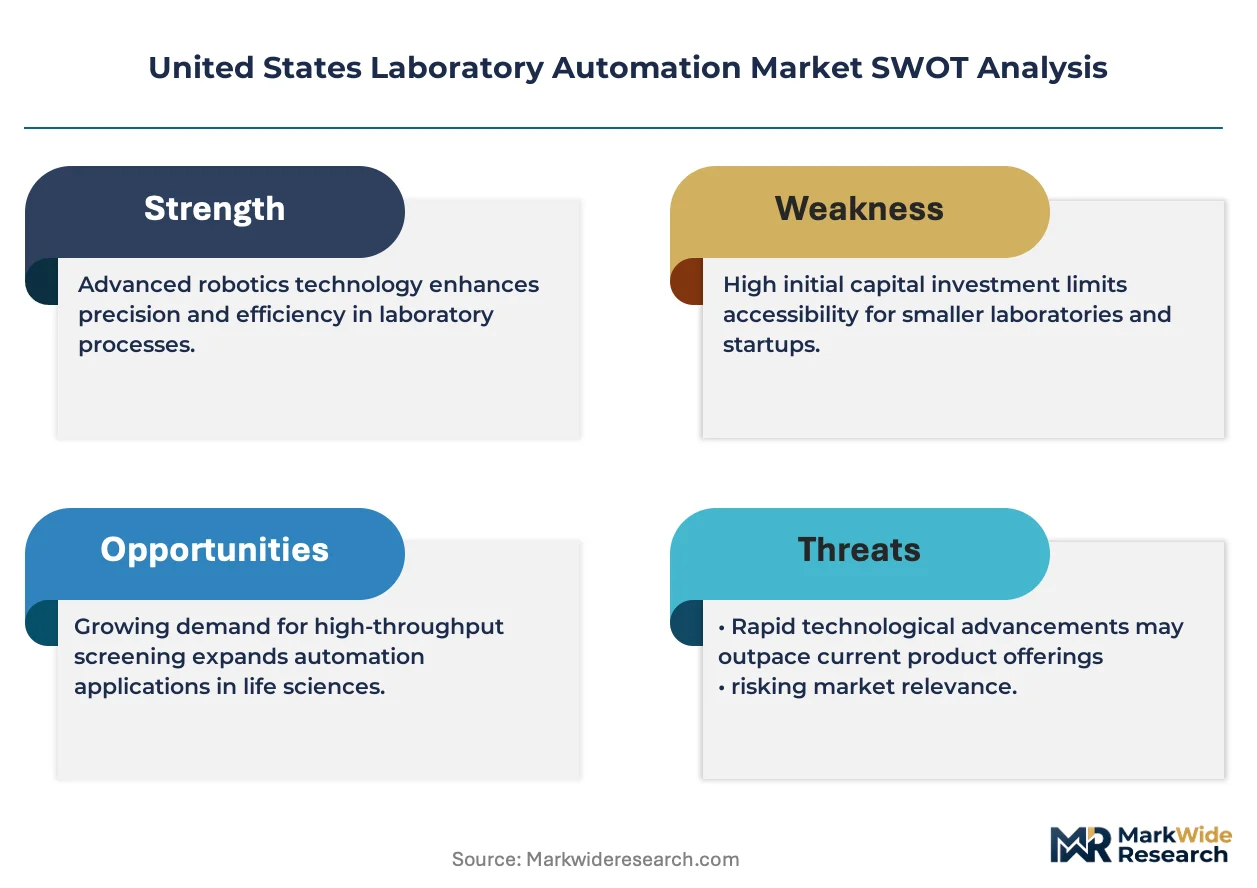
The capital-intensity divergence between integrated platform vendors and point-solution specialists is unwinding competitive dynamics across the sector. Thermo Fisher Scientific leverages its end-to-end consumables-to-software portfolio to sustain pricing power in high-throughput genomics workflows. Danaher Corporation anchors its position through Beckman Coulter's installed base in clinical diagnostics, while QIAGEN competes on modular sample-prep automation that integrates with third-party sequencers. Hudson Robotics differentiates through compact benchtop systems designed for academic budgets and limited floor space.
United States laboratory automation encompasses integrated hardware and software systems that execute repetitive analytical protocols with precision measured in microliter volumes and sub-millimeter positional accuracy, serving primarily to accelerate throughput and reduce human error in regulated environments. Liquid handling systems dominate current revenue as pharmaceutical companies retrofit legacy workflows, while artificial intelligence and machine learning represent the fastest-expanding technology layer as vendors embed predictive maintenance and autonomous protocol optimization into platform software. Robotics and automation software capture concentrated margin pools where customization complexity and regulatory validation requirements create stickier customer relationships.
FDA oversight of in vitro diagnostics under CLIA and the 21st Century Cures Act shapes product development timelines and software validation burdens for vendors targeting clinical laboratories. EPA guidelines on hazardous waste handling from automated processes and OSHA laboratory safety standards further constrain system design choices, particularly for high-throughput screening facilities. Stakeholders must monitor how CMS reimbursement decisions for algorithm-augmented diagnostics reshape the business case for AI-integrated automation platforms.
Market Dynamics
Pharmaceutical sponsors are compressing discovery timelines through automated liquid handling retrofits, forcing vendors to embed AI-driven protocol optimization into legacy hardware architectures rather than pursue rip-and-replace strategies.
Growth Catalysts
- 21st Century Cures Act:FDA's streamlined premarket review for algorithm-augmented diagnostics accelerates validation timelines for AI-integrated automation platforms in clinical laboratories.
- Contract research organizations:Boston-Cambridge corridor density creates concentrated demand pull for high-throughput screening systems serving outsourced drug development.
- Machine learning:Predictive maintenance algorithms reduce unplanned downtime in 24/7 production environments, improving asset utilization rates for capital-intensive installations.
Market Restraints
- Consumables lock-in economics:Proprietary reagent cartridges and tip formats from integrated platform vendors create switching costs that deter mid-tier laboratory migration.
- Validation burden:CLIA and FDA software documentation requirements extend deployment cycles for clinical diagnostic automation by 8-14 months.
- Specialized technician scarcity:Cross-functional expertise spanning robotics, bioinformatics, and regulatory compliance commands wage premiums exceeding 40% above general laboratory staffing.
Strategic Opportunities
- Academic price-tier penetration:Compact benchtop systems targeting space-constrained university laboratories currently served by manual workflows represent underpenetrated volume.
- Modular architecture:Sample-prep automation that integrates with third-party sequencers enables vendors to capture value without competing against entrenched sequencing platform ecosystems.
- OSHA laboratory safety standards:Automated hazardous waste handling compliance creates specification advantages for vendors certifying closed-system designs in high-throughput screening facilities.
Industry Challenges
- Legacy LIMS integration:Protocol translation between proprietary automation software and existing laboratory information management systems consumes 30-50% of deployment engineering hours.
- Cross-training requirements:Biologists transitioning to automated workflows require simultaneous proficiency in liquid handling physics, error-state troubleshooting, and experimental design optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Laboratory Automation Market |
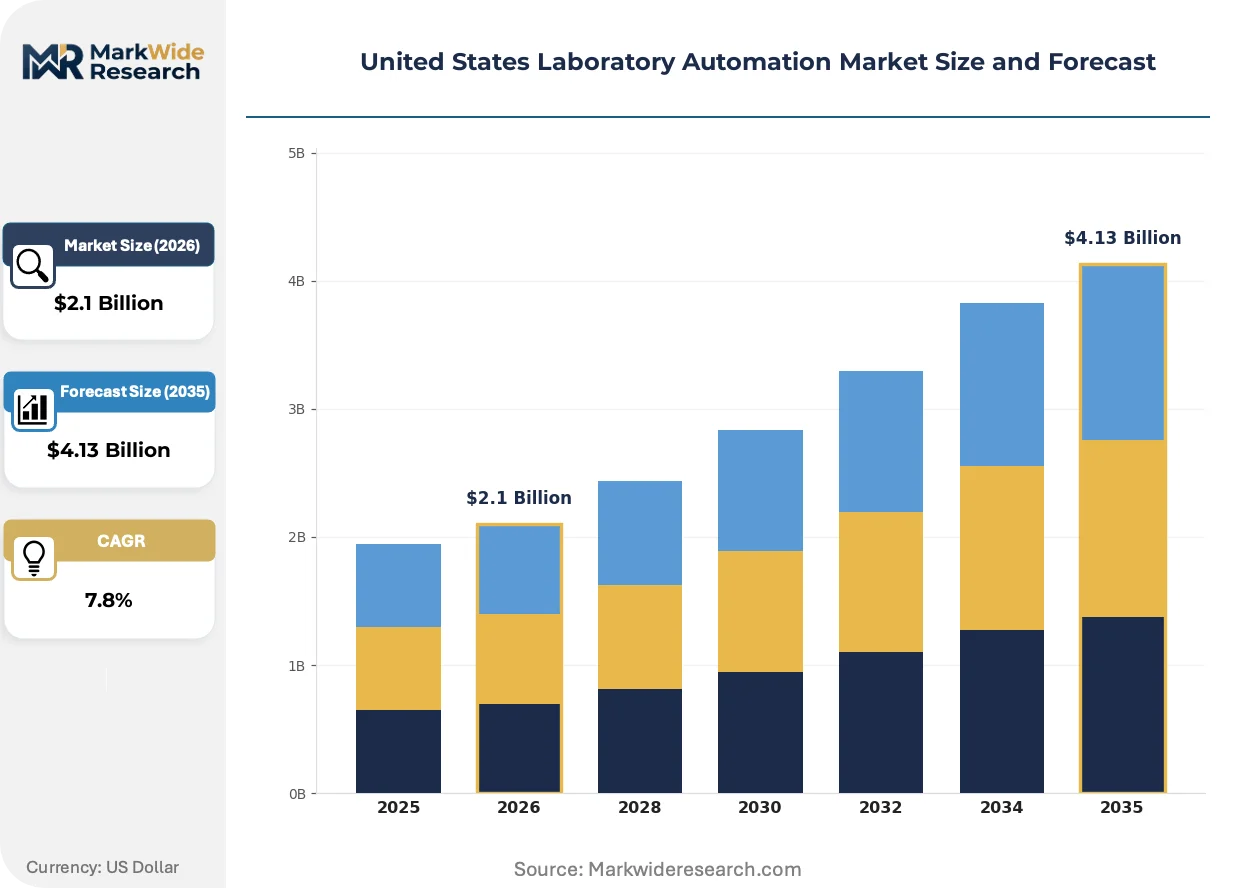
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.13 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Handling Systems, Robotics, Sample Storage Systems, Automation Software End User: Pharmaceutical Companies, Academic Research Institutes, Clinical Laboratories, Biotechnology Firms Application: Drug Discovery, Diagnostics, Genomics, Proteomics Technology: Microplate Technology, Lab-on-a-Chip, Artificial Intelligence, Machine Learning |
| Companies Covered | QIAGEN, Siemens Healthineers AG, Thermo Fisher Scientific Inc., Tecan Trading AG, Roche Diagnostics, Danaher Corporation, Agilent Technologies Inc., Hudson Robotics, Revvity Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Laboratory Automation Market Strategic Shifts & Innovations
Artificial intelligence is embedding into automation software layers faster than hardware refresh cycles, creating divergence between AI-augmented platforms and legacy equipment retrofits. Three developments are compressing competitive timelines.
Autonomous protocol optimization is bifurcating vendor strategies across the sector. Thermo Fisher Scientific and Danaher Corporation pursue end-to-end platform control, while modular specialists enable third-party sequencer integration. Pharmaceutical sponsors in the Boston-Cambridge corridor adopt both approaches simultaneously, running validated workflows on integrated systems while piloting modular architectures for emerging modalities. This technology is bifurcating the vendor base into closed-ecosystem incumbents and open-architecture challengers.
FDA's evolving guidance on software as a medical device is reshaping validation documentation burdens for clinical laboratory automation. Vendors must now submit algorithm change control protocols alongside hardware premarket notifications. Clinical diagnostics segments face compressed development timelines as sponsors race to secure 510(k) clearances before guidance finalization.
Service contracting is unbundling from hardware procurement as laboratory directors seek operational expenditure treatment for automation assets. Per-sample pricing models displace capital purchase structures in mid-tier pharmaceutical laboratories. This shift concentrates in the Research Triangle and San Diego biotech clusters where venture-backed sponsors prioritize cash flow flexibility over long-term cost optimization.
United States Laboratory Automation Market Segmentation
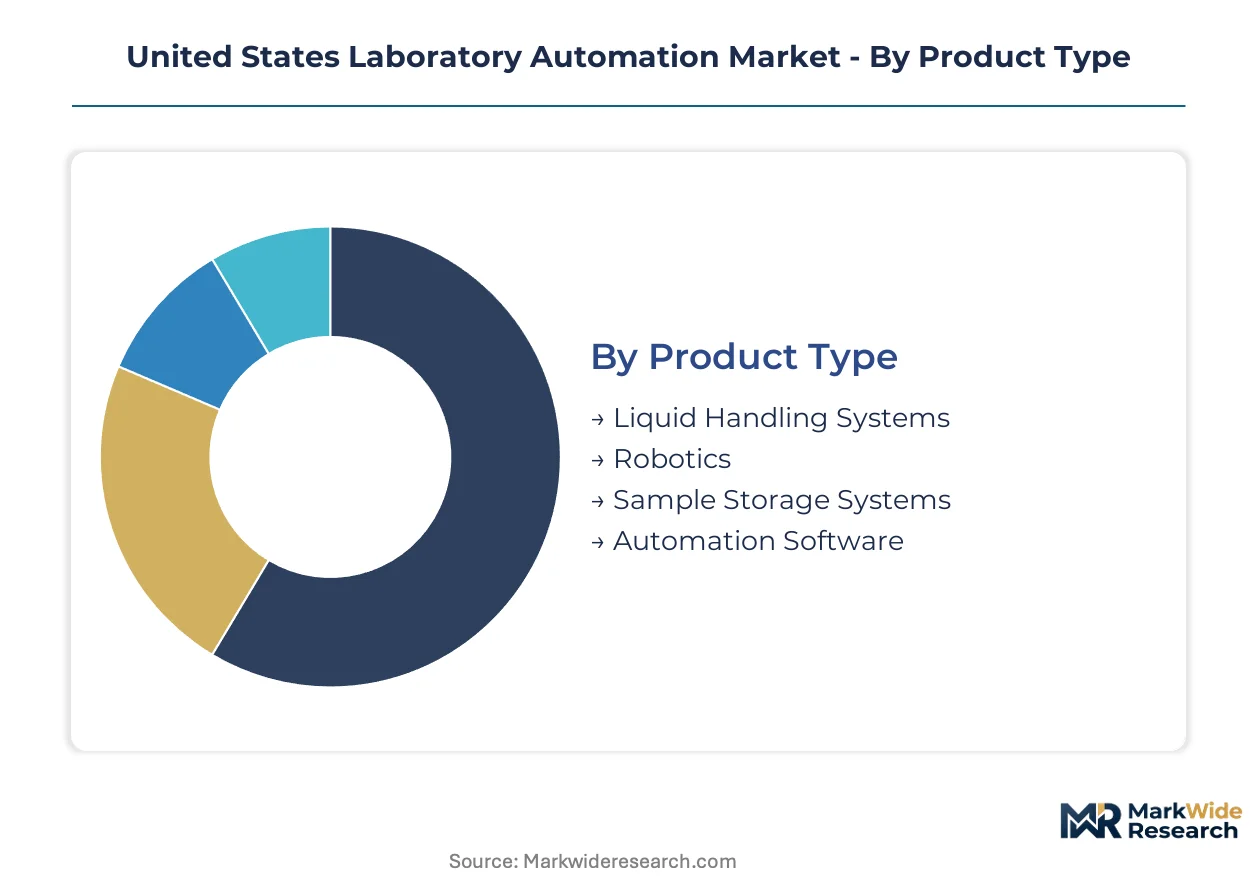
Laboratory automation vendors face divergent substitution pressures across hardware, software, and service layers. Segmentation reveals which product categories defend against modular point solutions and which end-user verticals command premium pricing for integrated platforms.
Product Type:
Liquid handling systems face substitution pressure from open-source robotic arms paired with third-party pipetting modules, while automation software confronts API-based integration layers that bypass proprietary control systems.
- Liquid Handling Systems:Precision dispensing platforms operate at microliter-to-nanoliter volumes with positional accuracy below 0.1 millimeters. Pharmaceutical companies in the Boston-Cambridge corridor dominate procurement for high-throughput screening retrofits, driven by compressed discovery timelines and FDA premarket review requirements for companion diagnostics.
- Robotics:Articulated arm and gantry systems execute plate handling, colony picking, and sample transport protocols. Academic research institutes prioritize compact benchtop configurations where floor space constraints and NIH grant funding cycles shape purchasing decisions.
- Sample Storage Systems:Automated freezers and retrieval robotics maintain chain-of-custody documentation for biobank specimens under CLIA and CAP accreditation standards.
- Automation Software:Protocol design, scheduling, and data management platforms integrate with LIMS and ELN systems through middleware architectures.
Liquid handling systems retain volume leadership; automation software holds the steepest expansion curve.
End User:
Cost tier stratification separates capital-intensive integrated platform purchasers from modular point-solution adopters, with reimbursement exposure creating additional segmentation across clinical versus research environments.
- Pharmaceutical Companies:Global sponsors deploy end-to-end automation suites across lead optimization and preclinical safety workflows. 21st Century Cures Act provisions for breakthrough therapy designation accelerate investment in AI-integrated platforms that compress IND-enabling study timelines.
- Academic Research Institutes:University core facilities and principal investigator laboratories prioritize price-accessible benchtop systems with minimal service contracts. NIH S10 shared instrumentation grants fund 40-60% of capital purchases, constraining vendor pricing power.
- Clinical Laboratories:Hospital and reference laboratories face CMS reimbursement pressure for algorithm-augmented diagnostics, shaping automation procurement toward 510(k)-cleared systems with documented clinical validity.
- Biotechnology Firms:Venture-backed sponsors in the Research Triangle and San Diego clusters favor per-sample pricing models and cloud-based software subscriptions to preserve cash runway.
Pharmaceutical companies retain volume leadership; biotechnology firms hold the steepest expansion curve.
Application:
Application maturity varies sharply, with diagnostics automation constrained by FDA validation burdens while genomics workflows expand through sequencing platform commoditization.
- Drug Discovery:High-throughput screening and lead optimization workflows consume the majority of liquid handling capacity. Contract research organizations in the Boston-Cambridge corridor concentrate demand for 24/7 operational systems with predictive maintenance algorithms.
- Diagnostics:Clinical chemistry, immunoassay, and molecular testing automation faces CLIA complexity and FDA 510(k) documentation requirements. Laboratory developed test enforcement discretion shapes platform selection for mid-tier hospital laboratories.
- Genomics:Next-generation sequencing sample prep and library construction drive modular automation adoption. Third-party sequencer integration requirements favor open-architecture vendors over closed-ecosystem incumbents.
- Proteomics:Mass spectrometry sample prep and fractionation workflows demand specialized liquid handling for detergent-compatible buffers and low-protein-binding surfaces.
Drug discovery retains volume leadership; genomics holds the steepest expansion curve.
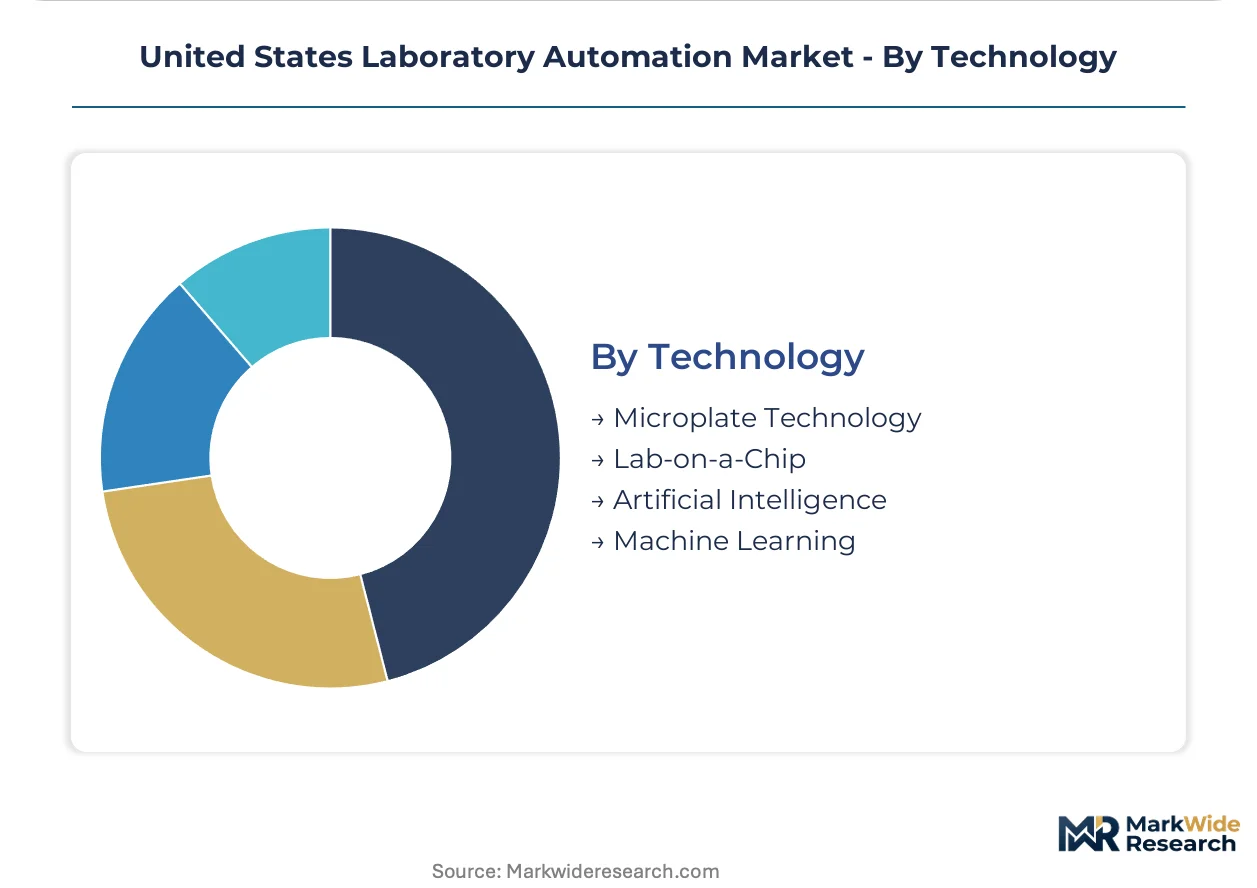
Technology:
Technology layering creates margin divergence, with AI and machine learning software capturing recurring revenue while microplate hardware faces commoditization from Asian contract manufacturers.
- Microplate Technology:96-well, 384-well, and 1536-well format handlers and readers remain the workhorse infrastructure for screening campaigns. Pharmaceutical sponsors in legacy facilities prioritize backward compatibility with existing compound libraries and detection reagents.
- Artificial Intelligence:Predictive maintenance, autonomous protocol optimization, and anomaly detection algorithms embed into vendor software stacks. FDA software as a medical device guidance drives validation documentation investment for clinical diagnostic deployments.
- Lab-on-a-Chip:Microfluidic integration of sample prep, reaction, and detection functions reduces reagent consumption for point-of-care and decentralized testing applications.
- Machine Learning:Supervised and reinforcement learning models optimize liquid handling parameters for viscosity-compensated dispensing and tip wear prediction.
Microplate technology retains volume leadership; artificial intelligence holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the Boston-Cambridge corridor, where pharmaceutical density sustains premium automation contracts, while academic markets in the Midwest and Southeast face compressed procurement budgets under NIH funding constraints.
Greater Boston
Pharmaceutical sponsors and contract research organizations drive concentrated demand for high-throughput screening systems. FDA premarket review pathways for companion diagnostics accelerate validation timelines for AI-integrated platforms. The Kendall Square biotech cluster hosts the densest automation procurement activity, with venture-backed firms retrofitting legacy workflows for compressed IND timelines.
San Diego County
Biotechnology firms prioritize per-sample pricing models and cloud-based software subscriptions to preserve cash runway. CMS reimbursement decisions for algorithm-augmented diagnostics reshape automation procurement toward 510(k)-cleared systems. The Torrey Pines and Sorrento Valley clusters concentrate demand for modular sample-prep automation integrating with third-party sequencers.
Research Triangle
Academic medical centers and contract research organizations balance capital constraints against 24/7 operational requirements. NIH S10 shared instrumentation grants fund 40-60% of capital purchases, constraining vendor pricing power. The Durham-Chapel Hill-Raleigh corridor concentrates demand for compact benchtop systems targeting space-constrained university laboratories.
San Francisco Bay Area
Venture-backed biotechnology sponsors and academic institutes generate bifurcated demand across integrated platforms and modular point solutions. EPA guidelines on hazardous waste handling from automated processes constrain system design choices for high-throughput screening facilities. The South San Francisco biotech cluster and Stanford University core facilities drive adoption of predictive maintenance algorithms for asset utilization improvement.
Midwest Academic Corridor
University core facilities and principal investigator laboratories prioritize price-accessible systems with minimal service contracts. OSHA laboratory safety standards create specification advantages for vendors certifying closed-system designs. The Illinois-Indiana-Ohio research triangle concentrates demand for backward-compatible liquid handling retrofits serving legacy compound libraries.
United States Laboratory Automation Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the United States laboratory automation sector. Integrated platform vendors sustain pricing power through end-to-end consumables-to-software portfolios, while modular specialists capture share through third-party sequencer integration. Three archetypes dominate: diversified life science conglomerates with clinical diagnostics installed bases, precision automation specialists targeting academic price tiers, and AI-embedded software layer vendors. Competitive dynamics center on M&A activity consolidating point-solution capabilities and strategic partnerships bridging legacy LIMS integration gaps.
Within the diversified conglomerate tier, Thermo Fisher Scientific Inc. and Danaher Corporation exemplify end-to-end platform control strategies. Among precision automation specialists, Hudson Robotics occupies a position representing compact benchtop system design for space-constrained budgets. QIAGEN anchors the modular architecture vector, exemplifying sample-prep automation that integrates with third-party sequencers without competing against entrenched sequencing ecosystems.
| Leading Market Players |
|---|
| QIAGEN |
| Siemens Healthineers AG |
| Thermo Fisher Scientific Inc. |
| Tecan Trading AG |
| Roche Diagnostics |
| Danaher Corporation |
| Agilent Technologies Inc. |
| Hudson Robotics |
| Revvity Inc. |
| Others |
Cost & Logistics Intelligence
FDA 510(k) clearance requirements for software as a medical device gate both vendor qualification and price stratification, forcing clinical-grade automation platforms to command premiums over research-use-only systems while constraining supply base to validated manufacturers. This regulatory threshold simultaneously protects incumbent pricing power and limits downstream substitution from uncertified competitors.
Pricing Analysis
Configured-to-order pricing for customized liquid handling workstations spreads 40-60% above standard catalog configurations for equivalent throughput specifications. The dominant structure combines capital equipment purchase with mandatory consumables contracts and tiered software licensing. Price differentiation hinges on CLIA complexity certification and predictive maintenance AI integration. Cost compression in mid-tier academic segments intensifies as NIH S10 grant constraints tighten procurement budgets. Biotechnology firms in San Diego and Research Triangle corridors exhibit highest price sensitivity, favoring per-sample operational expenditure models over capital deployment.
Supply Chain Analysis
Germany, Switzerland, and the United States anchor precision motion control component manufacturing for laboratory robotics, with Japanese suppliers dominating optical detection modules. Supply chains draw from specialized aluminum alloys for gantry frames, fluoropolymer formulations for liquid-contact surfaces, and field-programmable gate arrays for motion controllers. Single-source vulnerability concentrates in high-precision syringe pumps and linear encoder subassemblies sourced from German Mittelstand specialists. Distribution runs through direct field service organizations for integrated platforms and authorized distributors for benchtop systems serving academic price tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around FDA software validation documentation creates defensive moats for incumbents with established 510(k) clearance track records, while switching costs from proprietary consumables formats lock in recurring revenue streams.
For Market Incumbents: Fortify installed base retention through backward integration into specialized tip and reagent cartridge production, eliminating third-party consumables substitution. Expand predictive maintenance AI capabilities to deepen workflow entrenchment. The modular open-architecture challenge from QIAGEN and emerging software-layer vendors threatens closed-ecosystem pricing power. Certification investment in EPA closed-system hazardous waste handling standards creates specification advantages in high-throughput screening procurement. For New Entrants and Emerging Players: Differentiate on cloud-native software architectures that bypass legacy LIMS integration bottlenecks consuming 30-50% of incumbent deployment engineering. Target space-constrained academic core facilities in Midwest and Southeast corridors currently underserved by integrated platform vendors. White-space concentration exists in compact benchtop genomics sample-prep automation priced below NIH S10 grant thresholds. Go-to-market through per-sample pricing partnerships with venture-backed biotechnology sponsors prioritizing cash flow flexibility. For Investors and Strategic Acquirers: FDA finalization of software as a medical device guidance reshapes the acquisition landscape toward targets with documented algorithm change control protocols and clinical diagnostic validation infrastructure. Long-term viability favors vendors with recurring consumables revenue exceeding 50% of total mix and established service contracting capabilities. Acquisition target archetype: modular automation specialists with proven third-party sequencer integration and cloud-based protocol management platforms. Signal to monitor: CMS reimbursement decisions for algorithm-augmented diagnostics enabling clinical laboratory automation procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Integrated Platform Validation | FDA 510(k) clearance for predictive maintenance algorithms secures premium pricing in clinical diagnostics. |
| Consumables Backward Integration | Captive tip and reagent cartridge production locks in recurring revenue from installed liquid handling bases. |
| Cloud-Native LIMS Integration | API-first software architectures reduce deployment friction against legacy laboratory information management systems. |
| Academic Price-Tier Product Line | Compact benchtop configurations capture NIH S10 grant-funded procurement in space-constrained university facilities. |
| Per-Sample Service Contracting | Operational expenditure treatment preserves cash runway for venture-backed biotechnology sponsors in San Diego clusters. |
Research Approach
Desk research of FDA 510(k) premarket notification databases, NIH RePORTER grant award records, and CLIA laboratory accreditation registries preceded structured interviews with pharmaceutical automation engineering directors, clinical laboratory operations managers, academic core facility directors, and contract research organization procurement leads. Secondary validation drew from vendor SEC filings, EPA hazardous waste handling compliance documentation, and CMS reimbursement guidance releases. Bottom-up triangulation across end-user procurement volumes and top-down reconciliation against vendor reported automation segment revenues anchored market sizing.
Variance decomposition across product type, end user vertical, application workflow, and technology layer dimensions structured the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Modeled inputs incorporated pharmaceutical R&D capital expenditure cycles, NIH instrumentation grant funding trajectories, and FDA software as medical device guidance implementation timelines.
Decision-makers should treat outputs as directional under assumptions of continued 21st Century Cures Act implementation and stable NIH funding levels; material deviation in regulatory enforcement discretion or federal research appropriations would warrant model refresh. Recalibration cycles align with material shifts in FDA guidance finalization and CMS reimbursement determinations for algorithm-augmented diagnostics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Asia Pacific Marketing Automation Software Market
Automation
Automation Lifecycle Services Market
Automation
Global Sales Force Automation (SFA) Market
Automation
Global Database Automation Systems Market
Automation
Intelligent Remote Terminal Unit Market
Automation
Dropshipping Automation Software Market
Automation
Europe Laboratory Automation Market
Automation
Database Automation Market
Automation
Automated Cell Block Systems Market
Automation
Hyperautomation Market
Automation
Universal Process Control Market
Automation
Global Automated Sample Storage Systems Market
Automation
Automatic Message Handling System Market
Automation
Italy Marketing Automation Market
Automation
Global Direct Mail Automation Software Market
Automation
Italy Marketing Automation Software Market