
 Global Door and Window Automation Market | 2026-2036
Global Door and Window Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Door and Window Automation Market Intelligence
Distribution through specialized building technology integrators is tilting the competitive balance away from traditional hardware suppliers. ASSA ABLOY leverages its extensive portfolio of mechanical and electronic locks to offer bundled solutions. Schneider Electric specializes in integrating automation within its broader EcoStruxure building management platform. Meanwhile, dormakaba competes by focusing on seamless access control systems for commercial and public infrastructure.
Door and window automation involves motorized systems, typically electromechanical, that control the opening, closing, and locking of building access points. These systems integrate sensors and controllers, often communicating via protocols like KNX or BACnet, to manage function. The primary purpose is to improve building accessibility, security, and energy efficiency. Sliding door systems dominate commercial complexes, while automated roller shutter systems are gaining share in warehouse applications for security and operational speed.
Product design is shaped by regional safety and performance mandates. In Europe, CE marking and EN 16005 for powered doors are essential, while in the United States, ANSI/BHMA standards govern product safety. Accessibility regulations like the Americans with Disabilities Act (ADA) also define requirements for automated entrances. Future market position hinges on a vendor's ability to navigate the fragmented landscape of building IoT protocols.
Market Dynamics
The convergence of stringent energy efficiency regulations with the expansion of IoT-based building management platforms is the central force shaping the market. This dual pressure compels property owners to invest in intelligent systems beyond simple motorization.
Growth Catalysts
- Energy Efficiency Mandates:Regulations such as the European Union's Energy Performance of Buildings Directive (EPBD) compel commercial building owners to upgrade systems to reduce energy consumption, directly benefiting automated window and shutter vendors.
- Interoperability Standards:The adoption of open communication protocols like KNX and BACnet simplifies integration, reducing deployment complexity and encouraging adoption in new construction and major retrofits.
- Smart City Development:Government-led smart city initiatives in the United Arab Emirates and Singapore create large-scale demand for integrated automation systems in public transit hubs, commercial centers, and government buildings.
Market Restraints
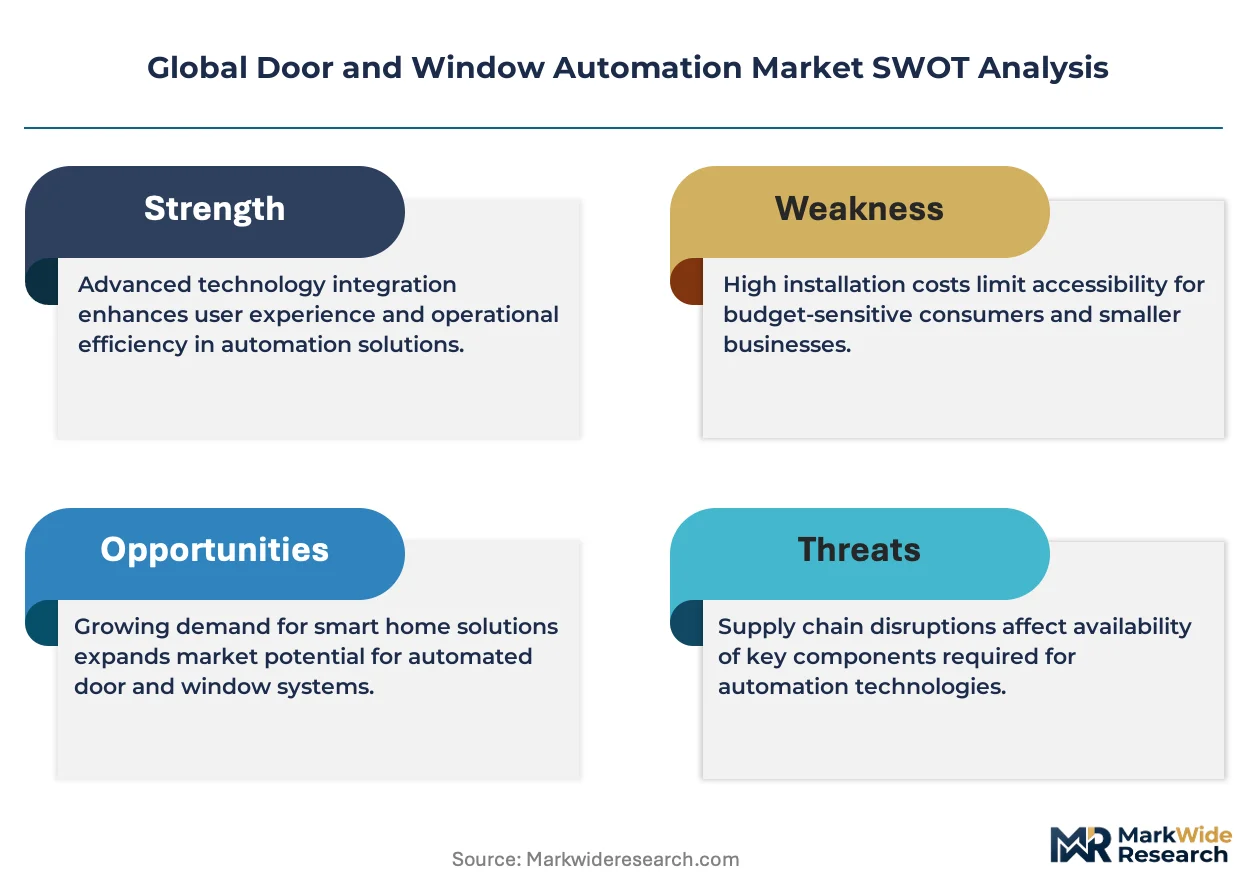
- High Retrofit Costs:The substantial capital investment required to install automated systems in existing buildings, particularly those with complex architectural features, limits adoption in the small and medium-sized commercial sector.
- Protocol Fragmentation:A lack of universal standardization across building IoT protocols creates interoperability risks, locking customers into specific vendor ecosystems and deterring investment from some facility managers.
- Cybersecurity Concerns:Network-connected doors and windows present a potential attack surface, and concerns over unauthorized access or system manipulation act as a barrier for security-sensitive applications like data centers or financial institutions.
Strategic Opportunities
- Healthcare and Assisted Living:Japan's aging population creates a significant opportunity for automated doors that enhance accessibility and safety in hospitals, elder care facilities, and private residences.
- Warehouse and Logistics:High-speed automated roller shutters and sectional doors offer a clear value proposition in distribution centers, where they improve operational speed, environmental control, and security.
- Predictive Maintenance Services:The integration of AI and sensor data enables vendors to offer subscription-based predictive maintenance, creating a recurring revenue stream and increasing customer lifetime value.
Industry Challenges
- Technician Skill Gaps:A persistent shortage of installers and service technicians proficient in both mechanical systems and IP networking protocols constrains the capacity of vendors to execute large-scale projects.
- Complex Compliance Landscape:Manufacturers must navigate a fragmented web of regional standards, including EN 16005 for safety in Europe and ANSI/BHMA standards alongside ADA accessibility rules in the United States.
- Legacy System Integration:Integrating modern automation controllers with outdated, proprietary building management systems during retrofits is technically complex and often results in budget overruns and performance compromises.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Door and Window Automation Market |
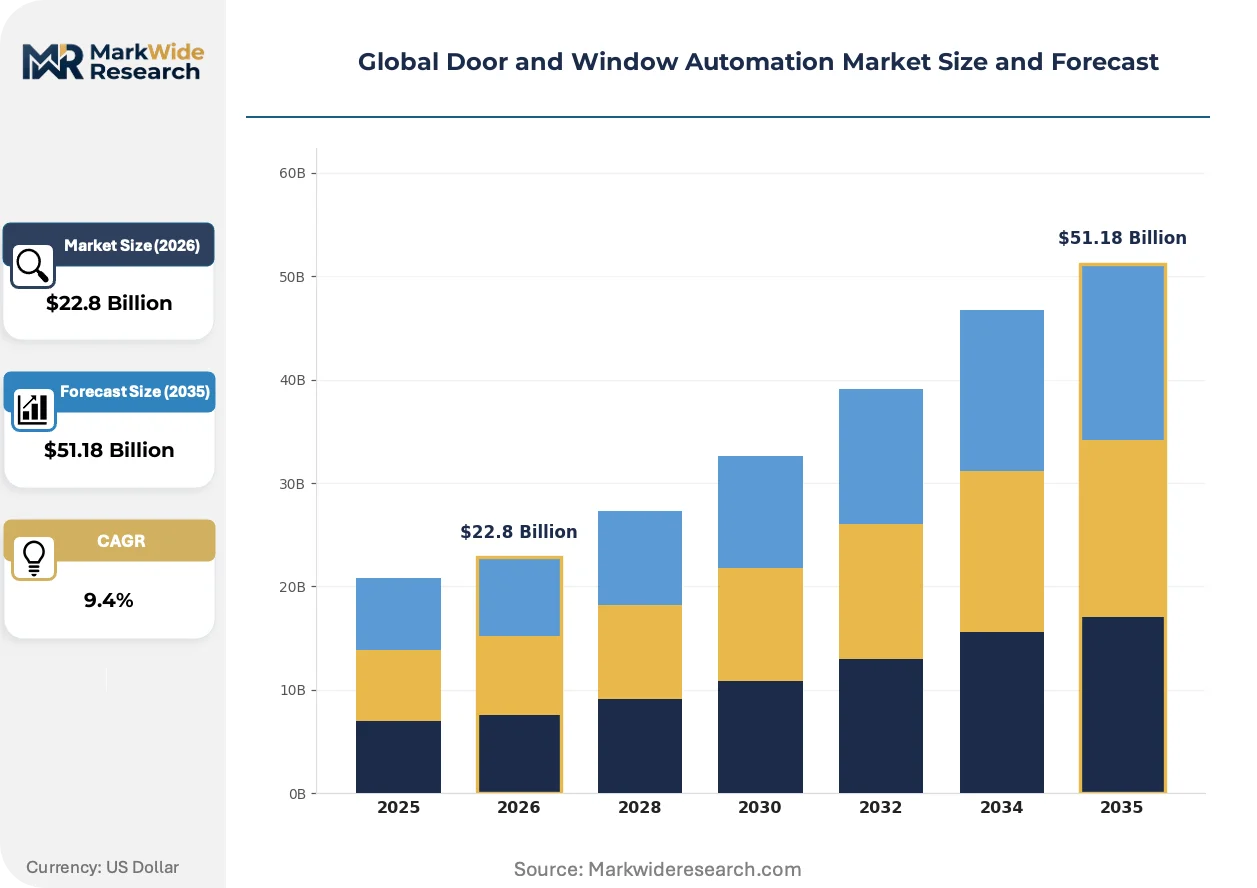
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $51.18 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sliding Door Systems, Swing Door Systems, Roller Shutter Systems, Casement Window Systems, Others Technology: Electromechanical, Electrohydraulic, Electropneumatic, Electrostatic, Manual Override Application: Commercial Complexes, Warehouses, Educational Institutions, Government Facilities, Public Infrastructure End User: Facility Management Companies, Property Developers, Retail Chains, Transportation Hubs, Entertainment Venues |
| Companies Covered | ASSA ABLOY, Allegion, Nabtesco Corporation, GEZE GmbH, dormakaba, Honeywell International, Schneider Electric, Stanley Access Technologies, Came Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Door and Window Automation Market Strategic Shifts & Innovations
The market is shifting from a focus on standalone motorized products to integrated, software-defined access ecosystems. This evolution prioritizes connectivity, data analytics, and integration with broader building intelligence platforms to deliver enhanced efficiency and security outcomes.
Wireless sensor and actuator technologies are a primary innovation. These systems, often using low-power protocols like Zigbee, allow for the automation of doors and windows without the need for extensive and costly electrical wiring. Commercial real estate and hospitality sectors are adopting these for retrofit projects, where minimizing tenant disruption is critical. This technology is rendering obsolete the assumption that automation requires invasive, hardwired infrastructure for every access point.
European energy directives are accelerating technology adoption. The EU's Energy Performance of Buildings Directive (EPBD) requires member states to implement policies for near-zero energy buildings, creating a powerful incentive for dynamic facade control. Commercial office and public building segments are most affected, responding by specifying automated windows and shades linked to building management systems to optimize natural light and thermal gain.
Buyer behavior is moving away from single-transaction hardware purchases toward service-oriented access control contracts. This model disrupts the business of traditional hardware distributors by bundling installation, maintenance, and software updates into a recurring subscription. This shift is most prominent within large corporate campuses and multi-tenant commercial properties in North America, where facility managers prioritize operational predictability and total cost of ownership.
Global Door and Window Automation Market Segmentation
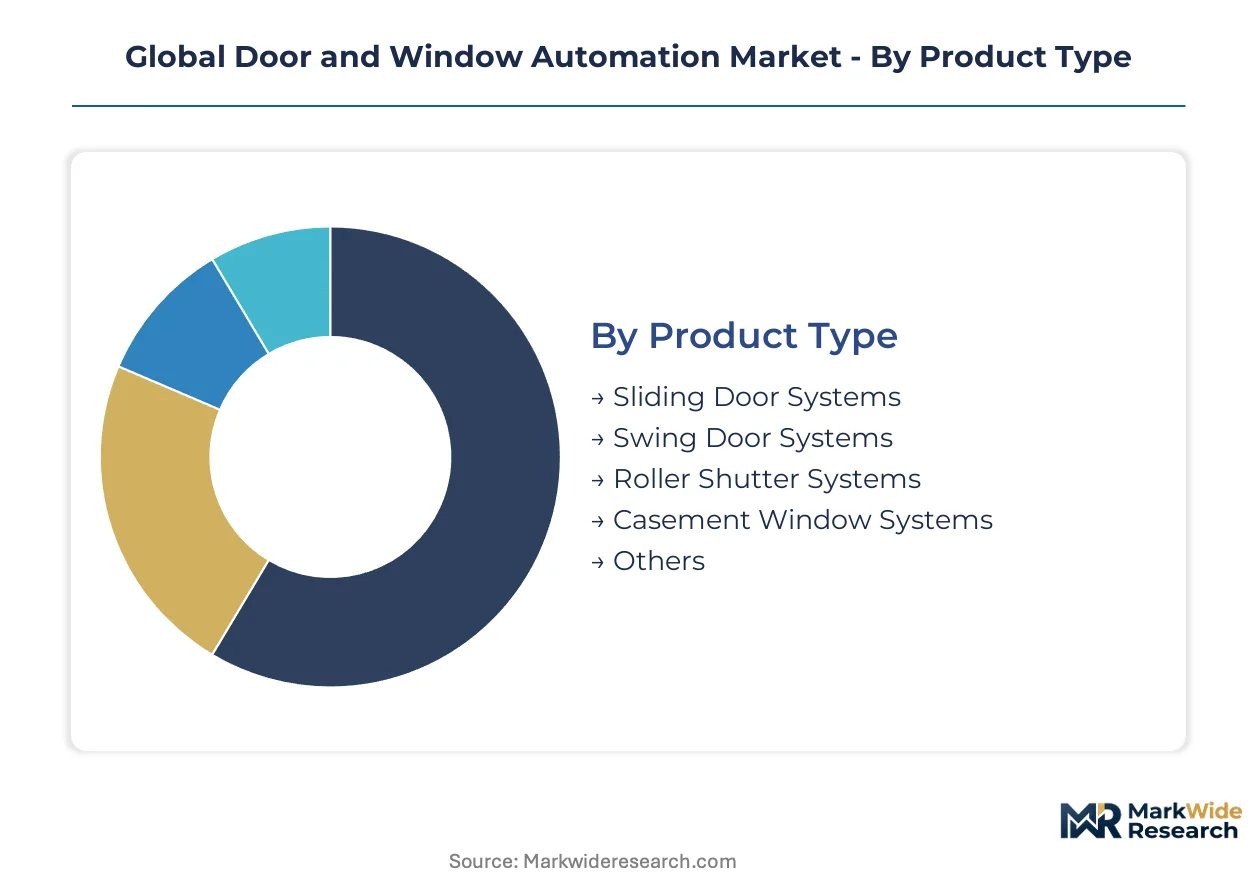
The global door and window automation market segments reflect the diverse functional requirements and operational environments for intelligent access solutions. Understanding these distinct categories allows vendors to tailor product development and service offerings to specific end-user needs and regulatory compliance frameworks.
Product Type:
After-sales service intensity varies significantly across product types, influencing long-term customer relationships and maintenance revenue streams for suppliers.
- Sliding Door Systems:These motorized systems operate on a linear track, offering seamless, hands-free access with integrated sensors for safety and traffic management. Demand concentrates in high-traffic commercial complexes and public transit hubs, driven by accessibility regulations like the Americans with Disabilities Act (ADA) and energy efficiency mandates.
- Roller Shutter Systems:Comprising interlocking slats that roll up and down, these robust systems provide security, environmental control, and operational speed for large openings. Warehouses and logistics centers represent a significant demand cluster, prioritizing asset protection and rapid access for goods movement.
- Swing Door Systems:These automated doors pivot on hinges, offering controlled opening and closing for single or double leaf configurations.
- Casement Window Systems:Motorized mechanisms control the outward or inward swing of windows, optimizing ventilation and natural light.
- Others:This category includes specialized solutions such as revolving doors, folding doors, and vertical lift doors, catering to unique architectural or functional demands.
Sliding Door Systems hold the largest share; momentum sits with Roller Shutter Systems.
Technology:
Application complexity dictates the choice of automation technology, balancing factors like force requirements, operational speed, and environmental resilience.
- Electromechanical:These systems utilize electric motors, gears, and sensors to power door and window movements, offering precise control and reliability. Commercial office buildings and residential complexes widely adopt electromechanical solutions for their balance of cost, performance, and energy efficiency.
- Electrohydraulic:Employing pressurized fluid to generate motion, electrohydraulic systems deliver high force and smooth operation, suitable for heavy-duty applications. Industrial facilities and high-security installations frequently deploy these robust systems for large, heavy access points requiring significant closing force.
- Electropneumatic:Compressed air drives the actuators in electropneumatic systems, offering clean operation and fast response times.
- Electrostatic:This nascent technology uses electrostatic forces for micro-actuation, finding niche applications in small-scale, precision automation.
- Manual Override:These integrated features allow for manual operation of automated systems during power outages or emergencies, ensuring safety and functionality.
Electromechanical systems lead volume, with Electrohydraulic solutions gaining share for specialized applications.
Application:
Volume of traffic and specific functional needs define automation requirements across various application environments.
- Commercial Complexes:These environments demand high-traffic, secure, and aesthetically pleasing automated access points for main entrances, internal doors, and windows. Energy Performance of Buildings Directive (EPBD) compliance in Europe drives significant upgrades in commercial properties, enhancing energy efficiency.
- Warehouses:Automation in warehouses focuses on large, high-speed doors and shutters to improve logistics efficiency, environmental control, and security. The expansion of e-commerce and global supply chains fuels demand for optimized material flow within these facilities.
- Educational Institutions:Automated doors and windows enhance accessibility, security, and ventilation in schools and universities.
- Government Facilities:These sites require robust security, controlled access, and reliable operation for public and restricted areas.
- Public Infrastructure:This category includes airports, train stations, and public transit hubs, where automated systems manage high pedestrian volumes and enhance safety.
Commercial Complexes constitute the largest deployment area, while Public Infrastructure projects are expanding most quickly.
End User:
Procurement patterns and long-term service agreements shape the engagement models with different end-user segments.
- Facility Management Companies:These entities manage the ongoing operation, maintenance, and optimization of building systems for property owners. They prioritize integrated solutions that offer remote monitoring, predictive maintenance, and operational predictability for multi-tenant commercial properties.
- Property Developers:Responsible for new construction and major renovation projects, property developers integrate automated systems during the design and build phases. Smart city initiatives in the United Arab Emirates and Singapore create substantial opportunities for large-scale, integrated automation deployments in new developments.
- Retail Chains:Automated doors enhance customer experience and security at store entrances and internal areas.
- Transportation Hubs:Airports, bus terminals, and train stations require high-traffic, secure, and reliable automated access for passenger flow.
- Entertainment Venues:Theaters, stadiums, and convention centers utilize automation for crowd control, accessibility, and emergency exits.
Property Developers drive initial market entry, with Facility Management Companies securing long-term service contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Energy efficiency regulations, such as the European Union's Energy Performance of Buildings Directive (EPBD), drive significant investment in automated door and window systems. These mandates compel property owners to upgrade existing infrastructure and integrate advanced solutions in new construction. Smart city initiatives also create substantial demand for intelligent building access.
United States
Demand for automated systems in the United States stems from accessibility requirements and security enhancements. The Americans with Disabilities Act (ADA) defines strict requirements for automated entrances, promoting wider adoption. Major metropolitan areas like New York City focus on commercial building retrofits and new construction projects.
Germany
European Union's Energy Performance of Buildings Directive (EPBD) mandates higher efficiency, spurring technology upgrades in Germany. CE marking and EN 16005 standards are essential for powered doors, ensuring product safety and performance. Industrial hubs like Stuttgart prioritize advanced electromechanical systems in new construction and commercial properties.
United Arab Emirates
Government-led smart city initiatives in the United Arab Emirates create large-scale demand for integrated automation systems. These projects focus on public transit hubs, commercial centers, and government buildings, requiring robust security and efficiency. Dubai and Abu Dhabi drive significant deployments in new urban developments and infrastructure upgrades.
Japan
Japan's aging population creates a significant opportunity for automated doors that enhance accessibility and safety. Specific national accessibility guidelines promote the use of automated systems in public and private facilities. Tokyo's healthcare and assisted living facilities extensively integrate automated doors for patient convenience and security.
Singapore
Smart city developments in Singapore generate substantial demand for integrated automation solutions in commercial and public infrastructure. Government initiatives prioritize advanced building management systems for energy optimization and security. The Marina Bay area projects extensively feature integrated automation systems for dynamic facade control and access management.
Global Door and Window Automation Market Key Industry Players
On the supply side, the industry is fragmented, yet established players leverage broad portfolios for market presence. Key archetypes include specialized integrators, comprehensive building management system providers, and access control specialists. Companies pursue portfolio diversification through bundled solutions and strategic partnerships to enhance IoT integration.
Specialists in integrated access solutions include ASSA ABLOY, which exemplifies leveraging extensive mechanical and electronic lock portfolios for bundled offerings. Schneider Electric represents integration within its broader EcoStruxure building management platform, providing comprehensive automation. Meanwhile, dormakaba focuses on seamless access control systems, particularly for commercial and public infrastructure projects globally.
| Leading Market Players |
|---|
| ASSA ABLOY |
| Allegion |
| Nabtesco Corporation |
| GEZE GmbH |
| dormakaba |
| Honeywell International |
| Schneider Electric |
| Stanley Access Technologies |
| Came Group |
| Others |
Cost & Logistics Intelligence
The Suez Canal's freight cost fluctuations directly influence the global door and window automation market, impacting supply concentration from Asian manufacturers and shaping downstream price differentiation across product tiers. This dynamic links global logistics to local market pricing structures.
Pricing Analysis
CE marking and ANSI/BHMA certifications create the primary price spread in door and window automation systems. Project-based pricing dominates for large installations, often incorporating long-term maintenance contracts. After-sales service bundles and customization levels are key differentiation drivers. Pricing softness in standard electromechanical systems reflects intense competition from regional manufacturers. Small and medium-sized commercial sectors are most price-sensitive, while public infrastructure projects are least sensitive to initial capital outlay.
Supply Chain Analysis
Export controls on advanced sensor technologies limit the free flow of critical components for smart automation systems. Supply concentration for specialized components rests in China, Germany, and South Korea. The industry draws from microcontrollers, specialized motors, and high-grade aluminum. Single-source vulnerability for embedded software represents a structural supply chain risk. Distribution predominantly runs through specialized building technology integrators who manage installation and integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting within the global door and window automation market as facility management companies consolidate procurement for large commercial portfolios.
For Market Incumbents:
Build a data-driven service moat around existing customer bases through subscription-based predictive maintenance. Integrate advanced security features to counter threats from cyber vulnerabilities in connected systems. Invest in R&D for multi-protocol IoT compatibility to maintain channel control. This strategy defends against new entrants leveraging niche software solutions.
For New Entrants and Emerging Players:
Establish a beachhead in smart city infrastructure projects by offering specialized, energy-efficient automated window solutions. Target assisted living facilities in Japan with ADA-compliant swing door systems, leveraging specific accessibility mandates. A direct-to-developer sales model can bypass traditional hardware distributors, offering quicker market access in new construction.
For Investors and Strategic Acquirers:
Access control software specialists with strong recurring revenue models represent attractive acquisition targets for long-term value creation. The shift from hardware-centric to software-defined ecosystems signals sustained growth over a five to ten-year window. Watch for increasing M&A activity among integrators as an inflection indicator of market consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand IoT Protocol Compatibility | Broadens market reach by enabling integration with diverse building management systems. |
| Develop Subscription-Based Maintenance | Creates stable recurring revenue streams and enhances customer lifetime value. |
| Acquire Niche Software Developer | Strengthens software capabilities and intellectual property in access control. |
| Invest in Technician Training Programs | Addresses skill gaps and improves project execution capacity across regions. |
| Target Healthcare Facility Retrofits | Capitalizes on aging population trends and accessibility mandates in key geographies. |
Research Approach
A spread of perspectives from facility managers, property developers, building technology integrators, and regulatory experts converged on the working assumptions for this study. This involved extensive primary interviews combined with secondary validation from EU EPBD reports, ANSI/BHMA standards documentation, and national smart city initiative whitepapers. A rigorous bottom-up and top-down triangulation approach ensured data coherence.
The demand-supply balance for door and window automation systems was rigorously modeled across the analysis window. Segmentation by product type, technology, application, and end-user informed volume and value projections, alongside regional regulatory clusters. Compound annual growth rates were derived from historical trends and projected adoption rates, considering factors like smart city investment and energy efficiency mandates.
Sensitivities concentrate around geopolitical trade policies, evolving cybersecurity threats, and the pace of smart city infrastructure rollouts. Forecasts reflect a specific set of underlying assumptions. Material shifts in global economic conditions or major regulatory changes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Data Center Automation Market
Automation
Italy Marketing Automation Software Market
Automation
Global Direct Mail Automation Software Market
Automation
Global Cloud Automation Market
Automation
Workload Scheduling and Automation Market
Automation
Global Business Process Automation Software Market
Automation
Self Bag Drop Machine Market
Automation
Home Automation System Market
Automation
Global Form Automation Software Market
Automation
Asia-Pacific Micro Fulfillment Market
Automation
Global Field Force Automation Market
Automation
Hyperautomation Market
Automation
Global Database Automation Systems Market
Automation
Global Automated Sample Storage Systems Market
Automation
Automation-As-A-Service Market
Automation
Service Delivery Automation (SDA) Market