
 Yam Products Market | 2026-2036
Yam Products Market Size, Share, and Industry Trends Forecast 2026-2036
Yam Products Market Analytics
ISO 22000 certification is rotating as the primary gatekeeper for yam processors seeking European retail placement. ORGANICWAY leverages its organic certification stack to command premium shelf positioning in German and Dutch supermarkets. BDS Natural Products anchors West African sourcing networks through direct farmer contracting in Ghana and Nigeria. Xi'an Rainbow Biotech competes on spray-dried yam powder specifications for pharmaceutical excipient contracts.
Yam products encompass all processed and unprocessed derivatives of Dioscorea species tubers, typically containing 15-25% starch by wet weight, prepared through washing, peeling, blanching, drying, milling, or canning for human consumption and industrial starch applications. Fresh yams dominate household and informal trade volumes across Sub-Saharan Africa, while dried yams command the fastest growth in export corridors due to extended shelf stability and reduced freight costs per unit solids. The food service end use captures concentrated margin pools in North American and European ethnic restaurant supply chains, whereas snack applications remain nascent outside East Asian markets.
Nigeria's National Agency for Food and Drug Administration and Control enforces mandatory product registration and labeling standards that determine which yam flour brands enter domestic retail circulation. The EU Deforestation Regulation, implemented by the European Commission, requires geolocation traceability for yam-derived imports, directly shaping investment priorities for export-oriented processors. Stakeholders must monitor evolving mycotoxin threshold harmonization between Codex Alimentarius and national regulators, as these standards will determine which processing configurations achieve cross-border market access.
Market Dynamics
The EU Deforestation Regulation's geolocation traceability mandate is restructuring export eligibility for yam processors, forcing capital reallocation toward certified aggregation networks and digital chain-of-custody systems.
Growth Catalysts
- EU Green Deal compliance pathways:Food processors in Germany and the Netherlands are prioritizing deforestation-free yam flour sourcing, creating certified channel premiums for compliant West African suppliers.
- Pharmaceutical excipient demand:Spray-dried yam powder specifications for tablet binding applications are expanding contract volumes with European generics manufacturers.
- Nigeria's Oyo-Benue corridor aggregation:Smallholder consolidation into registered cooperatives is unlocking export financing instruments previously inaccessible to fragmented producers.
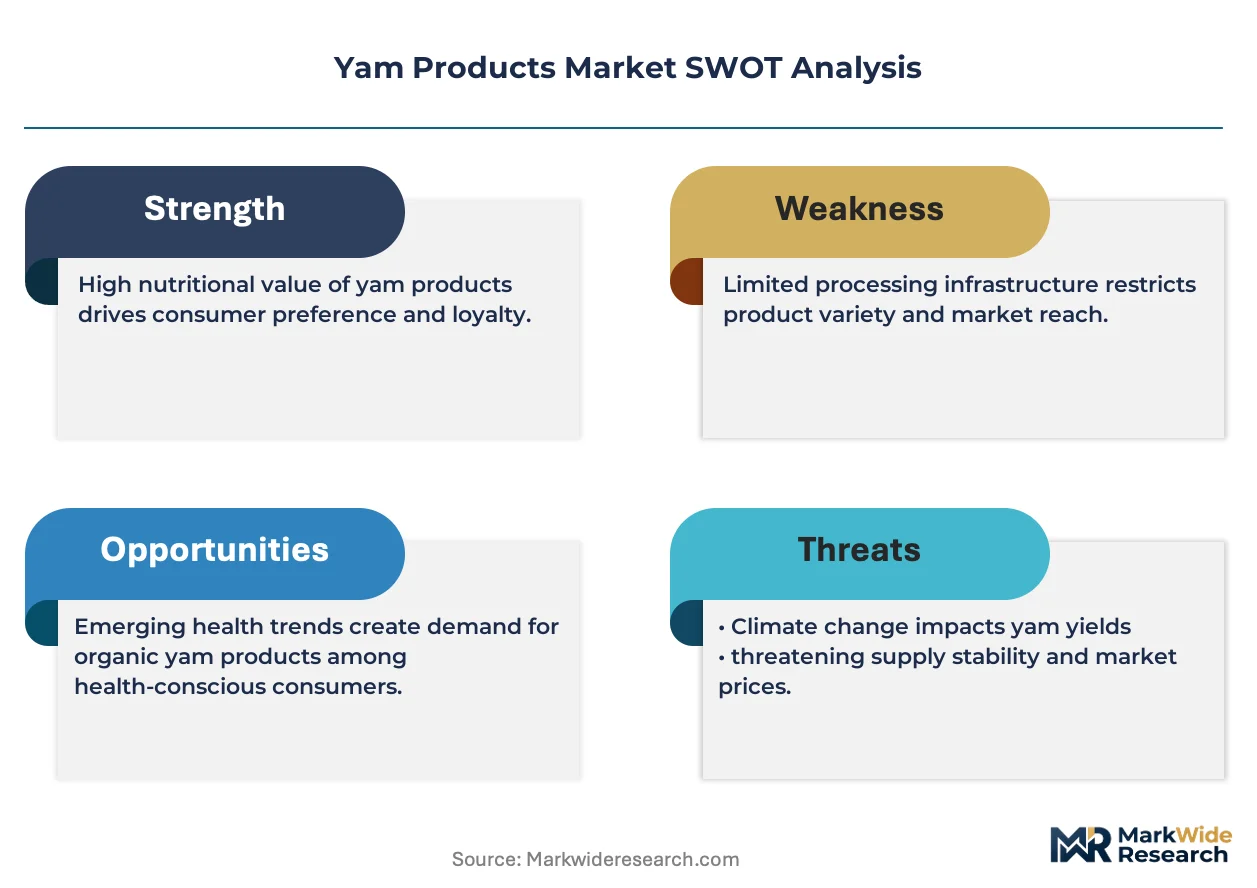
Market Restraints
- Input cost volatility:Diesel price fluctuations directly compress margins for processors operating captive generator sets during grid instability in Nigerian production zones.
- Supply concentration risk:Ghana's Ashanti Region hosts over half of nationally certified organic yam acreage, creating single-point vulnerability for premium export contracts.
- Substitution threat:Cassava starch from Southeast Asian integrated processors is displacing yam starch in lower-specification industrial applications.
Strategic Opportunities
- Underpenetrated North American ethnic retail:West African diaspora grocery chains in Houston and Atlanta remain underserved by branded yam flour distribution.
- Regulatory tailwind from Codex Alimentarius:Harmonized mycotoxin thresholds will reduce multi-jurisdiction testing burdens for cross-border processors achieving dual certification.
- Technology convergence:Blockchain-enabled farm-to-fork traceability is converging with mobile money settlement platforms to reduce working capital cycles for aggregator-processor relationships.
Industry Challenges
- ISO 22000 certification timeline:Nigerian processors face 14-18 month approval windows from NAFDAC, delaying European retail placement negotiations.
- Cold chain reconfiguration friction:Fresh yam exporters shifting from air freight to controlled-atmosphere sea containers require reworked port handling agreements at Lagos and Tema.
- Skill gap in digital traceability:Cooperative managers lack training in geotagging compliance data for EU Deforestation Regulation submission formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yam Products Market |
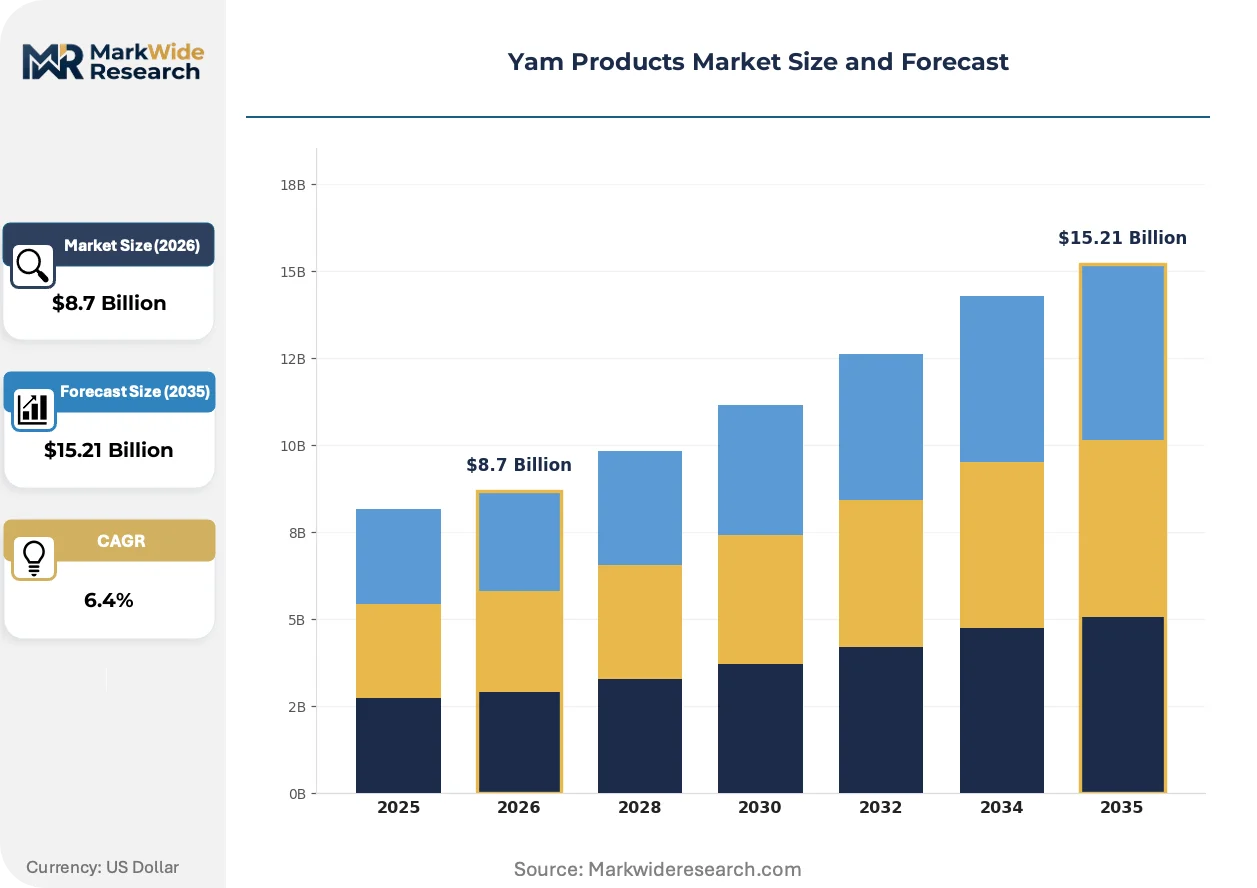
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Yams, Canned Yams, Frozen Yams, Dried Yams End Use: Household, Food Service, Food Processing, Snacks Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Wholesalers Packaging Type: Bags, Jars, Cans, Boxes |
| Companies Covered | ORGANICWAY, FZBIOTECH, BDS Natural Products, Wellgreen, Green Heaven India, Victar Bio-tech, HOKKOKU FOOD, Xi'an Rainbow Biotech, QinMing Bio-tech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yam Products Market Evolving Landscape
Processing technology decentralization and regulatory digitization are converging to compress the distance between West African farmgate and European retail shelf, while buyer procurement criteria harden around verifiable sustainability credentials.
Solar-powered mechanical dryers with variable temperature control are fragmenting the historical dominance of centralized fossil-fuel drying facilities. Mid-scale processors in Benue State are adopting 50-200 kg batch units to preserve starch integrity for pharmaceutical-grade output. This distributed infrastructure is fragmenting quality premiums away from legacy capital-intensive plants toward agile, certified micro-processors.
The EU Deforestation Regulation's geolocation data requirements are compelling Nigerian exporters to deploy farm-mapping software linked to NAFDAC registration databases. Compliance costs are concentrating contract volumes with processors possessing in-house traceability capabilities rather than third-party-reliant competitors. Dried yam chip exporters targeting Dutch traders are responding by mandating cooperative-level smartphone-based polygon mapping before purchase commitment.
Buyer certification-driven preference shifts are displacing price-first sourcing in European ethnic foodservice channels. German and Dutch restaurant distributors now require organic or Fairtrade yam flour credentials as table stakes for contract renewal. This behavioral change is most visible in Rotterdam's West African import wholesale cluster, where uncertified bulk offerings face 30-40% price discounts against labeled alternatives.
Yam Products Market Segmentation
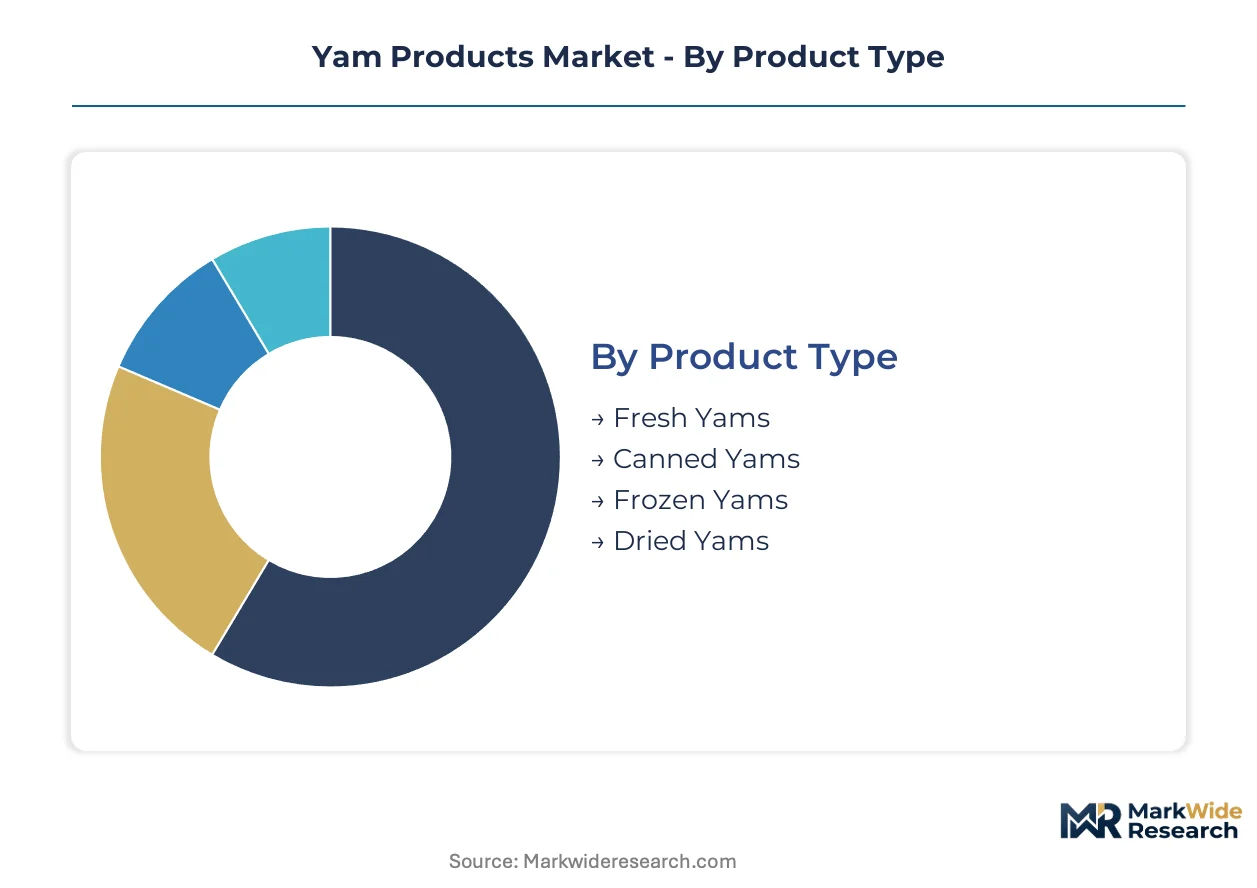
Yam product segmentation reflects divergent shelf-life requirements and certification burdens across export corridors. Regulatory differentiation by product form determines which processors capture EU retail placement versus domestic informal trade.
Product Type:
EU Deforestation Regulation traceability mandates favor processed derivatives with verifiable chain-of-custody documentation over fresh tuber shipments.
- Fresh Yams:Unprocessed Dioscorea tubers with 15-25% starch content by wet weight dominate household consumption across Nigerian Oyo and Benue states. Informal traders in Lagos and Ibadan markets capture volume through minimal handling overhead, though perishability limits export eligibility to air-freight corridors serving diaspora retailers in Houston and London.
- Dried Yams:Blanched, sliced, and dehydrated segments achieve 12-18 month stability with reduced freight cost per unit solids. German and Dutch supermarket buyers prioritize these specifications for deforestation-free procurement under EU Green Deal compliance pathways, with Benue State processors investing in solar-powered mechanical dryers to meet pharmaceutical-grade starch integrity standards.
- Canned Yams:Heat-sterilized segments in brine or syrup target North American food service channels with extended ambient storage. Ghana's Ashanti Region processors hold concentrated organic certification for this format.
- Frozen Yams:Blast-frozen par-cooked segments serve European ethnic restaurant supply chains requiring texture retention. Cold chain infrastructure gaps at Lagos and Tema ports constrain volume scaling.
Established volume favors Fresh Yams; emerging adoption favors Dried Yams.
End Use:
Customer procurement criteria harden around sustainability credentials in commercial channels while household segments prioritize price accessibility.
- Food Processing:Industrial buyers in Germany and the Netherlands source yam flour and starch for gluten-free bakery applications and pharmaceutical excipient contracts. Spray-dried powder specifications for tablet binding are expanding contract volumes with European generics manufacturers under ISO 22000 certification requirements.
- Household:Traditional consumption across West African urban centers drives fresh tuber demand through open-air markets and informal aggregation networks. Nigerian NAFDAC registration requirements for packaged flour brands are gradually formalizing retail penetration.
- Food Service:West African diaspora restaurants in Atlanta and Houston require consistent yam flour supply for fufu and pounded yam preparation. Rotterdam's wholesale cluster now mandates organic or Fairtrade credentials as contract renewal conditions.
- Snacks:Fried yam chip applications remain concentrated in East Asian markets with limited penetration into European or North American retail. Processing technology for shelf-stable seasoning adherence is still scaling.
Food Processing commands margin premiums; Household anchors absolute volume.
Distribution Channel:
Channel selection determines certification burden intensity and working capital cycle length for West African suppliers.
- Supermarkets:German and Dutch retail chains require deforestation-free geolocation data and organic certification stacks for yam flour shelf placement. ORGANICWAY leverages this channel for premium positioning through compliant West African sourcing networks.
- Wholesalers:Rotterdam and Hamburg import clusters aggregate bulk dried yam shipments for redistribution to ethnic foodservice distributors. Uncertified offerings face 30-40% price discounts against labeled alternatives in these trading hubs.
- Specialty Stores:West African diaspora grocers in Houston and Atlanta stock branded yam flour for household consumers seeking familiar preparation formats. Direct processor relationships bypass conventional import distributor markups.
- Online Retail:E-commerce penetration for yam products remains nascent outside packaged flour segments with standardized shipping weights. Cold chain requirements for frozen formats constrain digital channel viability.
Wholesalers dominate export volume; Supermarkets concentrate value capture.
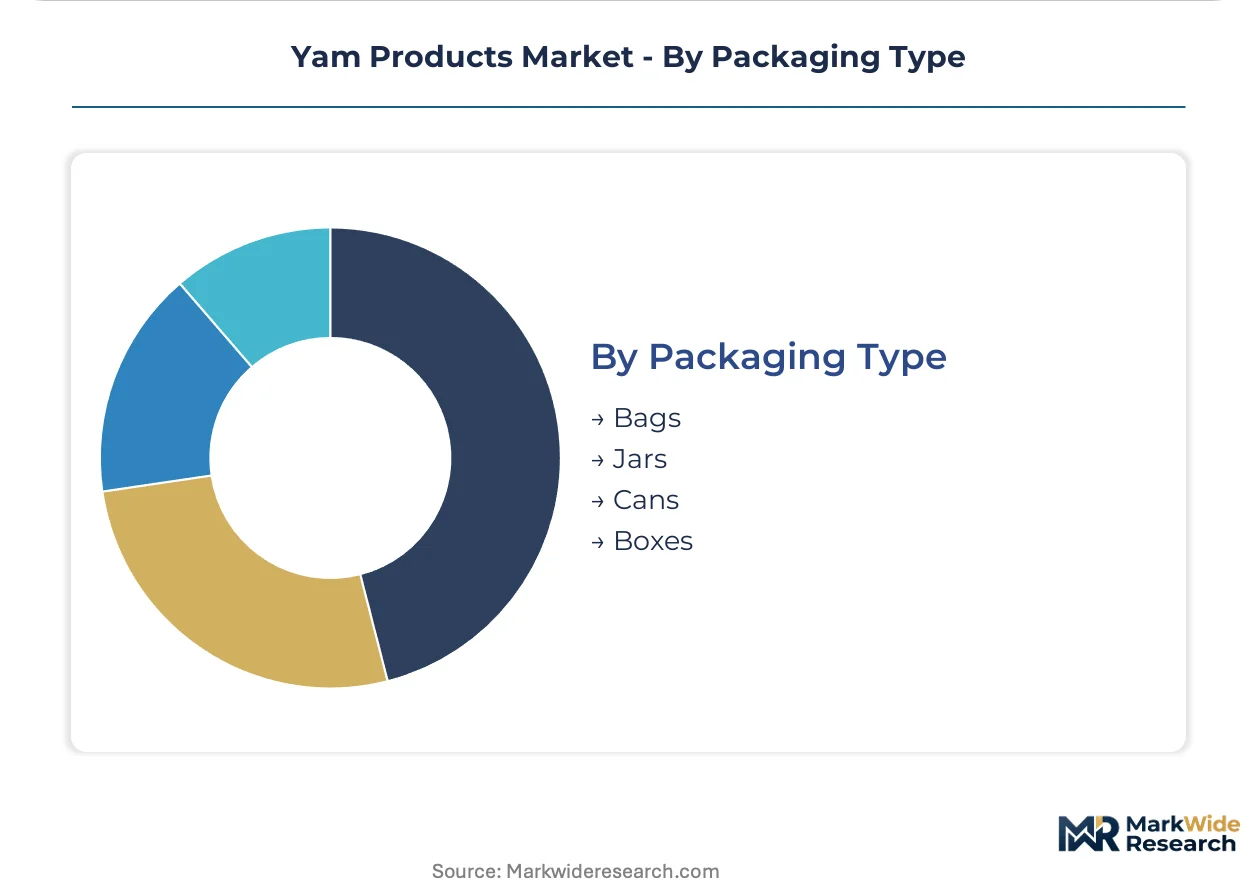
Packaging Type:
Material selection intersects with shelf stability requirements and retail format positioning across destination markets.
- Bags:Multi-layer polymer or kraft paper sacks hold dried yam flour and chips for industrial food processing and wholesale redistribution. Nigerian processors are adopting NAFDAC-compliant labeling for domestic retail bagged formats.
- Cans:Metal containers enable ambient-stable yam segments for North American food service and retail pantry stocking. Ghanaian organic processors prioritize this format for export contract compliance.
- Jars:Glass packaging targets premium ethnic retail positioning with visual product quality signaling. Limited adoption due to freight weight penalties and breakage risk in containerized shipping.
- Boxes:Corrugated fiberboard cases for bulk institutional delivery of frozen or dried segments. Standardized pallet configurations facilitate port handling efficiency at Lagos and Tema.
Bags dominate tonnage movement; Cans secure premium shelf positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Apapa and Tin Can Island ports in Lagos anchor West Africa's yam export infrastructure, handling containerized dried yam flour shipments to Rotterdam and Hamburg under EU Deforestation Regulation compliance protocols. These maritime gateways connect Nigerian processing clusters to European retail procurement networks.
Nigeria
Benue and Oyo states drive domestic yam flour production through solar-powered mechanical dryer adoption. NAFDAC enforces mandatory product registration and labeling standards that determine retail brand eligibility. Ibadan's processing cooperatives are consolidating smallholder aggregation into certified export channels.
Ghana
The Ashanti Region hosts concentrated organic yam acreage supplying canned and dried formats to North American food service buyers. The country's national food and drug regulator maintains export certification alignment with EU traceability requirements. Kumasi-based processors are investing in geolocation mapping software for farm-level compliance documentation.
Germany
Rotterdam's import wholesale cluster funnels West African yam flour to German supermarket chains under EU Green Deal procurement criteria. EFSA-aligned mycotoxin threshold harmonization is reducing multi-jurisdiction testing burdens for compliant suppliers. Hamburg's ethnic food distributors now mandate organic or Fairtrade credentials as contract renewal conditions.
Netherlands
Dutch traders prioritize deforestation-free yam flour sourcing through verified chain-of-custody systems linked to Nigerian farm polygons. The EU Deforestation Regulation's geolocation mandate is concentrating import volumes with processors possessing in-house traceability capabilities. Amsterdam's West African diaspora retail channels are expanding branded yam flour shelf placement.
United States
West African diaspora grocery chains in Houston and Atlanta represent underpenetrated demand for certified yam flour distribution. FDA import requirements for processed agricultural products shape labeling and safety documentation obligations. Georgia's ethnic foodservice distributors are negotiating direct processor relationships to bypass conventional import markups.
Yam Products Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and geographic sourcing control, creating a tiered structure where scale advantages intersect with compliance agility. The vendor base clusters around three strategic archetypes: integrated processors with captive farm networks, specialty ingredient suppliers targeting pharmaceutical excipient contracts, and organic-certified operators commanding premium retail positioning. Dominant competitive moves include backward integration into farmer contracting and technology licensing for blockchain-enabled traceability systems.
Within the organic-certified tier, ORGANICWAY leverages its certification stack for German and Dutch supermarket placement, while BDS Natural Products anchors West African sourcing through direct farmer engagement in Ghana and Nigeria. Xi'an Rainbow Biotech occupies a position among spray-dried powder specialists competing for pharmaceutical-grade contracts. These three exemplify how compliance infrastructure and processing technology differentiation determine contract access in deforestation-regulated corridors.
| Leading Market Players |
|---|
| ORGANICWAY |
| FZBIOTECH |
| BDS Natural Products |
| Wellgreen |
| Green Heaven India |
| Victar Bio-tech |
| HOKKOKU FOOD |
| Xi'an Rainbow Biotech |
| QinMing Bio-tech |
| Others |
Value Network & Pricing Analysis
Batch-scale solar dryer adoption in Benue and Oyo states fragments historical economies of scale, compressing price floors for pharmaceutical-grade yam flour while elevating premiums for certified micro-processors with direct EU retail access.
Pricing Analysis
Volume-discount tiering structures separate certified organic exporters from uncertified bulk suppliers and informal traders. ISO 22000 and EU Deforestation Regulation compliance command 30-40% premiums in Rotterdam and Hamburg wholesale clusters against unverified alternatives. Price differentiation rests on geolocation traceability documentation and NAFDAC registration status. Food processing buyers in Germany and the Netherlands exhibit lowest price sensitivity due to Green Deal procurement mandates, while West African household segments remain highly price-elastic.
Supply Chain Analysis
Nigeria and Ghana anchor West African yam production, with Benue and Oyo states driving flour output and Ashanti Region concentrating organic acreage. Processing inputs draw from diesel-powered captive generators, solar thermal drying equipment, and mobile money settlement platforms. Single-source vulnerability concentrates in Ghana's organic certification pipeline for North American canned yam contracts. Distribution runs through Apapa and Tin Can Island ports connecting to Rotterdam and Hamburg import clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward EU supermarket chains and German food processors as procurement criteria harden around deforestation-free credentials, fragmenting contract volumes away from price-first traders.
For Market Incumbents: Compound certification depth by integrating blockchain-enabled farm polygon mapping with in-house traceability systems rather than third-party reliance. Anchor backward integration into registered cooperatives across Nigeria's Oyo-Benue corridor to defend against spray-dried yam powder specialists capturing pharmaceutical excipient contracts. Prioritize NAFDAC-EU regulatory alignment to compress 14-18 month approval timelines. For New Entrants and Emerging Players: Anchor in underpenetrated North American ethnic retail channels, specifically West African diaspora grocery chains in Houston and Atlanta lacking branded yam flour distribution. Target food service segments in Georgia and Texas with direct processor relationships bypassing conventional import markups. Pursue organic or Fairtrade certification as table stakes for Rotterdam wholesale cluster access. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors processors with converged digital traceability and distributed solar drying infrastructure over legacy centralized plants. Long-term viability across the analysis window hinges on EU Deforestation Regulation compliance automation. Monitor NAFDAC-EU mycotoxin threshold harmonization as the inflection signal for cross-border processing configuration winners.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Traceability Deployment | EU Deforestation Regulation compliance automates geolocation data submission to Rotterdam traders. |
| Solar Dryer Network Expansion | Benue State micro-processors capture pharmaceutical-grade starch premiums from European generics manufacturers. |
| Direct Cooperative Contracting | Backward integration into Nigerian farmer aggregation unlocks export financing instruments. |
| NAFDAC-EU Dual Certification | Harmonized standards reduce multi-jurisdiction testing burdens for cross-border flour shipments. |
| North American Channel Development | Houston and Atlanta diaspora retail penetration bypasses conventional import distributor markups. |
Research Methodology
Desk research of customs trade records, EU regulatory filings, and NAFDAC registration databases preceded structured interviews with yam processing plant managers, cooperative aggregation officers, and European foodservice procurement leads. Primary fieldwork across Lagos, Ibadan, and Kumasi processing zones validated secondary data on solar dryer adoption rates and certification timelines. Bottom-up volume estimates from state-level production statistics triangulated against top-down import value flows through Rotterdam and Hamburg.
Variance decomposition across product type, end-use application, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segmented volume trajectories incorporated pharmaceutical excipient demand elasticity, EU Green Deal compliance adoption curves, and diesel price volatility impacts on Nigerian processing margins. Modeled inputs included NAFDAC registration pipeline data and EU Deforestation Regulation implementation phase-in schedules.
Material uncertainties — regulatory delay in mycotoxin threshold harmonization, diesel subsidy policy shifts in Nigeria, and cassava starch substitution acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions on cooperative consolidation rates and traceability technology penetration. Recalibration cycles align with material shifts in EU procurement criteria and West African grid infrastructure investment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
Butternut Squash Market
Vegetables
Vegetable Grader Market
Vegetables
Tanzania Fruit and Vegetables Market
Vegetables
Vegetable Chutney Market
Vegetables
Greenhouse Produce Market
Vegetables
Dried Peas Market
Vegetables
North America Christmas Tree Market
Vegetables
UAE Greenhouse Horticulture Market
Vegetables
Dried Vegetable Market
Vegetables
Air Dried Vegetables Market
Vegetables
Global Indoor Plant Market
Vegetables
Europe Christmas Tree Market
Vegetables
Japan Greenhouse Horticulture Market
Vegetables
Europe Flowers and Ornamental Plants Market
Vegetables
North America Microgreens Market
Vegetables
Cameroon Fruits and Vegetables Market