
 Europe Christmas Tree Market | 2026-2036
Europe Christmas Tree Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Christmas Tree Market Foresight
The EU Green Deal is repositioning the cost-of-entry calculus for European Christmas tree suppliers by mandating stricter sustainability credentials and traceability standards. Green Team Group A/S leverages its integrated Nordic cultivation network to meet these requirements efficiently. Dane Christmas Tree anchors its competitive stance through specialized regional sourcing across Denmark and Northern Germany. Baker Hughes Company competes in adjacent seasonal lighting and decoration infrastructure, extending its industrial manufacturing scale into consumer-facing holiday products.
Europe Christmas Trees encompass both cultivated evergreen conifers harvested for seasonal display and manufactured artificial alternatives constructed from PVC, PE, or hybrid materials with integrated lighting systems. Natural trees require soil pH between 5.5 and 6.5 and typical cultivation cycles of eight to twelve years before market readiness. Artificial tree variants dominate volume flows through online retail channels, where convenience-driven households sustain repeat-purchase behavior. Potted live trees represent the fastest-growing structural segment as urban consumers prioritize reusability and carbon footprint reduction. Specialty stores and garden centers capture premium margin pools by offering height-customized specimens and full-service installation for commercial spaces.
EMA guidelines on phytosanitary certification and the EU Green Deal's sustainable agriculture mandates shape cultivation practices and cross-border shipment protocols. REACH compliance governs chemical treatments and flame-retardant coatings applied to artificial tree materials. ECHA substance restrictions are forcing reformulation of traditional PVC blends toward bio-based polyethylene alternatives. Stakeholders must monitor evolving EUDR deforestation-free supply chain requirements and decide whether to invest in certified nursery capacity or pivot toward recycled-material artificial production lines.
Market Dynamics
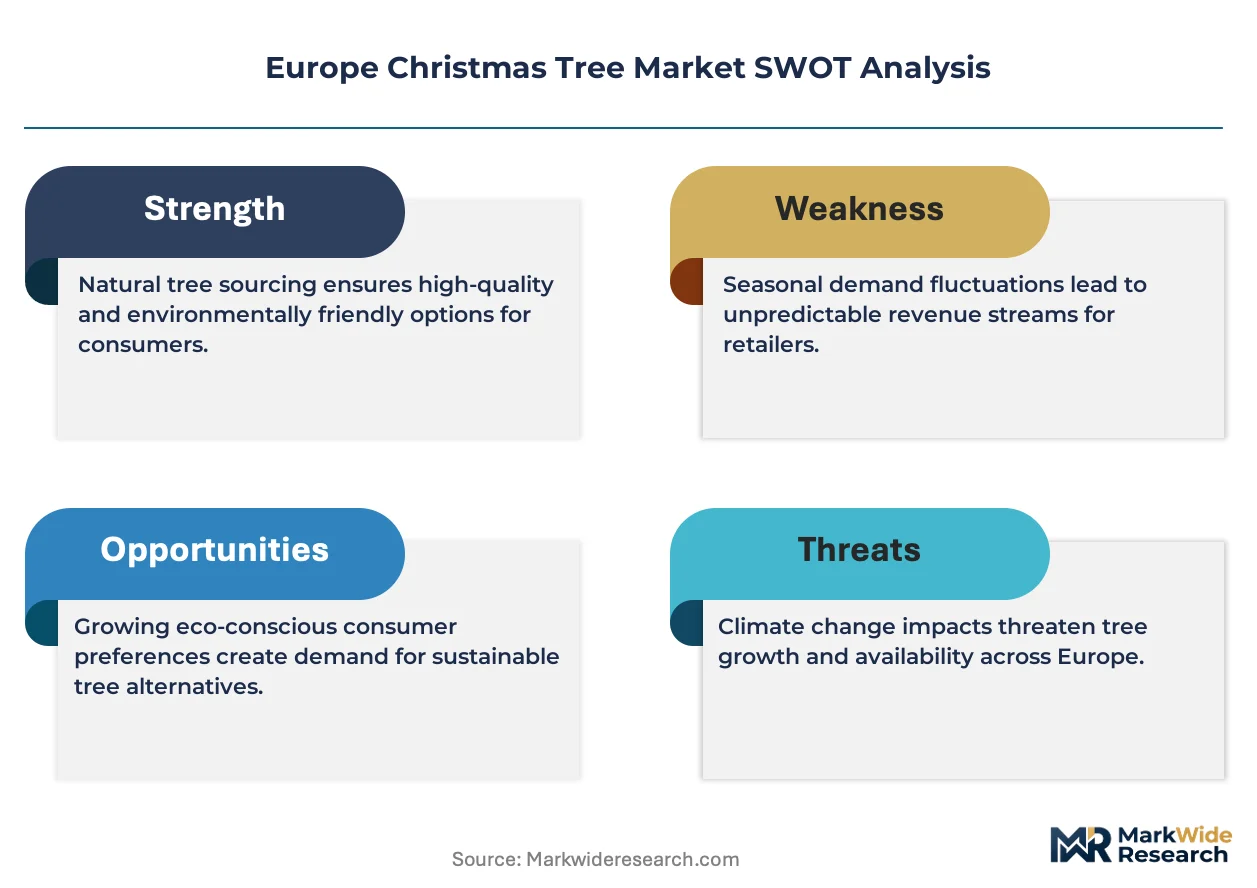
The EU Green Deal's sustainable agriculture mandates and EUDR deforestation-free supply chain requirements are restructuring cultivation economics and cross-border shipment protocols for European Christmas tree suppliers.
Growth Catalysts
- Urban Reusability Preference:Metropolitan households in France and Germany are driving potted live tree adoption as carbon footprint reduction becomes a primary purchase criterion.
- REACH Reformulation Pressure:ECHA substance restrictions on traditional PVC blends are accelerating bio-based polyethylene adoption across artificial tree manufacturing lines.
- Commercial Seasonal Décor Expansion:Retail chains and hospitality operators across the United Kingdom are increasing annual procurement volumes for height-customized specimens with installation services.
Market Restraints
- Soil pH Sensitivity:Natural tree cultivation requires sustained soil pH between 5.5 and 6.5, constraining viable growing regions and amplifying weather-related yield volatility.
- Input Cost Concentration:Fertilizer and irrigation system costs for eight-to-twelve-year cultivation cycles create capital intensity barriers for new nursery entrants.
- Cross-Border Phytosanitary Friction:EMA certification requirements for interstate shipments add documentation burden and inspection delays for Danish and Polish exporters.
Strategic Opportunities
- Spanish and Italian Nursery Underpenetration:Southern European markets show limited domestic cultivation capacity, creating import substitution potential for certified Nordic and German growers.
- Online Channel Infrastructure:Artificial tree volume flows through digital retail platforms remain underdeveloped for premium potted live categories, offering first-mover positioning.
- CSRD Sustainability Reporting:Corporate sustainability disclosure mandates are creating procurement preference for suppliers with traceable cultivation certification and carbon accounting systems.
Industry Challenges
- Skilled Cultivation Labor Scarcity:Eight-to-twelve-year production cycles require specialized agronomic expertise in pruning, disease management, and harvest timing that aging rural workforces struggle to replenish.
- Dual Certification Timeline Compression:Suppliers must simultaneously achieve EUDR deforestation-free verification and EU organic labeling, stretching compliance resources across overlapping audit schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Christmas Tree Market |
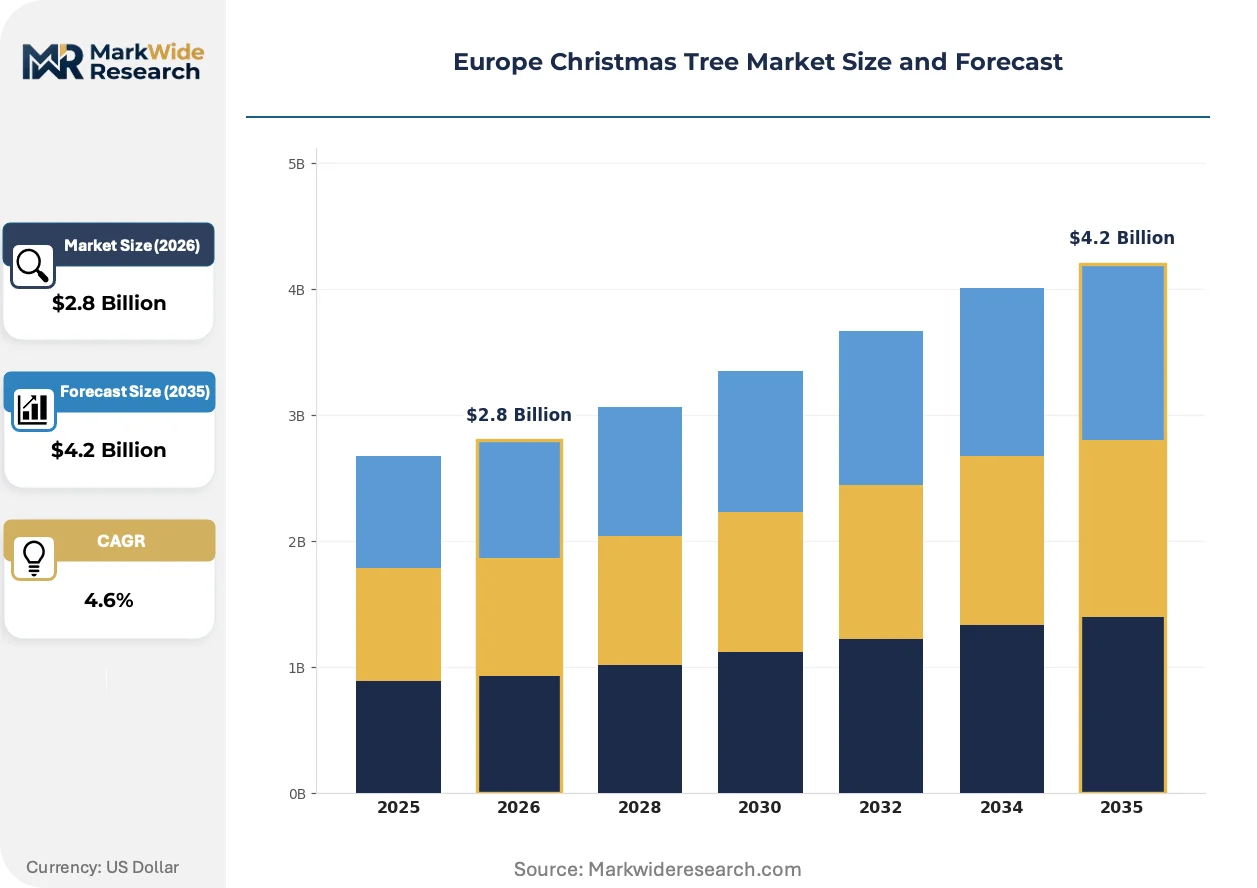
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Tree Type: Artificial, Natural, Potted, Fiber Optic End User: Households, Commercial Spaces, Institutions, Event Organizers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Garden Centers Tree Height: Under 4 Feet, 4-7 Feet, 7-9 Feet, Over 9 Feet |
| Companies Covered | Aker Solutions ASA, Shengji Group, TechnipFMC PLC, Green Team Group A/S, Dril-Quip Inc., Baker Hughes Company, Worldwide Oilfield Machine, Dane Christmas Tree, Schlumberger Limited, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Christmas Tree Market Shifts & Advancements
Technology convergence between bio-based materials and integrated lighting systems is compressing product development cycles. Regulatory pressure on chemical formulations is forcing material science pivots. Distribution channel fragmentation is reshaping how seasonal inventory reaches end buyers.
LED-integrated artificial trees with programmable color temperature and smartphone control are integrating lighting hardware directly into PE branch structures. German and Austrian retailers are piloting these systems for commercial installations. This convergence is integrating decorative functionality with energy efficiency specifications, compressing the traditional separation between lighting and tree procurement decisions.
REACH compliance deadlines for flame-retardant coating reformulation are forcing PVC-to-polyethylene transitions across artificial tree production lines. Manufacturers serving the United Kingdom and Benelux markets face the most compressed implementation timelines. The ECHA restriction on halogenated compounds is driving bio-based alternative testing at specialized polymer research facilities in the Netherlands and Denmark.
Urban households in Paris, Berlin, and London are compressing purchase timelines toward November pre-ordering through subscription-style services. Garden centers are responding with reserved specimen programs and delivery scheduling. This behavioral shift is most visible among millennial and Generation Z buyers prioritizing convenience over in-person selection.
Europe Christmas Tree Market Segmentation
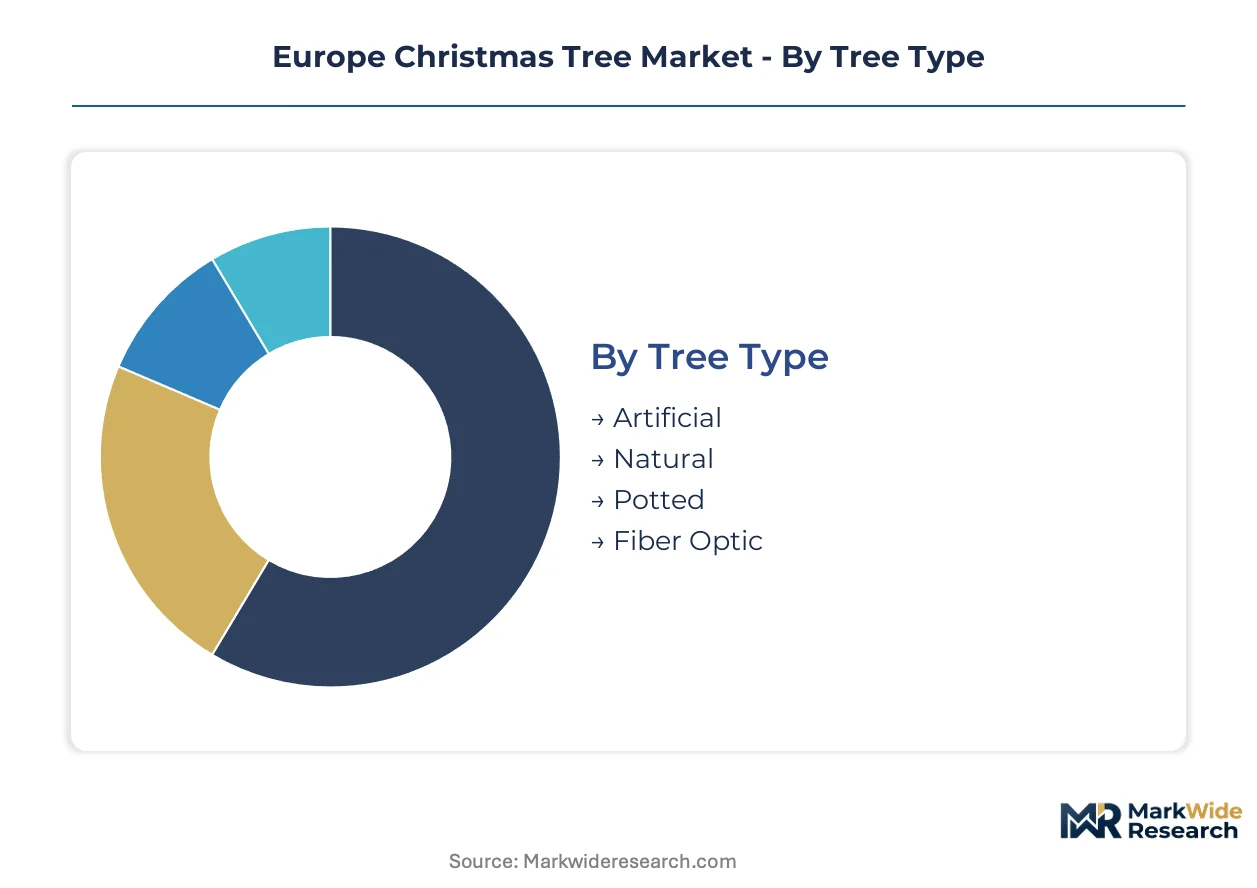
Segmentation in the Europe Christmas Tree Market reveals how regulatory requirements, distribution economics, and end-use specifications fragment procurement behavior. Each dimension carries distinct certification burdens and margin structures that reshape supplier positioning across the region.
Tree Type:
REACH compliance timelines and EUDR deforestation-free verification requirements split certification intensity across artificial versus natural cultivation pathways.
- Artificial:PVC and polyethylene constructions dominate manufacturing output. United Kingdom and Benelux retailers face compressed REACH deadlines for flame-retardant coating reformulation, accelerating bio-based polyethylene transitions at Dutch polymer research facilities.
- Natural:Cultivated evergreen conifers require EMA phytosanitary certification for cross-border shipment. German and Danish exporters absorb documentation burdens and inspection delays that constrain Polish nursery volume flows into Southern European markets.
- Potted:Reusable live specimens with root systems intact. Paris and Berlin urban households prioritize carbon footprint reduction through repeat-season adoption.
- Fiber Optic:LED-integrated constructions with pre-wired illumination. German and Austrian retailers pilot programmable color temperature systems for commercial installations.
Leading the category by volume: Artificial. Growing fastest: Potted.
End User:
Procurement scale and installation service requirements separate household convenience purchasing from commercial specification-driven contracts.
- Households:Convenience-driven repeat purchasing concentrates through online retail channels. Millennial and Generation Z buyers in London and Paris compress timelines toward November pre-ordering through subscription-style services.
- Commercial Spaces:Retail chains and hospitality operators across the United Kingdom procure height-customized specimens with full-service installation. Annual budget expansion for seasonal décor sustains premium margin capture at garden centers.
- Institutions:Municipal and educational buyers with formal procurement protocols. CSRD sustainability reporting mandates create preference for traceable cultivation certification and carbon accounting systems.
- Event Organizers:Temporary installation requirements with compressed deployment timelines. Demand concentrates in December peak periods with limited storage economics.
Households anchor volume absorption. Commercial spaces command steepest expansion trajectory.
Distribution Channel:
Channel selection determines margin retention, inventory risk allocation, and customer relationship depth across the seasonal purchase window.
- Online Retail:Artificial tree volume flows dominate digital platforms. Premium potted live categories remain underdeveloped, offering first-mover positioning for nursery operators with logistics infrastructure.
- Supermarkets:Mass-market artificial and cut natural specimens with price-competitive positioning. Limited height customization and no installation services constrain premium capture.
- Specialty Stores:Height-customized specimens with full-service installation for commercial spaces. German and French operators capture premium margin pools through specimen reservation programs.
- Garden Centers:Potted live tree specialization with delivery scheduling. Reserved specimen programs respond to urban household pre-ordering compression in Berlin and London.
Specialty stores lead margin extraction. Online retail gains share fastest.
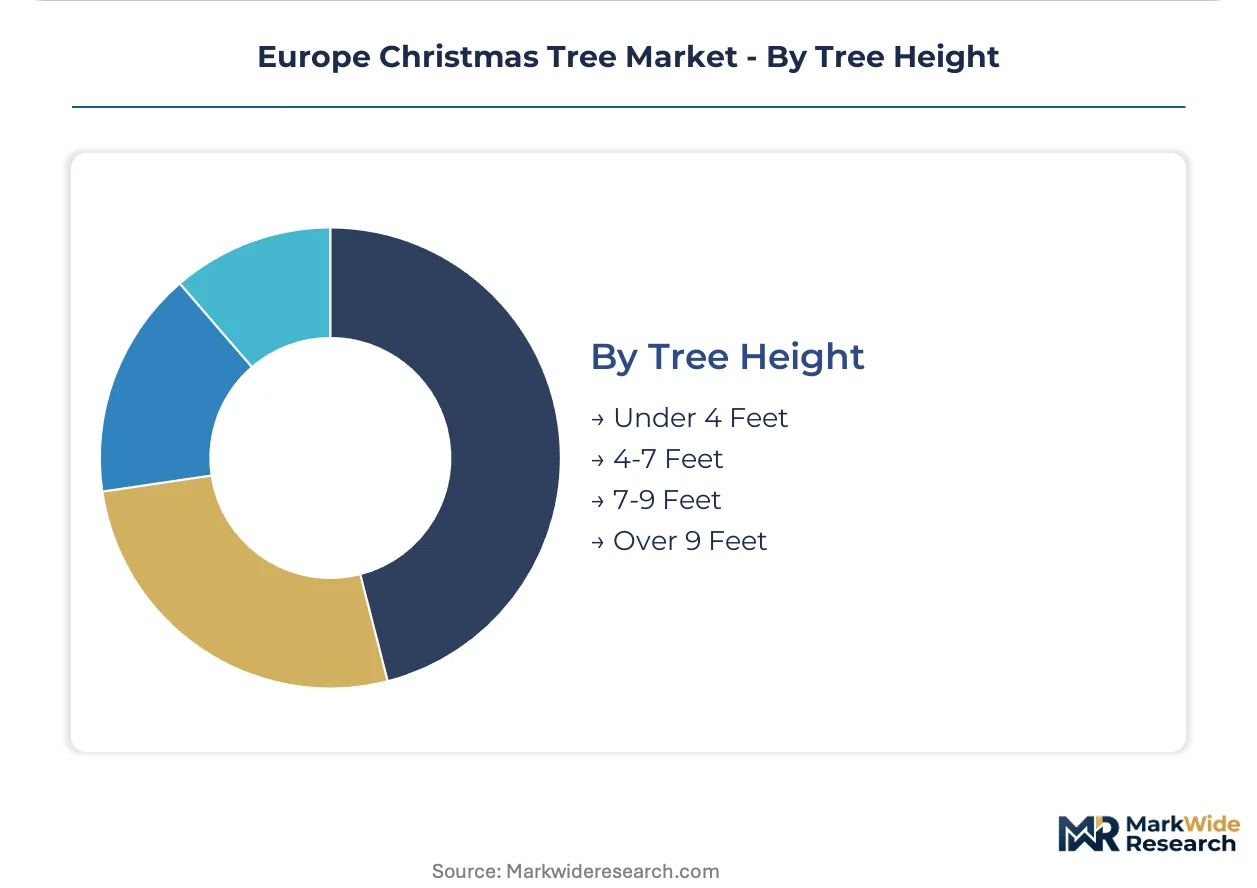
Tree Height:
Height specification drives cultivation cycle economics, shipping logistics complexity, and installation service requirements.
- Under 4 Feet:Compact artificial and potted specimens for apartment dwellers. Urban density in Paris and London sustains demand concentration.
- 4-7 Feet:Standard household dimensions dominating natural tree harvest profiles. Eight-to-twelve-year cultivation cycles in German and Danish nurseries align with this specification band.
- 7-9 Feet:Commercial lobby and retail atrium installations. United Kingdom hospitality operators drive procurement with full-service installation requirements.
- Over 9 Feet:Monumental specimens for institutional and flagship retail deployments. Limited cultivation supply and specialized handling equipment constrain competitive entry.
4-7 Feet commands volume leadership. 7-9 Feet climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Denmark's Nordic Nursery Zone concentrates specialized cultivation infrastructure for export-grade specimens. German federal states subsidize organic conversion under the EU Green Deal framework. French metropolitan clusters drive premium potted live adoption.
Germany
Commercial hospitality operators in Berlin and Munich expand annual procurement for height-customized installations. The EU Green Deal's sustainable agriculture mandates require EUDR deforestation-free verification for cross-border shipments. Lower Saxony nurseries absorb compliance costs while scaling certified organic capacity.
United Kingdom
Retail chains and hotel groups compress procurement timelines toward November pre-ordering. REACH compliance deadlines for flame-retardant coating reformulation accelerate bio-based polyethylene transitions. London garden centers pilot subscription-style reserved specimen programs for millennial households.
France
Paris urban households prioritize carbon footprint reduction through repeat-season potted live adoption. EMA phytosanitary certification requirements add documentation burden for interstate nursery shipments. Île-de-France specialty stores capture premium margin pools through full-service installation contracts.
Denmark
Export-oriented cultivation networks supply German and British retail channels with EUDR-verified specimens. Danish agronomic expertise in eight-to-twelve-year production cycles constrains rapid capacity expansion. Jutland Peninsula nurseries face skilled labor scarcity as aging rural workforces retire.
Poland
Emerging nursery operations target Southern European import substitution for Spanish and Italian markets. Cross-border phytosanitary friction with EMA certification delays constrains volume growth. Silesian and Greater Poland regions develop irrigation infrastructure for soil pH-sensitive cultivation zones.
Europe Christmas Tree Market Competitive Landscape
Nordic producers anchor the export-grade natural cultivation tier; Central European specialists hold proximity advantages for commercial installation services. Market structure fragments across integrated cultivation networks, regional sourcing specialists, and industrial-scale artificial manufacturers. Three archetypes dominate: certified organic nursery operators, PVC-to-polyethylene transition specialists, and full-service commercial installers. Competitive moves concentrate on EUDR certification acquisition and online channel infrastructure buildout.
Within the integrated cultivation network tier, Green Team Group A/S exemplifies Nordic scale advantages through its Denmark-based operations. Dane Christmas Tree occupies a position among regional sourcing specialists with concentrated Denmark and Northern Germany coverage. Baker Hughes Company sits within the industrial manufacturing archetype, extending equipment production capabilities into adjacent seasonal decoration infrastructure.
| Leading Market Players |
|---|
| Aker Solutions ASA |
| Shengji Group |
| TechnipFMC PLC |
| Green Team Group A/S |
| Dril-Quip Inc. |
| Baker Hughes Company |
| Worldwide Oilfield Machine |
| Dane Christmas Tree |
| Schlumberger Limited |
| Others |
Supply & Pricing Matrix
Family-owned Danish and German nursery operations anchor the mid-tier cultivation segment, translating eight-to-twelve-year production cycles into disciplined pricing power that resists spot-market volatility. Their patient capital structure enables withholding inventory during price troughs, tightening supply availability for United Kingdom and French commercial buyers during compressed November procurement windows.
Pricing Analysis
Short lead-time premiums dominate transaction economics, with November pre-orders commanding 15-25% markups over spot purchases in December. Three-tier pricing structure across premium EUDR-certified organic, standard phytosanitary-compliant, and economy cut-specimen levels separates buyer segments. Cost compression in the economy tier is intensifying because Polish nurseries flood Southern European channels with unbranded volume. Commercial hospitality operators show least price sensitivity, while metropolitan households in Berlin and Paris exhibit highest elasticity.
Supply Chain Analysis
Returns and refurbishment flows for potted live specimens create reverse-logistics infrastructure demands that Danish garden centers have pioneered through subscription renewal programs. Cultivation concentrates in Denmark, Germany, and Poland, drawing from specialized agronomic labor pools and irrigation-dependent soil management. Supply chain risk centers on EMA phytosanitary inspection delays at cross-border checkpoints. Distribution runs through specialty store networks for premium specimens, while artificial tree volume feeds direct-to-consumer online platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Eight-to-twelve-year cultivation cycles constrain rapid capacity expansion, embedding structural supply scarcity that protects pricing for certified organic operators. This bottleneck justifies patient capital deployment behind EUDR-verified nursery networks.
For Market Incumbents: Anchor defensive positioning through backward integration into propagation stock and controlled-environment cultivation infrastructure. Consolidate fragmented Polish nursery capacity before EUDR compliance costs escalate. Threat substitution from bio-based polyethylene artificial trees demands accelerated organic certification investment to maintain margin separation. For New Entrants and Emerging Players: LED-integrated fiber optic systems with smartphone-controlled color temperature offer a technology-first wedge into the underserved premium artificial segment. White-space concentration sits in Spanish and Italian markets lacking domestic cultivation capacity. Target online channel infrastructure for potted live tree subscription services as the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale Danish nursery operators with established EUDR documentation systems and aging ownership succession timelines. Long-term viability over the next decade hinges on traceable carbon accounting capabilities that satisfy CSRD procurement mandates. Watch for ECHA substance restriction acceleration on halogenated compounds as the inflection signal triggering PVC-to-polyethylene transition investment.| Strategic Initiative | Industry Significance |
|---|---|
| EUDR Certification Acquisition | Deforestation-free verification unlocks United Kingdom and German commercial procurement contracts under EU Green Deal mandates. |
| Online Channel Infrastructure Buildout | Reserved specimen programs with delivery scheduling capture millennial household pre-ordering compression in Paris and Berlin. |
| Bio-based Polyethylene Transition | REACH-compliant flame-retardant coatings secure Benelux market access ahead of ECHA restriction enforcement. |
| Vertical Cultivation Network Integration | Controlled-environment propagation reduces soil pH sensitivity and compresses time-to-market for premium specimens. |
| CSRD-Aligned Carbon Accounting Systems | Traceable cultivation certification satisfies institutional procurement preference under corporate sustainability disclosure mandates. |
Research Methodology
Multi-period observation of nursery capacity utilization rates, EUDR certification timelines, and cross-border shipment volumes anchored the trend analysis, supplemented by interviews with Danish nursery operators, German garden center procurement directors, United Kingdom hospitality facilities managers, Dutch polymer research scientists, and French metropolitan household buyers. Secondary validation drew from EMA phytosanitary databases, ECHA substance restriction filings, EU Green Deal implementation reports, and customs trade flow records. Bottom-up cultivation cost modeling and top-down retail revenue triangulation converged on segment-level estimates.
Input-output matrices mapped cultivation cycle economics against distribution channel margin structures across the projection horizon. Segmentation dimensions modeled included tree type, end user archetype, distribution channel, and tree height specification. CAGRs derived from regression analysis of historical volume flows and regulatory-driven demand shifts. Industry-specific forecast inputs incorporated soil pH suitability indices and skilled agronomic labor availability projections.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EUDR enforcement acceleration or severe weather disruption in Lower Saxony cultivation zones. Material deviation in ECHA substance restriction timelines or EU Green Deal subsidy reallocation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
Garlic Market
Vegetables
Canada Microgreens Market
Vegetables
Greenhouse Bell Pepper Market
Vegetables
Global Indoor Plant Market
Vegetables
Microgreens Market
Vegetables
Yams Market
Vegetables
Turkey Greenhouse Horticulture Market
Vegetables
Dried Mushroom Market
Vegetables
Fresh Vegetables Market
Vegetables
Australia Greenhouse Horticulture Market
Vegetables
Dry Onion Market
Vegetables
Japan Greenhouse Horticulture Market
Vegetables
Yam Products Market
Vegetables
Dried Vegetable Market
Vegetables
Greenhouse Produce Market
Vegetables
Zimbabwe Fruits and Vegetables Market