
 Fresh Onions and Shallots Market | 2026-2036
Fresh Onions and Shallots Market Size, Share, and Industry Trends Forecast 2026-2036
Fresh Onions and Shallots Market Analytics
Food service operators are rotating toward shallot-intensive cuisines, pulling demand away from traditional household bulk purchasing. Gills Onions leverages vertical integration from field to sliced-product lines for national restaurant chains. T&G Global anchors supply through controlled-atmosphere storage networks across Oceania. Peri & Sons Farms differentiates via organic certification and direct-to-retail channel control in North American premium segments.
Fresh onions and shallots comprise mature bulb vegetables of the Allium genus, harvested with intact fleshy scales and marketed within weeks of field collection to preserve pyruvic acid content and pungency indices for culinary applications. Yellow onions dominate volume through food manufacturing demand for dehydrated and frozen ingredient streams, while shallots command margin concentration in retail and food service channels due to labor-intensive cultivation and shorter shelf stability. Bulk packing still controls farmgate economics, though tray and bag formats expand in retail as supermarkets reduce backroom handling.
The USDA's Agricultural Marketing Service enforces grade standards for bulb shape and skin retention that determine access to federally procured school nutrition programs. The EU's REACH framework and residue monitoring by EFSA shape import eligibility for third-country suppliers. India's FSSAI and DGFT jointly regulate minimum export quality specifications for Bangladesh and Southeast Asian destinations. Stakeholders must monitor divergence between domestic food safety thresholds and importer MRL schedules when allocating crop across destination markets.
Market Dynamics
Food service procurement is rotating toward shallot-intensive cuisines while the EU's Farm to Fork Strategy tightens pesticide residue thresholds for imported bulb vegetables, compressing supplier margins and rewiring trade flows toward certified domestic production.
Growth Catalysts
- EU Green Deal residue mandates:The Farm to Fork Strategy under the European Green Deal is tightening maximum residue limits for imported bulb vegetables, accelerating investment in domestic European cultivation and controlled-atmosphere storage infrastructure.
- Food service premiumization:Restaurant chains are expanding shallot procurement for chef-driven menu applications, pulling demand away from commodity yellow onion contracts toward higher-margin specialty bulb categories.
- India's export-grade processing demand:Bangladesh and Southeast Asian destinations are absorbing expanded Indian processing-grade onion shipments, driven by FSSAI and DGFT quality specifications that formalize trade eligibility.
Market Restraints
- Input cost volatility:Labor-intensive shallot cultivation faces rising wage pressure in manual harvesting regions, squeezing farmgate economics against mechanized yellow onion competitors.
- Supply concentration risk:Controlled-atmosphere storage networks concentrate in Oceania and select European nodes, creating single-point vulnerability for counter-seasonal supply continuity.
- Regulatory friction:Divergence between USDA Agricultural Marketing Service grade standards and EFSA residue monitoring creates compliance complexity for multi-destination exporters.
Strategic Opportunities
- Organic certification premiums:North American retail channels are absorbing price premiums for certified organic shallots, rewarding growers who bypass conventional pesticide regimens entirely.
- Tray-format retail penetration:Supermarket backroom reduction initiatives are opening shelf space for consumer-packaged onion formats, displacing traditional bulk bins in urban store formats.
- Processing-grade export formalization:India's FSSAI export specifications for Bangladesh create template compliance frameworks that adjacent Southeast Asian markets are adopting.
Industry Challenges
- Post-harvest pyruvic acid retention:Maintaining pungency indices through cold chain handoffs requires precise temperature logging that many regional distributors lack.
- Multi-jurisdiction MRL alignment:Exporters must reconcile USDA, EFSA, and destination-country residue schedules when allocating single harvest lots across fragmented destination markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fresh Onions and Shallots Market |
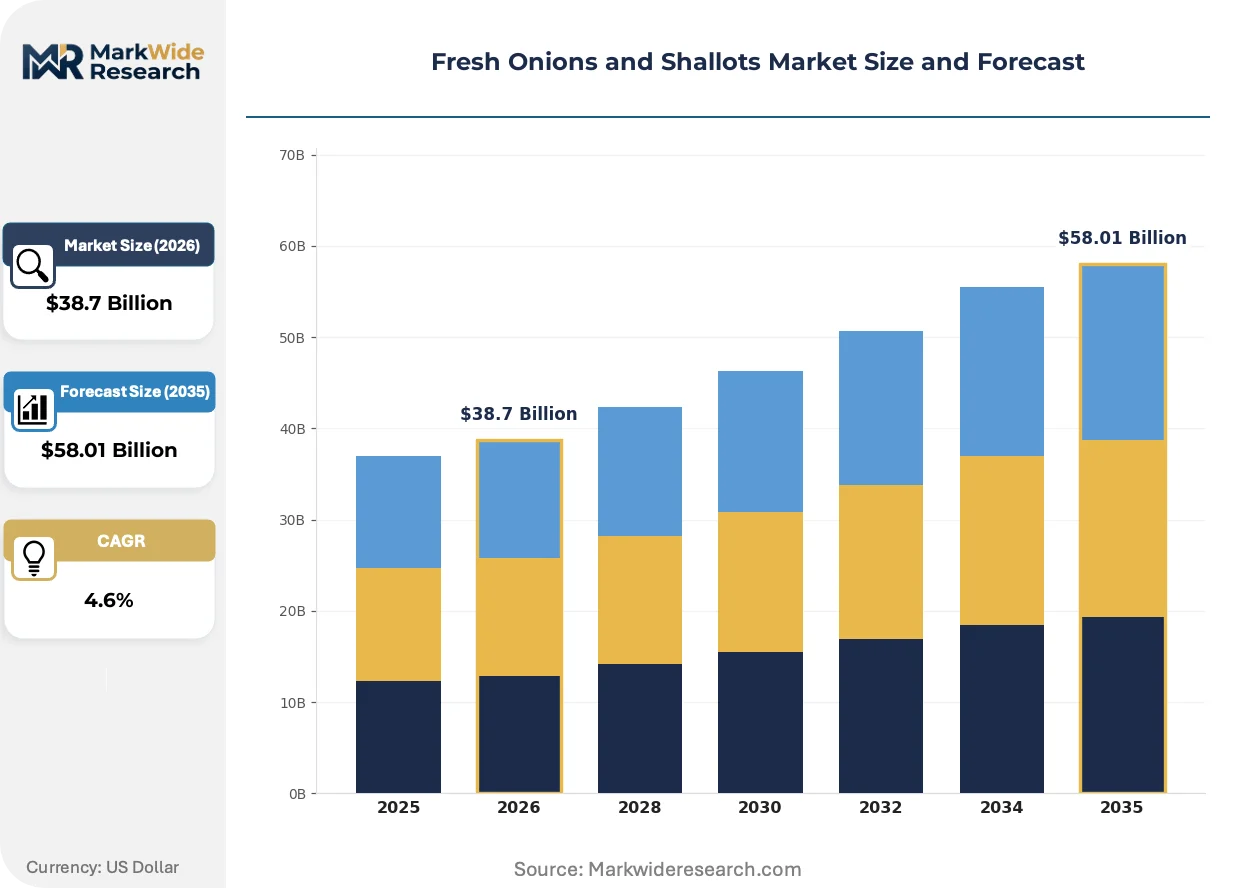
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $58.01 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yellow Onions, Red Onions, White Onions, Shallots Distribution Channel: Wholesale, Retail, Online, Direct Sales Packing Type: Bags, Boxes, Bulk, Trays End User: Household, Food Service, Food Manufacturing, Exporters |
| Companies Covered | River Point Farms, Gills Onions, T&G Global, Murakami Produce Company LLC, Peri & Sons Farms, Snake River Produce, JC Watson Company, Global Green Company, Vladam, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fresh Onions and Shallots Market Evolving Landscape
Controlled-atmosphere storage technology is reshaping seasonal availability patterns while regulatory divergence between major importing blocs is forcing compliance infrastructure investment. Buyer behavior is compressing traditional wholesale channels.
Modified atmosphere packaging is miniaturizing shelf-life extension from bulk warehouse scale to retail-ready pouches. National restaurant chains are adopting pre-sliced shallot products packaged in nitrogen-flushed films. This technology is miniaturizing the cold storage footprint required for national distribution, enabling regional processors to compete against integrated field-to-slice operators.
REACH framework amendments are tightening substance authorization for post-harvest treatments used on imported bulb vegetables. European importers are demanding batch-level residue documentation that exceeds domestic farmgate testing protocols. Third-country suppliers serving EU destinations are consolidating testing contracts with EFSA-recognized laboratories to preempt border rejection.
Direct-to-retail channel control is displacing traditional produce auction systems in premium shallot segments. Organic-certified growers in California's Central Valley are bypassing terminal markets to contract directly with supermarket chains. This pattern concentrates most visibly in North American metropolitan markets where retailers operate dedicated fresh procurement teams.
Fresh Onions and Shallots Market Segmentation
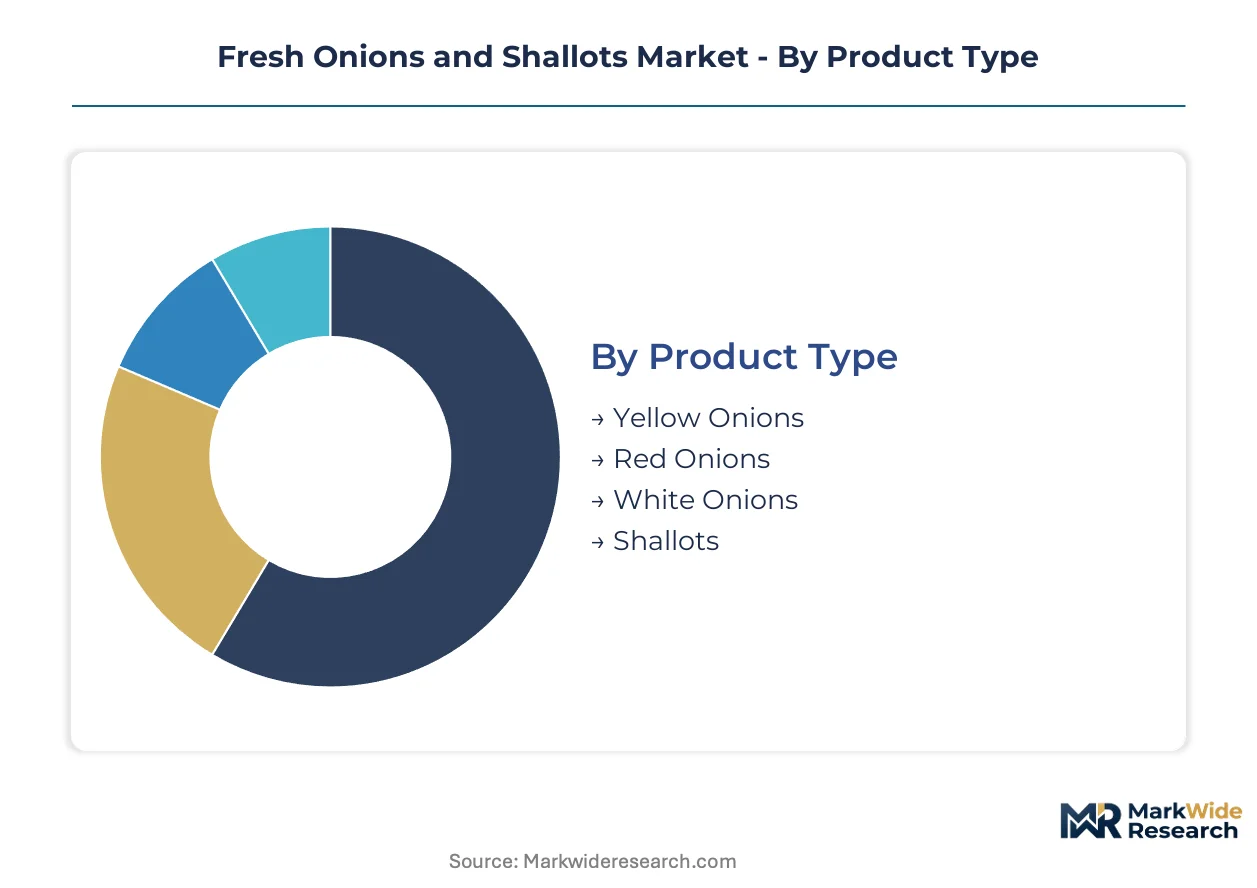
Segmentation in fresh bulb vegetables determines margin capture through channel control. Product type and packing format decisions cascade through distribution economics, while end-user concentration shapes harvest allocation and storage investment priorities.
Product Type:
Channel-mix patterns diverge sharply across bulb categories, with commodity volumes flowing through wholesale and food manufacturing while specialty grades command retail and direct-sale premiums.
- Yellow Onions:High-pungency varieties with elevated pyruvic acid content serve dehydration and frozen ingredient streams. Food manufacturing demand in India and the United States absorbs the bulk of harvest volume, with processors specifying tight diameter ranges for mechanical peeling compatibility.
- Shallots:Labor-intensive cultivation yields clustered bulbs with delicate skin and concentrated flavor compounds. Restaurant chains in France and California are expanding shallot procurement for chef-driven applications, pulling allocation away from household bulk channels toward premium food service contracts.
- Red Onions:Anthocyanin pigmentation drives retail preference for fresh applications. Supermarket chains in Germany and the United Kingdom favor red varieties for consumer-packaged tray formats.
- White Onions:Lower pungency and crisp texture suit raw consumption in Mexican and Central American cuisines. Exporters from Mexico and Peru target U.S. Southwest and Florida retail channels with white onion shipments.
Yellow onions dominate installed base. Shallots are where expansion concentrates.
Distribution Channel:
Cost-tier stratification separates commodity handlers from premium channel operators, with margin capture hinging on cold chain control and residue documentation capabilities.
- Wholesale:Terminal markets and produce auctions still handle the majority of yellow onion volume. Dutch auction systems at Bleiswijk and Rungis set reference pricing for European wholesale trade, though direct contracting is eroding their share in shallot categories.
- Retail:Supermarket backroom reduction initiatives are compressing traditional wholesale intermediaries. Chains in the United Kingdom and Australia are expanding direct-procurement teams for packaged onion lines, bypassing regional distributors.
- Online:E-commerce penetration remains limited by perishability and last-mile temperature control costs. Indian quick-commerce platforms are experimenting with 30-minute delivery windows for household onion packs in Mumbai and Bangalore.
- Direct Sales:Organic-certified growers in California's Central Valley and Provence are contracting directly with restaurant groups and specialty retailers. This channel captures the highest farmgate prices but requires batch-level residue documentation that exceeds conventional wholesale protocols.
Wholesale channels retain volume leadership. Direct sales are climbing the fastest.
Packing Type:
Application-driven format selection separates industrial-scale handlers from retail-ready packagers, with automation investment determining competitive position.
- Bulk:Loose jumble packing in 25-50kg sacks dominates farmgate economics for processing-grade shipments. Indian exporters to Bangladesh and Malaysia rely on bulk formats for cost-sensitive destination markets.
- Bags:Consumer-packaged mesh and poly bags are displacing loose bins in urban European retail. French supermarket chains are mandating standardized 1kg and 2kg bag formats to reduce backroom labor.
- Boxes:Corrugated containers with ventilation apertures serve food service and intermediate processing. National restaurant chains in the United States specify box formats with traceability coding for supply chain verification.
- Trays:Modified-atmosphere retail trays command shelf-space premiums in metropolitan markets. Australian and New Zealand supermarkets are expanding tray-format shallot offerings to reduce shrink and extend display life.
Bulk packing dominates installed base. Tray formats are gaining share fastest.
End User:
Customer-type concentration shapes harvest timing and storage duration decisions, with divergent quality specifications forcing segmentation in cultivation and post-harvest handling.
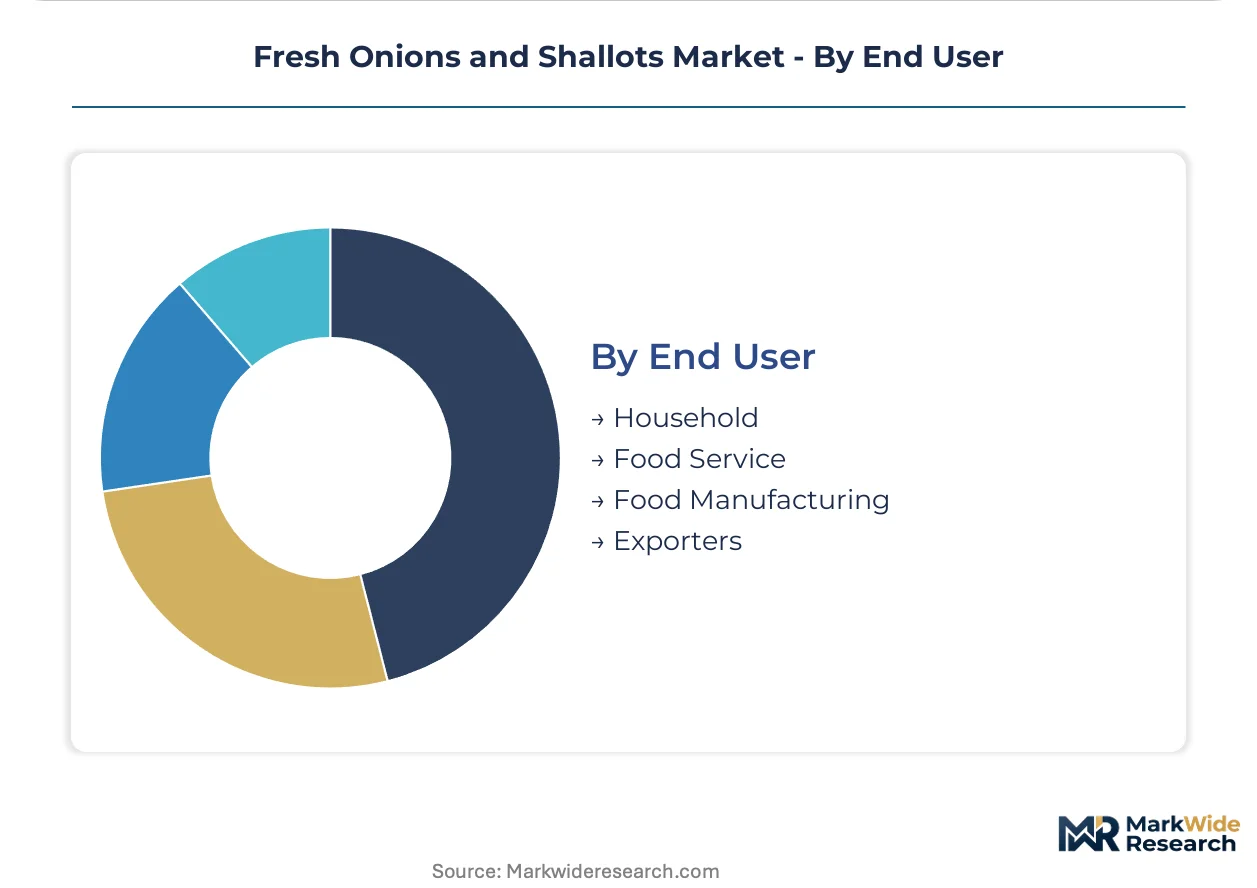
- Food Manufacturing:Dehydration and frozen food processors specify tight solids content and pungency ranges. Yellow onion supply contracts in India and the United States include penalty clauses for pyruvic acid deviation.
- Food Service:Restaurant chains and institutional caterers demand consistent bulb size and peelability for labor efficiency. Pre-sliced shallot products packaged in nitrogen-flushed films are penetrating national chain procurement in France and the United States.
- Household:Traditional bulk purchasing is compressing as urban consumers shift toward convenience formats. Indian household demand remains price-sensitive, with onion price spikes triggering political intervention.
- Exporters:Third-country suppliers serving EU destinations must consolidate testing contracts with EFSA-recognized laboratories. Bangladesh and Southeast Asian markets are absorbing expanded Indian processing-grade shipments under FSSAI and DGFT quality specifications.
Food manufacturing dominates installed base. Food service is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India ships processing-grade onions to Bangladesh and Southeast Asian markets under FSSAI and DGFT quality specifications, while EU importers pivot toward domestic European cultivation as Farm to Fork Strategy residue mandates tighten eligibility for third-country suppliers.
United States
Food manufacturing demand for yellow onion dehydration absorbs harvest volume from California's Central Valley and Idaho growing regions. The USDA Agricultural Marketing Service enforces grade standards determining access to federally procured school nutrition programs. Gills Onions operates integrated field-to-slice processing lines for national restaurant chains from its California base.
India
Domestic household consumption and processing-grade export demand to Bangladesh and Malaysia both expand, with onion price volatility triggering periodic political intervention. FSSAI and DGFT jointly regulate minimum export quality specifications for regional destinations. Nashik and Maharashtra growing clusters supply both domestic mandis and containerized export shipments to Southeast Asia.
France
Restaurant chains in Paris and Lyon expand shallot procurement for chef-driven menu applications, pulling allocation from household bulk channels. The EU Farm to Fork Strategy under the European Green Deal tightens pesticide residue thresholds for imported bulb vegetables. Provence-based organic growers bypass terminal markets to contract directly with supermarket chains.
Germany
Supermarket chains favor red onion varieties for consumer-packaged tray formats in urban retail formats. EFSA residue monitoring and REACH framework amendments shape import eligibility requirements for third-country suppliers. Bleiswijk auction systems still set reference pricing for European wholesale trade, though direct contracting erodes share in specialty categories.
Australia
Supermarkets expand tray-format shallot offerings to reduce shrink and extend display life in metropolitan Sydney and Melbourne stores. Controlled-atmosphere storage networks anchor counter-seasonal supply continuity across Oceania. T&G Global operates storage infrastructure enabling year-round availability for domestic retail and food service channels.
Fresh Onions and Shallots Market Competitive Landscape
Player mix skews toward vertically integrated field operators and regional storage specialists, with concentration in California, Idaho, and Oceania growing regions. Structure tiers between scale-driven commodity processors and premium-channel organic specialists. Dominant competitive moves include backward integration into controlled-atmosphere storage and direct-to-retail contracting bypassing wholesale intermediaries.
Among North American integrated operators, Gills Onions and Peri & Sons Farms exemplify divergent archetypes: the former anchors supply through captive processing infrastructure for food service chains, while the latter occupies a position within premium organic segments via certification and direct retail channel control. T&G Global represents the Oceania storage-network model, with controlled-atmosphere infrastructure enabling counter-seasonal distribution. River Point Farms and Murakami Produce Company LLC sit within the regional volume-processor tier, supplying commodity yellow onions to dehydration and frozen ingredient streams.
| Leading Market Players |
|---|
| River Point Farms |
| Gills Onions |
| T&G Global |
| Murakami Produce Company LLC |
| Peri & Sons Farms |
| Snake River Produce |
| JC Watson Company |
| Global Green Company |
| Vladam |
| Others |
Value Network & Pricing Analysis
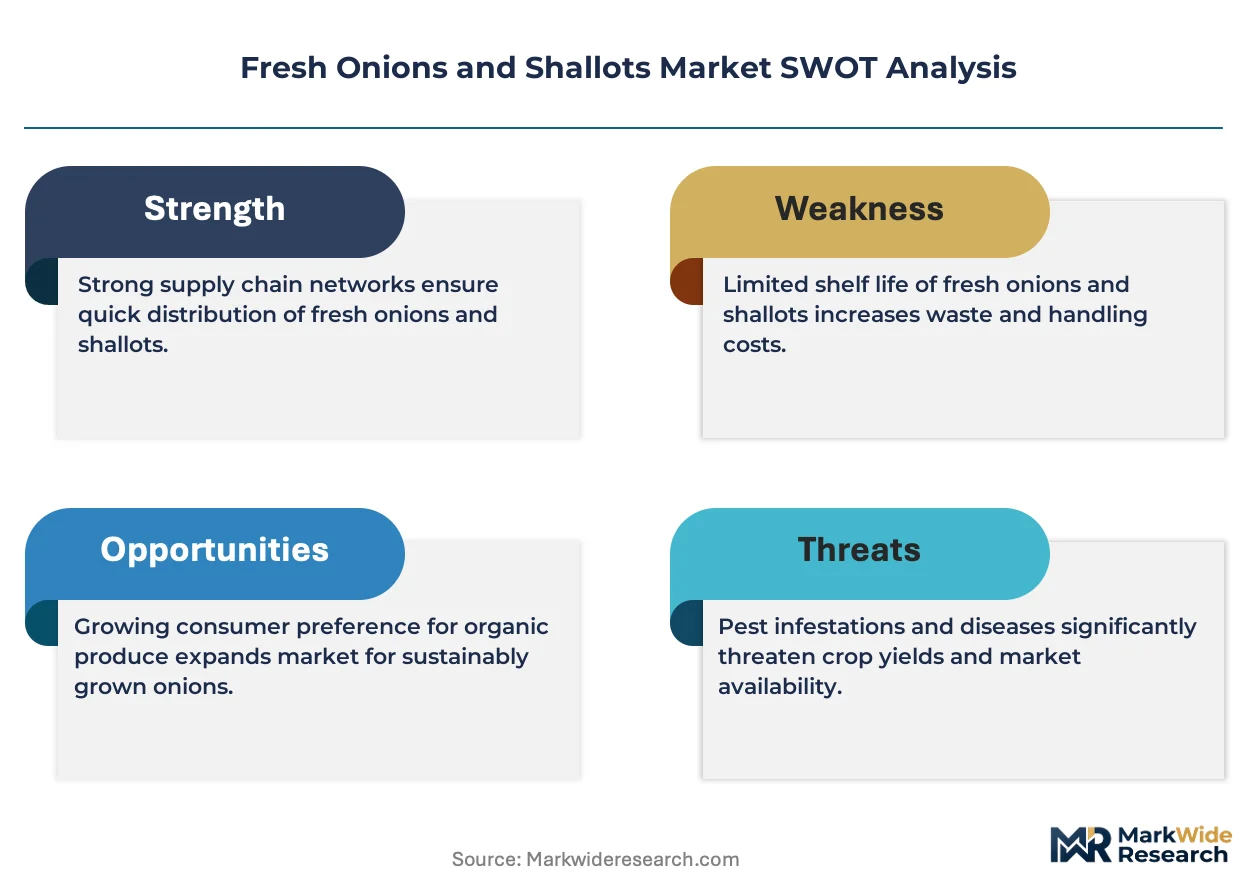
EU REACH framework amendments and EFSA residue monitoring protocols gate both supply qualification and price differentiation simultaneously, forcing third-country exporters to consolidate testing contracts with recognized laboratories while European domestic growers capture organic certification premiums. This regulatory bifurcation concentrates margin capture among certified operators who can bypass border rejection risk.
Pricing Analysis
Prior-generation bulk packing in 25-50kg sacks anchors farmgate economics for processing-grade yellow onions, while current-generation modified-atmosphere tray formats command retail shelf-space premiums, and next-generation nitrogen-flushed pre-sliced shallot products target food service contract escalation. Three-tier pricing structure across premium organic shallots, standard retail tray formats, and economy bulk processing grades separates margin capture by certification level and cold chain investment. Price erosion runs through conventional wholesale channels as supermarket backroom reduction initiatives compress intermediary margins. Food manufacturing buyers exhibit highest price sensitivity due to mechanical peeling compatibility specifications and penalty clauses for quality deviation, while direct-to-retail organic channels absorb premiums with least elasticity.
Supply Chain Analysis
India and the Netherlands anchor processing-grade onion volume for dehydration and frozen ingredient streams, while France and California's Central Valley concentrate shallot cultivation for premium food service and retail channels, and Australia provides counter-seasonal supply continuity through controlled-atmosphere infrastructure. Raw material dependencies center on labor-intensive manual harvesting for shallot clusters, pyruvic acid retention through temperature-controlled storage, and nitrogen-flushed film packaging for shelf-life extension. Single-point vulnerability concentrates in Oceania and select European controlled-atmosphere storage nodes, threatening counter-seasonal continuity. Distribution runs through direct-procurement teams at national restaurant chains and supermarket consolidation, bypassing traditional terminal market auction systems in premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fresh bulb vegetables sit in early-cycle expansion as food service operators rotate procurement toward shallot-intensive cuisines, with restaurant chain adoption of pre-sliced nitrogen-flushed products representing a penetration tailwind not yet saturated in North American and European metropolitan markets.
For Market Incumbents: Shield margin position by deepening backward integration into controlled-atmosphere storage infrastructure across California and Oceania growing regions, and accelerate organic certification coverage to preempt EU Farm to Fork Strategy residue threshold compression. Labor cost inflation in manual shallot harvesting regions threatens farmgate economics against mechanized yellow onion competitors, making automation investment in peeling and slicing lines the priority defensive lever. For New Entrants and Emerging Players: Differentiate on direct-to-retail channel control by contracting with supermarket chains operating dedicated fresh procurement teams in North American metropolitan markets, bypassing terminal market intermediaries entirely. White-space concentration sits in organic-certified shallot supply to French and California restaurant groups, with tray-format retail penetration in Australian and New Zealand supermarkets offering secondary entry. Go-to-market positioning should anchor in batch-level residue documentation exceeding conventional wholesale protocols. For Investors and Strategic Acquirers: EU Farm to Fork Strategy residue mandate implementation reshapes the acquisition landscape toward certified domestic European cultivation assets and EFSA-recognized testing laboratory networks. Long-term viability across the analysis window favors vertically integrated field-to-slice operators with captive processing infrastructure over pure-play growers exposed to commodity price volatility. The signal to monitor is divergence between USDA Agricultural Marketing Service grade standards and EFSA monitoring protocols, which would trigger consolidation pressure on multi-destination exporters lacking compliance infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Controlled-Atmosphere Storage | T&G Global's Oceania infrastructure enables year-round availability independent of seasonal harvest windows. |
| Organic Certification Program Expansion | Peri & Sons Farms' direct retail channel control in California bypasses Bleiswijk auction pricing pressure. |
| Pre-Sliced Product Line Launch | Gills Onions' nitrogen-flushed film packaging penetrates national restaurant chain procurement with labor-cost savings. |
| Direct-to-Retail Contracting | French supermarket chains mandating standardized bag formats displace regional distributor intermediaries. |
| EFSA-Recognized Laboratory Testing Consolidation | Indian exporters to EU destinations preempt border rejection through batch-level residue documentation. |
Research Methodology
A standing panel of produce procurement directors at national restaurant chains, supermarket category buyers, controlled-atmosphere storage facility operators, and organic certification compliance officers provided ongoing calibration across primary interview cycles. Secondary validation drew from USDA Agricultural Marketing Service grade standard filings, EFSA residue monitoring reports, FSSAI export specification notifications, customs trade data for Bangladesh and Southeast Asian onion shipments, and SEC filings from integrated field-to-slice operators. Bottom-up volume modeling across growing region clusters triangulated against top-down demand aggregation by end-user segment.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with analytical framework segmentation by bulb category, packing format, distribution channel, and end-user concentration. Modeled dimensions included pyruvic acid content tiers for food manufacturing compatibility, organic certification status for retail premium capture, and food service contract specifications for pre-processed shallot products. CAGRs derived from harvest volume trajectories, storage capacity expansion timelines, and regulatory compliance cost curves.
Decision-makers should treat outputs as directional under assumptions of sustained EU Farm to Fork Strategy implementation, stable India-Bangladesh trade corridor formalization, and continued food service premiumization; material deviation in pesticide residue threshold enforcement or labor cost inflation would warrant model refresh. Recalibration cycles align with material shifts in regulatory enforcement intensity and restaurant chain procurement pattern adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
North America Microgreens Market
Vegetables
Butternut Squash Market
Vegetables
Acorn Squash Market
Vegetables
North America Christmas Tree Market
Vegetables
Microgreens Market
Vegetables
Vegetable Chutney Market
Vegetables
Dry Onion Market
Vegetables
Cameroon Fruits and Vegetables Market
Vegetables
Canada Greenhouse Horticulture Market
Vegetables
Asparagus Market
Vegetables
Spain Avocado Market
Vegetables
Air Dried Vegetables Market
Vegetables
Global Indoor Plant Market
Vegetables
Japan Greenhouse Horticulture Market
Vegetables
Greenhouse Bell Pepper Market
Vegetables
United States Microgreens Market