
 Hydroponic Vegetable Market | 2026-2036
Hydroponic Vegetable Market Size, Share, and Industry Trends Forecast 2026-2036
Hydroponic Vegetable Market Outlook
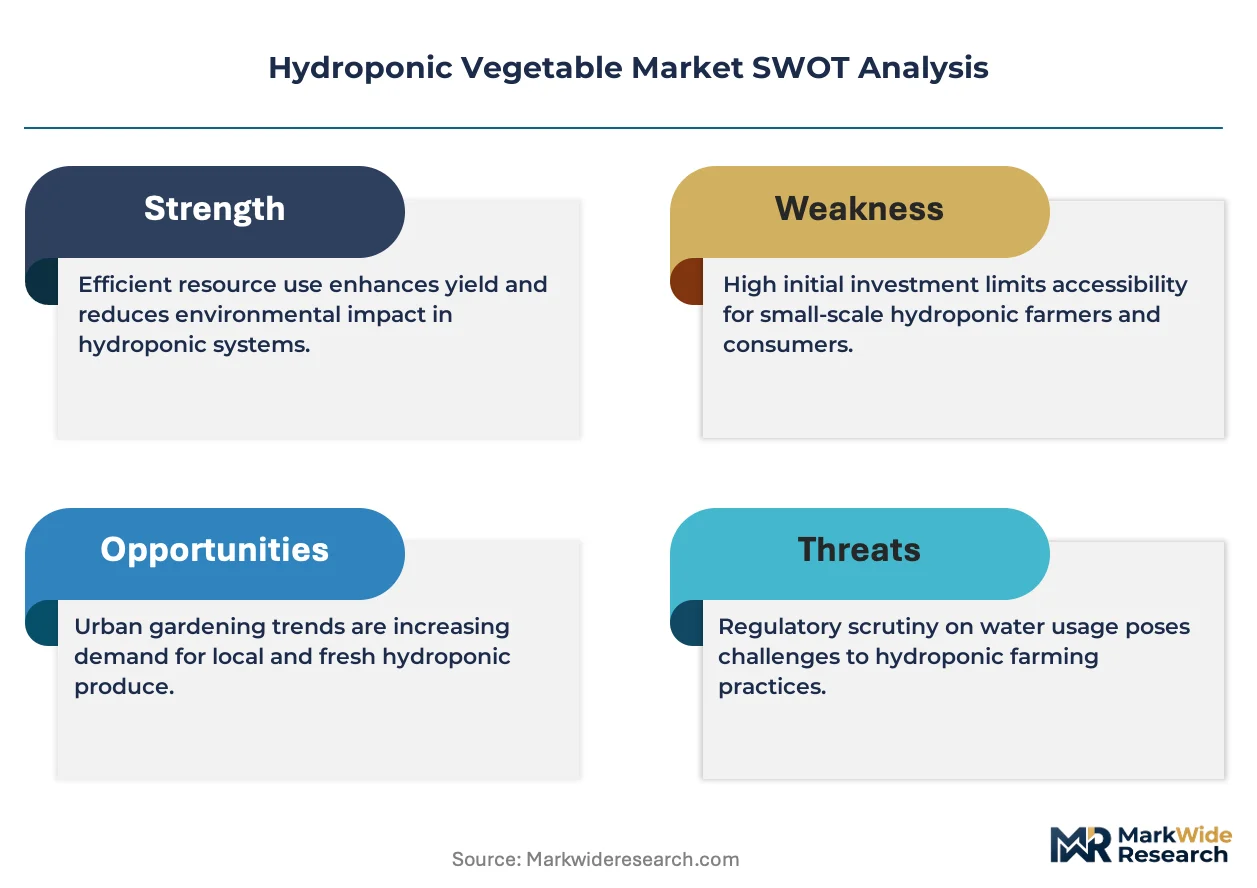
Rock wool is decoupling from premium hydroponic substrate economics as coco coir and peat-free blends gain cost parity in large-scale operations. AeroFarms leverages patented aeroponic towers to dominate vertical farming density metrics in urban corridors. Gotham Greens anchors its position through integrated greenhouse-to-retail distribution in major metropolitan markets. ScottsMiracle-Gro extends its traditional lawn and garden dominance into specialized hydroponic nutrient formulations for commercial operators.
Hydroponic vegetables are plants cultivated without soil, using mineral nutrient solutions dissolved in water, with roots supported by inert media such as perlite, vermiculite, or coconut coir, typically requiring controlled pH between 5.5 and 6.5 and electrical conductivity monitoring for optimal ion uptake. The primary commercial purpose is to deliver predictable yields with reduced water consumption and elimination of soil-borne pathogens for year-round supply to retail and foodservice channels. NFT systems lead commercial installations due to lower capital requirements and operational simplicity, while aeroponics captures the fastest expansion in research-intensive and high-value herb segments. Commercial growers concentrate margin pools through long-term supply contracts with supermarket chains, whereas home gardeners represent a fragmented but expanding channel through direct-to-consumer nutrient and system sales.
The EPA regulates agricultural runoff standards that indirectly pressure conventional field growers toward closed-loop hydroponic systems with zero discharge. The USDA administers organic certification criteria that now encompass hydroponic and aquaponic production methods, shaping label-driven consumer demand at retail. The EU Green Deal and F-Gas Regulation constrain synthetic fertilizer and refrigerant use in protected horticulture, redirecting investment toward renewable-powered controlled-environment facilities. Stakeholders must monitor evolving definitions of organic eligibility and carbon accounting methodologies for indoor agriculture as these frameworks determine market access premiums.
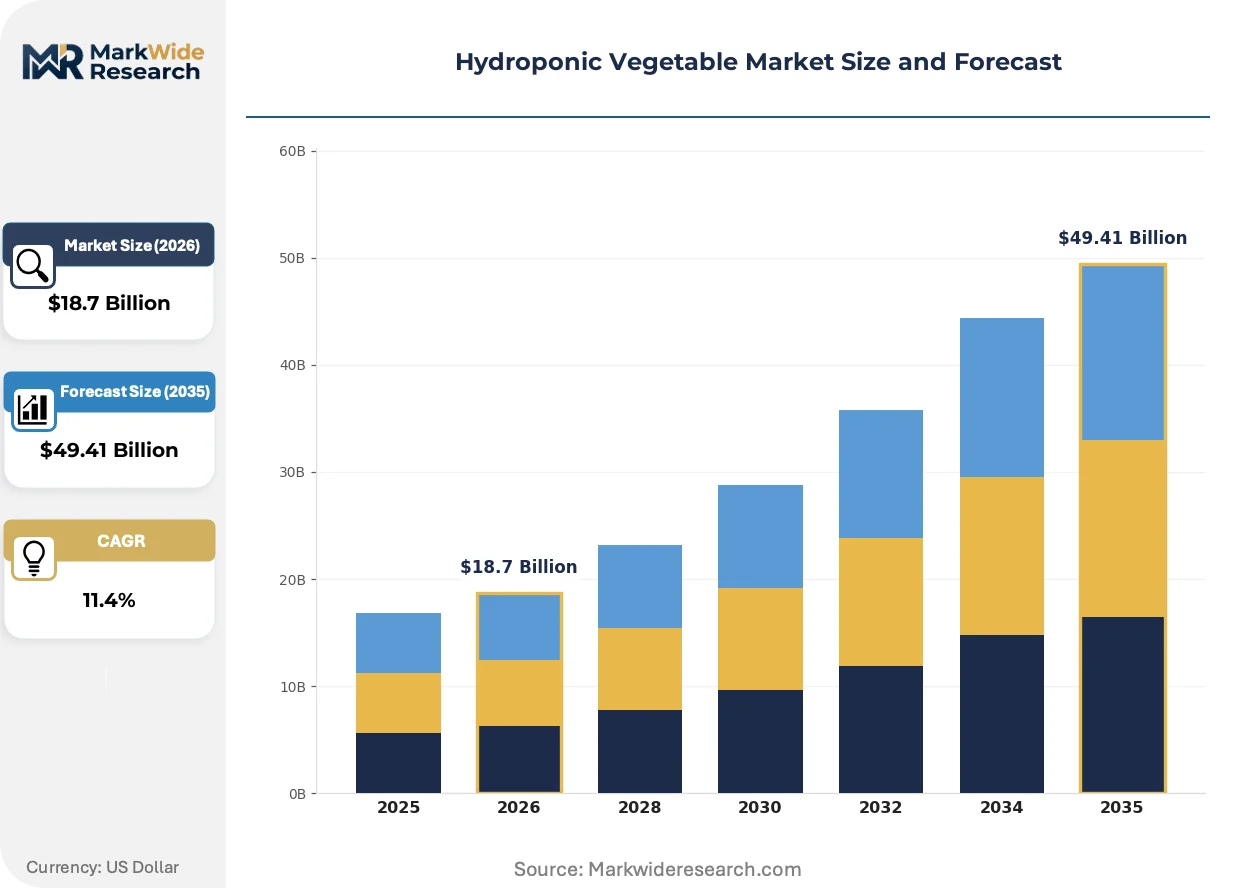
Market Dynamics
Retail grocery chains are consolidating produce procurement around year-round supply guarantees, forcing growers toward capital-intensive controlled-environment systems that eliminate seasonal volatility and soil-borne contamination risks.
Growth Catalysts
- EU Green Deal farm-to-fork targets:The European Commission's 2030 sustainability mandates are redirecting agricultural subsidies toward zero-runoff hydroponic facilities in the Netherlands and Spain.
- Water-stressed agriculture:Israel and Singapore are mandating closed-loop irrigation for commercial vegetable production, accelerating NFT and aeroponic system deployment.
- Perlite substrate innovation:Expanded perlite grades with engineered pore structures are reducing transplant shock in commercial tomato propagation, cutting nursery cycle times.
Market Restraints
- Phosphorus supply concentration:Morocco and Western Sahara control 70% of global phosphate rock reserves, exposing hydroponic nutrient formulators to geopolitical input cost volatility.
- F-Gas refrigeration constraints:The EU F-Gas Regulation is phasing down HFC coolants used in greenhouse climate control, forcing costly retrofit of existing protected horticulture infrastructure.
- Technical yield ceilings:Aeroponic systems face root desiccation thresholds that limit crop diversity to leafy greens and herbs, excluding fruiting vegetables from high-density vertical configurations.
Strategic Opportunities
- Saudi Arabia's food security mandate:The National Food Security Strategy is funding solar-powered desert greenhouses for tomato and cucumber production, creating demand for evaporative cooling and desalination-integrated hydroponics.
- Carbon accounting methodologies:Emerging ISO standards for indoor agriculture emissions measurement will enable premium pricing for renewable-powered produce in German and Swiss retail channels.
- Direct-to-restaurant distribution:Chefs in Copenhagen and Melbourne are contracting dedicated greenhouse capacity, bypassing wholesale produce markets for cultivar-specific supply agreements.
Industry Challenges
- Controlled-environment agronomy expertise:Commercial operators face acute shortages of technicians trained in electrical conductivity management and integrated pest management for soil-free systems.
- USDA organic certification timelines:Hydroponic producers seeking organic labels face 36-month transition audits and input documentation requirements that delay market access premiums.
- Proprietary aeroponic nozzle IP:Licensing disputes over high-pressure misting system designs are fragmenting equipment supply and inflating capital costs for vertical farm developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydroponic Vegetable Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lettuce, Spinach, Herbs, Tomatoes Technology: NFT, Aeroponics, Deep Water Culture, Ebb and Flow End User: Commercial Growers, Home Gardeners, Research Institutions, Agricultural Corporations Distribution Channel: Online Retail, Direct Sales, Wholesale, Farmers' Markets |
| Companies Covered | AeroFarms, Gotham Greens, ScottsMiracle-Gro, BrightFarms, Freight Farms, American Hydroponics, Plenty, Kalera, Village Farms International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydroponic Vegetable Market Strategic Shifts
Automation and sensing technologies are compressing labor inputs while precision nutrition software is enabling cultivar-specific recipe optimization, fundamentally altering the cost structure of protected vegetable production.
Containerized modular growing units equipped with LED spectrum tuning and automated nutrient dosing are decentralizing fresh produce supply chains. Regional food hubs in Texas and Ohio are deploying these systems to serve 150-mile distribution radii. The technology is decentralizing the historical concentration of winter vegetable production in California and Mexico, enabling year-round local supply in temperate climates.
The EU F-Gas Regulation's phase-down schedule for hydrofluorocarbon refrigerants is forcing greenhouse operators toward ammonia and CO2-based climate control systems. Dutch engineering firms are retrofitting existing Venlo structures with heat pump recovery loops. Protected horticulture in Belgium and the Netherlands faces the steepest compliance costs, accelerating consolidation among mid-scale growers unable to fund equipment upgrades.
Restaurant procurement teams are unbundling produce sourcing from broadline distributors, establishing direct contracts with greenhouse operators for specific cultivars and harvest maturity specifications. This pattern is most visible in Nordic markets where Noma's supply chain innovations have diffused to mid-tier dining groups. Copenhagen's hospitality sector now accounts for a disproportionate share of contract-grown microgreen and baby leaf volume, bypassing traditional wholesale channels entirely.
Hydroponic Vegetable Market Segmentation
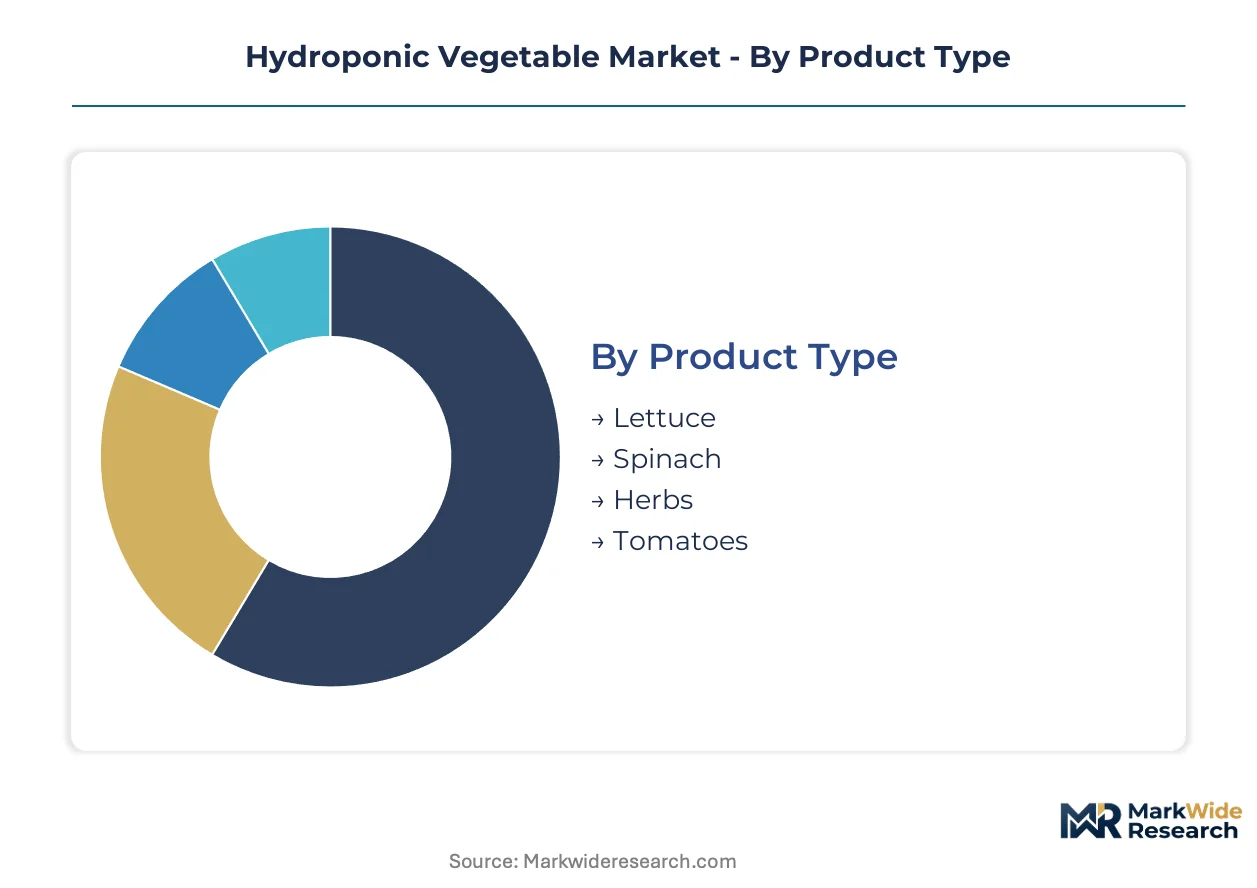
Product mix and technology choices determine capital intensity and margin profiles across hydroponic operations. Segment boundaries shift as substrate innovations and automation reshape cost structures for different crop categories and customer types.
Product Type:
Upgrade cycles in substrate formulations and LED spectrum tuning drive replanting decisions across vegetable categories, with faster-turn crops commanding more frequent system refreshes.
- Lettuce:Shallow-rooted varieties dominate NFT channel installations due to rapid harvest cycles and consistent head formation. Dutch greenhouse clusters supply year-round butterhead and romaine to German retail chains under long-term procurement contracts.
- Spinach:Baby leaf formats require precise nutrient timing to prevent nitrate accumulation. Israeli desert facilities deploy this crop in solar-powered hoop houses for European export during winter production gaps.
- Herbs:Basil and cilantro generate premium pricing in direct-restaurant channels.
- Tomatoes:Vine-ripened cultivars concentrate in high-wire greenhouse systems with CO2 enrichment.
Volume placements concentrate in lettuce; the faster expansion belongs to herbs.
Technology:
Cost tier differentiation separates capital-light entry systems from precision-controlled commercial infrastructure, with technology choice locking in operating expense profiles for multi-year horizons.
- NFT:Nutrient Film Technology circulates shallow solution flows through sloped channels, minimizing water volume and enabling rapid nutrient adjustment. Commercial tomato and lettuce operations in Spain's Almeria province favor NFT for its lower pumping energy versus substrate-based alternatives.
- Aeroponics:High-pressure misting delivers nutrients directly to exposed root zones, maximizing oxygen availability and planting density. Urban vertical farms in Singapore deploy aeroponic towers for leafy greens where land scarcity justifies elevated capital expenditure.
- Deep Water Culture:Floating raft systems suit low-profile crops with minimal structural support needs.
- Ebb and Flow:Periodic flooding and draining cycles suit propagation nurseries and potted herb production.
Commercial adoption clusters around NFT; steepest expansion trajectory belongs to aeroponics.
End User:
Customer type determines batch size, technical sophistication requirements, and sensitivity to input cost volatility across the supply base.
- Commercial Growers:Professional operations exceeding one hectare under glass or polymer concentrate margin capture through supermarket supply agreements and foodservice contracts. Netherlands-based cooperatives aggregate output for centralized quality grading and EU distribution.
- Home Gardeners:Countertop and balcony systems target urban consumers with cultivar-specific seed pod subscriptions. Direct-to-consumer nutrient formulations from ScottsMiracle-Gro and specialized entrants capture recurring revenue from this fragmented base.
- Research Institutions:Wageningen University and Singapore's Agency for Science conduct cultivar optimization trials.
- Agricultural Corporations:Integrated agribusinesses deploy hydroponics for supply chain control and brand differentiation.
Revenue concentration sits with commercial growers; home gardeners represent the fastest-climbing volume channel.
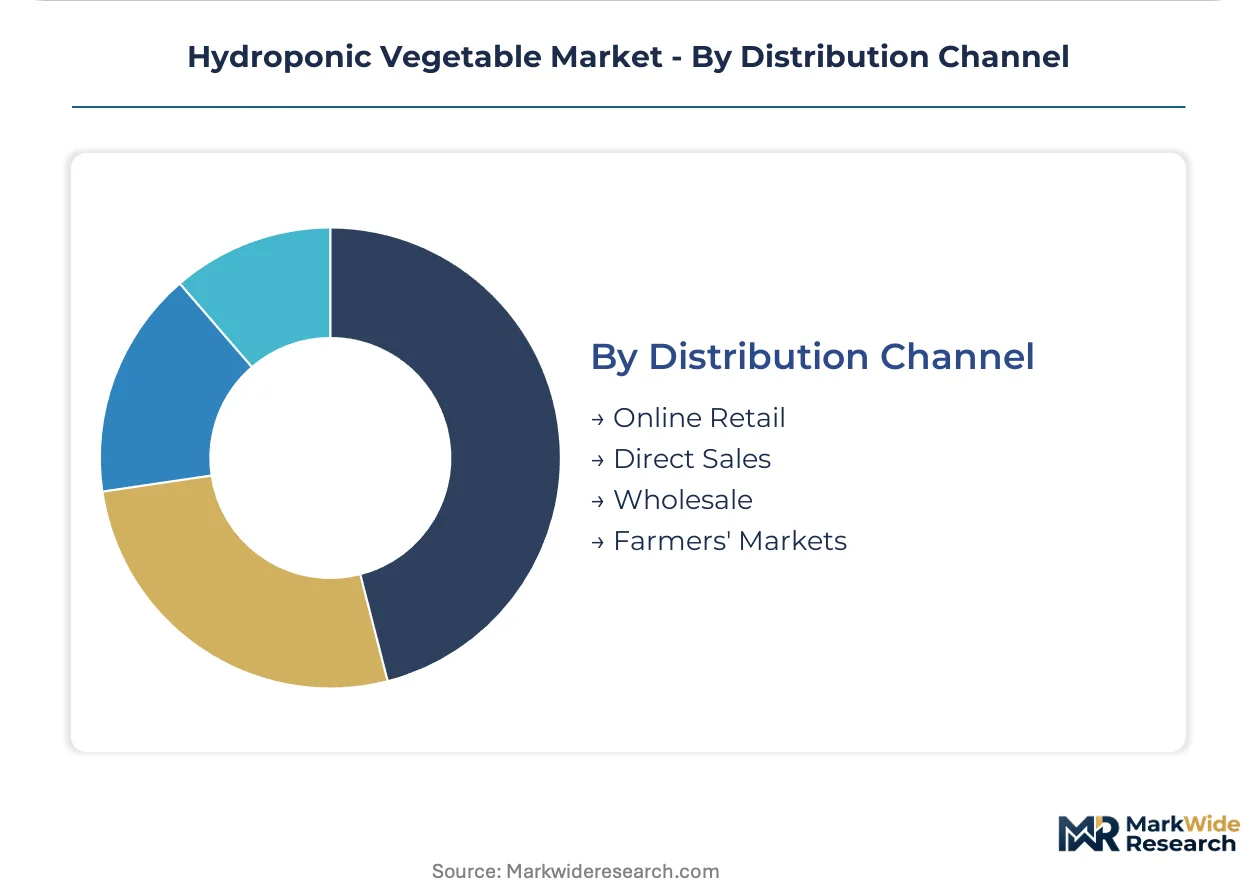
Distribution Channel:
Channel selection reflects crop perishability windows and buyer concentration, with direct relationships capturing value that wholesale intermediaries otherwise extract.
- Online Retail:E-commerce platforms aggregate home gardening systems, nutrients, and seed supplies for dispersed consumers. Amazon and specialized hydroponic retailers capture this channel through subscription replenishment models for consumable inputs.
- Direct Sales:Greenhouse operators bypass wholesale markets through dedicated contracts with restaurant groups and retail chains. Copenhagen's restaurant sector sources microgreens through direct grower agreements specifying harvest maturity and cultivar provenance.
- Wholesale:Traditional produce distributors aggregate volume for supermarket replenishment.
- Farmers' Markets:Local production for immediate consumption concentrates in peri-urban zones.
Transaction value pools in direct sales; online retail is gaining share fastest among emerging channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for hydroponic vegetables concentrates in nations with water scarcity, advanced greenhouse infrastructure, or food security mandates. The Netherlands, United States, Singapore, Saudi Arabia, and Spain each exhibit distinct regulatory and investment drivers shaping local market development.
Netherlands
Wageningen University research clusters and national export infrastructure support year-round tomato and lettuce production for German and British retail chains. The EU Green Deal's farm-to-fork sustainability targets redirect agricultural subsidies toward zero-runoff hydroponic facilities. Westland municipality greenhouse clusters deploy CO2 enrichment and LED spectrum tuning for vine-ripened cultivar optimization.
United States
Retail grocery chains in metropolitan markets consolidate procurement around year-round supply guarantees from controlled-environment operators. The USDA administers organic certification criteria encompassing hydroponic production methods, shaping label-driven consumer demand. New York and Chicago anchor integrated greenhouse-to-retail distribution networks serving dense urban populations.
Singapore
Land scarcity and food import dependence drive mandate for closed-loop irrigation in commercial vegetable production. The national food agency enforces strict agricultural standards while funding vertical farming deployment in urban corridors. Aeroponic towers in industrial zones maximize planting density for leafy greens serving local hospitality and retail channels.
Saudi Arabia
The National Food Security Strategy funds solar-powered desert greenhouses for tomato and cucumber production reducing import reliance. Government programs subsidize evaporative cooling and desalination-integrated hydroponics in arid zones. Riyadh-based operators contract with supermarket chains for domestic supply of previously imported vegetables.
Spain
Almeria province commercial growers favor NFT systems for lower pumping energy versus substrate-based alternatives in extensive greenhouse complexes. The EU F-Gas Regulation phases down HFC coolants used in climate control, forcing costly retrofit of protected horticulture infrastructure. Andalusian cooperatives aggregate output for centralized quality grading and EU distribution.
Hydroponic Vegetable Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated greenhouse operators capturing premium pricing through direct retail relationships while equipment suppliers serve fragmented home gardening demand. The vendor base organizes around three archetypes: vertical farm technology developers, integrated greenhouse-to-retail operators, and agricultural input formulators extending into specialized nutrients. Dominant competitive moves include strategic partnerships with supermarket chains for dedicated supply capacity and technology licensing agreements for proprietary growing system designs.
Among North American vertical farming specialists, AeroFarms and Plenty occupy positions exemplifying high-density aeroponic system development for urban corridors. Integrated greenhouse operators such as Gotham Greens represent the direct-to-retail archetype through metropolitan market penetration. ScottsMiracle-Gro anchors the agricultural input extension strategy, leveraging traditional lawn and garden distribution into hydroponic nutrient formulations.
| Leading Market Players |
|---|
| AeroFarms |
| Gotham Greens |
| ScottsMiracle-Gro |
| BrightFarms |
| Freight Farms |
| American Hydroponics |
| Plenty |
| Kalera |
| Village Farms International |
| Others |
Value Chain & Pricing Dynamics
Family-owned greenhouse cooperatives in the Netherlands and Spain anchor supply discipline through long-term offtake contracts with German and British retail chains, translating concentrated production capacity into stable contract pricing that resists spot-market volatility. Sovereign-backed operators in Saudi Arabia and Singapore inject capital-intensive infrastructure subsidies that compress delivered costs in water-stressed zones, creating geographic price dispersion that rewards controlled-environment scale.
Pricing Analysis
Volume placements cluster in standardized lettuce and tomato grades under fixed annual contracts, while margin capture concentrates in cultivar-specific herbs and microgreens sold through direct-restaurant channels. Three-tier pricing structure across premium organic-certified, standard greenhouse, and economy hydroponic tiers separates buyers by certification grade and harvest specification. Cost compression in standard lettuce tiers is intensifying because Moroccan phosphate rock concentration exposes nutrient formulators to input volatility. Home gardeners exhibit highest price sensitivity to system capital costs, whereas Copenhagen restaurant procurement teams prioritize cultivar provenance over unit economics.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Almeria aggregate output from dispersed greenhouse clusters before final-mile delivery to supermarket chains. Supply concentrates in the Netherlands, Spain, and Saudi Arabia, with substrate and LED equipment dependencies drawing from Chinese manufacturing hubs. Phosphorus supply vulnerability rests on Moroccan reserve concentration, creating single-source exposure for nutrient blenders. Distribution runs through cooperative-owned grading facilities that standardize quality before EU-wide retail placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Controlled-environment agronomy expertise scarcity props pricing for technically capable operators, as technician shortages in electrical conductivity management constrain rapid capacity expansion across the industry.
For Market Incumbents: Cement supermarket supply relationships through dedicated greenhouse capacity investments near Rotterdam and Chicago distribution hubs. Secure backward integration into perlite substrate production to offset Moroccan phosphate volatility. Prioritize CO2-based climate control retrofits ahead of EU F-Gas Regulation enforcement deadlines. For New Entrants and Emerging Players: Automated nutrient dosing systems offer a technology-first wedge into fragmented home gardening channels currently served by ScottsMiracle-Gro subscriptions. Target solar-powered desert greenhouse deployments in Saudi Arabia's National Food Security Strategy zones. Pursue direct-to-restaurant distribution in Nordic markets where Noma-influenced procurement bypasses wholesale intermediaries. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale Dutch greenhouse operators facing F-Gas retrofit compliance costs in Westland municipality clusters. Long-term viability hinges on renewable power purchase agreements that secure carbon-accounting premiums in German retail. Watch ammonia-based refrigeration adoption rates as inflection indicator for operational cost competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Production | Perlite and coco coir captive supply insulates Dutch operators from input cost volatility. |
| Direct-to-Restaurant Distribution Contracts | Copenhagen chef partnerships bypass wholesale markets for cultivar-specific microgreen supply. |
| CO2-Based Climate Control Retrofit | Dutch engineering firms deploy heat pump recovery loops ahead of EU F-Gas phase-down deadlines. |
| Solar-Powered Desert Greenhouse Deployment | Saudi Arabia's food security mandate funds evaporative cooling and desalination-integrated hydroponics. |
| Automated Nutrient Dosing Platform Launch | Precision nutrition software enables cultivar-specific recipe optimization for commercial tomato propagation. |
Study Parameters
Independent corroboration across greenhouse operator interviews, agricultural input supplier disclosures, and retail procurement data underwrites the qualitative findings. Primary fieldwork engaged commercial growers in Almeria and Westland, nutrient formulation chemists at ScottsMiracle-Gro, supermarket category buyers in Germany, and vertical farm engineers in Singapore. Secondary validation drew from EU F-Gas Regulation filings, USDA organic certification databases, Saudi National Food Security Strategy documents, and Wageningen University research publications. Bottom-up volume estimates from installed greenhouse hectarage triangulated against top-down retail produce procurement values.
Rate-of-change decomposition across technology adoption curves, regulatory compliance timelines, and capital deployment patterns shaped the analytical framework. Segmentation dimensions modeled include product type, growing system technology, end-user scale, and distribution channel structure across the projection horizon. CAGRs derived from geometric progression of year-over-year capacity additions and yield improvements. Industry-specific inputs incorporated LED energy efficiency trajectories, desalination cost curves, and phosphate rock price volatility assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU organic certification timeline delays and Moroccan export restriction scenarios. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
Europe Flowers and Ornamental Plants Market
Vegetables
Artichokes Market
Vegetables
Vegetable Chutney Market
Vegetables
Dried Mushroom Market
Vegetables
Garlic Market
Vegetables
Yarrow Market
Vegetables
Italy Greenhouse Horticulture Market
Vegetables
Asia-Pacific Peas Market
Vegetables
Fresh Mushroom Market
Vegetables
Global Mushroom Market
Vegetables
North America Sweet Potatoes Market
Vegetables
Dry Onion Market
Vegetables
Potato Market
Vegetables
Field Peas Market
Vegetables
Butternut Squash Market
Vegetables
Cameroon Fruits and Vegetables Market