
 Yams Market | 2026-2036
Yams Market Size, Share, and Industry Trends Forecast 2026-2036
Yams Market Outlook
Buyer concentration among food processing customers is expanding as multinational ingredient buyers consolidate supplier lists and demand certified traceability. McCall Farms Inc. leverages its southeastern U.S. processing infrastructure to serve institutional foodservice chains with consistent supply. Bio Botanica Inc. specializes in botanical extract applications, anchoring its position in dietary supplement channels. Frontier Co-op competes through cooperative sourcing networks that connect smallholder growers to North American retail and wholesale buyers.
Yams are starchy tubers from Dioscorea species, typically containing 15-25% dry matter with amylose-amylopectin ratios varying by cultivar, primarily cultivated for human consumption and industrial starch extraction. White Yam dominates fresh export trade due to longer shelf stability and established culinary preference in diaspora communities. Dietary Supplements represents the fastest-expanding application segment as standardized extracts gain traction in functional nutrition formulations. Culinary applications remain the mature volume base, though margin pools increasingly concentrate in processed and value-added product tiers.
FDA food safety regulations and USDA organic certification requirements govern U.S. market access, while EFSA novel food assessments shape European import pathways for processed yam ingredients. Nigeria's SON and Ghana's FDA enforce grade standards that determine export eligibility and price realization for West African suppliers. Stakeholders must monitor evolving phytosanitary protocols and invest in compliant cold chain infrastructure to secure preferential buyer relationships.
Market Dynamics
West African supply corridors are consolidating under stricter phytosanitary protocols, forcing exporters to upgrade cold chain infrastructure or lose access to European and North American ethnic food channels. Nigeria's SON grade enforcement and Ghana's FDA inspections now determine which suppliers qualify for premium export tiers.
Growth Catalysts
- EFSA novel food assessments:Processed yam ingredients gain formal approval pathways into European functional nutrition markets, expanding addressable demand beyond fresh tuber trade.
- Dietary supplement formulation:Standardized Dioscorea extracts command higher margin pools as botanical ingredient buyers consolidate supplier lists around certified traceability.
- Diaspora culinary channels:West African communities in the United Kingdom, Germany, and Canada sustain predictable offtake for White Yam cultivars with established shelf stability profiles.
Market Restraints
- Input cost volatility:Diesel and refrigerated transport expenses fluctuate with Nigerian naira instability, compressing exporter margins during peak harvest windows.
- Supply concentration risk:Nigerian smallholder networks dominate global export volume, creating single-origin vulnerability to regional climate shocks and port congestion.
- Cassava substitution threat:Industrial starch buyers in West Africa increasingly blend lower-cost cassava flour into food processing formulations, displacing yam-derived alternatives.
Strategic Opportunities
- USDA organic certification:Premium price realization awaits West African cooperatives that complete three-year conversion protocols and access North American natural retail channels.
- Pharmaceutical extraction:Diosgenin isolation for synthetic hormone precursors opens industrial demand from European and Indian API manufacturers seeking non-synthetic botanical sources.
- Direct-to-retail e-commerce:Ethnic grocery platforms in Canada and the United States bypass traditional importer-distributor markups, improving farmgate returns for compliant exporters.
Industry Challenges
- Post-harvest loss mitigation:Yams require specialized curing barns and humidity-controlled storage; capital scarcity among Nigerian smallholders drives 30-40% spoilage rates before export packing.
- Certification timeline compression:SON grade inspections and EFSA novel food dossier preparation demand 18-24 month lead times, misaligning with annual harvest cycles and buyer procurement calendars.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yams Market |
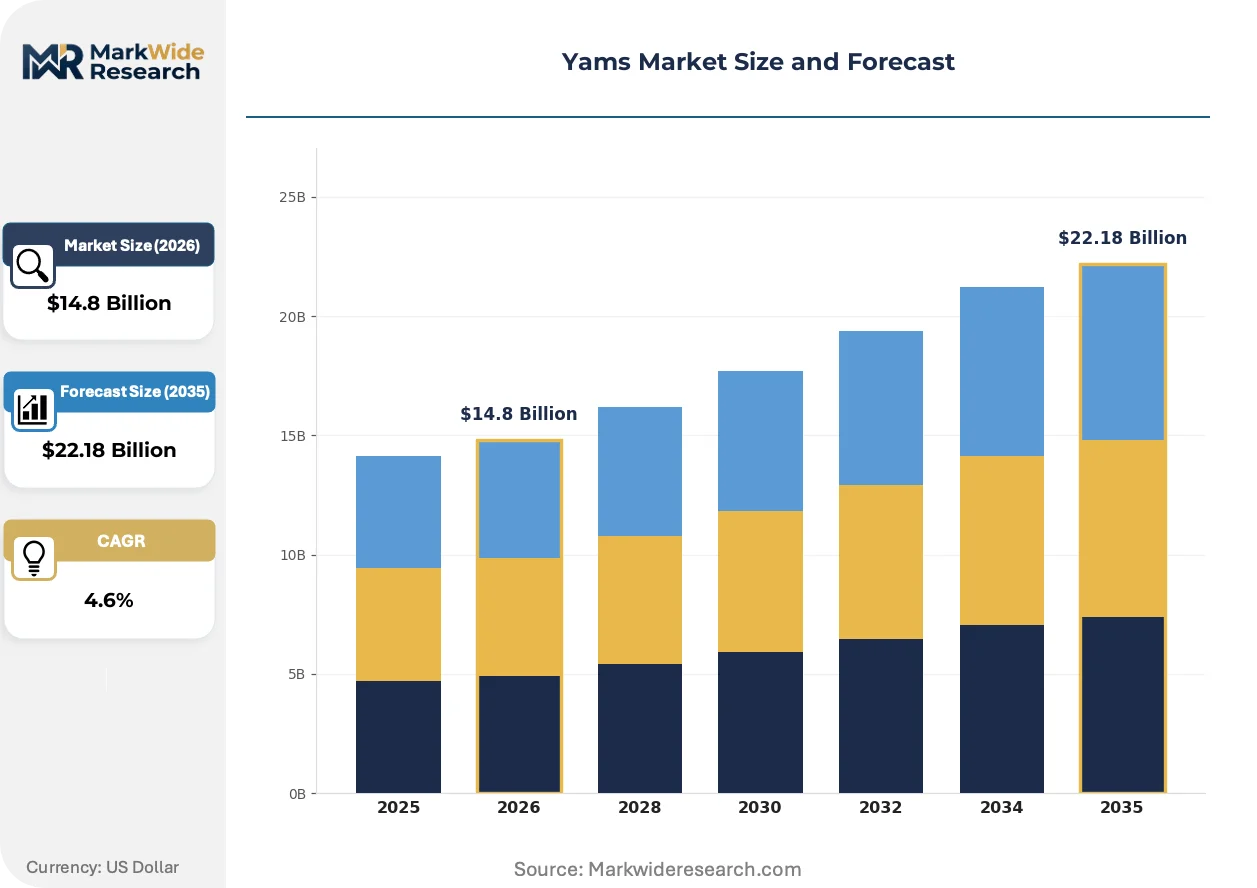
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yellow Yam, Water Yam, White Yam, Greater Yam End User: Household, Food Service, Food Processing, Exporters Distribution Channel: Supermarkets, Online Retail, Wholesale, Farmers' Markets Application: Culinary, Dietary Supplements, Animal Feed, Industrial Use |
| Companies Covered | BDS Natural Products Inc., Amruth Organics and Natural Store, Bio Botanica Inc., Dabur India Ltd., Dr. Willmar Schwabe GmbH and Co. KG, Frontier Co op, Green Amrut, McCall Farms Inc., Provital SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yams Market Strategic Shifts
Processing technology and regulatory digitization are compressing traditional trade structures. Buyers now demand batch-level traceability from farm to finished ingredient, while extraction methods unlock pharmaceutical-grade applications previously inaccessible to tuber crops.
Controlled atmosphere storage is consolidating around Nigerian export hubs. The technology extends White Yam shelf life from six weeks to four months by regulating oxygen and ethylene exposure. Major importers in the United Kingdom and Germany now mandate CA-stored shipments as a condition of annual contract renewal. This infrastructure investment is consolidating supplier tiers, excluding smallholders unable to finance retrofitting costs.
EFSA's 2023 guidance on novel food botanical extracts is reshaping European import pathways. The regulation requires comprehensive toxicological dossiers for concentrated yam ingredients entering supplement channels. Dutch and German ingredient houses are responding by vertically integrating backward into Ghanaian processing facilities to control documentation chains. Compliance costs are filtering marginal traders from the market.
Ethnic retail consolidation in North America is displacing traditional importer-wholesaler networks. Large-format Asian and African supermarket chains in Toronto, Houston, and London now contract directly with Nigerian export cooperatives, bypassing three layers of intermediate distribution. This disintermediation concentrates volume with SON-certified suppliers capable of consistent year-round fulfillment.
Yams Market Segmentation
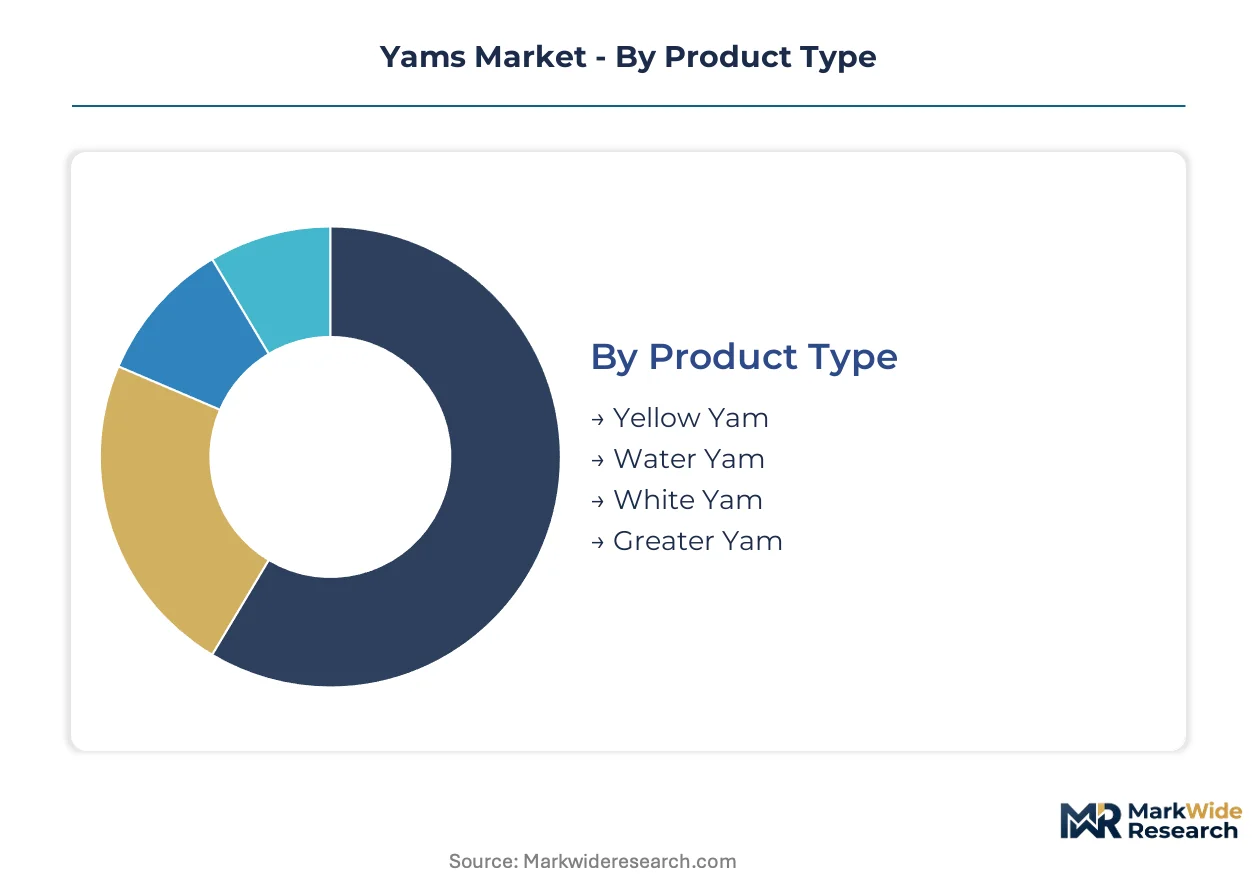
Yam cultivars exhibit distinct physicochemical profiles that dictate end-use suitability and price realization. Segmentation clarity enables buyers to match procurement specifications with processing requirements across fresh trade and extract applications.
Product Type:
Starch composition and tuber morphology define processing economics and shelf stability benchmarks.
- White Yam:Contains 20-24% dry matter with intermediate amylose content that resists retrogradation during storage. Diaspora communities in the United Kingdom and Canada sustain predictable procurement for this cultivar due to established culinary familiarity and six-week minimum shelf life under ambient conditions.
- Yellow Yam:Higher beta-carotene concentration delivers distinct coloration prized in traditional West African preparations. Nigerian export cooperatives command modest premiums for grade-A Yellow Yam shipments to German ethnic retail channels where visual consistency drives repeat purchase.
- Water Yam:Lower dry matter percentage (15-18%) suits immediate consumption rather than long-haul export. Domestic West African foodservice operators absorb regional harvest peaks before post-harvest deterioration accelerates.
- Greater Yam:Larger tuber dimensions reduce per-unit handling costs for industrial starch extraction facilities. Ghanaian processors favor this cultivar for flour milling operations serving regional bakery formulations.
Mature deployment sits with White Yam. Newer deployment is concentrated in Yellow Yam specialty channels.
End User:
Buyer scale and certification requirements create distinct service cost structures across the demand base.
- Food Processing:Multinational ingredient buyers consolidate supplier lists around certified traceability and batch-level documentation. These customers drive specification standardization for yam-derived starches entering gluten-free bakery and snack formulations.
- Household:Diaspora consumers in North American and European cities sustain ethnic retail volume with preference for whole-tuber freshness indicators. Price sensitivity limits margin capture compared to institutional channels.
- Food Service:West African restaurants and caterers in London, Houston, and Toronto require consistent sizing for portion control. This segment absorbs secondary grades rejected by export certification standards.
- Exporters:SON-certified Nigerian cooperatives and Ghanaian FDA-registered suppliers serve as gatekeepers to premium European and North American markets. Compliance infrastructure investments separate viable exporters from domestic-only traders.
Volume concentrates with Food Processing. Margin expansion is climbing the fastest with Exporters achieving certification tiers.
Distribution Channel:
Channel selection determines cold chain investment recovery and working capital intensity.
- Wholesale:Traditional importer-distributor networks in Rotterdam and Liverpool handle bulk consolidation from West African ports. These intermediaries absorb phytosanitary inspection risks and currency hedging costs.
- Supermarkets:Large-format African and Caribbean grocery chains in Toronto and London now contract directly with certified cooperatives, bypassing traditional wholesale markups. This disintermediation rewards suppliers capable of year-round fulfillment.
- Online Retail:Ethnic grocery platforms enable direct-to-consumer shipment of vacuum-packed yam portions. Last-mile cold chain costs currently limit geographic reach to major metropolitan clusters.
- Farmers' Markets:Hyperlocal sales within West African urban centers capture harvest peaks unsuitable for export grading. Price realization remains below structured channel alternatives.
Traditional volume flows through Wholesale. Disintermediation is gaining share fastest through Supermarket direct contracting.
Application:
Functional properties unlock divergent value capture across consumption and industrial pathways.
- Dietary Supplements:Standardized Dioscorea extracts command premium positioning in botanical supplement formulations. EFSA novel food dossier requirements filter marginal suppliers from European market access.
- Culinary:Fresh and processed yam products sustain the mature volume base across West African domestic markets and diaspora channels. Margin compression intensifies as cassava substitutes penetrate price-sensitive formulations.
- Industrial Use:Starch extraction for textile sizing and adhesive manufacturing competes with cassava and maize alternatives on cost per unit viscosity. Nigerian processors struggle to achieve scale economies against Asian starch imports.
- Animal Feed:Substandard tubers and processing residues enter ruminant feed formulations within West African domestic markets. Price realization trails food-grade applications by substantial margins.
Established volume anchors Culinary applications. Steepest expansion trajectory belongs to Dietary Supplements as functional nutrition demand accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diaspora communities in the United Kingdom, Germany, and Canada concentrate fresh yam demand outside West Africa. Nigerian exporters supply these corridors through Rotterdam and Liverpool consolidation hubs. Certification requirements now determine which origins qualify for premium tier access.
Nigeria
SON grade enforcement separates export-eligible suppliers from domestic-only traders. The Standards Organisation of Nigeria mandates moisture content and defect thresholds that determine price realization. Lagos and Ibadan processing clusters now invest in controlled atmosphere storage to extend White Yam shelf life for European contract fulfillment.
Ghana
FDA inspections determine which cooperatives access North American ethnic retail channels. Ghana's Food and Drugs Authority enforces pesticide residue limits that align with USDA import requirements. Accra-Tema export corridors consolidate under stricter documentation protocols as Dutch ingredient houses seek backward integration into local processing.
United Kingdom
West African diaspora communities in London, Birmingham, and Manchester sustain predictable White Yam offtake. EFSA novel food assessments for concentrated extracts reshape import pathways for processed ingredients. Large-format African supermarket chains now contract directly with SON-certified Nigerian cooperatives, bypassing traditional wholesale markups.
Germany
Yellow Yam premiums concentrate in Berlin and Frankfurt ethnic retail channels where visual consistency drives repeat purchase. German botanical ingredient houses respond to EFSA guidance by integrating into Ghanaian processing facilities. Hamburg and Bremen ports handle bulk consolidation from West African origins with phytosanitary inspection capacity.
Canada
Toronto and Houston ethnic grocery platforms enable direct-to-retail contracting with compliant exporters. Health Canada import requirements govern botanical extract entry for supplement applications. Vacuum-packed yam portions through online retail channels improve farmgate returns for certified Nigerian suppliers.
Yams Market Competitive Environment
West African producers anchor the raw material tier; North American and European specialists hold processing and extract formulation positions. The vendor base separates into SON-certified export cooperatives, ingredient houses with backward integration, and cooperative sourcing networks connecting smallholders to retail. Three archetypes dominate: vertically integrated processors, certified traceability aggregators, and botanical extract specialists. Competitive moves concentrate on certification infrastructure investment and direct retail channel capture.
Among North American operators, McCall Farms Inc. and Frontier Co-op occupy distinct positioning. McCall Farms Inc. represents the processing infrastructure archetype with southeastern U.S. capabilities. Frontier Co-op exemplifies cooperative sourcing networks that bridge smallholder growers to retail and wholesale buyers. Bio Botanica Inc. anchors the botanical extract specialist tier, serving dietary supplement channels with standardized ingredient positioning.
| Leading Market Players |
|---|
| BDS Natural Products Inc. |
| Amruth Organics and Natural Store |
| Bio Botanica Inc. |
| Dabur India Ltd. |
| Dr. Willmar Schwabe GmbH and Co. KG |
| Frontier Co op |
| Green Amrut |
| McCall Farms Inc. |
| Provital SA |
| Others |
Value Chain & Pricing Dynamics
Diesel and refrigerated transport expenses trace a volatile path from Nigerian naira instability through to compressed exporter margins during peak harvest windows, with SON grade enforcement creating three distinct pricing tiers that separate premium export-eligible suppliers from domestic-only traders.
Pricing Analysis
Volume concentrates in culinary applications while margin expansion climbs fastest with exporters achieving certification tiers. Three-tier pricing structure across premium, standard, and economy levels separates SON-certified White Yam shipments from secondary grades absorbed by foodservice channels and substandard tubers entering animal feed. Cost compression in the standard tier is intensifying because cassava substitution threatens industrial starch formulations. Household diaspora consumers exhibit highest price sensitivity, while dietary supplement buyers demonstrate lowest sensitivity due to functional nutrition positioning.
Supply Chain Analysis
Direct-to-retail channels through ethnic grocery platforms in Toronto and Houston bypass traditional importer-distributor markups. Nigerian smallholder networks, Ghanaian FDA-registered cooperatives, and Dutch ingredient houses with backward integration into Ghanaian processing anchor upstream supply. The chain draws from diesel fuel, refrigerated containers, and controlled atmosphere storage infrastructure. Single-source vulnerability to Nigerian regional climate shocks and port congestion constitutes the dominant structural risk. Distribution runs through Rotterdam and Liverpool consolidation hubs for European ethnic retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified traceability infrastructure represents the decisive upstream lever as buyers consolidate supplier lists around batch-level documentation, transforming the competitive arena into a vertical-integration race between SON-compliant cooperatives and European ingredient houses.
For Market Incumbents: Anticipate cassava substitution threats in industrial starch channels by deepening captive supply of standardized Dioscorea extracts for pharmaceutical applications. Secure backward integration into controlled atmosphere storage at Lagos and Ibadan processing clusters to defend margin position against emerging certified cooperatives. Prioritize EFSA novel food dossier completion to maintain European supplement channel access.
For New Entrants and Emerging Players: Ethnic grocery e-commerce platforms in Canadian metropolitan clusters offer the most penetrable route for vacuum-packed yam portions with reduced cold chain cost structures. Target USDA organic certification conversion to access North American natural retail channels with premium positioning. Deploy direct-to-retail contracting models that bypass traditional wholesale markups concentrated in Rotterdam and Liverpool.
For Investors and Strategic Acquirers: Dutch and German ingredient houses integrating into Ghanaian processing facilities is the leading indicator that pharmaceutical extraction demand for diosgenin isolation is accelerating. Long-term viability hinges on exposure to functional nutrition and synthetic hormone precursor supply chains rather than commoditized fresh tuber trade. Monitor EFSA toxicological dossier approval velocity as the critical inflection signal for European market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Controlled Atmosphere Storage Investment | Extends White Yam shelf life from six weeks to four months for European contract fulfillment. |
| EFSA Novel Food Dossier Completion | Unlocks formal approval pathways for concentrated yam ingredients entering European supplement channels. |
| USDA Organic Certification Conversion | Enables premium price realization through North American natural retail channel access. |
| Backward Integration into Ghanaian Processing | Provides Dutch and German ingredient houses with documentation chain control for regulatory compliance. |
| Direct-to-Retail Ethnic Grocery Contracting | Bypasses three layers of intermediate distribution to improve farmgate returns for compliant exporters. |
Study Parameters
Trade databases, agricultural export statistics, and phytosanitary inspection records formed the secondary backbone for this analysis. Primary interviews with export cooperative managers, FDA inspection officials, ingredient procurement leads at multinational food processors, and cold chain logistics operators combined with secondary validation. Bottom-up triangulation across Nigerian and Ghanaian supply corridors anchored volume estimates, while top-down cross-checks against diaspora consumption patterns in the United Kingdom, Germany, and Canada refined demand projections.
Historical trendline analysis of yam export volumes, certification tier distributions, and price realization differentials established baseline growth parameters across the projection horizon. Segmentation dimensions modeled include cultivar type, end-user category, distribution channel structure, and application pathway. CAGRs were derived through exponential smoothing of validated annual growth patterns. Industry-specific forecast inputs incorporated EFSA regulatory timeline assumptions and organic certification conversion pipeline estimates.
The model holds under stable phytosanitary protocol enforcement and diaspora population retention in target import markets; deviation in Nigerian naira volatility or European novel food approval velocity would shift trajectory assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
Tomato Market
Vegetables
Europe Christmas Tree Market
Vegetables
Italy Greenhouse Horticulture Market
Vegetables
Cameroon Fruits and Vegetables Market
Vegetables
North America Christmas Tree Market
Vegetables
Zimbabwe Fruits and Vegetables Market
Vegetables
Netherlands Greenhouse Horticulture Market
Vegetables
Fresh Onions and Shallots Market
Vegetables
Garden Cress Market
Vegetables
North America Peas Market
Vegetables
North America Sweet Potatoes Market
Vegetables
Squash Market
Vegetables
Global Indoor Plant Market
Vegetables
Dried Mushroom Market
Vegetables
Algeria Fruits and Vegetables Market
Vegetables
Europe Flowers and Ornamental Plants Market