
 Tomato Market | 2026-2036
Tomato Market Size, Share, and Industry Trends Forecast 2026-2036
Tomato Market Outlook
Market Context
Single-serve clamshell packaging is pivoting toward modular portion formats that let retailers unbundle bulk harvests into consumer-ready units. Del Monte Foods leverages its retail channel control to sustain shelf presence across North American grocery chains. The Morning Star Company anchors industrial paste supply through its vertically integrated California processing network. Kagome Co. Ltd. competes in Asian food-service segments with aseptic bag-in-box configurations.
Technical and Segment Structure
Tomatoes are fleshy berries of Solanum lycopersicum containing 94-95% water, 3-5% sugars, and 1-2% acids by weight, cultivated for fresh consumption, paste extraction, and sauce manufacturing. Cherry tomatoes and Roma tomatoes dominate distinct margin pools: cherry varieties command retail premium positioning due to snacking-format demand, while Roma tomatoes concentrate in processing-plant procurement for paste and diced-product lines. Clamshells and bulk bags split the packaging segment by channel, with clamshells penetrating supermarket fresh-produce sections and bulk bags supplying canning-industry intake at scale.
Regulatory Outlook
USDA grading standards and FDA food-safety rules govern tomato quality classification and processing-plant sanitation across the United States. EU REACH and EFSA pesticide residue limits shape import access for non-European suppliers into European processing chains. Stakeholders must monitor water-use regulations in California and traceability mandates in the EU, as compliance costs will increasingly separate integrated processors from fragmented field suppliers.
Market Dynamics
Climate-smart irrigation deployment in water-stressed growing regions is compressing yield variance and redrawing procurement geography for processing-grade tomatoes.
Growth Catalysts
- EU Green Deal agricultural transition:Carbon-border adjustments and sustainable farming incentives are pulling acreage toward certified low-water operations in Spain and Italy.
- Aseptic bag-in-box packaging:Food-service distributors are adopting this format to extend shelf life and reduce cold-chain energy intensity in institutional catering.
- China:Central kitchen expansion and quick-service restaurant chain growth are concentrating paste demand around COFCO Tunhe and Xinjiang Chalkis processing corridors.
Market Restraints
- California water allocation volatility:State-level groundwater sustainability mandates are constraining planted acreage and elevating input cost uncertainty for paste processors.
- Phosphate fertilizer price swings:Energy-intensive phosphate production links tomato cultivation cost directly to natural gas and sulfur market turbulence.
- EU REACH compliance:Pesticide residue thresholds and chemical authorization timelines create import friction for non-European field suppliers.
Strategic Opportunities
- Controlled-environment agriculture:Vertical farming and greenhouse clusters in the Netherlands and Belgium are enabling year-round cherry tomato supply to northern European retail.
- India:Cold-chain infrastructure gaps and quick-commerce expansion are creating first-mover advantage for modular clamshell packaging adapted to 15-minute delivery slots.
- Precision fermentation:Convergence with tomato-derived flavor compounds is opening alternative protein and plant-based sauce formulation channels.
Industry Challenges
- Agronomic data science talent:Field operations lack sufficient yield-modeling and predictive irrigation specialists to deploy sensor networks at scale.
- Sanitation capex cycles:FDA food-safety modernization rules are forcing processing-plant retooling timelines that strain mid-tier operator balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tomato Market |
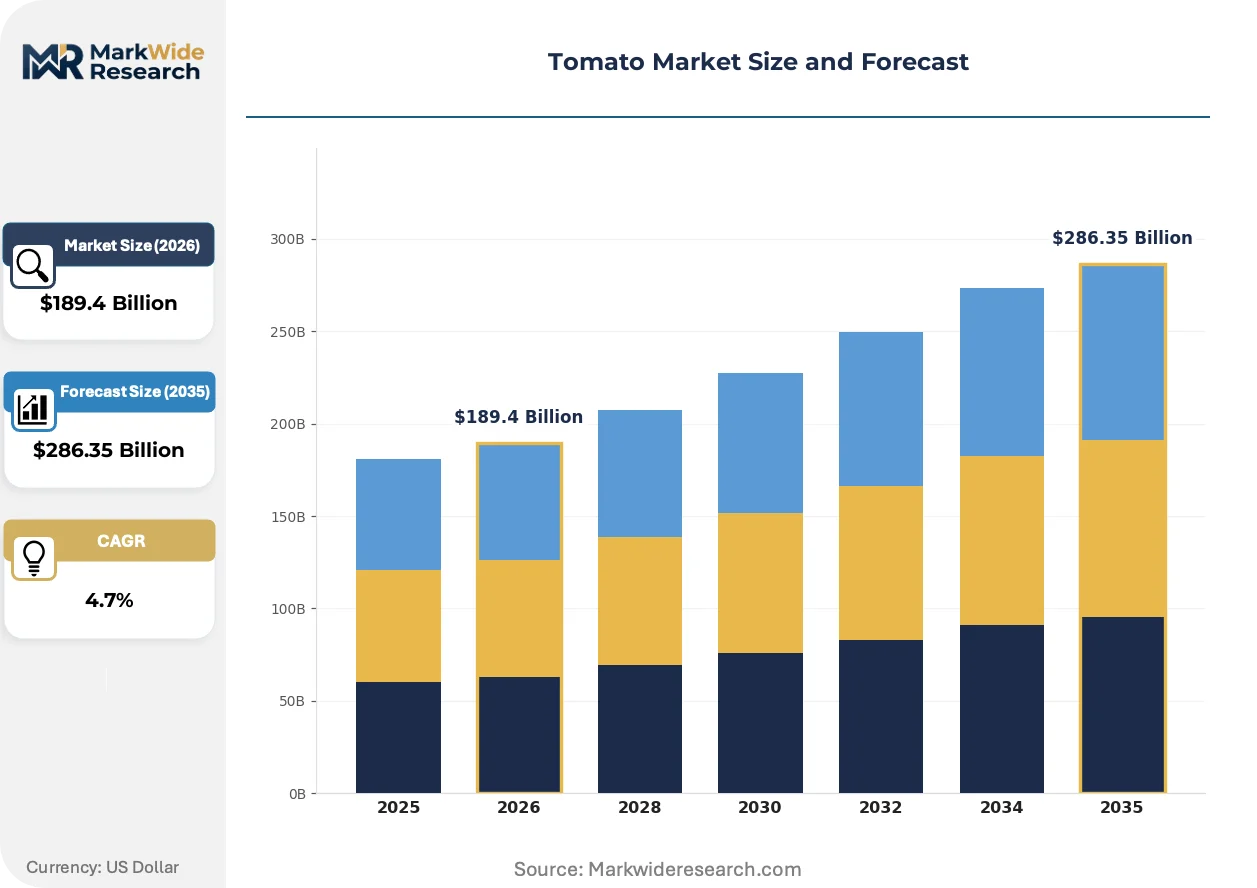
| Market Size in 2026 | $189.4 Billion |
| Market Size in 2035 | $286.35 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cherry Tomatoes, Roma Tomatoes, Beefsteak Tomatoes, Vine-Ripened Tomatoes Packaging Type: Cartons, Clamshells, Bulk Bags, Trays Distribution Channel: Supermarkets, Farmers Markets, Online Retail, Wholesalers End User: Food Service, Households, Canning Industry, Processing Plants |
| Companies Covered | Ingomar Packing Co., Del Monte Foods Inc., The Morning Star Company, Kagome Co. Ltd., Campbell Soup Company, COFCO Tunhe Tomato Co. Ltd., Conagra Brands Inc., Mutti S.p.A., Xinjiang Chalkis Company Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tomato Market Strategic Shifts
Digital agriculture platforms and packaging format innovation are compressing the gap between harvest and shelf while rewriting how quality premiums attach to origin stories.
Sensor-driven deficit irrigation is rewriting field water productivity benchmarks. California's Central Valley operators are deploying soil-moisture telemetry and evapotranspiration modeling to cut applied water volumes by double-digit percentages without paste yield sacrifice. This technology is compressing the cost spread between gravity-fed and precision-irrigated acreage.
EU Deforestation Regulation traceability mandates are reshaping import documentation burdens. Processors sourcing from Brazil, Argentina, and high-risk jurisdictions must now prove geolocation compliance for every field parcel. Tomato paste importers into Rotterdam and Hamburg are responding by shortening supplier lists to vertically integrated growers with captive satellite-mapped acreage.
Quick-commerce platforms are fragmenting retail procurement into smaller, more frequent orders. Dark-store operators in Seoul, São Paulo, and London are bypassing traditional wholesale markets and contracting directly with greenhouse clusters for 48-hour cherry tomato turnaround. This channel shift is most visible in East Asian megacities where 15-minute delivery apps now capture measurable fresh-tomato volume share.
Tomato Market Segmentation
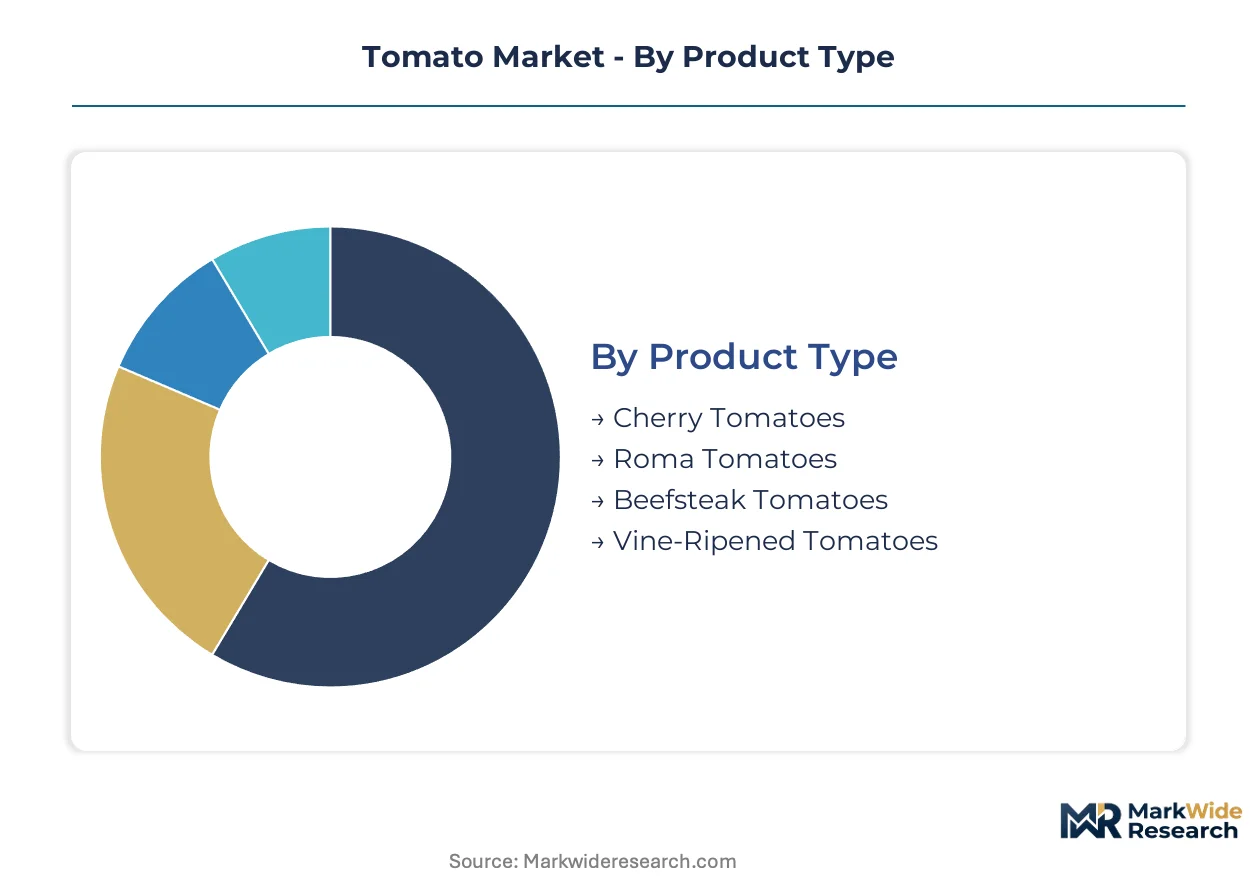
Tomato segmentation separates margin pools by use-case intensity and supply-chain position. Cherry and Roma varieties occupy distinct value chains, while packaging format determines whether product flows through retail or industrial channels.
Product Type:
Integration depth varies sharply: snacking formats operate as standalone consumer products, while processing-grade tomatoes embed as ingredients in downstream manufacturing.
- Cherry Tomatoes:Small-fruited varieties with elevated Brix content (6-8%) and thin skin optimized for raw consumption. Demand concentrates in East Asian quick-commerce channels where 15-minute delivery apps source directly from greenhouse clusters in the Netherlands and Belgium.
- Roma Tomatoes:Oblate, determinate varieties with lower moisture (92-93%) and thicker flesh engineered for paste concentration. California's Central Valley and Spain's Extremadura region anchor procurement for industrial processors; water allocation volatility constrains planted acreage.
- Beefsteak Tomatoes:Large, indeterminate slicing varieties with high juice content commanding sandwich and salad applications.
- Vine-Ripened Tomatoes:Cluster-harvested fruit sold on-the-vine for extended shelf life and visual retail appeal.
Volume placements concentrate in Roma tomatoes for paste extraction; the faster expansion belongs to cherry tomatoes in premium snacking formats.
Packaging Type:
Cost tier stratification runs from premium consumer-facing formats to bulk industrial intake systems.
- Clamshells:Clear PET or rPET hinged containers with modified atmosphere properties protecting cherry and grape tomatoes through retail distribution. Supermarket chains specify tamper-evident seals and modular case counts for automated shelf stocking.
- Bulk Bags:Woven polypropylene or paper sacks handling 25-50 pound loads for canning-industry intake. Processing plants in Italy's Po Valley and California's San Joaquin Valley specify food-grade liners meeting FDA and EFSA migration limits.
- Cartons:Corrugated fiberboard cases with ventilation apertures for vine-ripened and beefsteak varieties in wholesale produce markets.
- Trays:Expanded polystyrene or molded pulp platforms for food-service pre-portioning and institutional catering contracts.
Margin capture clusters in clamshell configurations; steepest volume expansion tracks bulk bags serving central kitchen and quick-service restaurant supply chains.
Distribution Channel:
Customer type determines fulfillment architecture: household purchasers trigger fragmented last-mile logistics, while institutional buyers consolidate through contracted procurement.
- Supermarkets:Traditional grocery chains controlling shelf space allocation and private-label sourcing decisions across North American and European retail networks.
- Online Retail:Quick-commerce platforms and e-grocers fragmenting order sizes while demanding 48-hour turnaround from greenhouse suppliers.
- Farmers Markets:Direct-to-consumer venues capturing premium pricing for heirloom and specialty varieties in urban catchment areas.
- Wholesalers:Centralized produce terminals aggregating field harvests for redistribution to independent retailers and food-service distributors.
Procurement gravity centers on supermarket chains for volume; online retail channels are climbing the fastest as dark-store networks expand across East Asian and Latin American megacities.
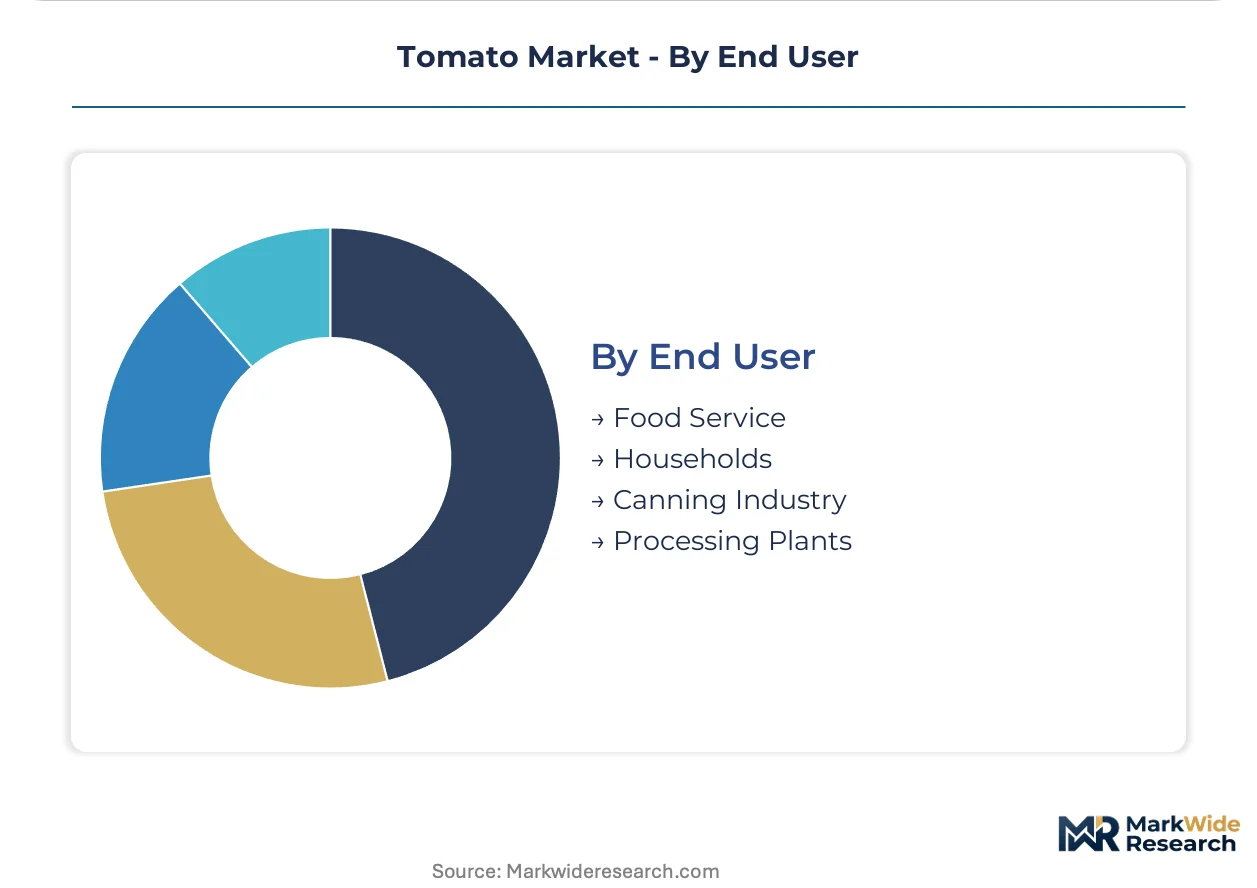
End User:
Application maturity separates established industrial demand from emerging consumption patterns in food-service and household segments.
- Canning Industry:Mature demand segment purchasing whole peeled, diced, and stewed tomato products in institutional formats. EU Deforestation Regulation traceability mandates are shortening approved supplier lists to vertically integrated growers with satellite-mapped acreage.
- Food Service:Restaurants, cafeterias, and catering operations specifying aseptic bag-in-box and pouch formats for sauce and paste applications. China's central kitchen expansion is concentrating demand around COFCO Tunhe processing corridors.
- Households:Retail consumers purchasing fresh tomatoes through supermarket and quick-commerce channels for home preparation.
- Processing Plants:Industrial facilities extracting paste, juice, and concentrate for downstream sauce and ketchup manufacturing.
Volume concentration remains with canning and processing plants; food-service applications are expanding most quickly through aseptic packaging adoption in institutional catering.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Processing-grade harvests concentrate in water-stressed zones while fresh consumption clusters near affluent urban corridors. California's Central Valley and Spain's Extremadura anchor paste extraction capacity. China's Xinjiang corridor and Italy's Po Valley complete the quartet of dominant supply basins.
United States
California's Central Valley supplies the majority of processing-grade Roma tomatoes for paste extraction. The state's Sustainable Groundwater Management Act constrains planted acreage through groundwater basin sustainability plans. Fresno County and San Joaquin Valley processors deploy sensor-driven deficit irrigation to maintain yields under tightening water allocations.
China
Central kitchen expansion and quick-service restaurant chain growth concentrate paste demand in Xinjiang and Inner Mongolia. The Ministry of Ecology and Environment enforces dual carbon goals that reshape energy inputs at processing facilities. COFCO Tunhe and Xinjiang Chalkis anchor processing corridors around Urumqi and Shihezi with integrated field-to-factory operations.
Spain
Extremadura and Andalusia field operations supply European canning and sauce manufacturers with processing-grade tomatoes. EU Green Deal agricultural transition incentives pull acreage toward certified low-water operations under Common Agricultural Policy restructuring. Badajoz province clusters greenhouse and open-field production for export to Northern European retail chains.
Italy
The Po Valley and Campania regions sustain heritage paste extraction and canned whole-peeled tomato production. EFSA pesticide residue limits and EU REACH chemical authorization timelines create compliance thresholds for non-European import competition. Parma and Foggia processing plants source from satellite-mapped acreage to satisfy EU Deforestation Regulation traceability mandates.
Netherlands
Greenhouse clusters in Westland and Venlo enable year-round cherry tomato supply to Northern European retail and quick-commerce channels. The country's national environmental agency enforces stringent water discharge and energy efficiency standards on controlled-environment agriculture. Dutch growers export premium snacking-format tomatoes to German supermarket chains and British e-grocers.
Tomato Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across distinct margin pools. The vendor base organizes around three strategic archetypes: vertically integrated field-to-factory operators controlling California or Xinjiang acreage; retail-brand conglomerates leveraging shelf-space negotiation power; and regional sauce specialists commanding premium positioning in European gastronomy channels. Dominant competitive moves include backward integration into captive tomato supply and geographic expansion through processing-plant acquisitions in water-secure jurisdictions.
Among North American integrated processors, The Morning Star Company and Del Monte Foods occupy positions at opposite ends of the control spectrum. The former exemplifies pure-play vertical integration through captive California processing networks, while the latter represents retail-channel leverage across grocery chain produce sections. Kagome Co. Ltd. anchors Asian food-service supply through aseptic packaging specialization, sitting within the regional-sauce archetype that competes on format innovation rather than field control.
| Leading Market Players |
|---|
| Ingomar Packing Co. |
| Del Monte Foods Inc. |
| The Morning Star Company |
| Kagome Co. Ltd. |
| Campbell Soup Company |
| COFCO Tunhe Tomato Co. Ltd. |
| Conagra Brands Inc. |
| Mutti S.p.A. |
| Xinjiang Chalkis Company Ltd. |
| Others |
Value Chain & Pricing Dynamics
Captive field-to-factory integration across California's Central Valley and Xinjiang processing corridors anchors both procurement security and margin capture for paste-grade tomato supply. This upstream control insulates integrated processors from spot-market volatility while compressing price premiums available to fragmented field suppliers.
Pricing Analysis
Margin tightening in standard-grade paste reflects phosphate fertilizer price volatility tied to natural gas and sulfur market turbulence. Three-tier pricing structure across premium snacking formats, standard processing grades, and economy bulk supply separates cherry tomato clamshells from Roma paste extraction and institutional food-service intake. Pricing pressure accelerates in California processing corridors as groundwater sustainability mandates constrain planted acreage. Quick-commerce platforms exhibit highest price sensitivity due to 15-minute delivery slot economics, while vertically integrated canning operations show lowest sensitivity through captive supply contracts.
Supply Chain Analysis
Phosphate fertilizer supply rests on Moroccan and Chinese mining operations, while aseptic packaging films draw from German and Japanese specialty chemical producers. Water allocation constraints in California and Spain concentrate processing-grade procurement geography, with seed genetics and irrigation equipment dependencies running through Dutch greenhouse technology clusters. Single-source vulnerability sits with Xinjiang corridor concentration for Asian paste supply. Distribution runs through Rotterdam and Hamburg port terminals for European canning intake, direct field contracts for quick-commerce dark stores, and contracted procurement for institutional food-service chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Deforestation Regulation traceability mandates erect a compliance moat that favors satellite-mapped, vertically integrated growers over fragmented field suppliers unable to document geolocation provenance.
For Market Incumbents: Anchor processing capacity in water-secure jurisdictions such as Spain's Extremadura or Italy's Po Valley to offset California groundwater allocation volatility. Invest in sensor-driven deficit irrigation certification to satisfy EU Green Deal agricultural transition incentives and defend margin position against emerging greenhouse operators in the Netherlands and Belgium. For New Entrants and Emerging Players: Precision fermentation platforms for tomato-derived flavor compounds offer technology-first wedge into alternative protein and plant-based sauce formulation channels. Target India's cold-chain infrastructure gaps with modular clamshell packaging adapted to 15-minute delivery slots, leveraging quick-commerce expansion in Mumbai and Bangalore through direct greenhouse contracts. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified food conglomerates seeking backward integration into captive tomato supply. Long-term viability favors processors with satellite-mapped acreage satisfying EU Deforestation Regulation mandates. Watch California Sustainable Groundwater Management Act enforcement intensity as inflection indicator for processing-grade supply constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Acreage | Satellite-mapped field operations satisfy EU Deforestation Regulation traceability mandates for Rotterdam and Hamburg import terminals. |
| Sensor-Driven Deficit Irrigation Deployment | Soil-moisture telemetry cuts applied water volumes while maintaining paste yields under California groundwater sustainability plans. |
| Aseptic Bag-in-Box Format Expansion | Extended shelf-life packaging reduces cold-chain energy intensity for institutional catering contracts in China's central kitchen corridor. |
| Controlled-Environment Agriculture Scale-Up | Greenhouse clusters in Westland and Venlo enable year-round cherry tomato supply to East Asian quick-commerce platforms. |
| Precision Fermentation Partnership | Tomato-derived flavor compound convergence opens alternative protein formulation channels beyond traditional paste extraction. |
Study Parameters
Independent corroboration across processing plant managers, agricultural procurement leads at canning conglomerates, greenhouse technology specialists, and food-service distribution channel partners underwrites the qualitative findings. Secondary validation draws from USDA grading standards documentation, EFSA pesticide residue databases, EU REACH chemical authorization timelines, and customs records tracking tomato paste import flows into Rotterdam and Hamburg. Bottom-up field interviews with California Central Valley operators and Xinjiang corridor processors triangulate against top-down trade data and regulatory filing analysis.
Rate-of-change decomposition across the analysis window separates volume trajectory from price realization and mix-shift effects. Segmentation dimensions modeled include product type (cherry, Roma, beefsteak, vine-ripened), packaging format (clamshell, bulk bag, carton, tray), distribution channel (supermarket, online retail, farmers market, wholesaler), and end-use application (canning, food service, household, processing plant). CAGRs derive from iterative convergence between supply-side capacity buildouts and demand-side penetration curves, with water allocation constraints and fertilizer cost volatility as tomato-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under California groundwater sustainability plan enforcement intensity and EU Green Deal carbon-border adjustment implementation pace. Forecasts reflect documented assumptions regarding climate-smart irrigation adoption rates and quick-commerce platform expansion trajectories. A small set of named triggers—phosphate fertilizer price spikes, FDA food-safety modernization rule retooling timelines, and China dual carbon goals enforcement—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
Europe Christmas Tree Market
Vegetables
Europe Flowers and Ornamental Plants Market
Vegetables
Asparagus Market
Vegetables
Sweet Potatoes Market
Vegetables
India Greenhouse Horticulture Market
Vegetables
North America Microgreens Market
Vegetables
Butternut Squash Market
Vegetables
Global Indoor Plant Market
Vegetables
Vegetable Grader Market
Vegetables
North America Christmas Tree Market
Vegetables
Asia-Pacific Peas Market
Vegetables
Italy Greenhouse Horticulture Market
Vegetables
Turkey Greenhouse Horticulture Market
Vegetables
Global Mushroom Market
Vegetables
Tanzania Fruit and Vegetables Market
Vegetables
Zimbabwe Fruits and Vegetables Market