
 Dried Peas Market | 2026-2036
Dried Peas Market Size, Share, and Industry Trends Forecast 2026-2036
Dried Peas Market Foresight
Direct sourcing contracts between processors and farm cooperatives is reshaping how dried peas move from field to formulation. AGT Food and Ingredients leverages its vertically integrated network across Canadian prairie provinces to secure consistent supply. Roquette Frères anchors European demand through its specialized pea protein extraction facilities in France. The Scoular Company competes by controlling inland logistics and origination points across the northern Great Plains.
Dried peas are mature legume seeds dehydrated to moisture levels below 14 percent, primarily milled into protein concentrates, starches, and fibers for food and feed applications. Yellow peas dominate industrial offtake due to higher protein content and neutral flavor profiles suited to extrusion processes. The plant-based products end-use segment leads growth velocity as food processors reformulate meat analogues around pea protein isolates. Supermarkets and wholesale distributors still occupy the largest share of volume movement, though online retailers are capturing specialty and organic SKUs.
The FDA oversees food-grade pea protein safety under GRAS notifications, while the USDA sets grading standards for whole and split peas that determine export eligibility. Health Canada and EFSA have each published favorable protein quality assessments that facilitate ingredient approvals in North American and European formulated foods. Stakeholders must monitor evolving allergen labeling requirements and carbon intensity scoring for plant-protein supply chains.
Market Dynamics
Yellow pea protein isolate demand from plant-based meat manufacturers is restructuring procurement relationships across the northern Great Plains processing corridor, forcing handlers to lock in multi-year origination contracts ahead of competing food ingredient buyers.
Growth Catalysts
- USDA Grading Standards:The USDA's uniform standards for whole and split peas create transparent quality benchmarks that facilitate export eligibility and reduce transaction friction in cross-border trade.
- EFSA Protein Quality Assessments:Favorable scientific opinions from EFSA on pea protein nutritional profiles accelerate ingredient approvals for European formulated food applications.
- Extrusion Technology Maturation:Advances in high-moisture extrusion enable food processors to achieve meat-like fibrous textures from yellow pea isolates at commercial scale.
Market Restraints
- Input Cost Volatility:Diesel and natural gas price swings directly compress margins for processors operating energy-intensive drying and milling equipment across prairie production zones.
- Supply Concentration Risk:Yellow pea origination concentrates in a narrow band of North Dakota, Minnesota, and Montana counties, exposing buyers to single-region weather shocks.
- Regulatory Friction:Divergent FDA and USDA jurisdiction over pea protein isolates versus whole peas creates compliance complexity for exporters serving multiple end-use categories.
Strategic Opportunities
- Carbon Intensity Scoring:Emerging EU Green Deal requirements for supply chain emissions transparency favor North American peas with lower transport distances to Atlantic ports versus competing origins.
- Specialty Organic Channels:Online retailers are capturing premium organic SKU volumes that bypass traditional supermarket wholesale distribution markups.
- Feed Protein Substitution:Aquaculture feed formulators in Norway and Scotland are testing pea protein concentrates as partial replacements for fishmeal and soybean meal.
Industry Challenges
- Allergen Labeling Complexity:Evolving FSSAI and Health Canada requirements for pulse allergen declarations force reformulation of legacy products and extended certification timelines.
- IP Licensing Friction:Patent thickets around specific pea protein extraction methods and functional property modifications create negotiation overhead for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dried Peas Market |
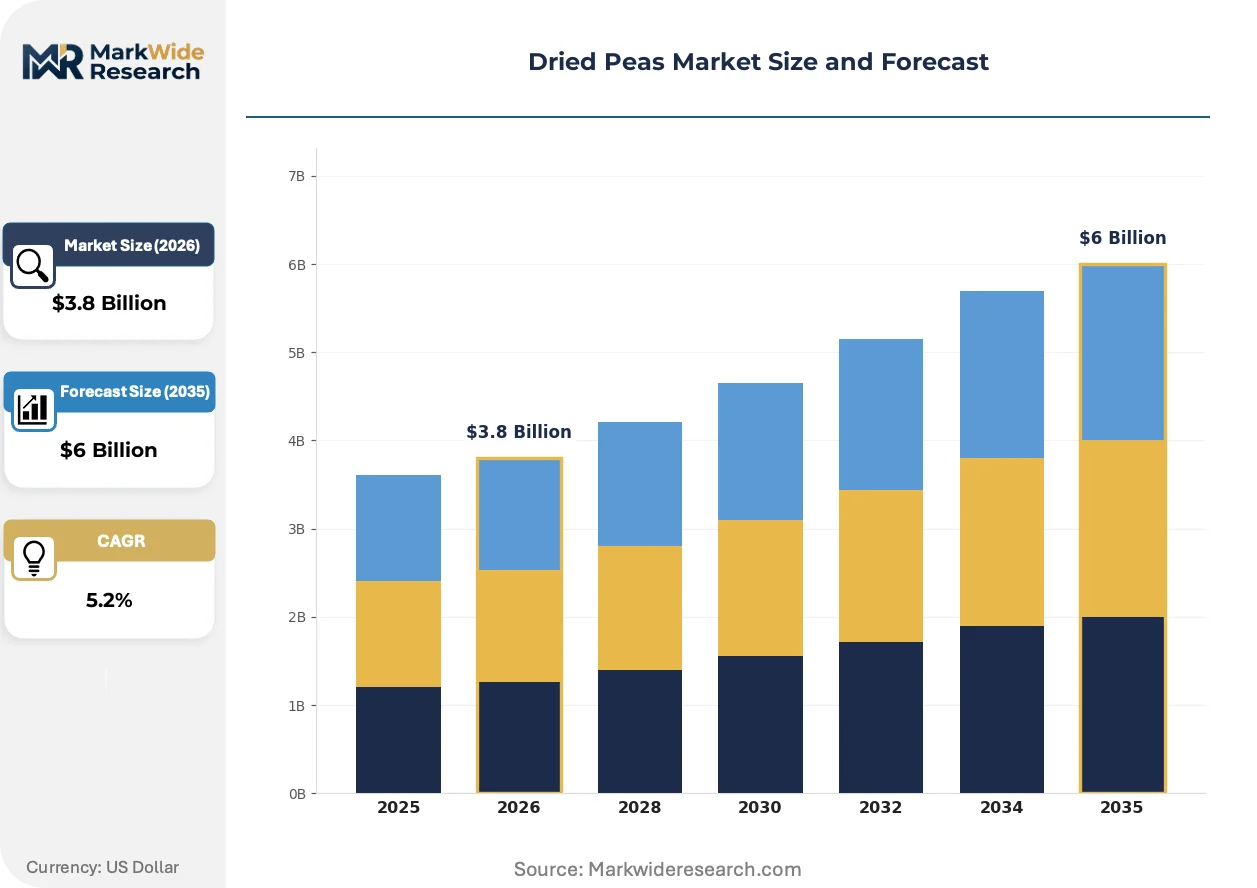
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Green Peas, Yellow Peas, Split Peas, Others End Use Industry: Food Processing, Animal Feed, Nutraceuticals, Plant-based Products Distribution Channel: Supermarkets, Online Retailers, Wholesale Distributors, Direct Sales Packaging Type: Bags, Bulk Containers, Boxes, Cans |
| Companies Covered | AGT Food and Ingredients, Roquette Frères, The Scoular Company, Vestkorn Milling AS, Dakota Dry Bean, Goya Foods, Ingredion, Cosucra Groupe Warcoing, Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dried Peas Market Shifts & Advancements
Processing technology and procurement models are converging to compress value chain margins while expanding addressable applications for pea-derived ingredients beyond traditional food uses.
Dry fractionation using air classification is collapsing the capital barrier between commodity pea milling and specialty protein concentrate production. Mid-scale processors in the Upper Midwest are adopting retrofitted equipment to capture isolate-grade output without greenfield extraction facilities. This technology diffusion is eroding the historical volume threshold that protected large-scale French and Canadian operators.
REACH registration requirements for novel protein isolates entering European industrial applications are tightening purity and contaminant documentation standards. The regulation forces exporters to invest in expanded laboratory testing capacity and batch-level traceability systems. Food-grade pea protein shipments to EU compounders now face extended pre-clearance protocols compared to feed-grade consignments.
Direct contracting between farm cooperatives and ingredient processors is displacing spot-market accumulation through traditional grain elevators. This pattern concentrates origination control among handlers with balance-sheet capacity to advance planting-season capital. The shift is most pronounced in North Dakota's Red River Valley, where processor-owned storage assets now capture twenty percent of regional production ahead of traditional merchant channels.
Dried Peas Market Segmentation
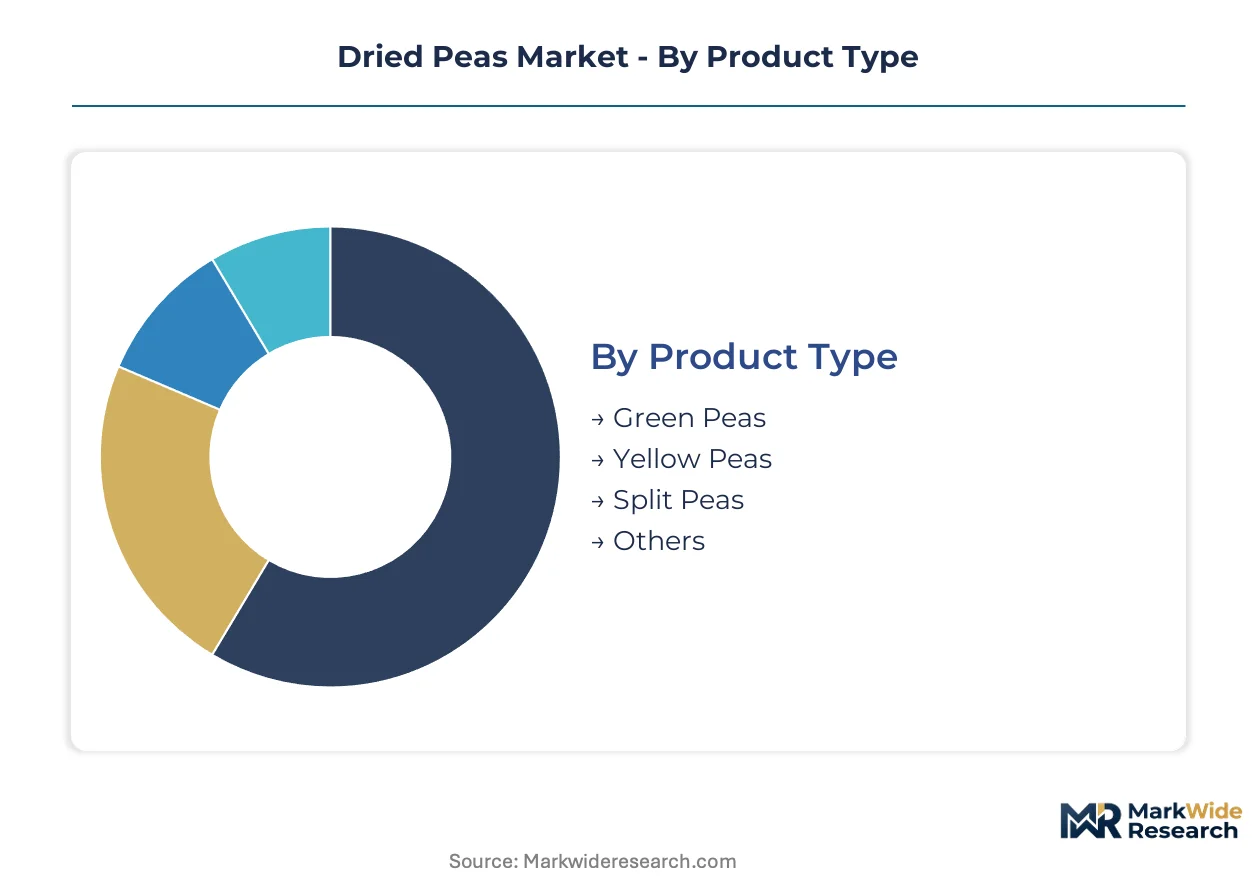
Dried peas fragment across four distinct classification axes that determine procurement economics and margin capture. Product type and end-use industry classifications exert the strongest influence on pricing power, while distribution channel and packaging type configurations shape working capital intensity for handlers.
Product Type:
Maturity varies sharply across this category, with commodity formats facing margin compression while protein-dense variants command ingredient-grade premiums.
- Yellow Peas:Higher protein content and neutral flavor profiles suit high-moisture extrusion processes for meat analogues. Demand concentrates in North Dakota and Minnesota processing corridors where Roquette and AGT Food and Ingredients anchor origination contracts for isolate production.
- Green Peas:Lower protein density limits industrial ingredient applications but sustains steady foodservice and retail whole-pea demand. European supermarkets and North American canneries maintain consistent offtake for soup and side-dish formulations.
- Split Peas:Mature milling product for soup manufacturers with established USDA grading specifications.
- Others:Specialty heirloom varieties and organic-certified lines serving premium online retail channels.
Yellow peas retain volume leadership in industrial procurement; green peas hold the steepest expansion curve in specialty organic channels.
End Use Industry:
Application diversity spans commodity feed rations through high-value nutraceutical isolates, with margin tiers separating bulk compounders from branded food manufacturers.
- Plant-based Products:Extruded meat analogues, dairy alternatives, and protein-fortified beverages drive isolate-grade demand. FDA GRAS notifications and EFSA protein quality assessments accelerate formulation approvals across North American and European food processing lines.
- Food Processing:Mature segment encompassing canned peas, dry soup mixes, and flour applications with price-sensitive procurement through wholesale distributors.
- Animal Feed:Aquaculture feed trials in Norway and Scotland test pea protein concentrates as partial fishmeal replacements.
- Nutraceuticals:Protein powders and supplement formulations requiring enhanced purity documentation under REACH registration protocols.
Food Processing retains volume leadership; Plant-based Products gains share fastest as extrusion technology matures.
Distribution Channel:
Channel selection determines margin retention versus volume velocity, with direct contracting eroding traditional elevator accumulation models.
- Direct Sales:Processor-to-cooperative contracting locks in origination ahead of harvest, concentrating control among handlers with planting-season advance capacity. The Scoular Company leverages this structure across Montana and North Dakota.
- Supermarkets:High-volume retail movement for branded and private-label dry goods with established shelf-space economics.
- Wholesale Distributors:Traditional aggregation point for foodservice and industrial buyers with regional warehousing networks.
- Online Retailers:Specialty organic SKUs bypass conventional markups, capturing premium pricing for traceable supply chains.
Wholesale Distributors retains volume leadership; Direct Sales climbs the fastest as origination control concentrates.
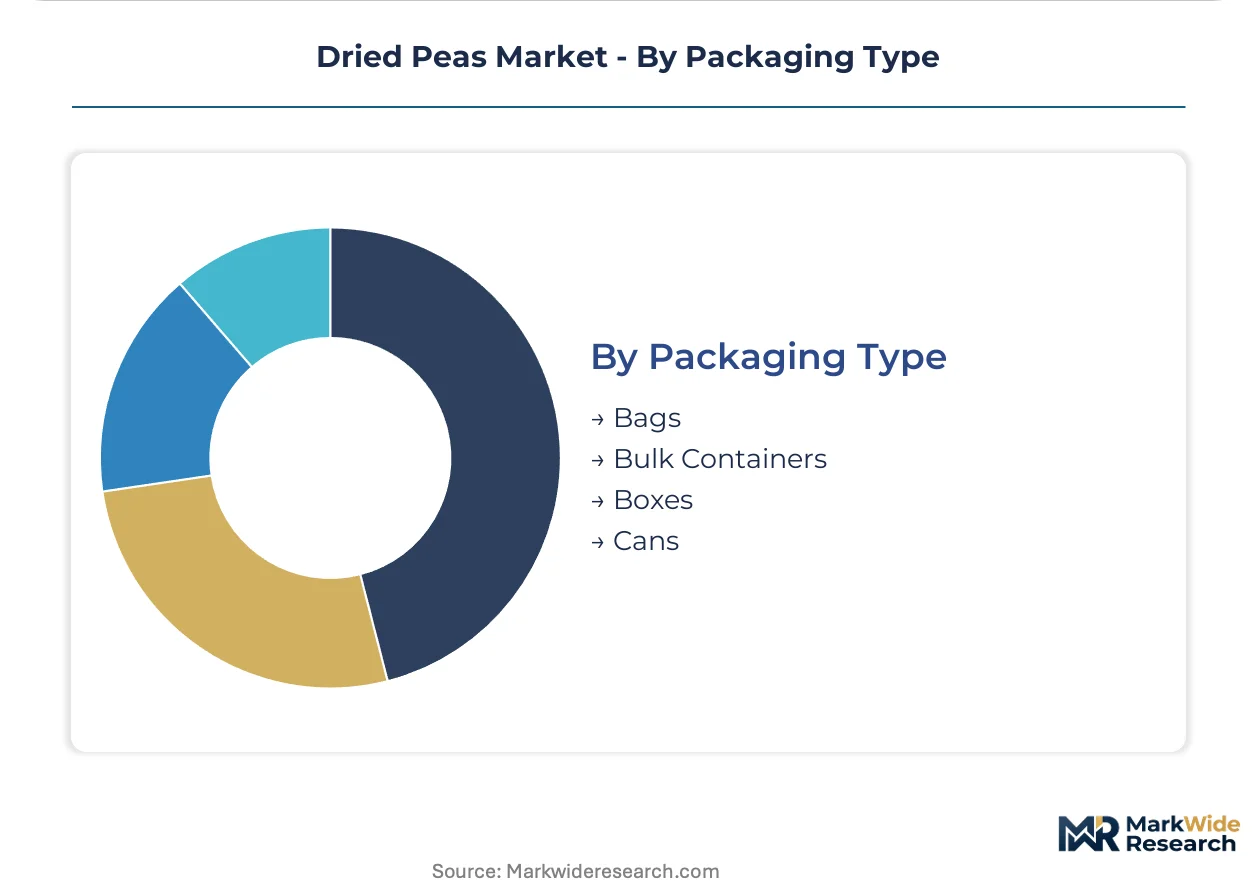
Packaging Type:
Packaging configuration aligns with customer scale and shelf-life requirements, from export-grade bulk to consumer-facing unit formats.
- Bulk Containers:Intermodal totes and railcar shipments dominate ingredient-processor procurement, minimizing per-unit handling costs for high-volume extrusion facilities.
- Bags:Standard 25-50 pound woven polypropylene for foodservice and small-scale food manufacturing.
- Boxes:Retail-ready cases for supermarket distribution with pallet-level traceability.
- Cans:Shelf-stable consumer formats for emergency food programs and conventional grocery.
Bulk Containers retains volume leadership; Bags holds the steepest expansion curve in mid-scale processor adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Vancouver anchors trans-Pacific pea protein shipments to Asian compounders. Canadian National Railway's prairie corridor links North Dakota processing plants to Pacific export terminals. Rotterdam's Maasvlakte distribution complex funnels North American isolates into European extrusion facilities.
United States
Yellow pea protein demand from Beyond Meat and Impossible Foods restructuring procurement across the northern Great Plains. The USDA maintains distinct grading standards for whole and split peas that determine cross-border export eligibility. North Dakota's Red River Valley concentrates processor-owned storage assets capturing twenty percent of regional production ahead of traditional merchant channels.
Canada
AGT Food and Ingredients leverages vertically integrated networks across Saskatchewan and Manitoba prairie provinces to secure consistent supply for European isolate buyers. Health Canada published favorable protein quality assessments facilitating ingredient approvals in North American formulated foods. The Port of Prince Rupert's deepening project accelerates containerized pea protein shipments to Asian markets versus Vancouver congestion.
France
Roquette Frères anchors European demand through specialized pea protein extraction facilities in Lestrem supplying Nestlé and Unilever reformulation programs. EFSA scientific opinions on pea protein nutritional profiles accelerate ingredient approvals for European food applications. The Hauts-de-France region's biorefinery cluster concentrates extrusion technology maturation for meat analogue texture replication.
Norway
Aquaculture feed formulators in Bergen and Trondheim test pea protein concentrates as partial replacements for fishmeal and soybean meal in salmon rations. REACH registration requirements for novel protein isolates tighten purity documentation standards forcing exporters to invest in expanded laboratory testing capacity. The Norwegian Food Safety Authority monitors evolving allergen labeling requirements for pulse ingredient declarations.
India
FSSAI evolving requirements for pulse allergen declarations force reformulation of legacy products and extended certification timelines for imported pea protein isolates. The country's national food regulator maintains distinct jurisdiction over plant-protein safety assessments versus feed-grade approvals. Mumbai's specialty chemical importers face extended pre-clearance protocols for food-grade consignments compared to feed-grade shipments.
Dried Peas Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream capturing margin on isolate purity and functional property specifications. The vendor base organizes around three archetypes: vertically integrated prairie processors controlling origination through farm cooperative contracts, European extraction specialists commanding premium isolate grades, and diversified agricultural traders leveraging logistics assets for spot-market accumulation. Dominant competitive moves include direct contracting between processors and farm cooperatives displacing traditional elevator accumulation, and technology licensing for high-moisture extrusion processes enabling meat-like texture replication.
Among North American vertically integrated processors, AGT Food and Ingredients and The Scoular Company occupy positions exemplifying the origination-control archetype. Roquette Frères sits within the European extraction-specialist tier commanding premium pricing for isolate-grade outputs. These three named entities represent the competitive structure without exhausting the participant base.
| Leading Market Players |
|---|
| AGT Food and Ingredients |
| Roquette Frères |
| The Scoular Company |
| Vestkorn Milling AS |
| Dakota Dry Bean |
| Goya Foods |
| Ingredion |
| Cosucra Groupe Warcoing |
| Archer Daniels Midland Company |
| Others |
Supply & Pricing Matrix
Single-region weather exposure in North Dakota, Minnesota, and Montana counties determines both the spread between contract and spot pricing tiers and the shape of origination relationships across the northern Great Plains processing corridor.
Pricing Analysis
Volume-discount tiering separates long-term offtake agreements from spot-market accumulation, with three-tier pricing structure across premium, standard, and economy levels tied to protein content certification and USDA grading tier. Price differentiation rests on isolate purity specifications and carbon intensity documentation under EU Green Deal requirements. Pricing pressure stems from diesel and natural gas cost swings compressing margins for energy-intensive drying operations. Small-scale food manufacturers show highest price sensitivity, while plant-based meat manufacturers absorb premiums for consistent isolate-grade supply.
Supply Chain Analysis
Contract-manufacturing concentration sits with AGT Food and Ingredients, Roquette Frères, and The Scoular Company controlling extraction capacity and origination infrastructure across Canada, France, and the United States. Raw material flows draw from prairie pea cultivation, railcar logistics networks, and Pacific port terminals. Single-source vulnerability concentrates in the Red River Valley storage asset base. Distribution runs through processor-to-cooperative direct contracting displacing traditional grain elevator accumulation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
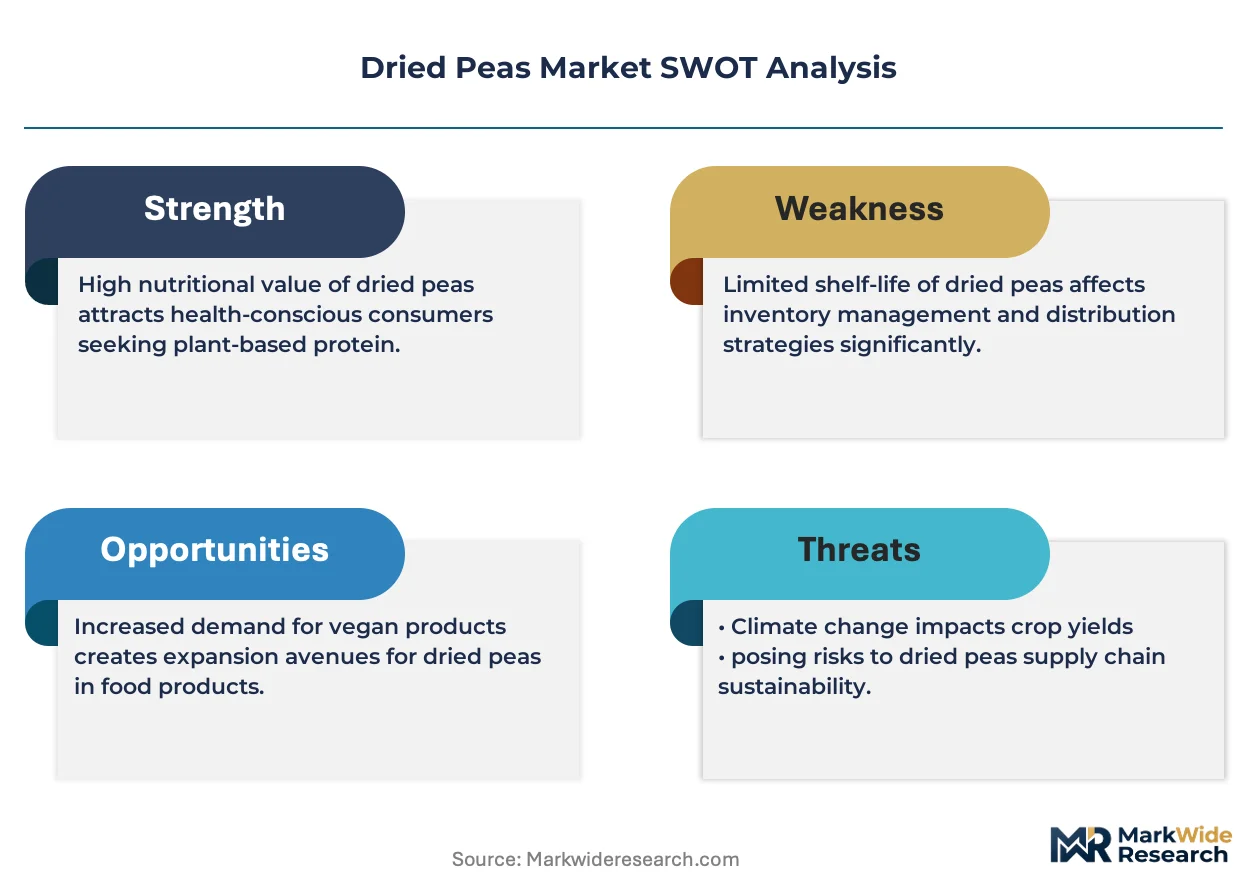
The dried peas market functions as a defensive-moat story where multi-year origination contracts create switching costs that lock processors and farm cooperatives into interdependent relationships resistant to spot-market disruption.
For Market Incumbents: Pre-empt emerging dry fractionation technology diffusion by retrofitting mid-scale milling assets in North Dakota and Minnesota before competitors collapse capital barriers to isolate-grade production. Secure planting-season advance capacity to defend origination control against diversified agricultural traders entering direct contracting. Prioritize carbon intensity scoring certification to capture EU Green Deal-compliant premium tiers.
For New Entrants and Emerging Players: Pursue specialty organic SKU channels where online retailers bypass traditional supermarket wholesale markups and reward traceable supply chain documentation. Target aquaculture feed formulators in Norway and Scotland testing pea protein concentrates as fishmeal replacements, a segment with lower purity barriers than food-grade isolate markets. Lead with sustainability credentials and batch-level traceability systems as the go-to-market angle.
For Investors and Strategic Acquirers: REACH registration requirements for novel protein isolates entering European industrial applications reshape the acquisition landscape by forcing laboratory testing capacity investments that favor scaled processors over niche operators. Long-term viability centers on handlers with balance-sheet capacity to advance planting-season capital and control inland logistics assets. Monitor FDA and USDA jurisdictional clarification efforts as the signal indicating regulatory compliance cost inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farm Cooperative Contracts | AGT Food and Ingredients secures consistent prairie supply ahead of competing ingredient buyers. |
| High-Moisture Extrusion Technology Licensing | Roquette Frères enables Nestlé and Unilever to achieve meat-like fibrous textures at commercial scale. |
| Carbon Intensity Scoring Certification | North American processors capture EU Green Deal-compliant premium tiers versus competing origins. |
| Direct-to-Processor Online Retail Channel | Specialty organic SKUs bypass traditional supermarket markups for traceable supply chains. |
| Aquaculture Feed Protein Substitution Partnership | Norwegian and Scottish formulators test pea concentrates as partial fishmeal replacements. |
Research Methodology
Initial hypotheses were tested against primary input from procurement directors at plant-based meat manufacturers, grain elevator operators, and regulatory affairs specialists at ingredient processors, and refined through secondary validation against USDA grading documentation, FDA GRAS notification filings, EFSA scientific opinions, and customs trade flow data. Bottom-up volume estimates from prairie county production statistics triangulated with top-down demand aggregation across end-use segments.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, modeling dried peas by product type, end-use industry, distribution channel, and packaging configuration dimensions. CAGRs were derived from segment-level growth trajectory convergence. Forecast inputs incorporated extrusion technology maturation curves and EU Green Deal carbon intensity scoring adoption rates.
Macroeconomic conditions sit as an overlay; deviation in diesel and natural gas price trajectories would shift the trajectory for processor margin compression and capital expenditure timing. Quarterly review of planting-season contract coverage ratios and Pacific port containerized shipment volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
Italy Greenhouse Horticulture Market
Vegetables
Saudi Arabia Greenhouse Horticulture Market
Vegetables
Fresh Mushroom Market
Vegetables
Algeria Fruits and Vegetables Market
Vegetables
Europe Pea Market
Vegetables
Field Peas Market
Vegetables
Roselle Market
Vegetables
Tomato Market
Vegetables
Hydroponic Vegetable Market
Vegetables
UAE Tomato Market
Vegetables
South America Peas Market
Vegetables
Turkey Greenhouse Horticulture Market
Vegetables
Yarrow Market
Vegetables
North America Christmas Tree Market
Vegetables
Dried Vegetable Market
Vegetables
Sprouts Market