
 UAE Tomato Market | 2026-2036
UAE Tomato Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Tomato Market Analytics
Saudi Arabia's controlled-environment agriculture expansion is tilting Gulf fresh produce dynamics toward regional self-sufficiency. Pure Harvest Smart Farms Limited leverages advanced hydroponic systems to supply premium tomatoes year-round. Al Ain Farms anchors conventional greenhouse output across the northern emirates. Elite Agro Projects LLC competes through integrated propagation-to-retail operations.
UAE tomatoes comprise Solanum lycopersicum fruits cultivated in soilless substrates or protected greenhouse environments, typically harvested at breaker-to-pink maturity stages for shelf-life optimization in desert climates. Cherry tomatoes dominate premium retail channels due to per-unit margin density and salad-kit integration. Beefsteak tomatoes sustain wholesale volume through food-service slicing applications. Clamshell packaging captures value-added supermarket placement while bulk formats serve hospitality procurement.
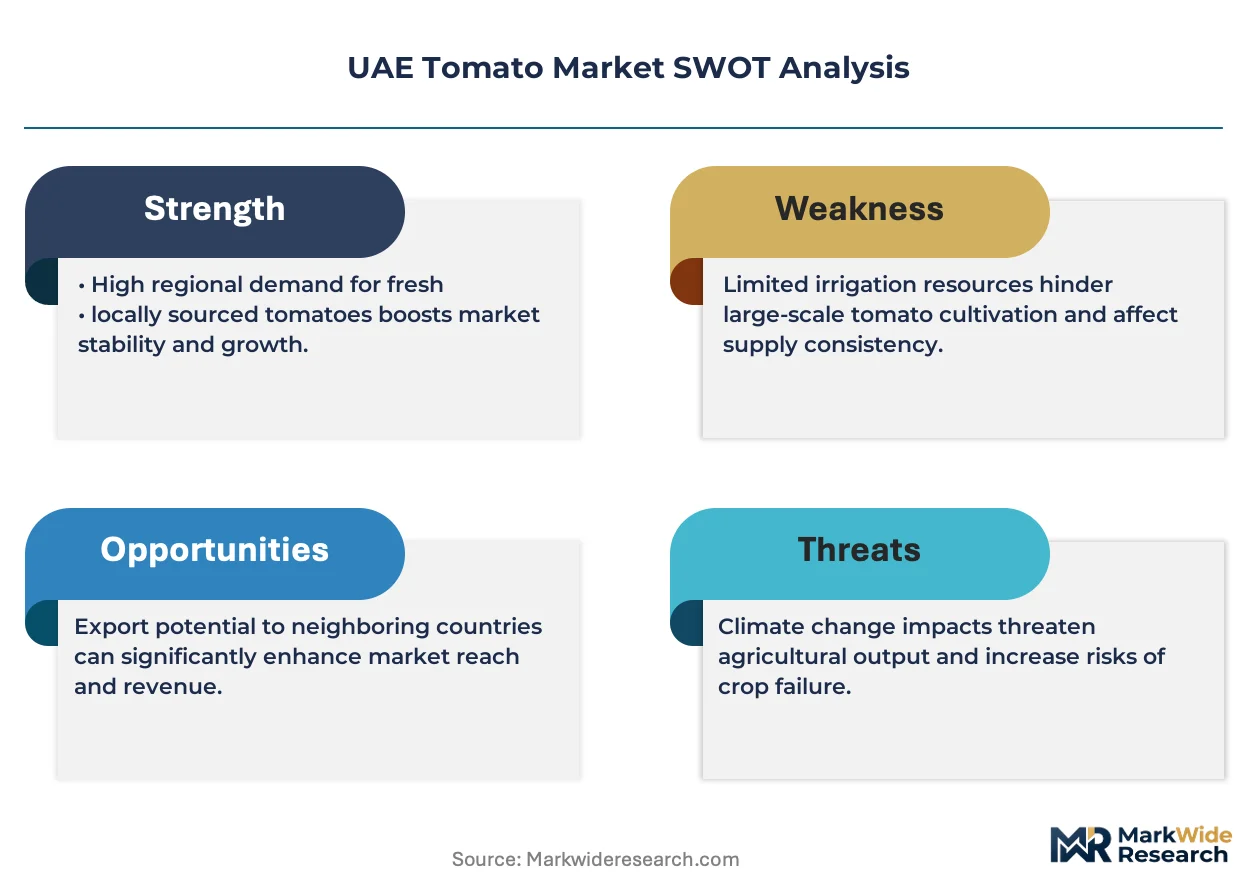
MOHAP enforces pesticide maximum residue limits aligned with GCC Standardization Organization benchmarks, compelling importers and domestic growers toward integrated pest management. The UAE's mandatory halal certification framework and ADQCC quality conformity requirements shape labeling, traceability, and cold-chain documentation for all fresh tomato distribution. Stakeholders must monitor desalination energy costs and labor visa policy shifts that directly alter protected cultivation economics.
Market Dynamics
MOHAP's tightening pesticide residue protocols are compressing import windows and forcing domestic greenhouse operators toward integrated pest management systems, fundamentally restructuring procurement economics across UAE hospitality and retail channels.
Growth Catalysts
- Controlled-Environment Agriculture:Hydroponic and greenhouse systems enable year-round Solanum lycopersicum production in desert climates, insulating domestic supply from seasonal import volatility.
- MOHAP Food Safety Framework:Stricter maximum residue limits on imported produce create preferential market access for compliant domestic growers serving hotel and restaurant clusters.
- Hospitality Sector Expansion:Dubai's hotel and restaurant procurement is concentrating demand for breaker-to-pink maturity tomatoes optimized for fresh culinary applications.
Market Restraints
- Desalination Energy Cost Exposure:Protected cultivation depends on energy-intensive reverse osmosis for irrigation, with input cost volatility directly compressing grower margins.
- Labor Visa Policy Dependency:Seasonal agricultural worker permits face administrative friction, constraining harvest workforce scalability during peak demand windows.
- Regional Import Competition:Saudi controlled-environment agriculture expansion is increasing Gulf fresh produce self-sufficiency, pressuring UAE domestic price premiums.
Strategic Opportunities
- ADQCC Quality Conformity Premium:Enhanced traceability and cold-chain documentation under halal certification frameworks unlock value-added supermarket placement.
- Cherry Tomato Segment Density:Per-unit margin concentration in salad-kit integration channels offers expansion potential beyond conventional beefsteak wholesale.
- Clamshell Packaging Innovation:Premium retail formats capture shelf-space differentiation in Dubai's consolidated supermarket landscape.
Industry Challenges
- Integrated Pest Management Skill Gaps:Biological control adoption requires specialized agronomic expertise scarce in the domestic labor pool.
- Propagation-to-Retail Coordination:Synchronized maturity staging across breaker-to-pink harvest windows demands precision logistics that strain existing cold-chain infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Tomato Market |
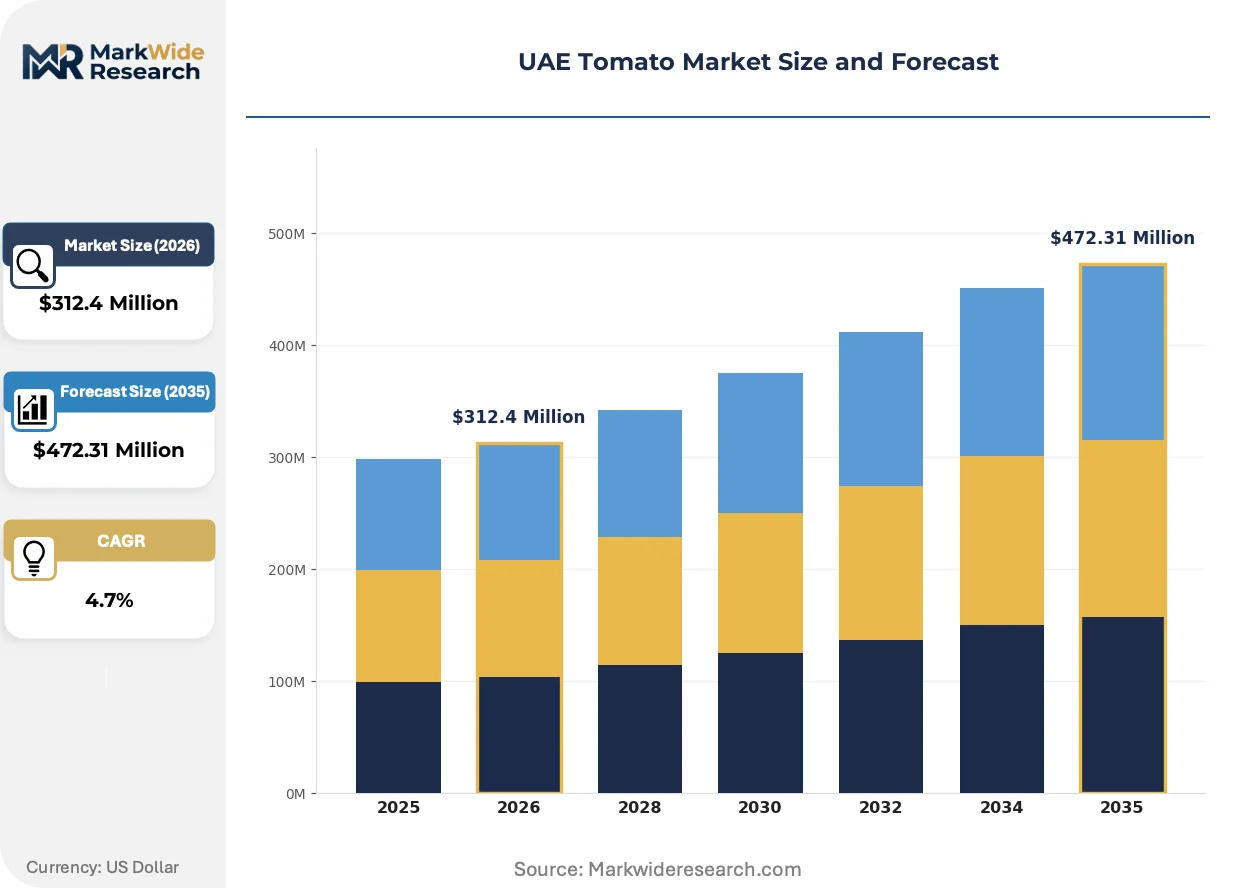
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cherry Tomatoes, Heirloom Tomatoes, Roma Tomatoes, Beefsteak Tomatoes Distribution Channel: Supermarkets, Wholesale Markets, Online Retailers, Local Farmers Markets End User: Households, Restaurants, Food Processing, Retailers Packaging Type: Clamshells, Bulk Packaging, Cartons, Polybags |
| Companies Covered | Al Ain Farms, Emirates Hydroponics Farms, Pure Harvest Smart Farms Limited, Elite Agro Projects LLC, Al Dahra Agricultural Company, Silal Food and Technology Company PJSC, Agthia Group, Badia Farms LLC, VeggiTech Farms LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Tomato Market Evolving Landscape
Horticultural technology adoption in UAE tomato production is accelerating around resource efficiency imperatives, with regulatory pressure and buyer consolidation driving convergence between automation, biological inputs, and packaging formats.
Closed-loop hydroponic nutrient film technique is migrating from experimental pilot installations to commercial-scale greenhouse operations. Large domestic growers are retrofitting conventional soil-based facilities to recirculating systems that reduce water consumption by over ninety percent. This technology compression is enabling premium cherry tomato output at unit economics competitive with imported Spanish and Dutch supply.
MOHAP's alignment with GCC Standardization Organization benchmarks is tightening enforcement timelines for pesticide residue documentation. Importers now face batch-level testing requirements that extend customs clearance durations. Domestic greenhouse operators with in-house laboratory capabilities are capturing hospitality procurement contracts previously held by Jordanian and Egyptian suppliers.
Consolidated buying by Dubai hotel procurement consortia is displacing fragmented spot-market purchasing. Large hospitality groups are negotiating annual volume contracts directly with Al Ain-based greenhouse operators, bypassing traditional wholesale intermediaries. This channel compression is most visible in the four and five-star hotel cluster along Sheikh Zayed Road.
UAE Tomato Market Segmentation
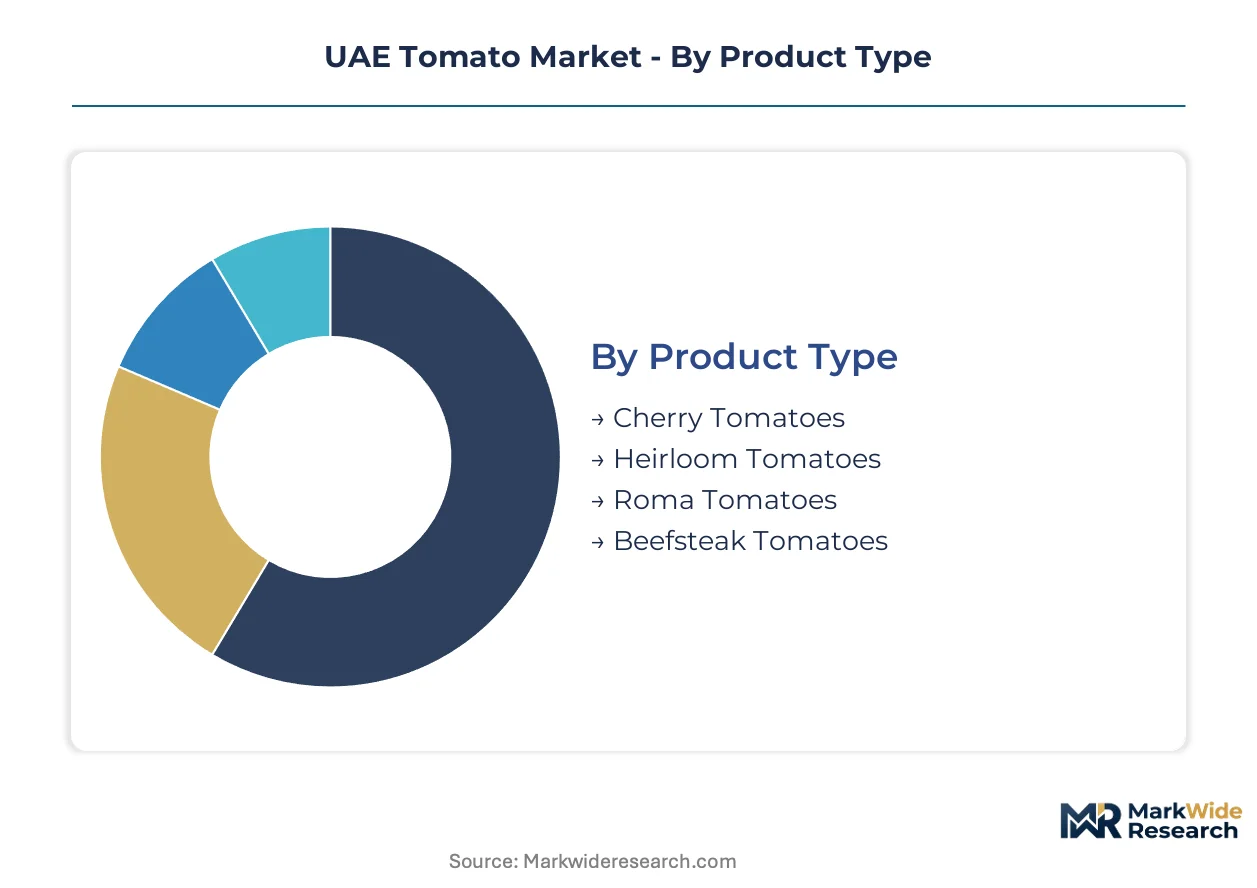
UAE tomato segmentation reflects the tension between hospitality procurement scale and premium retail margin capture. Category boundaries are blurring as controlled-environment growers pursue multi-channel placement strategies across Dubai's consolidated distribution landscape.
Product Type:
Cherry tomatoes anchor premium positioning through salad-kit integration and hotel garnish applications, while beefsteak varieties sustain food-service slicing volume across Dubai's restaurant clusters.
- Cherry Tomatoes:Small-fruited Solanum lycopersicum varieties harvested at full color for immediate consumption. Dubai hotel procurement consortia concentrate demand for uniform 15-25mm diameter fruits in clamshell presentations. Per-unit margin density and year-round greenhouse supply security favor domestic sourcing over Spanish imports.
- Beefsteak Tomatoes:Large, multi-locule fruits optimized for fresh slicing applications with pronounced ribbing and firm texture. Wholesale volume concentrates in Dubai's Al Aweer market and direct hotel contracts, with breaker-to-pink harvest timing calibrated to food-service prep schedules. Margin compression from Saudi greenhouse competition is accelerating quality differentiation investments.
- Heirloom Tomatoes:Open-pollinated varieties with non-uniform coloration and flavor intensity prized by fine-dining establishments. Limited domestic cultivation restricts supply to specialty importers and high-end restaurant direct contracts.
- Roma Tomatoes:Plum-type processing tomatoes with low moisture content and thick flesh. Food manufacturing demand for paste and sauce production channels volume through industrial procurement rather than fresh retail.
Established volume favors beefsteak tomatoes; emerging adoption favors cherry tomatoes.
Distribution Channel:
Channel structure in the UAE compresses around Dubai's logistics dominance, with cold-chain infrastructure investments determining access to premium placement tiers.
- Supermarkets:Consolidated retail banners in Dubai and Abu Dhabi demand ADQCC-compliant traceability documentation and halal certification for shelf placement. Clamshell formats and fixed-weight pricing predominate in this channel.
- Wholesale Markets:Al Aweer and Mina Zayed trading floors handle breaker-stage bulk volume for restaurant procurement and re-export to northern emirates. Spot pricing volatility and quality heterogeneity characterize transactions.
- Online Retailers:E-grocery platforms capture subscription-based household demand for cherry tomato SKUs integrated with meal-kit services. Last-mile cold-chain execution remains the critical operational constraint.
- Local Farmers Markets:Weekend direct-sales venues in Dubai and Al Ain offer premium pricing for vine-ripened greenhouse output with minimal handling stages. Limited scale constrains producer participation.
Supermarkets concentrate procurement scale; online retailers are climbing the fastest in channel expansion.
End User:
User segmentation tracks the divergence between institutional volume contracting and fragmented household purchasing patterns across the emirates.
- Restaurants:Four and five-star hotel clusters along Sheikh Zayed Road negotiate annual volume contracts directly with Al Ain-based greenhouse operators, bypassing wholesale intermediaries. Cherry tomato garnish specifications and beefsteak slicing standards dominate procurement criteria.
- Households:Consumer purchasing concentrates in supermarket clamshell formats with preference for uniform coloration and extended shelf-life indicators. Price sensitivity varies across expatriate demographic segments.
- Food Processing:Industrial users source Roma-type tomatoes for paste, sauce, and prepared meal manufacturing. Volume contracting favors Jordanian and Egyptian supply during UAE summer production gaps.
- Retailers:Independent grocery operators in Sharjah and Ras Al Khaimah depend on wholesale market intermediaries for mixed-grade tomato sourcing with limited quality consistency.
Restaurants command premium pricing power; households represent the steepest expansion trajectory in absolute volume terms.
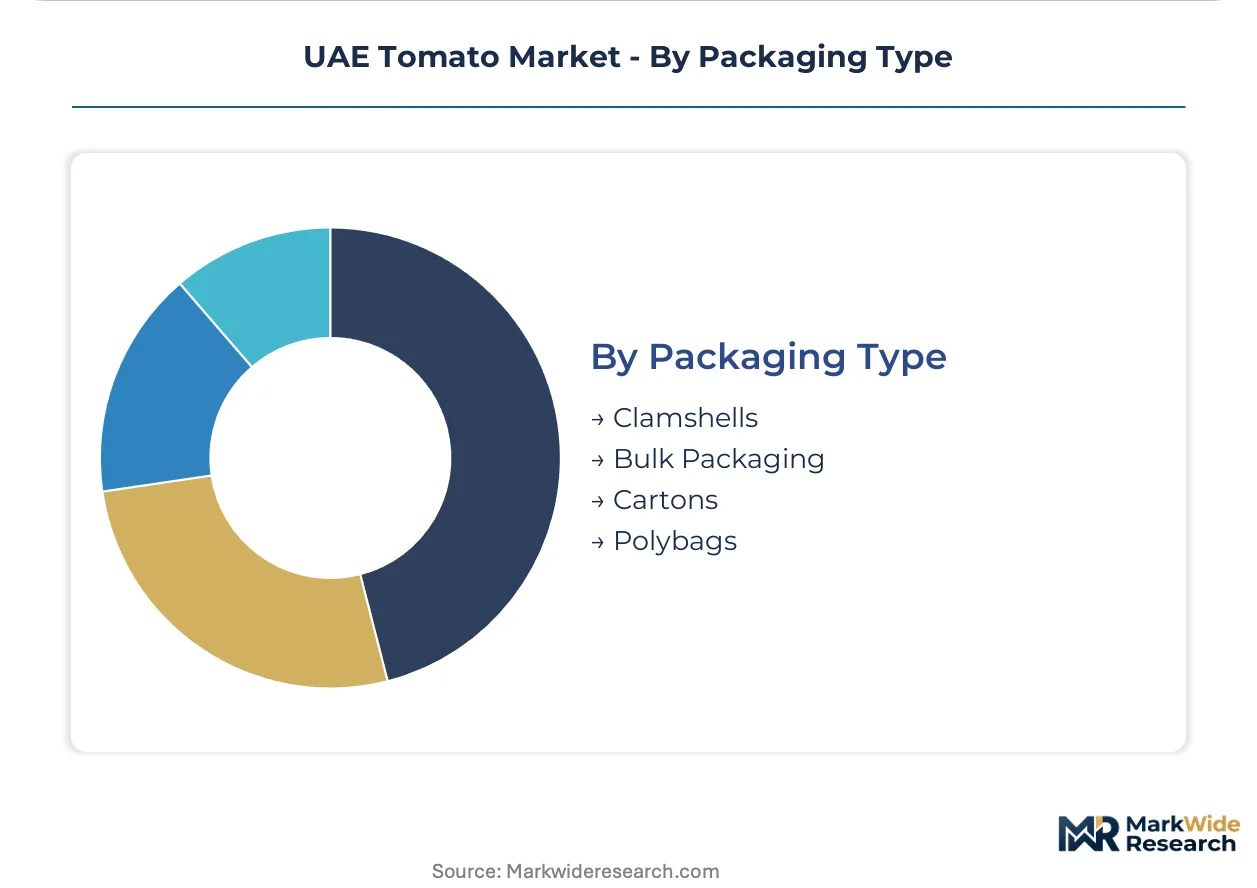
Packaging Type:
Packaging selection directly determines shelf-life extension and retail placement tier in Dubai's temperature-controlled distribution environment.
- Clamshells:Rigid PET containers with ventilation apertures protect cherry tomato integrity through multi-stage handling. ADQCC labeling requirements and barcode traceability integration are mandatory for supermarket placement.
- Bulk Packaging:Cardboard bins and wooden crates handle breaker-to-pink beefsteak volume for food-service processing. Minimal unit costs accommodate wholesale price compression but sacrifice retail presentation quality.
- Cartons:Corrugated containers with modified atmosphere liners extend transit shelf-life for inter-emirate distribution and re-export to Oman and Bahrain.
- Polybags:Perforated film sacks serve economy-tier retail and open-market trading with limited protection against mechanical damage and moisture accumulation.
Clamshells dominate value-added placement; bulk packaging retains cost advantage in hospitality procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fresh tomato consumption patterns across the Gulf diverge sharply from European and North American norms, with hospitality procurement dominating institutional volume while retail channels favor premium cherry varieties over processing-grade bulk.
Dubai
Sheikh Zayed Road's four and five-star hotel cluster drives concentrated demand for breaker-to-pink maturity tomatoes calibrated to food-service prep schedules. MOHAP's pesticide residue protocols compress import clearance timelines, privileging domestic greenhouse operators with in-house laboratory capabilities. Al Aweer wholesale market handles spot-market volume for restaurant procurement, though direct grower contracts are displacing traditional intermediaries.
Abu Dhabi
ADQCC quality conformity requirements shape labeling and cold-chain documentation for supermarket placement, with halal certification mandatory across all retail banners. Al Ain-based greenhouse operations anchor protected cultivation output for the northern emirates. Government-backed agricultural investment programs are expanding hydroponic infrastructure to reduce summer import dependency.
Sharjah
Independent grocery operators depend on wholesale market intermediaries for mixed-grade tomato sourcing with limited quality consistency. Northern emirate households exhibit higher price sensitivity than Dubai expatriate segments, favoring bulk formats over clamshell presentations. Weekend farmers markets in the emirate offer premium pricing for vine-ripened greenhouse output.
Saudi Arabia
Controlled-environment agriculture expansion in the Kingdom is increasing Gulf fresh produce self-sufficiency, pressuring UAE domestic price premiums. SFDA alignment with GCC Standardization Organization benchmarks creates regulatory harmonization across bilateral trade flows. Riyadh-based greenhouse operators are capturing re-export volume previously routed through Dubai.
Jordan
Seasonal production gaps in UAE summer months sustain Jordanian tomato exports to Gulf hospitality procurement channels. The country's national agricultural regulator enforces pesticide documentation that satisfies MOHAP batch-level testing requirements. Amman-based growers face margin compression as domestic UAE greenhouse capacity extends year-round supply security.
UAE Tomato Market Competitive Landscape
Capability concentration sits with technology-integrated greenhouse operators; scale advantage sits with diversified agribusiness conglomerates. The vendor base spans three tiers: hydroponic specialists with proprietary cultivation systems, conventional greenhouse operators with established retail relationships, and integrated propagation-to-retail platforms with captive distribution. Competitive moves center on backward integration into seed propagation and forward integration into direct hospitality contracting.
Among domestic greenhouse specialists, Pure Harvest Smart Farms Limited and Badia Farms LLC exemplify the technology-intensive archetype with advanced controlled-environment systems, while Al Ain Farms anchors the conventional scale-driven tier with established northern emirates coverage. Emirates Hydroponics Farms occupies a position bridging operational scale and cultivation innovation. Elite Agro Projects LLC represents the integrated model with propagation-to-retail coordination.
| Leading Market Players |
|---|
| Al Ain Farms |
| Emirates Hydroponics Farms |
| Pure Harvest Smart Farms Limited |
| Elite Agro Projects LLC |
| Al Dahra Agricultural Company |
| Silal Food and Technology Company PJSC |
| Agthia Group |
| Badia Farms LLC |
| VeggiTech Farms LLC |
| Others |
Value Network & Pricing Analysis
Jebel Ali port freight corridors channel Spanish and Dutch tomato imports through Dubai's logistics hub, with per-unit shipping cost differentials widening the spread between premium greenhouse cherry varieties and bulk beefsteak shipments. This corridor economics concentrates pricing power among domestic growers with year-round harvest capability, while forcing importers to absorb clearance delays under MOHAP's batch-level residue testing protocols.
Pricing Analysis
Price spreads between Al Ain greenhouse output and Jordanian import supply have widened as domestic controlled-environment operators capture hospitality contract premiums. Three-tier pricing structure across premium, standard, and economy levels separates ADQCC-certified clamshell cherry tomatoes from wholesale beefsteak bulk and spot-market polybag grades. Cost compression in standard-tier wholesale channels is intensifying because Saudi greenhouse expansion erodes UAE domestic price premiums. Food-service procurement clusters exhibit lowest price sensitivity; independent grocers in Sharjah and Ras Al Khaimah face highest margin pressure.
Supply Chain Analysis
Desalination energy cost volatility dominates supply chain risk exposure for UAE greenhouse operators tethered to reverse-osmosis irrigation infrastructure. Protected cultivation draws from Spain, Jordan, and Egypt for seasonal import gaps, with propagation materials and biological control agents sourced from Dutch and Israeli suppliers. Single-source vulnerability concentrates in specialized agronomic labor pools constrained by visa policy friction. Distribution runs through Dubai's Al Aweer wholesale floor for spot-market volume, while direct grower-hotel contracts bypass traditional intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE tomato market is recovering from import dependency cyclicality as domestic controlled-environment capacity extends year-round supply security. This recovery is anchored by government-backed agricultural investment programs expanding hydroponic infrastructure.
For Market Incumbents: Build regulatory compliance moats through in-house laboratory capabilities that satisfy MOHAP batch-level testing requirements ahead of import clearance timelines. Deepen backward integration into seed propagation to secure proprietary cherry tomato varieties for salad-kit channels. Channel control through direct annual volume contracts with Sheikh Zayed Road hotel consortia defends against Saudi greenhouse competition eroding price premiums.
For New Entrants and Emerging Players: Pursue white-space positioning in online retail subscription models for cherry tomato SKUs integrated with meal-kit services. Weekend farmers markets in Dubai and Al Ain offer the most penetrable segment for vine-ripened premium positioning with minimal intermediary layers. Go-to-market execution should emphasize last-mile cold-chain partnerships with established e-grocery platforms rather than supermarket slotting fee competition.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified agribusiness conglomerates with underutilized greenhouse assets lacking integrated propagation-to-retail coordination. Long-term viability over the next decade rests on technology-intensive operators with closed-loop hydroponic systems achieving water consumption reductions above ninety percent. The signal to watch is MOHAP enforcement timeline acceleration for GCC Standardization Organization benchmark alignment, which would compress import windows further and revalue domestic laboratory-capable assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Propagation | Captures proprietary genetics for cherry tomato salad-kit channels against Spanish import competition. |
| Direct Hospitality Contracting | Bypasses Al Aweer wholesale intermediaries for Sheikh Zayed Road hotel procurement volume. |
| In-House Laboratory Investment | Secures MOHAP compliance advantage as batch-level residue testing extends import clearance durations. |
| Closed-Loop Hydroponic Retrofit | Reduces desalination energy exposure by over ninety percent in water-constrained desert climates. |
| ADQCC Certification Program | Unlocks premium supermarket placement through halal-compliant traceability and cold-chain documentation. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with greenhouse operations managers, hospitality procurement directors, ADQCC compliance officers, and Al Aweer wholesale traders; and secondary validation through UAE customs import records, MOHAP food safety bulletins, GCC Standardization Organization benchmark publications, and desalination energy cost disclosures from FEWA and DEWA. Bottom-up crop volume estimates from individual greenhouse operators were triangulated against top-down hospitality sector procurement surveys.
Forecast inputs span product type segmentation across cherry, beefsteak, heirloom, and Roma varieties; distribution channel dynamics through supermarkets, wholesale markets, online retail, and direct farm sales; and end-user demand patterns across restaurants, households, food processing, and independent retail. CAGRs were derived from regression analysis of historical import volume fluctuations, domestic greenhouse capacity expansion trajectories, and hospitality sector growth indicators across the analysis window. Industry-specific inputs include desalination energy cost volatility indices and labor visa policy administrative friction measures.
Macroeconomic conditions sit as an overlay; deviation in oil-price-linked government agricultural subsidy levels or dirham-euro exchange rate movements would shift the trajectory of import competitiveness. Forecasts reflect assumptions around MOHAP enforcement intensity and Saudi greenhouse expansion pace that could revise domestic price premium sustainability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
Field Peas Market
Vegetables
Vegetable Grader Market
Vegetables
Yams Market
Vegetables
Qatar Greenhouse Market
Vegetables
Greenhouse Produce Market
Vegetables
United States Microgreens Market
Vegetables
Europe Flowers and Ornamental Plants Market
Vegetables
Europe Pea Market
Vegetables
Japan Greenhouse Horticulture Market
Vegetables
South America Peas Market
Vegetables
Microgreens Market
Vegetables
Yam Products Market
Vegetables
Dried Peas Market
Vegetables
Global Indoor Plant Market
Vegetables
Cabbages and Other Brassicas Market
Vegetables
Fresh Onions and Shallots Market