
 Smart Syringe Market | 2026-2036
Smart Syringe Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Syringe Market Intelligence
Homecare settings is repositioning demand patterns as patients managing diabetes and chronic pain shift from clinical to self-administered drug delivery. Becton, Dickinson and Company leverages its safety-engineered portfolio to dominate North American hospital procurement. Terumo Corporation anchors its competitive stance through advanced polymer science and Japanese manufacturing precision. SCHOTT Pharma specializes in glass-barrel pre-fillable systems that sustain premium positioning across European vaccination programs.
A smart syringe integrates active safety mechanisms, electronic sensors, or connectivity features into a single-use injection device, typically incorporating retractable needles, RFID tags, or Bluetooth-enabled dose verification to prevent needlestick injuries and medication errors. The primary purpose spans controlled drug delivery, patient compliance monitoring, and healthcare worker protection across acute and ambulatory settings. Safety syringes lead volume adoption due to WHO procurement mandates and OSHA compliance requirements in the United States. Pre-filled syringes capture concentrated margin pools as biologics manufacturers seek container closure integrity and reduced overfill. IoT-enabled technology segments are expanding fastest where health systems deploy connected devices for real-time adherence tracking in decentralized care models.
FDA 510(k) pathways and EMA Medical Device Regulation (MDR) classifications shape product development timelines and clinical evidence requirements for smart syringe manufacturers seeking market access. OSHA Bloodborne Pathogens Standard and EU sharps injury directives directly mandate safety-engineered device adoption in healthcare workplaces, creating regulatory pull through procurement specifications. Stakeholders must monitor evolving cybersecurity frameworks for connected devices as health authorities in the United States, Germany, and Japan develop guidance on IoT medical device data integrity.
Market Dynamics
The Smart Syringe Market pivots on the tension between decentralized care expansion and tightening safety mandates from FDA and EMA, forcing manufacturers to embed connectivity and active safety into single-use devices while managing polymer and electronics cost volatility.
Growth Catalysts
- OSHA Bloodborne Pathogens Standard:US healthcare employers must deploy safety-engineered needles, creating procurement pull through hospital group purchasing organizations and ambulatory surgery centers.
- Biologics manufacturing expansion:Pre-fillable glass-barrel systems capture concentrated demand from mRNA vaccine producers and monoclonal antibody developers requiring container closure integrity.
- Homecare self-administration:Diabetes and chronic pain patients in Germany and Japan are shifting from clinical settings to connected auto-injectors with dose verification.
Market Restraints
- Medical-grade polymer concentration:Cyclo-olefin polymer supply concentrates among Japanese and German specialty chemical producers, exposing device makers to input cost volatility.
- EMA MDR clinical evidence requirements:Connected devices face extended notified body review timelines and costly post-market surveillance obligations.
- Reusable auto-injector competition:Electronic reusable devices threaten single-use smart syringe volumes in high-frequency therapy segments like multiple sclerosis and fertility treatment.
Strategic Opportunities
- India's CDSCO fast-track pathway:Domestic manufacturing incentives and abbreviated approval timelines for safety devices open white space for localized production.
- Bluetooth-RFID convergence:Real-time adherence tracking for tuberculosis and HIV medication regimens creates new value pools in public health procurement.
- Direct-to-patient pharmacy channels:Specialty pharmacies in the United States are bypassing traditional distribution to deliver connected injection devices with embedded telehealth support.
Industry Challenges
- Cybersecurity skill scarcity:Connected device manufacturers face acute shortages of FDA-qualified cybersecurity engineers for pre-market submission documentation.
- Legacy EHR integration:Smart syringe data streams require costly middleware development to interface with hospital systems running decade-old architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Syringe Market |
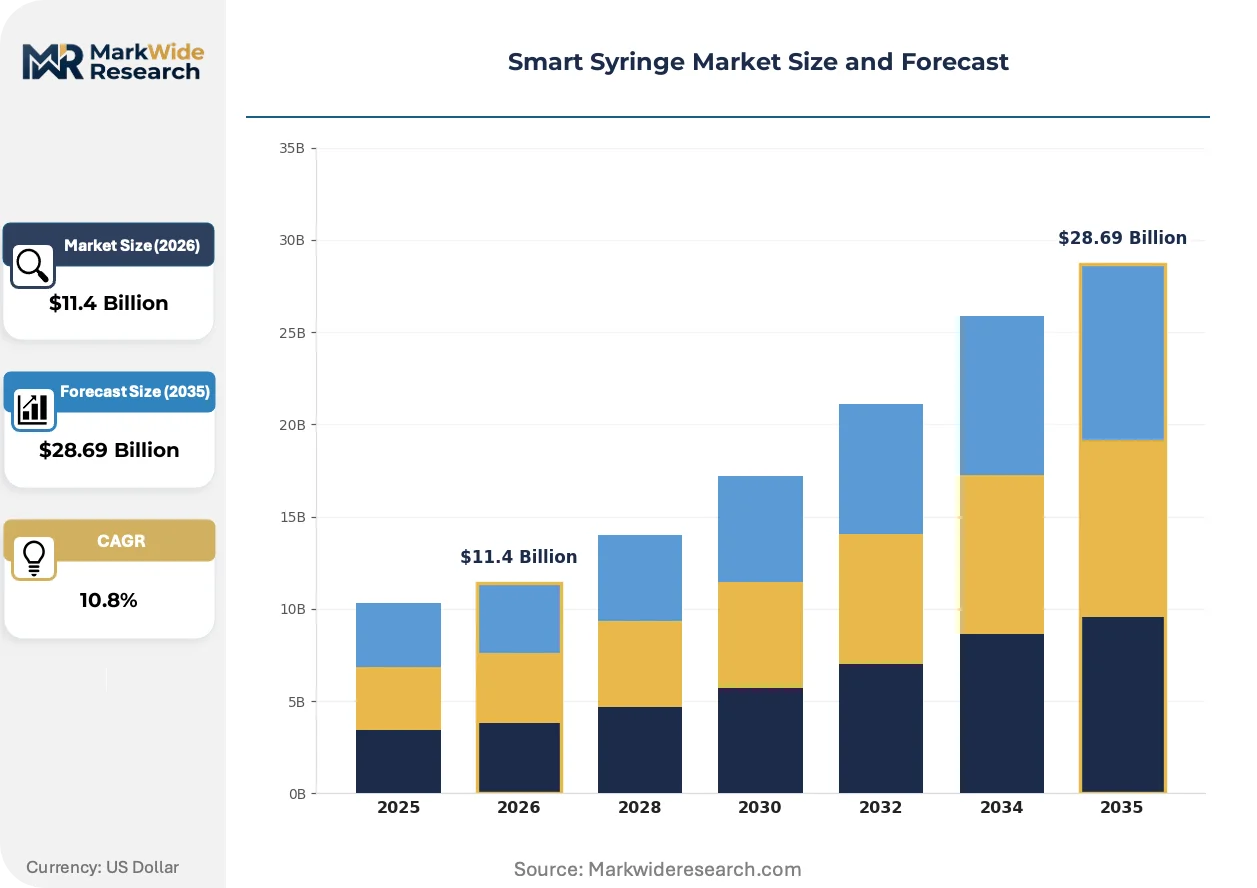
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $28.69 Billion |
| CAGR (2026 – 2036) | 10.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Auto-Disable Syringes, Safety Syringes, Pre-filled Syringes, Smart Insulin Syringes Technology: RFID, IoT-Enabled, Sensor-Based, Mobile Integration End User: Hospitals, Clinics, Homecare, Research Laboratories Application: Vaccination, Drug Delivery, Pain Management, Blood Sampling |
| Companies Covered | Becton, Dickinson and Company, Hindustan Syringes & Medical Devices, Terumo Corporation, Nipro Corporation, Gerresheimer AG, Retractable Technologies, Inc., SCHOTT Pharma, B. Braun Melsungen AG, Medtronic plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Syringe Market Strategic Shifts & Innovations
Active safety mechanisms and embedded sensors are converging with wireless connectivity, transforming injection devices from passive containers into data-generating care coordination tools that reshape competitive differentiation.
Micro-electromechanical systems (MEMS) pressure sensors embedded in syringe barrels are unifying dose verification, needlestick prevention, and patient identification into single disposable units. Hospital systems in the United States and Japan are piloting these devices for high-risk medication administration. This unification compresses the addressable market for standalone safety syringes while expanding margins for integrated smart platforms.
EU MDR Article 10 post-market clinical follow-up requirements are extending evidence generation timelines for connected devices, forcing manufacturers to maintain registry infrastructure across multiple member states. German notified bodies are applying heightened scrutiny to software-as-a-medical-device components. Pre-filled syringe specialists are responding by segregating European and non-European product lines to isolate regulatory risk.
Self-administration training is migrating from clinical staff to digital onboarding platforms embedded in device companion apps. Specialty pharmacies in the United States are unbundling injection training from drug dispensing, replacing nurse-led sessions with augmented reality guidance. This behavioral shift concentrates influence with pharmacy benefit managers and telehealth providers rather than traditional infusion clinic networks.
Smart Syringe Market Segmentation
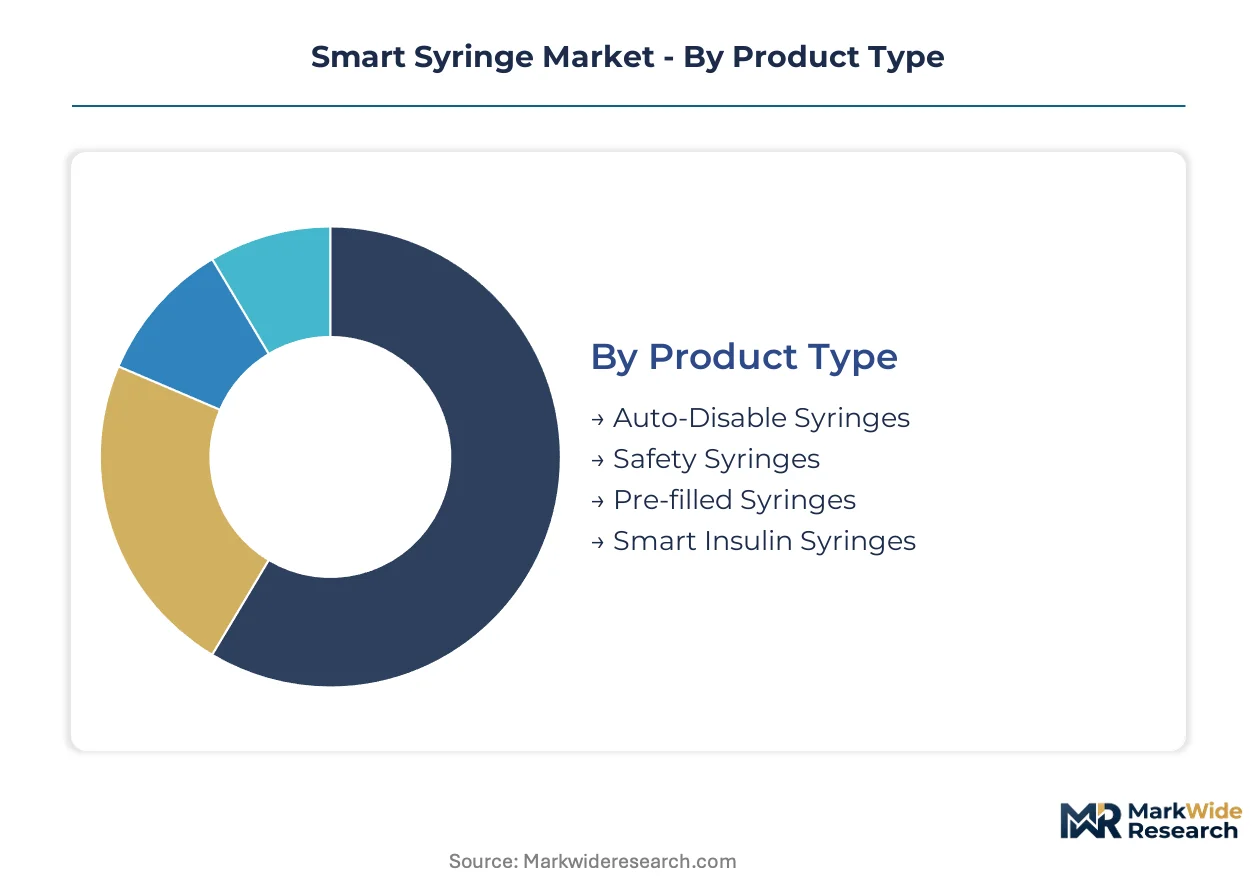
Smart syringe manufacturers engineer product portfolios around four intersecting axes: passive versus active safety mechanisms, connectivity depth, care setting infrastructure, and therapeutic application requirements. Segmentation choices directly determine regulatory pathway complexity, polymer selection, and margin structure across hospital procurement and direct-to-patient channels.
Product Type:
Technology specification separates commodity safety devices from premium integrated systems, with needle retraction mechanisms and pre-fillable barrel construction defining competitive tiers.
- Safety Syringes:Spring-loaded or manual needle retraction mechanisms prevent healthcare worker needlestick injuries in high-volume acute care settings. WHO procurement mandates and OSHA compliance requirements in the United States sustain dominant volume share across hospital group purchasing organizations.
- Pre-filled Syringes:Glass or polymer barrels pre-loaded with sterile drug product demand precision container closure integrity for biologics stability. mRNA vaccine manufacturers and monoclonal antibody developers in Germany and Japan concentrate procurement of premium borosilicate glass systems with integrated staked needles.
- Auto-Disable Syringes:Single-use mechanical locks prevent reuse in immunization campaigns across resource-limited settings. Gavi and UNICEF procurement specifications favor these devices for mass vaccination programs.
- Smart Insulin Syringes:Dose verification sensors and Bluetooth connectivity support diabetes self-management in homecare settings. Connected auto-injector competition is compressing standalone syringe volumes in this segment.
Safety Syringes lead on scale; Smart Insulin Syringes lead on momentum.
Technology:
Connectivity depth stratifies development cost, cybersecurity burden, and clinical evidence requirements across regulatory jurisdictions.
- Sensor-Based:MEMS pressure sensors embedded in syringe barrels enable real-time dose verification and injection completion detection. Hospital systems in the United States pilot these devices for high-risk medication administration where dosing errors carry severe liability.
- IoT-Enabled:Bluetooth Low Energy modules transmit adherence data to cloud platforms for remote patient monitoring. EMA MDR software-as-a-medical-device classifications extend approval timelines and post-market surveillance obligations for European deployments.
- RFID:Passive or active radio-frequency identification tags authenticate product provenance and track cold chain integrity. Vaccination programs in Japan leverage RFID for inventory management and counterfeit detection.
- Mobile Integration:Companion applications deliver augmented reality training and dose logging for self-administration patients. Specialty pharmacies in the United States unbundle injection training through these digital platforms.
Sensor-Based systems anchor hospital procurement; IoT-Enabled platforms are expanding most quickly in decentralized care models.
End User:
Care setting infrastructure determines device complexity, training requirements, and reimbursement pathway.
- Hospitals:Acute care settings demand active safety mechanisms and EHR-integrated dose documentation. OSHA mandates and FDA 510(k) safety device classifications shape procurement specifications across United States health systems.
- Homecare:Self-administration patients require simplified interfaces and telehealth connectivity for chronic disease management. Diabetes and chronic pain therapy segments in Germany are shifting volume from clinics to connected home devices.
- Clinics:Ambulatory settings balance cost constraints with safety compliance for routine immunization and medication administration.
- Research Laboratories:Preclinical and clinical trial applications demand precision dosing and chain-of-custody documentation for investigational compounds.
Hospitals dominate absolute volume; Homecare is gaining share fastest as reimbursement shifts toward outpatient models.
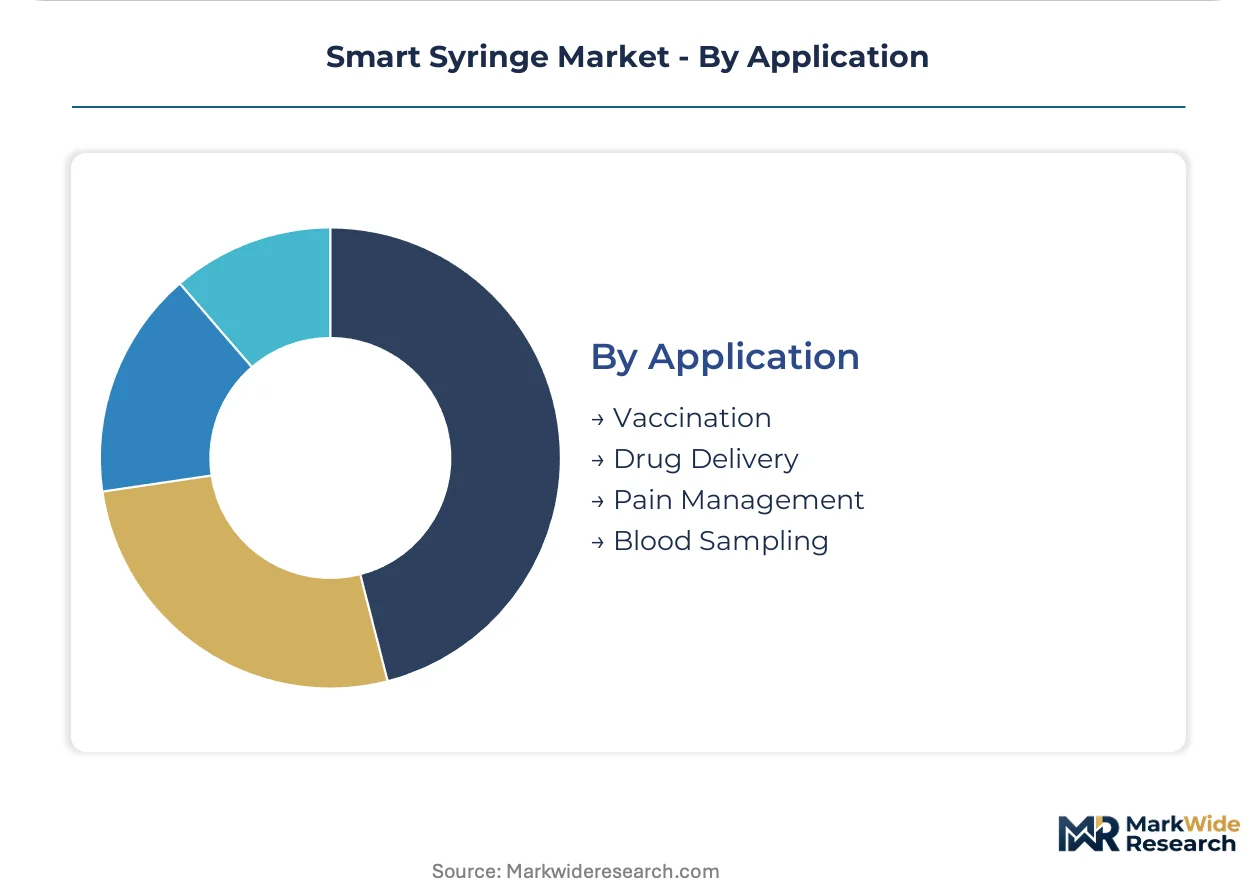
Application:
Therapeutic use case dictates barrel material, needle gauge, and connectivity requirements.
- Drug Delivery:Biologics administration requires pre-fillable systems with silicone-free lubrication and reduced tungsten residuals. Monoclonal antibody developers specify container closure integrity standards that sustain premium pricing.
- Vaccination:Mass immunization campaigns prioritize auto-disable mechanisms and ultra-cold chain compatibility for mRNA formulations. WHO prequalification programs standardize procurement across national immunization programs.
- Pain Management:Chronic opioid and non-opioid therapy demands dose verification to prevent diversion and monitor adherence.
- Blood Sampling:Integrated safety-engineered phlebotomy devices reduce needlestick exposure in diagnostic workflows.
Drug Delivery commands margin concentration; Vaccination sustains highest unit volumes through public health procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt's pharmaceutical manufacturing corridor concentrates European demand for pre-fillable glass-barrel systems, while Osaka's precision polymer cluster anchors Japanese supply chains for safety-engineered devices.
United States
OSHA Bloodborne Pathogens Standard mandates safety-engineered needles across hospital group purchasing organizations and ambulatory surgery centers. FDA 510(k) pathways shape product development timelines for connected devices seeking market access. Boston's biotech corridor drives concentrated procurement of pre-filled syringes for monoclonal antibody developers requiring container closure integrity.
Germany
Chronic disease patients in Germany are shifting from clinical settings to connected auto-injectors with dose verification for diabetes and pain management. EMA Medical Device Regulation classifications extend approval timelines for IoT-enabled platforms through software-as-a-medical-device scrutiny. Bavaria's medical technology cluster hosts specialty manufacturers engineering precision safety mechanisms for European vaccination programs.
Japan
METI industrial policy supports domestic manufacturing of advanced polymer components for single-use injection devices. PMDA regulatory frameworks govern connected device approvals with heightened cybersecurity documentation requirements. Osaka's precision engineering cluster concentrates production of cyclo-olefin polymer barrels for premium pre-filled systems serving Asian biologics markets.
India
CDSCO fast-track pathways and domestic manufacturing incentives open white space for localized safety device production. The country's national pharmaceutical regulator is streamlining abbreviated approval timelines for needlestick prevention technologies. Gujarat's medical device manufacturing corridor is expanding capacity to supply Gavi and UNICEF procurement specifications for auto-disable immunization syringes.
United Kingdom
NHS procurement frameworks are integrating connected injection devices into outpatient chronic disease management pathways. MHRA post-Brexit regulatory autonomy is diverging from EMA MDR timelines for software-enabled medical devices. London's health technology cluster is piloting Bluetooth-enabled dose verification systems for tuberculosis medication adherence programs.
Smart Syringe Market Key Industry Players
Portfolio diversification dominates the current landscape as manufacturers balance safety-engineered commodity volumes against premium connected device margins. The vendor base stratifies across three tiers: integrated healthcare conglomerates with full injection portfolios, specialized glass and polymer component suppliers, and emerging connectivity-focused entrants. Two strategic archetypes define competitive positioning: precision manufacturing specialists leveraging materials science differentiation, and digital health integrators embedding sensors and wireless modules. M&A activity concentrates on acquiring cybersecurity capabilities and sensor technology stacks, while capacity expansion targets Indian and Southeast Asian manufacturing zones to escape polymer cost volatility.
Within the integrated healthcare conglomerate tier, Becton, Dickinson and Company and Medtronic plc represent archetypal full-portfolio players spanning safety syringes through connected drug delivery platforms. Terumo Corporation exemplifies the precision manufacturing specialist archetype through its Japanese industrial base. Among component-focused suppliers, SCHOTT Pharma occupies a position exemplifying premium glass-barrel specialization for biologics applications. These named entities anchor the competitive structure without exhausting the participant base, as Hindustan Syringes & Medical Devices, Gerresheimer AG, and Retractable Technologies, Inc. represent additional geographic and technological positioning clusters.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Hindustan Syringes & Medical Devices |
| Terumo Corporation |
| Nipro Corporation |
| Gerresheimer AG |
| Retractable Technologies, Inc. |
| SCHOTT Pharma |
| B. Braun Melsungen AG |
| Medtronic plc |
| Others |
Cost & Logistics Intelligence
Captive production of cyclo-olefin polymer barrels by Japanese manufacturers anchors both supply security and premium pricing power for pre-filled syringe systems serving biologics markets in Germany and the United States.
Pricing Analysis
Medical-grade polymer cost pass-through dominates pricing dynamics, with cycloolefin polymer feedstock volatility transmitting directly to device manufacturers. Three-tier pricing structure across premium borosilicate glass, standard polymer, and economy polypropylene levels separates container closure integrity grades. Cost compression in standard polymer tiers is intensifying because German and Japanese specialty chemical producers maintain oligopolistic supply positions. Hospital group purchasing organizations exhibit highest price sensitivity for safety syringe volumes, while biologics developers show lowest sensitivity for pre-fillable systems where container closure integrity failures carry catastrophic batch loss risk.
Supply Chain Analysis
Single-source vulnerability sits with Japanese cyclo-olefin polymer producers, exposing device makers to input disruption from METI industrial policy shifts or logistics constraints through Osaka's precision engineering cluster. Manufacturing concentrates in Japan, Germany, and the United States for advanced polymer components and glass-barrel systems. Raw material dependencies span medical-grade polymers, borosilicate glass tubing, and silicone lubricants. Tariff exposure threatens cost structures as trade policy uncertainty affects cross-border component flows. Distribution runs through hospital group purchasing organizations in the United States, specialty pharmacy channels for homecare devices, and WHO procurement frameworks for immunization campaigns.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where OSHA Bloodborne Pathogens Standard and EMA MDR classifications continuously tighten compliance thresholds, mandating safety-engineered device replacement cycles that sustain demand irrespective of macroeconomic cycles.
For Market Incumbents: Deploy cybersecurity engineering capacity as the primary defensive lever against connected device entrants. Acquire FDA-qualified cybersecurity talent pools to accelerate 510(k) submission timelines for Bluetooth-enabled platforms. Build backward integration into cyclo-olefin polymer compounding to neutralize Japanese supply concentration risk. Expand manufacturing footprint in Gujarat's medical device corridor to capture CDSCO fast-track procurement for auto-disable immunization syringes. For New Entrants and Emerging Players: Enter via India's CDSCO abbreviated approval pathway for safety-engineered devices, where domestic manufacturing incentives and Gavi procurement specifications create white space absent entrenched incumbents. Target tuberculosis and HIV medication adherence tracking as the most penetrable connected device application, where Bluetooth-RFID convergence meets public health procurement budgets. Pursue specialty pharmacy direct-to-patient channels in the United States to bypass hospital group purchasing organization lock-in. For Investors and Strategic Acquirers: Consolidation pressure builds where cybersecurity skill scarcity meets EMA MDR software-as-a-medical-device scrutiny, forcing subscale connected device manufacturers toward acquisition. Long-term viability favors precision manufacturing specialists with captive polymer science capabilities over pure-play connectivity entrants lacking materials differentiation. Monitor FDA cybersecurity guidance document releases as the critical inflection signal for connected device valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Fast-Track Localization | Abbreviated approval timelines in India unlock Gavi and UNICEF procurement specifications for auto-disable syringes. |
| Bluetooth-RFID Convergence Development | Real-time adherence tracking creates new value pools in tuberculosis and HIV public health procurement. |
| Cybersecurity Engineering Acquisition | FDA-qualified talent scarcity extends 510(k) review timelines for connected device submissions. |
| Specialty Pharmacy Channel Partnership | Direct-to-patient distribution bypasses hospital group purchasing organization procurement lock-in. |
| EMA MDR Software Segregation | Separate European and non-European product lines isolate regulatory risk from notified body scrutiny. |
Research Approach
Direct dialogue with hospital procurement managers, GPO contracts specialists, biomedical engineers, and regulatory affairs directors at device manufacturers grounded qualitative insights. Secondary validation drew from FDA 510(k) filings, EMA MDR notified body documentation, WHO prequalification records, and hospital procurement database extracts. Bottom-up and top-down triangulation cross-checked unit volume assumptions against polymer feedstock demand and biologics manufacturing capacity expansion.
Bottom-up modeling anchored volume projections to safety syringe replacement cycles under OSHA mandates and pre-filled syringe demand from mRNA vaccine and monoclonal antibody production capacity. Segmentation dimensions spanned product type, connectivity depth, care setting infrastructure, and therapeutic application requirements. CAGRs were derived from installed base turnover rates and reimbursement pathway evolution across the projection horizon. Industry-specific forecast inputs incorporated EMA MDR transition timelines and METI industrial policy support for domestic polymer manufacturing.
Inputs from FDA submission databases and EMA notified body registers were available through the study window; gaps in private hospital procurement contract terms introduce uncertainty bands around pricing elasticity assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
South Africa Digital X-Ray Devices Market
Medical Devices
Appendage Management Market
Medical Devices
Asia-Pacific Single-Use Medical Device Reprocessing Market
Medical Devices
Insulin Storage Devices Market
Medical Devices
Sleep Apnea Devices Market
Medical Devices
Female Pelvic Implants Market
Medical Devices
Global Occlusion Devices Market
Medical Devices
Organ on a Chip Kit Market
Medical Devices
Support Surfaces Market
Medical Devices
Thoracolumbar Spine Devices Market
Medical Devices
Brazil Ultrasound Devices Market
Medical Devices
Global Surgical Tourniquets Market
Medical Devices
Global Voice Prosthesis Devices Market
Medical Devices
Gum Grafting Market
Medical Devices
Global Pathological Microscopes Market
Medical Devices
Eye Examination Equipment Market