
 Nepheline Syenite Market | 2026-2036
Nepheline Syenite Market Size, Share, and Industry Trends Forecast 2026-2036
Nepheline Syenite Market Intelligence
The incorporation of micronized nepheline syenite as a performance-enhancing functional filler is reshaping formulations in the paints and coatings industry. This shift expands its use beyond traditional fluxing applications. Sibelco leverages its extensive global mining and processing network to supply consistent grades for glass manufacturing. Imerys differentiates its offerings with specialized grades for plastics and coatings applications, while Covia Holdings focuses on serving North American construction and industrial customers from its regional assets.
Nepheline syenite is a naturally occurring, anhydrous sodium potassium aluminosilicate. Its primary industrial function is as a fluxing agent, lowering the vitrification temperature and improving melt characteristics in ceramics and glass production. The glass manufacturing application constitutes the largest consumption segment, with soda lime glass grade products leading in volume. In contrast, the ceramics application represents a mature and stable demand base, particularly for sanitaryware and tiles, where it improves firing cycles and body strength.
Market access is governed by chemical control regulations like the EU's REACH framework, managed by ECHA, and the EPA's Toxic Substances Control Act in the United States. These rules define purity requirements and occupational safety standards for mineral dust, influencing processing costs. Consequently, future competitive advantage depends on securing high-purity mineral deposits and innovating finer particle grades for advanced functional filler applications in polymers and specialty coatings.
Market Dynamics
The market's primary dynamic is the tension between its traditional role as a bulk fluxing agent and its emerging identity as a high-value functional filler, driven by advanced micronization technologies and stringent energy efficiency regulations.
Growth Catalysts
- Energy Efficiency Mandates:Frameworks like the EU Green Deal compel glass manufacturers to adopt energy-saving processes, increasing reliance on nepheline syenite to lower furnace temperatures and reduce fuel consumption.
- Asian Industrialization:Rapid expansion in China's automotive and construction sectors creates sustained demand for the specialty glass, ceramics, and coatings that utilize nepheline syenite as a key raw material.
- Micronization Technology:Advances in fine-grinding and classification technologies are unlocking new applications for micronized grades as functional fillers in paints, coatings, and polymers, expanding the addressable market.
Market Restraints
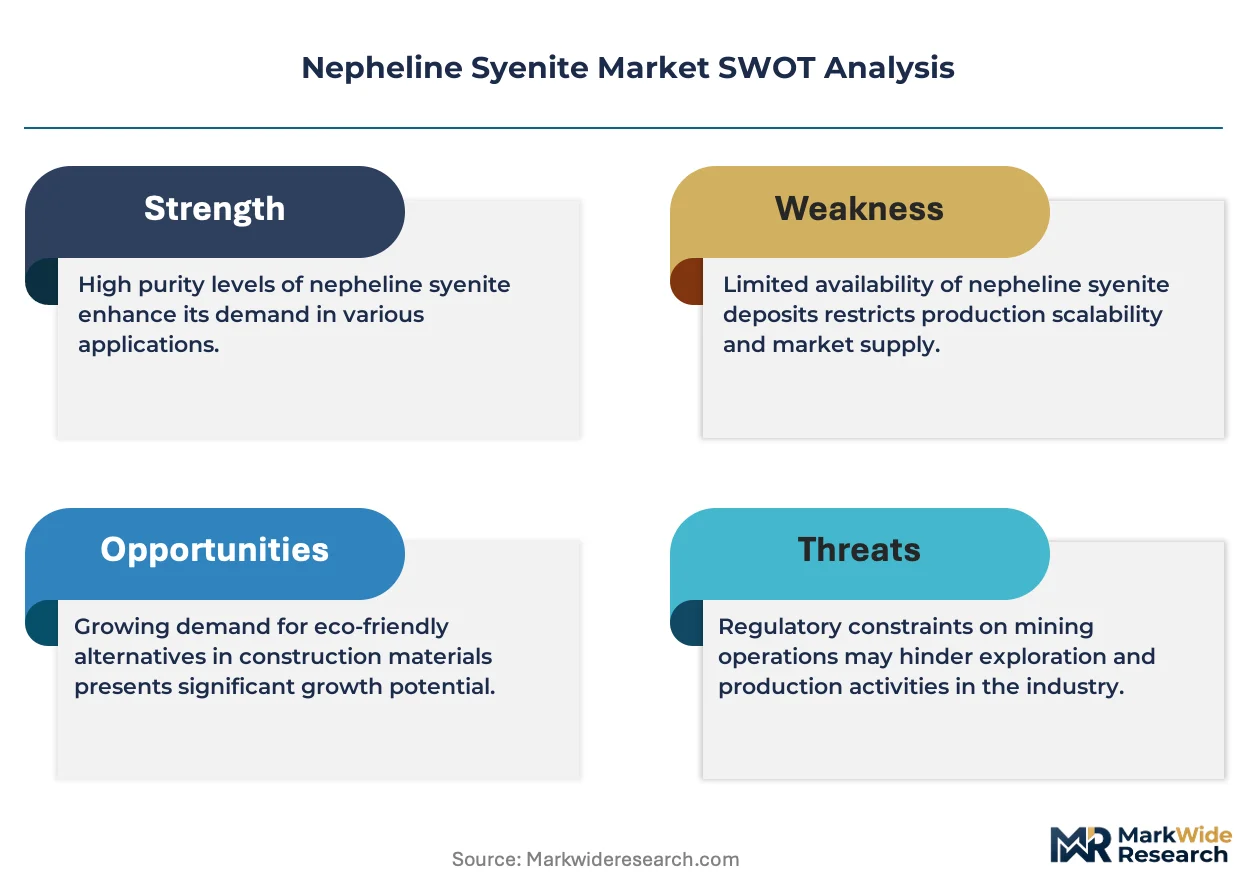
- Geographic Supply Concentration:The concentration of high-purity, commercially viable deposits in a few countries, including Canada and Russia, creates potential for supply chain disruptions and price volatility.
- Regulatory Compliance Costs:Adherence to chemical control laws like the EU's REACH and the EPA's TSCA imposes significant costs for testing, registration, and managing occupational exposure to mineral dust.
- Substitution from Feldspar:In cost-sensitive, lower-performance ceramic applications like traditional tiling, feldspar remains a viable, lower-priced alternative flux, capping price ceilings in certain segments.
Strategic Opportunities
- Advanced Polymer Additives:Developing surface-modified grades can enhance compatibility and performance in engineering polymers, opening a high-value market for functional fillers in automotive and electronics applications.
- Southeast Asian Market Entry:Industrial growth in countries like Vietnam and Indonesia presents an opportunity to supply emerging glass, ceramics, and paint manufacturers who currently have limited local access to the mineral.
- Agricultural Applications:The mineral's potassium content offers potential for use as a slow-release fertilizer and soil conditioner, representing a non-traditional application with large volume potential.
Industry Challenges
- Capital-Intensive Processing:The high capital expenditure required to establish and operate micronization facilities capable of producing fine and ultra-fine particle grades presents a barrier to new entrants.
- Lengthy Customer Qualification:Gaining specification approval for use in technical applications, such as automotive coatings or plastics, is a multi-year process requiring extensive testing and collaboration.
- Global Logistics Management:Ensuring consistent quality and managing the transportation costs of a bulk mineral from remote mining locations to industrial customers worldwide is a persistent operational hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nepheline Syenite Market |
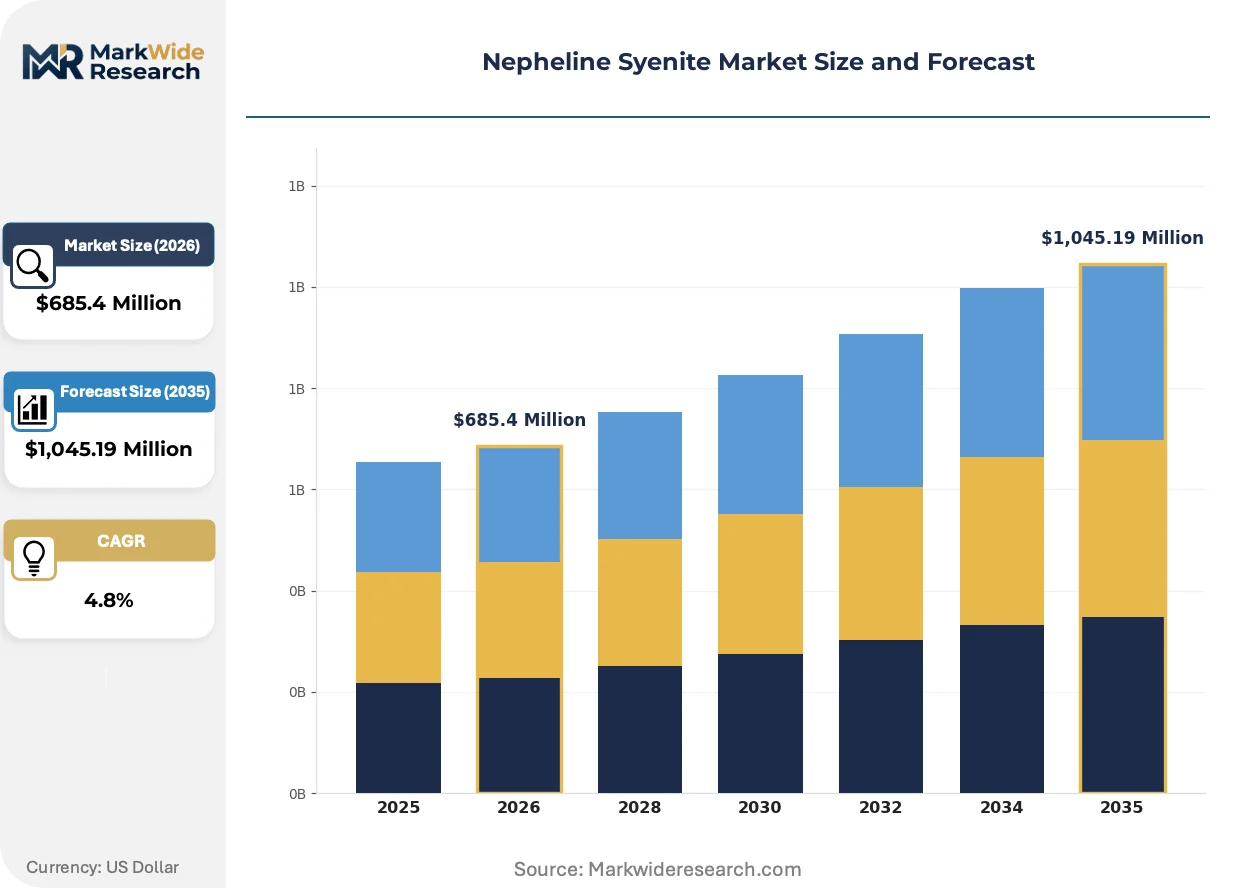
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,045.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fused Nepheline Syenite, Soda Lime Glass Grade, Coarse Grade, Chemical Grade Application: Paints & Coatings, Ceramics, Plastics, Glass Manufacturing, Adhesives End User Industry: Construction Materials, Automotive Component Makers, Electricals, Packaging Manufacturers Packaging Type: Bulk Bags, Paper Bags, Woven Sacks, Jumbo Bags |
| Companies Covered | Quarzwerke, Anglo Pacific Minerals, Sibelco, Fineton Industrial Minerals, RUSAL, Covia Holdings, AGSCO Corporation, Imerys, 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nepheline Syenite Market Strategic Shifts & Innovations
Material science advancements are transforming nepheline syenite from a passive process aid into an active performance component. This evolution is driven by a convergence of processing technology, regulatory pressures, and sophisticated end-user demands for multi-functional additives.
Surface-treated nepheline syenite provides enhanced weatherability and chemical resistance in coatings. Automotive OEM and industrial maintenance sectors are accelerating its adoption. This development is hybridizing the material's function, allowing it to act as both a flux and a specialized reinforcing agent, competing with engineered fillers.
Occupational safety regulations, such as OSHA standards in the United States concerning respirable crystalline silica (RCS), create a market pull. Because nepheline syenite is naturally low in free silica, it provides a safer alternative to fillers like ground silica. The abrasives and construction materials segments are actively reformulating products to minimize worker exposure to RCS.
A preference for total cost of ownership (TCO) models is replacing simple price-per-ton procurement. Buyers in technical ceramics and specialty glass evaluate how a grade impacts energy use, firing times, and final product quality. This shift is most pronounced in Germany’s automotive supply chain and Japan’s electronics sector, where process efficiency is critical.
Nepheline Syenite Market Segmentation
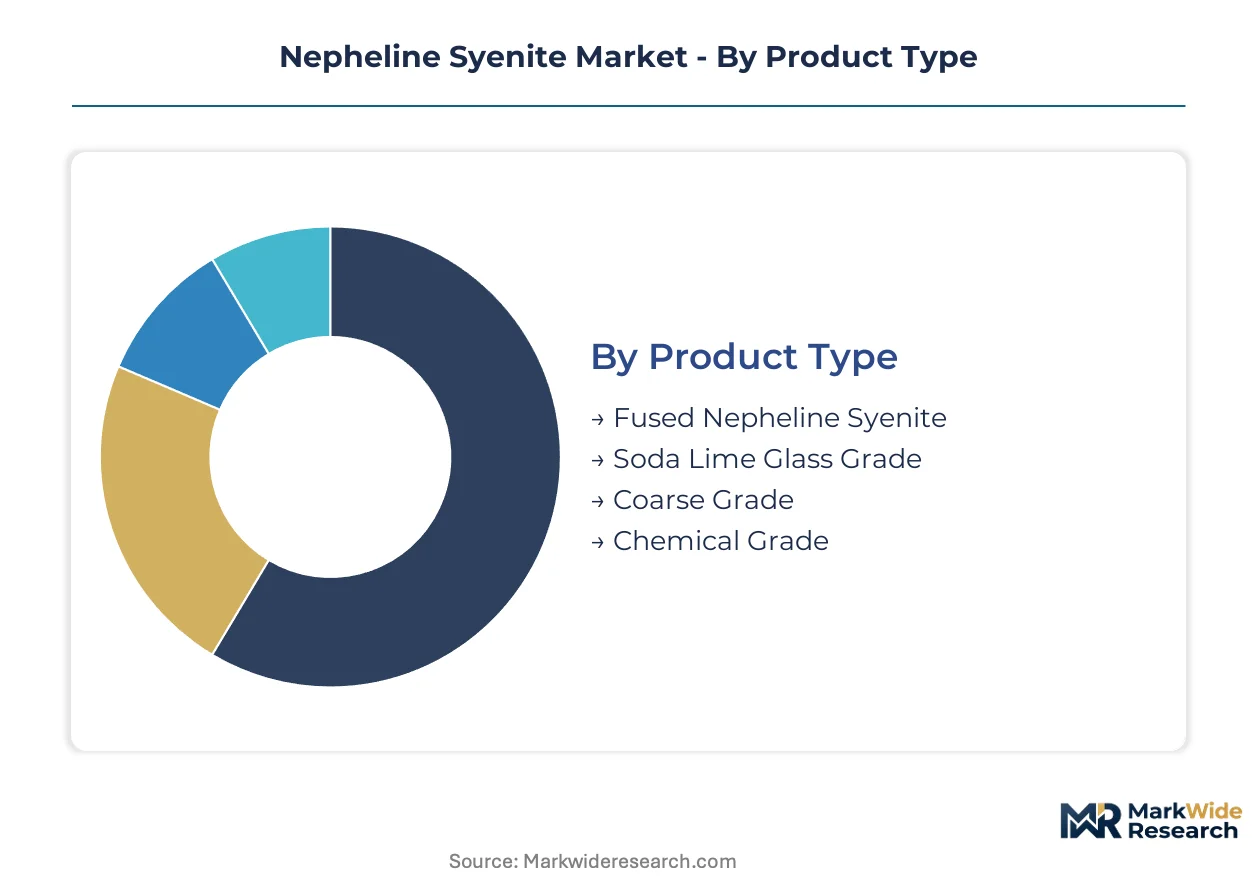
Nepheline syenite market segmentation reveals diverse product forms and end-use applications driving demand across industries. Understanding these distinct segments helps identify specific growth pockets and competitive dynamics within the value chain. This granular view highlights where innovation and market access strategies yield the most impact.
Product Type:
The nepheline syenite product type spectrum includes both mature, established grades and specialized variants addressing evolving industrial requirements.
- Fused Nepheline Syenite:This material undergoes a high-temperature fusion process, resulting in a dense, low-porosity product with enhanced chemical inertness. Automotive component makers in Germany utilize this for specialized glass and ceramic applications requiring superior strength.
- Soda Lime Glass Grade:This grade is characterized by its specific particle size distribution and low iron content, optimized for glass melting. Demand concentrates in China's construction sector, driven by vast requirements for window glass and container glass production.
- Coarse Grade:This grade serves as a bulk filler and aggregate in less demanding applications, such as certain building materials.
- Chemical Grade:This highly refined grade meets stringent purity standards for sensitive chemical processes or advanced material formulations.
Soda Lime Glass Grade handles the majority of throughput; Fused Nepheline Syenite is the fastest mover on share.
Application:
Nepheline syenite finds application across several industrial sectors, each leveraging its unique fluxing and filler properties for specific performance outcomes.
- Glass Manufacturing:This segment extensively uses nepheline syenite as a fluxing agent, reducing melting temperatures and energy consumption in glass furnaces. European glass producers, particularly in the Netherlands, prioritize this application to meet stringent EU Green Deal efficiency targets.
- Paints & Coatings:Micronized nepheline syenite acts as a functional filler, enhancing durability, scrub resistance, and tint strength in various paint formulations. North American automotive OEMs integrate these coatings for improved finish and weatherability on vehicle exteriors.
- Ceramics:Nepheline syenite lowers firing temperatures and improves body strength in ceramic products like sanitaryware and tiles.
- Plastics:As a functional filler, it imparts stiffness and dimensional stability to polymer compounds, particularly in engineering plastics.
- Adhesives:It serves as a rheology modifier and filler in adhesive formulations, influencing viscosity and bond strength.
Glass Manufacturing applications account for the largest consumption volume, while Paints & Coatings applications demonstrate the steepest expansion trajectory.
End User Industry:
The end-user industry segmentation highlights the diverse demand sources for nepheline syenite, reflecting its broad utility in manufacturing processes.
- Construction Materials:This industry utilizes nepheline syenite in various building products, including tiles, sanitaryware, and specialty glass, for improved strength and firing characteristics. Chinese construction firms drive significant demand for these materials in large-scale infrastructure projects.
- Automotive Component Makers:Manufacturers integrate nepheline syenite into specialized glass, coatings, and plastic parts for vehicles, benefiting from enhanced performance and reduced weight. Japanese automotive suppliers increasingly adopt these materials for lightweighting initiatives and aesthetic finishes.
- Electricals:The electrical industry incorporates nepheline syenite in ceramic insulators and electronic glass for its dielectric properties.
- Packaging Manufacturers:This sector uses nepheline syenite in glass containers and plastic films to improve material properties and production efficiency.
Construction Materials hold a dominant share of nepheline syenite consumption, with Automotive Component Makers showing consistent growth.
Packaging Type:
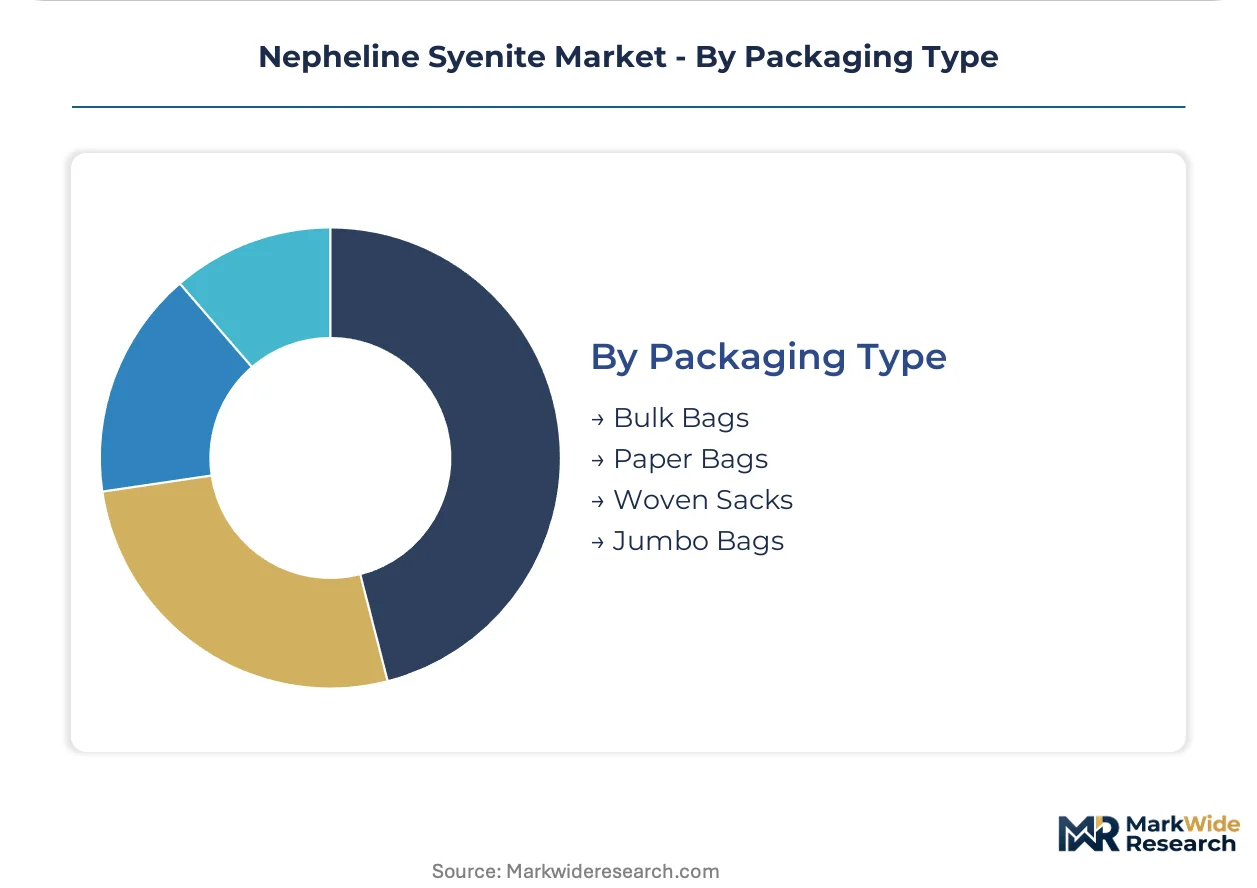
Packaging type segmentation reflects the logistical requirements and handling preferences for nepheline syenite, influencing supply chain efficiency.
- Bulk Bags:These large containers, typically holding 500-2000 kg, are preferred for high-volume industrial users due to their efficiency in handling and reduced packaging waste. Manufacturers in Canada frequently ship nepheline syenite in bulk bags to major glass plants.
- Jumbo Bags:Similar to bulk bags but often larger, jumbo bags are used for extremely high-volume shipments to large-scale industrial facilities, optimizing freight costs. Major ceramic producers in India rely on jumbo bags for their raw material deliveries to streamline operations.
- Paper Bags:Smaller quantities of specialized or finer grades are often packaged in multi-ply paper bags for ease of handling and precise dosing.
- Woven Sacks:These durable, often polypropylene, sacks are suitable for medium-volume shipments, offering good protection and stackability during transit.
Bulk Bags and Jumbo Bags are the preferred packaging solutions for large industrial customers, minimizing handling costs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nepheline syenite trade flows primarily from mining regions like Canada and Russia to major industrial consumers across Asia and Europe. This mineral supports diverse manufacturing processes globally, driven by specific regional demands and regulatory frameworks. Energy efficiency mandates significantly influence its adoption in key markets.
China
China's expansive construction and automotive sectors drive substantial demand for specialized glass and ceramics. The country's dual carbon goals encourage manufacturers to adopt energy-efficient processes using nepheline syenite. Large-scale glass and ceramic production in the Yangtze River Delta consumes significant volumes of soda lime glass grade products.
Germany
German automotive component makers and technical ceramic producers increasingly utilize nepheline syenite for enhanced performance. The EU Green Deal mandates push glass manufacturers towards energy-saving melting processes with this mineral. Automotive suppliers in Bavaria prioritize total cost of ownership models, valuing nepheline syenite's impact on process efficiency.
Canada
Canada serves as a crucial global supplier of high-purity nepheline syenite, primarily for glass manufacturing industries worldwide. Health Canada regulations ensure safe mining and processing practices for mineral dust. Mining operations in Ontario consistently produce and ship bulk quantities to international industrial customers.
Japan
Japanese electronics manufacturers and automotive suppliers integrate nepheline syenite for advanced materials and lightweighting initiatives. METI guidelines promote industrial efficiency, favoring materials that reduce energy consumption in production. The Kanto region's sophisticated manufacturing facilities require high-purity grades for technical ceramics and specialty glass.
India
Indian ceramic producers, particularly for sanitaryware and tiles, rely on nepheline syenite to improve firing cycles and body strength. BIS standards ensure material quality for various industrial applications within the country. The vibrant ceramic industry in Gujarat utilizes large volumes, often transported in jumbo bags for efficiency.
Nepheline Syenite Market Key Industry Players
Channel-controlling players compete with product-specialist players in the nepheline syenite market, influencing both distribution efficiency and advanced application development. The market exhibits a tiered structure, encompassing large integrated mining and processing operations alongside agile niche functional filler suppliers. Strategic archetypes include global raw material providers, regionally focused industrial mineral distributors, and highly specialized additive formulators. Companies consistently prioritize capacity expansion, portfolio diversification, and targeted geographic expansion to address evolving end-user demands across various industries.
Global raw material suppliers like Sibelco anchor the market, leveraging extensive mining and processing networks to deliver consistent grades primarily for high-volume glass manufacturing. Imerys represents a specialized additive formulator, offering differentiated grades tailored for high-performance plastics and coatings applications, moving beyond traditional bulk fluxing. Covia Holdings, a North American-based entity, occupies a distinct position focused on serving regional construction and industrial customers, utilizing its local assets and established supply chains effectively.
| Leading Market Players |
|---|
| Quarzwerke |
| Anglo Pacific Minerals |
| Sibelco |
| Fineton Industrial Minerals |
| RUSAL |
| Covia Holdings |
| AGSCO Corporation |
| Imerys |
| 3M Company |
Cost & Logistics Intelligence
Canada's high-purity nepheline syenite deposits concentrate upstream supply, directly influencing downstream pricing power for specialized grades. Global logistics management for this bulk mineral also significantly impacts overall cost structures for industrial customers.
Pricing Analysis
The technology-generation pricing gap differentiates micronized functional fillers from traditional bulk fluxing agents. Contract-based long-term offtake agreements govern high-volume transactions for glass manufacturing. Price differentiation stems from quality grade, particularly low iron content, and geographic delivery costs to industrial hubs. Pricing softness for commodity grades in ceramics stems from substitution by lower-priced feldspar. Construction materials end-users exhibit the most price sensitivity, while automotive component makers prioritize performance over cost.
Supply Chain Analysis
Export-control regimes, particularly for critical minerals, could impact the global flow of nepheline syenite, though not currently a major factor. Geographic supply concentrates in Canada and Russia, creating a reliance on these regions for high-purity ore. The supply chain draws from specific mining operations, with limited viable deposits globally. This geographic concentration creates single-source vulnerability, particularly for specialized grades. Distribution runs through direct sales from producers to large industrial customers, supplemented by regional mineral distributors for smaller volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nepheline syenite market presents a fragmentation opportunity. Demand for micronized grades as functional fillers creates specialized niches across diverse industrial applications.
For Market Incumbents: Entrench core positions by investing in advanced micronization technologies and securing long-term offtake agreements with key glass manufacturers. This strategy counters the threat of substitution from feldspar in cost-sensitive segments. R&D into surface-modified grades for polymers offers a lever for market expansion and value creation. Maintain strong relationships with established customers to ensure consistent volume throughput.
For New Entrants and Emerging Players: Southeast Asian emerging glass, ceramics, and paint manufacturers represent the most penetrable entry point. Target these regions with locally processed, standard grades to address immediate industrialization needs. Focus on consistent supply chain reliability and competitive pricing for bulk materials. Agricultural applications, leveraging the mineral's potassium content, offer a non-traditional, large-volume white space for new market development.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated players with high-purity mineral deposits and proprietary processing technologies. The market offers stable, long-term growth driven by essential industrial demand. Acquisition targets should include companies with strong R&D capabilities in surface modification or a diversified mineral portfolio. A signal to watch for inflection is regulatory tightening on respirable crystalline silica (RCS), favoring low-silica alternatives like nepheline syenite.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Addresses growing demand for bulk and specialized grades in industrial applications. |
| Product Portfolio Diversification | Extends market reach into high-value functional filler segments beyond traditional uses. |
| Long-term Supply Agreement | Secures consistent raw material access for major industrial customers and ensures revenue stability. |
| R&D in Surface Modification | Unlocks new applications in advanced polymers and specialty coatings, enhancing material performance. |
| Geographic Market Entry (Southeast Asia) | Captures industrialization-driven demand in emerging economies with limited local mineral access. |
Research Approach
The analysis maps glass manufacturing, paints & coatings, ceramics, and plastics sub-sectors, each validated through extensive primary interviews. These discussions included plant managers at glass manufacturers, R&D leads in coatings, procurement officers for ceramic producers, and mineral traders. Secondary validation utilized regulatory filings from ECHA and EPA, trade association reports for glass and ceramics, company annual reports, and technical journals. Bottom-up data from production volumes informed top-down market sizing for comprehensive triangulation.
The analytical framework assumes stable geopolitical conditions and consistent regulatory enforcement across the analysis window. Segmentation dimensions modeled include product type, application, end-user industry, packaging type, and regional consumption patterns. Compound Annual Growth Rates (CAGRs) were derived from historical growth trends and projected industrial expansion forecasts. Key industry-specific forecast inputs included industrial production indices and construction spending forecasts across major economies.
Macroeconomic conditions sit as an overlay; deviation in global GDP growth, industrial output, or energy prices would shift the trajectory. Forecasts reflect assumptions documented through a rigorous validation process. Material shifts in mineral dust regulations or a significant new nepheline syenite deposit discovery would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
Snowflake Salt Market
Industrial Minerals
Global Cristobalite Market
Industrial Minerals
Europe Feed Minerals Market
Industrial Minerals
Mineral Salt Ingredients Market
Industrial Minerals
Anhydrite Market
Industrial Minerals
Feldspathic Minerals Market
Industrial Minerals
Aluminium Potassium Sulphate Market
Industrial Minerals
Fluorspar Market
Industrial Minerals
Potassium Schoenite Market
Industrial Minerals
Global Commercial Perlite Market
Industrial Minerals
Industrial Garnet Market
Industrial Minerals
Global Epsom Salt Market
Industrial Minerals
Europe Frac Sand Market
Industrial Minerals
Europe Limestone Market
Industrial Minerals
China Feed Minerals Market
Industrial Minerals
Industrial Diamond Market