
 Europe Frac Sand Market | 2026-2036
Europe Frac Sand Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Frac Sand Market Intelligence
Proppant logistics and last-mile delivery services is shifting how frac sand contracts are structured across Europe. SCR Sibelco NV anchors its position through integrated quarry-to-wellhead supply chains in Western Europe. Badger Mining Corp leverages its Northern White Sand reserves to compete on sphericity and crush resistance specifications. US Silica Holdings Inc extends its reach through direct rail access to major European port terminals.
Frac sand consists of high-purity quartz grains processed to specific mesh sizes, typically between 20/40 and 40/70 mesh, with sphericity exceeding 0.6 and acid solubility below 2% to withstand deep-well closure stresses. Its primary purpose is to prop open hydraulically induced fractures in unconventional reservoirs, enabling hydrocarbon flow. Northern White Sand commands premium positioning due to superior conductivity performance in high-pressure formations, while Resin-Coated Sand captures expanding share as operators seek reduced flowback and embedment risks in tighter gas plays. Brown Sand occupies a mature, cost-driven niche in shallow conventional wells where conductivity demands remain modest.
REACH regulations under ECHA mandate crystalline silica exposure limits and chemical safety documentation, directly elevating testing costs and restricting non-compliant imports. The EU Green Deal and national carbon border adjustments are pressuring energy sector buyers to document embedded emissions across proppant supply chains. Stakeholders must monitor how F-Gas Regulation amendments and emerging methane performance standards reshape well completion economics and proppant selection criteria.
Market Dynamics
REACH compliance under ECHA is tightening crystalline silica exposure thresholds, forcing proppant suppliers to restructure testing protocols and documentation workflows across European supply chains.
Growth Catalysts
- Black Sea Basin Development:Romania's offshore gas concessions are accelerating hydraulic fracturing programs, creating concentrated demand zones for high-conductivity Northern White Sand proppants.
- F-Gas Regulation Amendments:Tighter methane performance standards under EU climate frameworks are pushing operators toward resin-coated sand to minimize flowback emissions and embedment risks.
- Poland Shale Expansion:State-backed unconventional gas licensing rounds are extending frac sand procurement timelines and locking in multi-year supply agreements with integrated logistics providers.
Market Restraints
- Import Dependency Concentration:Premium sphericity specifications for deep-well applications tie European buyers to Wisconsin and Minnesota Northern White Sand deposits, exposing margins to transatlantic freight volatility.
- REACH Testing Cost Burden:ECHA-mandated crystalline silica documentation and chemical safety assessments add fixed compliance overhead that disadvantages smaller regional quarries.
- Resin-Coated Substitution Pressure:Synthetic polymer coatings on ceramic proppants are capturing share in high-pressure formations where crush resistance exceeds quartz grain limits.
Strategic Opportunities
- Baltic States Unconventional Potential:Lithuania and Latvia hold underexplored shale formations where pilot fracturing programs could establish early-mover supply relationships before infrastructure matures.
- Rail-to-Port Distribution Innovation:Direct unit-train access to Rotterdam and Hamburg terminals is compressing landed costs for US-origin sand and enabling just-in-time wellsite delivery models.
- EU Green Deal Carbon Border Adjustments:Embedded emissions documentation requirements are creating first-mover advantage for quarries with renewable-powered processing and electric rail links.
Industry Challenges
- Specialized Logistics Coordination:Last-mile wellsite delivery requires frac sand-specific pneumatic equipment and storage silos that generalist hauliers rarely maintain, forcing operators to integrate transportation or accept scheduling rigidity.
- Multi-Jurisdiction Certification Timelines:Harmonizing ECHA registrations with national mining permits and coastal discharge authorizations stretches new quarry development cycles across overlapping review periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Frac Sand Market |
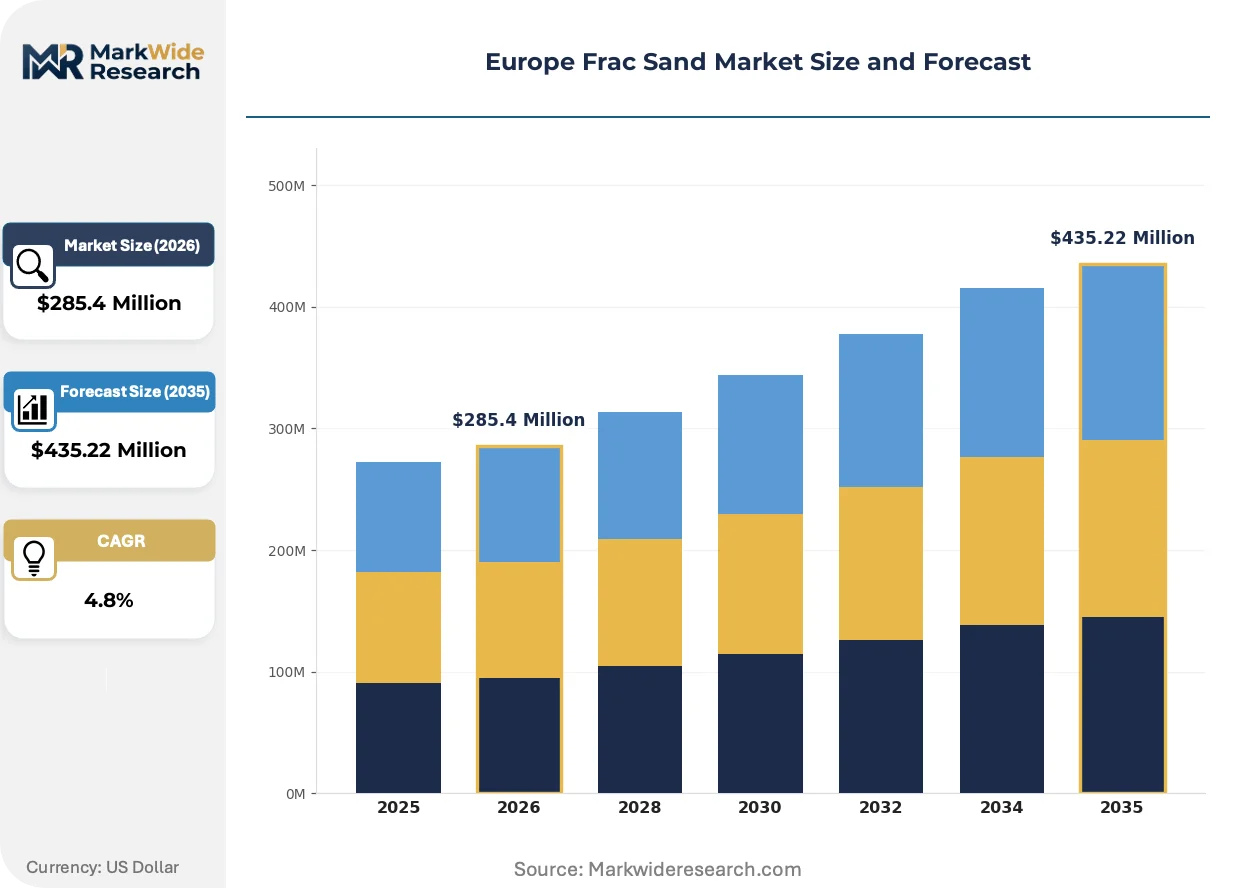
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $435.22 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Northern White Sand, Brown Sand, Resin-Coated Sand, Coated Sand Application: Oil Extraction, Gas Extraction, Geological Exploration, Hydraulic Fracturing End User: Energy Sector, Construction Industry, Mining Companies, Environmental Services Distribution Channel: Direct Sales, Retailers, Online Platforms, Wholesale Distributors |
| Companies Covered | Badger Mining Corp, SmartSand Inc, SCR Sibelco NV, Preferred Proppants LLC, Hi Crush Inc, US Silica Holdings Inc, CARBO Ceramics Inc, Source Energy Services Ltd, Covia Holdings LLC, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Frac Sand Market Strategic Shifts & Innovations
Digital tracking and automated quality verification are compressing procurement cycles and reshaping how European operators validate proppant specifications before wellsite acceptance.
Real-time particle size distribution sensors integrated into rail unloading terminals are automating batch verification against API/ISO sphericity and crush resistance standards. Major Polish shale operators are adopting these systems to reduce lab testing delays. The technology is automating rejection decisions that previously required manual sampling and third-party certification.
REACH authorization requirements for crystalline silica are extending safety data sheet obligations through downstream oilfield service providers. ECHA's 2023 guidance updates mandate exposure scenario documentation across the full proppant handling chain. Resin-coated sand formulations with encapsulated silica are capturing preference among buyers seeking simplified compliance pathways.
Integrated quarry-to-wellhead contracts are displacing spot procurement as the dominant commercial structure. European operators are locking in volume commitments with logistics-inclusive pricing to secure railcar allocation and storage capacity. This pattern concentrates most visibly in Romania's Black Sea development corridors where infrastructure bottlenecks threaten drilling schedules.
Europe Frac Sand Market Segmentation
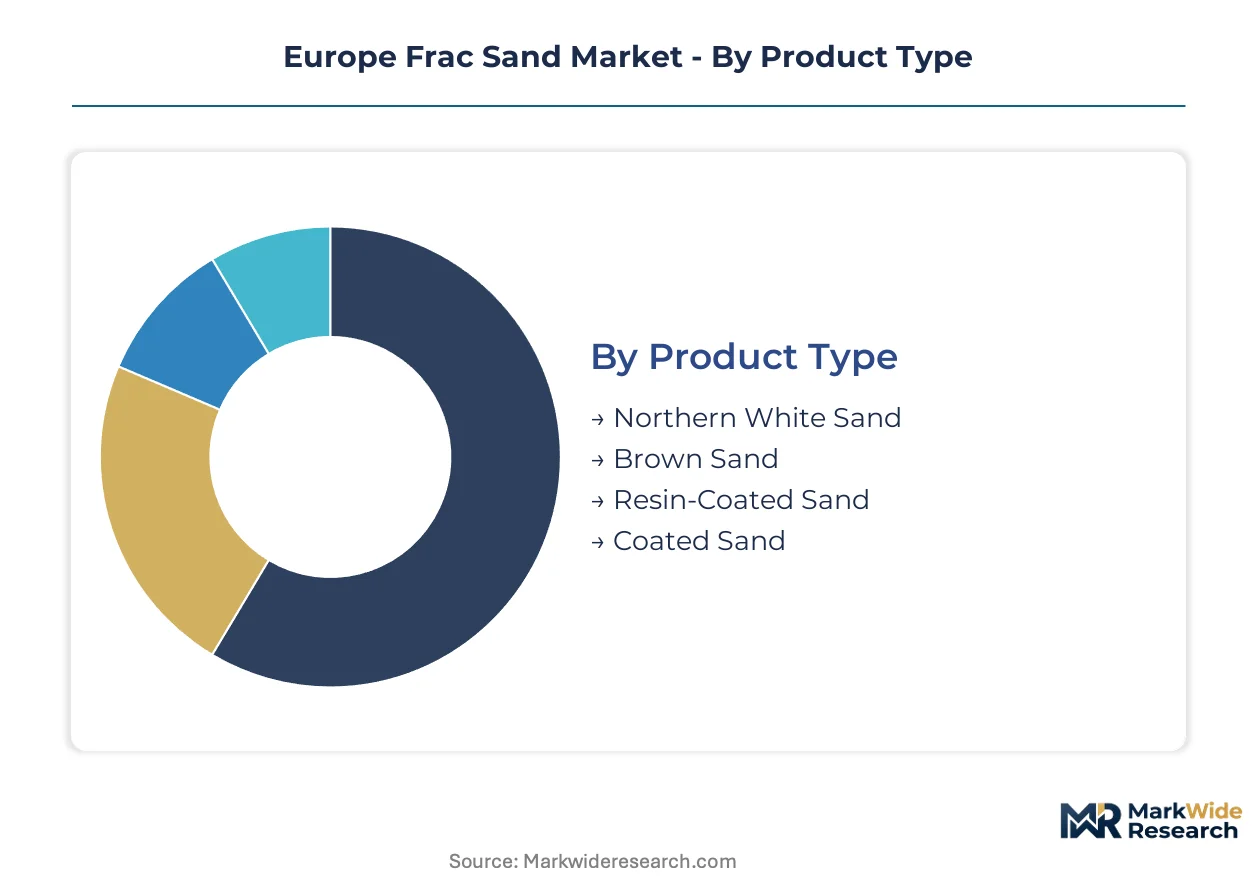
Frac sand procurement in Europe fragments across technical specifications, extraction applications, and logistics structures. Each segmentation dimension reveals distinct margin profiles and compliance burdens that shape supplier positioning.
Product Type:
Supply concentration for premium sphericity grades anchors procurement strategies across European unconventional plays.
- Northern White Sand:High-purity quartz from Wisconsin and Minnesota deposits delivers crush resistance above 8,000 psi and sphericity exceeding 0.6 for deep-well applications. Demand concentrates in Romania's Black Sea basin where high-pressure formations require maximum conductivity proppants. ECHA REACH documentation requirements for crystalline silica exposure add fixed testing overhead that favors large-volume importers with established compliance workflows.
- Resin-Coated Sand:Synthetic polymer encapsulation reduces flowback rates and embedment risks in tighter gas formations. Polish shale operators are expanding procurement of these grades under tightening F-Gas Regulation methane performance standards. The coating adds 15-25% premium pricing but simplifies downstream safety data sheet obligations.
- Brown Sand:Lower-purity regional deposits serve shallow conventional wells where conductivity demands remain modest.
- Coated Sand:Alternative surface treatments including ceramic or thermoplastic layers occupy niche applications between raw and resin-encapsulated grades.
Today's leader: Northern White Sand. Tomorrow's challenger: Resin-Coated Sand.
Application:
End-use differentiation tracks reservoir depth, pressure regimes, and regulatory exposure across European hydrocarbon provinces.
- Hydraulic Fracturing:Primary demand driver for high-grade proppants in unconventional shale and tight gas development. Polish and Romanian operators are locking in multi-year supply agreements as state-backed licensing rounds accelerate drilling schedules. Last-mile pneumatic delivery requirements favor integrated logistics providers with dedicated wellsite equipment.
- Gas Extraction:Black Sea basin offshore concessions and Baltic shale pilots are creating concentrated demand zones for premium conductivity grades. EU Green Deal carbon border adjustments pressure operators to document embedded emissions across proppant supply chains.
- Oil Extraction:Mature conventional fields in the North Sea basin drive steady demand for cost-optimized brown sand specifications.
- Geological Exploration:Pilot fracturing programs in Lithuania and Latvia require smaller batch sizes with rapid specification turnaround.
Hydraulic fracturing commands current volume leadership. Gas extraction applications are climbing the fastest as offshore Romania development scales.
End User:
Customer type determines contract structure, from integrated energy majors to fragmented environmental remediation specialists.
- Energy Sector:International oil companies and national operators dominate procurement volumes. These buyers are displacing spot markets with quarry-to-wellhead contracts that bundle rail allocation, port storage, and pneumatic delivery.
- Mining Companies:Quarry operators with captive sand processing are backward integrating into logistics to capture margin from wellsite delivery.
- Construction Industry:Secondary demand from geotechnical applications and industrial sand uses creates price-sensitive offtake for lower-specification grades.
- Environmental Services:Remediation and water treatment applications require specialized sizing and purity certifications.
Energy sector concentration defines today's procurement patterns. Mining company vertical integration poses the structural challenge.
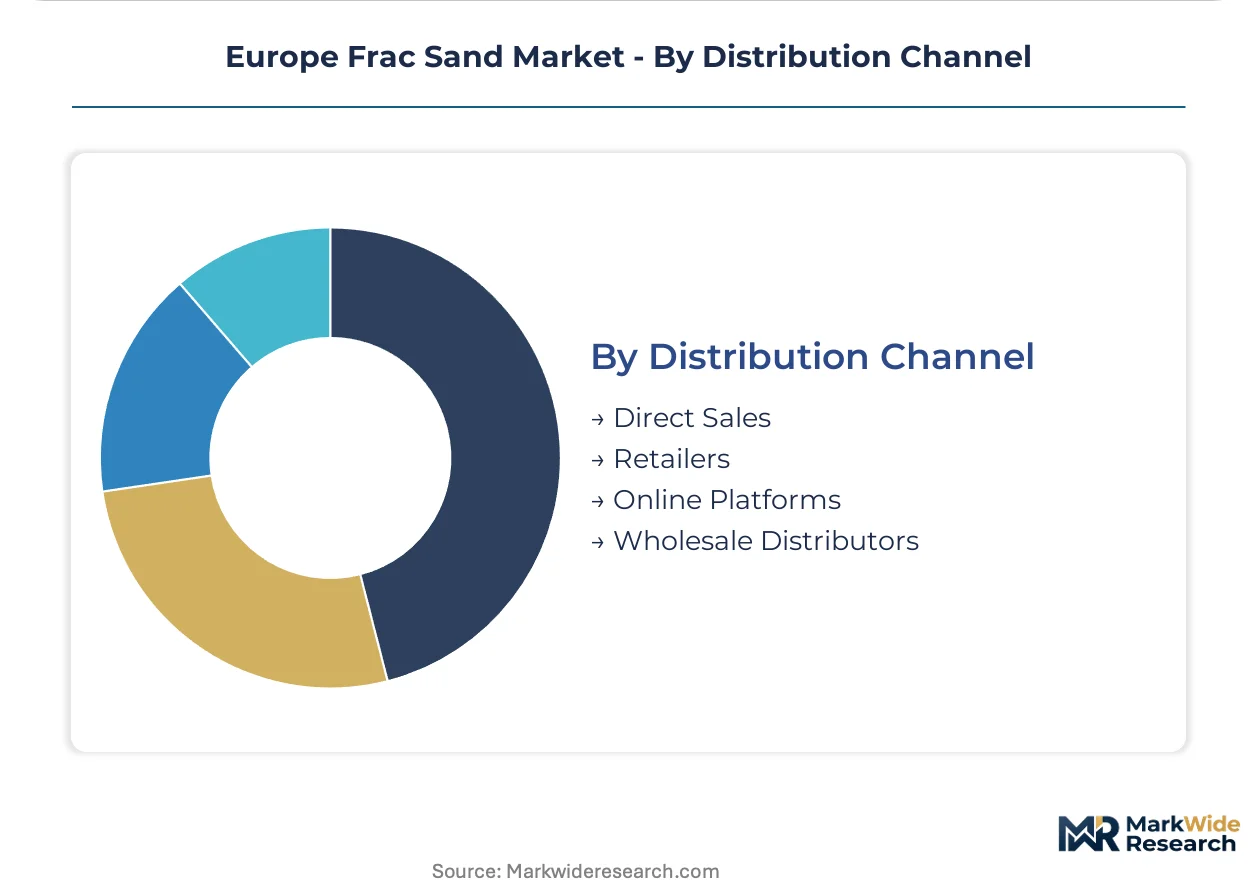
Distribution Channel:
Channel selection reflects batch size requirements, specification urgency, and infrastructure access across European supply corridors.
- Direct Sales:Unit-train volumes from US origins through Rotterdam and Hamburg terminals bypass intermediary markups for major Polish and Romanian operators. Real-time particle size verification sensors at rail unloading points are automating batch acceptance decisions.
- Wholesale Distributors:Regional stockholding points buffer smaller operators from railcar allocation constraints and port congestion.
- Retailers:Limited to specialty grades and emergency spot requirements where specification flexibility outweighs unit cost.
- Online Platforms:Emerging for standardized mesh sizes with documented API/ISO certification, though pneumatic delivery coordination remains offline.
Direct sales capture the premium tier. Wholesale distributors are gaining share fastest as mid-cap operators seek inventory flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Romania concentrates Black Sea basin demand while Poland drives shale expansion, yet both markets depend on common import corridors through Rotterdam and Hamburg terminals.
Romania
Black Sea offshore gas concessions are accelerating hydraulic fracturing programs for high-pressure formations. ECHA REACH compliance mandates crystalline silica documentation across proppant handling chains. Constanța port infrastructure is expanding dedicated pneumatic unloading capacity for Northern White Sand unit trains.
Poland
State-backed unconventional gas licensing rounds are extending multi-year frac sand procurement timelines. F-Gas Regulation amendments are tightening methane performance standards for well completions. Lower Silesia shale basins are locking in integrated logistics contracts with direct rail-to-wellsite providers.
Germany
Industrial sand processing clusters serve as distribution hubs for Central European unconventional plays. EU Green Deal carbon border adjustments pressure documentation of embedded emissions across supply chains. Hamburg terminal operators are installing real-time particle size verification sensors to automate batch acceptance.
Netherlands
Rotterdam's deep-water port anchors transatlantic Northern White Sand import volumes for the broader region. REACH authorization requirements for crystalline silica extend safety data sheet obligations through downstream oilfield service providers. Pernis industrial zone storage facilities are expanding dedicated silo capacity for resin-coated sand grades.
United Kingdom
North Sea mature field maintenance drives steady demand for cost-optimized brown sand specifications. The country's national mining regulator enforces coastal discharge authorizations for quarry development. Scottish shale exploration pilots are testing smaller batch procurement models with rapid specification turnaround.
Europe Frac Sand Market Key Industry Players
Top-tier vendors anchor premium sphericity supply, while mid-cap regional quarries compete on last-mile logistics integration. The vendor base stratifies across three tiers: integrated multinationals with captive rail networks, specialized proppant miners with Northern White Sand reserves, and regional construction sand operators diversifying into energy applications. Two dominant competitive moves are reshaping positioning: backward integration into pneumatic wellsite delivery fleets, and strategic port terminal partnerships to secure unit-train unloading priority.
Among North American-based miners, Badger Mining Corp and US Silica Holdings Inc exemplify the premium-reserve archetype with Wisconsin and Minnesota deposit access. SCR Sibelco NV anchors the European-integrated tier through quarry-to-wellhead supply chain control. These three occupy positions defined by their geographic origin and corporate structure rather than specific technology claims.
| Leading Market Players |
|---|
| Badger Mining Corp |
| SmartSand Inc |
| SCR Sibelco NV |
| Preferred Proppants LLC |
| Hi Crush Inc |
| US Silica Holdings Inc |
| CARBO Ceramics Inc |
| Source Energy Services Ltd |
| Covia Holdings LLC |
| Others |
Cost & Logistics Intelligence
Polish shale operators' multi-year procurement lock-ins are forcing supply chain reconfiguration toward integrated rail-to-wellhead contracts, compressing spot market liquidity and elevating price premiums for guaranteed volume allocation. REACH compliance documentation costs are filtering through to contract structures, with ECHA-mandated crystalline silica testing bundled into landed pricing rather than treated as separable service fees.
Pricing Analysis
Capacity additions in Romania's Black Sea development corridors are reshaping price floors for Northern White Sand grades as dedicated pneumatic infrastructure at Constanța port reduces unloading bottlenecks. Three-tier pricing structure across premium Northern White, mid-grade resin-coated, and economy brown sand specifications tracks crush resistance thresholds and sphericity certification tiers. Price differentiation intensifies between direct sales with real-time particle verification and wholesale distributor markups for smaller batch procurement. Cost compression in economy brown sand runs through regional quarry competition, while premium tiers maintain pricing power through Wisconsin deposit scarcity and transatlantic freight volatility.
Supply Chain Analysis
Return flows of contaminated proppant from Romanian wellsite cleanup operations are creating secondary material streams that regional processors are refining for lower-specification construction applications. Geographic supply concentration anchors in Wisconsin and Minnesota for premium sphericity grades, with Poland and Romania serving as demand-side processing hubs. Raw material dependencies rest on high-purity quartz deposits, synthetic polymer resins for coating applications, and specialized pneumatic handling equipment. Single-source vulnerability concentrates in transatlantic unit-train scheduling through Rotterdam and Hamburg terminals. Distribution runs through direct rail contracts for major operators and wholesale stockholding points for mid-cap buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe frac sand market functions as a regulatory compounder where ECHA REACH crystalline silica exposure thresholds are accelerating compliance investment and consolidating procurement around documented supply chains.
For Market Incumbents: Acquire dedicated pneumatic wellsite delivery fleets to lock in last-mile margin capture as Polish and Romanian operators disintermediate generalist hauliers. Secure priority unloading agreements at Rotterdam and Hamburg terminals before port capacity constraints harden into allocation rationing. Resin-coated sand substitution technology threatens raw quartz market share in high-pressure formations, requiring coating capability investment or strategic partnership with polymer suppliers. For New Entrants and Emerging Players: Regional wholesale distributors with existing construction sand infrastructure represent the most penetrable channel partner type for energy sector diversification. Baltic States unconventional pilots in Lithuania and Latvia offer white-space demand before infrastructure maturity attracts incumbent attention. Target rapid specification turnaround services for exploration-phase operators with smaller batch requirements and compressed procurement timelines. For Investors and Strategic Acquirers: Asymmetric upside sits with quarries possessing renewable-powered processing and electric rail links as EU Green Deal carbon border adjustments mature into enforceable documentation requirements. Five-to-ten year viability favors integrated supply chain controllers with ECHA registration workflows already operational. Monitor F-Gas Regulation amendment implementation timelines as the signal for resin-coated sand demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pneumatic Logistics | Captures wellsite delivery margin that generalist hauliers forfeit under REACH handling protocols. |
| Resin-Coating Capacity Buildout | Positions suppliers for F-Gas Regulation methane performance standards tightening across Polish shale basins. |
| Renewable-Powered Processing Certification | Creates first-mover advantage under EU Green Deal embedded emissions documentation requirements. |
| Direct Rail-to-Port Terminal Partnerships | Secures unit-train unloading priority at Rotterdam and Hamburg as Black Sea demand concentrates. |
| Real-Time Particle Verification Deployment | Automates batch acceptance decisions and reduces lab testing delays for Romanian offshore operators. |
Research Approach
Multiple input streams — executive interviews with proppant procurement directors, technical consultations with ECHA compliance specialists, and operational briefings with port terminal operators — were reconciled against customs trade data, ECHA registration databases, and SEC filings from North American sand miners. Primary engagement covered quarry operators, integrated oilfield service providers, and rail logistics coordinators across Poland, Romania, Germany, and the Netherlands. Secondary validation drew from EU Green Deal policy documentation, F-Gas Regulation amendment drafts, and Black Sea basin concession award records. Bottom-up volume modeling and top-down market sizing were cross-checked for consistency.
Data-stream reconciliation across the analysis window applied segmented demand modeling by product grade, application pressure regime, and distribution channel structure. CAGRs were derived from production capacity trajectories, licensing round schedules, and infrastructure investment pipelines rather than extrapolated from historical trends. Forecast inputs incorporated REACH testing cost pass-through assumptions, transatlantic freight rate volatility bands, and resin-coated sand substitution elasticity estimates.
Revisions become necessary when ECHA crystalline silica exposure thresholds tighten beyond current guidance, F-Gas Regulation amendments accelerate methane performance standard timelines, or Black Sea basin drilling schedules shift with concession renegotiations. Practitioners should monitor ECHA guidance updates, Romanian port infrastructure commissioning announcements, and Polish state licensing round outcomes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
United States Feed Minerals Market
Industrial Minerals
Mineral Salt Ingredients Market
Industrial Minerals
Oman Industrial Salts Market
Industrial Minerals
Anhydrite Market
Industrial Minerals
North America Silica Sand Market
Industrial Minerals
Snowflake Salt Market
Industrial Minerals
Bentonite Market
Industrial Minerals
Europe Feed Minerals Market
Industrial Minerals
Europe Diatomite Market
Industrial Minerals
Global Epsom Salt Market
Industrial Minerals
Industrial Salts Market
Industrial Minerals
Caustic Calcined Magnesite Market
Industrial Minerals
Talc Market
Industrial Minerals
Mineral Wool Material Market
Industrial Minerals
Calcined Anthracite Market
Industrial Minerals
Limestone Mill Market