
 Feldspathic Minerals Market | 2026-2036
Feldspathic Minerals Market Size, Share, and Industry Trends Forecast 2026-2036
Feldspathic Minerals Market Foresight
Modular batch customization is expanding across feldspar supply contracts, letting ceramic buyers blend potassium and sodium grades to precise alkali ratios rather than accepting fixed compositions. Sibelco leverages its vertically integrated milling network across Turkey and Norway to sustain consistent particle-size distribution for vitrified tile lines. Imerys Ceramics anchors European supply through its Spruce Pine operations, while Kaltun Madencilik Sanayi ve Ticaret dominates Anatolian output with direct rail links to Izmir port.
Feldspathic minerals comprise aluminosilicate rock-forming minerals—primarily orthoclase, albite, and anorthite—containing 10-16% K₂O or Na₂O and 18-20% Al₂O₃, which lower the melting point of ceramic bodies and glass batches while improving chemical durability and mechanical strength. Potassium feldspar leads volume in tableware and sanitaryware applications where higher viscosity during firing reduces deformation, whereas sodium feldspar claims faster growth in flat glass manufacturing due to its superior fluxing action at lower temperatures. The ceramics application segment captures the deepest margin pools through long-term supply agreements with multinational tile producers, while glass manufacturing remains the most price-sensitive offtake channel.
China's SAMR enforces GB/T 14506 feldspar quality standards that mandate maximum Fe₂O₃ content below 0.3% for premium ceramic grades, effectively restricting market access for unprocessed run-of-mine material. Turkey's Mining Law and Environmental Impact Assessment regulations require Kaltun Madencilik and competitors to rehabilitate open-pit sites, adding compliance costs that transfer into contract pricing. India's BIS certification for ceramic-grade feldspar is gaining traction among Morbi exporters shipping to the Middle East and Africa. Stakeholders must monitor how tightening alkali-ratio specifications in EU ceramic tile standards reshape procurement criteria across Mediterranean supply chains.
Market Dynamics
Modular batch customization is compressing traditional fixed-grade supply contracts, compelling processors to deliver precise potassium-to-sodium ratios rather than standardized feldspar shipments. China's tightening GB/T 14506 purity thresholds and India's BIS certification expansion are simultaneously elevating quality barriers while fragmenting procurement patterns across ceramic manufacturing clusters.
Growth Catalysts
- Vitrified tile expansion:Southeast Asian ceramic manufacturers are scaling high-density tile output, driving concentrated feldspar offtake from Turkish and Norwegian milling networks.
- GB standards tightening:China's SAMR enforcement of maximum Fe₂O₃ thresholds below 0.3% for premium ceramic grades is filtering out unprocessed run-of-mine material and rewarding investment in beneficiation capacity.
- Flat glass flux optimization:Sodium feldspar's superior fluxing action at lower temperatures is displacing traditional soda ash in float glass batches, particularly across Middle Eastern manufacturing installations.
Market Restraints
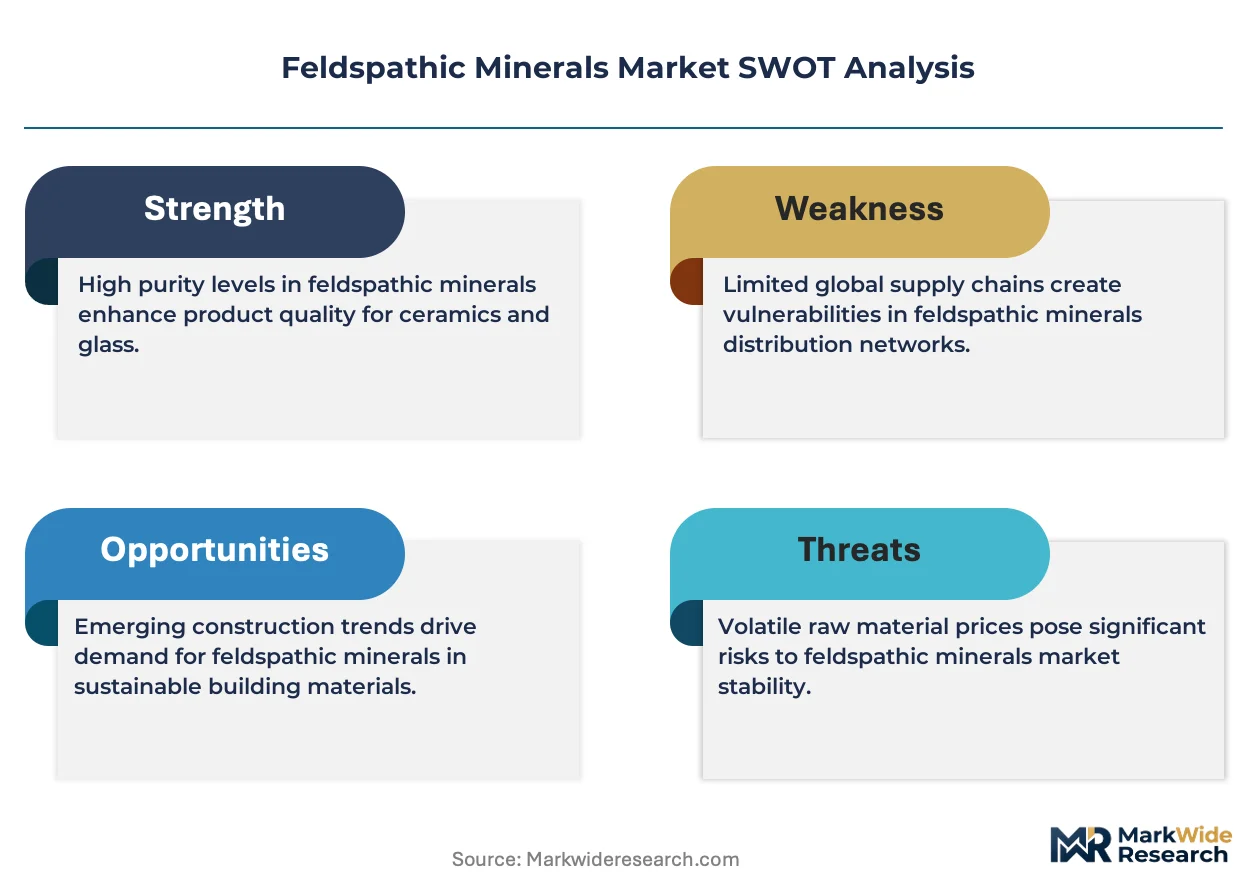
- Energy cost volatility:Ball milling and spray-drying operations consume substantial electricity and natural gas, exposing processors to input cost swings that compress margin pools on fixed-price contracts.
- Anatolian supply concentration:Turkish rail-linked export capacity dominates seaborne feldspar trade, creating geographic chokepoint risk for European and Asian ceramic producers dependent on Izmir port throughput.
- Alumina substitution pressure:Synthetic nepheline syenite and recycled glass cullet are encroaching on feldspar's fluxing role in lower-specification ceramic body formulations.
Strategic Opportunities
- Morbi cluster verticalization:Gujarat-based tile producers are backward-integrating into captive feldspar beneficiation, creating equipment and technical service demand for mineral processing specialists.
- EU Green Deal alignment:REACH-registered feldspar grades with verified carbon footprints are commanding preferential placement in sustainability-scored ceramic tile procurement frameworks.
- Digital particle-size control:Laser diffraction real-time monitoring converging with automated mill adjustment is enabling contract manufacturers to guarantee tighter distribution tolerances for vitrified tile lines.
Industry Challenges
- Process mineralogy expertise scarcity:Qualified geologists capable of optimizing flotation circuits for feldspar-quartz separation are concentrated among a handful of academic programs and retiring cohorts.
- BIS certification timeline compression:Indian exporters to Middle East and Africa markets face extended laboratory testing queues and documentation backlogs that delay contract execution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Feldspathic Minerals Market |
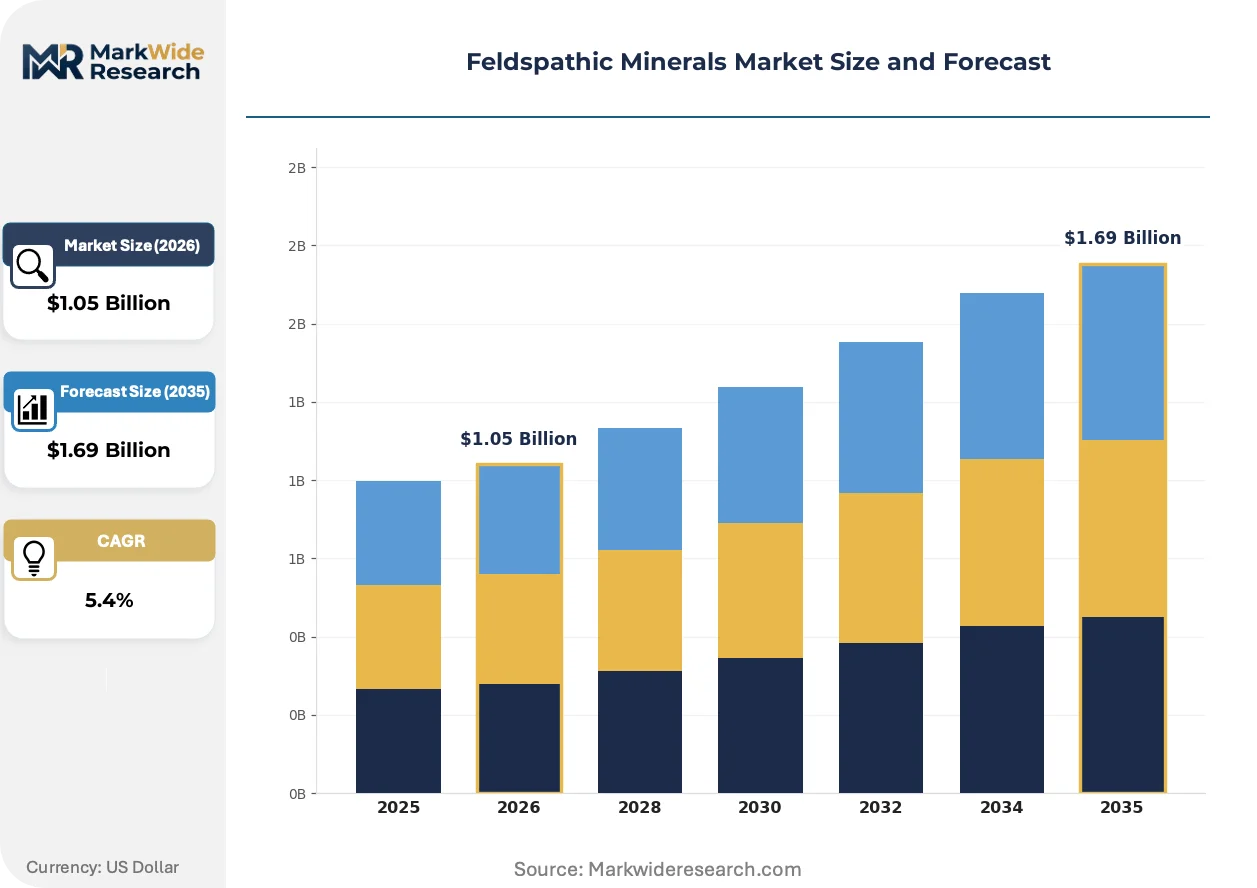
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.69 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Potassium Feldspar, Sodium Feldspar, Mixed Feldspar, Other Feldspars Application: Ceramics, Glass Manufacturing, Plastics, Paints End User: Construction, Automotive, Electronics, Consumer Goods Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale |
| Companies Covered | Imerys Ceramics, Sibelco, Eczacıbaşı Holding, Asia Mineral Processing, Kaltun Madencilik Sanayi ve Ticaret, El Waha Mining & Fertilizers, Minerali Industriali, I-Minerals Inc., Gottfried Feldspat, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Feldspathic Minerals Market Shifts & Advancements
Dry beneficiation technologies and digital quality assurance systems are displacing water-intensive processing methods across feldspar milling operations. Regulatory carbon accounting and buyer sustainability scoring are simultaneously reshaping procurement criteria and supplier investment priorities.
Sensor-based ore sorting is unifying grade control with throughput optimization in Turkish and Norwegian processing plants. Ceramic tile manufacturers in Spain and Italy are adopting these pre-concentration outputs to reduce downstream energy consumption. The technology is compressing capital requirements for new entrants while elevating quality consistency benchmarks across Mediterranean supply chains.
China's MEE enforcement of dual carbon goals is tightening emissions monitoring at feldspar mining and milling facilities. Processors in Shandong and Fujian provinces are retrofitting kilns with waste-heat recovery systems to maintain operating licenses. Premium ceramic-grade output is migrating toward state-owned mining groups with centralized environmental compliance infrastructure.
Specification-driven contracting is replacing spot-market purchasing among multinational tile producers. Long-term alkali-ratio agreements with penalty clauses for deviation are displacing traditional tonnage-based procurement in Morbi and Sassuolo manufacturing clusters. This behavioral shift is most visible in sanitaryware and tableware segments where firing viscosity tolerances are narrowest.
Feldspathic Minerals Market Segmentation
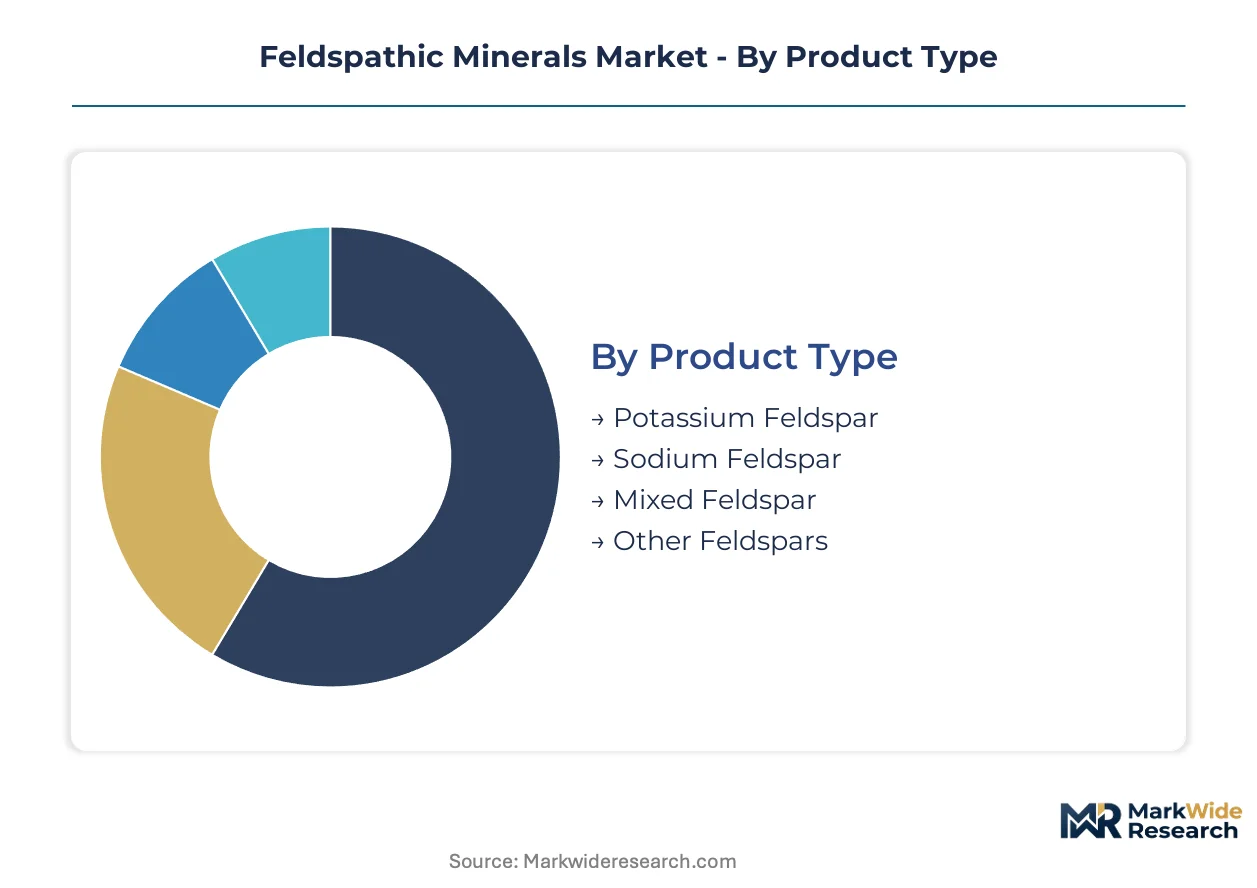
Feldspathic mineral procurement patterns diverge sharply between integrated ceramic manufacturers demanding precise alkali ratios and commodity buyers accepting standardized flux grades. Segmentation reveals how specification depth, application chemistry, and supply chain configuration reshape contract structures across mineral processing networks.
Product Type:
Potassium and sodium variants operate as standalone flux inputs requiring precise blending, while mixed grades embed directly into pre-formulated ceramic body preparations.
- Potassium Feldspar:Contains 10-16% K₂O with higher viscosity during firing, making it essential for tableware and sanitaryware applications where deformation resistance matters. Morbi-based tile producers in Gujarat anchor concentrated offtake for vitrified lines demanding dimensional stability.
- Sodium Feldspar:Delivers superior fluxing action at lower temperatures due to its 10-12% Na₂O content and lower melting point. Flat glass manufacturers across Middle Eastern installations are displacing traditional soda ash with sodium feldspar to reduce energy consumption in float glass batches.
- Mixed Feldspar:Pre-blended potassium-sodium compositions simplify procurement for mid-tier ceramic producers lacking in-house mineralogy expertise. Turkish milling networks dominate supply through rail-linked export capacity.
- Other Feldspars:Includes calcium-rich anorthite and specialized lithic variants serving niche refractory and dental ceramic applications.
Volume placements concentrate in Potassium Feldspar; the faster expansion belongs to Sodium Feldspar.
Application:
Application segments separate by specification tolerance, with ceramics demanding certified alkali ratios and glass manufacturing prioritizing cost-efficient flux performance.
- Ceramics:Captures the deepest margin pools through long-term supply agreements with multinational tile producers. China's SAMR enforcement of GB/T 14506 standards mandating Fe₂O₃ below 0.3% for premium grades filters out unprocessed material and rewards beneficiation investment.
- Glass Manufacturing:Remains the most price-sensitive offtake channel, with sodium feldspar displacing synthetic fluxes in float glass batches. Middle Eastern manufacturing installations lead adoption due to energy cost pressures.
- Plastics:Serves as functional filler in engineering polymers where alumina content enhances mechanical properties.
- Paints:Provides matting agents and extenders in industrial coatings, with particle-size distribution determining performance.
Procurement volumes cluster in Ceramics; Glass Manufacturing is climbing the fastest as energy optimization accelerates flux substitution.
End User:
End user segments stratify by technical specification depth, with construction and automotive demanding certified traceability versus electronics and consumer goods accepting broader quality bands.
- Construction:Vitrified tile producers across Southeast Asia scale feldspar procurement as high-density tile output expands. India's BIS certification is gaining traction among Morbi exporters shipping to Middle East and Africa markets.
- Automotive:Ceramic brake pad and spark plug insulator applications require controlled thermal expansion coefficients.
- Electronics:Specialized high-purity grades serve semiconductor packaging and substrate applications.
- Consumer Goods:Tableware and sanitaryware manufacturers prioritize firing viscosity control to reduce deformation.
Contract volumes anchor in Construction; Electronics is gaining share fastest as substrate miniaturization drives purity requirements.
Distribution Channel:
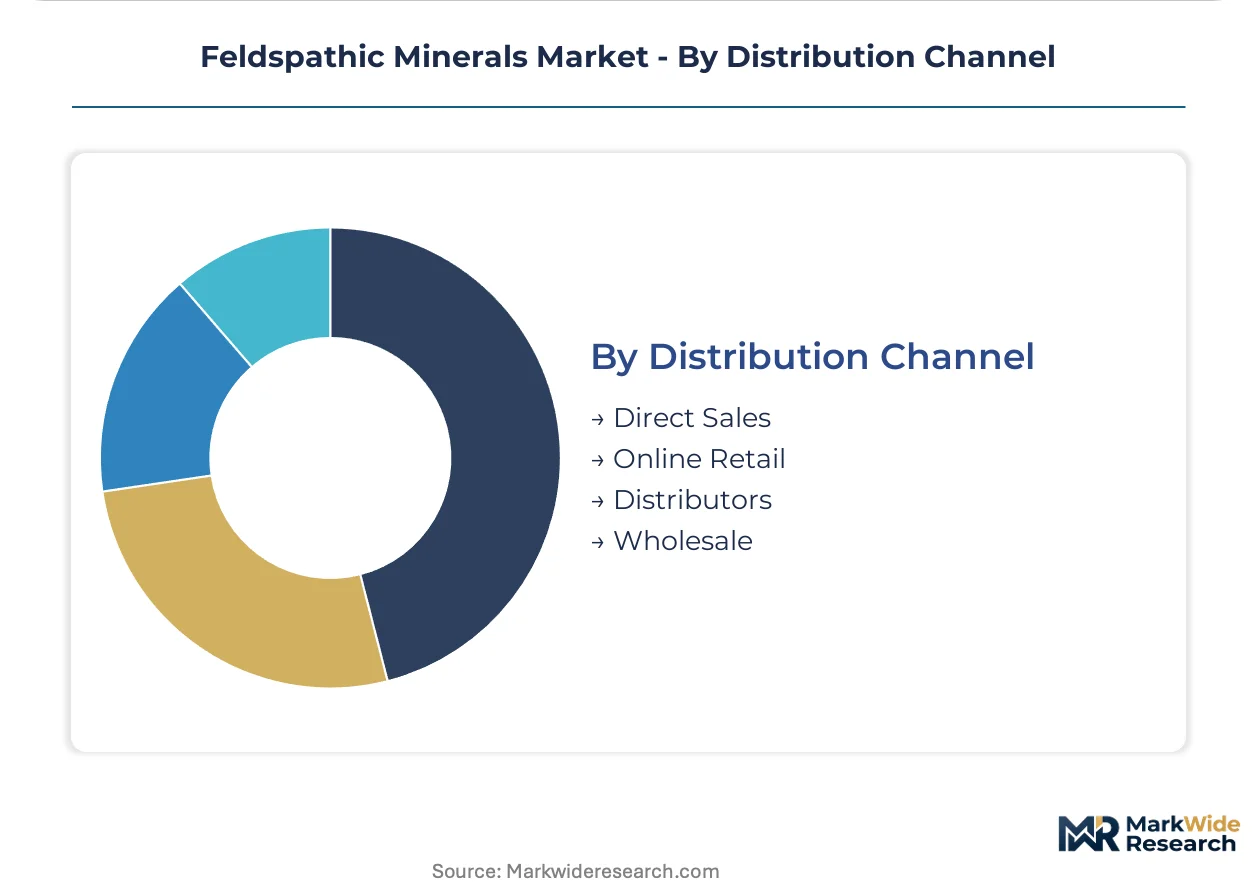
Channel selection reflects buyer scale and specification complexity, with direct sales dominating integrated manufacturers and intermediaries serving fragmented procurement.
- Direct Sales:Multinational tile producers negotiate long-term alkali-ratio agreements with penalty clauses for deviation, displacing spot-market purchasing. Sibelco and Imerys Ceramics anchor European supply through vertically integrated milling networks.
- Distributors:Serve mid-tier ceramic producers lacking mineralogy expertise, with Turkish and Norwegian processors consolidating regional distribution.
- Wholesale:Handles commodity-grade feldspar for lower-specification ceramic body formulations facing alumina substitution pressure.
- Online Retail:Emerging for specialty grades and small-batch laboratory supplies.
Shipment volumes concentrate in Direct Sales; Distributors show the steepest expansion trajectory as modular batch customization spreads to mid-market buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China mines the bulk of raw feldspathic ore yet Turkey and Norway dominate refined export supply. This production-consumption divide shapes trade flows and quality stratification across ceramic and glass manufacturing networks.
China
Vitrified tile manufacturers in Guangdong and Fujian provinces scale high-density output, pulling concentrated feldspar offtake through domestic milling networks. SAMR enforces GB/T 14506 purity thresholds capping Fe₂O₃ below 0.3% for premium ceramic grades, filtering out unprocessed run-of-mine material. Shandong processors retrofit kilns with waste-heat recovery systems to maintain operating licenses under MEE dual carbon enforcement.
Turkey
Anatolian open-pit operations feed rail-linked export capacity through Izmir port, anchoring seaborne trade to European and Asian ceramic producers. Mining Law and Environmental Impact Assessment regulations mandate site rehabilitation, adding compliance costs that transfer into contract pricing. Kaltun Madencilik and competitors concentrate beneficiation investment in western Anatolia to meet tightening alkali-ratio specifications.
India
Morbi-based tile producers in Gujarat account for rising regional feldspar offtake as vitrified output expands. BIS certification for ceramic-grade material gains traction among exporters shipping to Middle East and Africa markets, though laboratory testing queues delay contract execution. The state cluster is backward-integrating into captive beneficiation, creating equipment demand for mineral processing specialists.
Norway
Sibelco leverages vertically integrated milling networks to sustain consistent particle-size distribution for European vitrified tile lines. REACH-registered grades with verified carbon footprints command preferential placement in sustainability-scored procurement frameworks aligned with EU Green Deal criteria. Coastal processing plants optimize logistics for Mediterranean ceramic manufacturing clusters.
Italy
Sassuolo ceramic manufacturers adopt specification-driven contracting with long-term alkali-ratio agreements displacing spot-market purchasing. Sensor-based ore sorting from Turkish and Norwegian pre-concentration outputs reduces downstream energy consumption. The Emilia-Romagna cluster tightens firing viscosity tolerances for tableware and sanitaryware segments.
Feldspathic Minerals Market Competitive Landscape
The competitive structure tilts toward vertically integrated mineral processors with captive milling networks and rail-port logistics. Tiered supplier groups separate multinational specialists delivering certified alkali ratios from regional miners selling standardized flux grades. Three archetypes dominate: integrated processors controlling beneficiation-to-distribution chains, state-linked mining groups with centralized compliance infrastructure, and mid-tier distributors serving fragmented ceramic producers. Capacity expansion and specification-driven partnership structures represent the dominant competitive moves as buyers abandon spot purchasing.
Among European-integrated specialists, Imerys Ceramics and Sibelco occupy positions defined by coastal milling networks and REACH-registered sustainability credentials. Kaltun Madencilik Sanayi ve Ticaret exemplifies the Anatolian rail-linked export model that dominates Mediterranean seaborne supply. These three represent distinct geographic and structural archetypes rather than direct product competitors.
| Leading Market Players |
|---|
| Imerys Ceramics |
| Sibelco |
| Eczacıbaşı Holding |
| Asia Mineral Processing |
| Kaltun Madencilik Sanayi ve Ticaret |
| El Waha Mining & Fertilizers |
| Minerali Industriali |
| I-Minerals Inc. |
| Gottfried Feldspat |
| Others |
Supply & Pricing Matrix
Family-owned mid-caps across Anatolia and coastal Norway anchor refined feldspar supply, translating operational discipline into pricing power that resists spot-market volatility. Their captive milling networks and rail-port logistics create bid-ask spreads that commodity traders cannot compress, while long-term offtake contracts with ceramic manufacturers lock in alkali-ratio premiums.
Pricing Analysis
Cost-down pressure on standard-grade flux accelerates because synthetic nepheline syenite and recycled glass cullet encroach on lower-specification ceramic formulations. Contract-based long-term offtake dominates procurement, with price differentiation resting on GB/T 14506 certification tier and verified particle-size distribution. Premium ceramic-grade material commands substantial premiums over commodity flux, yet glass manufacturers remain the most price-sensitive buyers. Energy cost volatility in ball milling and spray-drying operations compresses margins on fixed-price agreements.
Supply Chain Analysis
Single-source vulnerability sits with Turkish rail-linked export capacity through Izmir port, where Kaltun Madencilik and competitors concentrate beneficiated output for European and Asian ceramic producers. Raw material dependencies draw from Anatolian open-pit feldspar, Norwegian Spruce Pine pegmatite deposits, and Indian Gujarat-run-of-mine feedstock. Tariff exposure looms as BIS certification requirements fragment procurement patterns across Middle East and Africa-bound shipments. Distribution runs through vertically integrated processors with direct mill-to-plant logistics rather than commodity exchanges.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's SAMR enforcement of GB/T 14506 purity thresholds erects a cost-of-compliance barrier that rewards incumbent beneficiation investment and filters out unprocessed run-of-mine competition. This regulatory moat deepens as MEE dual carbon enforcement adds emissions compliance infrastructure requirements.
For Market Incumbents: Hedge against alumina substitution pressure by deepening beneficiation capacity in western Anatolia and Gujarat, where Morbi-based tile producers backward-integrate into captive processing. Secure REACH-registered sustainability credentials to capture EU Green Deal-aligned procurement premiums before carbon footprint verification becomes mandatory across Mediterranean supply chains. For New Entrants and Emerging Players: Begin with sensor-based ore sorting technology deployment serving mid-tier ceramic producers lacking in-house mineralogy expertise, a white-space segment between multinational specialists and commodity traders. Target Indian BIS certification services and digital particle-size control equipment supply as the most penetrable entry vector, leveraging laboratory testing queue backlogs as a service gap. For Investors and Strategic Acquirers: Distressed-cycle entries favor Anatolian processors with rail-port logistics and existing GB/T 14506-equivalent quality infrastructure, where Mining Law rehabilitation liabilities have compressed valuations. Watch for inflection when EU ceramic tile standards tighten alkali-ratio specifications, triggering specification-driven contract restructuring across Sassuolo and Morbi manufacturing clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Beneficiation Capacity Expansion | Captures GB/T 14506 premium grades as SAMR filters unprocessed material from Chinese procurement. |
| Backward Integration into Mining | Secures Anatolian open-pit feedstock before Mining Law rehabilitation costs transfer into contract pricing. |
| REACH Carbon Footprint Registration | Positions Sibelco and Imerys Ceramics for EU Green Deal sustainability-scored tile procurement frameworks. |
| Digital Particle-Size Control Deployment | Enables laser diffraction real-time monitoring guarantees for vitrified tile line tolerances. |
| BIS Certification Service Provision | Addresses laboratory testing queue backlogs delaying Indian exporter contract execution to Middle East markets. |
Research Methodology
Independent corroboration across mineral processing plant managers, procurement leads at multinational tile manufacturers, Turkish mining regulatory officials, and glass batch chemists underwrites the qualitative findings. Secondary validation draws from SAMR GB standard filings, Indian BIS certification databases, Turkish Mining Law compliance disclosures, and EU REACH registration records. Bottom-up volume estimates from beneficiation capacity utilization triangulate against top-down trade flow analysis across Izmir port and Mediterranean ceramic manufacturing clusters.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon, with analytical frameworks modeling product type segmentation by potassium-sodium-calcium chemistry, application tier by ceramics-glass-plastics-paints end-use, and distribution channel by direct-distributor-wholesale configuration. CAGRs derive from alkali-ratio specification tightening trajectories, vitrified tile output expansion rates in Southeast Asia, and flat glass flux substitution elasticities. Industry-specific inputs include MEE dual carbon enforcement timelines and EU ceramic tile standard revision cycles.
Underlying measurement precision varies by segment; ceramics application data carry tighter precision than plastics filler applications due to concentrated multinational buyer disclosure. Forecasts reflect assumptions about regulatory enforcement intensity, beneficiation technology diffusion rates, and synthetic flux substitution thresholds. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
Caustic Calcined Magnesite Market
Industrial Minerals
Talc Market
Industrial Minerals
Global Carbonate Minerals Market
Industrial Minerals
China Feed Minerals Market
Industrial Minerals
Nepheline Syenite Market
Industrial Minerals
Industrial Salts Market
Industrial Minerals
Barite Mining Market
Industrial Minerals
Pyrophyllite Market
Industrial Minerals
Micronized Salt Market
Industrial Minerals
Diatomite Mining Market
Industrial Minerals
India Feed Minerals Market
Industrial Minerals
Chelated Minerals Market
Industrial Minerals
Anhydrite Market
Industrial Minerals
Feldspar Mining Market
Industrial Minerals
Mineral Salt Ingredients Market
Industrial Minerals
Dolomite Mining Market