
 China Feed Minerals Market | 2026-2036
China Feed Minerals Market Size, Share, and Industry Trends Forecast 2026-2036
China Feed Minerals Market Analysis
Market Context
China's GB standards for feed-grade mineral additives is pivoting the cost-of-entry calculus for new premix suppliers. BASF SE leverages its Ludwigshafen technical base to sustain high-purity trace mineral output for Chinese compound feed mills. Cargill Inc. anchors its position through integrated supply chains linking Brazilian ore sources to Yangtze port processing facilities. Adisseo competes by specializing in methionine-chelated trace minerals that bypass antagonistic mineral interactions in high-density poultry diets.
Technical Definition and Segment Structure
China feed minerals comprise inorganic and organic compounds including zinc oxide, copper sulfate, manganese oxide, and selenium yeast, formulated to precise ppm concentrations in premixes that prevent deficiency disorders and optimize feed conversion ratios in monogastric and ruminant systems. Trace minerals command premium formulation attention due to narrow therapeutic windows between deficiency and toxicity thresholds in livestock metabolism. Macro minerals occupy mature volume positions in swine and ruminant rations where calcium-phosphorus ratios follow standardized NRC-derived matrices. Aquaculture applications represent the fastest-growing mineral demand vector as shrimp and finfish producers adopt species-specific mineral premixes for immune resilience and shell integrity.
Regulatory Framework
China's Ministry of Agriculture and Rural Affairs, the National Health Commission, and SAMR collectively enforce feed additive catalogues, maximum permitted levels, and quality certification protocols that determine which mineral forms gain market access. The country's national standards regulator maintains GB testing methodologies that foreign suppliers must navigate for import registration and domestic blending authorization. Stakeholders must monitor pending revisions to organic mineral inclusion rates and environmental discharge rules that will reshape premix formulation priorities and sourcing strategies.
Market Dynamics
China's GB standards revision for feed-grade mineral additives is compressing the supplier base by raising purity thresholds and testing rigor, forcing domestic blenders to retool formulation protocols and foreign entrants to secure costly import registrations.
Growth Catalysts
- Swine sector consolidation:Large-scale operations in Henan and Shandong provinces are standardizing mineral premix protocols to optimize feed conversion ratios and reduce mortality from deficiency disorders.
- GB standards harmonization:The Ministry of Agriculture and Rural Affairs is aligning domestic testing methodologies with Codex Alimentarius frameworks, accelerating quality upgrades across Yangtze River Delta feed mills.
- Organic mineral chelation:Methionine-bound trace minerals are penetrating high-density poultry diets to bypass copper-iron antagonism and improve bioavailability at lower inclusion rates.
Market Restraints
- Copper sulfate price volatility:Electrolytic copper fluctuations on the Shanghai Futures Exchange transmit directly to premix cost structures, squeezing margin predictability for compound feed manufacturers.
- Import dependency for selenium yeast:Domestic production capacity for food-grade selenium precursors remains concentrated in Hubei and Jilin provinces, creating supply vulnerability during environmental compliance inspections.
- Antagonistic mineral interactions:High-density calcium formulations in layer rations depress zinc and manganese absorption, forcing costly over-formulation or specialized chelate substitution.
Strategic Opportunities
- Southwest aquaculture corridor:Guangxi and Yunnan shrimp producers are adopting species-specific mineral premixes for shell integrity and immune resilience, opening formulation specialization channels.
- Dual carbon policy alignment:MEE environmental discharge rules are incentivizing low-carbon mineral processing technologies that reduce sulfur dioxide emissions from sulfate production.
- Precision livestock farming integration:Real-time mineral status monitoring via near-infrared spectroscopy is converging with automated premix dispensing systems in Guangdong mega-farms.
Industry Challenges
- Formulation chemist scarcity:Technical expertise in species-specific mineral matrices and antagonism management is concentrated among retiring specialists at state research institutes.
- GB certification timeline compression:New organic mineral forms face 18-24 month approval windows at SAMR, delaying market entry against faster domestic competitor registrations.
Report Scope
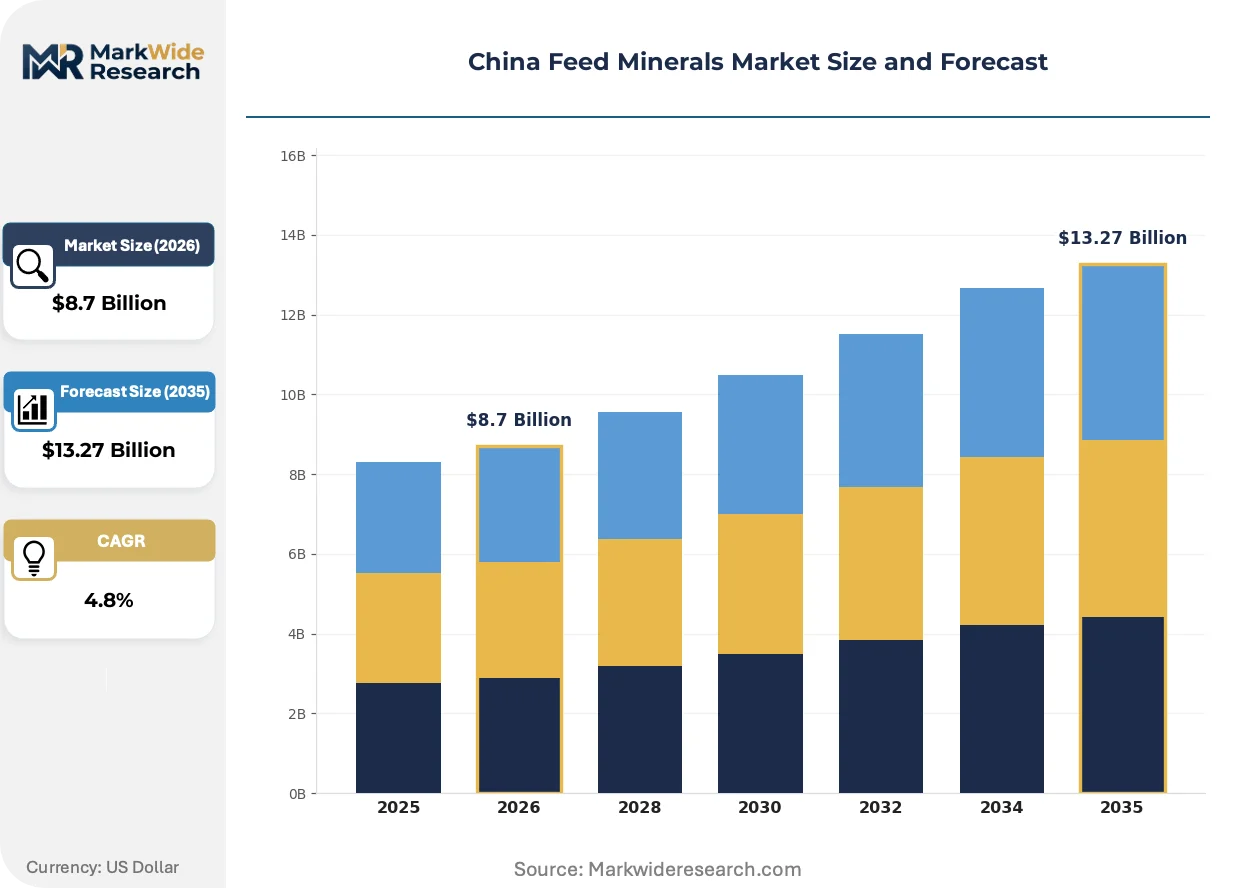
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Feed Minerals Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.27 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Amino Acids, Trace Minerals, Macro Minerals Application: Poultry, Swine, Ruminants, Aquaculture Distribution Channel: Direct Sales, Distributors, Online Sales, Retail End User: Feed Manufacturers, Livestock Farmers, Aquaculture Producers, Veterinary Clinics |
| Companies Covered | Alltech Inc., BASF SE, Cargill Inc., Archer Daniels Midland Co., Adisseo, Solvay S.A., Kemin Industries, Nutreco N.V., Phibro Animal Health Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Feed Minerals Market Emerging Trajectories
Mineral delivery systems are pivoting from bulk commodity inclusions toward precision-formulated organic chelates and nano-dispersion technologies that bypass digestive antagonisms in high-performance livestock operations.
Nano-particulate zinc oxide is converging with polymer encapsulation techniques to sustain antimicrobial efficacy in weanling pig diets at reduced environmental discharge levels. Leading swine integrators in Jiangsu province are piloting these formulations to replace conventional pharmacological zinc doses. The technology is compressing the therapeutic window between deficiency prevention and regulatory maximums, enabling compliance with pending MEE effluent standards.
SAMR's pending revision to maximum permitted levels for copper and zinc in complete feeds is forcing reformulation across the premix sector. The regulation will prohibit growth-promotion copper levels in fattening rations and mandate reduced zinc oxide for diarrhea control. Poultry and swine premix manufacturers are accelerating organic mineral substitution programs to maintain performance at lower total inclusion rates.
Integrated farming conglomerates are consolidating mineral procurement through captive premix subsidiaries rather than independent suppliers. Wens Foodstuff Group and New Hope Liuhe have established in-house blending facilities to secure formulation control and cost transparency. This pattern is most visible in the Pearl River Delta, where vertical integration is displacing third-party premix relationships among top-ten feed producers.
China Feed Minerals Market Segmentation
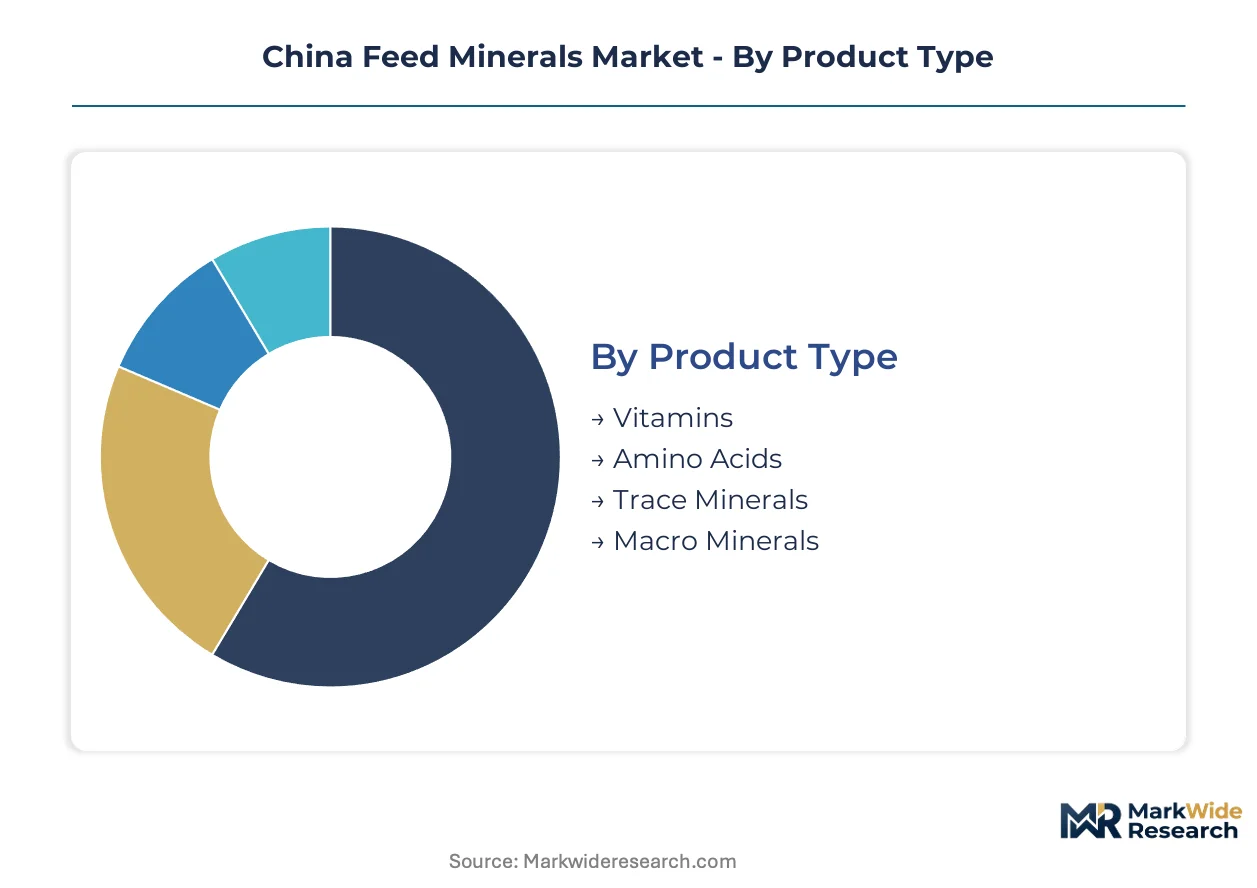
Feed mineral segmentation in China reflects divergent formulation priorities across livestock species and procurement channels. Suppliers must align product portfolios with the technical specifications of large-scale integrators versus fragmented backyard operations.
Product Type:
Volume concentration favors bulk macro minerals, while premium capture concentrates in bioavailable trace mineral chelates.
- Trace Minerals:Zinc oxide, copper sulfate, and selenium yeast formulated at ppm precision for metabolic enzyme activation and immune function. Demand clusters in Shandong swine integrators pursuing pharmacological zinc for weanling gut health within pending MEE discharge limits.
- Macro Minerals:Calcium carbonate, dicalcium phosphate, and sodium chloride blended at percentage inclusion rates for skeletal development and osmotic balance. Mature volume positions in Henan dairy operations follow standardized NRC calcium-phosphorus matrices with minimal formulation differentiation.
- Vitamins:Fat-soluble and water-soluble vitamin premixes co-formulated with minerals in complete feed additives.
- Amino Acids:Lysine, methionine, and threonine supplemented alongside minerals to optimize protein utilization efficiency.
Mature deployment sits with Macro Minerals. Newer deployment is concentrated in Trace Minerals.
Application:
Species-specific mineral matrices separate commodity poultry rations from precision-formulated aquaculture diets.
- Swine:Zinc-copper premixes targeting post-weaning diarrhea control and growth promotion, with reformulation urgency around SAMR's pending copper reduction mandates. Large-scale Henan operations are piloting nano-zinc oxide to sustain efficacy at lower inclusion rates.
- Aquaculture:Species-specific mineral premixes for shrimp shell mineralization and finfish immune resilience. Guangxi producers are adopting chelated selenium and zinc complexes for whiteleg shrimp farming in intensive pond systems.
- Poultry:Layer rations balancing calcium density with zinc-manganese bioavailability, often requiring organic chelate substitution to bypass antagonistic absorption inhibition.
- Ruminants:Sustained-release mineral boluses and free-choice supplements for grazing cattle in Inner Mongolia pastoral zones.
Volume leadership remains with Swine. Steepest expansion trajectory belongs to Aquaculture.
Distribution Channel:
Channel selection tracks customer scale, with direct relationships dominating tonnage and distributor networks covering geographic whitespace.
- Direct Sales:Long-term supply contracts between premix manufacturers and top-twenty feed producers, securing volume commitments and formulation co-development. Wens Foodstuff and New Hope Liuhe have shifted toward captive blending, compressing third-party direct sales scope.
- Distributors:Provincial-level mineral traders serving mid-tier feed mills and independent livestock farms in peripheral provinces. Networks concentrate in Sichuan and Hunan where feed producer fragmentation sustains intermediary relevance.
- Online Sales:E-commerce platforms targeting smallholder farmers with packaged mineral supplements, limited by technical consultation requirements for proper inclusion rate guidance.
- Retail:Agricultural supply stores stocking standard mineral blocks and loose salt mixtures for backyard ruminant operations.
Procurement consolidation is accelerating in Direct Sales. Distributors retain relevance in county-level market penetration.
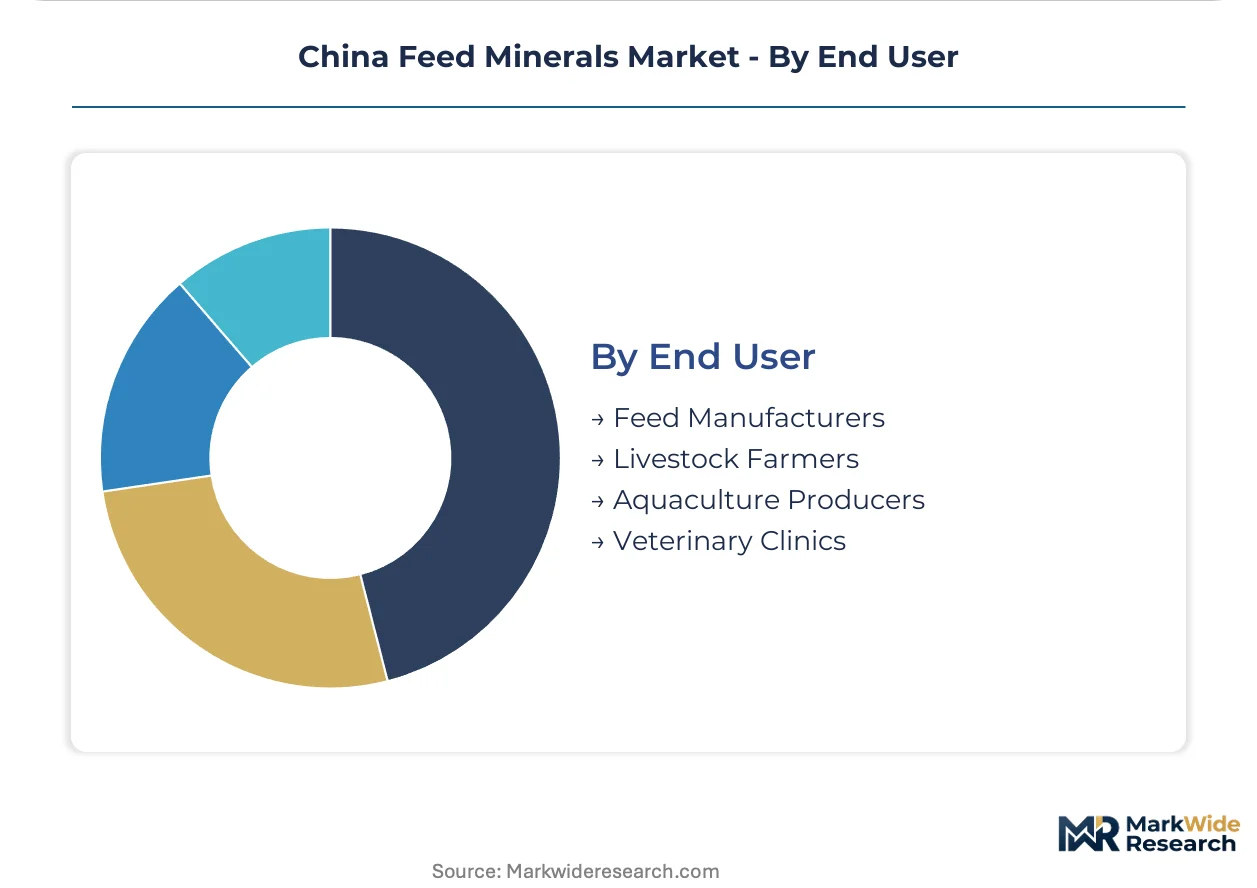
End User:
Customer technical sophistication spans automated premix dispensing systems at mega-farms to manual blending at household operations.
- Feed Manufacturers:Compound feed mills purchasing bulk mineral premixes for integration into complete rations, with Yangtze River Delta producers driving specification tightening around GB testing compliance.
- Livestock Farmers:Direct mineral procurement by large-scale integrators with in-house nutrition teams, particularly in Jiangsu and Guangdong where precision livestock farming adoption is highest.
- Aquaculture Producers:Specialized demand from intensive shrimp and finfish operations in Guangxi and Hainan requiring species-tailored mineral matrices.
- Veterinary Clinics:Therapeutic mineral supplementation for deficiency correction in companion animals and small ruminant flocks.
Feed Manufacturers command formulation standardization. Aquaculture Producers are driving the fastest specification evolution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta Economic Zone concentrates China's feed mineral demand through integrated farming corridors linking Shanghai, Jiangsu, and Zhejiang provinces. Provincial governments in Shandong and Henan have designated livestock modernization zones with accelerated mineral premix adoption timelines.
Shandong Province
Swine integrators in Linyi and Weifang are expanding pharmacological zinc oxide programs for weanling gut health. The provincial agriculture department enforces stricter effluent discharge permits under MEE coordination. Qingdao-based feed mills are piloting nano-zinc formulations to preempt national copper-zinc reduction mandates.
Henan Province
Dairy operations around Zhengzhou and Luoyang are standardizing calcium-phosphorus premix matrices for Holstein herds. SAMR's provincial offices conduct quarterly GB standard compliance audits at compound feed facilities. Nanyang's emerging poultry belt is driving manganese and selenium yeast procurement from Yangtze Delta suppliers.
Jiangsu Province
Precision livestock farming adoption in Suzhou and Changzhou is converging mineral status monitoring with automated premix dispensing. The provincial dual carbon implementation office incentivizes low-sulfur processing technologies. Nanjing's feed research institutes are testing polymer-encapsulated zinc oxide for reduced environmental discharge.
Guangdong Province
Pearl River Delta mega-farms are consolidating mineral procurement through captive premix subsidiaries. Local MEE bureaus are tightening water quality standards for intensive aquaculture operations. Foshan and Jiangmen shrimp producers are importing chelated selenium complexes for whiteleg shell mineralization.
Guangxi Zhuang Autonomous Region
Aquaculture corridors around Beihai and Qinzhou are adopting species-specific mineral premixes for intensive pond systems. The regional agriculture bureau promotes standardized shrimp farming protocols with immune-resilience mineral matrices. Nanning distributors are expanding trace mineral coverage into Yunnan border markets.
China Feed Minerals Market Vendor Landscape
European chemical conglomerates anchor one tier through Ludwigshafen and Antwerp technical bases; Chinese state-linked feed groups hold volume positions through Yangtze corridor processing assets. The supplier base compresses around three archetypes: multinational premix formulators with import registration advantages, domestic blenders with provincial distribution density, and captive integrator subsidiaries with formulation control. Competitive moves concentrate on backward integration into ore sourcing and technology licensing for organic chelate production.
Within the multinational tier, BASF SE and Cargill Inc. occupy positions defined by integrated supply chains and technical service depth. BASF exemplifies the high-purity trace mineral archetype through its Ludwigshafen manufacturing base serving Chinese compound feed mills. Cargill represents the agricultural-commodity-to-premix integrator model with Brazilian ore linkages to Yangtze port facilities. Adisseo sits within the specialty organic mineral segment, anchoring methionine-chelated trace mineral supply for poultry operations seeking bioavailability advantages.
| Leading Market Players |
|---|
| Alltech Inc. |
| BASF SE |
| Cargill Inc. |
| Archer Daniels Midland Co. |
| Adisseo |
| Solvay S.A. |
| Kemin Industries |
| Nutreco N.V. |
| Phibro Animal Health Corporation |
| Others |
Supply Flow & Price Mechanics
Large-scale feed manufacturers in the Yangtze River Delta anchor procurement volumes and command contract-based pricing with volume-scaled discounts, while smaller compound feed mills absorb spot-market premiums for trace mineral premixes. This buyer-tier concentration compresses margin pools for domestic blenders serving fragmented backyard operations in peripheral provinces.
Pricing Analysis
Short lead-time premiums of 8-15 percent apply to nano-zinc oxide and methionine-chelated trace minerals needed for SAMR compliance deadlines, while standard-grade copper sulfate and manganese oxide trade at spot discounts when Brazilian ore shipments clear Yangtze ports. Price differentiation rests on GB certification tier and vertical integration depth, with BASF and Cargill capturing brand premiums through Ludwigshafen and Antwerp technical validation. Cost compression in standard inorganic minerals is intensifying as Henan swine integrators consolidate procurement through captive blending subsidiaries. Mid-tier feed mills show highest price sensitivity, while Wens Foodstuff and New Hope Liuhe absorb premiums for formulation co-development rights.
Supply Chain Analysis
Freight costs from Brazilian ore terminals to Yangtze port facilities add 12-18 percent to copper sulfate and manganese oxide landed costs, compressing margins for non-integrated premix suppliers. Supply concentrates in Brazil, Chile, and Peru for copper and manganese precursors, while selenium yeast production draws from Hubei and Jilin domestic capacity. Raw material dependencies span electrolytic copper, phosphate rock, and food-grade selenium precursors. Single-source vulnerability runs through Brazilian ore linkages subject to drought-disrupted mining output. Distribution runs through provincial mineral traders in Sichuan and Hunan covering mid-tier feed mills, with direct sales contracts dominating tonnage at top-twenty producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The China feed minerals sector functions as a vertical-integration race where upstream ore sourcing and downstream captive blending determine cost position. Players securing Brazilian offtake agreements or Pearl River Delta processing assets gain structural advantage over pure-formulation competitors.
For Market Incumbents: Deploy GB certification acceleration programs to preempt SAMR's pending organic mineral inclusion revisions, locking in 18-24 month approval timelines before domestic competitors replicate methionine-chelate portfolios. Secure backward integration into Hubei selenium yeast production or Brazilian manganese ore offtake to reduce import dependency exposure during environmental compliance inspections. Channel control through direct sales contracts with Yangtze Delta integrators defends against Wens Foodstuff and New Hope Liuhe captive blending expansion.
For New Entrants and Emerging Players: Provincial distributors in Guangxi and Yunnan represent the most penetrable channel archetype, covering aquaculture corridors where species-specific mineral premixes command formulation premiums absent from commoditized swine rations. Target whiteleg shrimp producers in Beihai and Qinzhou with chelated selenium-zinc complexes for shell mineralization, bypassing saturated Henan poultry and Shandong swine markets. Go-to-market leverage rests on technical service partnerships with Nanning agricultural extension bureaus promoting standardized intensive pond protocols.
For Investors and Strategic Acquirers: The window for entry favors domestic blenders with SAMR registration pipelines and Yangtze corridor processing assets, positioned to capture reformulation demand from SAMR's copper-zinc reduction mandates. Long-term viability hinges on dual carbon policy alignment through low-sulfur processing technology licensing from European chemical conglomerates. Acquisition screening should prioritize Hubei-based selenium yeast producers with MEE environmental compliance clearance. The signal to watch is SAMR publication of final maximum permitted levels for copper and zinc in complete feeds, which will trigger accelerated organic mineral substitution programs and consolidate premix supplier tiers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ore Sourcing | Brazilian manganese offtake agreements reduce exposure to Shanghai Futures Exchange copper volatility. |
| GB Certification Acceleration | SAMR approval timelines for organic mineral forms compress competitive response windows to 18-24 months. |
| Low-Sulfur Processing Transition | MEE environmental discharge rules incentivize sulfur dioxide reduction from sulfate production methods. |
| Captive Blending Subsidiary Establishment | Pearl River Delta integrators secure formulation control and cost transparency versus third-party premix relationships. |
| Species-Specific Aquaculture Formulation | Guangxi shrimp producers adopt chelated selenium complexes for shell mineralization in intensive pond systems. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across feed formulation chemists, SAMR registration specialists, Yangtze Delta procurement directors, and Hubei selenium yeast plant managers. Bottom-up volume modeling triangulated against top-down mineral inclusion rate assumptions derived from NRC-derived matrices and GB standard specifications. Secondary sources spanned Ministry of Agriculture and Rural Affairs additive catalogues, SAMR quality certification protocols, and Yangtze port customs clearance records for Brazilian ore shipments.
Data-stream reconciliation across production volumes, premix formulation rates, and livestock population statistics generated segment-level outputs across the projection horizon. Segmentation dimensions spanned product type (trace minerals, macro minerals, organic chelates), application species (swine, poultry, aquaculture, ruminants), and distribution channel (direct sales, provincial distributors, captive blending). CAGRs derived from mineral inclusion rate evolution, livestock sector consolidation trajectories, and regulatory reformulation mandates. Industry-specific inputs included SAMR pending revision timelines for copper-zinc maximums and MEE environmental discharge inspection schedules.
Caveats apply where SAMR regulatory publication delays, Brazilian mining output disruptions, or MEE environmental compliance enforcement intensity could materially shift the outlook. Forecasts reflect documented assumptions around livestock population growth, premix adoption rates, and import registration timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
Olivine Sand Market
Industrial Minerals
Global Cristobalite Market
Industrial Minerals
Feldspathic Minerals Market
Industrial Minerals
Slate Market
Industrial Minerals
Global Epsom Salt Market
Industrial Minerals
United States Feed Minerals Market
Industrial Minerals
Nepheline Syenite Market
Industrial Minerals
Calcined Anthracite Market
Industrial Minerals
Aluminium Potassium Sulphate Market
Industrial Minerals
Middle East Feed Minerals Market
Industrial Minerals
Global Commercial Perlite Market
Industrial Minerals
Mineral Enrichment Ingredients Market
Industrial Minerals
Mineral Adsorbent Market
Industrial Minerals
Dolomite Powder Market
Industrial Minerals
Bentonite Market
Industrial Minerals
Seaweed Derived Minerals Market