
 Mexico Floor Coatings Market | 2026-2036
Mexico Floor Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Floor Coatings Market Outlook
Performance-grade epoxy systems is bifurcating the Mexico floor coatings landscape as industrial end-users demand thicker-film, chemical-resistant specifications over commodity offerings. PPG Industries Inc anchors its position through captive resin sourcing and technical service networks across Monterrey and Mexico City. Sherwin-Williams controls distribution density via dedicated contractor channels and color-matching infrastructure. Sika AG specializes in rapid-cure cementitious overlays that reduce facility downtime for automotive and food-processing clients.
Floor coatings comprise resin-based protective layers applied to concrete substrates, typically ranging from two to ten mils in dry-film thickness, designed to resist abrasion, chemical attack, and moisture vapor transmission in industrial and commercial environments. Epoxy formulations dominate volume in heavy-manufacturing applications due to superior adhesion and compressive strength, while polyurethane gains share in flexible, high-traffic commercial settings where thermal cycling occurs. Water-based systems are expanding fastest among institutional and residential applications as SEMARNAT enforcement tightens solvent emissions, though 100% solids epoxies retain margin pools in aerospace and pharmaceutical cleanrooms where zero-VOC performance commands specification premiums.
SEMARNAT's NOM-086-ECOL-1994 and evolving state-level air-quality programs in Nuevo León and Jalisco are forcing reformulation investments and compliance documentation across imported and locally manufactured product lines. Mexico's Federal Commission for the Protection against Sanitary Risk (COFEPRIS) regulates antimicrobial claims in healthcare and food-processing floor systems, adding testing burdens for cross-border suppliers. Stakeholders must monitor pending amendments to NOM standards and assess whether captive blending in Mexico or tariff-advantaged imports from USMCA partners offers the more durable supply architecture.
Market Dynamics
SEMARNAT's tightening VOC limits are forcing a wholesale resin reformulation cycle across Mexican floor coatings manufacturing, compressing margins for solvent-dependent producers while elevating specification premiums for compliant water-based and 100% solids systems.
Growth Catalysts
- Automotive Cleanroom Expansion:Guanajuato and Querétaro assembly plants are mandating epoxy and polyurethane flooring systems that meet ISO 14644 cleanliness standards for precision manufacturing environments.
- NOM-086-ECOL-1994 Enforcement:SEMARNAT's evolving emissions framework is accelerating water-based system adoption in institutional and residential segments previously dominated by solvent-borne products.
- Bajío FDI Influx:Foreign direct investment in aerospace and electronics assembly across the industrial corridor is generating specialized coating specifications for electrostatic discharge control and chemical resistance.
Market Restraints
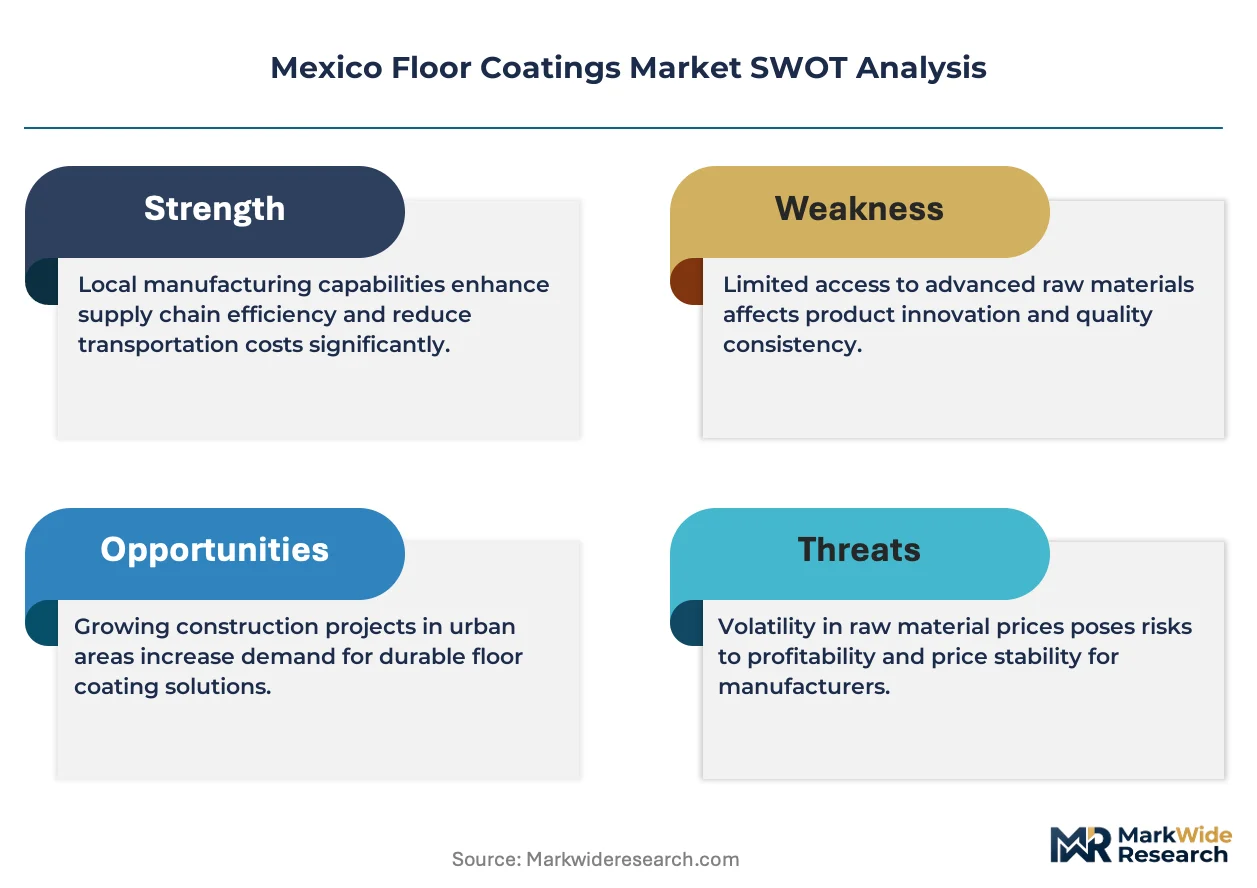
- Epoxy Resin Import Dependence:Local formulators rely on bisphenol-A and epichlorohydrin feedstock from US Gulf Coast petrochemical complexes, exposing margin structures to cross-border tariff volatility and freight cost spikes.
- Technical Limitation in Thermal Cycling:Standard epoxy systems exhibit brittleness under temperature fluctuation, restricting their deployment in food-processing facilities with steam-cleaning protocols where polyurethane commands higher unit economics.
- Substitution Threat from Polished Concrete:Densifier and sealer treatments for bare concrete are capturing light-commercial maintenance budgets in retail and warehousing applications where coating durability requirements remain minimal.
Strategic Opportunities
- Yucatán Peninsula Industrialization:Nearshoring momentum in Mérida and Progreso is creating first-mover advantage for coating applicators establishing technical service infrastructure ahead of aerospace supplier clustering.
- Antimicrobial Floor System Certification:COFEPRIS healthcare facility regulations are opening specification windows for silver-ion and copper-oxide embedded epoxies in hospital and pharmaceutical cleanroom construction.
- Cementitious Overlay Convergence:Rapid-cure polyurethane-modified cement systems are displacing traditional trowel-down epoxies in automotive plant refurbishment cycles where 24-hour return-to-service compresses contractor scheduling.
Industry Challenges
- Applicator Certification Bottleneck:COFEPRIS antimicrobial claim validation requires laboratory testing partnerships that few Mexican contractors maintain, constraining qualified installation capacity for healthcare specifications.
- Moisture Vapor Transmission Expertise Gap:Complex slab assessment and calcium chloride testing protocols for high-performance aerospace flooring exceed the technical training of generalist construction labor pools in emerging industrial zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Floor Coatings Market |
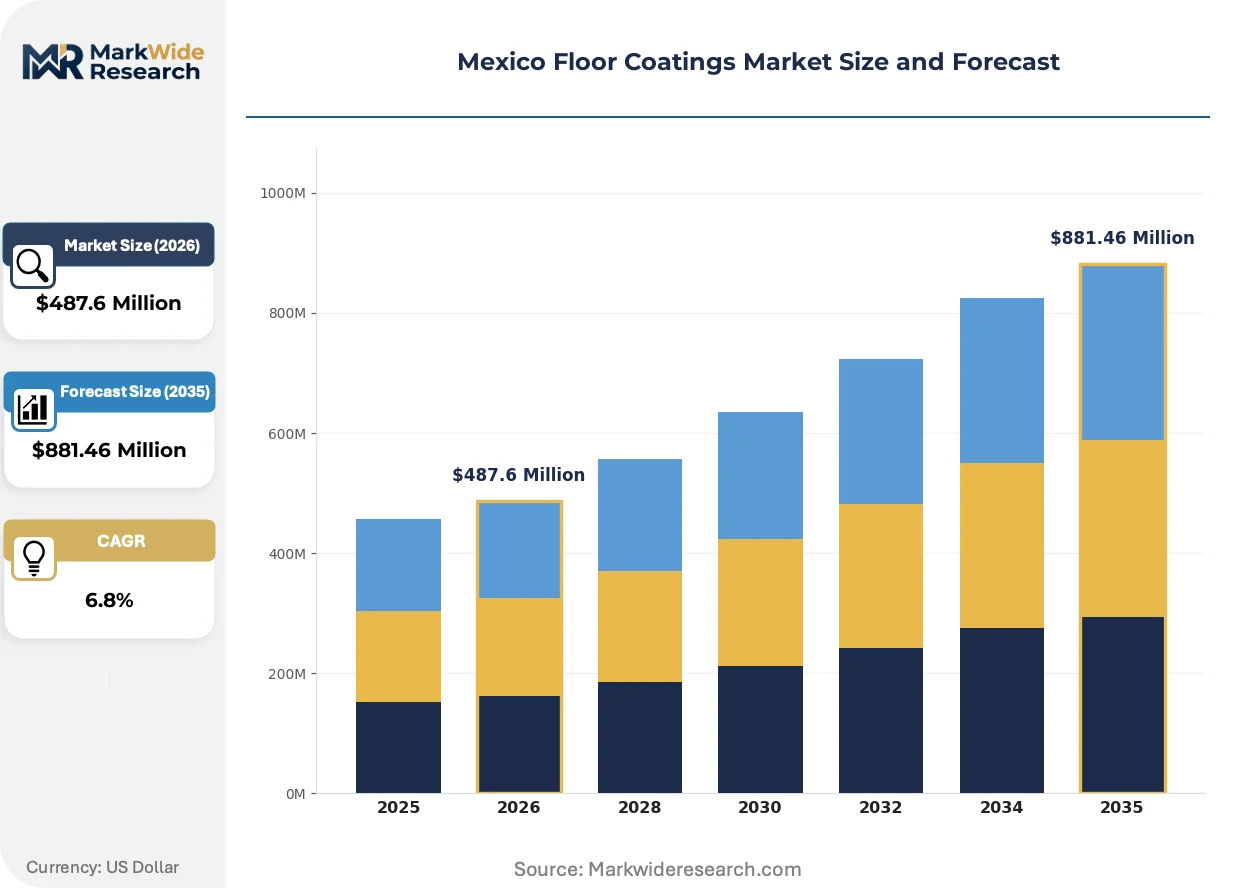
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Cementitious Application: Residential, Commercial, Industrial, Institutional Formulation: Water-Based, Solvent-Based, 100% Solids, Hybrid End User: Contractors, Homeowners, Facility Managers, Industrial Operators |
| Companies Covered | Sika AG, AkzoNobel NV, PPG Industries Inc, The Sherwin-Williams Company, RPM International Inc, BASF SE, Jotun, LATICRETE INTERNATIONAL INC, Teknos Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Floor Coatings Market Strategic Shifts
Reformulation chemistry and application automation are compressing project timelines while elevating performance thresholds across Mexican industrial flooring specifications.
Polyaspartic aliphatic polyurea technology is fragmenting the traditional epoxy-polyurethane dichotomy in high-traffic commercial environments. Property managers in Mexico City retail complexes are specifying 2-4 hour return-to-service systems that eliminate multi-day facility closures. This speed-performance hybrid is compressing contractor scheduling windows and displacing commodity epoxy quotations in time-sensitive refurbishment cycles.
SEMARNAT's state-level air-quality program expansions in Nuevo León and Jalisco are forcing inventory segmentation between compliant and non-compliant product lines. Formulators must maintain parallel solvent-borne stocks for export markets while building water-based capacity for domestic enforcement zones. Automotive OEMs in the Bajío corridor are responding by mandating 100% solids epoxies that satisfy both VOC compliance and zero-VOC cleanroom specifications without dual inventory complexity.
Facility engineering departments are consolidating coating procurement under single-source maintenance contracts that bundle specification, installation, and warranty coverage. Automotive and food-processing plants in Querétaro are displacing fragmented contractor bidding with multi-year service agreements that transfer performance risk to coating system suppliers. This concentration pattern is most visible in foreign-owned manufacturing campuses where corporate standardization protocols override local subcontractor relationships.
Mexico Floor Coatings Market Segmentation
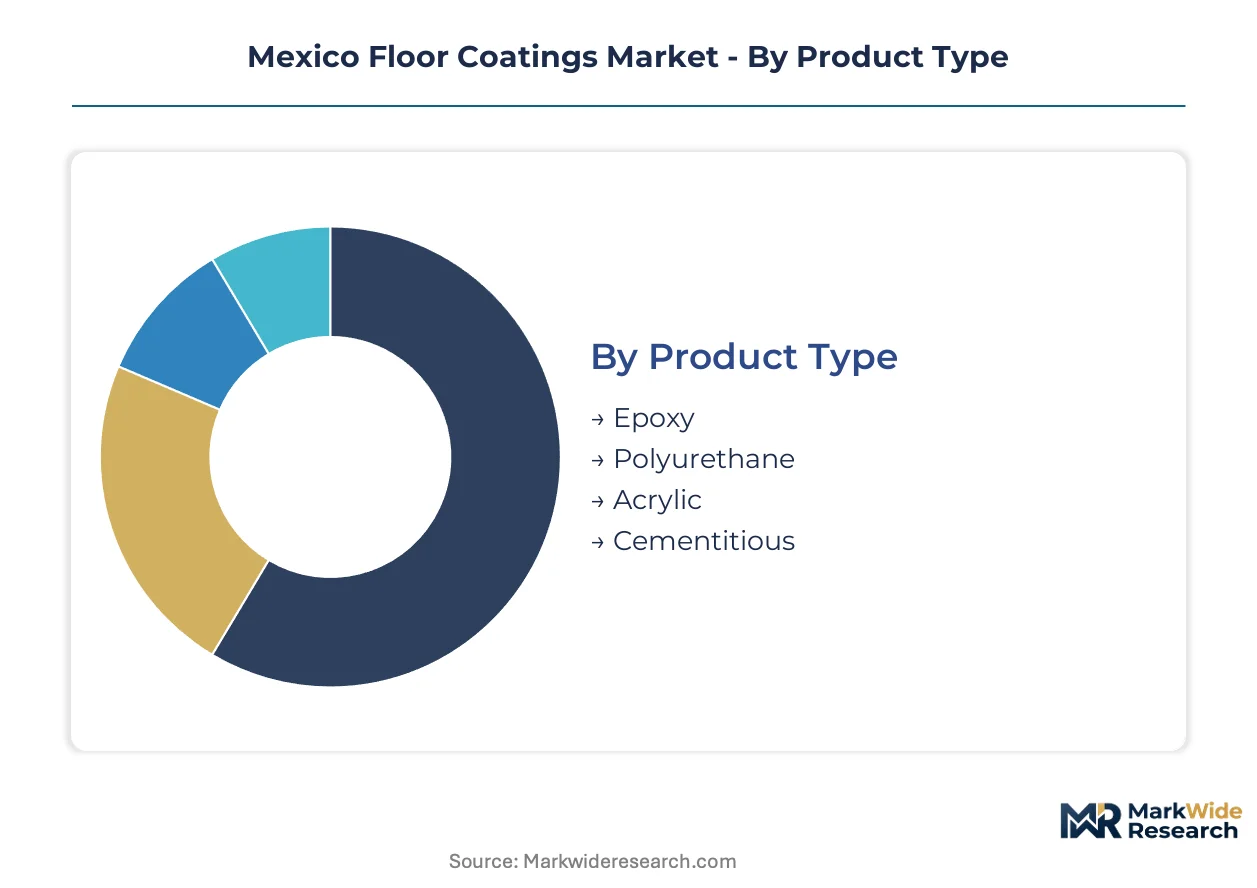
Floor coatings in Mexico stratify across resin chemistry, application environment, and procurement authority, with each dimension carrying distinct margin profiles and regulatory exposure. Understanding these fault lines reveals where substitution threats from polished concrete and densifier systems concentrate most intensely.
Product Type:
Polished concrete densifiers pose the sharpest substitution threat to thin-film commodity coatings, pressuring acrylic and standard epoxy formulations while sparing high-build performance systems.
- Epoxy:Two-part thermosetting systems built from bisphenol-A and epichlorohydrin resins deliver superior compressive strength and chemical resistance. Bajío automotive plants specify high-solids epoxies for assembly line trenches and battery production zones where electrolyte spill containment is mandatory.
- Polyurethane:Aliphatic and aromatic urethane formulations provide elastomeric recovery and UV stability absent in epoxies. Querétaro food-processing facilities deploy polyurethane topcoats over epoxy primers in thermal shock zones adjacent to flash-freezing equipment and steam-cleaning stations.
- Acrylic:Water-dispersed or solvent-borne thermoplastic resins offering rapid dry-to-touch and decorative gloss retention.
- Cementitious:Portland cement-based overlays modified with polymers for resurfacing damaged concrete slabs.
Epoxy anchors the volume base while polyurethane gains share at the steepest rate.
Application:
Margin compression follows divergent paths across application tiers, with industrial specifications commanding technical premiums and residential segments facing price erosion from DIY acrylic alternatives.
- Residential:Decorative garage floor kits and basement sealants sold through retail channels dominate this price-sensitive tier. SEMARNAT's VOC enforcement has pushed major retailers to delist solvent-borne garage epoxies in Nuevo León and Jalisco, accelerating water-based acrylic displacement.
- Commercial:Retail complexes, hospitality venues, and office buildings balance aesthetics with traffic durability. Mexico City property managers are specifying polyaspartic polyurea systems in high-visibility atriums where 4-hour return-to-service eliminates revenue loss from extended closures.
- Industrial:Heavy manufacturing, warehousing, and logistics facilities demand thick-film performance. Aerospace suppliers in Guanajuato mandate electrostatic dissipative epoxies meeting ANSI/ESD S20.20 for electronics assembly cleanrooms.
- Institutional:Healthcare, education, and government facilities prioritize antimicrobial performance and regulatory compliance. COFEPRIS validation requirements for hospital flooring systems create specification barriers that filter out uncertified contractors.
Industrial applications concentrate the highest value per square meter while institutional specifications expand most quickly under healthcare infrastructure investment.
Formulation:
Regulatory geography now overrides performance as the primary segmentation driver, with state-level SEMARNAT enforcement creating compliant and non-compliant inventory zones.
- Water-Based:Acrylic and epoxy dispersions with VOC content below NOM-086-ECOL-1994 thresholds. Institutional and residential segments in Jalisco and Nuevo León have shifted procurement almost entirely to these systems following 2023 state air-quality program expansions.
- Solvent-Based:Traditional high-VOC alkyd and epoxy formulations retaining cost advantages in export markets and enforcement-lag regions. Formulators maintain parallel production lines to serve Central American export demand while building water-based domestic capacity.
- 100% Solids:Zero-VOC epoxy and polyurethane systems cured through chemical reaction without solvent evaporation. Aerospace and pharmaceutical cleanrooms in Querétaro specify these exclusively to satisfy both SEMARNAT compliance and corporate zero-emission protocols.
- Hybrid:Blended water-solvent or epoxy-polyurethane systems optimizing cost and performance trade-offs.
Solvent-based formulations retain volume leadership in export-adjacent production while 100% solids systems climb the fastest on cleanroom specification premiums.
End User:
Procurement authority consolidation is restructuring channel relationships, with facility managers and industrial operators displacing fragmented contractor bidding through integrated maintenance contracts.
- Contractors:Licensed applicators purchasing materials through distributor networks and manufacturer direct accounts. Bajío automotive plant construction cycles have concentrated demand among 15-20 large flooring contractors with SEMARNAT compliance documentation and COFEPRIS antimicrobial certification partnerships.
- Homeowners:Retail consumers selecting DIY garage and basement coating kits. Home Depot and Lowe's México have expanded water-based epoxy shelf space in Monterrey and Guadalajara stores following Nuevo León and Jalisco enforcement actions.
- Facility Managers:Corporate maintenance departments consolidating coating procurement under multi-year service agreements. Foreign-owned manufacturing campuses in Querétaro are displacing spot contracting with PPG and Sherwin-Williams direct service contracts bundling specification, installation, and warranty coverage.
- Industrial Operators:Plant engineering departments with specialized technical requirements for chemical resistance and electrostatic control.
Contractors move the largest material volumes while facility managers are consolidating procurement authority fastest through corporate standardization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation capacity clusters along the Bajío industrial corridor and northern border states, with captive resin blending facilities concentrated near Monterrey and Querétaro to minimize freight exposure to US Gulf Coast feedstock volatility.
Bajío Region
Guanajuato and Querétaro assembly plants drive specification-grade epoxy consumption for automotive cleanrooms and battery production zones. SEMARNAT's NOM-086-ECOL-1994 enforcement has pushed OEMs toward 100% solids systems that satisfy both emissions compliance and corporate zero-VOC protocols. Aerospace supplier clustering near Querétaro generates demand for electrostatic dissipative coatings meeting ANSI/ESD S20.20.
Nuevo León
Monterrey's manufacturing base anchors northern Mexico's largest coating formulation and distribution hub. State-level air-quality program expansions in 2023 forced retailers to delist solvent-borne garage epoxies, accelerating water-based acrylic displacement in residential channels. Heavy industry in the metropolitan area sustains thick-film polyurethane specifications for warehousing and logistics facilities.
Jalisco
Guadalajara's electronics assembly and food-processing sectors generate dual demand streams for rapid-cure cementitious overlays and antimicrobial floor systems. COFEPRIS validation requirements for hospital flooring create specification barriers that filter out uncertified contractors in the metropolitan health infrastructure expansion. State enforcement of SEMARNAT standards has shifted institutional procurement almost entirely to compliant water-based formulations.
Mexico City Metro
Property managers in retail complexes and hospitality venues specify polyaspartic polyurea systems where 4-hour return-to-service eliminates revenue loss from extended closures. The capital's dense commercial real estate stock drives refurbishment cycles for high-visibility atriums and public circulation spaces. Federal procurement standards influence specification trends that propagate to secondary markets.
Yucatán Peninsula
Mérida and Progreso nearshoring momentum is creating first-mover advantage for applicators establishing technical service infrastructure ahead of aerospace supplier clustering. Moisture vapor transmission expertise gaps in emerging industrial zones complicate high-performance flooring deployment for precision manufacturing. Proposed special economic zone status would accelerate foreign direct investment in specialized coating specifications.
Mexico Floor Coatings Market Competitive Environment
Concentration sits with multinational chemical conglomerates possessing captive resin sourcing and continental distribution networks. Three to five integrated manufacturers control specification-grade formulations for automotive and aerospace cleanrooms, while regional formulators compete on price in commodity residential segments. Strategic moves center on backward integration into epoxy resin production and multi-year service agreements that bundle installation with material supply.
Among Switzerland-based and Netherlands-based specialists, Sika AG and AkzoNobel NV exemplify the premium-systems archetype through rapid-cure cementitious technologies and global technical service infrastructure. PPG Industries Inc anchors the North American integrated manufacturer tier with direct contractor channel control across Monterrey and Mexico City. These three occupy positions where specification authority, regulatory compliance documentation, and warranty risk transfer consolidate procurement decisions under single-source relationships.
| Leading Market Players |
|---|
| Sika AG |
| AkzoNobel NV |
| PPG Industries Inc |
| The Sherwin-Williams Company |
| RPM International Inc |
| BASF SE |
| Jotun |
| LATICRETE INTERNATIONAL INC |
| Teknos Group |
| Others |
Value Chain & Pricing Dynamics
Polished concrete densifier penetration in light-commercial warehousing is simultaneously displacing thin-film epoxy demand and compressing freight economics for imported resin feedstock, forcing formulators to rebalance toward high-build performance systems that justify premium positioning against bare-concrete alternatives.
Pricing Analysis
NOM-086-ECOL-1994 dictates the pricing tier structure across Mexican floor coatings, separating SEMARNAT-compliant water-based and 100% solids formulations at premium levels from solvent-borne commodity grades facing margin erosion in enforcement zones. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with aerospace cleanroom specifications commanding the highest unit economics. Pricing pressure stems from raw material import exposure to US Gulf Coast petrochemical pricing volatility. Residential DIY segments exhibit the sharpest price sensitivity, while industrial facility managers prioritize total-cost-of-ownership over initial material outlay.
Supply Chain Analysis
US Gulf Coast petrochemical complex access underwrites Mexican epoxy resin supply, with bisphenol-A and epichlorohydrin feedstock drawing from Texas and Louisiana production hubs. Formulation capacity clusters in Nuevo León and Querétaro to minimize cross-border freight exposure, though finished goods distribution runs through dedicated contractor channels and manufacturer-direct service networks. Tariff volatility on USMCA-origin chemicals represents the dominant structural risk, compounded by single-source vulnerability for specialized aerospace-grade resins. Regional formulators compete on price through local blending of imported base resins, while multinationals maintain captive supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement authority consolidation among foreign-owned manufacturing campuses is shifting buyer power toward facility managers demanding bundled specification-installation-warranty contracts, fragmenting traditional contractor bidding structures.
For Market Incumbents: Consolidate technical service infrastructure in the Bajío corridor to defend specification-grade positioning against regional price competitors. Backward integration into captive resin blending in Monterrey or Querétaro mitigates US Gulf Coast feedstock tariff exposure. COFEPRIS antimicrobial certification partnerships filter qualified installation capacity for healthcare segments, creating defensive moats. For New Entrants and Emerging Players: Moisture vapor transmission expertise gaps in the Yucatán Peninsula present first-mover opportunity for applicators establishing slab assessment capabilities ahead of aerospace supplier clustering. Target rapid-cure cementitious overlay segments where 24-hour return-to-service compresses contractor scheduling and displaces traditional epoxy quotations. Go-to-market through direct facility manager relationships bypasses entrenched distributor channels. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional formulators lacking SEMARNAT compliance documentation and cleanroom specification authority. Long-term viability hinges on regulatory enforcement trajectory and nearshoring momentum durability. Watch NOM standard amendment timing as inflection indicator for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epoxy Resin Production | Captive bisphenol-A supply from US Gulf Coast partners insulates margin structures from tariff volatility. |
| COFEPRIS Antimicrobial Certification Investment | Silver-ion and copper-oxide embedded system validation opens hospital and pharmaceutical cleanroom specifications. |
| Yucatán Technical Service Infrastructure Buildout | Mérida and Progreso aerospace clustering creates first-mover advantage for slab assessment expertise deployment. |
| Multi-Year Facility Manager Service Contracts | Bundled procurement transfers performance risk from fragmented contractors to integrated system suppliers. |
| Water-Based Formulation Capacity Expansion | Nuevo León and Jalisco enforcement actions accelerate compliant system adoption in institutional channels. |
Study Parameters
Operator-level perspectives from plant engineers, facility maintenance directors, coating applicators, and procurement leads at automotive OEMs anchored the qualitative base for this study. Primary interviews triangulated with customs and trade data from Mexican customs authorities, SEMARNAT regulatory filings, and SEC 10-K disclosures from listed coating manufacturers. Secondary validation drew from industry association reports and regional construction permit databases. Bottom-up volume estimates across resin chemistry, application environment, and procurement authority converged with top-down market sizing from feedstock consumption patterns.
Sensitivity analysis tested forecast outputs against alternative scenarios for NOM-086-ECOL-1994 enforcement intensity and USMCA tariff regime stability across the projection horizon. Segmentation dimensions modeled include resin chemistry tier, application environment, formulation compliance grade, and end-user procurement authority. CAGRs derived from regression analysis of historical consumption patterns against industrial construction permits and foreign direct investment flows. Aerospace supplier clustering timelines and automotive cleanroom buildout schedules served as industry-specific demand inputs.
Forecasts assume regulatory continuity in SEMARNAT emissions frameworks and USMCA origin rules; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as state-level air-quality program expansions and nearshoring momentum evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Textile Coatings Market
Coatings
Italy Automotive OEM Coatings Market
Coatings
Europe Anti-Friction Coatings Market
Coatings
Global Performance Coating Market
Coatings
North America Powder Coatings Market
Coatings
Wood Sealer Market
Coatings
South Africa Protective Coatings Market
Coatings
Hydrophilic Interior Glass Defogging Coatings Market
Coatings
Global Anti Slip Coatings Market
Coatings
Anti-Microbial Coatings Market
Coatings
Global Battery Coating Market
Coatings
Packaging Coatings Market
Coatings
Global Low Temperature Powder Coatings Market
Coatings
Stain Resistance Coatings Market
Coatings
Global Plastic Coatings Market
Coatings
Spain Automotive OEM Coatings Market