
 Aluminum Potassium Sulfate Market | 2026-2036
Aluminum Potassium Sulfate Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Potassium Sulfate Market Outlook
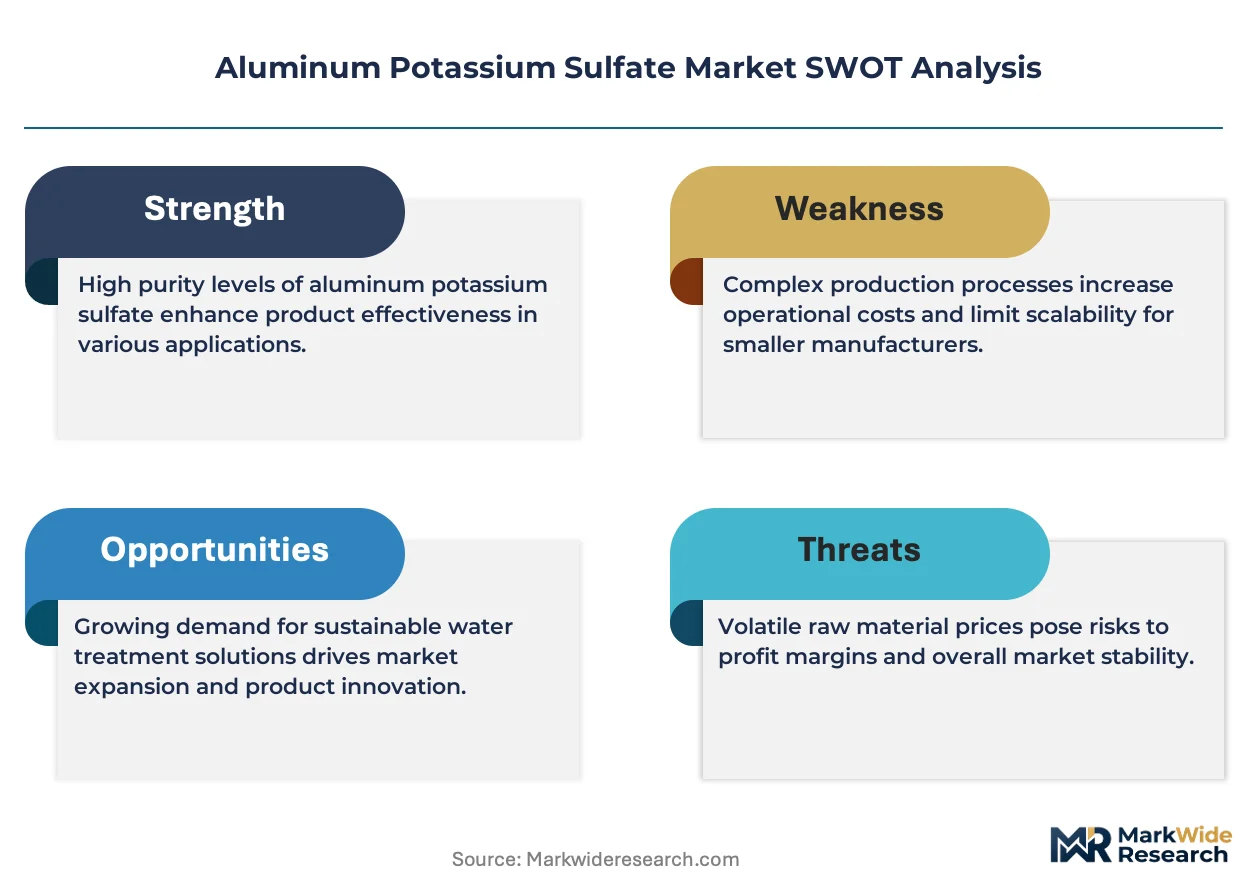
A shortage of qualified chemical process engineers is redrawing competitive boundaries among alum manufacturers. American Elements leverages its vertically integrated rare earth and specialty chemical platform to control raw material sourcing for high-purity aluminum potassium sulfate. Merck KGaA sustains pharmaceutical-grade production standards that command premium positioning in analytical reagent segments. Wenzhou Alum Mine anchors regional supply through its captive bauxite-to-alum conversion infrastructure in Zhejiang Province.
Aluminum potassium sulfate, commonly known as potash alum or KAl(SO4)2·12H2O, is a double salt synthesized through neutralization of aluminum sulfate with potassium sulfate, typically crystallized to achieve technical or food-grade purity specifications. The compound functions primarily as a flocculating agent, pH stabilizer, and astringent across municipal water treatment, food processing, and cosmetic formulations. Powder and granule product types dominate volume flows into water treatment applications where dosing precision and dissolution rates determine procurement decisions. Crystal grades command margin premiums in cosmetics and specialty food applications where visual clarity and low heavy-metal content are specified by beauty brands and food manufacturers.
EPA drinking water standards and FDA food additive regulations in the United States establish maximum contaminant levels and purity thresholds that shape product certification requirements for domestic suppliers. REACH registration obligations and the EU F-Gas Regulation's indirect pressure on chemical process efficiency are tightening environmental compliance costs for European alum producers. Stakeholders must monitor evolving PFAS contamination testing protocols and their potential to alter coagulant selection criteria in municipal procurement frameworks.
Market Dynamics
REACH registration obligations and the EU F-Gas Regulation are compressing margins for European alum producers while China's Shandong Province concentrates global supply. Municipal procurement frameworks are rewriting coagulant selection criteria around PFAS contamination testing protocols.
Growth Catalysts
- Emerging economy water infrastructure:Utilities in India and Brazil are expanding chemical coagulant procurement for municipal treatment plants. EPA drinking water standards are tightening maximum contaminant levels for aluminum residuals in finished water.
- EU Green Deal compliance:Purity specifications for industrial-grade alum products are tightening across European manufacturing. Food-grade crystal specifications are commanding margin premiums in cosmetic and specialty food applications.
- Process intensification:Continuous crystallization systems are reducing energy consumption in alum production. Captive bauxite-to-alum conversion infrastructure is anchoring regional supply security in Zhejiang Province.
Market Restraints
- Input cost volatility:Sulfuric acid and potassium sulfate prices fluctuate with energy markets and fertilizer demand cycles. Producers lack long-term hedging instruments for these commodity inputs.
- Supply concentration risk:China's chemical manufacturing belt around Shandong Province controls disproportionate global alum capacity. Geopolitical friction or logistics disruption creates systemic vulnerability.
- Substitution threat:Polyaluminum chloride and ferric chloride are displacing aluminum potassium sulfate in some water treatment applications. These alternatives offer lower dosing requirements in high-turbidity source waters.
Strategic Opportunities
- Pharmaceutical-grade vertical:Analytical reagent segments command premium positioning through USP and ACS certification. Merck KGaA's production standards demonstrate viable margin architecture.
- PFAS remediation protocols:Evolving testing requirements for per- and polyfluoroalkyl substances are altering municipal procurement frameworks. Alum producers with verified low-fluoride content specifications can capture specification-driven demand.
- Cosmetic formulation growth:Beauty brands are specifying low heavy-metal content and visual clarity for crystal grades. Natural astringent positioning in clean-label personal care products opens formulation partnerships.
Industry Challenges
- Chemical process engineering scarcity:Qualified engineers capable of optimizing crystallization and neutralization processes are in short supply. American Elements leverages its vertically integrated rare earth and specialty chemical platform to secure talent.
- Certification timeline compression:FDA food additive regulations and EPA drinking water standards require multi-year validation cycles. New entrants face extended pathways to commercial procurement eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Potassium Sulfate Market |
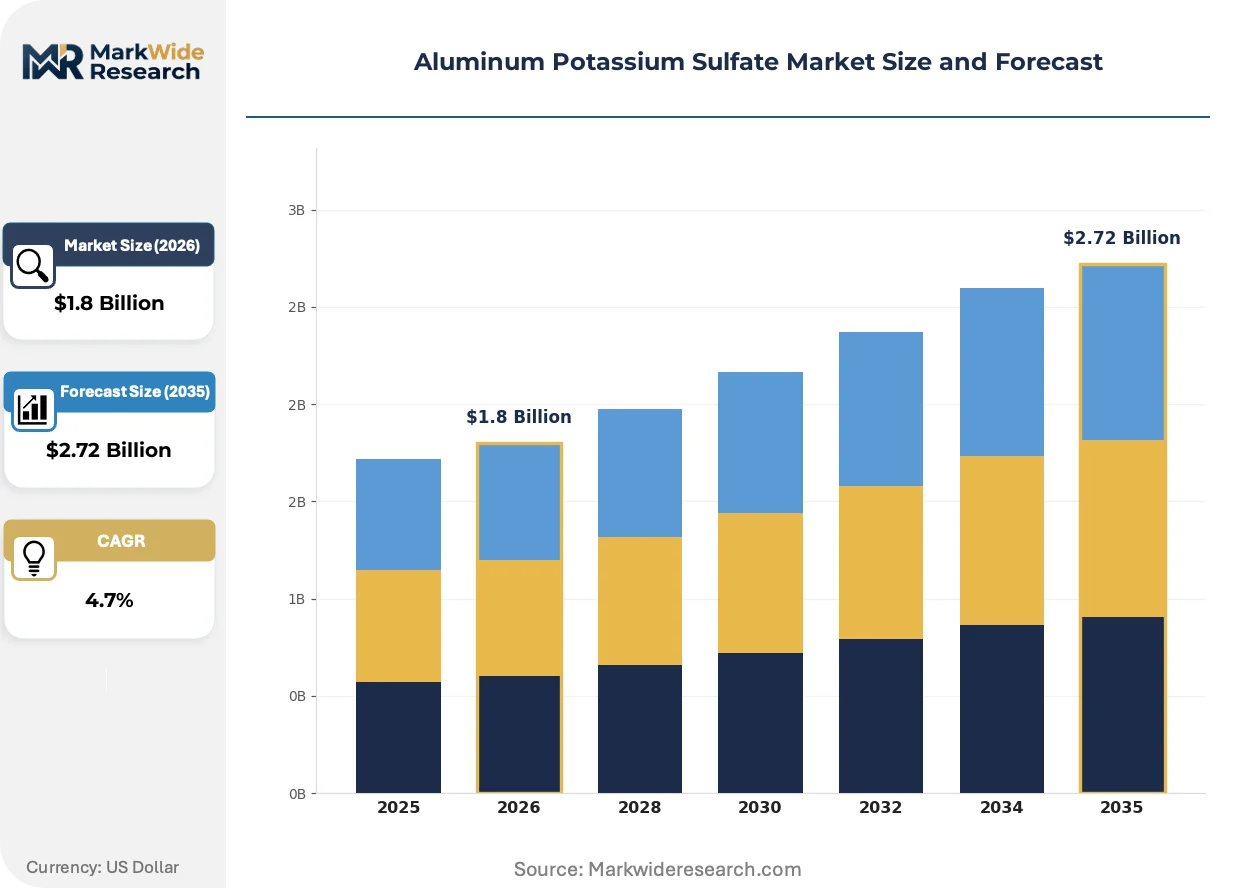
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Powder, Crystals, Liquid Application: Water Treatment, Food Industry, Agriculture, Cosmetics End User: Municipalities, Food Manufacturers, Farmers, Beauty Brands Distribution Channel: Direct Sales, Online Retailers, Distributors, Wholesalers |
| Companies Covered | Holland Company, Aamar Narain, American Elements, Merck KGaA, Sigma-Aldrich Co. LLC, Wenzhou Alum Mine, Zibo Honggui Donghua, Thermo Fisher Scientific, Oker-Chemie, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Potassium Sulfate Market Strategic Shifts
Continuous processing technologies are supplanting batch crystallization in alum manufacturing while regulatory testing protocols rewrite municipal procurement criteria. These shifts are compressing legacy cost structures and opening specification-driven premium tiers.
Membrane-assisted crystallization is supplanting conventional evaporative cooling in high-purity alum production. Municipal water treatment utilities in Germany and Japan are piloting these systems for consistent crystal size distribution. The technology is supplanting energy-intensive thermal processes and enabling real-time quality monitoring that reduces off-spec batches.
REACH registration obligations are tightening environmental compliance costs for European alum producers. ECHA's expanded substance evaluation program is requiring additional toxicological data packages for aluminum compounds. Pharmaceutical-grade and food-grade segments are absorbing these costs through premium pricing while technical-grade suppliers face margin compression.
Specification-driven procurement is consolidating buyer decision criteria around certified low-fluoride and low-iron content grades. Large municipal utilities in California and Texas are unbundling chemical supply from technical service contracts. This behavioral shift is most visible in US Southwest water districts where drought-driven source water quality variability demands precise coagulant performance guarantees.
Aluminum Potassium Sulfate Market Segmentation
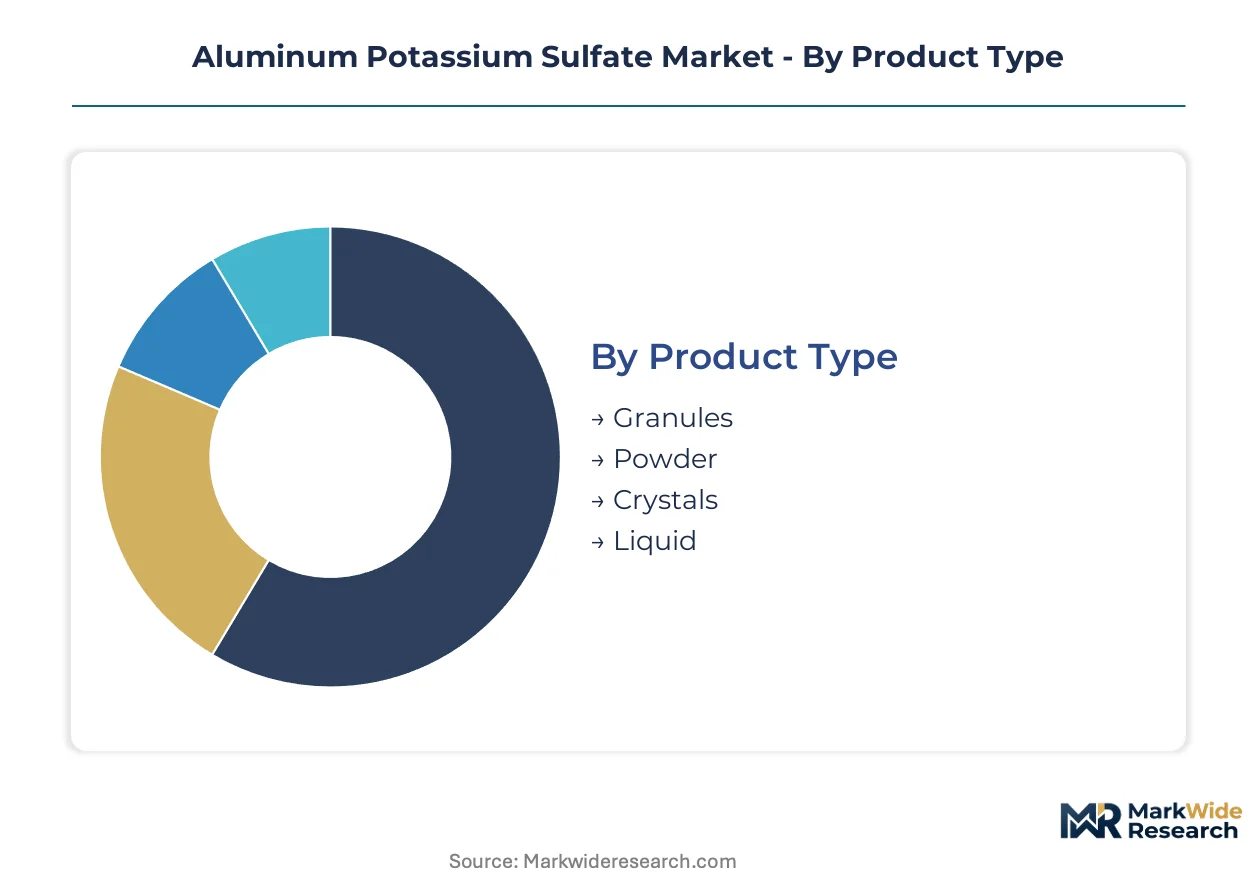
Aluminum potassium sulfate procurement patterns diverge sharply across physical forms and customer types. Specification requirements from EPA drinking water standards and FDA food additive regulations create tiered margin pools that reward purity certification over commodity volume.
Product Type:
Premium margins concentrate in crystal grades where visual clarity and heavy-metal thresholds command price multiples over technical grades.
- Crystals:Transparent, geometrically regular formations with low iron and fluoride content specifications. Beauty brands in Japan and Germany specify these grades for astringent formulations where visual purity supports clean-label positioning.
- Powder:Finely milled particulate with controlled particle size distribution for rapid dissolution. Municipal utilities in Texas and California prioritize powder grades for automated dosing systems managing variable source water turbidity.
- Granules:Intermediate particle size offering handling stability and metered dissolution for agricultural and industrial applications.
- Liquid:Pre-dissolved solutions eliminating on-site preparation steps for small-scale water treatment operations.
The dominant share belongs to Powder, while Crystals is closing the gap fastest.
Application:
End-use economics split between regulated infrastructure spending and discretionary consumer formulation budgets.
- Water Treatment:Municipal coagulant procurement governed by EPA maximum contaminant levels for aluminum residuals. Utilities in India and Brazil are expanding chemical procurement for new treatment capacity.
- Cosmetics:Natural astringent positioning in clean-label personal care drives specification for low heavy-metal crystal grades. Formulators in France and South Korea specify certified cosmetic-grade alum for toner and aftershave products.
- Food Industry:Firming agent applications in pickling and baking subject to FDA food additive regulations and purity thresholds.
- Agriculture:Soil amendment and fertilizer applications competing with commodity sulfate inputs on cost per unit sulfur.
Water Treatment retains the largest volume position, though Cosmetics is gaining share fastest on premium pricing.
End User:
Customer concentration and procurement sophistication determine contract structures and technical service bundling.
- Municipalities:Large water utilities unbundling chemical supply from technical service contracts in US Southwest districts. Drought-driven source water variability demands precise performance guarantees and certified low-fluoride specifications.
- Beauty Brands:Clean-label positioning requirements in Japan and Germany specifying visual clarity and heavy-metal testing documentation.
- Food Manufacturers:Multi-year FDA validation cycles for food additive applications creating extended commercial pathways for new suppliers.
- Farmers:Price-sensitive procurement comparing alum against polyaluminum chloride and ferric chloride alternatives for soil conditioning.
Municipalities account for the dominant procurement volume, while Beauty Brands is expanding most quickly on specification premiums.
Distribution Channel:
Channel economics reflect customer scale, geographic concentration, and technical support requirements.
- Distributors:Regional chemical distributors aggregating demand from smaller municipal utilities and industrial users across fragmented geographies. Inventory pooling reduces logistics costs for mid-volume customers.
- Direct Sales:Producer-to-utility contracts for large municipal accounts with dedicated technical service requirements and annual volume commitments.
- Online Retailers:Small-package fulfillment for cosmetic formulators, artisan food producers, and agricultural users with intermittent demand patterns.
- Wholesalers:Bulk commodity movement for agricultural and technical-grade applications with standardized specifications.
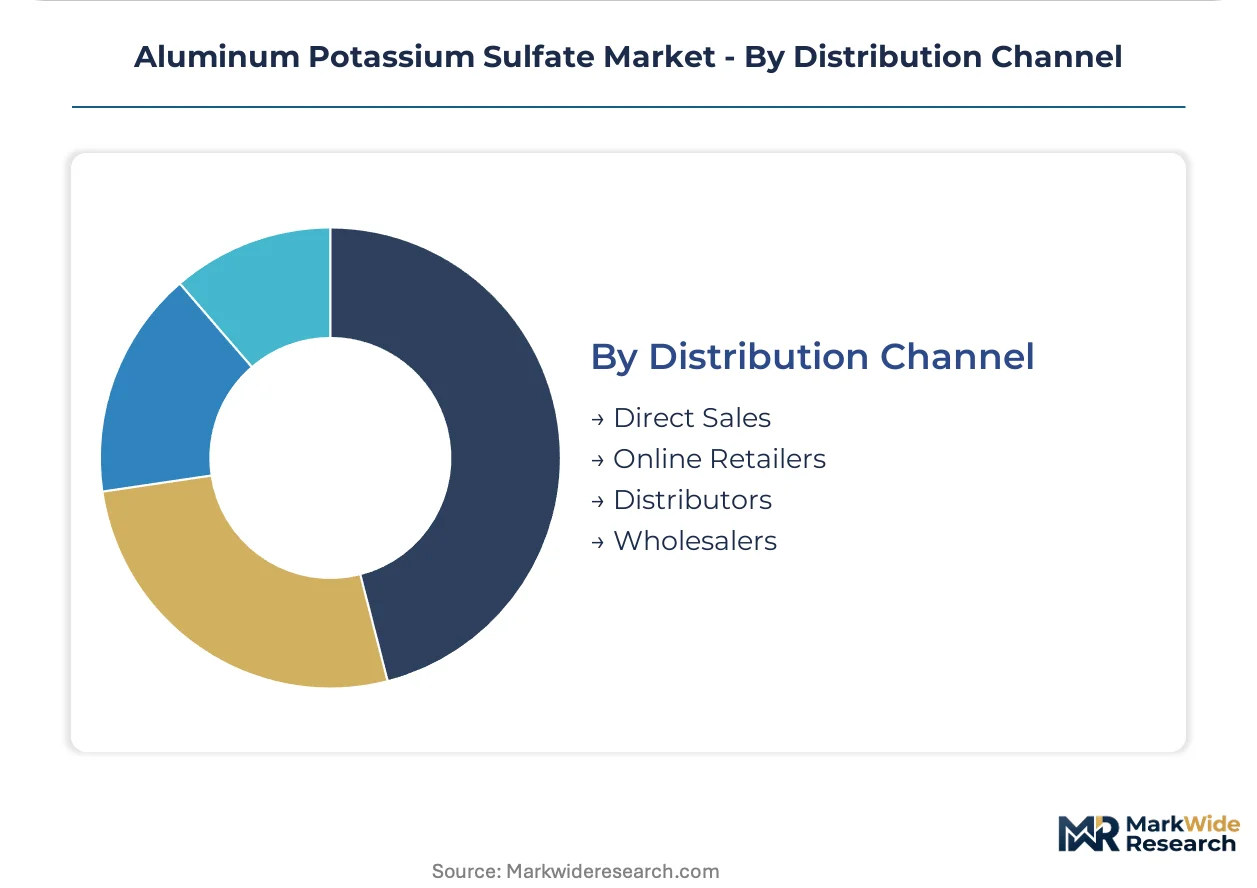
Distributors hold the dominant channel position, while Direct Sales is climbing the fastest on unbundling trends in large utility procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Ministry of Ecology and Environment (MEE) anchors regulatory oversight for the world's largest alum production base, while REACH obligations reshape European competitive economics and EPA standards drive specification premiums in North American procurement.
China
Shandong Province concentrates captive bauxite-to-alum conversion infrastructure serving water treatment and industrial chemical demand. MEE enforcement of dual carbon goals is tightening energy efficiency standards for crystallization processes. Zibo and surrounding cities host integrated manufacturing clusters where producers optimize sulfuric acid logistics against fertilizer market cycles.
United States
Texas and California municipal utilities unbundle chemical supply from technical service contracts amid drought-driven source water variability. EPA maximum contaminant levels for aluminum residuals in finished water tighten procurement specifications. Southwest water districts specify certified low-fluoride grades for automated dosing systems managing turbidity fluctuations.
Germany
ECHA's expanded substance evaluation program requires additional toxicological data packages for aluminum compounds under REACH. Membrane-assisted crystallization pilots in municipal utilities supplant energy-intensive thermal processes. Industrial clusters in North Rhine-Westphalia optimize continuous processing technologies for consistent crystal size distribution.
India
Utilities in Maharashtra and Gujarat expand chemical coagulant procurement for new municipal treatment capacity. BIS standards for drinking water chemicals create certification pathways for domestic suppliers. Chemical manufacturing investment in Gujarat's Special Economic Zones targets import substitution for water treatment grades.
Brazil
SABESP and state water utilities in São Paulo increase alum procurement for expanded treatment infrastructure. ANVISA pharmaceutical-grade standards create premium positioning for analytical reagent segments. Industrial chemical distributors in São Paulo state aggregate demand from fragmented municipal accounts across the Southeast region.
Aluminum Potassium Sulfate Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with high-purity specialists commanding specification premiums against scale-driven commodity producers. The vendor base organizes around three strategic tiers: vertically integrated rare earth platforms, pharmaceutical-grade certification holders, and captive bauxite-to-alum converters. Consolidation pressure concentrates in technical-grade segments where energy costs and input volatility compress margins. Competitive moves center on backward integration into sulfuric acid supply and continuous crystallization technology licensing.
Among specialty chemical platforms, American Elements and Merck KGaA exemplify divergent premium-tier strategies. Wenzhou Alum Mine anchors regional supply security through Zhejiang Province infrastructure. Sigma-Aldrich Co. LLC and Thermo Fisher Scientific occupy positions in analytical reagent distribution. Holland Company and Oker-Chemie represent European formulation specialists navigating REACH compliance costs.
| Leading Market Players |
|---|
| Holland Company |
| Aamar Narain |
| American Elements |
| Merck KGaA |
| Sigma-Aldrich Co. LLC |
| Wenzhou Alum Mine |
| Zibo Honggui Donghua |
| Thermo Fisher Scientific |
| Oker-Chemie |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day inventory cycles at Shandong Province producers concentrate pricing power with captive bauxite converters while forcing spot-market buyers into premium positions during sulfuric acid price spikes. This lead-time asymmetry between integrated and non-integrated supply chains directly shapes margin capture across technical and pharmaceutical-grade tiers.
Pricing Analysis
Price spreads between Zhejiang Province crystal grades and European REACH-compliant technical grades exceed threefold multiples, with certification-driven premiums separating pharmaceutical-grade holders from commodity producers. Cost compression in technical-grade segments intensifies as Shandong's energy-efficient crystallization capacity expands, while drought-driven procurement in Texas and California utilities creates spot-price volatility for certified low-fluoride specifications. Municipal buyers exhibit highest price sensitivity through unbundled chemical supply contracts, whereas Japanese and German cosmetic formulators absorb premiums for visual clarity documentation.
Supply Chain Analysis
Strategic stockpiling of potassium sulfate dominates producer behavior during fertilizer demand cycles, contrasting with just-in-time sulfuric acid procurement that exposes margin volatility. Supply concentrates in China, India, and Germany, with raw material dependencies on bauxite ore, sulfuric acid, and potassium sulfate feedstocks. Single-source vulnerability runs through Shandong Province's crystallization capacity concentration. Distribution runs through regional chemical distributors aggregating fragmented municipal demand, supplemented by direct sales for large utility accounts with technical service requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive boundaries as continuous crystallization technology licensing creates interoperability standards that favor early movers with captive process engineering talent.
For Market Incumbents: Secure backward integration into sulfuric acid supply chains to buffer against fertilizer market cyclicality, while locking pharmaceutical-grade certification pathways through USP and ACS validation investments. Polyaluminum chloride substitution in high-turbidity water treatment demands defensive specification engineering for low-fluoride grades. For New Entrants and Emerging Players: Differentiate on membrane-assisted crystallization technology licensing to German and Japanese municipal utilities piloting energy-efficient production systems. Cosmetic-grade crystal supply to South Korean and French beauty brands offers the most penetrable white-space target, with clean-label astringent positioning as the viable go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a specialty-chemical consolidation play because margin compression in technical-grade segments will force distressed asset availability while pharmaceutical-grade certification holders sustain pricing power. Watch for ECHA substance evaluation program expansions altering REACH compliance cost structures as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulfuric Acid | Captive acid supply buffers Shandong producers against fertilizer demand cyclicality and energy price spikes. |
| Continuous Crystallization Technology Licensing | Membrane-assisted systems enable German utilities to reduce thermal energy consumption while tightening crystal size consistency. |
| Pharmaceutical-Grade Certification Investment | USP and ACS validation opens analytical reagent segments where Merck KGaA demonstrates sustainable margin architecture. |
| Cosmetic-Grade Supply Partnerships | Low heavy-metal crystal specifications align with Japanese beauty brand clean-label positioning requirements. |
| Long-term Municipal Supply Agreements | Direct contracts with Texas and California utilities secure volume commitments amid unbundling of technical service bundling. |
Study Parameters
Desk research of customs trade data, SEC chemical company filings, and ECHA REACH registration databases preceded structured interviews with alum plant managers, municipal water utility procurement leads, cosmetic formulator R&D directors, and regional chemical distribution channel partners. Primary fieldwork validated production capacity estimates and crystallization technology adoption timelines, with bottom-up volume triangulation against top-down trade flow analysis ensuring cross-verification of Shandong Province supply concentration metrics.
Variance decomposition across grade tier, end-use application, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segment-level volume build-ups incorporating EPA maximum contaminant level enforcement trajectories and EU Green Deal purity specification tightening. Industry-specific inputs included sulfuric acid price elasticity coefficients and potassium sulfate fertilizer demand correlation factors.
The analysis sits within stated boundaries; outcomes outside sustained REACH compliance cost absorption or PFAS testing protocol adoption would require recalibration. Forecasts reflect assumptions around continuous crystallization technology diffusion rates and municipal procurement unbundling momentum. Revision becomes warranted when polyaluminum chloride substitution rates in high-turbidity applications cross thresholds altering coagulant selection criteria.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Sulfur Palletized Plant and Granulator Market
Bulk Chemicals
India Carbon Black Market
Bulk Chemicals
Ammonium Molybdate Market
Bulk Chemicals
Diisopropylbenzene Market
Bulk Chemicals
Asia-Pacific Bitumen Market
Bulk Chemicals
Iodine Market
Bulk Chemicals
DL-Methionine Market
Bulk Chemicals
White Charcoal Powder Market
Bulk Chemicals
Global Fermentation Chemicals Market
Bulk Chemicals
Sodium Hydroxide Market
Bulk Chemicals
Asia-Pacific Formaldehyde Market
Bulk Chemicals
Acetate Salt Market
Bulk Chemicals
Sodium Molybdate Market
Bulk Chemicals
Gluconic Acid Market
Bulk Chemicals
Glucaric Acid Market
Bulk Chemicals
Europe Quicklime Market