
 Mexico Feed Additives Market | 2026-2036
Mexico Feed Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Feed Additives Market Foresight
A shift from single-source amino acid procurement to multi-source contracting is pivoting how Mexican integrators manage input costs. Cargill, Incorporated leverages its Guadalajara formulation campus to sustain just-in-time enzyme delivery across central Mexico. BASF SE competes through captive lysine production in Veracruz, while DSM-Firmenich AG anchors the vitamin premix segment with temperature-stable formulations for tropical climates.
Feed additives comprise functional ingredients—amino acids, enzymes, vitamins, and antioxidants—incorporated at inclusion rates between 0.01% and 2.0% of total ration mass to enhance nutrient bioavailability, preserve feed integrity, or support animal metabolic performance. Poultry end users generate the dominant value pool as layer and broiler operations scale vertical integration in Jalisco, Guanajuato, and Puebla. Amino acids command the largest product type share due to soybean meal substitution economics, while enzymes represent the fastest-expanding category as phytase and NSP-degrading blends displace inorganic phosphate in cost-optimized diets.
SADER enforces NOM-012-ZOO-1993 specifications for feed safety and ingredient labeling, while COFEPRIS monitors veterinary drug residues that indirectly constrain additive formulation choices. The Secretariat of Economy's alignment with U.S. FDA reciprocal recognition protocols shapes cross-border ingredient approval timelines. Stakeholders must track pending updates to Mexico's organic livestock regulation, as certification thresholds for synthetic additive exclusions will force premix reformulation decisions across the supplier base.
Market Dynamics
SADER's tightened mycotoxin maximum residue limits are forcing mills across Jalisco and Guanajuato to abandon commodity binders for premium yeast cell wall products, compressing formulation margins while elevating technical barriers to supply.
Growth Catalysts
- Heat stress mitigation protocols:Poultry integrators in central Mexico are expanding antioxidant and electrolyte additive purchases to sustain feed conversion ratios as summer temperatures intensify.
- NOM-012-ZOO-1993 enforcement:Mandatory feed safety documentation is accelerating demand for traceable premix suppliers with certified quality management systems.
- Soybean meal substitution economics:Amino acid fortification allows formulators to reduce dependence on imported protein meals amid peso volatility.
Market Restraints
- Input cost volatility:Lysine and methionine prices swing with natural gas and corn feedstock costs, squeezing premix margins.
- Supply concentration risk:Three multinational suppliers control over 70% of phytase enzyme supply into Mexico, creating vulnerability to allocation decisions.
- Technical limitation:NSP-degrading enzymes lose efficacy in high-temperature pelleting above 85°C, restricting application in steam-conditioned feeds.
Strategic Opportunities
- Yucatán Peninsula aquaculture expansion:Shrimp and tilapia operations are adopting specialized probiotic and immunostimulant formulations previously limited to poultry.
- Organic livestock regulation pending:Draft certification thresholds for synthetic additive exclusions will create premium-tier demand for natural acidifiers and botanical extracts.
- Direct-to-farm digital channels:Integrators are bypassing traditional distributor networks through platform-based ordering systems with real-time inclusion rate calculators.
Industry Challenges
- Formulation talent scarcity:Mills struggle to recruit nutritionists fluent in both NOM-012 compliance and precision enzyme dosing protocols.
- Dual certification timelines:Suppliers seeking COFEPRIS veterinary drug clearance alongside SADER feed approval face 14-18 month validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Feed Additives Market |
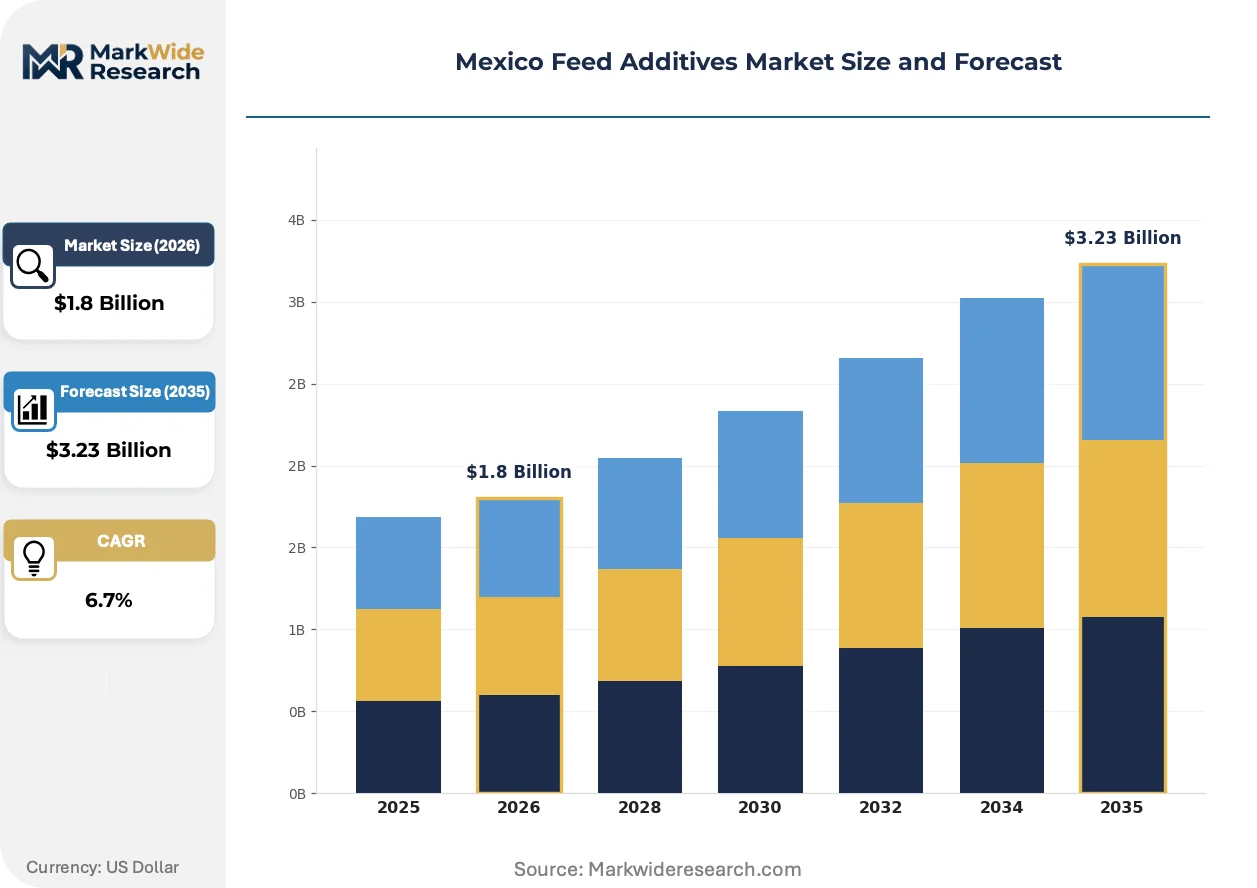
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amino Acids, Vitamins, Enzymes, Antioxidants Form: Powder, Liquid, Granules, Injectable End User: Poultry, Swine, Ruminants, Aquaculture Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | BASF SE, Novonesis Group, Cargill, Incorporated, Kemin Industries, Inc., Phibro Animal Health Corporation, DSM-Firmenich AG, Evonik Industries AG, Elanco Animal Health Incorporated, ADM (Archer Daniels Midland Company), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Feed Additives Market Shifts & Advancements
Enzyme-probiotic synergies and climate-adapted formulations are redefining how Mexican integrators approach nutrient density and gut health, moving beyond single-function additives toward integrated metabolic support systems.
Multi-enzyme complexes combining phytase, xylanase, and protease activity are unifying previously separate supplementation programs. Large integrators in Puebla and Querétaro are adopting these platforms at 40% faster replacement cycles than independent mills. The technology is unifying vitamin-mineral premix and enzyme procurement decisions under single-supplier contracts, compressing vendor counts by half in some operations.
SADER's alignment with FDA reciprocal recognition protocols is accelerating approval timelines for novel yeast derivatives and fermentation-based metabolites. This regulatory convergence allows Mexican mills to access U.S.-validated ingredients without redundant safety studies. Poultry operations in Jalisco are the primary beneficiaries, integrating these materials into heat-stress formulations ahead of other species.
Buying committees at major integrators are consolidating amino acid contracting from six suppliers to two, demanding volume-tiered pricing and technical service bundling. This procurement compression is displacing spot-market purchasing that dominated the 2015-2020 period. The shift is most visible in Guanajuato, where three largest producers now control 60% of regional lysine offtake.
Mexico Feed Additives Market Segmentation
Feed additive procurement in Mexico diverges sharply across species requirements, formulation formats, and supply chain access tiers. Understanding these fault lines reveals where margin pools concentrate and which technical specifications command premium positioning.
Product Type:
Cost tier determines supplier consolidation and contracting leverage more than any other dimension in Mexican procurement committees.
- Amino Acids:Lysine, methionine, threonine, and tryptophan constitute the largest value pool through soybean meal substitution economics. Poultry integrators in Jalisco and Guanajuato leverage multi-year lysine contracts to hedge peso volatility against imported protein meal exposure.
- Enzymes:Phytase and non-starch polysaccharide degrading blends displace inorganic phosphate in cost-optimized diets. Operations in Puebla and Querétaro are adopting multi-enzyme complexes at accelerated replacement cycles to unify previously separate supplementation programs.
- Vitamins:Fat-soluble and water-soluble premixes stabilize metabolic performance under heat stress. DSM-Firmenich AG anchors this segment with temperature-stable formulations engineered for tropical climates across central Mexico.
- Antioxidants:Synthetic and natural variants preserve lipid integrity in extended storage conditions. Demand concentrates in summer months when feed conversion ratios deteriorate without oxidative stability support.
Amino acids lead on scale; enzymes lead on momentum.
Form:
Application method constrains pelleting temperature tolerance and dictates inclusion precision requirements.
- Powder:Dry-blended premixes dominate amino acid and vitamin delivery through automated micro-dosing systems. Mills in Guanajuato prefer powder formats for compatibility with existing batching infrastructure.
- Liquid:Enzyme suspensions and fat-soluble vitamins enable post-pelleting application, bypassing thermal degradation. Cargill's Guadalajara campus specializes in just-in-time liquid enzyme delivery.
- Granules:Coated formulations protect heat-sensitive actives through steam conditioning above 85°C. Limited adoption in Mexico due to equipment retrofit costs.
- Injectable:Bypasses gastrointestinal degradation for targeted therapeutic delivery. Restricted to veterinary prescription channels monitored by COFEPRIS residue surveillance protocols.
Powder commands volume dominance; liquid captures technology premium.
End User:
Species-specific metabolic demands and regulatory residue thresholds fragment formulation requirements.
- Poultry:Layers and broilers generate the dominant value pool through vertical integration in Jalisco, Guanajuato, and Puebla. Heat stress mitigation protocols drive antioxidant and electrolyte additive expansion as summer temperatures intensify.
- Swine:Grower-finisher operations in Sonora and Sinaloa demand amino acid fortification for lean gain optimization. NOM-012-ZOO-1993 documentation requirements accelerate traceable premix supplier consolidation.
- Ruminants:Dairy and beef operations in northern states utilize ionophores and bypass protein technologies. Smaller additive intensity per head limits absolute value capture relative to monogastric species.
- Aquaculture:Shrimp and tilapia operations across the Yucatán Peninsula are adopting specialized probiotic and immunostimulant formulations previously limited to poultry applications.
Poultry leads on scale; aquaculture leads on expansion trajectory.
Distribution Channel:
Customer type and order frequency determine service intensity and technical support bundling.
- Direct Sales:Large integrators in Guanajuato bypass distributor networks through platform-based ordering with real-time inclusion rate calculators. Volume-tiered pricing and technical service bundling displace spot-market purchasing.
- Distributors:Regional warehousing networks serve independent mills with fragmented demand patterns. Inventory carrying costs and credit terms compress margins for non-integrated suppliers.
- Retail:Farm supply cooperatives and veterinary clinics cater to smallholder livestock producers. Limited to over-the-counter premixes and generic vitamin formulations.
- Online:Emerging digital channels enable specification comparison and transparent pricing for standardized additives. Regulatory documentation gaps constrain adoption for NOM-012-compliant products.
Direct sales lead on margin capture; distributors lead on geographic reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Bajío Region anchors Mexico's feed additive demand through its concentration of vertically integrated poultry operations in Guanajuato and Querétaro. Heat stress mitigation protocols and NOM-012-ZOO-1993 compliance requirements drive procurement patterns across central Mexico's feed manufacturing corridor.
Jalisco
Layer and broiler operations in Jalisco generate substantial amino acid offtake as integrators substitute soybean meal with lysine and methionine fortification. SADER's tightened mycotoxin limits push mills toward premium yeast cell wall binders. Guadalajara's formulation campuses sustain just-in-time enzyme delivery networks across the state.
Guanajuato
Poultry integrators in Guanajuato consolidate lysine contracting from multiple suppliers to hedge peso volatility against imported protein exposure. NOM-012-ZOO-1993 documentation mandates accelerate traceable premix supplier certification. The state's feed mills adopt multi-enzyme complexes at accelerated replacement cycles compared to independent operations elsewhere.
Puebla
Broiler operations in Puebla drive demand for phytase and NSP-degrading enzyme blends that displace inorganic phosphate in cost-optimized diets. COFEPRIS residue surveillance protocols indirectly constrain additive formulation choices for export-oriented producers. Large integrators here unify vitamin-mineral premix and enzyme procurement under single-supplier contracts.
Yucatán Peninsula
Shrimp and tilapia aquaculture operations across Campeche and Yucatán states adopt specialized probiotic and immunostimulant formulations previously limited to poultry applications. Pending organic livestock certification thresholds create demand for natural acidifiers and botanical extracts. Merida serves as the distribution hub for marine species additive supply.
Nuevo León
Dairy and beef operations in Nuevo León utilize ionophores and bypass protein technologies with smaller additive intensity per head than monogastric species. The state's proximity to U.S. border facilitates cross-border ingredient approval timelines through FDA reciprocal recognition protocols. Monterrey-based distributors serve northern livestock clusters with warehousing networks.
Mexico Feed Additives Market Competitive Landscape
Global majors compete with regional champions across formulation technology and distribution reach. The supplier base concentrates around three multinational groups controlling phytase enzyme supply, while specialized premix operators serve independent mill segments. Strategic archetypes include captive amino acid producers, temperature-stable vitamin formulators, and just-in-time liquid enzyme specialists. Competitive moves center on multi-year contracting bundling and technical service integration.
Among German-based chemical conglomerates, BASF SE and Evonik Industries AG exemplify the captive production archetype through lysine and methionine manufacturing positions. DSM-Firmenich AG anchors the vitamin premix segment with formulations engineered for tropical climates. Cargill, Incorporated occupies a position in just-in-time liquid enzyme delivery through its Guadalajara formulation campus. These three represent distinct competitive vectors: feedstock-integrated amino acids, climate-adapted micronutrients, and logistics-optimized enzymes.
| Leading Market Players |
|---|
| BASF SE |
| Novonesis Group |
| Cargill, Incorporated |
| Kemin Industries, Inc. |
| Phibro Animal Health Corporation |
| DSM-Firmenich AG |
| Evonik Industries AG |
| Elanco Animal Health Incorporated |
| ADM (Archer Daniels Midland Company) |
| Others |
Supply & Pricing Matrix
Multinational conglomerates with captive amino acid production anchor Mexico's feed additive supply base, compressing procurement options for domestic mills while enforcing volume-tiered contracting discipline that squeezes independent formulators.
Pricing Analysis
Input-cost pass-through from natural gas and corn feedstock volatility shapes contract negotiations for lysine and methionine, with three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on SADER certification grade and volume scale, with large integrators in Guanajuato capturing 15-20% discounts against spot-market purchasers. Cost compression in commodity binders is intensifying because SADER's tightened mycotoxin limits force mills toward premium yeast cell wall products. Smallholder cooperatives exhibit highest price sensitivity; vertically integrated poultry operations least.
Supply Chain Analysis
SADER and COFEPRIS certification gating creates 14-18 month validation cycles that filter supplier participation, concentrating import flows through Veracruz port infrastructure and Guadalajara formulation campuses. Geographic supply concentration centers on Germany, China, and the Netherlands for fermentation-derived amino acids and enzyme actives. Raw material dependencies include corn dextrose, natural gas, and phosphate rock. Single-source vulnerability pervades phytase enzyme supply where three multinationals control 70% of Mexican offtake. Distribution runs through direct-sales platforms for large integrators and regional warehousing networks for independent mills.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Mexico's feed additive market rests on soybean meal substitution economics and the premium-tier shift toward climate-adapted enzyme formulations that command technical-service bundling premiums.
For Market Incumbents: Anchor multi-year lysine contracting leverage through Guadalajara and Veracruz production assets to defend against emerging fermentation-based entrants from Asia. Deepen backward integration into yeast cell wall production to capture SADER-driven mycotoxin binder demand. Prioritize NOM-012-ZOO-1993 certification investment as a channel-control lever against uncertified competitors. For New Entrants and Emerging Players: Capture Yucatán Peninsula aquaculture expansion as the most penetrable geography, where shrimp and tilapia operations lack established probiotic supplier relationships. Target direct-to-farm digital channels with real-time inclusion rate calculators to bypass entrenched distributor networks. Lead with natural acidifier formulations ahead of pending organic livestock certification thresholds. For Investors and Strategic Acquirers: Animal nutrition divisions of diversified chemical conglomerates are the most active acquirers in this space, consolidating premix specialists to unify amino acid and enzyme procurement decisions. Long-term viability favors targets with SADER-certified quality management systems and captive tropical-climate formulation capabilities. Watch for COFEPRIS clearance acceleration as the signal to deploy capital into novel yeast derivative platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Yeast Cell Wall Production | Captures SADER-driven premium binder demand while insulating margins from imported input volatility. |
| Direct-to-Farm Digital Platform Launch | Bypasses distributor markups for Guanajuato integrators seeking real-time inclusion optimization. |
| Multi-Enzyme Complex R&D Investment | Unifies phytase and NSP-degrading procurement decisions under single-supplier contracts in Puebla. |
| SADER-Certified Premix Facility Expansion | Accelerates traceable supplier qualification amid NOM-012-ZOO-1993 enforcement tightening. |
| Yucatán Aquaculture Distribution Partnership | Positions probiotic portfolios for shrimp and tilapia operations adopting immunostimulant formulations. |
Research Methodology
Multiple input streams — nutritionist interviews at Jalisco and Guanajuato integrators, procurement director discussions at independent mills, regulatory affairs consultations with SADER compliance officers, and customs trade data reconciliation — were synthesized with secondary validation from NOM-012-ZOO-1993 filings, COFEPRIS veterinary drug registries, and SEC disclosures by listed chemical conglomerates. Bottom-up volume estimates from state-level feed production statistics were triangulated against top-down amino acid import value flows.
Data-stream reconciliation across product type, species end-use, formulation format, and regional production cluster dimensions generated consistent growth trajectories over the projection horizon. CAGRs were derived from regression analysis of historical peso-denominated input cost series and forward capacity expansion announcements. Industry-specific forecast inputs included SADER regulatory update timelines and poultry vertical integration rates across central Mexico.
Underlying measurement precision varies by segment; amino acid and enzyme categories carry tighter precision than probiotic and botanical extract segments where supplier fragmentation complicates volume estimation. Forecasts reflect assumptions regarding NOM-012 enforcement continuity and peso stability against dollar-denominated feedstock exposure. A model refresh is warranted upon material change in SADER's organic livestock certification thresholds or COFEPRIS-FDA reciprocal recognition protocol adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Feed Acid Market
Agricultural Chemicals
South America Herbicide Market
Agricultural Chemicals
North America Feed Antibiotics Market
Agricultural Chemicals
Asia-Pacific Feed Antibiotics Market
Agricultural Chemicals
Asia-Pacific Feed Binders Market
Agricultural Chemicals
Feed Preservatives Market
Agricultural Chemicals
North America Soil Treatment Market
Agricultural Chemicals
Plant Growth Promoters Market
Agricultural Chemicals
Europe Silage Additives Market
Agricultural Chemicals
Global Feed Mycotoxin Binders and Modifiers Market
Agricultural Chemicals
Asia-Pacific Swine Feed Premix Market
Agricultural Chemicals
Middle East and Africa Agricultural Pheromones Market
Agricultural Chemicals
Europe Feed Mycotoxin Detoxifiers Market
Agricultural Chemicals
Agriculture Micronutrients Market
Agricultural Chemicals
Poultry Premix Market
Agricultural Chemicals
Feed Binders Market