
 Global Crop Oil Concentrates Market | 2026-2036
Global Crop Oil Concentrates Market Size, Share, and Industry Trends Forecast 2026-2036
Global Crop Oil Concentrates Market Foresight
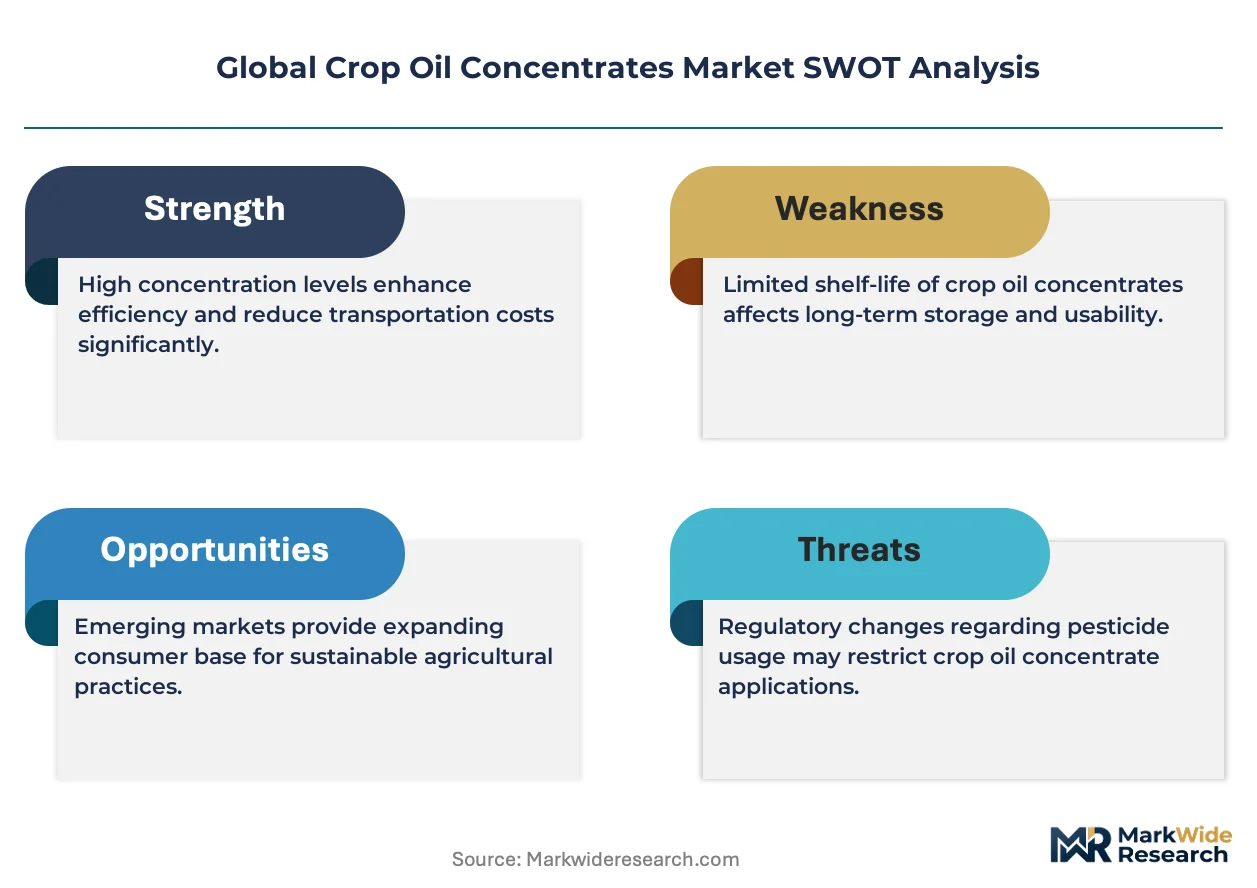
EPA biofuel blending mandates and FIFRA registration requirements are hardening the cost-of-entry calculus for new entrants. BASF SE leverages its integrated surfactant chemistry portfolio to sustain formulation leadership across emulsifiable concentrate grades. Croda International anchors its position through bio-based oil sourcing networks that navigate evolving renewable content thresholds. FMC Corporation competes through specialized distribution partnerships with agricultural retailers in North American row-crop regions.
Crop oil concentrates are petroleum-derived or vegetable-based oil formulations containing surfactant blends, typically at 80-97% oil content with 1-5% emulsifier loading, designed to enhance pesticide droplet retention and cuticular penetration on leaf surfaces. Emulsifiable concentrate formulations dominate volume flows due to compatibility breadth across tank-mix partners, while superior spray oil variants command margin pools in specialty fruit and vegetable applications where phytotoxicity thresholds tighten. Herbicide adjuvant applications lead demand structurally as glyphosate-resistant weed pressure escalates, and insecticide adjuvant use grows fastest among oilseed producers seeking to maximize pyrethroid efficacy at reduced active rates.
EPA registrations under FIFRA, REACH compliance for European export-bound formulations, and Brazil's ANVISA pesticide adjuvant notification requirements collectively shape product standard thresholds and market access corridors. ISO 17025 testing protocols for oil purity and emulsion stability increasingly filter supplier qualification decisions by multinational distributors. Stakeholders must monitor regulatory divergence between jurisdictions where oil-origin disclosure rules tighten versus regions where performance claims face stricter substantiation requirements.
Market Dynamics
Herbicide resistance pressure in soybean and corn systems is accelerating adjuvant specification intensity, forcing reformulation cycles that compress supplier response windows and concentrate procurement authority with multinational distributors.
Growth Catalysts
- EPA biofuel blending mandates:Renewable fuel standards in the United States are tightening vegetable oil feedstock specifications, pulling crop oil concentrate producers toward higher-purity emulsifier systems that qualify for renewable content credits.
- Glyphosate-resistant weed proliferation:Palmer amaranth and waterhemp infestations across the US Midwest and Brazil's Mato Grosso are compelling farmers to add oil concentrates to tank mixes, restoring herbicide efficacy on resistant biotypes.
- Precision application hardware:Drone-mounted sprayers and pulse-width modulation nozzles are demanding adjuvants with narrower droplet spectra, creating specification pull from equipment manufacturers.
Market Restraints
- Petroleum feedstock volatility:Paraffinic base oil prices track crude oil benchmarks, exposing formulators to margin compression when energy markets spike without corresponding pesticide price adjustments.
- REACH registration costs:European Union chemical compliance obligations impose six-figure dossier preparation expenses that screen smaller blenders from export markets, concentrating supply among integrated multinationals.
- Vegetable oil supply concentration:Soybean oil sourcing networks cluster in Argentina and Brazil crush facilities, creating geographic single-point vulnerability for bio-based concentrate producers.
Strategic Opportunities
- India's rice-wheat belt penetration:Basmati and wheat farmers in Punjab and Haryana remain underpenetrated for adjuvant use, presenting first-mover positioning as pesticide intensification accelerates.
- Drone application compatibility:Low-volume aerial spraying requires ultra-low phytotoxicity oil grades, opening premium formulation tiers for specialty surfactant chemistries.
- EU Green Deal bio-content thresholds:Renewable sourcing mandates for agricultural inputs are creating compliant product categories that command distributor preference in German and French markets.
Industry Challenges
- Emulsion stability testing capacity:ISO 17025 laboratory accreditation for cold-storage and hot-storage protocols requires capital investment that mid-tier blenders struggle to fund.
- Tank-mix compatibility verification:Pesticide registrants are narrowing approved adjuvant lists, forcing concentrate producers to maintain extensive compatibility databases across hundreds of active ingredients.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Crop Oil Concentrates Market |
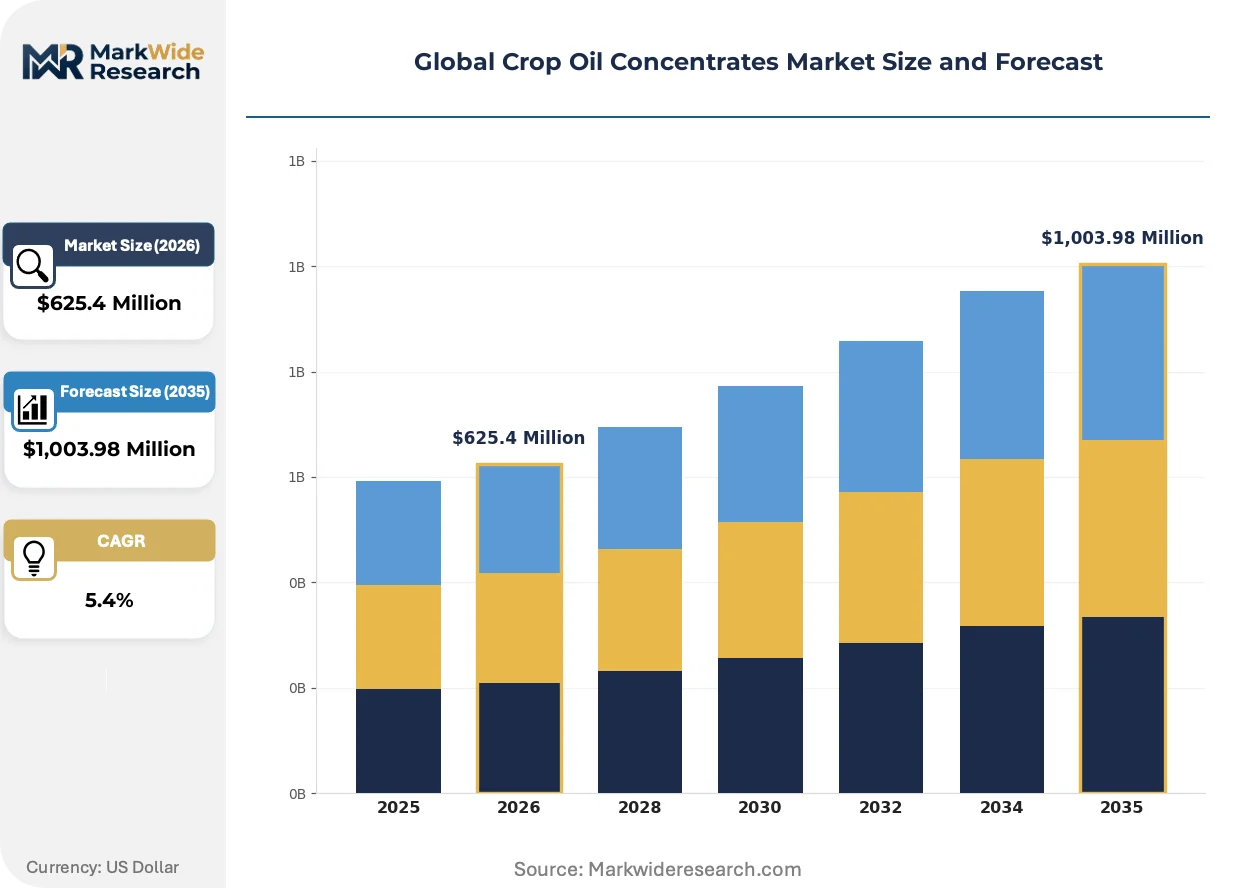
| Market Size in 2026 | $625.4 Million |
| Market Size in 2035 | $1,003.98 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsifiable Concentrate, Spray Oil, Superior Spray Oil, Crop Oil, Crop Oil Concentrate, Others Application: Fungicide Adjuvant, Herbicide Adjuvant, Insecticide Adjuvant, Fertilizer Adjuvant, Plant Growth Regulator Adjuvant End User: Corn Growers, Vegetable Farmers, Fruit Cultivators, Oilseed Producers, Legume Farmers Distribution Channel: Direct Sales, Agricultural Retailers, Online Marketplaces, Cooperative Societies, Wholesale Distributors |
| Companies Covered | BASF SE, Croda International, Wilbur-Ellis Company LLC, Corteva Agriscience, Clariant AG, FMC Corporation, Cargill, Evonik, Albaugh LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Crop Oil Concentrates Market Shifts & Advancements
Formulation chemistry is pivoting from petroleum-derived bases toward renewable feedstocks, while regulatory disclosure requirements and precision agriculture hardware are reshaping product specification hierarchies.
Methylated seed oil technology is converging with esterified vegetable oil platforms to create hybrid concentrates that combine petroleum-derived penetration enhancement with bio-based content qualifying for renewable fuel credits. Large-scale corn and soybean operations in Illinois and Iowa are specifying these blends for fall burndown applications. The convergence is compressing demand for pure petroleum-based grades while expanding the addressable market for dual-origin formulations.
REACH Article 33 disclosure obligations are forcing European-bound concentrate shipments to document full oil-origin chain of custody, including surfactant feedstock provenance. Formulators must now maintain segregated production lines for EU-compliant versus non-EU product streams. Specialty fruit and vegetable producers in Spain and Italy are shifting procurement toward suppliers with certified renewable content documentation.
Retailer agronomists at cooperative buying groups are displacing independent crop consultants as the primary adjuvant specification channel in North American row-crop regions. These agronomists bundle concentrate recommendations with pesticide and seed purchases, compressing standalone adjuvant brand loyalty. The pattern is most visible in Minnesota and the Dakotas, where regional cooperatives control majority input distribution.
Global Crop Oil Concentrates Market Segmentation
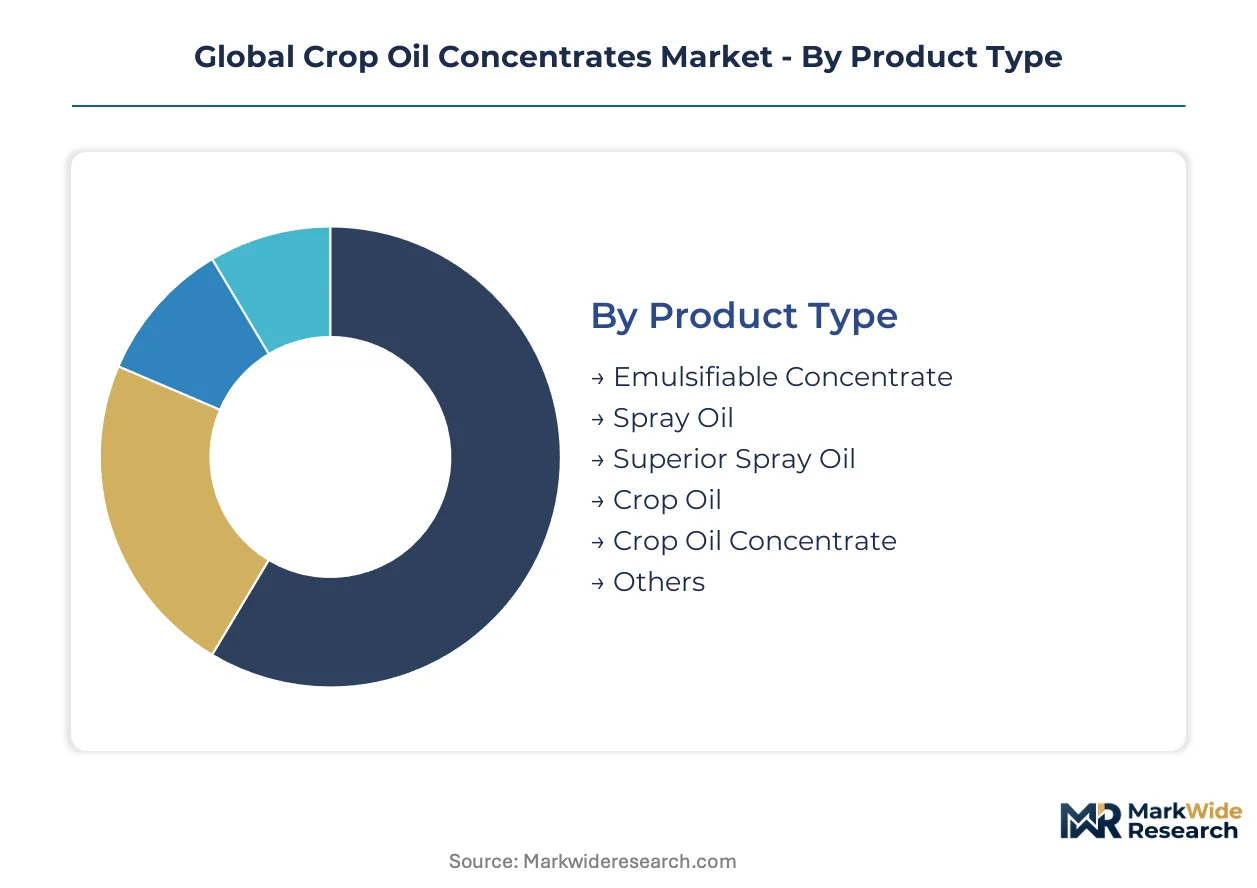
Crop oil concentrate specifications diverge sharply across application contexts, with formulation chemistry and distribution pathways determining margin capture and customer lock-in. Understanding these segment boundaries illuminates where procurement authority concentrates and which technical specifications command pricing power.
Product Type:
Customization intensity spans from commodity-grade petroleum bases to precision-engineered surfactant systems, with specification stringency tightening as crop value per hectare rises.
- Emulsifiable Concentrate:These formulations contain 80-97% petroleum or vegetable oil combined with 1-5% emulsifier loading, designed for broad tank-mix compatibility across herbicide and insecticide portfolios. Corn and soybean operations in Illinois and Iowa specify these grades for fall burndown programs where glyphosate tank-mix flexibility dominates purchasing decisions.
- Superior Spray Oil:Refined paraffinic or methylated seed oil grades with ultra-low unsulfonated residue specifications, engineered for specialty fruit and vegetable applications where phytotoxicity thresholds tighten. Spanish citrus growers and Italian vineyard operators in Valencia and Tuscany mandate these formulations for spring fungicide applications where crop sensitivity peaks.
- Spray Oil:Standard refined petroleum or vegetable oil bases without premium emulsifier packages, serving cost-sensitive broadacre applications.
- Crop Oil:Basic oil formulations with minimal surfactant enhancement, used in legacy tank-mix protocols with older pesticide chemistries.
- Crop Oil Concentrate:Blended formulations with intermediate surfactant loading, occupying the specification gap between commodity spray oils and premium emulsifiable concentrates.
- Others:Niche formulations including esterified vegetable oils and proprietary penetration enhancers for specialized pesticide compatibility requirements.
Leading the category by volume: Emulsifiable Concentrate. Growing fastest: Superior Spray Oil.
Application:
Adjuvant specification intensity tracks pesticide resistance pressure and active ingredient cost structure, with herbicide adjuvants commanding the broadest volume flows and insecticide adjuvants climbing fastest on pyrethroid rate reduction strategies.
- Herbicide Adjuvant:Oil concentrates restore efficacy against glyphosate-resistant Palmer amaranth and waterhemp biotypes by improving cuticular penetration and droplet retention. Brazilian soybean operations in Mato Grosso and US Midwest corn systems drive specification intensity here, with farmers adding concentrates to tank mixes as resistance pressure escalates.
- Insecticide Adjuvant:Fastest-expanding application segment as oilseed producers in Argentina and Canada seek to maximize pyrethroid efficacy at reduced active rates, cutting chemical costs while maintaining pest control thresholds. Drone-mounted spraying in Australian cotton regions accelerates demand for low-volume compatible oil grades.
- Fungicide Adjuvant:Concentrates enhance systemic fungicide uptake in high-value vineyard and orchard operations, with French and German wine regions specifying premium grades.
- Fertilizer Adjuvant:Oil-based carriers for foliar nutrient applications, gaining traction in Indian Punjab wheat systems where micronutrient delivery efficiency matters.
- Plant Growth Regulator Adjuvant:Specialized formulations ensuring uniform PGR uptake in cotton defoliation and fruit thinning applications.
Herbicide Adjuvant generates the largest volume flows. Insecticide Adjuvant posts the steepest expansion trajectory.
End User:
Customer sophistication and input procurement authority vary dramatically across crop types, with oilseed and corn operations consolidating purchasing through cooperative channels while vegetable and fruit growers retain more direct supplier relationships.
- Oilseed Producers:Soybean and canola operations in Brazil, Argentina, and Canada represent the most concentrated demand pool, with crop oil concentrates essential for glyphosate efficacy on resistant weeds. These growers purchase through multinational distributor networks and regional cooperatives, bundling adjuvants with seed and pesticide procurement.
- Vegetable Farmers:Specialty producers in California's Central Valley and Spain's Murcia region specify low-phytotoxicity superior spray oils for integrated pest management compliance, with procurement often channeled through independent crop consultants rather than cooperative agronomists.
- Corn Growers:US Midwest operations drive emulsifiable concentrate volume through fall herbicide programs, with purchasing concentrated among regional cooperative buying groups in Minnesota and the Dakotas.
- Fruit Cultivators:Citrus, apple, and grape growers in Italy, Spain, and Washington State demand certified renewable-content formulations for EU Green Deal compliance and export market access.
- Legume Farmers:Pulse producers in India and Australia use concentrates for fungicide and insecticide enhancement in chickpea and lentil systems.
Oilseed Producers anchor category volume. Vegetable Farmers command the highest per-hectare specification intensity.
Distribution Channel:
Channel structure determines pricing transparency and supplier margin capture, with direct sales preserving premium positioning and cooperative societies consolidating procurement authority across millions of hectares.
- Agricultural Retailers:Dominant channel in North American row-crop regions, with retailer agronomists at cooperative buying groups displacing independent consultants as primary specification influencers. These agronomists bundle concentrate recommendations with pesticide and seed purchases, compressing standalone brand loyalty.
- Cooperative Societies:Farmer-owned purchasing cooperatives in Brazil and the US Midwest aggregate demand across thousands of members, negotiating volume-based pricing and exclusive supplier relationships that concentrate market access.
- Direct Sales:Large-scale farming enterprises and integrated agribusiness operations in Australia and Ukraine purchase directly from formulators, bypassing distributor margins for high-volume annual contracts.
- Wholesale Distributors:Regional logistics specialists serving smaller formulators and independent retailers, particularly in Eastern European and Southeast Asian markets.
- Online Marketplaces:Emerging channel for standard-grade concentrates in price-transparent comparison shopping, though specification complexity limits penetration in premium segments.
Agricultural Retailers and Cooperative Societies together control the majority of volume flows. Direct Sales commands the highest margin realization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's Mato Grosso soybean belt functions as the primary tax-incentive zone concentrating crop oil concentrate demand, with special agricultural development districts accelerating adjuvant procurement intensity across glyphosate-dependent operations.
United States
EPA biofuel blending mandates under the Renewable Fuel Standard are pulling formulators toward higher-purity emulsifier systems that qualify for renewable content credits. FIFRA registration requirements harden cost-of-entry for new market participants. Illinois and Iowa corn operations specify emulsifiable concentrate grades for fall burndown programs where glyphosate tank-mix flexibility dominates purchasing decisions.
Brazil
ANVISA pesticide adjuvant notification requirements shape product standard thresholds for export-bound formulations. Glyphosate-resistant Palmer amaranth infestations across Mato Grosso and Goiás are compelling farmers to add oil concentrates to tank mixes. Brazilian cooperative societies aggregate demand across thousands of soybean producers, negotiating volume-based pricing that concentrates market access.
Germany
EU Green Deal bio-content thresholds for agricultural inputs are creating compliant product categories that command distributor preference. REACH Article 33 disclosure obligations force concentrate shipments to document full oil-origin chain of custody. Specialty fruit producers in Baden-Württemberg and Bavaria shift procurement toward suppliers with certified renewable content documentation.
India
Punjab and Haryana basmati and wheat farmers remain underpenetrated for adjuvant use, presenting first-mover positioning as pesticide intensification accelerates. FSSAI and central agricultural ministry guidelines on adjuvant safety are tightening product registration protocols. The Indo-Gangetic Plain rice-wheat belt represents an emerging demand cluster as micronutrient delivery efficiency gains priority.
Argentina
Soybean oil sourcing networks cluster in Rosario and Buenos Aires crush facilities, creating geographic concentration for bio-based concentrate producers. The country's national agricultural regulator maintains adjuvant import standards that align with Mercosur trade bloc harmonization. Pampas region soybean operations drive specification intensity for glyphosate-resistant weed management protocols.
Global Crop Oil Concentrates Market Competitive Landscape
German and Swiss producers anchor the premium formulation tier; North American specialists hold distribution-intensive positions in retailer-channel markets. The vendor base concentrates among integrated multinationals with captive surfactant chemistry capabilities and regional blenders serving cooperative procurement networks. Two strategic archetypes dominate: integrated chemical conglomerates leveraging backward integration into emulsifier feedstocks, and agricultural distribution specialists bundling adjuvants with seed and pesticide portfolios. Competitive moves center on M&A for surfactant technology access and capacity expansion in Brazil and US Midwest production corridors.
Within the integrated chemical tier, BASF SE and Croda International exemplify formulation leadership archetypes. BASF represents the diversified conglomerate model with integrated surfactant chemistry portfolios sustaining position across emulsifiable concentrate grades. Croda anchors the renewable sourcing specialist position through bio-based oil networks navigating evolving content thresholds. FMC Corporation occupies the distribution-partnership archetype, with positioning tied to agricultural retailer relationships in North American row-crop regions.
| Leading Market Players |
|---|
| BASF SE |
| Croda International |
| Wilbur-Ellis Company LLC |
| Corteva Agriscience |
| Clariant AG |
| FMC Corporation |
| Cargill |
| Evonik |
| Albaugh LLC |
| Others |
Supply & Pricing Matrix
EU Green Deal bio-content mandates and EPA renewable fuel specifications are forcing formulators to segregate production lines and absorb certification costs that compress mid-tier margins while premium grades capture distributor preference. Supply response concentrates among integrated multinationals with captive emulsifier capabilities, pricing smaller blenders out of compliant product tiers.
Pricing Analysis
Short lead-time premiums for certified renewable-content concentrates run 15-25% above standard petroleum grades as Brazilian and German buyers accelerate procurement timelines. Contract-based annual offtake dominates volume flows, with price differentiation anchored in ISO 17025 accreditation status and oil-origin chain-of-custody documentation. Cost compression in commodity petroleum-based tiers intensifies as Argentine soybean oil feedstock volatility feeds through to bio-based formulations. Cooperative buying groups in the US Midwest exhibit highest price sensitivity; Spanish citrus growers and Italian vineyard operators show lowest elasticity due to phytotoxicity compliance requirements.
Supply Chain Analysis
Agricultural retailer channels handle hyperscale demand from North American row-crop cooperatives, while direct sales serve Australian and Ukrainian agribusiness enterprises. Manufacturing concentrates in the United States, Brazil, and Germany, with surfactant feedstock dependencies tethered to BASF's Ludwigshafen complex, Croda's bio-based sourcing networks, and Argentine crush facilities. Single-source vulnerability in methylated seed oil precursors creates exposure to Rosario port logistics disruptions. Distribution runs through cooperative societies in Brazil's Mato Grosso and Minnesota-Dakota buying groups that aggregate procurement across thousands of members.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as formulators pursue backward integration into emulsifier feedstocks to secure margin control against petroleum price volatility and renewable certification requirements.
For Market Incumbents: Anticipate regulatory divergence between EU oil-origin disclosure rules and US renewable content thresholds by maintaining segregated production lines and dual-registration dossiers. BASF and Croda should deepen captive surfactant capacity to defend against distribution-partnership competitors like FMC. Channel control through exclusive retailer agronomist relationships in Minnesota and the Dakotas represents the critical defensive lever. For New Entrants and Emerging Players: Agricultural drone service providers represent the most penetrable channel partner type for ultra-low phytotoxicity oil grades, as aerial application volumes accelerate in Australian cotton and Brazilian soybean regions. Target India's Punjab and Haryana rice-wheat belt with micronutrient adjuvant bundles, where pesticide intensification outpaces adjuvant adoption. A certification-first go-to-market angle—securing EU Green Deal compliance before market entry—unlocks distributor preference in German and French procurement networks. For Investors and Strategic Acquirers: The window for entry favors mid-tier blenders with ISO 17025 laboratory accreditation and established Brazilian ANVISA registration pathways. Surfactant technology specialists with methylated seed oil expertise command scarcity premiums as hybrid petroleum-bio formulations displace pure grades. Watch for inflection when EPA finalizes renewable content threshold increases that would obsolete non-compliant inventory.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Emulsifier Feedstocks | BASF's captive surfactant chemistry preserves margin control against petroleum volatility. |
| ISO 17025 Laboratory Accreditation | Cold-storage and hot-storage testing capability filters supplier qualification by multinational distributors. |
| EU Green Deal Compliance Certification | Certified renewable content documentation commands procurement preference in German and French markets. |
| Drone Application Compatibility Development | Low-volume aerial spraying specifications open premium tiers for ultra-low phytotoxicity oil grades. |
| Exclusive Retailer Agronomist Partnerships | Cooperative buying groups in Minnesota and the Dakotas displace independent consultants as specification channels. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across formulation chemists at integrated multinationals, procurement leads at Brazilian and US Midwest cooperative societies, distribution channel partners in agricultural retail networks, and technical R&D directors at surfactant suppliers. EPA FIFRA registration databases, ANVISA adjuvant notification records, REACH Article 33 disclosure filings, and ISO 17025 accreditation registries provided validation layers. Bottom-up volume triangulation against top-down value estimates ensured cross-verification.
Data-stream reconciliation across product type, application, end-user crop category, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level demand elasticity modeling, feedstock price scenario analysis, and regulatory compliance cost absorption curves. Industry-specific inputs included glyphosate-resistant weed pressure indices from US Midwest extension services and Brazilian soybean planting intensity forecasts from CONAB.
Caveats apply where EPA renewable fuel standard revisions or EU bio-content threshold adjustments could materially shift the outlook, particularly for non-compliant inventory obsolescence risk. Feedstock concentration in Argentine crush facilities and surfactant supply bottlenecks represent additional revision triggers. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
North America Agricultural Disinfectants Market
Agricultural Chemicals
Plant Growth Regulators Market
Agricultural Chemicals
Feed Preservatives Market
Agricultural Chemicals
Gibberellins Market
Agricultural Chemicals
United States Feed Amino Acids Market
Agricultural Chemicals
Pesticide Adjuvant Market
Agricultural Chemicals
ASEAN Livestock Disinfectant Market
Agricultural Chemicals
Asia-Pacific Swine Feed Premix Market
Agricultural Chemicals
Organic Bromide Market
Agricultural Chemicals
Feed Antioxidants Market
Agricultural Chemicals
North America Soil Treatment Market
Agricultural Chemicals
Berry Greenhouse Premium Micronutrient Package Market
Agricultural Chemicals
China Feed Enzymes Market
Agricultural Chemicals
North America Feed Amino Acids Market
Agricultural Chemicals
Vietnam Feed Additives Market
Agricultural Chemicals
Agricultural Grade Zinc Chemicals Market