
 Soilless Substrate-Specific Fertility Solution Market | 2026-2036
Soilless Substrate-Specific Fertility Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Soilless Substrate-Specific Fertility Solution Market Insights
Aftermarket nutrient calibration services is tilting from generic fertilizer distributors toward substrate-specialized agronomy firms. ICL Group leverages its vertical integration from specialty minerals to finished hydroponic formulations. Haifa Group anchors its position through precision agriculture laboratories that diagnose substrate-specific deficiencies. Yara International competes via controlled-release technology platforms optimized for inert media.
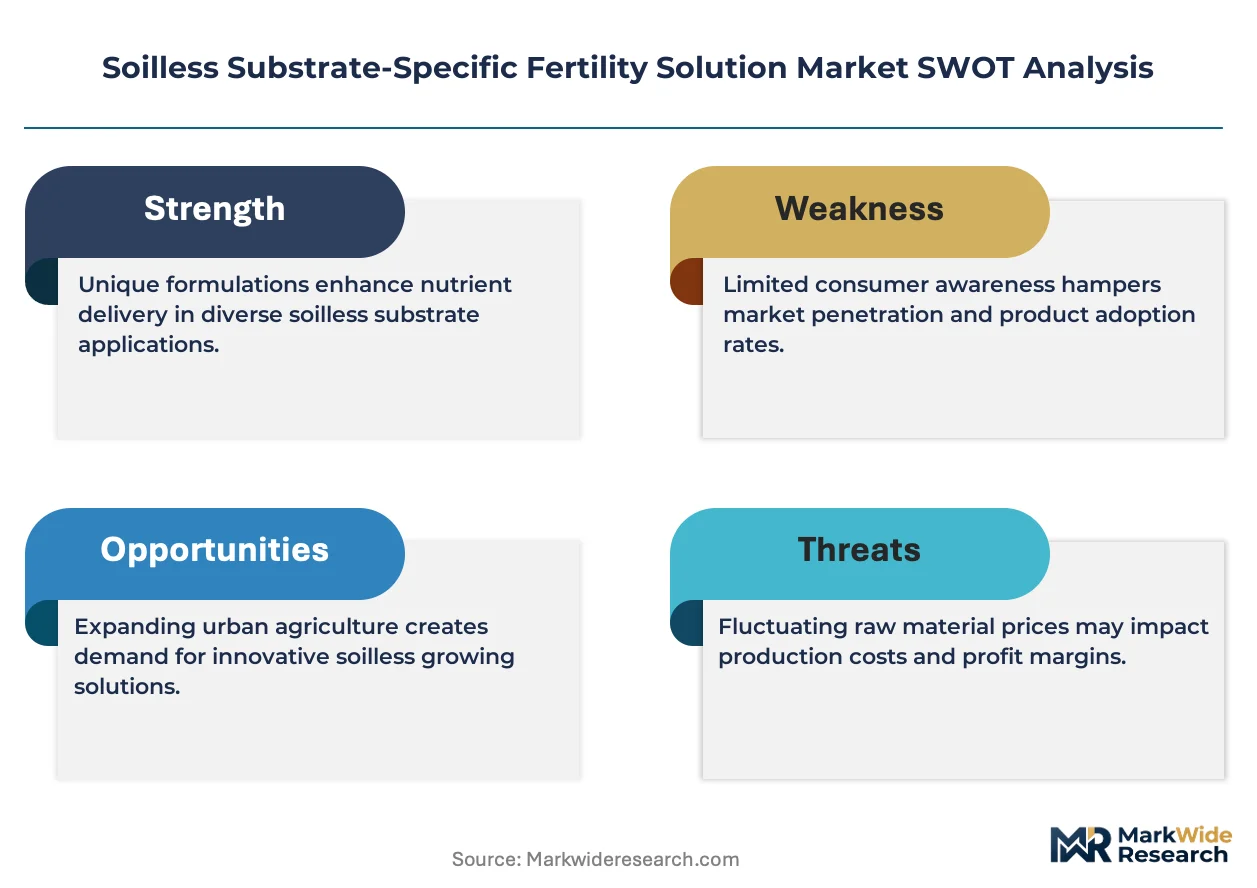
Soilless substrate-specific fertility solutions are chemically formulated nutrient blends engineered to compensate for the zero cation-exchange capacity and sterile biological profile of inert growing media such as rockwool, perlite, and coco coir, typically delivered as dual-component A/B concentrates with electrical conductivity targets between 1.5 and 3.0 mS/cm. Hydroponic nutrients occupy the dominant value share as greenhouse tomato and cucumber operations scale across temperate climates. Liquid fertilizers sustain the fastest expansion trajectory, driven by automated dosing systems in vertical farming installations. Biostimulants represent an emerging margin pool where amino acid and seaweed extract additives command premium positioning against commodity salts.
The EU Fertilizing Products Regulation harmonizes CE-marking requirements for substrate-compatible nutrients across member states, while the EPA oversees discharge limits for hydroponic runoff in US protected agriculture zones. ISO 17025 accreditation for substrate testing laboratories is becoming a de facto market access threshold in export-oriented supply chains. Stakeholders must monitor evolving carbon footprint disclosure rules for fertilizer production, as Scope 3 emissions reporting reshapes supplier qualification criteria.
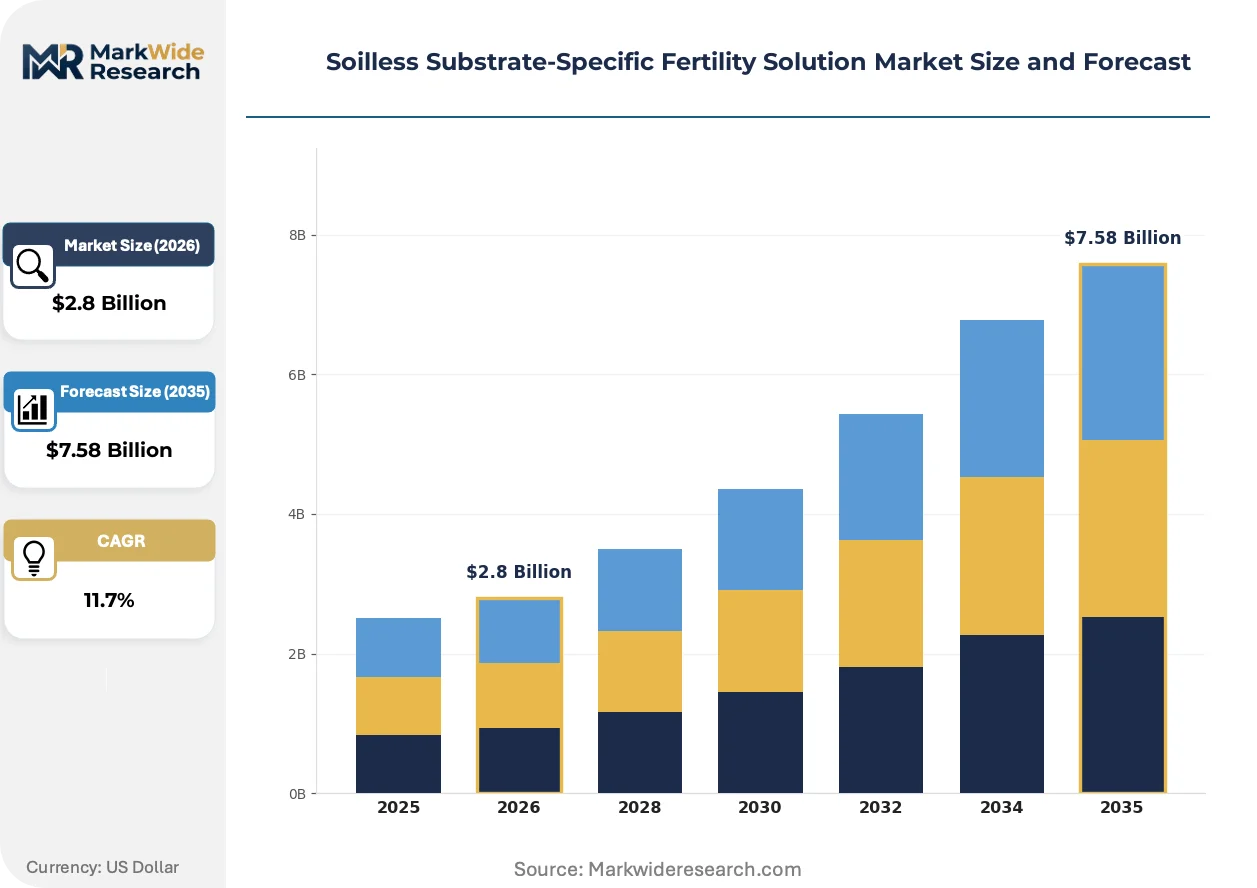
Market Dynamics
The transition from commodity fertilizer blending toward substrate-calibrated precision chemistry is compressing margin pools for generic distributors while elevating agronomy-intensive service models in protected horticulture supply chains.
Growth Catalysts
- EU Fertilizing Products Regulation:Harmonized CE-marking requirements for substrate-compatible nutrients eliminate national fragmentation and accelerate cross-border formulation sales across member states.
- Automated dosing infrastructure:Vertical farming installations in the Netherlands and Denmark deploy sensor-integrated fertigation systems that demand liquid concentrates with precise electrical conductivity specifications.
- Rockwool and coco coir:These inert media now dominate greenhouse tomato and cucumber operations across Spain and Italy, creating captive demand for compensatory nutrient chemistry.
Market Restraints
- Potassium and phosphorus input volatility:Specialty mineral salts face price instability tied to concentrated Moroccan phosphate rock and Belarusian potash supply disruptions.
- Zero cation-exchange capacity:Inert substrates provide no nutrient buffer, forcing continuous monitoring and raising technical failure costs for operators.
- EPA discharge limits:Hydroponic runoff regulations in US protected agriculture zones impose treatment infrastructure costs that deter small-scale greenhouse entry.
Strategic Opportunities
- Biostimulant additives:Amino acid and seaweed extract formulations command premium positioning against commodity salts in high-value berry and leafy green segments.
- ISO 17025 accreditation:Certified substrate testing laboratories become mandatory gatekeepers for export-oriented supply chains serving Middle Eastern and East Asian markets.
- Scope 3 emissions disclosure:Carbon footprint reporting requirements for fertilizer production reshape supplier qualification criteria toward low-carbon mineral sourcing.
Industry Challenges
- Substrate-specific agronomy expertise:Greenhouse operators lack personnel trained in electrical conductivity management and ionic balance diagnostics for sterile media.
- Dual-component A/B formulation complexity:Incompatible concentrate mixing creates precipitation failures that damage irrigation infrastructure and crop yields.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soilless Substrate-Specific Fertility Solution Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.58 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydroponic Nutrients, Aeroponic Formulations, Coco Coir Fertilizers, Rockwool Additives, Peat Substitute Enhancers Application: Greenhouse Cultivation, Vertical Farming, Controlled Environment Agriculture, Urban Farming, Hydroponic Systems End User: Commercial Growers, Research Institutions, Nursery Operators, Organic Farm Specialists, Vertical Farm Developers Technology: Slow Release Formulation, Liquid Fertilizers, Controlled Release Capsules, Foliar Sprays, Biostimulants |
| Companies Covered | ICL Group, Haifa Group, Yara International, SQM, COMPO EXPERT, Van Iperen International, OAT Agrio, Nutrien, EuroChem Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soilless Substrate-Specific Fertility Solution Market Trends and Innovations
Digital agronomy platforms and precision dosing hardware are converging to displace manual nutrient management in intensive protected horticulture operations across temperate climate zones.
Cloud-based fertigation control systems is virtualizing the traditional role of on-site agronomists by automating real-time nutrient adjustments based on substrate sensor arrays. Large-scale greenhouse operators in the Netherlands deploy these platforms across multi-hectare tomato facilities. The technology is compressing labor costs while raising entry barriers for smaller competitors lacking capital for integrated automation stacks.
REACH substance registration requirements for fertilizer additives are tightening purity specifications for hydroponic micronutrient chelates entering European markets. Formulators must now document full toxicological profiles for iron EDTA and manganese complexes. Specialty mineral suppliers with pre-registered substance portfolios capture share from commodity blenders facing compliance delays.
Buyer consolidation among commercial greenhouse cooperatives is forcing nutrient suppliers to unbundle technical advisory services from product pricing. Dutch auction-linked grower associations now demand standalone agronomy contracts separate from chemical procurement. This disintermediation of service and product revenue streams is most advanced in the Westland cluster south of The Hague.
Soilless Substrate-Specific Fertility Solution Market Segmentation
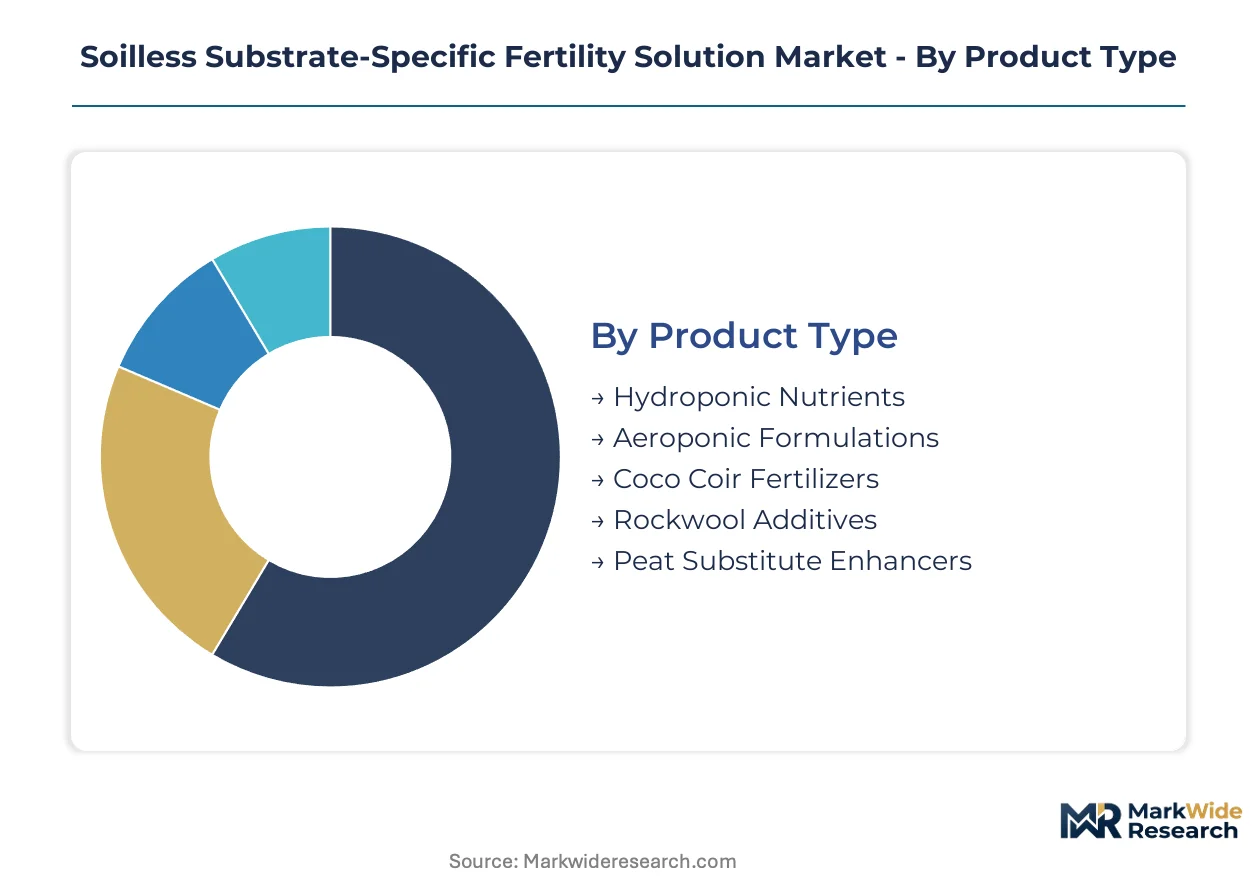
Substrate-specific fertility solutions fragment across four critical dimensions that determine formulation chemistry, delivery mechanism, and commercial access. Product type dictates mineral salt composition and pH buffering capacity. Application context governs electrical conductivity targets and dosing frequency. End-user sophistication shapes technical service bundling. Technology platform determines capital intensity and automation compatibility.
Product Type:
Mature hydroponic and rockwool formulations anchor commercial volume, while emerging coco coir and peat substitute enhancers capture share from sustainability-driven substrate transitions.
- Hydroponic Nutrients:Dual-component A/B concentrates engineered for zero cation-exchange capacity media, with electrical conductivity specifications between 1.5 and 3.0 mS/cm. Dutch and Spanish greenhouse tomato operators deploy these formulations across multi-hectare facilities, driven by automated fertigation infrastructure requiring precise ionic balance control.
- Rockwool Additives:Calcium-magnesium fortified blends compensating for the alkaline leaching profile of stone wool substrates. Mediterranean basin cucumber producers in Almería and Sicily rely on these additives to prevent blossom-end rot in high-yielding protected cultivation systems.
- Aeroponic Formulations:Ultra-low viscosity nutrient mists optimized for high-pressure nozzle delivery in root-suspension systems. NASA-derived research institutions and premium lettuce operations deploy these solutions.
- Coco Coir Fertilizers:Buffered potassium and calcium blends addressing the natural sodium and chloride content of coconut husk substrates. Southeast Asian export nurseries drive adoption.
- Peat Substitute Enhancers:Microbial inoculant and humic acid combinations improving water retention in wood fiber and composted bark alternatives. Nordic organic certification requirements accelerate uptake.
Hydroponic nutrients retain volume leadership; peat substitute enhancers hold the steepest expansion curve.
Application:
Cost tier segmentation separates capital-intensive controlled environment installations from lower-barrier urban farming deployments, with technology sophistication determining service bundling intensity.
- Greenhouse Cultivation:Large-scale polytunnel and glasshouse operations spanning temperate climate zones, requiring seasonal formulation adjustments for light-integrated growth cycles. Dutch Westland cluster cooperatives negotiate consolidated procurement contracts with standalone agronomy service unbundling.
- Controlled Environment Agriculture:Fully enclosed vertical stack systems with HVAC-integrated climate control, demanding precise nutrient temperature management. Danish pharmaceutical-grade lettuce producers and Emirates desert facilities deploy these systems.
- Vertical Farming:Multi-layer indoor installations with LED-optimized spectrum delivery, requiring liquid concentrate compatibility with sensor-integrated dosing hardware. Singapore and New York City urban density constraints drive facility construction.
- Hydroponic Systems:Recirculating deep water culture and nutrient film technique installations in educational and small-scale commercial settings. University research stations and regional extension services maintain demand.
- Urban Farming:Rooftop and repurposed industrial space operations with space-constrained logistics and local distribution mandates. Paris and Berlin municipal subsidy programs support entry.
Greenhouse cultivation commands the largest addressable base; controlled environment agriculture is gaining share fastest.
End User:
Customer type stratification distinguishes volume-driven commercial procurement from specification-intensive research contracting, with certification requirements fragmenting access tiers.
- Commercial Growers:Professional greenhouse cooperatives and independent operators with technical staff capable of electrical conductivity diagnostics and ionic balance adjustments. Dutch auction-linked associations now demand ISO 17025-accredited laboratory partnerships.
- Vertical Farm Developers:Technology-integrated operators building automated cultivation facilities with proprietary software stacks, requiring API-compatible nutrient dosing systems. Plenty and Infarm alumni-founded ventures in London and Munich drive specification.
- Research Institutions:University agricultural departments and government extension services conducting cultivar trials and substrate comparison studies. Wageningen University and UC Davis maintain active formulation evaluation programs.
- Nursery Operators:Ornamental and propagation-focused businesses requiring pathogen-free sterile media and juvenile plant-appropriate nutrient dilutions. Italian and Colombian flower export nurseries represent concentrated demand.
- Organic Farm Specialists:Certification-constrained operators limited to approved mineral sources and natural biostimulant additives. EU Organic Regulation compliance restricts chelated micronutrient options.
Commercial growers retain volume leadership; vertical farm developers hold the steepest expansion curve.
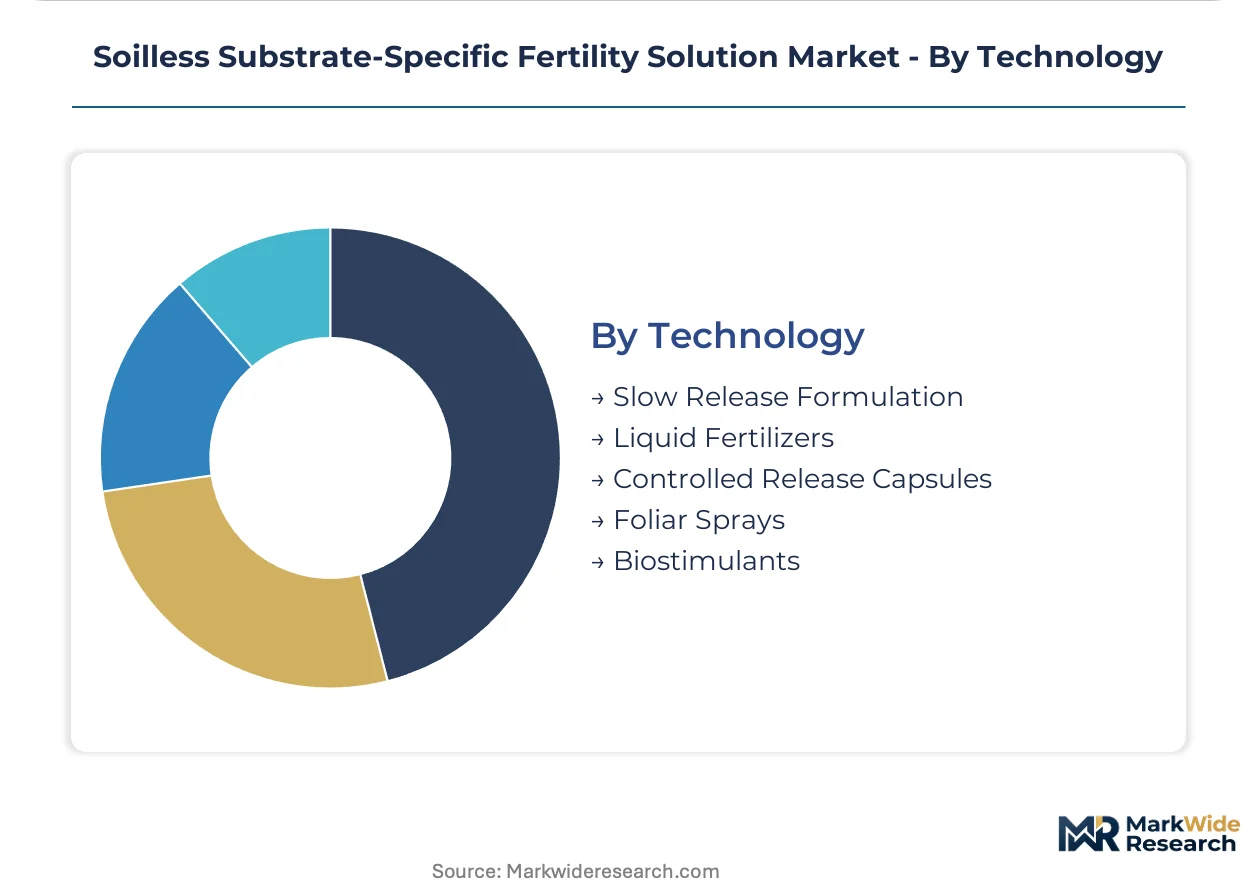
Technology:
Margin structure differentiates commodity salt blending from premium biostimulant and controlled-release platforms, with automation compatibility determining growth trajectory.
- Liquid Fertilizers:Fully soluble concentrates compatible with automated dosing infrastructure and real-time electrical conductivity feedback systems. Netherlands and Denmark vertical farming installations sustain the fastest technology adoption.
- Biostimulants:Amino acid, seaweed extract, and microbial inoculant additives commanding premium positioning against commodity salts in high-value berry and leafy green segments. Yara International and Haifa Group compete via proprietary fermentation and extraction platforms.
- Controlled Release Capsules:Polymer-coated granules with temperature-dependent nutrient diffusion for reduced dosing frequency in labor-constrained operations. Australian and Israeli protected agriculture sectors trial deployment.
- Slow Release Formulation:Urea-formaldehyde and sulfur-coated products with extended nitrogen availability for seasonal crops. Traditional greenhouse pepper operations in Mexico maintain usage.
- Foliar Sprays:Micronutrient chelate solutions applied directly to leaf tissue for rapid deficiency correction. Emergency intervention use limits scale.
Liquid fertilizers retain volume leadership; biostimulants hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between Mediterranean basin countries deploying substrate-specific fertility in intensive greenhouse tomato and cucumber operations versus Northern European markets where vertical farming automation drives liquid concentrate demand. Dutch operators prioritize precision dosing infrastructure while Spanish growers emphasize cost-calibrated rockwool compensation chemistry.
Netherlands
Westland cluster cooperatives negotiate consolidated procurement contracts for dual-component A/B concentrates serving multi-hectare tomato facilities. The EU Fertilizing Products Regulation harmonizes CE-marking requirements that Dutch formulators leverage for cross-border sales into Belgium and Germany. Wageningen University maintains active substrate testing partnerships with commercial greenhouse operators.
Spain
Almería province greenhouse complexes consume calcium-magnesium fortified blends preventing blossom-end rot in high-yielding cucumber systems. The country's national agricultural regulator enforces residue monitoring protocols for hydroponic runoff discharge. Mediterranean basin protected horticulture concentrates demand in Murcia and Granada provinces.
United States
California Central Valley greenhouse operators face EPA discharge limits imposing treatment infrastructure costs on hydroponic runoff. The state's agricultural extension services promote substrate-specific fertility adoption among strawberry propagators. Salinas Valley leafy green producers trial automated dosing systems.
China
Shandong Peninsula protected vegetable cultivation expands substrate-calibrated nutrient programs for export-oriented tomato operations. The Ministry of Ecology and Environment monitors fertilizer production carbon disclosure requirements under dual carbon goals. Yangtze River Delta vertical farming installations source liquid concentrate formulations.
Denmark
Pharmaceutical-grade lettuce producers deploy controlled environment agriculture systems with HVAC-integrated nutrient temperature management. Danish agricultural authorities certify organic substrate enhancers under EU Organic Regulation compliance frameworks. Copenhagen metropolitan vertical farming ventures specify API-compatible dosing hardware.
Soilless Substrate-Specific Fertility Solution Market Competitive Landscape
Capability concentration sits with specialty mineral suppliers possessing REACH-registered chelate portfolios; scale advantage sits with diversified agricultural chemical conglomerates with captive phosphate and potash access. The vendor base stratifies across three tiers: integrated mining-to-formulation operators, regional blending specialists with ISO 17025 laboratory partnerships, and commodity salt distributors facing margin compression. Dominant competitive moves include backward integration into specialty mineral sourcing and strategic unbundling of technical advisory services from product pricing.
Within the integrated formulation tier, ICL Group exemplifies vertical control from specialty minerals through finished hydroponic chemistry, while Haifa Group anchors its position through precision agriculture laboratory infrastructure. Yara International occupies a position emphasizing controlled-release technology platforms. These three entities represent distinct strategic postures: mineral integration, service-intensive agronomy, and technology-platform optimization.
| Leading Market Players |
|---|
| ICL Group |
| Haifa Group |
| Yara International |
| SQM |
| COMPO EXPERT |
| Van Iperen International |
| OAT Agrio |
| Nutrien |
| EuroChem Group |
| Others |
Pricing and Supply Chain Analysis
Almería province greenhouse complexes anchor European supply capacity for calcium-magnesium fortified blends, with their concentrated procurement power compressing margins for commodity salt distributors while elevating agronomy-intensive service providers. Dutch Westland cluster cooperatives negotiate consolidated contracts that strip product pricing from technical advisory fees, reshaping how formulation suppliers capture value downstream.
Pricing Analysis
Long-term offtake agreements dominate procurement between Dutch auction-linked grower associations and integrated mineral-to-formulation operators, though spot purchasing persists for emergency micronutrient corrections. Price differentiation rests on ISO 17025 laboratory accreditation tier and bundled agronomy service intensity. Pricing pressure stems from potassium and phosphorus input volatility tied to Belarusian potash and Moroccan phosphate rock disruptions. Commercial greenhouse cooperatives exhibit highest price sensitivity; pharmaceutical-grade controlled environment agriculture operators show lowest.
Supply Chain Analysis
Upstream feedstock concentration centers on Israeli and Jordanian specialty mineral deposits for potassium nitrate, plus Moroccan phosphate rock processing for phosphorus inputs. Formulation chemistry draws from Chilean nitrate caliche and North American magnesium sulfate. Single-source vulnerability runs through concentrated potash corridors facing geopolitical disruption. Distribution feeds from regional blending facilities near Rotterdam and Valencia into greenhouse cooperative procurement networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through Dutch auction-linked grower association consolidation, forcing nutrient suppliers to unbundle services from product pricing and ceding margin control to procurement committees.
For Market Incumbents: Pre-empt margin erosion by securing backward integration into REACH-registered chelate portfolios before commodity blenders achieve compliance. Lock in multi-year laboratory service contracts with ISO 17025 accreditation as the mandatory gatekeeper threshold. Defend against cloud-based fertigation platform disintermediation by embedding proprietary dosing hardware compatibility into liquid concentrate specifications. For New Entrants and Emerging Players: Establish a beachhead in peat substitute enhancers for Nordic organic certification-constrained operators, where microbial inoculant and humic acid combinations face limited incumbent specialization. Target Southeast Asian coco coir export nurseries with buffered potassium formulations addressing natural sodium content. Lead with API-compatible nutrient dosing systems for vertical farm developers building automated cultivation facilities. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision agriculture laboratory infrastructure over commodity salt blending capacity, as cloud-based fertigation control systems virtualize traditional agronomist roles. Long-term viability hinges on carbon footprint disclosure compliance for Scope 3 emissions reporting reshaping supplier qualification. Watch for EPA discharge limit tightening in US protected agriculture zones as the inflection signal forcing treatment infrastructure investment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Minerals | REACH-registered chelate portfolios capture share from commodity blenders facing compliance delays. |
| ISO 17025 Laboratory Accreditation | Certified substrate testing becomes mandatory gatekeeper for export-oriented supply chains serving Middle Eastern markets. |
| API-Compatible Dosing Hardware Development | Vertical farm developers in Copenhagen and Singapore specify sensor-integrated liquid concentrate systems. |
| Biostimulant Additive Platform Expansion | Amino acid and seaweed extract formulations command premium positioning against commodity salts in berry segments. |
| Carbon Disclosure Program Implementation | Scope 3 emissions reporting reshapes supplier qualification criteria under EU Fertilizing Products Regulation. |
Research Methodology
Initial hypotheses were tested against primary input from greenhouse operations managers, procurement leads at Dutch grower cooperatives, precision agriculture laboratory directors, and substrate formulation chemists, then refined through secondary validation against EU Fertilizing Products Regulation implementation documents, EPA discharge limit enforcement records, SEC filings from listed agricultural chemical conglomerates, and customs trade data for specialty mineral salt flows. Bottom-up volume estimates from individual greenhouse facility nutrient consumption were triangulated against top-down market sizing from formulation supplier revenue aggregation.
Demand-supply balance dynamics across the projection horizon were modeled through segmentation across product type, application context, end-user sophistication tier, and technology platform capital intensity. CAGRs were derived from growth driver elasticity analysis applied to base-year consumption estimates, with hydroponic nutrient volume and biostimulant margin expansion serving as primary forecast calibration inputs.
Stress conditions across potash supply disruption severity, EPA regulatory enforcement intensity, and vertical farming automation adoption pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EU regulatory harmonization progress and substrate transition timelines. Material shifts in REACH substance registration timelines or Moroccan phosphate export policy would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Animal Feed Enzymes Market
Agricultural Chemicals
China Feed Amino Acids Market
Agricultural Chemicals
Agricultural Antibacterials Market
Agricultural Chemicals
North America Feed Pigments Market
Agricultural Chemicals
South America Feed Antioxidants Market
Agricultural Chemicals
South America Feed Acidifiers Market
Agricultural Chemicals
Indonesia Herbicide Market
Agricultural Chemicals
Agricultural Insect Pheromones Market
Agricultural Chemicals
Humic and Fulvic Acid Based Biostimulants Market
Agricultural Chemicals
Field Marking Paint Market
Agricultural Chemicals
Europe Feed Pigments Market
Agricultural Chemicals
North America Feed Premix Market
Agricultural Chemicals
Plant Growth Promoters Market
Agricultural Chemicals
Neem Pesticides Market
Agricultural Chemicals
Global Feed Palatability Enhancers Market
Agricultural Chemicals
Asia-Pacific Feed Additives Market