
 Indonesia Herbicide Market | 2026-2036
Indonesia Herbicide Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Herbicide Market Insights
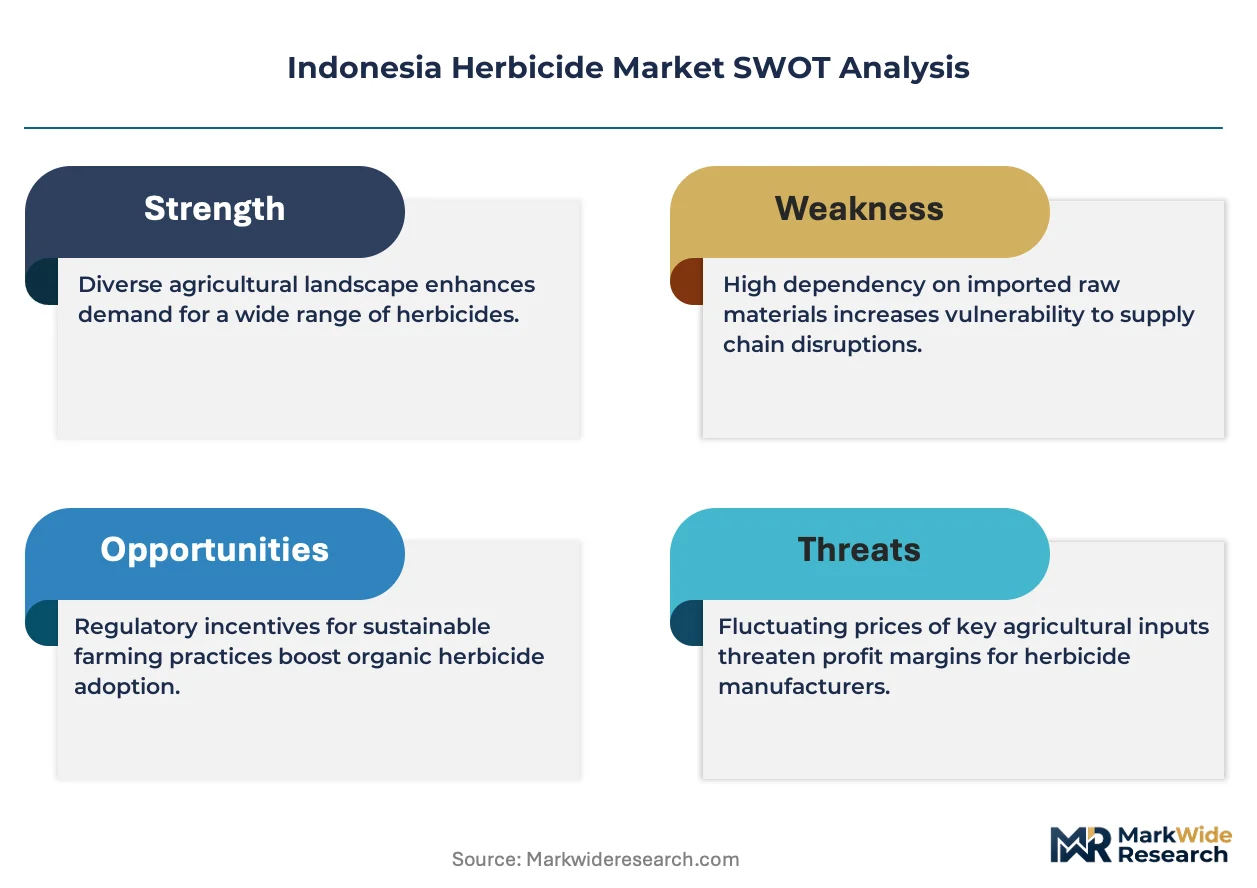
The capital-intensity divergence between integrated multinationals and domestic formulators is rotating competitive dynamics across Indonesia's herbicide sector. BASF SE leverages its Ludwigshafen-based active ingredient synthesis network to supply Indonesian distributors with proprietary glufosinate formulations. PT Biotis Agrindo anchors its position through backward integration into local surfactant blending and Javanese logistics hubs. UPL Limited differentiates via its India-to-Indonesia technical manufacturing corridor and regulatory dossier depth.
Indonesia herbicides comprise synthetic and bio-based chemical formulations designed to suppress or eliminate unwanted vegetation in agricultural and plantation settings, typically delivered as emulsifiable concentrates or wettable powders with specified active ingredient loadings measured in grams per hectare. These compounds function by disrupting photosynthesis, amino acid synthesis, or cell division in target weed species, thereby protecting yield-bearing crops from nutrient competition and harvest interference. Selective herbicides occupy the dominant revenue position as rice and palm oil growers demand crop-safe chemistries that eliminate grassy weeds without damaging cultivated plants. Non-selective formulations represent the fastest-expanding category as no-till farming spreads across Sumatra and Kalimantan, while liquid formulations capture the majority of value due to farmer familiarity with knapsack sprayer application.
BIS certification requirements and Ministry of Agriculture registration protocols govern product approval timelines, with the Pesticide Commission evaluating efficacy data and toxicological profiles before issuing distribution permits. The EU Green Deal's deforestation-free supply chain regulations indirectly pressure Indonesian exporters to document herbicide traceability across plantation estates. Stakeholders must monitor how Indonesia's national carbon accounting framework treats chemical weed control versus mechanical alternatives in certified sustainable palm oil audits.
Market Dynamics
Labor cost inflation across Sumatran and Kalimantan plantation belts is forcing estate operators to substitute mechanical weeding with chemical control, reshaping procurement volumes and formulation preferences toward long-residual products.
Growth Catalysts
- EU Deforestation Regulation:Brussels' supply chain traceability mandates push Indonesian palm oil exporters toward documented herbicide application records, creating compliance-driven demand for registered formulations with batch-level tracking.
- No-till farming expansion:Zero-tillage adoption across Riau and North Sumatra oil palm estates accelerates non-selective herbicide consumption for pre-plant burndown and in-crop weed management.
- Minimum wage escalation:Provincial labor boards in Riau and North Sumatra have ratcheted manual weeding costs above chemical alternatives, flipping the cost equation for estate managers.
Market Restraints
- Active ingredient import dependence:Domestic formulators lack synthesis capacity for glyphosate and glufosinate technicals, exposing margins to Chinese and Indian supply volatility and currency fluctuation.
- Residue limit compression:Indonesia's Ministry of Agriculture has tightened maximum residue limits for glyphosate and paraquat under national food safety protocols, forcing reformulation investments and portfolio pruning.
- Mechanical weeding substitution:Slashing machines and cover crop systems retain viability in steep-terrain estates where chemical runoff risks trigger watershed protection orders from provincial environmental agencies.
Strategic Opportunities
- Papua plantation frontier:Transmigration zone development in Merauke and Boven Digoel districts opens greenfield acreage for oil palm and food crop expansion with minimal incumbent chemical supplier presence.
- Bioherbicide registration pathway:Indonesia's Pesticide Commission has established accelerated evaluation tracks for microbial and botanical active ingredients, rewarding early movers with reduced approval timelines.
- Drone application services:Knapsack sprayer replacement via UAV-based precision spraying reduces labor exposure and enables variable-rate application across heterogeneous terrain in Central Kalimantan peatland estates.
Industry Challenges
- Toxicology dossier compilation:Registration submissions require chronic toxicity studies and environmental fate data that domestic laboratories cannot generate, forcing reliance on European contract research organizations with 18-month queues.
- Spray operator certification gaps:Ministry of Agriculture mandates for certified applicator training outpace vocational institute capacity in outer island provinces, creating compliance bottlenecks for estate expansion timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Herbicide Market |
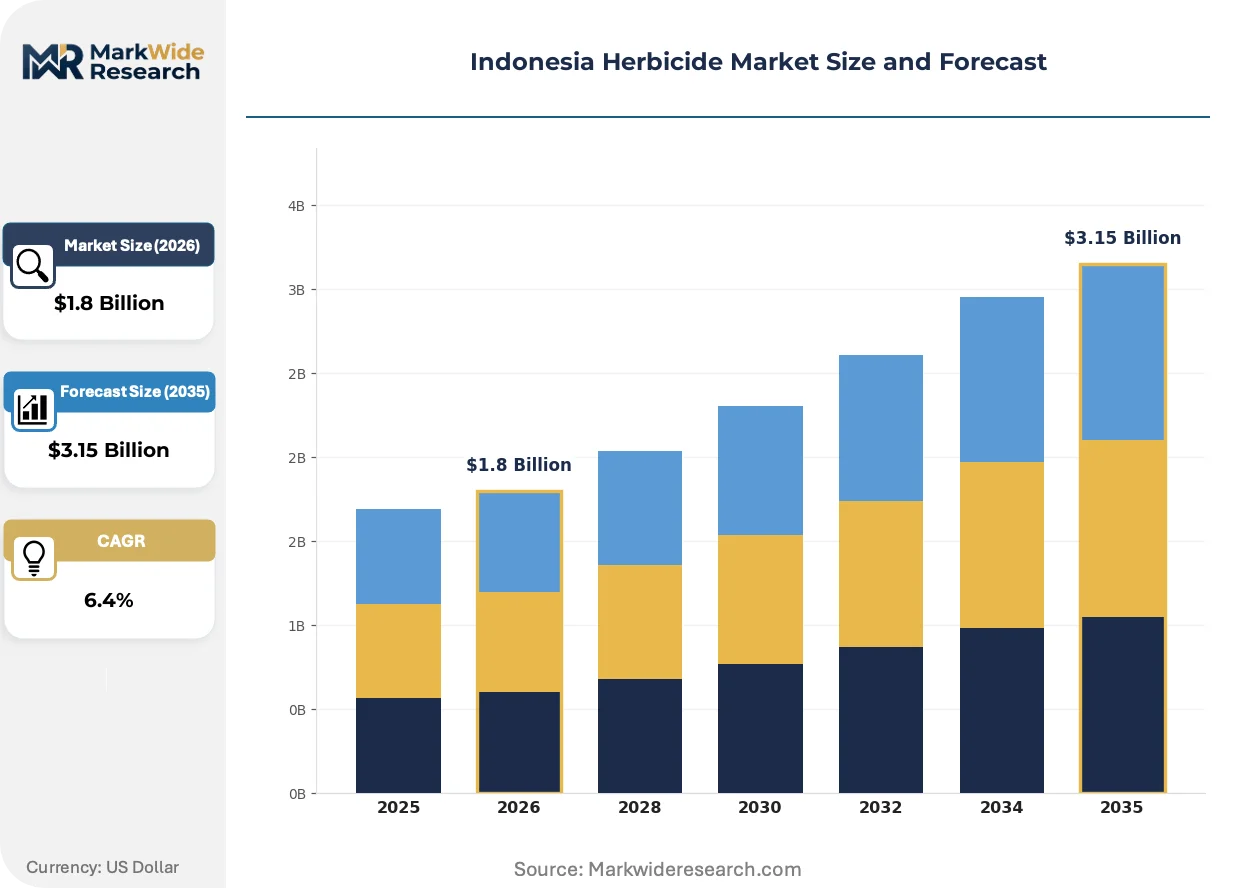
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Selective, Non-Selective, Pre-Emergent, Post-Emergent Application Method: Foliar Spray, Soil Treatment, Granular Application, Injection Crops: Rice, Corn, Soybean, Sugarcane Formulation: Liquid, Granular, Emulsifiable Concentrate, Wettable Powder |
| Companies Covered | BASF SE, Bayer AG, Syngenta Group, FMC Corporation, UPL Limited, Corteva Agriscience, ADAMA Agricultural Solutions, Nufarm Limited, PT Biotis Agrindo, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Herbicide Market Trends and Innovations
Digital traceability systems and biological active ingredient platforms are converging to displace legacy synthetic chemistries in premium supply chains, while application technology shifts reduce labor dependence.
RNA interference herbicides are fragmenting the research pipeline for novel modes of action. Bayer AG and Corteva Agriscience have advanced sprayable double-stranded RNA formulations through early-stage screening. Indonesian plantation groups monitor these developments through Singapore-based technical liaison offices. The technology is fragmenting competitive advantage away from traditional synthesis scale toward biologics manufacturing and sequence design capabilities.
Indonesia's Ministry of Agriculture has harmonized maximum residue limit schedules with Codex Alimentarius standards while adding indigenous crop categories. This regulatory convergence simplifies export compliance for palm oil and rubber consignments destined for EU and Japanese food processing customers. Formulators now face dual registration requirements for domestic sale versus export-grade certification, segmenting product portfolios by destination market.
Estate procurement offices are consolidating vendor relationships from fragmented distributor networks toward direct technical supply agreements with multinational manufacturers. Large plantation groups in Riau and North Sumatra now negotiate annual volume contracts with BASF SE and Syngenta AG for active ingredient supply, bypassing local formulator intermediaries. This concentration is most visible among certified sustainable palm oil estates where traceability documentation requirements favor single-source chemical procurement.
Indonesia Herbicide Market Segmentation
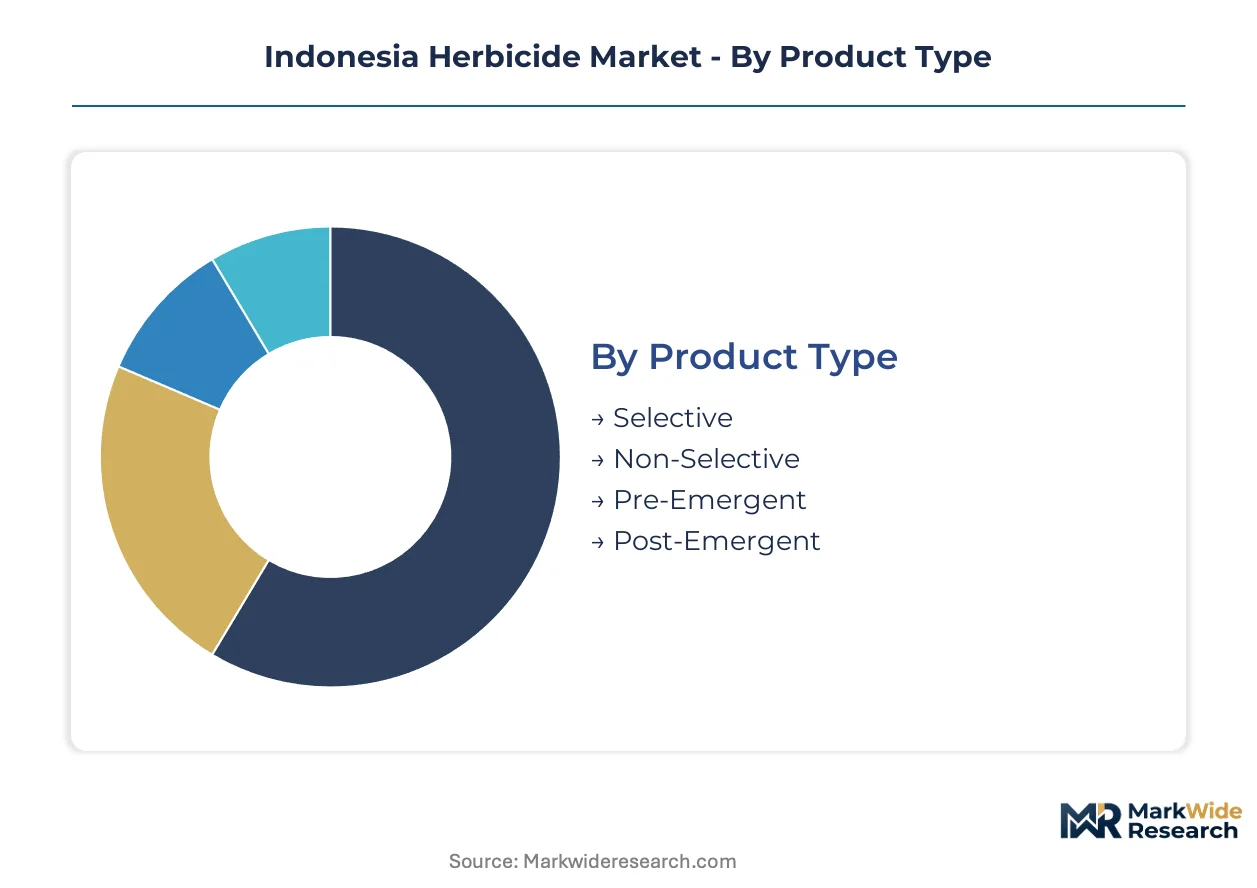
Segmentation in Indonesia's herbicide market reveals how substitution pressures reshape procurement priorities across plantation estates. Estate managers weigh chemical control against mechanical alternatives based on terrain constraints, labor economics, and residue compliance requirements.
Product Type:
Selective herbicides face intensifying substitution pressure from cover crop systems and slashing machines in steep-terrain estates where runoff risks trigger watershed protection orders.
- Selective:These formulations target specific weed species while preserving cultivated crops through differential uptake mechanisms. Rice growers in Central Java and palm oil operators in Riau prioritize crop-safe chemistries that eliminate grassy weeds without damaging yield-bearing plants. Labor cost escalation across Sumatran plantation belts accelerates selective herbicide substitution for manual weeding crews.
- Non-Selective:Broad-spectrum compounds destroy all vegetation through contact or systemic action, typically containing glyphosate or paraquat active ingredients. No-till farming spreads across Kalimantan peatland estates drive non-selective demand for pre-plant burndown applications. Zero-tillage adoption flips the cost equation against mechanical land preparation.
- Pre-Emergent:Soil-applied formulations create chemical barriers before weed seed germination, requiring precise timing with planting schedules.
- Post-Emergent:Foliar-active compounds control established weed populations through direct contact or translocation to root systems.
Selective herbicides retain volume leadership; non-selective formulations hold the steepest expansion curve.
Application Method:
Application technology segmentation tracks capital-labor trade-offs as estate operators mechanize weed control programs.
- Foliar Spray:Knapsack sprayers dominate smallholder operations while tractor-mounted booms serve large estates. UAV-based precision spraying gains traction in Central Kalimantan peatlands where heterogeneous terrain complicates ground-based application.
- Soil Treatment:Pre-emergent incorporation requires specialized equipment for uniform distribution and depth control.
- Granular Application:Solid formulations reduce operator exposure and enable precise placement around sensitive crop rows.
- Injection:Direct soil placement minimizes drift and surface runoff in watershed-protected zones.
Foliar spray retains volume leadership; injection methods gain share fastest in regulated watershed districts.
Crops:
Crop segmentation concentrates demand in plantation belts where monoculture systems create predictable weed pressure patterns.
- Rice:Paddy systems in Java and Sulawesi demand selective chemistries compatible with flooded cultivation. BIS residue limits and Ministry of Agriculture protocols govern aquatic toxicity profiles for rice-field applications.
- Corn:Upland cultivation in Lampung and East Nusa Tenggara requires pre-emergent and post-emergent rotation programs.
- Soybean:Dryland farming systems in West Java face competition from volunteer rice and grassy weed complexes.
- Sugarcane:Long-cycle ratoon crops in East Java justify long-residual herbicide investments against perennial weed establishment.
Rice retains volume leadership; oil palm estates (tracked through non-selective demand) drive the steepest expansion curve.
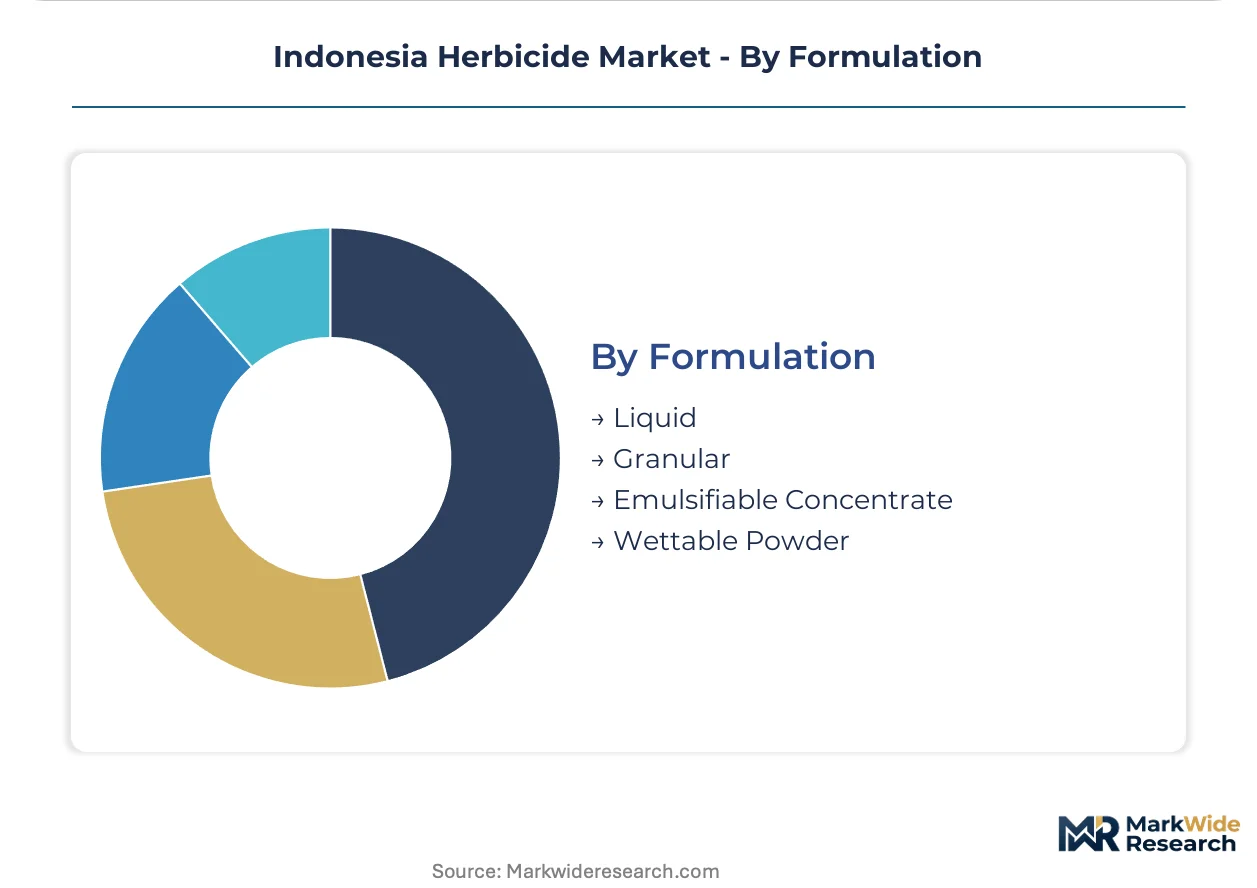
Formulation:
Formulation preferences reflect application infrastructure availability and storage constraints across dispersed plantation geographies.
- Liquid:Ready-to-use and concentrate solutions dominate due to farmer familiarity with knapsack sprayer calibration and mixing protocols. Estate procurement offices in North Sumatra negotiate annual volume contracts for liquid technical supply.
- Granular:Solid formulations reduce packaging waste and enable mechanical spreading in row crops.
- Emulsifiable Concentrate:Oil-based carriers enhance penetration of waxy leaf surfaces in tropical weed species.
- Wettable Powder:Dry formulations offer storage stability in high-humidity climates without solvent costs.
Liquid formulations retain volume leadership; emulsifiable concentrates gain share fastest in premium plantation supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sumatra commands premium pricing leverage over Kalimantan due to denser distributor networks and established plantation infrastructure. Java's rice belt operates on thinner margins driven by smallholder fragmentation. Papua's frontier estates face supply chain premiums that compress procurement flexibility.
Sumatra
Riau and North Sumatra provinces generate concentrated herbicide demand through oil palm and rubber estate dominance. The Ministry of Agriculture's tightened maximum residue limits force reformulation investments among formulators serving Medan-based procurement offices. Pekanbaru logistics clusters anchor technical import distribution for glufosinate and glyphosate supply chains.
Java
Central Java and East Java rice paddies drive selective herbicide volumes through flooded cultivation systems. BIS certification requirements govern aquatic toxicity profiles for paddy applications, extending product approval timelines. Surabaya formulators blend surfactants for wettable powder distribution across the island's cooperative networks.
Kalimantan
Central Kalimantan peatland estates accelerate non-selective herbicide adoption for zero-tillage oil palm expansion. Provincial environmental agencies issue watershed protection orders that restrict chemical runoff in steep-terrain districts. Pontianak distributor networks serve emerging plantation zones with delayed payment terms compared to Sumatran counterparts.
Papua
Merauke and Boven Digoel transmigration zones present greenfield acreage with minimal incumbent chemical supplier presence. The Pesticide Commission's registration protocols create compliance bottlenecks for new market entrants. Jayapura-based logistics face infrastructure gaps that inflate landed costs for technical imports.
Sulawesi
North Sulawesi and South Sulawesi cocoa-corn intercropping systems generate specialized weed control demand. Estate operators negotiate direct technical supply agreements to bypass fragmented distributor layers. Makassar procurement offices consolidate vendor relationships toward multinational manufacturers with traceability documentation capabilities.
Indonesia Herbicide Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Indonesia's herbicide sector. Integrated multinationals with proprietary active ingredient synthesis networks dominate premium formulation segments, while domestic formulators compete on blending flexibility and Javanese logistics proximity. Three archetypes structure competitive positioning: global technical suppliers with registration dossier depth, regional manufacturers with India-to-Indonesia manufacturing corridors, and local blenders with backward integration into surfactant production. Dominant competitive moves include direct technical supply agreements that bypass distributor intermediaries, and accelerated bioherbicide registration through Pesticide Commission evaluation tracks.
Among multinational technical suppliers, BASF SE and Bayer AG exemplify the synthesis-scale archetype with Ludwigshafen-based active ingredient networks. UPL Limited occupies a position within the regional manufacturing tier, leveraging India-to-Indonesia technical corridors. PT Biotis Agrindo anchors the domestic blender category through Javanese logistics hub control and local surfactant integration. These three players represent the structural divergence between global R&D intensity and regional operational proximity.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| Syngenta Group |
| FMC Corporation |
| UPL Limited |
| Corteva Agriscience |
| ADAMA Agricultural Solutions |
| Nufarm Limited |
| PT Biotis Agrindo |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day technical import lead times from Chinese and Indian synthesis hubs concentrate pricing power among integrated multinationals with captive active ingredient supply, while domestic formulators absorb currency volatility through Javanese surfactant blending arbitrage. This inventory-to-pricing coupling forces estate procurement offices toward annual volume contracts that lock in glyphosate and glufosinate technical access.
Pricing Analysis
Configured-to-order formulation premiums stretch 15-25% above standard wettable powder pricing, reflecting Ministry of Agriculture registration dossier investments and batch-level traceability documentation for EU Deforestation Regulation compliance. Contract-based long-term offtake dominates estate procurement, with price differentiation anchored in certification grade and volume scale. Cost compression in generic glyphosate formulations is intensifying because Chinese technical oversupply has eroded spot market premiums. Smallholder cooperatives in Java exhibit highest price sensitivity; certified sustainable palm oil estates in Riau show lowest sensitivity due to traceability mandate pass-through.
Supply Chain Analysis
Port congestion at Tanjung Priok and Singapore transshipment hubs inflates inbound logistics costs for technical imports, compressing margins for domestic formulators without direct manufacturer relationships. Supply concentrates in China, India, and Germany for glyphosate, glufosinate, and proprietary surfactant chemistries. Raw material dependencies center on paraquat technicals, petroleum-based solvent carriers, and palm-oil-derived adjuvants. Single-source vulnerability from Chinese synthesis concentration poses structural risk. Distribution runs through Medan and Surabaya logistics clusters serving plantation belts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against mechanical weeding substitution as labor cost inflation plateaus and slashing machine economics improve in steep-terrain estates.
For Market Incumbents: Fortify backward integration into surfactant production and Javanese logistics hub control to offset Chinese technical price volatility. Accelerate bioherbicide registration through Pesticide Commission evaluation tracks before microbial platforms commoditize. Channel control via direct technical supply agreements with Riau plantation groups neutralizes distributor margin stacking. For New Entrants and Emerging Players: Lead with drone application service partnerships in Central Kalimantan peatland estates where heterogeneous terrain blocks ground-based competition. Papua's Merauke transmigration zones offer white-space plantation acreage with minimal incumbent chemical supplier presence. Target bioherbicide registration as the most penetrable segment given accelerated evaluation timelines and multinational R&D gaps. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because estate procurement concentration favors scale players with traceability documentation capabilities. Acquire domestic formulators with Pesticide Commission registration dossiers and established distributor relationships in Sumatra. Watch for EU Deforestation Regulation enforcement intensity as the inflection signal for compliance-premium pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Surfactant Production | Javanese logistics hub control neutralizes Chinese technical price volatility for domestic formulators. |
| Bioherbicide Registration Acceleration | Pesticide Commission evaluation tracks reward early movers with reduced approval timelines versus synthetic pathways. |
| Direct Technical Supply Agreements | Bypassing distributor intermediaries captures margin from Riau plantation procurement consolidation. |
| Drone Application Service Partnerships | UAV-based precision spraying addresses labor exposure constraints in Central Kalimantan peatland terrain. |
| Traceability Documentation Investment | Batch-level tracking capabilities satisfy EU Deforestation Regulation mandates for certified sustainable palm oil estates. |
Research Methodology
Cross-validation between Ministry of Agriculture registration databases and plantation procurement office interviews anchors the qualitative findings on formulation preferences and compliance burdens. Primary engagement with technical R&D directors at multinational manufacturers, procurement leads at Riau and North Sumatra estate groups, distribution channel partners in Medan and Surabaya, and Pesticide Commission regulatory affairs specialists combined with secondary validation from customs/trade data, BIS certification records, and SEC filings from listed agrochemical parents. Bottom-up volume estimates from plantation acreage and application rate assumptions triangulate against top-down market value reconstructions.
Sensitivity analysis around labor cost inflation trajectories and EU Deforestation Regulation enforcement intensity shapes the projection framework across the analysis window. Segmentation dimensions modeled include product type, application method, crop system, and formulation chemistry, cross-tabulated by regional plantation belt. CAGRs derive from acreage expansion forecasts, substitution elasticity between chemical and mechanical weeding, and registration pipeline velocity. Industry-specific inputs center on provincial minimum wage board decisions and watershed protection order issuance patterns from environmental agencies.
Forecasts assume regulatory continuity in Indonesia's Ministry of Agriculture protocols and EU Green Deal implementation schedules; material policy shifts would require re-modeling around accelerated residue limit compression or deforestation-free supply chain mandate suspension. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
South America Feed Antioxidants Market
Agricultural Chemicals
Global Medicated Feed Additives Market
Agricultural Chemicals
Global Agricultural Colorants Market
Agricultural Chemicals
United States Feed Enzymes Market
Agricultural Chemicals
Global Carbofuran Market
Agricultural Chemicals
Agricultural Surfactants Market
Agricultural Chemicals
Asia-Pacific Feed Additives Market
Agricultural Chemicals
Stored Grain Insecticides Market
Agricultural Chemicals
North America Fungicide Market
Agricultural Chemicals
North America Soil Treatment Market
Agricultural Chemicals
Europe Silage Additives Market
Agricultural Chemicals
India Phosphate Rich Organic Manure (PROM) Market
Agricultural Chemicals
Asia Pacific Fungicide Market
Agricultural Chemicals
Feed Pigments Market
Agricultural Chemicals
Asia-Pacific Feed Binders Market
Agricultural Chemicals
China Herbicide Market