
 Europe Silage Additives Market | 2026-2036
Europe Silage Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Silage Additives Market Foresight
The EU Green Deal is restructuring cost-of-entry calculus for silage additive suppliers by binding farm subsidies to verifiable methane reductions. BASF SE leverages its microbial strain library to dominate inoculant formulation across Northern European dairy belts. Lallemand Animal Nutrition sustains competitive position through captive yeast production facilities in France and Belgium. Evonik Industries AG differentiates via amino acid-enhanced preservative blends that extend anaerobic stability windows.
Europe silage additives comprise microbial inoculants, organic acids, enzymes, and chemical preservatives applied to forage crops to accelerate fermentation, suppress spoilage organisms, and preserve nutritional value for ruminant feed. These formulations typically deliver lactic acid bacteria counts exceeding 100,000 colony-forming units per gram to achieve pH reduction below 4.5 within 48 hours of ensiling. Inoculants capture the dominant value share as dairy cooperatives demand guaranteed homofermentative performance for high-moisture corn and grass silages. Liquid formulations lead volume throughput due to compatibility with farm-scale applicator systems, though granular products gain traction among feed manufacturers seeking extended shelf stability and dosing precision.
EMA feed additive authorization protocols and EU F-Gas Regulation compliance requirements shape product development timelines and cross-border market access for novel microbial strains. REACH chemical safety assessments further constrain acid-based preservative formulations, pushing investment toward biological alternatives. Stakeholders must monitor pending revisions to the EU Animal Feed Regulation that could mandate real-time fermentation monitoring as a condition of additive efficacy claims.
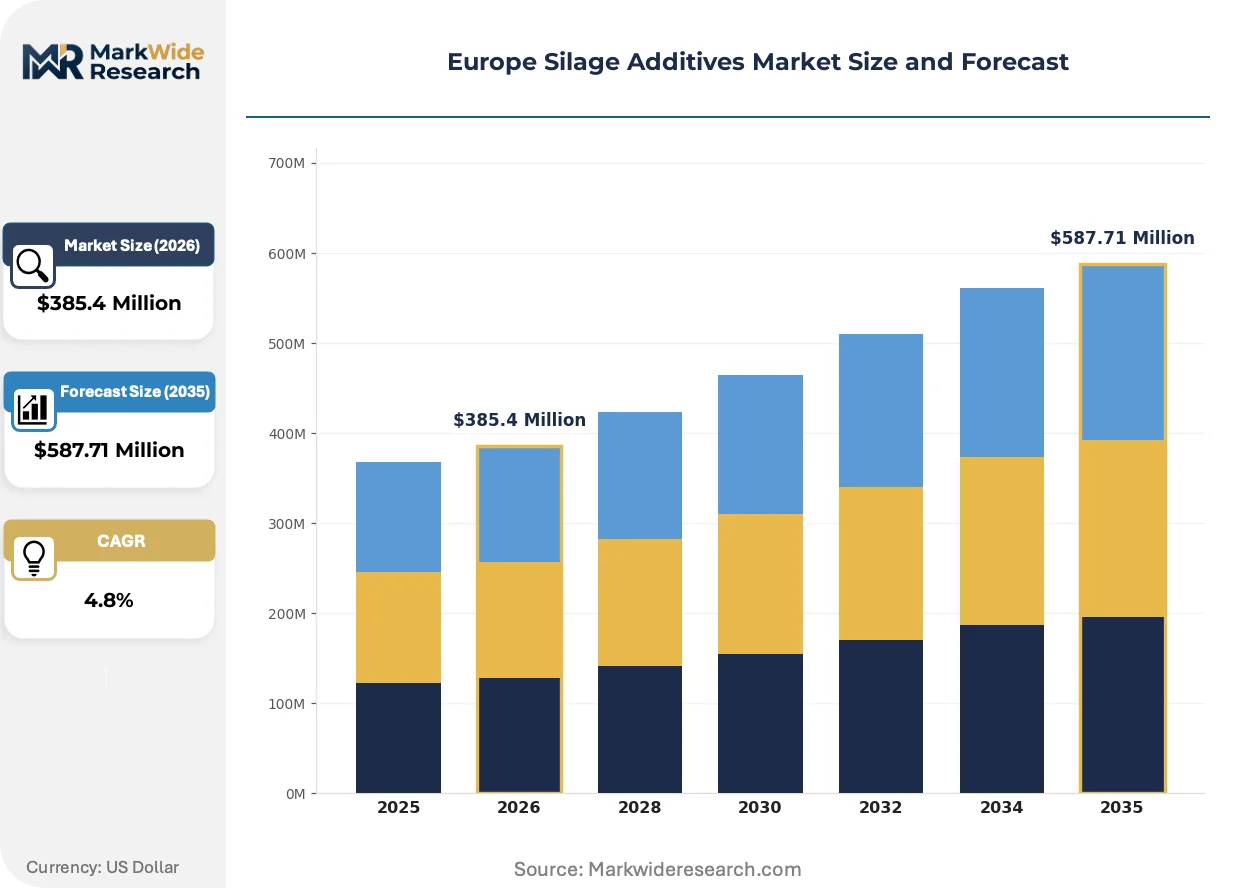
Market Dynamics
The EU Green Deal's methane reduction mandates are restructuring farm subsidy eligibility across Northern European dairy belts, forcing cooperative buyers to demand verified inoculant performance data as a procurement prerequisite.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of synthetic refrigerants in on-farm storage is accelerating biological preserv adoption as dairy processors seek temperature-stable feed inputs.
- Precision fermentation infrastructure:French cooperatives are scaling anaerobic bioreactor investments that require standardized inoculant dosing protocols for batch consistency.
- High-moisture corn expansion:German and Dutch farms are increasing silage corn acreage under CAP greening requirements, driving homofermentative inoculant pull-through.
Market Restraints
- Raw material concentration:Lactic acid bacteria strain supply concentrates in Belgian and Danish culture collection facilities, creating single-source vulnerability.
- REACH compliance costs:Chemical preserv formulations face extended ECHA safety assessment timelines that delay product refresh cycles.
- Organic acid price volatility:Propionic and formic acid feedstock costs track petrochemical indices, compressing margin predictability for acid-based blends.
Strategic Opportunities
- Poland and Romania underpenetration:Eastern European dairy consolidation lags Western benchmarks, creating first-mover whitespace for microbial inoculant education programs.
- Real-time fermentation monitoring:Pending EU Animal Feed Regulation revisions may mandate sensor-based efficacy verification, opening hardware-software bundling potential.
- Enzyme-inoculant convergence:Fibrolytic enzyme pairing with homofermentative strains is gaining traction in Irish grass silage systems for fiber digestibility gains.
Industry Challenges
- Microbiologist talent scarcity:Strain characterization and stability testing expertise concentrates in legacy culture collection institutions, constraining R&D velocity.
- EMA authorization timelines:Novel microbial strain approvals average 18-24 months, freezing product pipeline visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Silage Additives Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $587.71 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inoculants, Acids, Enzymes, Preservatives Application: Dairy Farms, Beef Cattle, Feedlots, Silage Bags Form: Liquid, Powder, Granular, Tablet End User: Farmers, Cooperative Societies, Feed Manufacturers, Livestock Producers |
| Companies Covered | BASF SE, Lallemand Animal Nutrition, DSM, Volac International Limited, ADDCON, Evonik Industries AG, Novozymes A/S, Schaumann BioEnergy GmbH, ForFarmers NV, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Silage Additives Market Shifts & Advancements
Silage additive formulation is pivoting from commodity preservation chemistry toward precision microbiology, with digital verification layers and biological complexity management becoming core competitive differentiators.
Multi-strain inoculant cocktails incorporating heterofermentative Lactobacillus buchneri alongside standard homofermentative workhorses is unifying aerobic stability and fermentation speed in a single application. Dutch dairy cooperatives are adopting these unified formulations at the fastest clip, compressing the historical trade-off between rapid pH drop and bunk life extension into one product tier.
REACH chemical safety assessments are tightening acid-based preserv pathways, pushing investment toward biological alternatives. ECHA's extended data requirements for formic acid derivatives are forcing reformulation cycles that favor microbial inoculants in high-value dairy applications. Northern European suppliers are responding by accelerating strain library expansion to fill the functional gap.
Dairy procurement officers are consolidating supplier relationships around vendors offering fermentation monitoring dashboards rather than standalone product transactions. This bundled service model is displacing traditional distributor-mediated purchasing in the Netherlands and Denmark, where cooperative buyers demand real-time pH and temperature telemetry as contract conditions.
Europe Silage Additives Market Segmentation
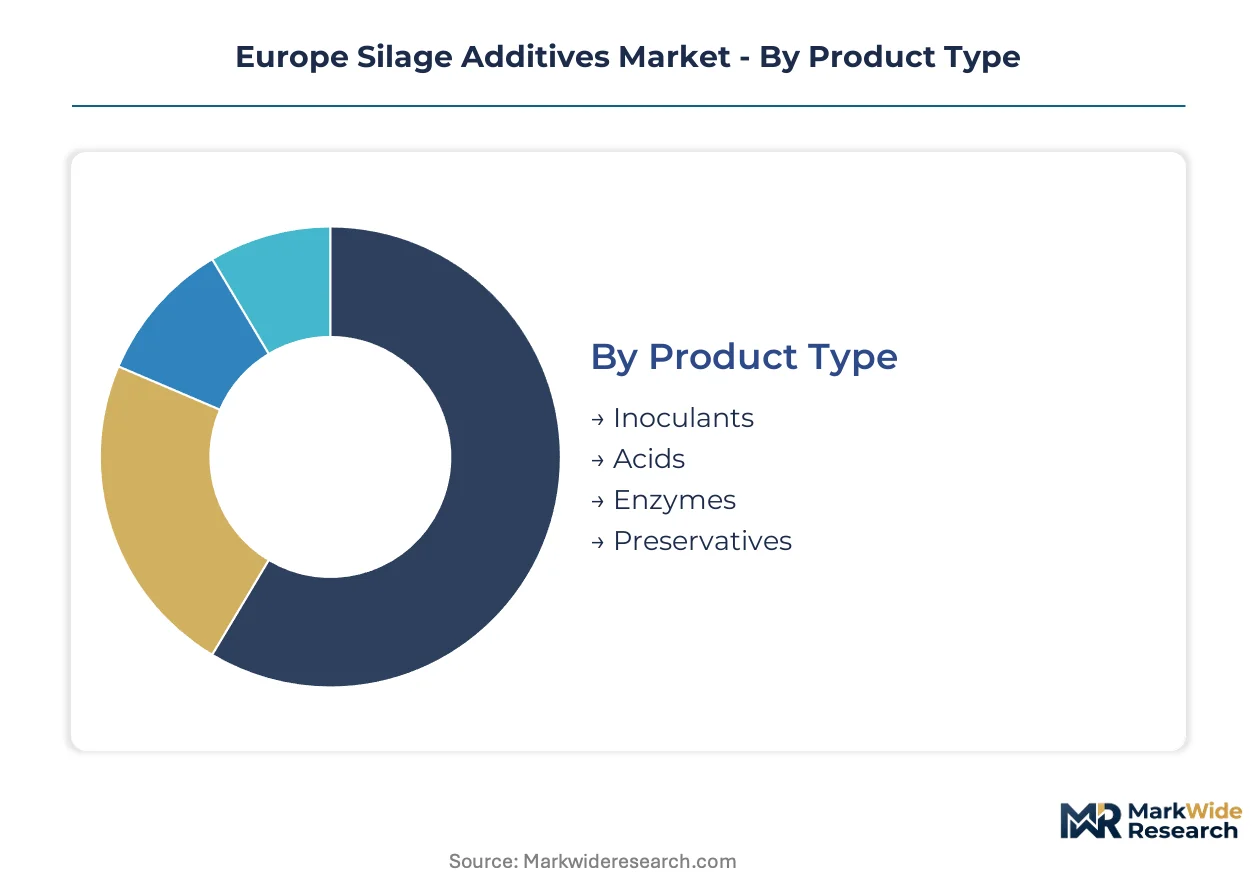
Silage additive purchasing patterns diverge sharply between volume-driven farm operations and precision-focused cooperative buyers. Understanding these splits enables suppliers to align formulation, packaging, and service bundling with distinct technical requirements and procurement workflows.
Product Type:
Microbial inoculants command premium positioning against commodity chemical alternatives, with volume concentration in standardized acid formulations.
- Inoculants:Multi-strain bacterial preparations delivering lactic acid bacteria counts exceeding 100,000 CFU per gram for rapid pH reduction below 4.5 within 48 hours. Dutch and German dairy cooperatives are consolidating procurement around vendors offering fermentation monitoring dashboards alongside homofermentative performance guarantees.
- Acids:Propionic, formic, and benzoic acid blends providing chemical preservation through direct pH suppression and mold inhibition. Irish beef cattle operations continue favoring acid-based treatments for cost predictability amid volatile petrochemical feedstock pricing.
- Enzymes:Fibrolytic preparations targeting cellulose and hemicellulose breakdown to improve fiber digestibility in grass silage systems.
- Preservatives:Synthetic and natural antimicrobial compounds extending aerobic stability during feedout phases.
Mature deployment sits with acid-based formulations across traditional beef operations. Newer deployment is concentrated in multi-strain inoculant cocktails incorporating heterofermentative Lactobacillus buchneri for unified fermentation speed and bunk life extension.
Application:
Dairy farm demand concentrates in high-moisture corn and grass silage systems under EU Green Deal methane reduction mandates, while feedlot applications prioritize cost-efficient spoilage prevention.
- Dairy Farms:Ruminant operations requiring guaranteed nutritional preservation for milk yield optimization. French cooperative sector scaling drives precision fermentation investments with standardized inoculant dosing protocols.
- Beef Cattle:Pasture-based and finishing operations emphasizing dry matter retention and palatability in grass silage systems.
- Feedlots:Intensive finishing operations prioritizing bulk preservation economics over fermentation precision.
- Silage Bags:Flexible storage systems creating distinct additive requirements for anaerobic seal integrity and oxygen exclusion.
Volume leadership belongs to dairy farm applications across Northern European belts. Expansion is climbing fastest in silage bag systems as Eastern European operations adopt flexible storage infrastructure.
Form:
Liquid formulations dominate throughput compatibility with farm-scale applicator systems, though granular alternatives capture feed manufacturer preference for extended shelf stability.
- Liquid:Pump-compatible suspensions enabling uniform distribution through standard spraying equipment. German and Dutch farms favor liquid delivery for high-moisture corn acreage expansion under CAP greening requirements.
- Powder:Dry concentrates requiring reconstitution prior to application, common in smaller operations with intermittent additive use.
- Granular:Free-flowing particulate formulations with 18-24 month stability windows. Belgian feed manufacturers specify granular products for dosing precision in centralized mixing operations.
- Tablet:Unit-dose compressed forms targeting smallholder convenience and transport simplicity.
Liquid deployment holds established position across cooperative procurement networks. Granular adoption is gaining share fastest among feed manufacturers seeking supply chain flexibility.
End User:
Procurement authority concentrates in cooperative societies with centralized technical specification, while independent farmers retain price sensitivity and brand fragmentation.
- Farmers:Individual operators selecting additives through distributor channels with variable technical support. Polish and Romanian dairy consolidation lags Western benchmarks, creating education program whitespace.
- Cooperative Societies:Member-owned aggregators dictating standardized additive specifications across hundreds of farms. Netherlands and Denmark lead cooperative buyer consolidation around bundled fermentation monitoring services.
- Feed Manufacturers:Industrial compounders integrating silage additives into total mixed ration formulations.
- Livestock Producers:Vertically integrated operations controlling forage production through finished animal output.
Established purchasing patterns center on farmer-level distributor relationships. Cooperative society procurement is displacing traditional channels fastest in Denmark and the Netherlands through telemetry-linked contract structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Northern European dairy belts where cooperative procurement power drives standardization, while Eastern European markets remain fragmented with education-dependent adoption curves.
Germany
High-moisture corn expansion under CAP greening requirements pulls homofermentative inoculant volumes through farm-scale applicator networks. REACH compliance timelines from ECHA constrain acid-based preservative refresh cycles. Bavarian dairy cooperatives anchor procurement consolidation around bundled fermentation monitoring services.
France
Precision fermentation infrastructure investments by cooperative societies standardize inoculant dosing protocols for batch consistency. EU Green Deal methane reduction targets bind farm subsidies to verified additive performance data. The Brittany dairy belt scales anaerobic bioreactor capacity requiring telemetry-linked contract structures.
Netherlands
Cooperative buyers displace traditional distributor channels through real-time pH and temperature telemetry as contract conditions. F-Gas Regulation phasedown accelerates biological preserv adoption for temperature-stable feed inputs. Dutch dairy belts adopt multi-strain inoculant cocktails unifying fermentation speed and bunk life extension.
Poland
Eastern European dairy consolidation lags Western benchmarks, creating whitespace for microbial inoculant education programs targeting independent farmers. National agricultural extension services channel EU rural development funds toward silage quality improvement. Masovian and Greater Poland voivodeships lead flexible storage infrastructure adoption.
Belgium
Lactic acid bacteria strain supply concentrates in Belgian culture collection facilities, creating single-source vulnerability for regional formulation networks. EMA feed additive authorization protocols shape product development timelines for novel microbial strains. Flemish feed manufacturers specify granular products for dosing precision in centralized mixing operations.
Europe Silage Additives Market Competitive Landscape
German chemical conglomerates anchor one tier through microbial strain libraries and preservative chemistry; French and Belgian specialists hold differentiated positions in captive yeast production and culture collection services. Market structure tilts toward consolidated supply relationships with cooperative buyers, though independent farmer channels retain fragmentation. Three archetypes dominate: diversified chemical majors with biological portfolios, dedicated animal nutrition specialists with fermentation expertise, and regional feed compounders with distribution density. Competitive moves concentrate on M&A for strain library expansion and strategic partnerships for precision fermentation infrastructure access.
Among diversified chemical majors, BASF SE and Evonik Industries AG exemplify the integrated archetype spanning microbial inoculants through acid-based preservatives. Lallemand Animal Nutrition occupies a specialist position with geographic concentration in French and Belgian production assets. These three anchors represent the competitive spectrum from commodity chemistry through precision microbiology, with cooperative procurement consolidation favoring vendors offering bundled fermentation monitoring capabilities alongside core additive formulations.
| Leading Market Players |
|---|
| BASF SE |
| Lallemand Animal Nutrition |
| DSM |
| Volac International Limited |
| ADDCON |
| Evonik Industries AG |
| Novozymes A/S |
| Schaumann BioEnergy GmbH |
| ForFarmers NV |
| Others |
Supply & Pricing Matrix
Cooperative procurement consolidation across Dutch and Danish dairy belts demands bundled fermentation monitoring services, forcing suppliers to absorb hardware-software integration costs that compress margins on standalone additive formulations. This buyer-driven service bundling concentrates pricing power among vendors with captive telemetry capabilities while fragmenting commodity inoculant suppliers into price-tender competition.
Pricing Analysis
Volume leadership in liquid inoculants for farm-scale applicators runs on thin margins, while granular formulations for Belgian feed manufacturers capture premium pricing through extended shelf stability guarantees. Three-tier pricing structure across premium multi-strain cocktails, standard homofermentative preparations, and economy acid-based preservatives reflects certification grade and after-sales telemetry bundling. Pricing pressure stems from REACH compliance cost absorption for chemical preservative reformulation. Independent farmers in Poland and Romania exhibit highest price sensitivity, whereas cooperative societies in the Netherlands prioritize performance guarantees over unit cost.
Supply Chain Analysis
Lactic acid bacteria strain supply rests on Belgian and Danish culture collection facilities, with propionic acid feedstock drawing from German and Dutch petrochemical networks. Key inputs include homofermentative Lactobacillus strains, heterofermentative L. buchneri cultures, and formic acid derivatives for acid-based blends. Single-source vulnerability in strain supply creates concentration risk for regional formulation networks. Distribution runs through cooperative procurement channels displacing traditional farm-level distributors in Northern Europe, while independent distributor networks persist in Eastern European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's methane reduction mandates construct a cost-of-compliance moat around EMA-authorized microbial strains, elevating incumbents with established culture collections while raising capital barriers for unproven entrants lacking fermentation infrastructure.
For Market Incumbents: Lock in cooperative procurement relationships through exclusive telemetry-linked contract structures that embed real-time pH monitoring as a non-substitutable service layer. Deepen backward integration into strain characterization capabilities to offset microbiologist talent scarcity at legacy culture collection institutions. Prioritize capacity expansion in anaerobic bioreactor infrastructure serving French cooperative precision fermentation scale-up. For New Entrants and Emerging Players: Enter via microbial inoculant education programs targeting independent farmers in Poland and Romania where cooperative consolidation lags Western benchmarks. White space concentrates in silage bag system additive formulations for Masovian and Greater Poland voivodeships adopting flexible storage infrastructure. A technical service-led go-to-market model bypasses entrenched distributor relationships. For Investors and Strategic Acquirers: Re-rating potential sits with dedicated animal nutrition specialists given EU Animal Feed Regulation revisions mandating sensor-based efficacy verification. Long-term viability favors archetypes combining strain library depth with fermentation monitoring hardware capabilities. Watch for EMA authorization timeline acceleration as the inflection signal for pipeline visibility improvement.| Strategic Initiative | Industry Significance |
|---|---|
| Strain Library Expansion | Captures functional gap left by REACH-constrained acid-based preservative pathways. |
| Precision Fermentation Infrastructure Partnership | Secures standardized dosing protocol adoption across French cooperative bioreactor networks. |
| Telemetry-Linked Contract Structuring | Displaces traditional distributor channels in Netherlands and Denmark procurement consolidation. |
| Multi-Strain Cocktail Development | Unifies aerobic stability and fermentation speed for Dutch dairy cooperative demand. |
| Eastern European Education Program Buildout | Establishes first-mover positioning in Poland and Romania underpenetrated markets. |
Research Methodology
Independent corroboration across primary interviews with cooperative procurement officers, feed manufacturer technical directors, and EMA regulatory affairs specialists underwrites the qualitative findings. Secondary validation draws from EU Animal Feed Regulation revision drafts, ECHA REACH assessment timelines, and CAP greening implementation reports. Bottom-up additive volume estimates triangulate against top-down dairy sector forage production data.
Comparable-period anchoring to historical inoculant adoption curves across German high-moisture corn expansion phases informs the projection framework. Segmentation dimensions span product type, application system, formulation state, and end-user procurement authority. CAGRs derive from installed base growth in cooperative bioreactor capacity and F-Gas Regulation phasedown timing. Forecast inputs incorporate EMA authorization pipeline visibility and Eastern European dairy consolidation velocity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EMA timeline acceleration or REACH chemical restriction tightening. Assumptions reflect current EU Green Deal implementation trajectory and cooperative procurement consolidation pace. A small set of named triggers—pending Animal Feed Regulation sensor mandates, strain supply disruption events, and CAP greening requirement revisions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Agricultural Grade Zinc Chemicals Market
Agricultural Chemicals
Global Agricultural Micronutrients Market
Agricultural Chemicals
Global Agricultural Chelates Market
Agricultural Chemicals
South America Soil Treatment Market
Agricultural Chemicals
Seed Binders Market
Agricultural Chemicals
Global Carbofuran Market
Agricultural Chemicals
Foliar Spray Market
Agricultural Chemicals
Agricultural Surfactants Market
Agricultural Chemicals
Gibberellins Market
Agricultural Chemicals
Lawn Care Chemicals Market
Agricultural Chemicals
Africa Feed Antioxidants Market
Agricultural Chemicals
Artificial Humus Market
Agricultural Chemicals
North America Plant Growth Regulators Market
Agricultural Chemicals
North America Castor Oil Market
Agricultural Chemicals
Neonicotinoid Insecticides Market
Agricultural Chemicals
Feed Pelletizing Agents Market