
 South America Soil Treatment Market | 2026-2036
South America Soil Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
South America Soil Treatment Market Analytics
Market Context
Modular service bundling is expanding across South America as suppliers unbundle traditional full-service soil treatment into tiered agronomic packages. BASF SE leverages its crop science division to anchor premium bundled offerings across Brazil's grain belt. Syngenta AG competes through digital soil mapping integration with its treatment protocols. UPL Ltd specializes in bio-based amendment distribution networks throughout the Southern Cone.
Technical Definition and Structural Segments
South America soil treatment encompasses mechanical, chemical, and biological interventions applied to agricultural and non-agricultural soils to modify pH, nutrient availability, contaminant levels, or structural properties, typically involving lime application rates of 2-6 tons per hectare for acidic tropical soils. The primary purpose centers on restoring soil fertility for commercial crop production while remediating degraded lands for regulatory compliance or reclamation. Fertilizers dominate product type revenue due to established distribution infrastructure and recurring seasonal demand across Argentina's Pampas and Brazil's Mato Grosso. Bioremediation technologies capture accelerated interest as ANVISA and national environmental agencies tighten pesticide residue thresholds in groundwater protection zones. Agricultural applications anchor volume demand, though horticulture segments in Chile's Central Valley and Colombia's flower corridors generate disproportionate margin contribution through specialized micronutrient formulations.
Regulatory Framework and Outlook
ANVISA in Brazil and SENASA in Argentina enforce maximum residue limits that directly shape product registration requirements and treatment interval scheduling for export-oriented farms. REACH-aligned chemical standards in Mercosur trade discussions and Chile's evolving soil protection law create compliance complexity that favors suppliers with multi-jurisdictional regulatory expertise. Stakeholders must monitor how Brazil's revised fertilizer registration timelines and emerging carbon credit methodologies for soil carbon sequestration reshape service pricing and portfolio priorities.
Market Dynamics
Modular service bundling is fragmenting traditional full-service soil treatment contracts across South America, as suppliers unbundle agronomic packages into tiered offerings that let soybean and corn growers self-select intervention intensity based on field-level ROI thresholds.
Growth Catalysts
- ANVISA residue thresholds:Brazil's tightened pesticide maximum residue limits in groundwater protection zones force export-oriented farms to adopt precision amendment scheduling that synchronizes treatment intervals with harvest windows.
- Carbon credit methodologies:Emerging soil carbon sequestration certification frameworks in Brazil and Argentina create revenue stacking opportunities where treatment providers monetize verified carbon removals alongside agronomic services.
- Soybean expansion in the Cerrado:Double-cropping intensity across Mato Grosso and Goiás generates recurring lime and gypsum demand that anchors year-round treatment service contracts.
Market Restraints
- Input cost volatility:Ammonium sulfate and phosphoric acid price swings tied to natural gas and sulfur markets compress treatment service margins during planting season peaks.
- Supplier concentration in maritime logistics:Port capacity bottlenecks at Santos and Paranaguá concentrate import dependence for specialized micronutrient formulations.
- Laboratory capacity gaps:Limited accredited soil testing infrastructure in Paraguay's Chaco and Bolivia's Santa Cruz delays precision prescription turnaround times.
Strategic Opportunities
- Colombia's flower corridor penetration:Cut-flower export zones around Bogotá and Medellín remain underserved by specialized micronutrient formulation services calibrated for volcanic-derived soils.
- Drone-based variable-rate application:Convergence of aerial imagery with prescription algorithms enables per-hectare pricing models that displace flat-rate mechanical spreading.
- SENASA bioremediation protocols:Argentina's advancing regulatory acceptance of microbial degradation for pesticide residue cleanup opens service lines for contaminated orchard and vineyard remediation.
Industry Challenges
- Agronomic data integration complexity:Legacy farm management software in Brazil's mid-sized operations lacks API compatibility with modern soil sensor networks, forcing manual data transcription.
- Certification timeline compression:Brazil's revised fertilizer registration timelines at MAPA reduce product launch windows, requiring pre-positioned regulatory dossiers before field trial completion.
Report Scope
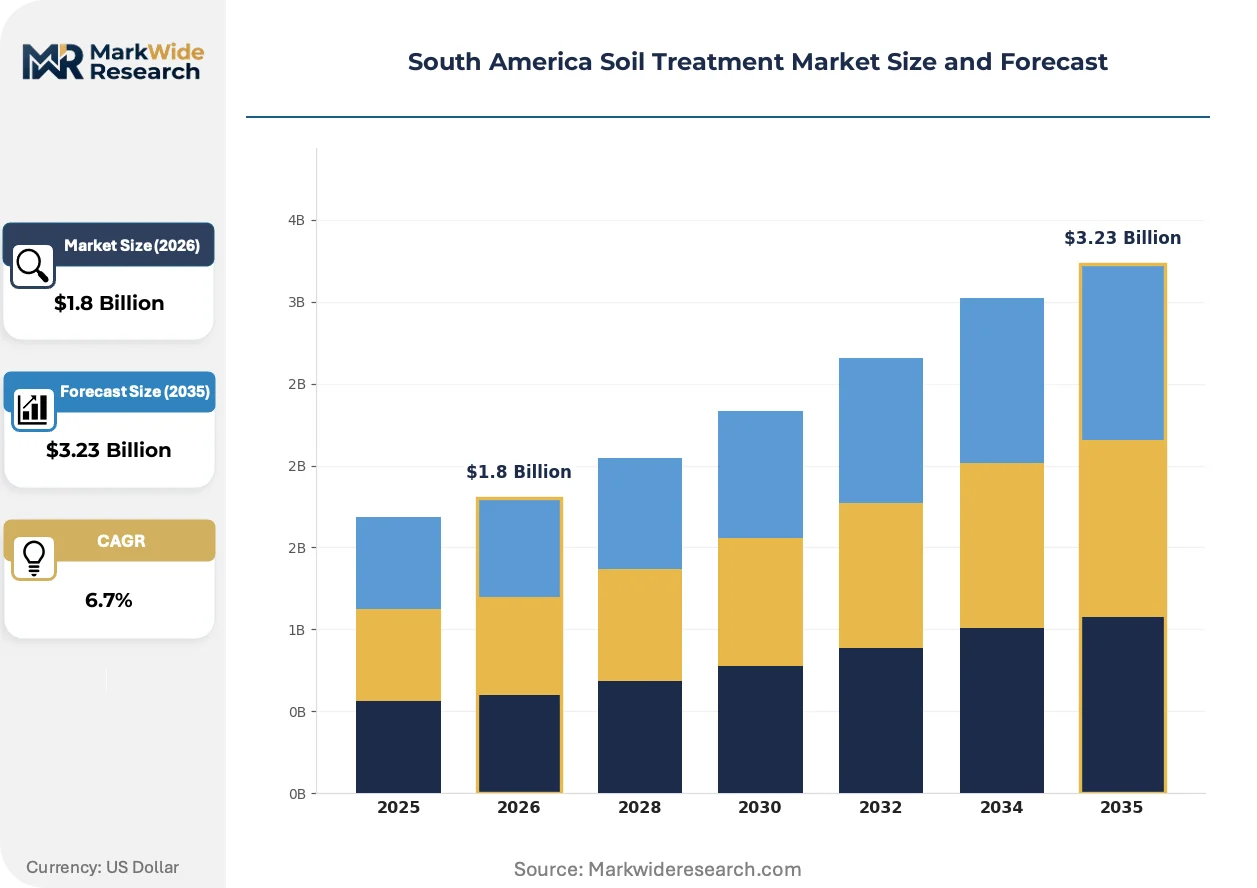
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Soil Treatment Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fertilizers, Soil Amendments, Biochar, Cover Crops Application: Agriculture, Horticulture, Landscaping, Forestry Technologies: Organic Treatment, Chemical Treatment, Bioremediation, Nano-technology End User: Farmers, Agricultural Cooperatives, Government Agencies, Research Institutions |
| Companies Covered | Novozymes Ltd, UPL Ltd, BASF SE, Syngenta AG, Bayer AG, Terral, Visafertil Group, Forth Jardim, Isagro Columbia, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Soil Treatment Market Evolving Landscape
Digital soil mapping and biological amendment protocols are converging to displace blanket-rate chemical application across South America's major grain belts, creating pressure on suppliers to reconfigure service delivery around field-specific data layers rather than zone-averaged prescriptions.
Microbial inoculant formulations targeting phosphorus solubilization and nitrogen fixation are overtaking conventional starter fertilizer programs in Brazil's Cerrado. Large-scale soybean and corn operations in Mato Grosso and Bahia are adopting these biologicals at scale for the 2024-2025 crop cycle. The technology is compressing per-hectare synthetic input costs while requiring suppliers to build cold-chain distribution networks that chemical fertilizers never demanded.
Chile's evolving soil protection law is mandating baseline contamination assessments for agricultural land transfers in the Central Valley. The legislation forces treatment providers to document pre-existing heavy metal and pesticide residue loads before lease or sale completion. Vineyard and orchard operators in the Maipo and Colchagua valleys are responding by integrating remediation clauses into long-term land rental contracts.
Outcome-based service contracts are displacing input-supply agreements across Argentina's Pampas grain belt. Growers now compensate treatment providers based on verified yield response rather than tons of lime or fertilizer applied. The model concentrates in Buenos Aires and Córdoba provinces where satellite-based yield monitoring enables transparent performance benchmarking between service seasons.
South America Soil Treatment Market Segmentation
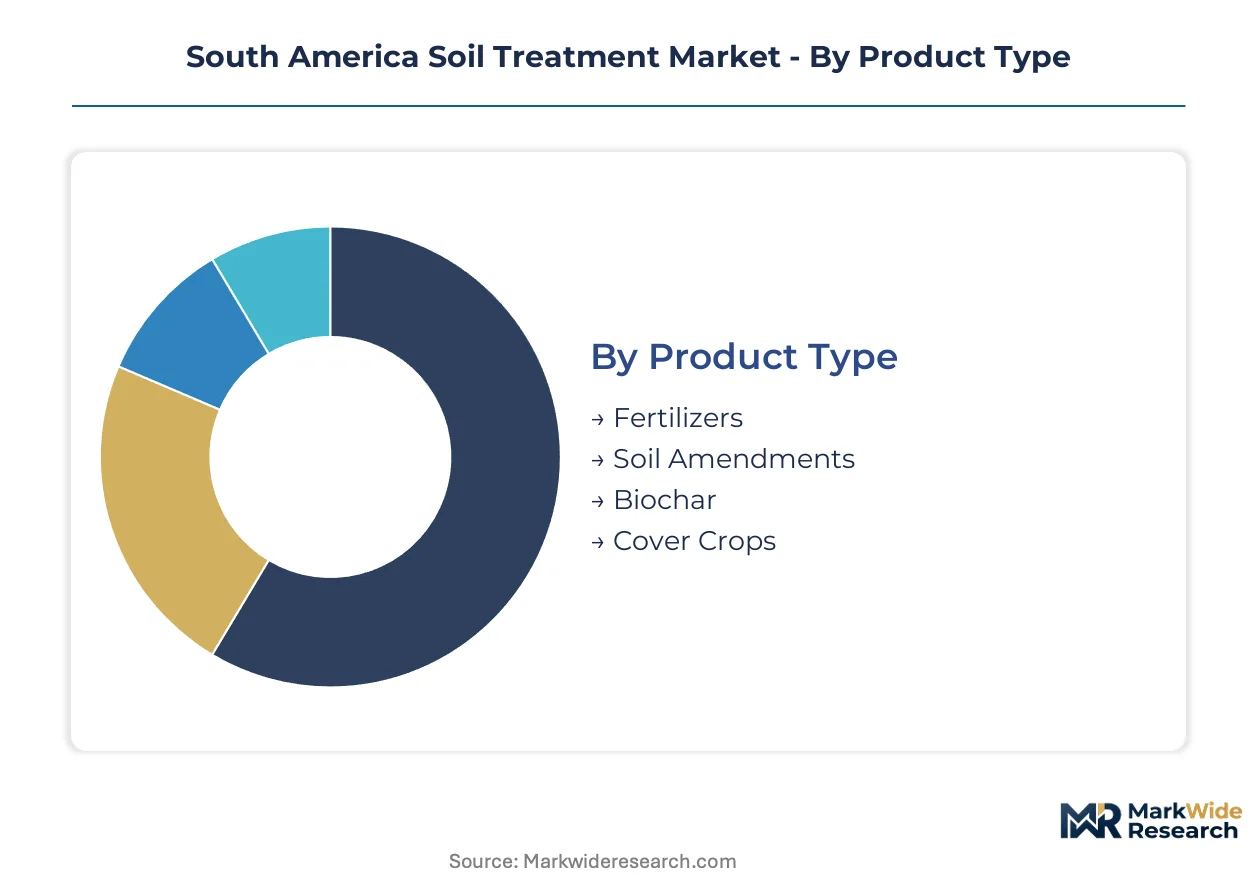
Soil treatment suppliers across South America configure their portfolios around distinct intervention types, crop systems, and customer capabilities. Segmentation clarity enables precise matching of lime rates, amendment formulations, and service intensity to field-specific conditions and buyer procurement sophistication.
Product Type:
Replacement cycles vary sharply across product categories, with annual fertilizer applications contrasting against multi-year soil amendment investments and biochar applications that persist across cropping seasons.
- Fertilizers:Nitrogen-phosphorus-potassium blends and compound formulations dominate commercial volume through established distribution networks in Brazil's Mato Grosso and Argentina's Buenos Aires province. Double-cropped soybean-corn systems in the Cerrado generate recurring seasonal demand that anchors supplier revenue predictability and forward-contracting programs.
- Soil Amendments:Lime and gypsum products correct acidic tropical soils typical of Brazil's central-west, with application rates of 2-6 tons per hectare driving substantial logistics requirements. ANVISA residue thresholds push export-oriented farms toward precision timing that synchronizes amendment windows with harvest and planting schedules.
- Biochar:Pyrolyzed carbon amendments sequester soil carbon while improving water retention in drought-prone zones.
- Cover Crops:Leguminous and grass species deployed as green manure between commercial cropping cycles.
Fertilizers sit at the top of the volume ranking, with biochar climbing the fastest as carbon credit methodologies mature.
Application:
Margin structures diverge across application contexts, with broadacre agriculture optimizing for per-hectare cost efficiency while specialized horticulture segments absorb premium pricing for micronutrient precision.
- Agriculture:Soybean, corn, and wheat production across Brazil's grain belt and Argentina's Pampas consumes lime, gypsum, and NPK formulations at scale. SENASA protocols in Argentina and ANVISA requirements in Brazil shape treatment intervals for export-bound commodity flows.
- Horticulture:Cut-flower corridors around Bogotá and Medellín, plus Chile's Central Valley fruit operations, demand specialized micronutrient formulations calibrated for volcanic-derived soils. Premium pricing reflects batch customization and cold-chain logistics that commodity grain applications rarely require.
- Landscaping:Urban green space maintenance in São Paulo and Santiago generates seasonal demand for rapid-visibility turf treatments.
- Forestry:Eucalyptus and pine plantation establishment in southern Brazil and Chile's Biobío region drives site preparation and ongoing nutrition management.
Agriculture commands the largest absolute volume, with horticulture expanding most quickly on margin contribution.
Technologies:
Technology selection correlates with farm scale and data infrastructure maturity, as biological and precision approaches displace blanket chemical application where sensor networks and prescription algorithms prove viable.
- Organic Treatment:Compost, manure, and green manure applications build soil organic matter in diversified farming systems and certified organic operations. Supply concentration around peri-urban livestock zones creates logistics constraints for remote grain operations.
- Chemical Treatment:Synthetic fertilizers, pH correctors, and pesticide formulations retain dominance through distribution density and immediate efficacy visibility. Input cost volatility in ammonium sulfate and phosphoric acid compresses service margins during planting season demand peaks.
- Bioremediation:Microbial degradation protocols for pesticide residue cleanup gain regulatory traction under SENASA guidelines in Argentina and emerging groundwater protection rules in Brazil. Contaminated orchard and vineyard remediation opens service lines in Mendoza and the Colchagua Valley.
- Nano-technology:Nano-fertilizers and nano-encapsulated amendments target controlled nutrient release with reduced environmental losses.
Chemical treatment maintains volume leadership, with bioremediation gaining share fastest on regulatory tightening.
End User:
Procurement sophistication varies dramatically across end-user categories, from individual farmers managing single-field decisions to government agencies administering watershed-scale programs.
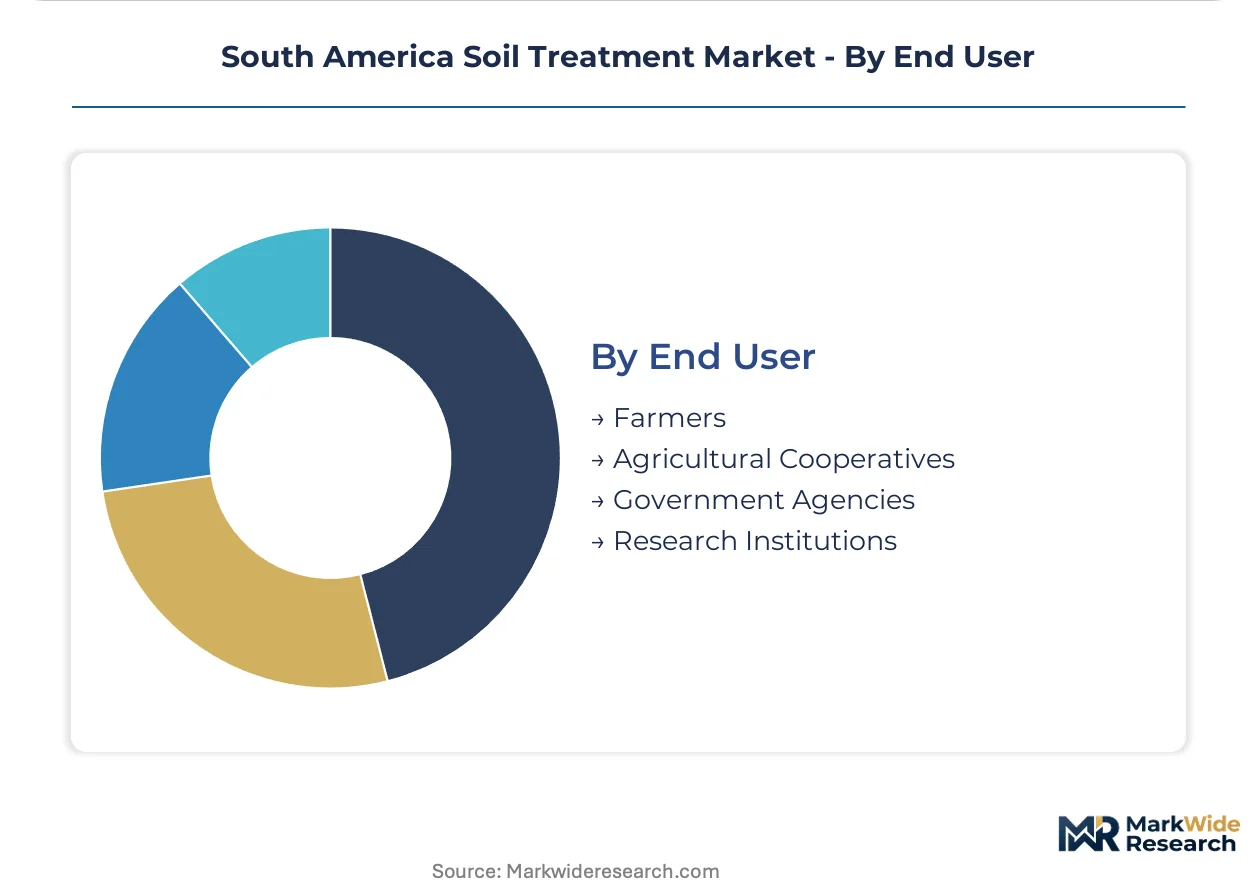
- Farmers:Individual operators and family enterprises across Brazil's Mato Grosso and Argentina's Córdoba province select treatment packages based on field-level ROI thresholds and credit access. Outcome-based contracts that compensate providers on verified yield response concentrate where satellite monitoring enables transparent benchmarking.
- Agricultural Cooperatives:Member-owned enterprises aggregate demand to negotiate volume pricing and shared equipment pools. Co-ops in Rio Grande do Sul and Santa Catarina coordinate lime spreading and fertilizer procurement across thousands of hectares.
- Government Agencies:Federal and state agricultural extension services administer soil recovery programs in degraded pasture zones.
- Research Institutions:Universities and agricultural research centers trial amendment protocols and validate carbon sequestration methodologies.
Farmers represent the largest customer base, with agricultural cooperatives climbing fastest on consolidated procurement scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil pioneered large-scale lime application programs for acidic Cerrado soils during the 1970s agricultural frontier expansion, establishing the technical foundation that now spreads across Southern Cone grain belts. Argentina and Chile subsequently developed specialized protocols for Pampas fertility management and volcanic soil amendment respectively.
Brazil
Double-cropped soybean-corn systems across Mato Grosso and Goiás generate recurring demand for precision lime and gypsum programs. ANVISA's tightened pesticide residue thresholds in groundwater protection zones force export-oriented farms to synchronize treatment intervals with harvest windows. The Rondonópolis corridor concentrates supplier service depots that anchor year-round logistics networks.
Argentina
Wheat and soybean production across Buenos Aires and Córdoba provinces drives seasonal fertilizer procurement at scale. SENASA protocols for maximum residue limits shape product registration requirements and treatment scheduling for export-bound commodity flows. The Rosario grain hub anchors distribution infrastructure for specialized amendment formulations.
Chile
Volcanic-derived soils in the Central Valley demand micronutrient formulations calibrated for low natural fertility and high aluminum content. The country's evolving soil protection law mandates baseline contamination assessments for agricultural land transfers in Maipo and Colchagua valleys. Vineyard and orchard operators integrate remediation clauses into long-term rental contracts.
Colombia
Cut-flower export zones around Bogotá and Medellín generate premium-margin demand for specialized micronutrient services. The national agricultural institute administers soil recovery programs in degraded pasture zones across the eastern plains. Floriculture clusters in Cundinamarca and Antioquia departments absorb batch-customized formulations with cold-chain logistics requirements.
Paraguay
Soybean expansion across the Chaco and eastern regions drives adoption of mechanical soil correction programs. Limited accredited soil testing infrastructure delays precision prescription turnaround times for mid-sized operations. Ciudad del Este serves as a logistics gateway for imported specialized formulations from Brazilian suppliers.
South America Soil Treatment Market Competitive Landscape
Premium-margin players sit above commodity-margin players across service bundling sophistication, with digital integration and biological formulation capabilities commanding pricing power. The supplier base fragments between multinational crop science divisions, regional amendment distributors, and specialized bioremediation service providers. Three archetypes dominate: integrated agronomy platforms, bio-based amendment specialists, and precision application technology vendors. Consolidation pressure manifests through equipment pooling alliances and cross-border distribution partnerships rather than outright acquisition activity.
Among the integrated platform tier, BASF SE and Syngenta AG occupy positions that exemplify premium bundling strategies anchored by crop science divisions. UPL Ltd represents the bio-based distribution archetype with specialized amendment networks throughout the Southern Cone. Novozymes Ltd sits within the biological technology vector, anchoring microbial formulation capabilities that service providers integrate into precision programs.
| Leading Market Players |
|---|
| Novozymes Ltd |
| UPL Ltd |
| BASF SE |
| Syngenta AG |
| Bayer AG |
| Terral |
| Visafertil Group |
| Forth Jardim |
| Isagro Columbia |
| Others |
Value Network & Pricing Analysis
Chile's evolving soil protection law gates qualified supply and premium-tier pricing access, as treatment providers must document baseline contamination assessments before land transfers, creating compliance overhead that only certified operators can absorb while pushing uncertified competitors toward commodity lime and gypsum segments.
Pricing Analysis
Outcome-based contracts calibrated to verified yield response dominate Argentina's Pampas grain belt, with pricing stratifying across premium digital-integrated packages, standard precision amendment programs, and economy mechanical spreading services. Price differentiation hinges on satellite monitoring integration and cold-chain biological handling certification. Cost compression in economy tiers is intensifying because ammonium sulfate and phosphoric acid volatility erodes flat-rate margins. Smallholder farmers in Paraguay's Chaco exhibit highest price sensitivity, while Chilean vineyard operators in the Colchagua Valley absorb premium micronutrient formulations with minimal negotiation.
Supply Chain Analysis
Empty amendment container return flows and spent lime transport backhauls shape logistics economics across Brazil's Mato Grosso corridor, where reverse freight utilization determines depot profitability. Supply concentrates in Brazil, Argentina, and Chile, with Brazilian producers drawing from domestic sulfur deposits and imported phosphoric acid. Maritime bottlenecks at Santos and Paranaguá create single-source vulnerability for specialized micronutrient formulations. Distribution runs through agricultural cooperative networks in Rio Grande do Sul and Santa Catarina, with direct-to-farm delivery displacing traditional distributor tiers for large-scale soybean operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America soil treatment market represents a late-cycle quality story, as double-cropped soybean-corn systems in Brazil's Cerrado shift procurement toward carbon-verified amendment programs that command pricing premiums over conventional inputs.
For Market Incumbents: Anchor defensive positioning through backward integration into cold-chain biological distribution networks, locking out competitors from microbial inoculant segments where temperature-controlled logistics create moats. Accelerate certification investment for ANVISA-aligned residue management protocols before Brazil's MAPA compresses registration timelines further, raising barriers for late entrants. For New Entrants and Emerging Players: Enter via Colombia's cut-flower corridors around Bogotá and Medellín, where volcanic-derived soils and export-grade quality requirements remain underserved by specialized micronutrient formulation services calibrated for floriculture. Target drone-based variable-rate application as the go-to-market angle, displacing flat-rate mechanical spreading with per-hectare precision pricing that mid-sized grain operations in Mato Grosso find accessible. For Investors and Strategic Acquirers: Roll-up economics work for regional amendment distributors with captive logistics networks because fragmented depot infrastructure across Brazil's central-west creates consolidation value through route density optimization. Focus acquisition screening on operators with ANVISA pre-registered product dossiers and established cooperative relationships in Rio Grande do Sul. Monitor Brazil's carbon credit methodology finalization for soil sequestration as the inflection signal that revalues biological amendment portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Credit Certification Program | Enables revenue stacking for Brazilian treatment providers through verified soil sequestration alongside agronomic services. |
| Drone-Based Variable-Rate Application | Displaces flat-rate mechanical spreading with per-hectare precision pricing across Mato Grosso soybean operations. |
| Cold-Chain Biological Distribution | Builds captive logistics networks for microbial inoculants that chemical fertilizers never demanded in Brazil's Cerrado. |
| ANVISA Pre-Registration Investment | Pre-positions regulatory dossiers before MAPA compresses fertilizer launch windows, accelerating product-to-market cycles. |
| Outcome-Based Service Contracting | Aligns provider compensation with satellite-verified yield response in Argentina's Buenos Aires and Córdoba provinces. |
Research Methodology
Direct dialogue with agronomists at Brazilian cooperatives, Argentine export farm managers, Chilean vineyard operators, and Colombian floriculture technical directors grounded qualitative findings, cross-referenced with customs records for lime and fertilizer imports, ANVISA registration databases, MAPA regulatory filings, and SENASA protocol documents. Bottom-up field-level demand estimates triangulated against top-down supplier revenue aggregation across the analysis window.
Segmented outputs for fertilizers, soil amendments, biochar, and cover crops intersected with agricultural, horticulture, landscaping, and forestry applications, with technology splits across organic, chemical, bioremediation, and nano-technology protocols. CAGRs derived from trend extrapolation of double-cropping intensity, ANVISA enforcement trajectory, and emerging carbon methodology adoption curves.
Inputs from cooperative agronomists and vineyard operators were available through the study window; gaps in real-time carbon credit pricing introduce uncertainty bands around biochar adoption forecasts. Practitioners should monitor MAPA registration timeline announcements and SENASA bioremediation protocol expansions for early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Field Marking Paint Market
Agricultural Chemicals
Stored Grain Insecticides Market
Agricultural Chemicals
Europe Silage Additives Market
Agricultural Chemicals
North America Plant Growth Regulators Market
Agricultural Chemicals
Feed Preservatives Market
Agricultural Chemicals
Middle East and Africa Agricultural Pheromones Market
Agricultural Chemicals
Africa Feed Antioxidants Market
Agricultural Chemicals
Global Carbofuran Market
Agricultural Chemicals
Europe Swine Feed Premix Market
Agricultural Chemicals
North America Specialty Animal Feed Additives Market
Agricultural Chemicals
Asia-Pacific Feed Mycotoxin Detoxifiers Market
Agricultural Chemicals
China Castor Oil Market
Agricultural Chemicals
Europe Feed Premix Market
Agricultural Chemicals
Feed Antioxidants Market
Agricultural Chemicals
Global Seed Colorant Market
Agricultural Chemicals
South America Feed Antioxidants Market