
 Plant Growth Regulators Market | 2026-2036
Plant Growth Regulators Market Size, Share, and Industry Trends Forecast 2026-2036
Plant Growth Regulators Market Analysis
REACH is restructuring registration requirements for synthetic plant growth regulators across Europe, forcing reformulation investments that favor established producers with dedicated regulatory affairs teams. BASF SE leverages its integrated agrochemical pipeline to sustain auxin registration advantages across multiple jurisdictions. Syngenta Group anchors its position through deep field trial networks that generate country-specific efficacy data for gibberellin registrations. Bayer AG competes by controlling proprietary delivery systems that improve cytokinin uptake efficiency in high-value fruit crops.
Plant growth regulators comprise synthetic or naturally derived organic compounds that modulate physiological processes such as cell division, elongation, and senescence at concentrations typically measured in parts per million, with auxins and gibberellins representing the most commercially significant chemistries for yield optimization and harvest timing control. Their primary industrial purpose centers on precise manipulation of crop architecture, flowering synchronization, and post-harvest quality retention in intensive production systems. Cytokinin formulations command premium positioning in greenhouse vegetable propagation where rooting speed directly determines facility throughput economics, while ethylene-based products dominate mature fruit ripening applications with thinner margin profiles but higher volume throughput. Liquid formulations absorb disproportionate R&D investment due to compatibility demands with precision irrigation infrastructure, whereas granular products occupy stable positions in broad-acre cereal production where equipment compatibility limits format switching.
The EPA governs residue tolerance setting and ecological risk assessment for plant growth regulators in the United States, while the EU Green Deal's pesticide reduction targets are forcing accelerated biomolecule screening programs that favor microbial fermentation-derived candidates over petrochemical synthetics. China's MEE implements environmental release monitoring that constrains manufacturing site expansion for high-burden chemistries, redirecting capacity toward aqueous formulation technologies with lower volatile organic compound profiles. Stakeholders must monitor evolving pollinator risk assessment protocols, as these emerging standards threaten existing registrations for compounds with demonstrated sublethal bee toxicity effects.
Market Dynamics
REACH restructuring is forcing synthetic plant growth regulator reformulation investments across Europe, compressing margins for smaller producers while established players with dedicated regulatory affairs teams capture re-registration advantages. Specialty greenhouse operators in the Netherlands are accelerating cytokinin applications to compress crop cycling timelines.
Growth Catalysts
- Protected Horticulture Expansion:Shandong Province's rapid protected acreage growth is concentrating demand for precision growth modulation in China's vegetable propagation sector.
- EU Green Deal Acceleration:The Farm to Fork strategy's residue limit tightening is accelerating bio-based formulation approvals, creating first-mover advantages for microbial fermentation-derived candidates.
- Precision Irrigation Compatibility:Liquid formulation R&D investment is rising to meet compatibility demands with drip and fertigation infrastructure in intensive greenhouse systems.
Market Restraints
- Petrochemical Input Volatility:Synthetic auxin and gibberellin production remains tethered to benzene and naphthalene derivative costs, compressing formulation margins during upstream price spikes.
- Pollinator Risk Protocol Uncertainty:Emerging sublethal bee toxicity assessment standards threaten existing registrations for multiple cytokinin and ethylene-based compounds.
- Regulatory Friction from REACH:The European Chemicals Agency's re-registration burden is freezing market entry for mid-scale producers lacking dedicated regulatory affairs infrastructure.
Strategic Opportunities
- Microbial Fermentation Convergence:Combining CRISPR-edited bacterial strains with continuous bioreactor processing is opening cost-parity pathways for bio-identical gibberellin production.
- Underpenetrated Protected Vegetable Sectors:Turkey's expanding greenhouse cluster in Antalya Province offers cytokinin penetration potential where rooting speed economics remain underexploited.
- Direct-to-Grower Digital Channels:E-procurement platforms are disintermediating traditional agrochemical distribution in Brazil's Mato Grosso soybean belt, enabling formulation customization at volume.
Industry Challenges
- Field Trial Talent Scarcity:Country-specific efficacy data generation for gibberellin registrations requires specialized agronomists with multi-season trial design expertise, creating recruitment bottlenecks.
- Legacy Equipment Integration:Granular product manufacturers face friction retrofitting production lines for aqueous formulation technologies with lower volatile organic compound profiles demanded by China's MEE.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant Growth Regulators Market |
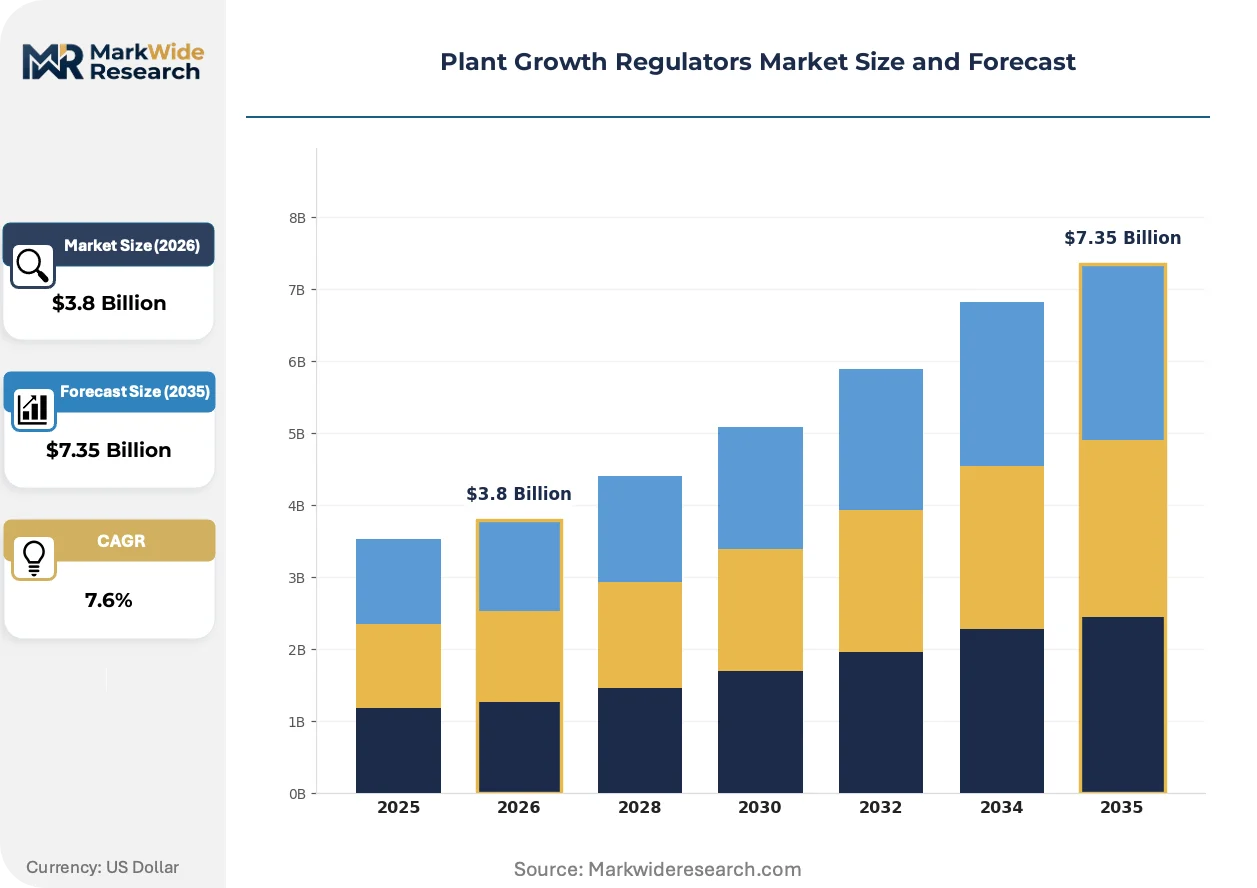
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Auxins, Gibberellins, Cytokinins, Ethylene Application: Horticulture, Agriculture, Turf Management, Forestry End User: Farmers, Nurseries, Greenhouses, Landscaping Services Formulation: Liquid, Powder, Granular, Emulsifiable Concentrate |
| Companies Covered | BASF SE, Syngenta Group, Bayer AG, Corteva Agriscience, FMC Corporation, Nufarm, Sumitomo Chemical Co., Ltd., UPL Limited, Tata Chemicals Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant Growth Regulators Market Emerging Trajectories
Formulation chemistry and delivery mechanism innovation is compressing application windows and enabling precision dosing at scale. Three developments are restructuring competitive positioning across synthetic and bio-based segments.
Encapsulated cytokinin delivery systems are consolidating control over uptake efficiency in high-value fruit crops. Mediterranean citrus propagators are adopting these systems at accelerating rates to synchronize flowering across varietal blocks. The technology is consolidating premium pricing power among producers with proprietary polymer matrix intellectual property.
REACH's 2023 registration deadline restructuring is forcing biomolecule screening program acceleration across European formulation houses. Petrochemical synthetic pipelines are freezing while microbial fermentation-derived candidates receive expedited toxicity review pathways. Greenhouse vegetable propagators in the Netherlands are pre-qualifying bio-based cytokinin suppliers to secure uninterrupted access under tightening residue limits.
Buyer concentration among specialty greenhouse operators is compressing switching cycles and unbundling after-sales technical service from product pricing. Large-scale Dutch and Belgian propagation facilities are consolidating procurement through cooperative purchasing alliances, displacing independent distributor relationships. This concentration is most visible in the Benelux glasshouse cluster where facility throughput economics dominate supplier selection criteria.
Plant Growth Regulators Market Segmentation
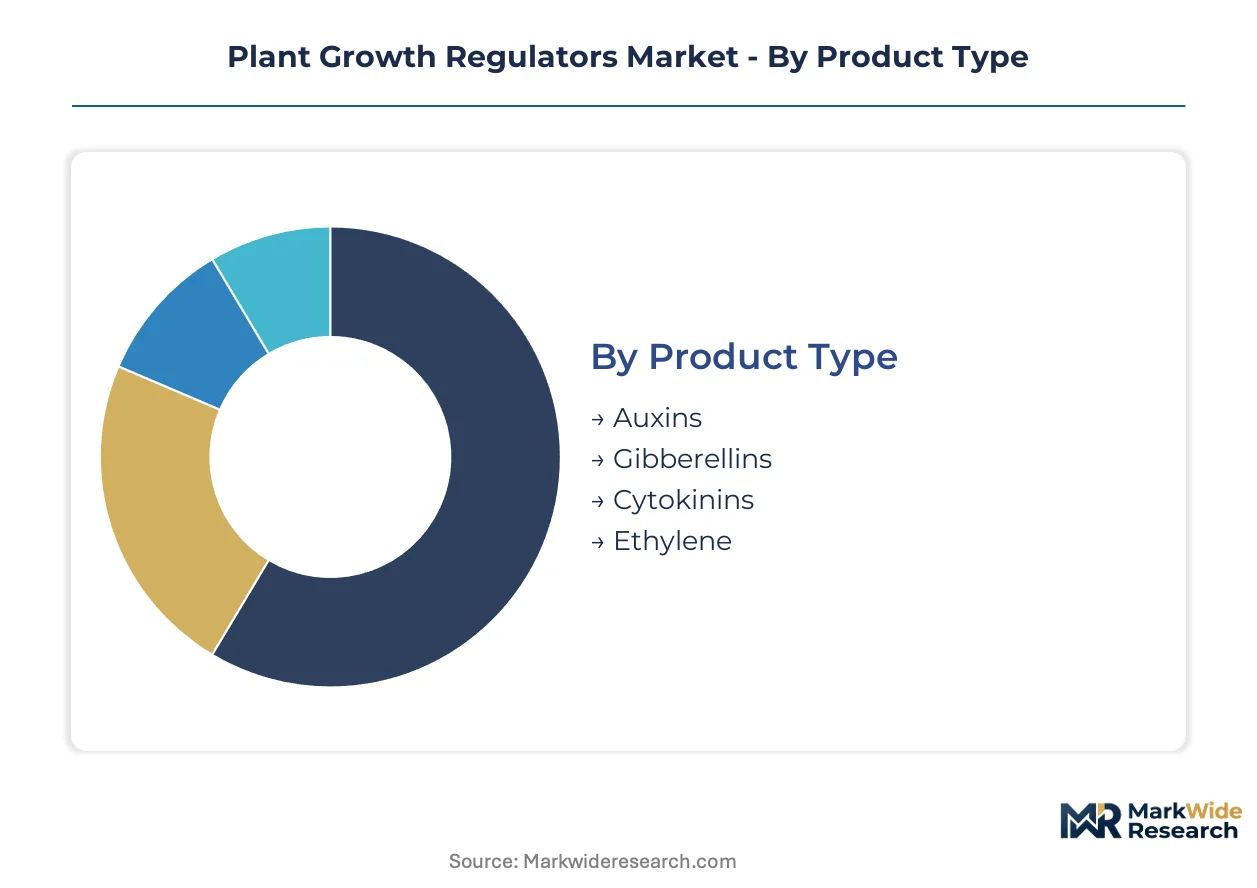
Plant growth regulator procurement hinges on precise matching between compound class, crop system, and application infrastructure. Buyers prioritize formulation compatibility with existing equipment over unit cost, creating segmented demand pockets that resist commoditization.
Product Type:
Technical performance requirements and residue tolerance positioning drive selection across compound classes.
- Auxins:Synthetic naphthaleneacetic acid and indole-3-butyric acid formulations dominate rooting hormone applications. Dutch greenhouse propagators specify auxin concentrations for tomato grafting operations where rooting speed determines facility throughput economics.
- Gibberellins:GA3 and GA4+7 mixtures regulate stem elongation and flowering synchronization in seedless grape production. California table grape growers command premium pricing through harvest timing precision enabled by gibberellin scheduling.
- Cytokinins:Benzyladenine and kinetin formulations command premium positioning in high-value fruit sizing applications.
- Ethylene:Ethephon releases drive uniform ripening in mature fruit handling with thinner margin profiles but higher volume throughput.
Volume sits with auxins; growth tilts toward cytokinins.
Application:
Intensity of growth modulation requirements and value-per-hectare determine adoption depth across crop systems.
- Horticulture:Protected vegetable and ornamental production demands precision growth control at multiple phenological stages. Shandong Province's expanding greenhouse cluster concentrates cytokinin demand for cucumber and pepper propagation.
- Agriculture:Broad-acre cereal and oilseed applications focus on lodging prevention and harvest timing. Brazilian soybean operators in Mato Grosso deploy ethephon for desiccation timing to optimize combine logistics.
- Turf Management:Golf course and sports field maintenance requires growth suppression for mowing frequency reduction.
- Forestry:Plantation establishment uses auxin rooting hormones for cutting propagation in clonal eucalyptus programs.
Revenue concentrates in horticulture; acreage expansion favors agriculture.
End User:
Technical sophistication and procurement scale create distinct service requirements across buyer categories.
- Greenhouses:Controlled-environment operators in the Netherlands and Belgium demand formulation customization for specific cultivar responses. Cooperative purchasing alliances among large-scale propagation facilities displace independent distributor relationships.
- Farmers:Broad-acre producers prioritize equipment compatibility and tank-mix stability over compound novelty. Mato Grosso soybean belt e-procurement platforms enable direct manufacturer relationships.
- Nurseries:Container stock producers balance rooting speed against transplant shock mitigation.
- Landscaping Services:Municipal and commercial maintenance contractors favor ready-to-use formulations minimizing calibration requirements.
Procurement scale clusters with greenhouses; price sensitivity peaks among landscaping services.
Formulation:
Application infrastructure and environmental release constraints dictate format selection.
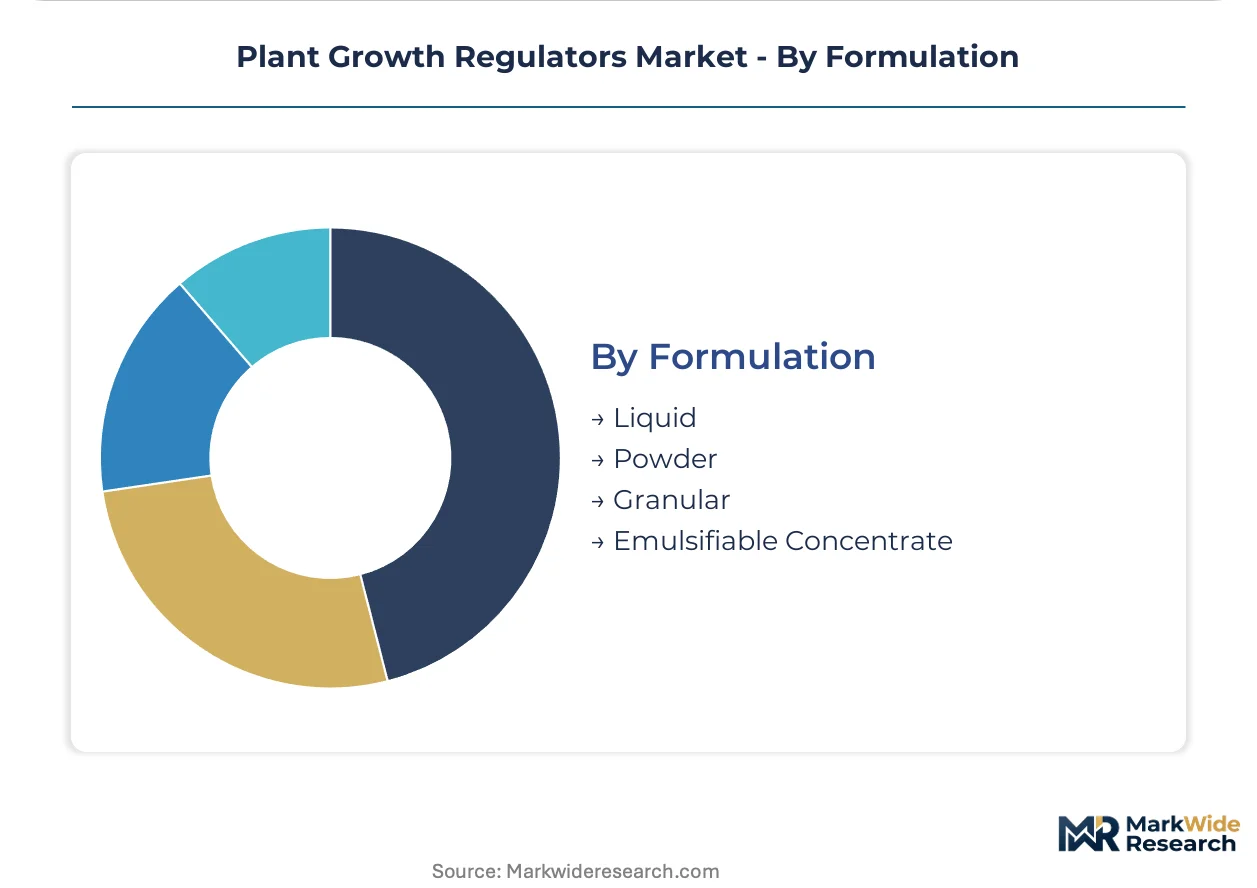
- Liquid:Aqueous solutions and soluble concentrates absorb disproportionate R&D investment for drip and fertigation compatibility. China's MEE environmental release monitoring redirects capacity toward aqueous technologies with lower volatile organic compound profiles.
- Granular:Slow-release formulations occupy stable positions in broad-acre cereal production where equipment compatibility limits format switching. Legacy production line retrofitting creates friction for manufacturers transitioning from solvent-based processes.
- Powder:Wettable powders serve nursery propagation requiring precise dilution control.
- Emulsifiable Concentrate:Oil-based formulations persist in fruit ripening applications requiring cuticular penetration.
Investment flows to liquid; granular retains volume in cereals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in China's Shandong Province and the Netherlands' greenhouse belt, with regulatory divergence between REACH restructuring in Europe and EPA residue protocols in North America fragmenting formulation strategies across jurisdictions.
United States
California table grape growers command premium harvest timing precision through gibberellin scheduling, while Brazilian soybean operators in Mato Grosso deploy ethephon for desiccation timing. EPA residue tolerance setting governs ecological risk assessment. The Pacific Northwest nursery cluster anchors auxin demand for clonal propagation programs.
China
Shandong Province's expanding protected horticulture acreage concentrates cytokinin demand for cucumber and pepper propagation. MEE environmental release monitoring constrains manufacturing site expansion for high-burden chemistries. The Yangtze River Delta greenhouse belt redirects capacity toward aqueous formulation technologies with lower volatile organic compound profiles.
Netherlands
Specialty greenhouse operators accelerate cytokinin applications to compress crop cycling timelines for tomato grafting operations. REACH registration deadline restructuring forces biomolecule screening program acceleration. The Westland glasshouse cluster consolidates procurement through cooperative purchasing alliances displacing independent distributor relationships.
Brazil
Mato Grosso soybean belt e-procurement platforms enable direct manufacturer relationships and formulation customization at volume. ANVISA governs agrochemical registration and residue monitoring. The Cerrado expansion zone drives ethephon demand for pre-harvest desiccation timing to optimize combine logistics.
Turkey
Antalya Province's expanding greenhouse cluster offers cytokinin penetration potential where rooting speed economics remain underexploited. The national agricultural ministry implements residue limit harmonization with EU standards. The Mediterranean coastal belt concentrates protected vegetable propagation infrastructure investment.
Plant Growth Regulators Market Vendor Landscape
European producers anchor the premium formulation tier; Asian specialists hold volume positions in generic active ingredient supply. The vendor base stratifies across integrated agrochemical conglomerates with dedicated regulatory affairs infrastructure and regional formulation houses serving protected horticulture clusters. Three archetypes dominate: integrated pipeline operators controlling proprietary delivery systems, fermentation-derived bio-based specialists, and contract manufacturers serving distributor private labels. Consolidation pressure concentrates in regulatory affairs capabilities and field trial network scale.
Within the integrated pipeline tier, BASF SE, Syngenta Group, and Bayer AG exemplify archetypes visible in the competitive structure. BASF SE represents the integrated agrochemical conglomerate with sustained registration advantages across multiple jurisdictions. Syngenta Group occupies a position anchored through deep field trial networks generating country-specific efficacy data. Bayer AG sits within the proprietary delivery system segment, with positioning tied to uptake efficiency improvements in high-value fruit crops.
| Leading Market Players |
|---|
| BASF SE |
| Syngenta Group |
| Bayer AG |
| Corteva Agriscience |
| FMC Corporation |
| Nufarm |
| Sumitomo Chemical Co., Ltd. |
| UPL Limited |
| Tata Chemicals Ltd. |
| Others |
Supply Flow & Price Mechanics
Microbial fermentation-derived cytokinin production is displacing petrochemical synthesis, simultaneously compressing unit economics for bio-based entrants and fragmenting supply concentration away from legacy naphthalene derivative hubs. This transition redistributes pricing power toward fermentation specialists with continuous bioreactor capabilities while forcing synthetic incumbents to absorb reformulation costs under REACH restructuring.
Pricing Analysis
Volume concentrates in ethephon-based fruit ripening with thinner margin profiles, while cytokinin formulations for greenhouse propagation capture premium positioning through rooting speed economics. Three-tier pricing structure across premium encapsulated delivery systems, standard aqueous formulations, and economy-grade wettable powders reflects formulation complexity and equipment compatibility tiers. Cost compression in synthetic auxins is intensifying because benzene and naphthalene derivative feedstock volatility feeds directly into formulation margins. Landscaping services exhibit peak price sensitivity due to ready-to-use format requirements, whereas Dutch greenhouse cooperatives prioritize throughput optimization over unit cost.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Shanghai, and São Paulo anchor hub-and-spoke patterns for liquid formulation distribution, with granular products flowing through agricultural cooperative networks. Active ingredient manufacturing concentrates in China, India, and Germany, with formulation blending distributed closer to end-use clusters. Raw material dependencies span naphthalene derivatives for synthetic auxins, fermentation feedstocks for bio-based gibberellins, and specialty polymer matrices for encapsulated cytokinin delivery. Single-source vulnerability sits with benzyladenine technical supply from limited fermentation capacity. Distribution runs through agrochemical distributors in mature markets and direct e-procurement platforms in Brazil's Mato Grosso soybean belt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The plant growth regulator market sits in a technology-transition phase, with microbial fermentation platforms replacing petrochemical synthesis as the dominant production methodology for premium cytokinin and gibberellin formulations.
For Market Incumbents: Hedge synthetic registration exposure by accelerating microbial fermentation partnerships before REACH re-registration deadlines freeze petrochemical pipelines. Build captive supply of CRISPR-edited bacterial strains to secure cost-parity pathways for bio-identical gibberellin production. Defensive consolidation around field trial networks generates country-specific efficacy data that mid-scale competitors cannot replicate.
For New Entrants and Emerging Players: Begin with Turkey's Antalya Province greenhouse cluster, where cytokinin penetration for rooting speed economics remains underexploited relative to Dutch benchmarks. Target Brazil's Mato Grosso soybean belt through direct-to-grower digital channels that disintermediate traditional distributor relationships. Anchor initial positioning through formulation customization for precision irrigation compatibility rather than commodity generic supply.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated agrochemical conglomerates seeking regulatory affairs infrastructure and proprietary delivery system intellectual property. Long-term viability favors fermentation-derived bio-based specialists with continuous bioreactor processing capabilities over legacy synthetic operators facing REACH compliance burdens. Watch pollinator risk assessment protocol finalization as the critical inflection signal for registration threat exposure across cytokinin and ethylene-based compound portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Microbial Fermentation Scale-Up | Continuous bioreactor deployment achieves cost parity with synthetic gibberellin production in European facilities. |
| Encapsulated Delivery System Development | Proprietary polymer matrix intellectual property consolidates premium pricing in Mediterranean citrus propagation. |
| REACH Registration Compliance Investment | Dedicated regulatory affairs teams capture re-registration advantages unavailable to mid-scale synthetic producers. |
| Direct E-Procurement Platform Launch | Digital channels in Brazil's Mato Grosso enable formulation customization at volume without distributor intermediation. |
| Field Trial Network Expansion | Country-specific efficacy data generation secures gibberellin registrations in emerging protected horticulture clusters. |
Methodological Framework
Document review covered agrochemical registration databases, EPA tolerance filings, and ECHA REACH submission records, complemented by interviews with formulation R&D directors, greenhouse operations managers, and agricultural cooperative procurement leads. Primary fieldwork engaged regulatory affairs specialists at integrated agrochemical conglomerates and technical agronomists managing multi-season efficacy trials. Secondary validation drew from customs trade data, SEC 10-K filings of listed agrochemical producers, and national agricultural ministry statistics. Bottom-up demand modeling across crop systems and top-down supply capacity assessment were triangulated against manufacturer production disclosures.
Segment-level value and volume trajectories were generated through multi-factor modeling across compound class, formulation type, application intensity, and regional regulatory cluster dimensions. CAGRs were derived from fitted growth curves incorporating protected horticulture acreage expansion rates, residue limit tightening schedules, and equipment compatibility transition timelines. Industry-specific forecast inputs included Shandong Province greenhouse construction permits, Dutch cooperative purchasing alliance procurement patterns, and Brazil soybean belt e-procurement platform transaction volumes.
Underlying measurement precision varies by segment; liquid formulation demand in intensive greenhouse systems carries tighter precision than granular product volumes in broad-acre cereals where equipment switching friction obscures adoption timing. Forecasts reflect assumptions around REACH implementation pacing, pollinator risk protocol finalization, and microbial fermentation yield improvement curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
US Home and Garden Fungicides Market
Agricultural Chemicals
South America Feed Minerals Market
Agricultural Chemicals
Poultry Feed Premix Market
Agricultural Chemicals
United States Feed Enzymes Market
Agricultural Chemicals
Middle East Feed Enzymes Market
Agricultural Chemicals
North America Herbicide Market
Agricultural Chemicals
Europe Feed Enzymes Market
Agricultural Chemicals
Paclobutrazol Market
Agricultural Chemicals
Soilless Substrate-Specific Fertility Solution Market
Agricultural Chemicals
Global Agricultural Colorants Market
Agricultural Chemicals
Organic Bromide Market
Agricultural Chemicals
Stored Grain Insecticides Market
Agricultural Chemicals
Poultry Premix Market
Agricultural Chemicals
Glyphosate Herbicide Market
Agricultural Chemicals
Global Agricultural Chelates Market
Agricultural Chemicals
India Phosphate Rich Organic Manure (PROM) Market