
 Strobilurin Fungicide Market | 2026-2036
Strobilurin Fungicide Market Size, Share, and Industry Trends Forecast 2026-2036
Strobilurin Fungicide Market Insights
Aftermarket service revenue from resistance management advisory programs is rewriting how value gets captured downstream from basic chemical sales. BASF leverages its global field-station network to anchor premium pricing through localized pathogen monitoring. Syngenta competes by bundling strobilurin seed treatments with digital agronomy platforms. FMC Corporation differentiates through proprietary formulation chemistry that extends residual activity in high-rainfall zones.
Strobilurin fungicides are synthetic analogs of the natural antibiotic strobilurin A, operating through mitochondrial respiration inhibition at the Qo site of cytochrome bc1 complex with application rates typically ranging from 100 to 500 grams active ingredient per hectare; their primary commercial purpose is broad-spectrum control of Ascomycete and Basidiomycete pathogens in high-value row crops. Azoxystrobin occupies the largest volume position due to its systemic mobility and early-entry patent expiry, while suspension concentrate formulations are gaining fastest as drift-reduction policies tighten and farmers seek tank-mix compatibility. Pyraclostrobin leads margin pools in turf management where aesthetic thresholds justify premium pricing.
The EPA's Endangered Species Act consultation requirements for pesticide registration are lengthening approval timelines for new strobilurin actives, while REACH compliance in Europe forces reformulation away from certain co-formulants. Brazil's national health surveillance agency, ANVISA, maintains residue tolerance schedules that directly shape export-oriented spraying calendars for soybean and corn growers. Stakeholders must monitor emerging pathogen resistance maps to decide when to rotate strobilurins with succinate dehydrogenase inhibitors.
Market Dynamics
Resistance management protocols are restructuring how value flows through the strobilurin value chain, with advisory services now commanding premium positioning alongside basic chemical sales. Field-station networks and digital agronomy platforms compete for farmer loyalty as pathogen monitoring becomes a core differentiator.
Growth Catalysts
- EU Sustainable Use of Pesticides Regulation:Tightening residue limits accelerate demand for low-dose suspension concentrate formulations that reduce environmental loading while maintaining efficacy.
- Asian soybean rust pressure:Brazil's Cerrado region drives volume expansion as farmers deploy strobilurins as foundation chemistry in resistance-rotation programs.
- Drift-reduction policies:Suspension concentrate technology gains regulatory preference across multiple jurisdictions, favoring tank-mix compatibility and operator safety.
Market Restraints
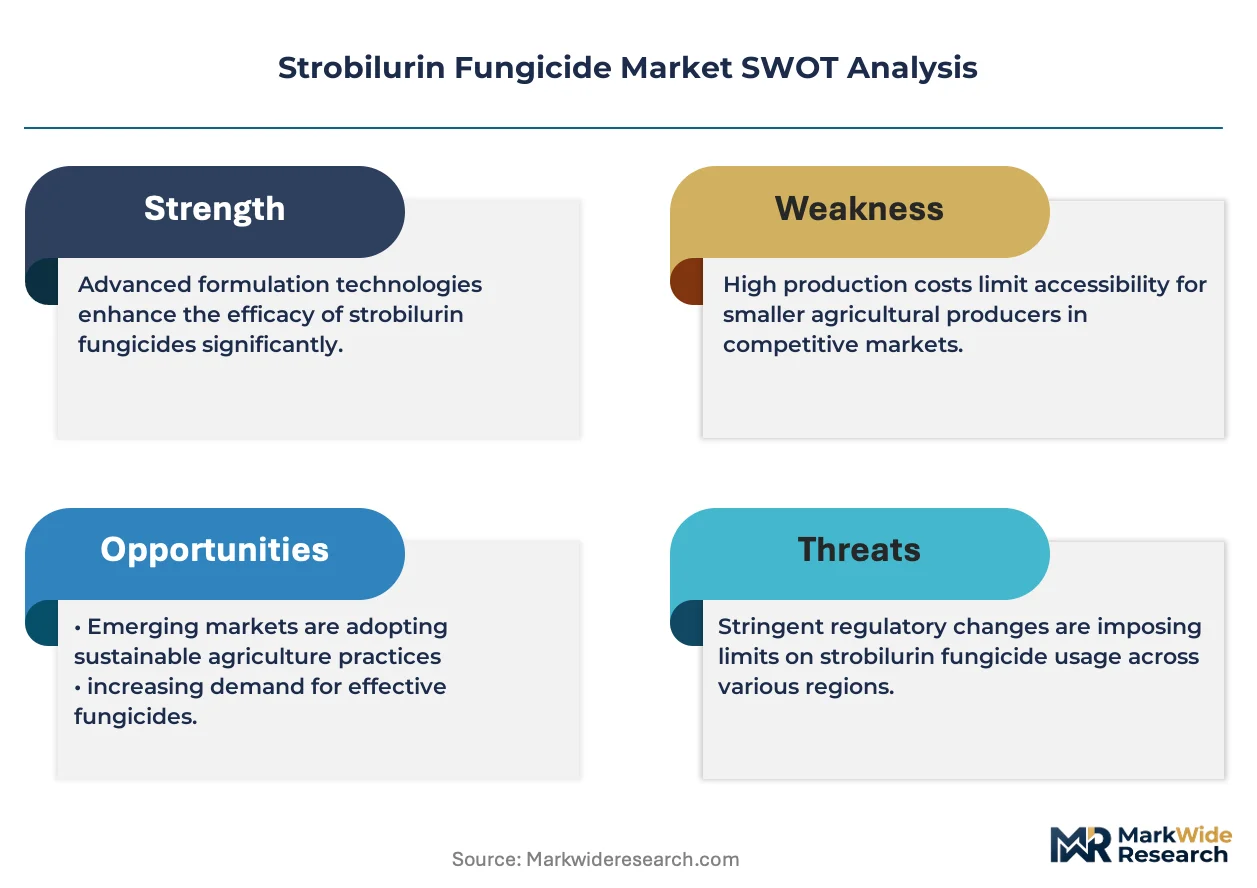
- Active ingredient cost volatility:Petrochemical feedstock fluctuations and specialized intermediate supply concentration in China create margin pressure for formulators.
- Pathogen resistance accumulation:Widespread historical use of azoxystrobin and related analogs compresses effective product lifecycles and accelerates rotation requirements.
- EPA Endangered Species Act consultation:Lengthening registration timelines for new strobilurin actives delays pipeline commercialization and extends payback periods for R&D investment.
Strategic Opportunities
- Seed treatment convergence:Bundling strobilurin chemistry with biological inoculants creates differentiated early-season protection packages for row crop growers.
- Turf management premiumization:Aesthetic thresholds in golf course and ornamental segments justify higher-margin positioning for residual-activity formulations.
- Digital agronomy integration:Sensor-based pathogen monitoring and predictive spraying algorithms enable outcome-based pricing models for advisory services.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in suspension concentrate stability and co-formulant compatibility limits rapid product development cycles.
- REACH compliance reconfiguration:European co-formulant restrictions force costly reformulation of established products without patent protection for modified compositions.
- Multi-site resistance monitoring:Coordinated field surveillance across disparate geographies demands sustained investment in diagnostic infrastructure and data standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Strobilurin Fungicide Market |
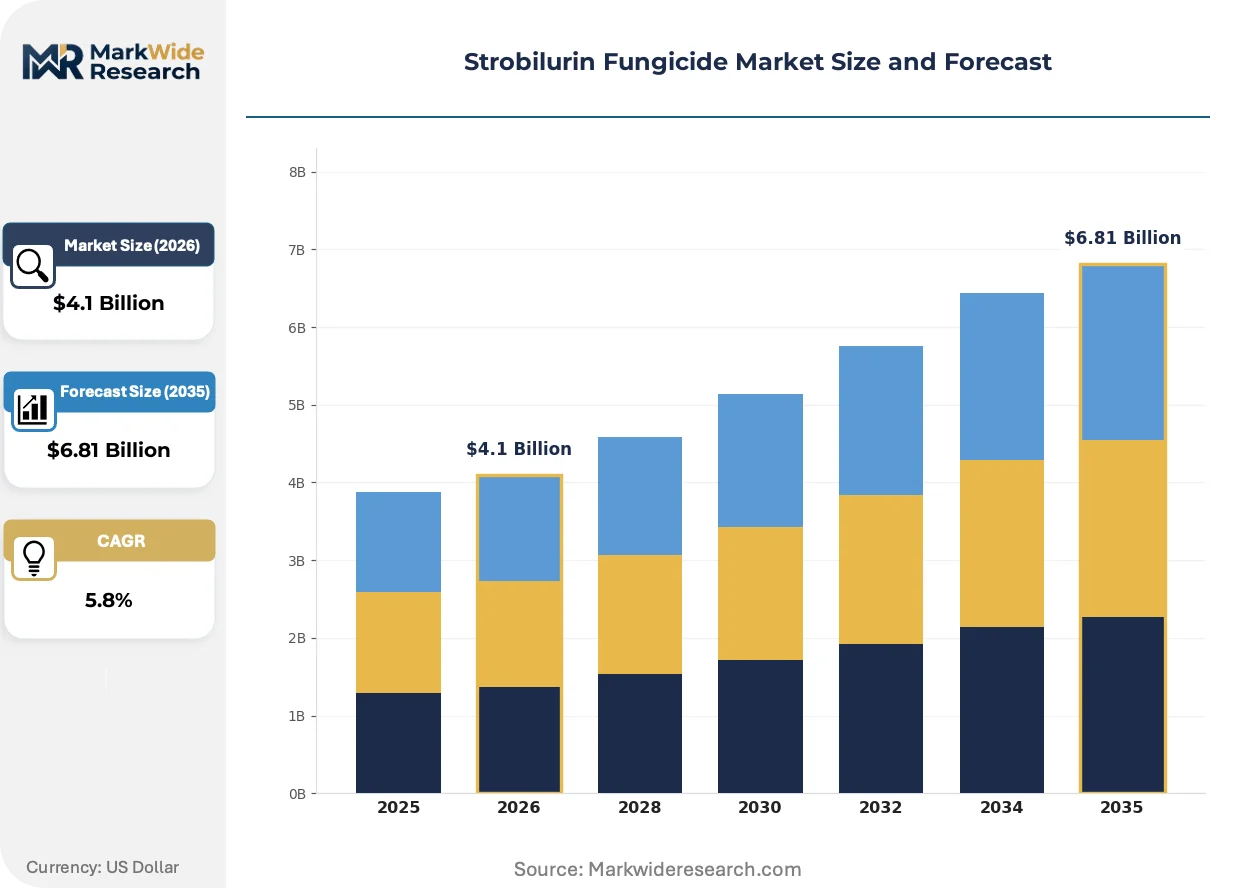
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Azoxystrobin, Pyraclostrobin, Trifloxystrobin, Kresoxim-methyl Application: Crop Protection, Turf Management, Ornamentals, Seed Treatment Formulation: Granules, Liquids, Wettable Powder, Suspension Concentrate End User: Agricultural Producers, Lawn Care Companies, Greenhouses, Distributors |
| Companies Covered | BASF, Syngenta, Bayer Group, Corteva, FMC Corporation, UPL, Sumitomo Chemical Co., Ltd., Nufarm Limited, Limin Group Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Strobilurin Fungicide Market Trends and Innovations
Formulation chemistry and digital delivery systems are converging to redefine how fungicide value is captured and measured in field applications. Three developments dominate this transformation.
Nano-dispersion suspension concentrate technology is rendering obsolete conventional emulsifiable concentrate formulations in high-rainfall zones. Large-scale mechanized operators in Brazil's Mato Grosso state adopt these systems fastest, prioritizing rainfastness and reduced drift liability. The shift compresses demand for solvent-based delivery vehicles and redirects formulation R&D toward aqueous stability engineering.
REACH compliance deadlines in Europe are forcing systematic replacement of certain solvent co-formulants and surfactant packages. Formulators face dual-track development to maintain product registrations while preserving biological performance. High-value specialty crop segments absorb initial cost premiums as manufacturers pass through reformulation expenses.
Subscription-based resistance monitoring services are displacing transactional chemical purchasing in progressive soybean and corn operations. Agronomy platforms bundle pathogen surveillance with automated spray timing recommendations, capturing recurring revenue streams. This model concentrates fastest among export-oriented growers in Brazil who must document residue compliance for European buyers.
Strobilurin Fungicide Market Segmentation
Strobilurin fungicide purchasing patterns diverge sharply across user types, with advisory service intensity determining margin capture. Formulation choices and application contexts reshape how manufacturers structure field support and technical service investments.
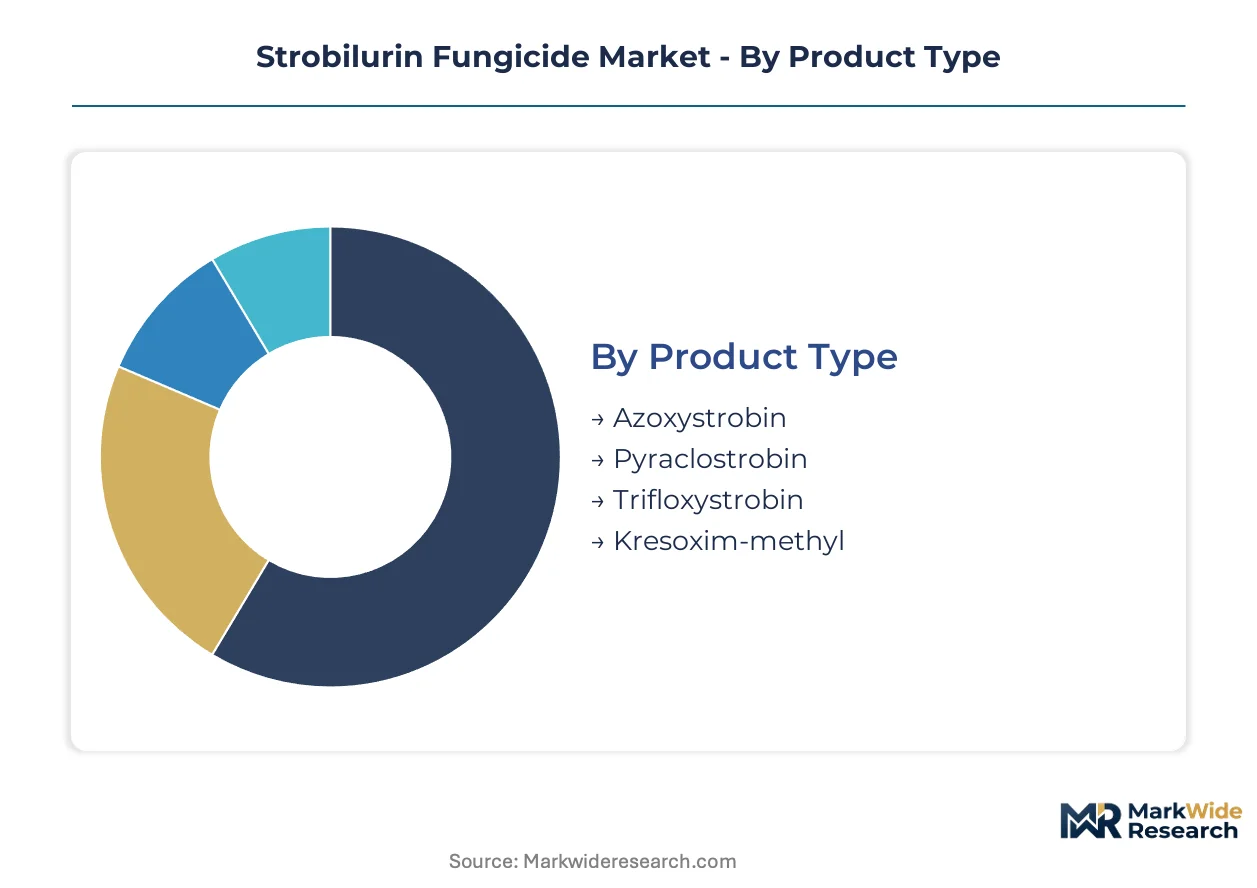
Product Type:
After-sales service intensity peaks with systemic actives requiring resistance monitoring protocols and spray timing optimization.
- Azoxystrobin:Systemic mobility enables phloem and xylem translocation for protective and curative applications. Brazilian soybean operations in Mato Grosso deploy this chemistry as a resistance-rotation foundation; EPA registration timelines and generic competition compress premium pricing windows.
- Pyraclostrobin:Superior leaf surface retention and mesostemic activity deliver extended residual control. Turf management segments in the United States absorb premium positioning where aesthetic thresholds justify higher input costs; drift-reduction policies favor low-volatility formulations.
- Trifloxystrobin:Rapid cuticular penetration and rainfastness suit high-rainfall cropping zones. European cereal growers under REACH compliance pressure favor this active for reduced-rate application programs.
- Kresoxim-methyl:Vapor-phase activity provides secondary redistribution across leaf surfaces. Ornamental producers in controlled-environment agriculture value its fumigant-like coverage for dense canopy penetration.
Azoxystrobin holds the largest share; momentum sits with pyraclostrobin in premium turf segments.
Application:
Cost tier stratification separates commodity row crop deployment from high-margin specialty segments requiring technical support.
- Crop Protection:Foliar sprays on soybean, corn, wheat, and rice constitute volume demand. Brazil's Cerrado region anchors expansion as Asian soybean rust pressure intensifies; ANVISA residue schedules shape export-oriented spraying calendars.
- Turf Management:Golf courses and sports fields command formulation premiums for visual uniformity. United States lawn care contractors bundle strobilurin applications with soil health services; aesthetic thresholds resist price elasticity.
- Ornamentals:Greenhouse and nursery operations prioritize worker re-entry intervals and phytotoxicity margins. European ornamental producers under EU Sustainable Use of Pesticides Regulation face tightening dose restrictions.
- Seed Treatment:Early-season protection against soil-borne pathogens reduces foliar spray frequency. Large-scale mechanized farms in Brazil's Mato Grosso state adopt seed-applied strobilurins for operational efficiency; digital agronomy platforms bundle monitoring with treatment recommendations.
Crop protection dominates volume; seed treatment climbs the fastest on precision agriculture integration.
Formulation:
Volume concentration in suspension concentrate technology reflects drift-reduction policy convergence across multiple jurisdictions.
- Suspension Concentrate:Aqueous nano-dispersion systems reduce drift liability and improve tank-mix compatibility. Brazilian large-scale operators prioritize rainfastness; REACH compliance deadlines in Europe accelerate solvent replacement.
- Liquids:Emulsifiable concentrate formulations retain share in established product lines. Reformulation costs pressure margin structures as co-formulant restrictions multiply.
- Wettable Powder:Solid carrier systems suit remote storage and extended shelf-life requirements. Smaller agricultural producers in developing markets favor packaging simplicity.
- Granules:Controlled-release matrices extend residual activity in high-leaching environments. Turf management applications absorb premium positioning for season-long protection.
Suspension concentrate holds the largest share; granules gain share fastest in premium turf segments.
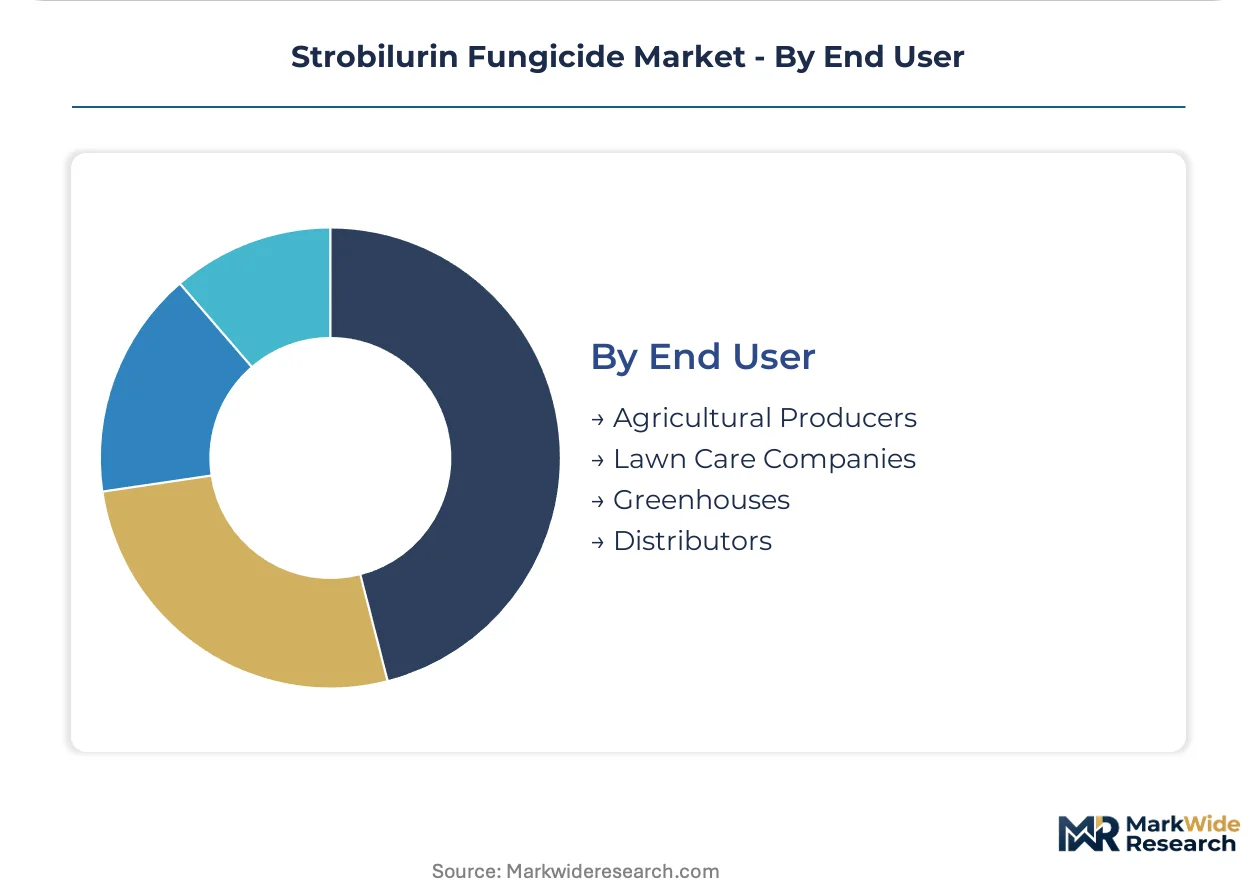
End User:
Customer type determines service model intensity, from distributor technical support to direct-to-farm digital advisory platforms.
- Agricultural Producers:Row crop farmers purchase through cooperative channels and direct manufacturer relationships. Brazilian soybean growers subscribe to resistance monitoring services; documentation requirements for European export markets drive platform adoption.
- Distributors:Wholesale and retail channels manage inventory and localized technical support. Formulation chemist scarcity limits rapid product development for private-label offerings.
- Lawn Care Companies:Professional applicators demand consistent performance across variable weather windows. United States contractors bundle strobilurin treatments with irrigation management.
- Greenhouses:Controlled-environment operators prioritize worker safety and re-entry interval compliance. European ornamental producers navigate ECHA co-formulant restrictions.
Agricultural producers command the largest share; distributors expand most quickly on advisory service bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between export-oriented soybean operations and domestic-focused cereal systems. Brazil's Cerrado farmers deploy strobilurins as resistance-rotation anchors, while European cereal growers prioritize reduced-rate programs under tightening residue regimes.
Brazil
Asian soybean rust pressure drives intensive strobilurin rotation in Mato Grosso's mechanized farms. ANVISA residue tolerance schedules directly shape export-oriented spraying calendars for European-bound soybean shipments. Large-scale operators in the Cerrado cluster adopt suspension concentrate formulations for drift compliance and tank-mix flexibility.
United States
Turf management segments absorb premium pyraclostrobin formulations where aesthetic thresholds resist price elasticity. EPA Endangered Species Act consultation requirements lengthen registration timelines for new actives, compressing premium pricing windows for early entrants. Midwest corn-soybean belt distributors bundle strobilurin seed treatments with digital agronomy platforms.
Germany
REACH compliance deadlines force systematic replacement of solvent co-formulants in established strobilurin product lines. ECHA restrictions on specific surfactant packages redirect formulation R&D toward aqueous stability engineering. Bavarian cereal growers under EU Sustainable Use of Pesticides Regulation favor trifloxystrobin for reduced-rate application programs.
China
Specialized intermediate supply concentration creates feedstock cost volatility for global strobilurin formulators. The country's national chemical regulator maintains registration requirements that shape export-oriented manufacturing standards. Shandong Province chemical clusters supply key building blocks for azoxystrobin and pyraclostrobin synthesis.
India
Rice and wheat protection programs drive volume demand for cost-optimized strobilurin formulations. FSSAI residue monitoring for food grains shapes domestic spraying calendars and export compliance documentation. Maharashtra's cooperative distribution channels anchor technical service intensity for smallholder advisory programs.
Strobilurin Fungicide Market Competitive Landscape
Capability concentration sits with integrated agrochemical conglomerates; scale advantage sits with broad-portfolio multinationals. The market structure consolidates around patent-era innovators and post-patent generic formulators, with formulation chemistry expertise serving as the primary differentiation vector. Three archetypes dominate: field-station network operators, digital platform bundlers, and proprietary formulation specialists. Competitive moves concentrate on resistance monitoring service integration and nano-dispersion formulation licensing.
Among integrated German chemical conglomerates, BASF anchors premium positioning through localized pathogen surveillance infrastructure. Swiss agrochemical specialists Syngenta occupy the digital convergence tier, bundling chemistry with predictive agronomy platforms. At the formulation-differentiation end, FMC Corporation exemplifies proprietary rainfastness technology for high-rainfall zones. These three represent distinct value-capture strategies: service-anchored pricing, platform-recurring revenue, and performance-premium chemistry.
| Leading Market Players |
|---|
| BASF |
| Syngenta |
| Bayer Group |
| Corteva |
| FMC Corporation |
| UPL |
| Sumitomo Chemical Co., Ltd. |
| Nufarm Limited |
| Limin Group Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Shandong Province's chemical manufacturing clusters anchor global intermediate supply for azoxystrobin and pyraclostrobin synthesis, with capacity utilization swings directly transmitting into formulation cost structures for downstream agrochemical majors. Petrochemical feedstock volatility and specialized intermediate concentration in China create asymmetric pricing power that favors integrated producers with captive supply arrangements.
Pricing Analysis
Long-term offtake agreements dominate procurement between Brazilian soybean cooperatives and strobilurin formulators, locking in volume commitments against Asian intermediate price swings. Three-tier pricing structure across premium residual-activity formulations, standard suspension concentrates, and economy wettable powders separates turf management contractors from row crop commodity buyers. Cost compression in generic azoxystrobin segments is intensifying because Chinese intermediate oversupply and patent expiry have eroded brand premiums. Agricultural producers in Brazil's Mato Grosso state exhibit highest price sensitivity due to export margin pressures, while United States golf course operators resist elasticity around pyraclostrobin aesthetic thresholds.
Supply Chain Analysis
Contract manufacturing concentration sits with Limin Group and UPL's Indian technical synthesis facilities, supplemented by European formulation tolling at BASF's Ludwigshafen complex. Active pharmaceutical ingredient-grade intermediates draw from Shandong and Jiangsu provinces in China, with acetoacetic ester derivatives and methoxyacrylate building blocks feeding global production networks. Single-source vulnerability concentrates in Chinese specialty chemical clusters subject to environmental compliance shutdowns. Distribution runs through cooperative channels in Brazil, distributor networks in the United States Midwest, and direct manufacturer relationships for large-scale mechanized operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Strobilurin fungicide markets face high-growth disruption from nano-dispersion formulation chemistry and subscription-based resistance monitoring services, with EU REACH compliance deadlines forcing systematic product reformulation across established portfolios.
For Market Incumbents: Insulate premium positioning through backward integration into Chinese intermediate supply and proprietary rainfastness formulation licensing. Anchor field-station pathogen surveillance networks against digital agronomy platform entrants. Defend margin structures by locking Brazilian cooperatives into multi-year resistance monitoring subscriptions before generic competition erodes azoxystrobin pricing. For New Entrants and Emerging Players: India's rice belt underpenetration offers white-space expansion for cost-optimized wettable powder formulations targeting FSSAI-compliant export channels. European ornamental segments under EU Sustainable Use of Pesticides Regulation pressure seek reduced-rate trifloxystrobin alternatives. Seed treatment convergence with biological inoculants provides the most penetrable entry vector for precision agriculture bundling. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors proprietary formulation specialists with aqueous stability engineering capabilities over commodity generic producers. Five-to-ten year viability hinges on resistance management service recurring revenue models displacing transactional chemical sales. Watch for ANVISA residue tolerance revisions and EPA Endangered Species Act consultation outcomes as inflection signals for Brazilian and United States market access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Intermediate Supply | Captive sourcing from Shandong chemical clusters insulates margin structures against petrochemical volatility. |
| Nano-Dispersion Formulation Licensing | Rainfastness technology transfers unlock premium positioning in Brazil's high-rainfall Cerrado soybean zones. |
| Resistance Monitoring Platform Launch | Subscription pathogen surveillance captures recurring revenue from export-oriented Brazilian growers facing ANVISA compliance. |
| REACH-Compliant Reformulation Program | Aqueous stability engineering preserves European registrations as ECHA solvent restrictions phase in. |
| Seed Treatment Biological Bundling | Early-season protection packages integrate strobilurin chemistry with inoculant platforms for operational efficiency. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with agrochemical R&D directors, Brazilian cooperative procurement managers, European ornamental greenhouse operators, and turf management contractors; and secondary validation through ANVISA residue tolerance schedules, EPA registration databases, ECHA REACH compliance filings, and customs trade data for strobilurin intermediate flows. Bottom-up triangulation across formulation chemistry patent landscapes and top-down demand modeling from soybean hectarage and rust pressure indices anchored volume estimates.
Forecast inputs span active ingredient type, formulation technology, application context, and regional regulatory cluster intensity across the projection horizon. Segmentation dimensions modeled include product mobility characteristics, delivery system architecture, end-use crop value tier, and compliance documentation requirements. CAGRs derive from pathogen resistance accumulation curves, generic entry timing, and drift-reduction policy adoption rates in major agricultural jurisdictions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by digital agronomy platform entrants or Chinese intermediate producers would shift outcomes. Quarterly review of ANVISA tolerance revisions, EPA consultation timelines, and Shandong environmental compliance enforcement is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Gibberellins Market
Agricultural Chemicals
Vietnam Feed Additives Market
Agricultural Chemicals
North America Plant Growth Regulators Market
Agricultural Chemicals
Global Feed Mycotoxin Binders and Modifiers Market
Agricultural Chemicals
South America Plant Growth Regulators Market
Agricultural Chemicals
North America Agricultural Chemical Packaging Market
Agricultural Chemicals
Feed Antibiotics Market
Agricultural Chemicals
Agricultural Insect Pheromones Market
Agricultural Chemicals
Feed Acid Market
Agricultural Chemicals
Plant Activator Market
Agricultural Chemicals
Global Agricultural Micronutrients Market
Agricultural Chemicals
Europe Feed Antibiotics Market
Agricultural Chemicals
Europe Feed Acidifiers Market
Agricultural Chemicals
Agriculture Micronutrients Market
Agricultural Chemicals
South America Feed Acidifiers Market
Agricultural Chemicals
Agricultural Miticides Market