
 United States Neonatal and Prenatal Devices Market | 2026-2036
United States Neonatal and Prenatal Devices Market Size, Share, and Industry Trends Forecast 2026-2036
United States Neonatal and Prenatal Devices Market Analytics
Buyer consolidation among integrated hospital networks is repositioning procurement leverage toward group purchasing organizations. GE Healthcare leverages its installed base of maternal-infant care platforms to sustain service contract renewal rates. Medtronic anchors its position through deep critical care monitoring integration across NICU workflows. Koninklijke Philips N.V. competes on connected care architectures that span prenatal through postnatal continuity.
Neonatal and prenatal devices encompass thermoregulation systems, fetal surveillance platforms, respiratory support apparatus, and diagnostic imaging modalities engineered for gestational ages under thirty-seven weeks and antepartum surveillance. These systems incorporate precision thermal regulation within 0.5°C tolerance bands, acoustic signal processing for fetal heart rate extraction, and low-flow oxygen blending to prevent retinopathy of prematurity. Fetal monitors and imaging systems capture disproportionate margin pools as hospitals prioritize early anomaly detection capabilities. Ventilation technology segments face upgrade cycles driven by volume-targeted modes and non-invasive support protocols that reduce chronic lung disease incidence.
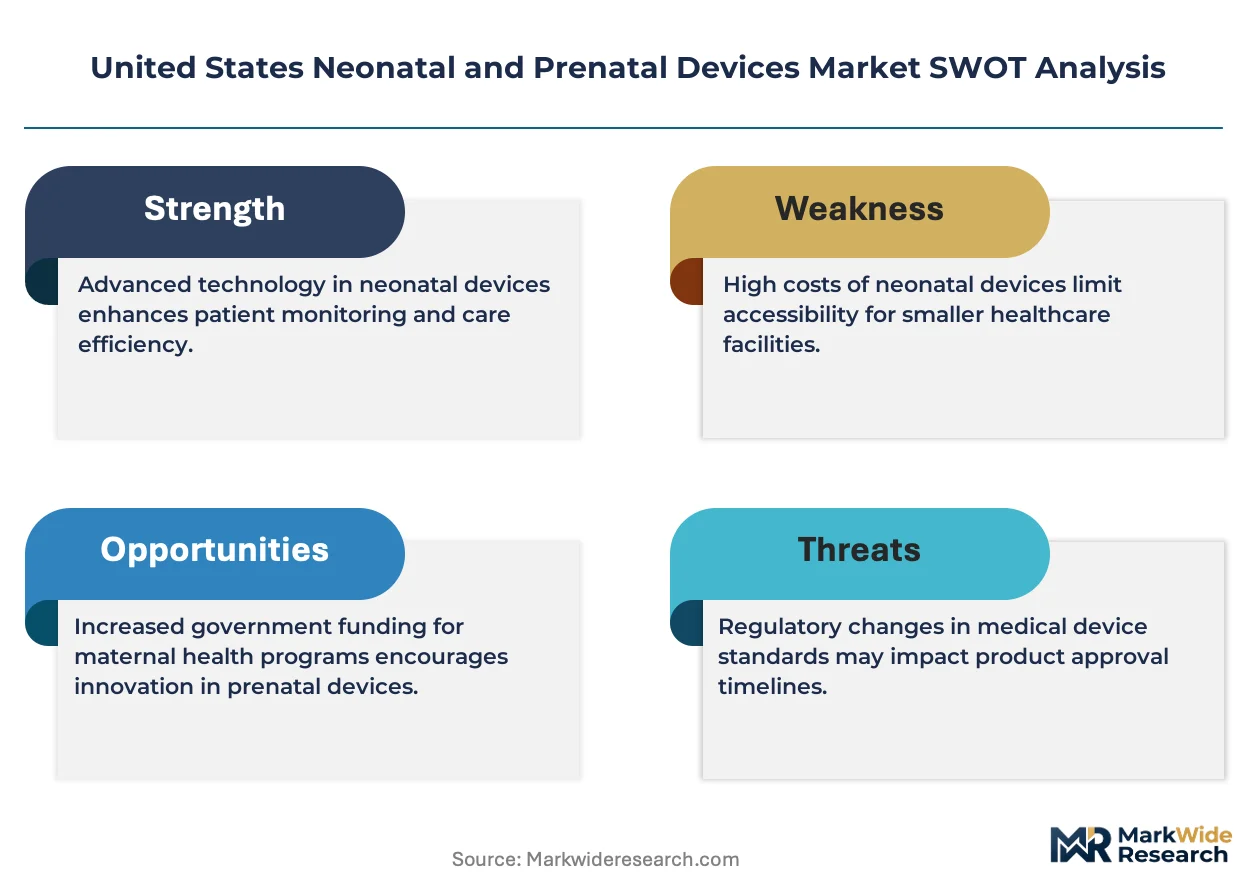
FDA 510(k) clearance pathways and AAP Level NICU designation standards shape product validation requirements and facility capital planning. CMS newborn care reimbursement codes and state Medicaid expansion formulas determine equipment acquisition timelines for safety-net hospitals. Stakeholders must monitor FDA guidance on artificial intelligence-enabled fetal monitoring algorithms and evolving AAP recommendations on family-centered NICU design.
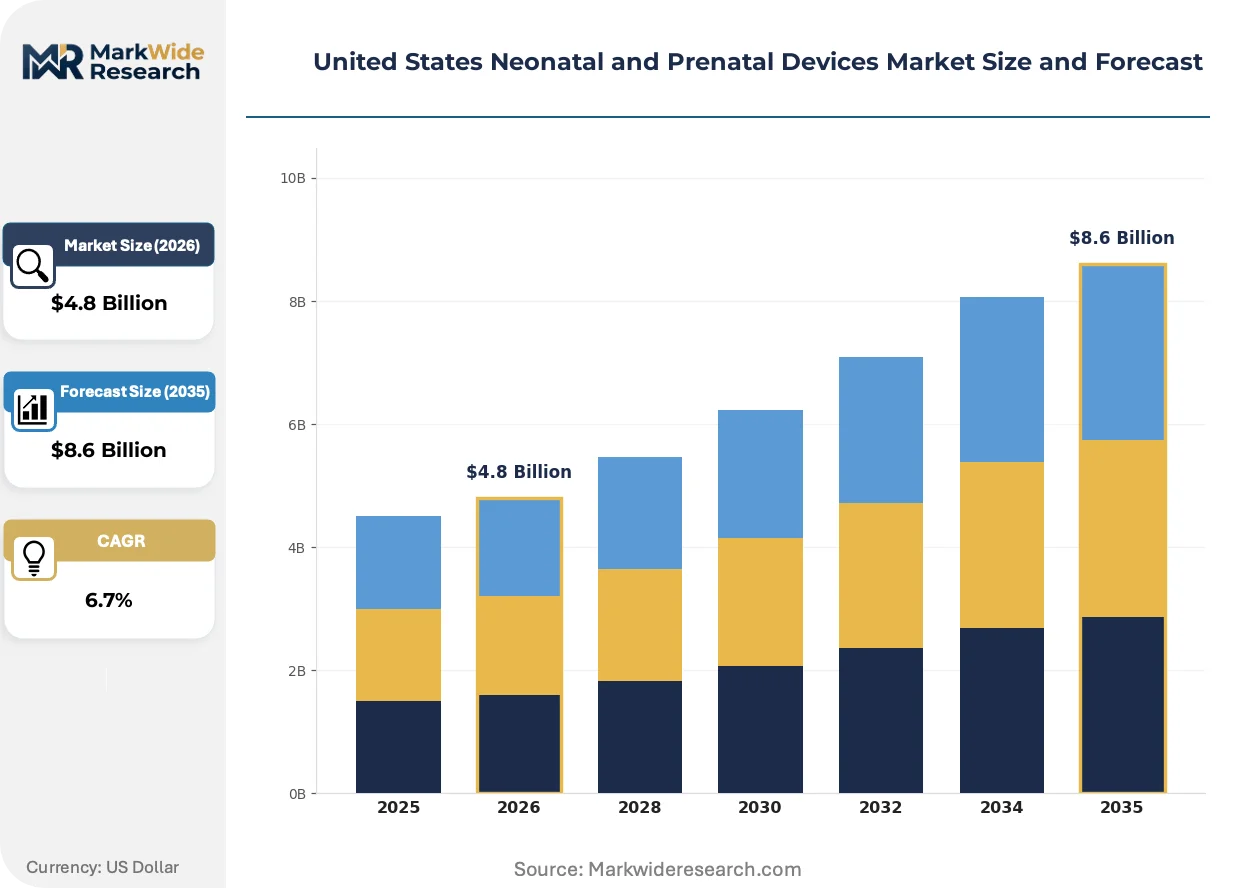
Market Dynamics
Hospital network consolidation is concentrating procurement leverage into fewer decision-makers, forcing device manufacturers to restructure sales organizations around group purchasing organization contracting cycles rather than individual facility relationships.
Growth Catalysts
- Level IV NICU Expansion:Texas, California, and Florida health systems are adding capacity for complex neonatal surgeries, driving capital equipment orders for integrated monitoring and respiratory platforms.
- FDA 510(k) Pathway Efficiency:Streamlined premarket notification for moderate-risk devices accelerates product validation timelines, compressing development-to-revenue cycles for thermoregulation and fetal surveillance systems.
- Medicaid Expansion Formulas:State-level coverage expansions for maternal health services extend reimbursement eligibility to safety-net hospitals, unlocking equipment acquisition budgets previously constrained by uncompensated care exposure.
Market Restraints
- Capital Equipment Intensity:NICU ventilators and imaging systems require multi-year depreciation schedules, stretching payback periods and limiting replacement frequency at independent community hospitals.
- Regulatory Friction from FDA AI Guidance:Evolving standards for algorithm-enabled fetal monitoring create validation uncertainty, delaying commercialization timelines for machine learning-based anomaly detection features.
- Skilled Specialist Scarcity:Neonatal respiratory therapists and perinatal sonographers face geographic maldistribution, constraining effective utilization of advanced device capabilities in non-urban markets.
Strategic Opportunities
- Remote Fetal Monitoring:Home-based antepartum surveillance platforms address maternal transport barriers in rural Texas and Florida counties, creating new reimbursement categories for telehealth-integrated devices.
- Family-Centered NICU Design:AAP recommendations for single-family room configurations drive demand for compact, low-noise thermoregulation systems that accommodate parental presence.
- Service Contract Unbundling:Independent service organizations are capturing preventive maintenance revenue from original equipment manufacturers, fragmenting the aftermarket and creating channel entry points for third-party device suppliers.
Industry Challenges
- Interoperability Integration:Legacy NICU monitoring networks resist seamless data exchange with enterprise electronic health record systems, forcing costly middleware development for device connectivity.
- Workforce Training Compression:Rapid ventilation mode upgrades outpace clinical education programs, creating capability gaps between device functionality and frontline operator proficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Neonatal and Prenatal Devices Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infant Incubators, Fetal Monitors, Oxygen Delivery Devices, Imaging Systems Application: Neonatal Care, Prenatal Monitoring, Diagnostics, Therapeutic Procedures End User: Hospitals, Clinics, Home Care Settings, Diagnostic Laboratories Technology: Ultrasound, Fetal Heart Rate Monitoring, Phototherapy, Ventilation |
| Companies Covered | GE Healthcare, Medtronic, Koninklijke Philips N.V., Drägerwerk AG & Co. KGaA, Masimo Corporation, Natus Medical Incorporated, Fisher & Paykel Healthcare, Becton Dickinson, Cardinal Health, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Neonatal and Prenatal Devices Market Evolving Landscape
Neonatal care technology is converging around precision physiology management and predictive analytics, with hardware miniaturization enabling care migration from centralized NICU pods toward distributed bedside architectures.
Volume-targeted ventilation modes with integrated plethysmography feedback are overtaking pressure-limited conventional support in Level III and IV NICU facilities. Academic medical centers in California and Texas adopted these systems at accelerated cadences through 2023-2024 capital cycles. The technology is compressing chronic lung disease incidence rates and shortening ventilator weaning timelines, reshaping outcome metrics that drive group purchasing organization contract awards.
FDA guidance on artificial intelligence-enabled fetal monitoring algorithms is mandating prospective clinical validation datasets for algorithm training, not retrospective registry mining. This industrial consequence elevates development costs for predictive analytics features while creating competitive moats for developers with established institutional research partnerships. Fetal surveillance platform manufacturers with embedded AI capabilities are responding by restructuring regulatory affairs teams to manage iterative algorithm updates under 510(k) modification pathways.
Consolidated purchasing decisions within integrated delivery networks are displacing individual hospital capital committees as the primary device selection authority. Group purchasing organization contracts now specify performance guarantees and uptime commitments that transfer operational risk to manufacturers. This pattern is most visible in Texas, where Methodist, Baylor Scott and White, and HCA networks have centralized neonatal equipment procurement into system-level supply chain functions.
United States Neonatal and Prenatal Devices Market Segmentation
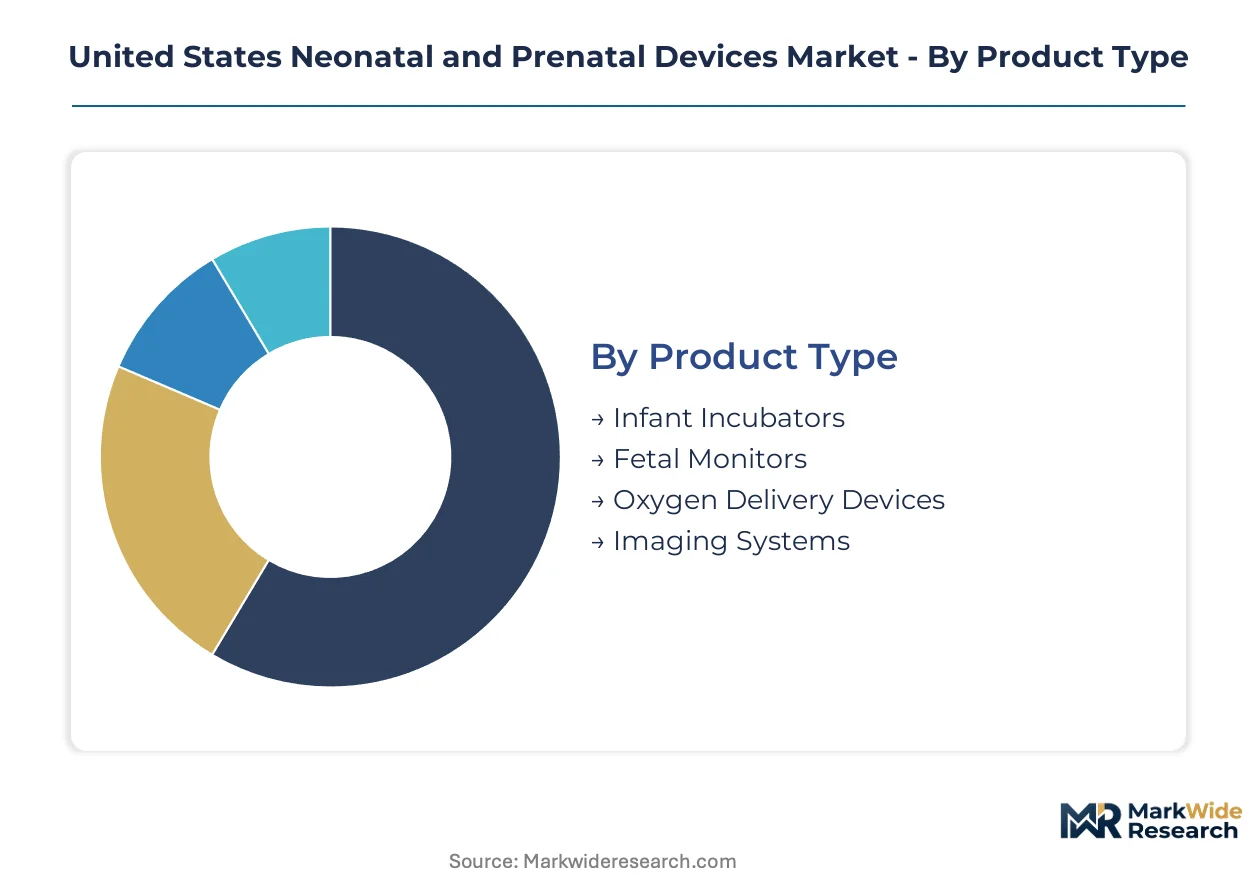
Device segmentation in the United States neonatal and prenatal market reveals distinct procurement patterns across care settings. Hospital network consolidation and CMS reimbursement structures reshape how manufacturers prioritize product development investments.
Product Type:
Capital intensity and clinical outcome metrics differentiate purchasing committees across health system tiers.
- Infant Incubators:Precision thermal regulation systems maintain gestational temperature within 0.5°C tolerance bands through servo-controlled heating elements. Texas and California Level IV NICU expansions drive demand for double-wall designs with integrated humidity control and parental access ports.
- Fetal Monitors:Acoustic signal processing platforms extract fetal heart rate variability from abdominal transducers, with Doppler ultrasound and tocodynamometer integration. Hospital networks in Florida prioritize wireless telemetry configurations that support maternal mobility during labor.
- Oxygen Delivery Devices:Low-flow blenders and nasal cannula systems prevent retinopathy of prematurity through precise FiO2 titration.
- Imaging Systems:Portable ultrasound and radiography modalities engineered for low-dose neonatal protocols.
Volume sits with fetal monitors; growth tilts toward infant incubators.
Application:
Reimbursement coding density determines which applications attract device manufacturer R&D allocation.
- Neonatal Care:Post-birth interventions spanning respiratory support, thermoregulation, and nutritional delivery for infants under thirty-seven weeks gestational age. Safety-net hospitals in Medicaid expansion states unlock capital budgets for comprehensive NICU platforms.
- Prenatal Monitoring:Antepartum surveillance for fetal anomaly detection and maternal risk stratification. Rural Texas counties generate demand for home-based telemetry systems addressing transport barriers to tertiary care.
- Diagnostics:Laboratory and imaging-based screening for congenital conditions.
- Therapeutic Procedures:Device-assisted interventions including phototherapy and surfactant administration.
Neonatal care commands installed base; prenatal monitoring climbs the fastest.
End User:
Facility scale and payer mix create divergent procurement authority structures.
- Hospitals:Integrated delivery networks consolidate purchasing decisions for Level III and IV NICU equipment, with Methodist, Baylor Scott and White, and HCA systems in Texas centralizing supply chain functions. Group purchasing organization contracts specify uptime guarantees and performance metrics.
- Clinics:Outpatient obstetric practices require compact fetal surveillance platforms for antepartum testing.
- Home Care Settings:Remote monitoring devices address geographic maldistribution of perinatal specialists.
- Diagnostic Laboratories:Reference labs process neonatal screening samples requiring automated analytical instruments.
Procurement concentrates in hospitals; home care settings gain share fastest.
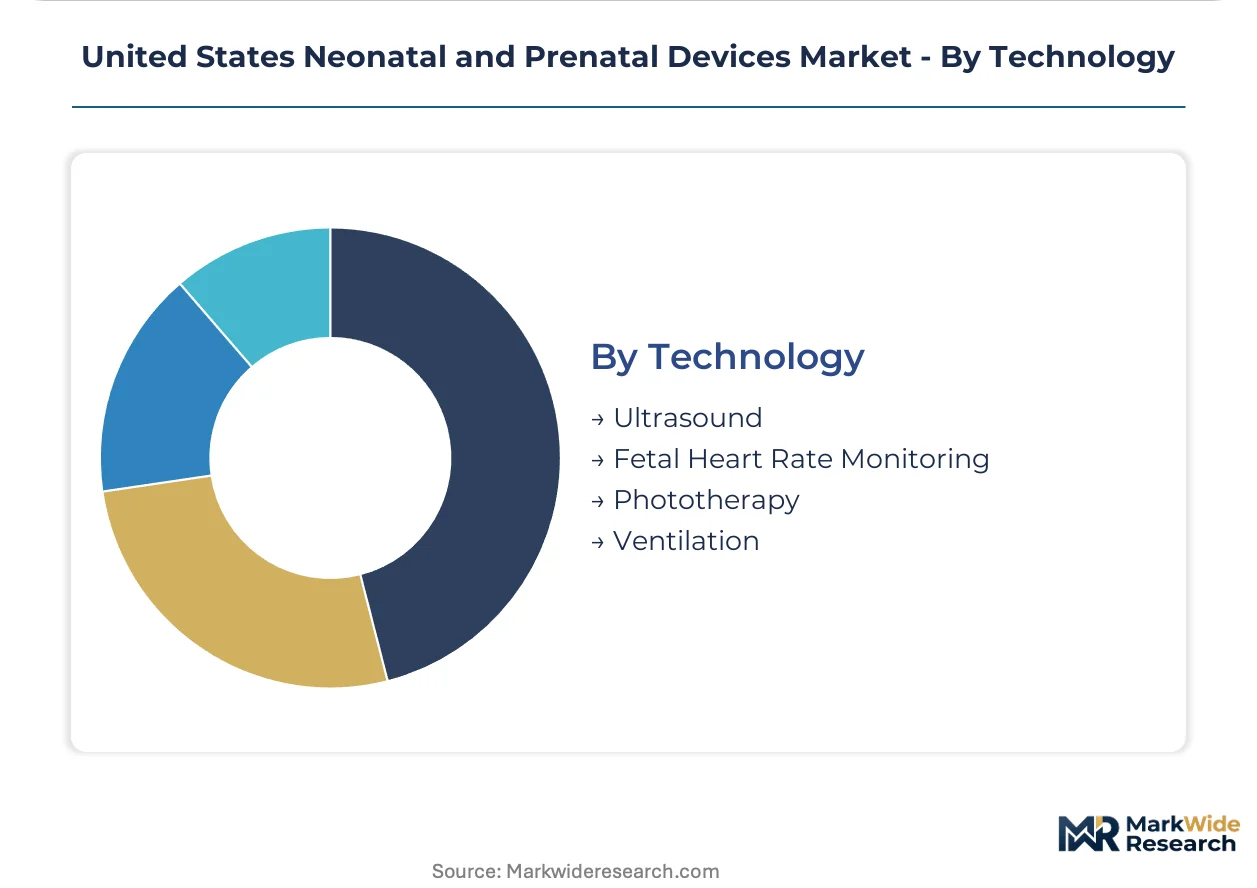
Technology:
Regulatory validation burden and algorithm complexity fragment competitive positioning.
- Ultrasound:High-frequency transducer arrays for fetal anatomical imaging and Doppler flow assessment. FDA 510(k) pathways for AI-enabled anomaly detection mandate prospective clinical datasets, elevating development costs.
- Fetal Heart Rate Monitoring:Electronic signal processing with ST-segment analysis for hypoxia detection. Academic medical centers in California adopt machine learning-enhanced pattern recognition.
- Phototherapy:LED-based bilirubin reduction systems with irradiance feedback control.
- Ventilation:Volume-targeted modes with integrated plethysmography feedback compress chronic lung disease incidence.
Ultrasound anchors revenue; ventilation shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for neonatal and prenatal devices concentrates in states with Level IV NICU capacity expansions and high birth volumes. Texas, California, and Florida health systems drive capital equipment procurement through consolidated purchasing networks.
Texas
Methodist, Baylor Scott and White, and HCA networks centralize neonatal equipment procurement into system-level supply chain functions. CMS reimbursement codes for newborn intensive care support capital budgeting at safety-net hospitals in Medicaid expansion counties. Houston and Dallas medical centers anchor demand for integrated monitoring platforms serving complex neonatal surgeries.
California
Academic medical centers in Los Angeles and San Francisco adopt volume-targeted ventilation systems with plethysmography feedback at accelerated cadences. FDA 510(k) pathway efficiency benefits developers with established institutional research partnerships at Stanford and UCSF. The Bay Area cluster concentrates predictive analytics development for AI-enabled fetal monitoring algorithms.
Florida
Rural counties generate demand for home-based antepartum telemetry systems addressing maternal transport barriers to tertiary care. State Medicaid expansion formulas extend reimbursement eligibility to safety-net hospitals in Miami-Dade and Orange counties. Jacksonville and Tampa health systems prioritize wireless fetal surveillance configurations supporting maternal mobility during labor.
New York
Greater Boston and New York Metro academic centers drive adoption of family-centered NICU designs with single-family room configurations. AAP recommendations for parental presence accommodations stimulate demand for compact, low-noise thermoregulation systems. Columbia and Mount Sinai networks influence equipment specifications through group purchasing organization contract templates.
Illinois
Chicago-area health systems balance capital equipment intensity constraints with outcome-based procurement criteria. Independent community hospitals in Cook County face extended depreciation schedules for NICU ventilators and imaging systems. Northwestern Medicine anchors demand for connected care architectures spanning prenatal through postnatal continuity.
United States Neonatal and Prenatal Devices Market Competitive Landscape
United States producers anchor one tier; European specialists hold differentiated positions in respiratory and monitoring platforms. The vendor base concentrates around integrated delivery network procurement leverage, with three to five manufacturers capturing disproportionate contract value. Diversified health technology conglomerates, dedicated neonatal care specialists, and emerging remote monitoring developers constitute the primary strategic archetypes. Competitive moves center on service contract bundling and predictive analytics integration.
Within the diversified health technology tier, GE Healthcare, Medtronic, and Koninklijke Philips N.V. occupy positions shaped by installed base scale and critical care workflow integration. These manufacturers represent archetypes of platform consolidation, where maternal-infant care ecosystems and connected care architectures define competitive positioning. Drägerwerk AG & Co. KGaA exemplifies the European specialist model focused on precision respiratory support, while Masimo Corporation and Natus Medical Incorporated sit within the monitoring and diagnostics specialization segment.
| Leading Market Players |
|---|
| GE Healthcare |
| Medtronic |
| Koninklijke Philips N.V. |
| Drägerwerk AG & Co. KGaA |
| Masimo Corporation |
| Natus Medical Incorporated |
| Fisher & Paykel Healthcare |
| Becton Dickinson |
| Cardinal Health |
| Others |
Value Network & Pricing Analysis
Medical-grade sensor component indices and precision thermoregulation element benchmarks cascade through three pricing tiers, compressing margins at the standard level while premium configurations absorb volatility through long-term service bundling with integrated delivery networks.
Pricing Analysis
Volume concentrates in fetal monitors; margin pools sit with imaging systems and AI-enabled surveillance platforms. Three-tier pricing structure across premium, standard, and economy levels differentiates by FDA 510(k) clearance tier and after-sales integration depth. Pricing pressure stems from group purchasing organization contract consolidation, forcing manufacturers to absorb uptime guarantee costs. Independent community hospitals exhibit highest price sensitivity; Level IV NICU networks prioritize outcome metrics over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with precision acoustic transducer suppliers concentrated in Germany and Japan. Domestic assembly draws from Taiwanese semiconductor foundries, Mexican contract manufacturing, and domestic precision machining. Tariff exposure on Chinese-sourced printed circuit assemblies elevates landed costs for standard-tier devices. Distribution runs through manufacturer-direct sales organizations serving consolidated health systems, with regional service depots managing preventive maintenance cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into proprietary sensor manufacturing and captive service labor pools is reshaping competitive economics, with upstream control over thermoregulation element supply emerging as the decisive margin lever.
For Market Incumbents: Cement installed base retention by unbundling service contracts into preventive maintenance subscriptions that third-party ISOs cannot replicate. Acquire remote monitoring software capabilities to counter emerging telehealth-integrated entrants. Deepen backward integration into precision temperature sensor production to offset component cost volatility.
For New Entrants and Emerging Players: Launch via independent service organization partnerships targeting community hospital aftermarket capture in Medicaid expansion states. Target home-based antepartum telemetry in rural Texas and Florida counties where maternal transport barriers create reimbursement arbitrage. Pursue FDA 510(k) clearance for AI-enabled fetal monitoring algorithms through academic medical center validation partnerships.
For Investors and Strategic Acquirers: The window for entry favors remote monitoring platform developers with established institutional research partnerships. Long-term viability hinges on regulatory moats around algorithm validation datasets and GPO contract tenure. Watch FDA guidance finalization on AI-enabled fetal monitoring as the inflection signal for predictive analytics valuation step-ups.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates commercialization timelines for thermoregulation and surveillance systems through streamlined premarket notification. |
| Hospital System Partnership | Locks in multi-year equipment procurement with Methodist, Baylor Scott and White, and HCA networks in Texas. |
| Software Companion Development | Enables AI-enabled fetal monitoring algorithms to meet prospective clinical validation requirements under evolving FDA guidance. |
| Reimbursement Strategy | Aligns product positioning with CMS newborn care codes and state Medicaid expansion formulas for safety-net hospital access. |
| CE Marking Pathway | Facilitates European market entry for US-developed neonatal respiratory platforms through MDR compliance architecture. |
Research Methodology
FDA 510(k) clearance databases, CMS reimbursement code repositories, and hospital procurement records formed the secondary backbone. Primary interviews with NICU medical directors, biomedical engineers, GPO contracts managers, and neonatal respiratory therapists validated demand assumptions. Bottom-up and top-down triangulation cross-checked equipment shipment data against capital expenditure disclosures.
Bottom-up modeling aggregated unit economics across product type, application, end user, and technology segments; top-down verification anchored against health system capital planning cycles. CAGRs derived from installed base replacement timelines and Level IV NICU capacity expansion pipelines. Forecast inputs incorporated AAP designation standards evolution and FDA AI guidance trajectory.
The model assumes a particular technology adoption path; alternative pathways for volume-targeted ventilation would alter the outlook. Forecasts reflect assumptions around Medicaid expansion continuity and group purchasing organization contract concentration. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neonatal Care
Infant Resuscitators Market
Neonatal Care
Neonatal Phototherapy Devices Market
Neonatal Care
Germany Neonatal and Prenatal Devices Market
Neonatal Care
Neonatal and Prenatal Devices Market
Neonatal Care
Necrotising Enterocolitis (NEC) Market
Neonatal Care
Neonatal Respiratory Distress Syndrome Market
Neonatal Care
Neonatal Respiratory Distress Syndrome Treatment Market
Neonatal Care
Umbilical Market
Neonatal Care
Japan Neonatal and Prenatal Devices Market
Neonatal Care
North America Fetal and Neonatal Care Equipment Market
Neonatal Care
Australia Neonatal and Prenatal Devices Market
Neonatal Care
Neonatal Phototherapy Market
Neonatal Care
Neonatal Critical Care Equipment Market
Neonatal Care
Neonatal Intensive Care Market
Neonatal Care
Preterm Birth Prevention and Management Market
Neonatal Care
India Neonatal and Prenatal Devices Market