
 Necrotising Enterocolitis (NEC) Market | 2026-2036
Necrotising Enterocolitis (NEC) Market Size, Share, and Industry Trends Forecast 2026-2036
Necrotising Enterocolitis (NEC) Market Foresight
The EU Green Deal's pharmaceutical sustainability criteria is decoupling neonatal nutrition procurement from conventional supply chains across European hospital networks. Abbott Laboratories leverages its human milk fortifier portfolio to sustain leadership in North American NICU nutrition protocols. Nestlé S.A. competes through specialized preterm infant formula research while Prolacta Bioscience anchors its position in donor milk-derived therapeutics for surgical NEC cases.
Necrotising Enterocolitis constitutes an acute inflammatory bowel disease primarily affecting premature infants, characterized by intestinal mucosal injury that progresses to transmural necrosis requiring surgical resection in severe presentations. The condition demands immediate clinical intervention through parenteral nutrition support, antimicrobial therapy, and potential intestinal diversion procedures to prevent systemic sepsis and mortality. Pharmaceuticals command the dominant product segment as clinicians prioritize broad-spectrum antibiotic protocols and emerging probiotic interventions, while nutritional products represent the fastest-expanding category driven by human milk-based fortifier adoption. Neonatal care units concentrate the highest end-user demand given their specialized ventilatory support and surgical capabilities for critically ill preterm infants.
The FDA's pediatric study requirements and EMA's neonatal investigation plans shape clinical trial design and market access timelines for novel NEC therapeutics across their respective jurisdictions. WHO Essential Medicines List inclusion criteria for neonatal sepsis treatments indirectly influence procurement standards in low-resource settings where prematurity mortality remains elevated. Stakeholders must monitor evolving regulatory harmonization between FDA and EMA neonatal trial frameworks while assessing probiotic strain-specific efficacy data to inform therapeutic positioning decisions.
Market Dynamics
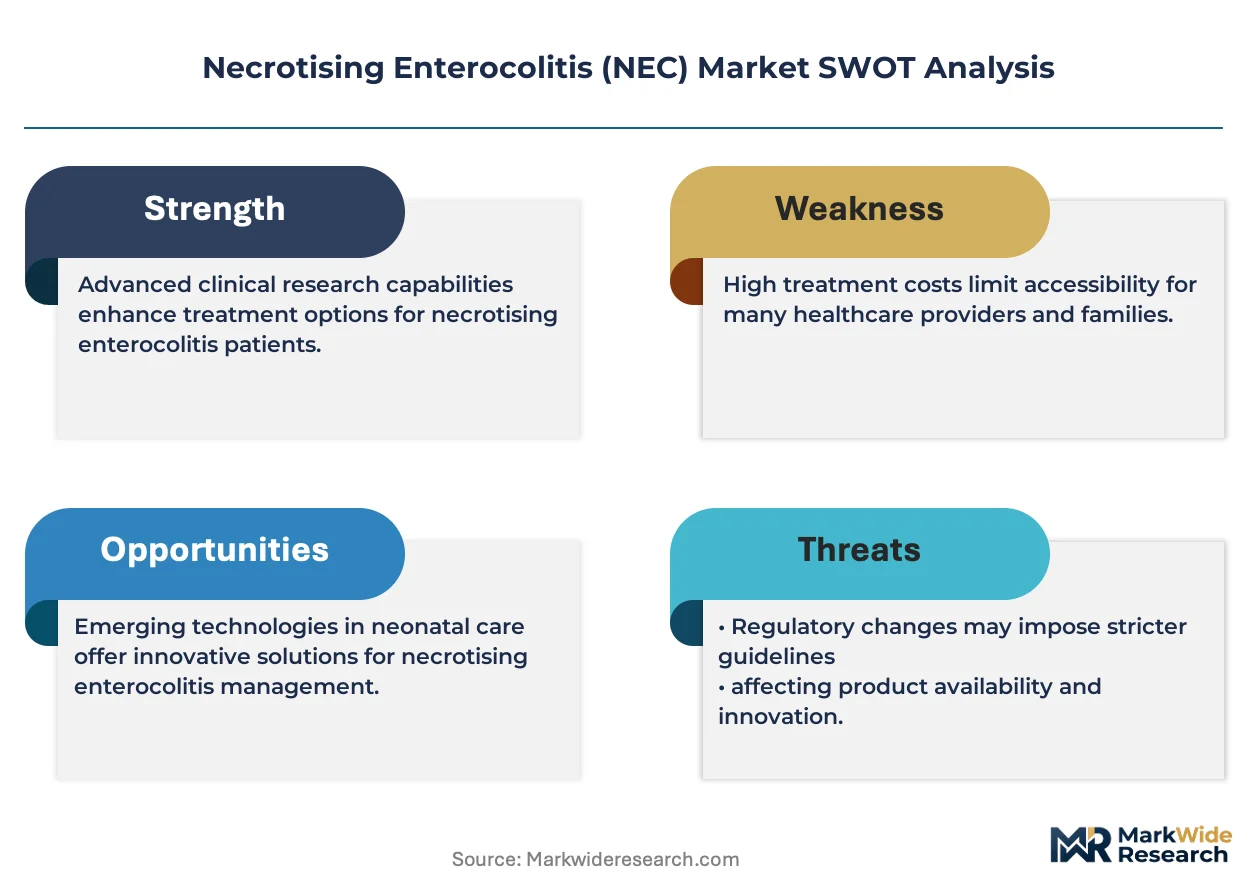
FDA pediatric exclusivity incentives and EMA neonatal investigation plans are compressing clinical trial timelines while WHO prequalification pathways expand addressable patient populations across low-resource settings. These regulatory frameworks simultaneously accelerate therapeutic development and fragment market access requirements.
Growth Catalysts
- Neonatal intensive care infrastructure:Tertiary hospital NICU capacity expansion in the United States, Germany, and Japan creates dedicated channels for specialized NEC interventions. Surgical capabilities and ventilatory support systems attract high-acuity patient transfers.
- Human milk fortifier protocols:Donor milk-derived therapeutics and standardized fortification regimens reduce surgical NEC incidence in preterm populations. Clinical guideline adoption drives nutritional product integration into standard care pathways.
- Pediatric regulatory incentives:FDA's pediatric study requirements and EMA's neonatal investigation plans provide extended market exclusivity for developers addressing unmet neonatal needs. These frameworks offset development cost burdens for low-volume indications.
Market Restraints
- Donor milk supply concentration:Human milk banking infrastructure remains geographically concentrated in North American and Western European urban centers. Limited collection networks constrain fortifier production scale-up.
- Probiotic strain heterogeneity:Variable efficacy across Lactobacillus and Bifidobacterium formulations complicates standardized therapeutic protocols. Meta-analysis inconsistency delays regulatory endorsement for specific strains.
- Sepsis diagnostic overlap:NEC clinical presentation mimics late-onset sepsis, creating diagnostic ambiguity that prolongs antibiotic exposure. Empiric therapy protocols delay definitive surgical intervention.
Strategic Opportunities
- Low-resource NICU development:WHO Essential Medicines List alignment for neonatal sepsis treatments creates procurement pathways in sub-Saharan African and South Asian markets where prematurity mortality exceeds developed-country benchmarks.
- Microbiome diagnostic convergence:Integration of intestinal microbiome profiling with standard laboratory parameters enables risk-stratified intervention timing. Preterm infant gut colonization patterns predict NEC onset before clinical deterioration.
- EU Green Deal procurement criteria:Pharmaceutical sustainability standards decouple neonatal nutrition from conventional supply chains. Hospital network purchasing consortia prioritize locally sourced donor milk and reduced-packaging formulations.
Industry Challenges
- Neonatal trial recruitment:Small patient populations and parental consent complexity extend enrollment timelines for randomized controlled studies. Multicenter coordination across tertiary NICU networks demands substantial operational infrastructure.
- Formulation stability requirements:Probiotic viability maintenance through cold chain distribution creates logistics complexity for hospital pharmacy operations. Strain-specific temperature sensitivity limits geographic reach of live biotherapeutic products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Necrotising Enterocolitis (NEC) Market |
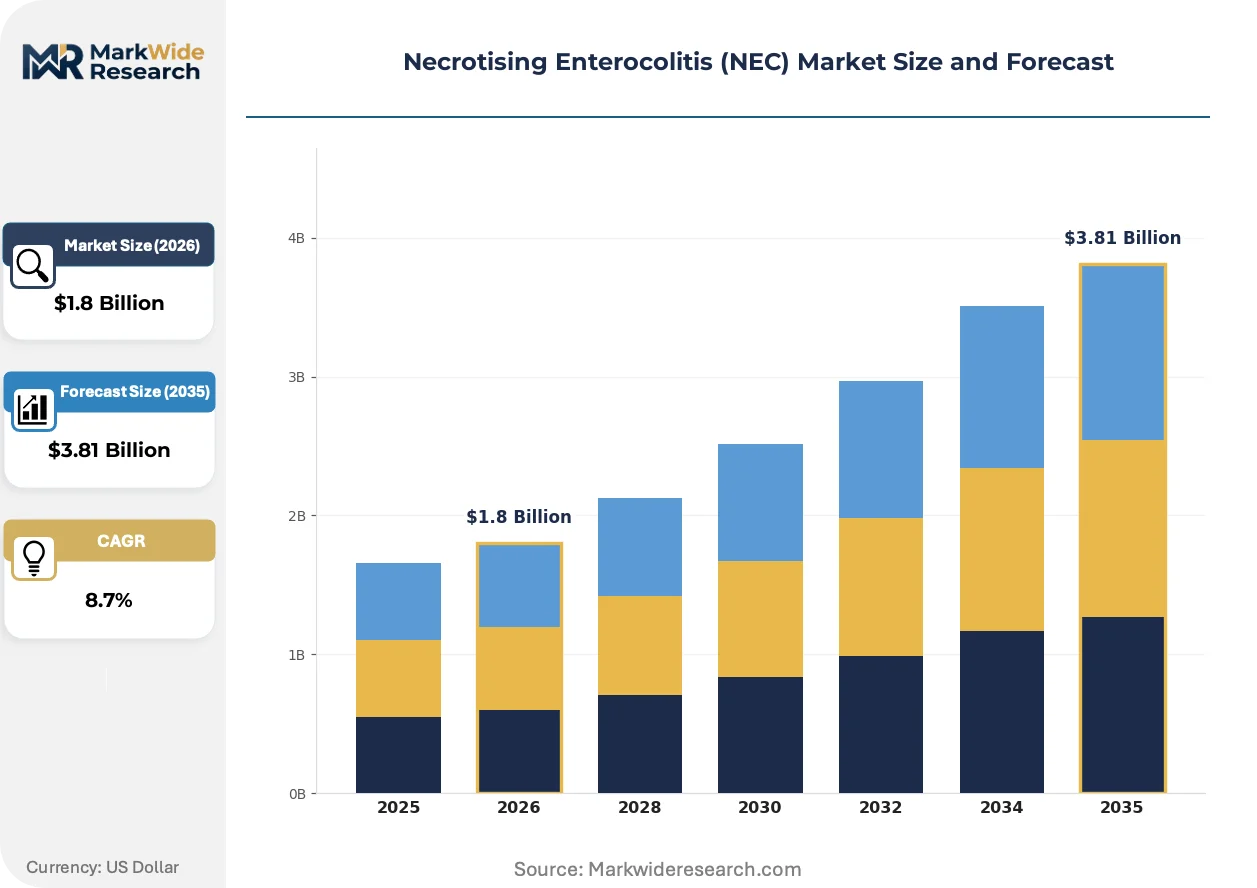
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Nutritional Products, Surgical Devices, Diagnostic Tools End User: Pediatrics, Neonatal Care Units, Hospitals, Research Facilities Application: Therapeutic Management, Preventive Care, Diagnostic Assessment, Clinical Research Delivery Mode: Oral, Intravenous, Surgical, Enteral |
| Companies Covered | Abbott Laboratories, Nestlé S.A., Danone S.A., Mead Johnson Nutrition Company, Fresenius Kabi AG, Prolacta Bioscience, Hollister Incorporated, Baxter International, Infant Bacterial Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Necrotising Enterocolitis (NEC) Market Shifts & Advancements
Live biotherapeutic products and microbiome-targeted interventions are displacing empiric antibiotic protocols in prophylactic NEC management. Regulatory frameworks struggle to accommodate these novel therapeutic categories within existing pharmaceutical approval pathways.
Multi-strain probiotic formulations is unifying previously fragmented prophylactic approaches into standardized NICU protocols. Level III neonatal units in the United States and Japan are adopting these combinations at accelerating pace. This unification is compressing the competitive window for single-strain alternatives and elevating manufacturing quality requirements.
EMA's neonatal investigation plans and FDA pediatric study requirements are harmonizing trial endpoint definitions across Atlantic jurisdictions. Standardized Bell staging criteria and composite morbidity-mortality outcomes reduce regulatory submission redundancy. Surgical NEC incidence reduction claims face heightened evidentiary scrutiny in both jurisdictions.
Hospital purchasing consortia are consolidating procurement authority for neonatal nutrition products. Group Purchasing Organizations negotiate exclusive supply agreements for human milk fortifiers and specialized preterm formulas. This concentration is most visible in United States health system networks where integrated delivery systems control multiple tertiary NICU sites.
Necrotising Enterocolitis (NEC) Market Segmentation
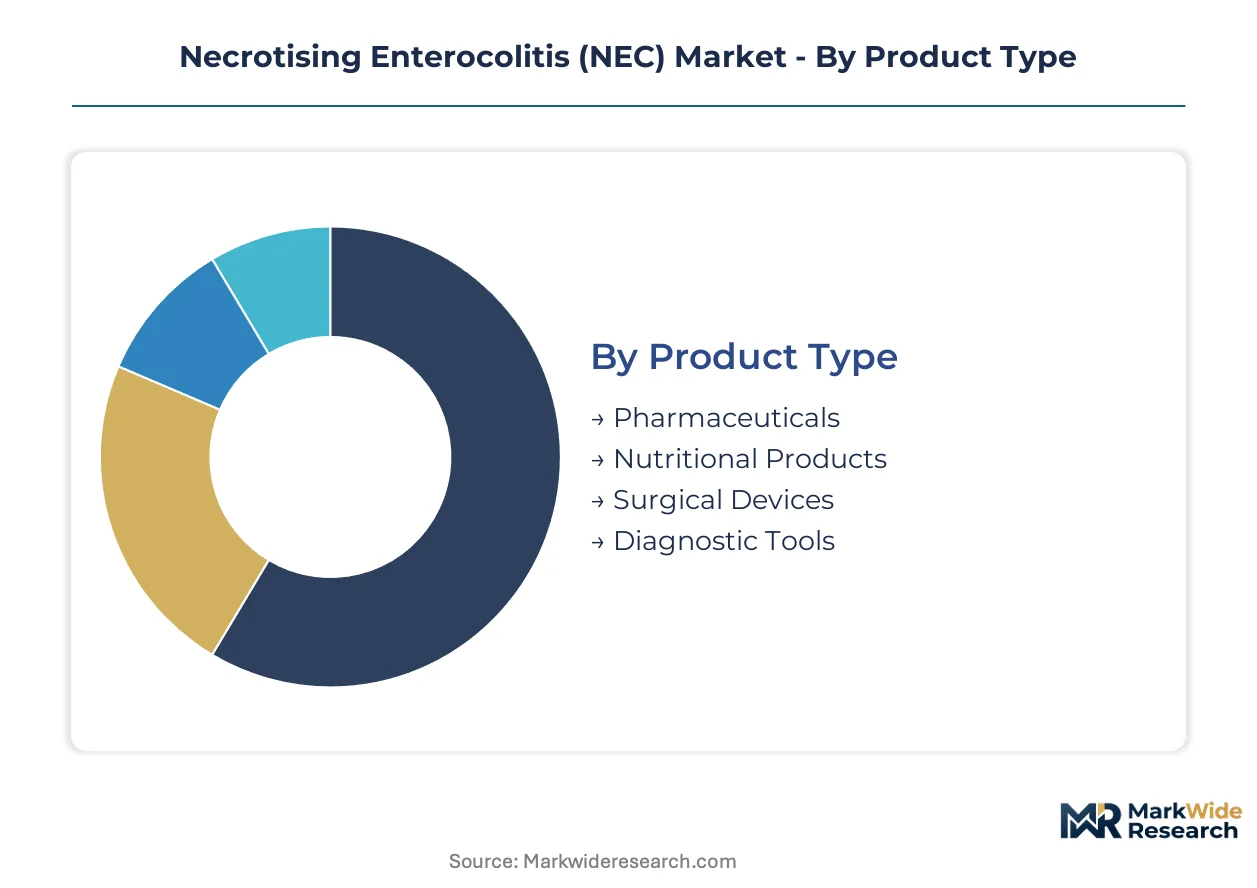
NEC intervention requires coordinated deployment across pharmaceuticals, nutrition, and surgical modalities. Segmentation reveals which product categories integrate into standard care pathways versus specialized tertiary settings.
Product Type:
Pharmaceuticals operate as standalone emergency interventions while nutritional products embed into continuous feeding protocols.
- Pharmaceuticals:Broad-spectrum antibiotic cocktails and emerging probiotic formulations target acute inflammatory control. Demand concentrates in United States tertiary NICUs where FDA pediatric exclusivity incentives accelerate novel therapeutic development.
- Nutritional Products:Human milk fortifiers and specialized preterm formulas reduce mucosal injury progression. German hospital networks prioritize EU Green Deal-compliant donor milk sourcing as sustainability criteria reshape procurement.
- Surgical Devices:Intestinal diversion hardware and resection instrumentation for transmural necrosis cases.
- Diagnostic Tools:Abdominal imaging systems and laboratory biomarker panels distinguishing NEC from late-onset sepsis.
Pharmaceuticals lead volumes today; nutritional products are gaining share fastest.
End User:
Care setting determines intervention intensity, with ventilatory capability and surgical access defining patient routing.
- Neonatal Care Units:Level III facilities combine ventilatory support, parenteral nutrition infrastructure, and pediatric surgical access. Japanese tertiary centers attract high-acuity transfers from regional hospitals lacking intestinal resection capability.
- Hospitals:General pediatric wards manage stabilized post-surgical cases and lower-acuity presentations. United States integrated delivery systems consolidate NEC purchasing across multiple NICU sites through group purchasing organizations.
- Pediatrics:Outpatient follow-up services for surgical recovery and growth monitoring.
- Research Facilities:Academic medical centers conducting microbiome-targeted intervention trials under EMA neonatal investigation plans.
Neonatal care units dominate patient volume; research facilities show steepest expansion trajectory.
Application:
Prophylactic integration into standard preterm protocols is displacing reactive therapeutic approaches.
- Preventive Care:Standardized human milk fortification and multi-strain probiotic protocols reduce surgical NEC incidence. Clinical guideline adoption across United States Level III units drives protocol integration.
- Therapeutic Management:Emergency antibiotic administration, bowel rest, and surgical intervention for established disease. German NICUs emphasize rapid escalation to surgical consultation given diagnostic overlap with sepsis.
- Diagnostic Assessment:Bell staging criteria implementation and biomarker panel deployment for risk stratification.
- Clinical Research:Microbiome profiling studies and live biotherapeutic product trials under harmonized FDA-EMA frameworks.
Therapeutic management anchors current utilization; preventive care is climbing the fastest.
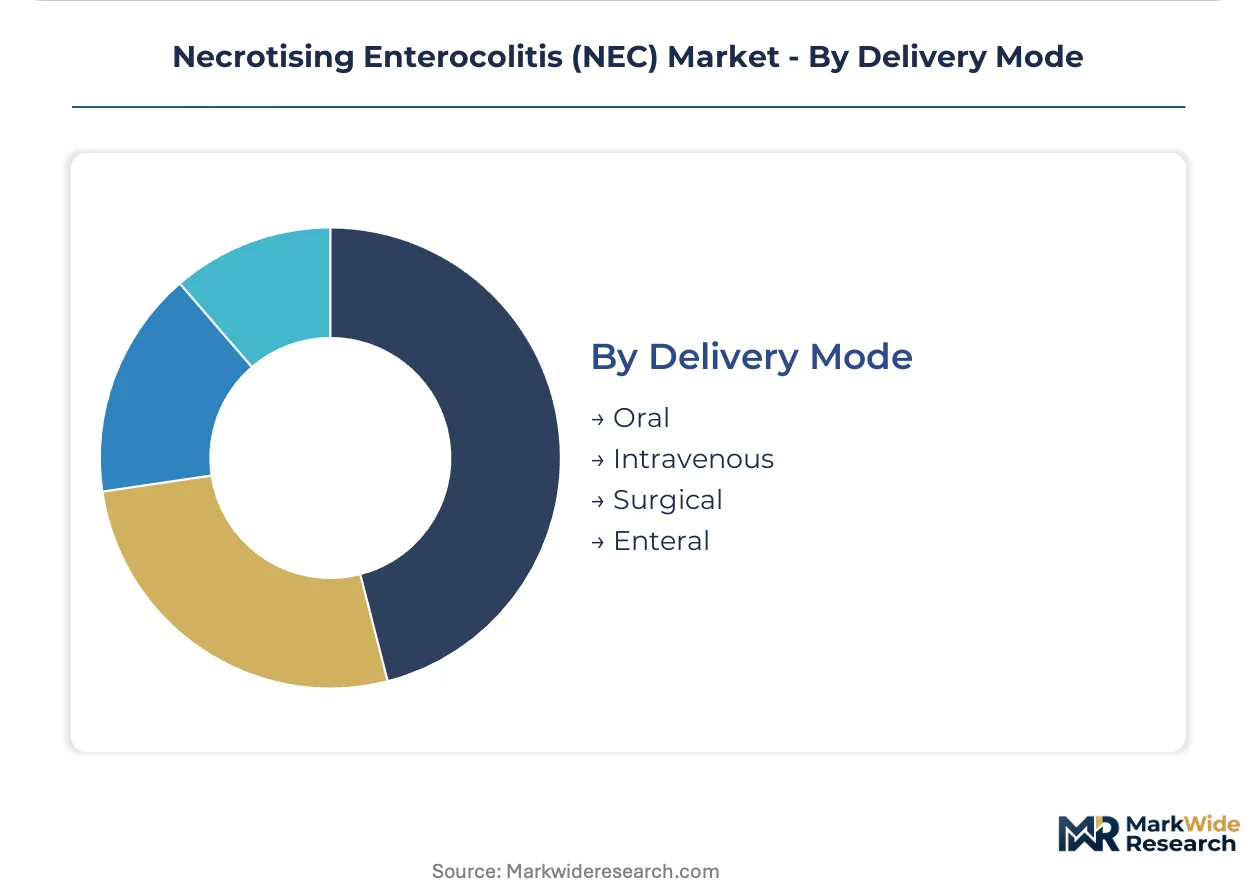
Delivery Mode:
Route selection tracks disease severity, with enteral advancement protocols governing recovery progression.
- Enteral:Nasogastric and orogastric feeding tubes deliver human milk fortifiers and medications directly to the intestinal lumen. Japanese NICUs prioritize early minimal enteral feeding to promote gut maturation.
- Intravenous:Parenteral nutrition maintains caloric support during bowel rest periods. United States hospital pharmacies manage complex compounding for preterm fluid restrictions.
- Oral:Probiotic suspensions and limited enteral feeds for stable preterm infants.
- Surgical:Percutaneous drainage and laparotomy for perforated NEC with peritonitis.
Enteral delivery leads procedural volume; intravenous administration maintains steady utilization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pediatric neonatology specialists cluster in tertiary hospital networks across five countries where prematurity intervention infrastructure commands concentrated investment. NICU capacity and regulatory incentive structures determine geographic competitive intensity.
United States
FDA pediatric exclusivity incentives attract developers of live biotherapeutic products and human milk-derived formulations. Level III neonatal units in Boston, Philadelphia, and California medical centers anchor clinical trial recruitment for novel NEC interventions. Group purchasing organizations consolidate procurement authority across integrated health systems.
Germany
EMA neonatal investigation plans harmonize trial protocols with FDA frameworks, accelerating multi-jurisdictional study designs. EU Green Deal sustainability criteria reshape hospital network procurement for donor milk and reduced-packaging nutrition products. Bavarian and North Rhine-Westphalian hospital consortia lead fortifier adoption.
Japan
PMDA pediatric regulatory pathways align with international neonatal trial standards under METI industrial policy guidance. Tokyo and Osaka metropolitan medical centers concentrate surgical NEC intervention capabilities with intestinal resection expertise. Early minimal enteral feeding protocols differentiate Japanese NICU practice patterns.
United Kingdom
NHS specialized commissioning frameworks concentrate high-acuity neonatal care in designated tertiary centers across London, Birmingham, and Manchester clusters. Human milk banking infrastructure expansion addresses donor supply constraints for fortifier production scale-up. NICE clinical guideline updates drive standardized probiotic protocol adoption.
India
CDSCO pediatric drug approval pathways and WHO prequalification alignment create procurement access for neonatal sepsis treatments in sub-national health programs. Maharashtra and Karnataka state medical college hospitals develop Level III NICU capacity for surgical NEC management. Prematurity mortality reduction targets concentrate public health investment.
Necrotising Enterocolitis (NEC) Market Competitive Landscape
Capital-heavy pharmaceutical manufacturers compete with asset-light biotechnology developers for NEC therapeutic positioning. Market structure shows moderate consolidation around nutrition incumbents with diversified neonatal portfolios, while probiotic specialists fragment the emerging live biotherapeutics segment. Three archetypes dominate: diversified nutrition conglomerates with human milk fortifier platforms, hospital supply contractors with parenteral nutrition infrastructure, and microbiome-focused developers with strain-specific intellectual property. Competitive moves center on strategic partnerships between milk banking networks and fortifier producers, plus regulatory exclusivity pursuit through pediatric trial investment.
Among diversified nutrition conglomerates, Abbott Laboratories and Nestlé S.A. occupy positions anchored by established neonatal feeding protocol relationships, while Prolacta Bioscience exemplifies the donor milk-derived therapeutics specialist archetype with concentrated focus on surgical NEC case management.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Nestlé S.A. |
| Danone S.A. |
| Mead Johnson Nutrition Company |
| Fresenius Kabi AG |
| Prolacta Bioscience |
| Hollister Incorporated |
| Baxter International |
| Infant Bacterial Therapeutics |
| Others |
Supply & Pricing Matrix
Human milk fortifier certification tiers bifurcate sharply between FDA-registered donor milk platforms and unregulated donor pooling arrangements, with that divergence manifesting in both per-unit pricing spreads and cold chain infrastructure investments. German hospital networks under EU Green Deal procurement mandates now require sustainability-certified sourcing, compressing margins for uncertified suppliers while rewarding vertically integrated milk banking operations with long-term exclusive supply agreements.
Pricing Analysis
Bundled service contracts for complete NEC nutritional protocols command premium positioning against unbundled commodity fortifier sales. Three-tier pricing structure across premium, standard, and economy levels tracks FDA pediatric exclusivity status, donor milk provenance documentation, and after-sales clinical support inclusion. Pricing pressure stems from group purchasing organization consolidation across United States integrated delivery systems. Academic medical centers exhibit lowest price sensitivity given research funding offsets, while regional hospitals in India face acute budget constraints driving procurement toward WHO-prequalified economy alternatives.
Supply Chain Analysis
Single-source vulnerability sits with North American donor milk banking infrastructure, where collection networks concentrate in California, Texas, and Ontario province. Raw material dependencies encompass lactating donor recruitment, cold chain logistics capacity, and probiotic strain cultivation facilities. Supply chain risk centers on temperature excursion during live biotherapeutic distribution, which degrades strain viability before hospital pharmacy receipt. Distribution runs through specialized neonatal nutrition distributors with NICU-specific cold storage capabilities rather than general pharmaceutical wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The NEC market functions as a stable compounder anchored by irreversible prematurity incidence rates and permanent NICU infrastructure investment in tertiary centers. Regulatory pediatric exclusivity incentives provide predictable returns for developers addressing this orphan indication.
For Market Incumbents: Anticipate microbiome diagnostic convergence by securing exclusive partnerships with intestinal profiling platforms before standardized protocols emerge. Defensive positioning requires backward integration into donor milk collection networks to lock supply against Prolacta Bioscience's concentrated sourcing advantage. Priority investment targets multi-strain probiotic manufacturing capacity with strain-specific intellectual property moats. For New Entrants and Emerging Players: The premium-economy pricing gap in live biotherapeutic products opens white-space entry below Abbott Laboratories' fortified positioning. Target India's emerging Level III NICU capacity in Maharashtra and Karnataka states, where CDSCO pathways align with WHO prequalification for rapid procurement access. Go-to-market leverage rests on demonstrating surgical NEC incidence reduction under harmonized FDA-EMA trial endpoints rather than prophylactic claims facing evidentiary scrutiny. For Investors and Strategic Acquirers: Consolidation pressure builds where probiotic strain heterogeneity fragments manufacturing scale and regulatory submission costs exceed standalone developer capacity. Five-to-ten year viability favors platforms with harmonized FDA-EMA approval pathways and established hospital formulary placement. Acquisition target archetype: microbiome-focused developers with completed Phase II NEC data and exclusive milk banking network partnerships. Signal to watch is EMA neonatal investigation plan harmonization completion, which would compress multi-jurisdictional approval timelines and revalue late-stage assets.| Strategic Initiative | Industry Significance |
|---|---|
| Donor Milk Banking Network Expansion | Exclusive collection agreements in California and Ontario secure fortifier supply against geographic concentration risk. |
| Multi-Strain Probiotic Manufacturing Scale-Up | Level III NICU protocol unification elevates quality requirements beyond single-strain competitor capabilities. |
| EMA-FDA Trial Endpoint Harmonization | Standardized Bell staging criteria reduce regulatory submission redundancy for surgical NEC claims. |
| Microbiome Diagnostic Platform Integration | Preterm infant gut colonization profiling enables risk-stratified intervention timing before clinical deterioration. |
| WHO Prequalification Pathway Alignment | Low-resource NICU procurement access in sub-Saharan Africa and South Asia expands addressable patient populations. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with neonatology department heads, hospital pharmacy directors, regulatory affairs specialists at live biotherapeutic developers, and donor milk banking operations managers. Secondary validation drew from FDA pediatric exclusivity filings, EMA neonatal investigation plan submissions, ClinicalTrials.gov NEC intervention records, and WHO Essential Medicines List neonatal sepsis criteria. Bottom-up patient volume modeling across United States, German, Japanese, United Kingdom, and Indian tertiary NICU networks triangulated against top-down pharmaceutical and nutritional product revenue estimates.
Comparable-period anchoring established baseline surgical NEC incidence rates and human milk fortifier adoption curves before projecting intervention volume and pricing evolution across the analysis window. Segmentation dimensions encompassed product type, end-user facility tier, application intent, and delivery mode, with additional stratification by regulatory jurisdiction cluster. CAGRs derived from exponential smoothing of historical NICU capacity expansion and prematurity intervention guideline adoption patterns, incorporating probiotic protocol penetration curves and donor milk banking infrastructure build-out timelines as industry-specific inputs.
The model assumes a particular technology adoption path; alternative pathways for live biotherapeutic product integration would alter the outlook if regulatory endorsement delays or strain-specific safety signals emerge. Forecasts reflect documented assumptions about EMA-FDA harmonization completion and sustained EU Green Deal procurement criteria enforcement. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neonatal Care
North America Fetal and Neonatal Monitoring Market
Neonatal Care
Umbilical Market
Neonatal Care
Europe Fetal and Neonatal Care Equipment Market
Neonatal Care
Global NICU Catheter Market
Neonatal Care
United States Neonatal and Prenatal Devices Market
Neonatal Care
India Fetal and Neonatal Care Equipment Market
Neonatal Care
Neonatal Intensive Care Market
Neonatal Care
Neonatal Respiratory Distress Syndrome Market
Neonatal Care
Neonatal Critical Care Equipment Market
Neonatal Care
India Neonatal and Prenatal Devices Market
Neonatal Care
Germany Neonatal and Prenatal Devices Market
Neonatal Care
Japan Neonatal and Prenatal Devices Market
Neonatal Care
Neonatal Phototherapy Market
Neonatal Care
Australia Neonatal and Prenatal Devices Market
Neonatal Care
UAE Neonatal and Prenatal Devices Market
Neonatal Care
Neonatal Infant Care Market