
 Spain Neonatal and Prenatal Devices Market | 2026-2036
Spain Neonatal and Prenatal Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Neonatal and Prenatal Devices Market Analytics
Maternity clinics and home care settings is broadening the addressable base for neonatal monitoring beyond traditional hospital wards. Siemens Healthineers leverages its imaging systems footprint to anchor prenatal ultrasound demand in Spanish tertiary centers. Philips Healthcare sustains channel control through integrated fetal monitoring and maternal care platforms deployed across public hospital networks. GE Healthcare competes on technology leadership in portable incubator and warming device design for regional maternity units.
Neonatal and prenatal devices encompass equipment engineered for gestational monitoring, infant thermoregulation, respiratory assistance, and jaundice management, typically operating within precision ranges such as incubator temperature control of 36.0–37.5°C and phototherapy irradiance thresholds of 30 μW/cm²/nm. These systems serve to reduce infant mortality, manage preterm birth complications, and enable early detection of congenital conditions in clinical and ambulatory settings. Fetal monitors and respiratory support devices capture concentrated margin pools due to high replacement frequency and critical care dependency in Spanish NICUs. Wearable devices and telemedicine solutions are expanding fastest as regional health services integrate remote maternal monitoring to address access gaps in rural Castile-La Mancha and Extremadura. Imaging systems retains structural dominance in prenatal screening workflows, though growth rates trail connected monitoring segments.
Spain's national health system enforces EU MDR compliance through the Spanish Agency for Medicines and Health Products, while CE marking remains mandatory for market access across all device classes. The country's Ministry of Health coordinates with regional autonomous communities to standardize procurement specifications for neonatal equipment in public hospitals. Stakeholders must monitor evolving EU AI Act implications for algorithm-assisted fetal diagnostic tools and prenatal risk scoring software.
Market Dynamics
Spain's neonatal and prenatal devices market is being fundamentally restructured by the EU MDR compliance deadline forcing manufacturers to resubmit technical documentation for legacy products, compressing available supplier pools and redistributing procurement power toward CE-marked incumbents.
Growth Catalysts
- Regional NICU expansion:Pediatric hospitals in Madrid and Barcelona are adding dedicated neonatal intensive care capacity, creating concentrated demand clusters for respiratory support and thermoregulation equipment.
- EU MDR enforcement:Spain's Agency for Medicines and Health Products is accelerating CE marking reviews for prenatal imaging systems, clearing regulatory pathways for compliant device manufacturers.
- Wearable monitoring convergence:Telemedicine infrastructure deployment in Castile-La Mancha and Extremadura is pulling wireless neonatal monitoring into rural maternal care workflows.
Market Restraints
- MDR transition costs:Small and mid-sized device manufacturers face documentation and clinical evidence burdens that consume 18-24 month compliance timelines.
- Component supply concentration:Precision temperature sensors and phototherapy LED arrays depend on concentrated Asian component suppliers, exposing Spanish assemblers to input volatility.
- Specialized technician scarcity:Biomedical engineering talent for fetal monitor calibration and incubator maintenance remains concentrated in Barcelona and Madrid metropolitan clusters.
Strategic Opportunities
- Home care channel development:Maternity clinics in Andalusia are piloting rental and subscription models for portable phototherapy units, expanding addressable demand beyond hospital procurement.
- EU AI Act positioning:Algorithm-assisted fetal diagnostic tools face forthcoming conformity requirements, creating first-mover advantage for compliant risk-scoring software developers.
- Basque Country manufacturing:Regional industrial policy supports medical device production clusters, offering localized assembly alternatives to import-dependent supply chains.
Industry Challenges
- Legacy system integration:Public hospital networks in Catalonia operate mixed-vendor fetal monitoring architectures that complicate platform standardization and data interoperability.
- Certification timeline compression:EU MDR notified body capacity constraints are extending CE marking intervals for Class IIb and III prenatal devices, delaying market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Neonatal and Prenatal Devices Market |
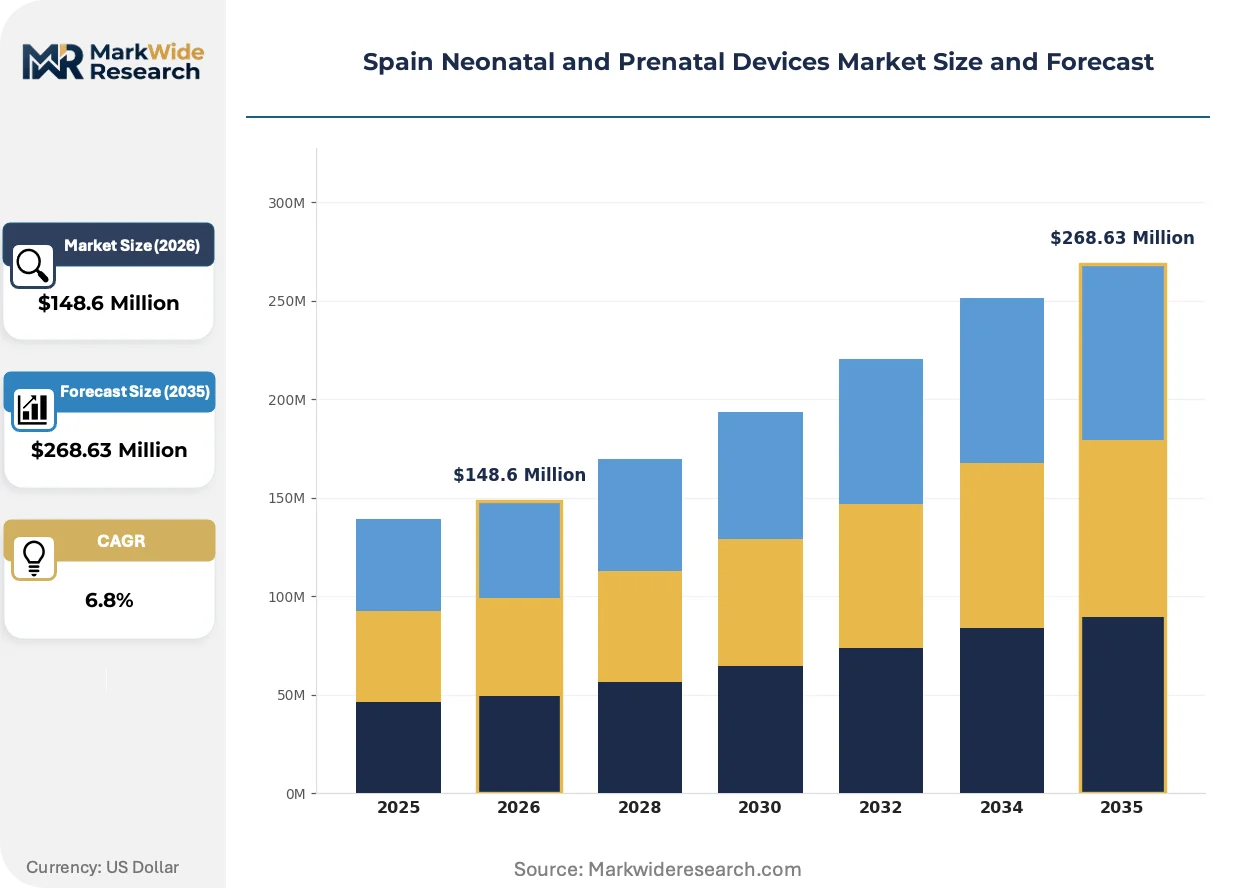
| Market Size in 2026 | $148.6 Million |
| Market Size in 2035 | $268.63 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infant Incubators, Fetal Monitors, Phototherapy Devices, Respiratory Support Devices Application: Neonatal Care, Prenatal Screening, High-Risk Pregnancy Management, Emergency Resuscitation End User: Pediatric Hospitals, Maternity Clinics, Research Institutions, Home Care Settings Technology: Wearable Devices, Imaging Systems, Monitoring Equipment, Telemedicine Solutions |
| Companies Covered | Siemens Healthineers, Getinge AB, Philips Healthcare, Natus Medical Incorporated, Masimo, GE Healthcare, Dragerwerk AG & Co. KGaA, Cardinal Health, Medtronic, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Neonatal and Prenatal Devices Market Evolving Landscape
Wearable neonatal monitoring technology is actively redrawing care delivery boundaries in Spain, pushing continuous vital sign tracking from centralized NICUs toward ambulatory and home settings. Three interconnected developments are accelerating this transition.
Wireless patch-based cardiorespiratory monitors are decentralizing physiological surveillance from bedside equipment to skin-adherent sensors that transmit real-time data to centralized nursing stations. Regional health services in Extremadura are deploying these systems to reduce rural maternal transport burdens. The technology is compressing the distinction between hospital-grade and ambulatory monitoring tiers.
Spain's Ministry of Health is enforcing EU MDR post-market surveillance requirements through enhanced vigilance reporting for fetal monitoring software. Manufacturers must now submit periodic safety updates and clinical follow-up data. Prenatal imaging systems with embedded diagnostic algorithms face the steepest compliance adaptation curves.
Hospital procurement consortia across autonomous communities are consolidating device purchasing through framework agreements that bundle fetal monitors, incubators, and respiratory support into multi-year service contracts. Basque Country and Galicia health authorities pioneered this model, displacing transactional equipment sales with performance-guaranteed supply arrangements.
Spain Neonatal and Prenatal Devices Market Segmentation
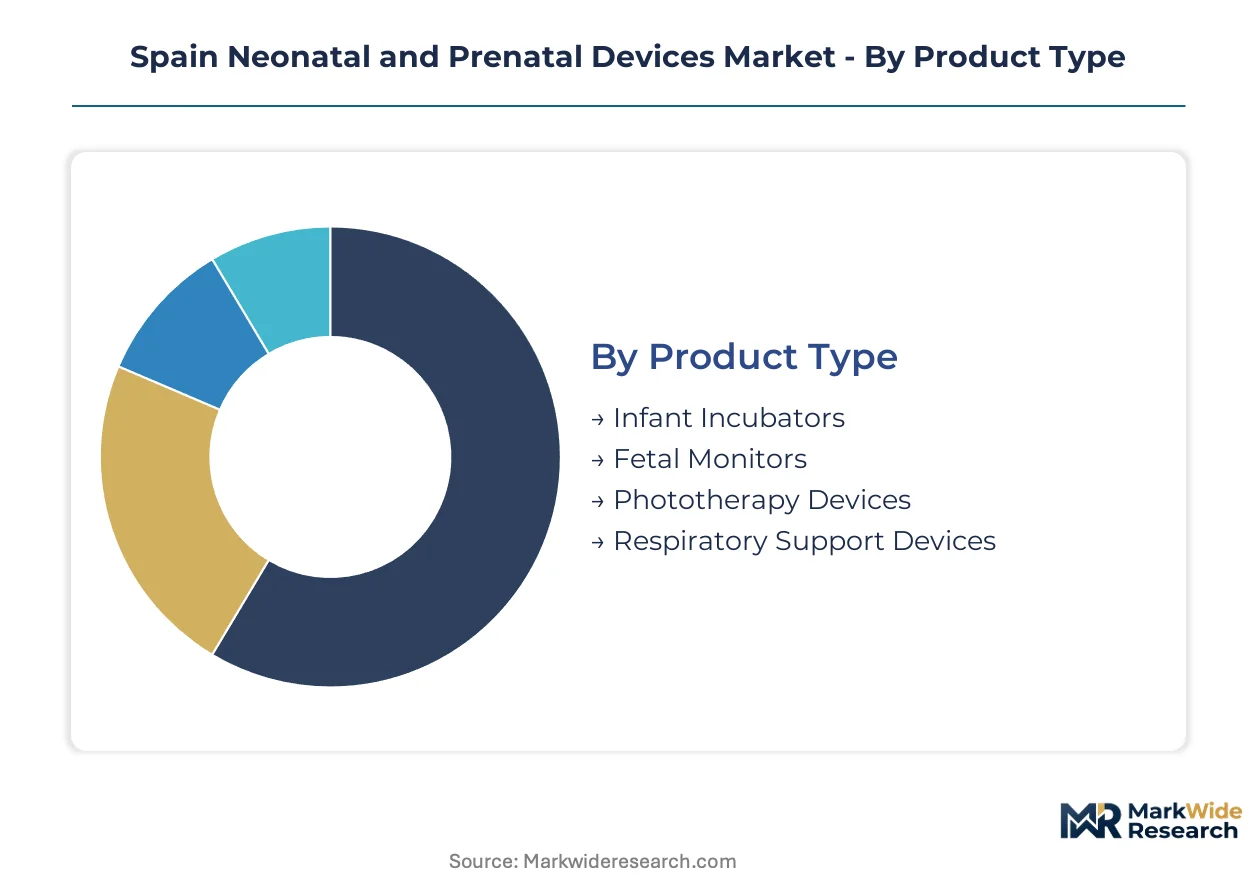
Device segmentation in Spain's neonatal and prenatal market reveals how procurement priorities diverge across acute care, ambulatory, and home-based delivery models. Understanding these splits enables suppliers to align R&D investment and channel strategy with where purchasing power is actually concentrating.
Product Type:
Pediatric hospitals in Madrid and Barcelona weight capital decisions toward precision thermoregulation and continuous physiological surveillance capabilities.
- Infant Incubators:These systems maintain neonatal body temperature within 36.0–37.5°C through servo-controlled heating elements and humidity regulation. Demand concentrates in tertiary NICU expansions across Catalonia, where Basque Country manufacturers are gaining procurement share against traditional import suppliers.
- Fetal Monitors:Cardiotocography and electronic fetal monitoring systems track uterine contractions and fetal heart rate patterns during labor. Maternity units in Andalusia are replacing legacy wired systems with wireless transducer platforms that enable ambulatory labor positioning.
- Phototherapy Devices:LED-based systems deliver therapeutic irradiance at 30 μW/cm²/nm for neonatal jaundice management. Castile-La Mancha clinics are piloting portable rental units for home-based bilirubin treatment.
- Respiratory Support Devices:CPAP, high-flow nasal cannula, and mechanical ventilator systems for preterm infant respiratory distress syndrome. Extremadura's rural transport networks are driving demand for compact, battery-powered emergency resuscitation configurations.
Respiratory support devices lead on scale; phototherapy devices lead on momentum.
Application:
Clinical workflow integration determines device specification requirements across Spanish autonomous communities with varying maternal risk profiles.
- Neonatal Care:Thermoregulation, feeding support, and infection control equipment for post-delivery infant stabilization. NICU capacity expansions in Barcelona's Hospital Universitari Vall d'Hebron are pulling integrated monitoring-incubator systems.
- Prenatal Screening:Ultrasound imaging and biochemical marker testing for fetal anomaly detection. Madrid's public hospital networks are consolidating procurement through framework agreements that bundle imaging hardware with AI-assisted diagnostic software.
- High-Risk Pregnancy Management:Specialized monitoring for maternal hypertension, gestational diabetes, and multiple gestations. Basque Country health authorities are deploying remote monitoring infrastructure to reduce tertiary center transport burdens.
- Emergency Resuscitation:Portable warming, airway management, and cardiac support equipment for delivery room critical events. Andalusian emergency transport services are standardizing on lightweight, battery-operated warming platforms.
Neonatal care dominates installed base; high-risk pregnancy management is expanding most quickly through telemedicine integration.
End User:
Procurement authority and reimbursement pathways vary sharply across institutional buyers and emerging home care channels.
- Pediatric Hospitals:Tertiary centers with dedicated NICU infrastructure and specialized neonatology staffing. Madrid's Hospital Infantil Universitario Niño Jesús anchors demand for the most sophisticated respiratory and surgical support platforms.
- Maternity Clinics:Mid-acuity birthing centers requiring fetal monitoring and basic resuscitation capabilities. Private clinic chains in Catalonia are driving subscription-based equipment service models.
- Research Institutions:Academic medical centers conducting clinical trials on neonatal therapeutic interventions. Barcelona's biomedical research clusters generate specialized demand for precision monitoring instrumentation.
- Home Care Settings:Emerging channel for post-discharge monitoring and phototherapy rental services. Extremadura's rural health services are pioneering wearable monitoring deployment to reduce readmission rates.
Pediatric hospitals command procurement volume; home care settings are gaining share fastest as reimbursement shifts toward ambulatory models.
Technology:
Connectivity architecture and data integration capabilities are becoming primary selection criteria as Spanish health systems digitize maternal care pathways.
- Wearable Devices:Skin-adherent sensors for continuous cardiorespiratory and temperature monitoring without wired tethering. Castile-La Mancha's rural maternal health pilots are validating wireless patch platforms for home-based surveillance.
- Imaging Systems:Ultrasound hardware with embedded diagnostic algorithms for fetal anatomical assessment. EU MDR compliance timelines are compressing available supplier pools toward CE-marked incumbents with established notified body relationships.
- Monitoring Equipment:Bedside and transportable systems for physiological parameter tracking in clinical environments. Galicia's hospital procurement consortia are bundling multi-parameter monitors into performance-guaranteed service contracts.
- Telemedicine Solutions:Remote data transmission and clinical decision support platforms connecting peripheral sites with tertiary specialists. Andalusian regional health services are integrating these systems to address specialist scarcity in rural provinces.
Imaging systems retain structural dominance; wearable devices show the steepest expansion trajectory as ambulatory care models mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Catalonia anchors device procurement concentration through Barcelona's tertiary pediatric infrastructure and the region's biomedical manufacturing corridor. Madrid's Hospital Universitario La Paz and Hospital Infantil Universitario Niño Jesús drive demand for integrated neonatal monitoring platforms. The Basque Country, Andalusia, and Valencia complete the five-region demand map, each exhibiting distinct procurement patterns shaped by autonomous health authority priorities.
Catalonia
Hospital Universitari Vall d'Hebron and Hospital de la Santa Creu i Sant Pau are expanding NICU capacity with integrated monitoring-incubator systems. The Catalan Agency for Health Quality and Assessment enforces EU MDR compliance timelines for fetal monitoring software deployments. Barcelona's biomedical research cluster generates specialized demand for precision phototherapy instrumentation from local assembly operations.
Madrid
The Ministry of Health headquarters coordinates national procurement frameworks that bundle respiratory support devices across the region's seven public hospital networks. Madrid's Agency for Medicines and Health Products accelerates CE marking reviews for prenatal imaging systems. The Hospital Universitario La Paz anchors demand for portable incubator platforms serving high-risk maternal transport corridors.
Basque Country
Regional industrial policy supports medical device production clusters offering localized alternatives to import-dependent supply chains. Basque Health Service procurement consortia pioneered performance-guaranteed service contracts bundling multi-parameter monitors. Vitoria-Gasteiz assembly facilities are gaining procurement share in precision temperature control systems against traditional import suppliers.
Andalusia
Private maternity clinic chains are driving subscription-based equipment service models for fetal monitoring and phototherapy platforms. The Andalusian Health Service integrates telemedicine infrastructure to address specialist scarcity in rural Córdoba and Jaén provinces. Málaga's expanding pediatric hospital network is standardizing on wireless transducer platforms enabling ambulatory labor positioning.
Valencia
The Valencian Health Service deploys wearable neonatal monitoring pilots to reduce readmission rates in post-discharge home care settings. Regional procurement frameworks prioritize portable phototherapy units for rental and subscription distribution models. Alicante's maternal health networks are validating battery-operated warming platforms for emergency transport services.
Spain Neonatal and Prenatal Devices Market Competitive Landscape
Strategic partnerships dominate the current landscape as manufacturers align with regional procurement consortia and telemedicine infrastructure deployers. The vendor base concentrates around imaging systems incumbents, diversified health technology conglomerates, and specialized neonatal equipment fabricators. Three archetypes define competitive positioning: CE-marked legacy suppliers with established notified body relationships, diversified platforms bundling fetal and maternal monitoring, and regional assembly specialists leveraging Basque Country industrial policy support. Portfolio diversification and geographic anchoring through regional manufacturing partnerships represent the dominant competitive moves.
Among diversified health technology conglomerates, Siemens Healthineers, Philips Healthcare, and GE Healthcare occupy positions shaped by their imaging systems footprints and integrated care platform architectures. Siemens Healthineers exemplifies the CE-marked incumbent archetype through its established notified body relationships and tertiary center anchoring. Philips Healthcare represents the bundled platform strategy, with its fetal monitoring and maternal care deployments across Spanish public hospital networks. GE Healthcare sits within the portable device specialization tier, competing on thermoregulation and warming platform design for regional maternity units.
| Leading Market Players |
|---|
| Siemens Healthineers |
| Getinge AB |
| Philips Healthcare |
| Natus Medical Incorporated |
| Masimo |
| GE Healthcare |
| Dragerwerk AG & Co. KGaA |
| Cardinal Health |
| Medtronic |
| Others |
Value Network & Pricing Analysis
EU MDR sustainability and circular economy mandates for medical device lifecycle management gate qualified supplier status and premium-tier pricing access in Spain's neonatal equipment procurement. Spanish autonomous communities increasingly bundle extended service obligations into framework agreements, compressing margins for non-compliant assemblers while rewarding CE-marked incumbents with pricing power.
Pricing Analysis
Distributor margins on fetal monitors and respiratory devices typically range 15-25% before hospital procurement consortia negotiate direct manufacturer contracts. Three-tier pricing structure across premium, standard, and economy levels separates AI-embedded imaging platforms from basic monitoring hardware and refurbished legacy systems. Cost compression in standard-tier phototherapy devices is intensifying because Basque Country assembly operations undercut import-dependent suppliers. Public hospital networks exhibit highest price sensitivity, while private maternity clinics in Catalonia prioritize after-sales service bundling over unit economics.
Supply Chain Analysis
Refurbishment and remanufacturing flows for precision temperature sensors and phototherapy LED arrays remain underdeveloped, creating stranded asset risk in incumbent service inventories. Component sourcing draws from Germany, China, and South Korea for servo-controlled heating elements, wireless transducer platforms, and diagnostic algorithm chipsets. Single-source vulnerability concentrates in Asian phototherapy LED suppliers, exposing Spanish assemblers to input volatility during regulatory transition periods. Distribution runs through regional health service procurement consortia in Madrid, Catalonia, and Basque Country, displacing traditional medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's neonatal device market functions as a geographic-arbitrage play where EU MDR compliance costs in peripheral European markets exceed Spain's notified body efficiency, creating first-mover advantage for CE-marked suppliers establishing Spanish assembly footholds.
For Market Incumbents: Hedge against Basque Country manufacturing competition by securing backward integration into precision temperature sensor supply. Siemens Healthineers and Philips Healthcare should anchor capacity expansion in Vitoria-Gasteiz industrial clusters to neutralize regional assembly cost advantages. Certification investment in EU AI Act-compliant fetal diagnostic algorithms represents the critical lever for pricing power retention.
For New Entrants and Emerging Players: Enter via home care channel subscription models for portable phototherapy and wearable monitoring in Extremadura and Castile-La Mancha rural health networks. The most penetrable segment sits in telemedicine-integrated high-risk pregnancy management, where public procurement frameworks remain unsettled. A direct-to-clinic rental service model bypasses consolidated hospital procurement gatekeepers.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap Spanish device assemblers with dormant CE marking applications awaiting MDR transition completion. Long-term viability over a five-to-ten-year window hinges on AI-assisted diagnostic software integration rather than hardware commoditization. Monitor EU AI Act implementing guidance publication as the inflection signal for algorithm-assisted fetal risk-scoring platform valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | Accelerated notified body relationships with Spain's Agency for Medicines and Health Products compress competitor entry timelines. |
| Hospital System Partnership | Framework agreements with Madrid's seven public hospital networks lock out rival suppliers through multi-year performance contracts. |
| Software Companion Development | AI-assisted fetal diagnostic modules embedded in ultrasound platforms command premium pricing in tertiary screening workflows. |
| Backward Integration | In-house production of precision temperature sensors insulates Basque Country assemblers from Asian component volatility. |
| Reimbursement Strategy | Remote maternal monitoring reimbursement codes in Castile-La Mancha validate subscription pricing for wearable device deployments. |
Research Methodology
Multiple input streams — clinical workflow observation, procurement database analysis, and regulatory filing review — were reconciled to construct segment-level demand estimates. Primary interviews with neonatologists, biomedical engineers, hospital purchasing committee members, and GPO contracts managers informed device replacement cycle and specification priorities. Secondary validation drew from EU MDR notified body disclosure databases, Spanish autonomous community procurement registries, and hospital capital expenditure plans. Bottom-up equipment unit economics and top-down health system budget allocation triangulation anchored market size construction.
Historical shipment patterns were cross-referenced against panel input from device manufacturers and regional health authority planners across the analysis window. Segmentation modeling incorporated product type, application workflow, end-user institution class, and connectivity architecture dimensions. CAGRs were derived from fitted trend extrapolation adjusted for EU MDR transition disruption effects and telemedicine infrastructure deployment schedules. Forecast inputs included NICU capacity expansion timelines in Madrid and Barcelona, and wearable monitoring pilot scale-up commitments in Extremadura.
The model holds under stable EU MDR enforcement and autonomous community procurement consolidation; deviation in notified body capacity constraints or AI Act algorithm classification would shift competitive positioning. Practitioners should monitor Basque Country industrial policy subsidy announcements and rural telemedicine reimbursement code expansions for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neonatal Care
North America Fetal and Neonatal Care Equipment Market
Neonatal Care
Preterm Birth Prevention and Management Market
Neonatal Care
Global Preterm Birth and PROM Testing Market
Neonatal Care
Neonatal Intensive Care Market
Neonatal Care
Global Neonatal Thermoregulation Market
Neonatal Care
Neonatal Dialysis Market
Neonatal Care
Germany Neonatal and Prenatal Devices Market
Neonatal Care
Neonatal Monitoring Equipment Market
Neonatal Care
Neonatal Phototherapy Market
Neonatal Care
Neonatal Ventilators Market
Neonatal Care
Necrotising Enterocolitis (NEC) Market
Neonatal Care
North America Fetal and Neonatal Monitoring Market
Neonatal Care
Australia Neonatal and Prenatal Devices Market
Neonatal Care
Neonatal Phototherapy Devices Market
Neonatal Care
United States Neonatal and Prenatal Devices Market
Neonatal Care
UAE Neonatal and Prenatal Devices Market