
 Australia Neonatal and Prenatal Devices Market | 2026-2036
Australia Neonatal and Prenatal Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Neonatal and Prenatal Devices Market Outlook
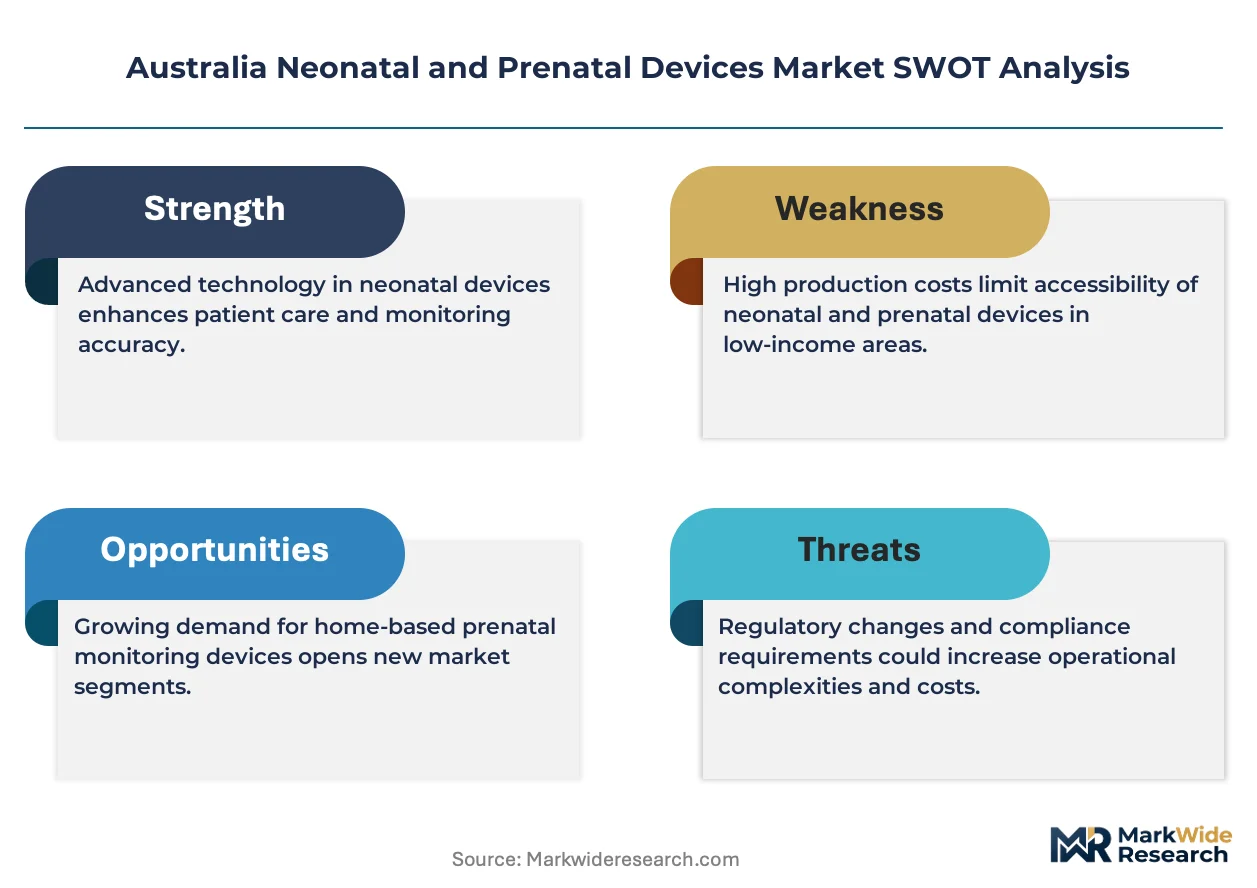
TGA conformity assessment cycles for Class IIb neonatal ventilators is collapsing from eighteen months to under ten, tightening which manufacturers can sustain commercial presence. GE Healthcare leverages its installed base of maternal-infant care platforms across Australian tertiary hospitals. Fisher & Paykel Healthcare Corporation Ltd anchors the humidification and resuscitation segment through specialized neonatal circuit design. Masimo competes on pulse oximetry and cerebral oximetry technology leadership in neonatal intensive care units.
Australia neonatal and prenatal devices encompass thermoregulation, respiratory support, hemodynamic monitoring, and diagnostic imaging equipment engineered for gestational ages from twenty-two weeks through the neonatal period, with functional parameters including servo-controlled thermal environments and fractional inspired oxygen precision to one percent. The primary commercial purpose centers on reducing perinatal mortality and neurodevelopmental impairment in preterm and low-birth-weight infants. Fetal monitors and infant incubators occupy mature margin pools sustained by replacement cycles in public hospital networks, while wireless and integrated systems represent the fastest-growing technology dimension as maternity centers pursue decentralized monitoring architectures. Phototherapy devices sustain steady demand linked to jaundice incidence in neonatal populations.
TGA medical device regulations, the Therapeutic Goods Act, and ISO 13485 quality management standards govern market access, with post-market surveillance obligations intensifying documentation burdens for offshore manufacturers. The Therapeutic Goods Amendment regulations shape product standards by mandating software validation for connected prenatal monitoring devices. Stakeholders must monitor TGA's alignment with EU MDR technical documentation requirements to anticipate parallel audit demands that will reshape supplier qualification protocols.
Market Dynamics
TGA's compressed conformity assessment timelines for Class IIb devices are restructuring competitive viability, favoring manufacturers with established Australian regulatory infrastructure and documented post-market surveillance capabilities.
Growth Catalysts
- Wireless fetal monitoring adoption:Public maternity hospitals in New South Wales and Victoria are expanding procurement of decentralized monitoring architectures. This technology shift enables continuous surveillance without restricting maternal mobility during labor.
- TGA framework acceleration:The Therapeutic Goods Amendment regulations mandate software validation for connected prenatal devices, creating faster pathways for compliant manufacturers. Approval cycles for neonatal ventilators have collapsed from eighteen months to under ten.
- Metropolitan perinatal center concentration:Sydney, Melbourne, and Brisbane tertiary hospitals are consolidating high-acuity births, concentrating demand for advanced thermoregulation and respiratory support equipment in specialized facilities.
Market Restraints
- Offshore documentation burden:TGA's intensified post-market surveillance obligations disproportionately burden manufacturers without local quality management infrastructure, compressing the viable supplier base.
- Replacement cycle maturity:Fetal monitors and infant incubators operate in mature margin pools sustained by extended replacement cycles in public hospital networks, limiting volume expansion.
- Input concentration in specialized circuits:Neonatal humidification and resuscitation equipment relies on proprietary circuit designs with limited alternative suppliers, creating vulnerability to supply disruptions.
Strategic Opportunities
- Regional hospital network penetration:Queensland and Western Australia perinatal centers remain underpenetrated relative to New South Wales and Victoria, offering expansion potential for wireless monitoring platforms.
- Phototherapy device steady-state demand:Jaundice incidence in neonatal populations sustains consistent replacement demand for LED-based phototherapy systems across all Australian states.
- EU MDR alignment preparation:TGA's anticipated convergence with EU MDR technical documentation requirements creates first-mover advantage for manufacturers with parallel audit capabilities.
Industry Challenges
- ISO 13485 quality management specialization:The shallow pool of auditors qualified for neonatal device-specific quality system certification extends supplier qualification timelines.
- Legacy platform integration complexity:Tertiary hospitals with installed maternal-infant care platforms face capital-intensive upgrade paths to achieve wireless system interoperability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Neonatal and Prenatal Devices Market |
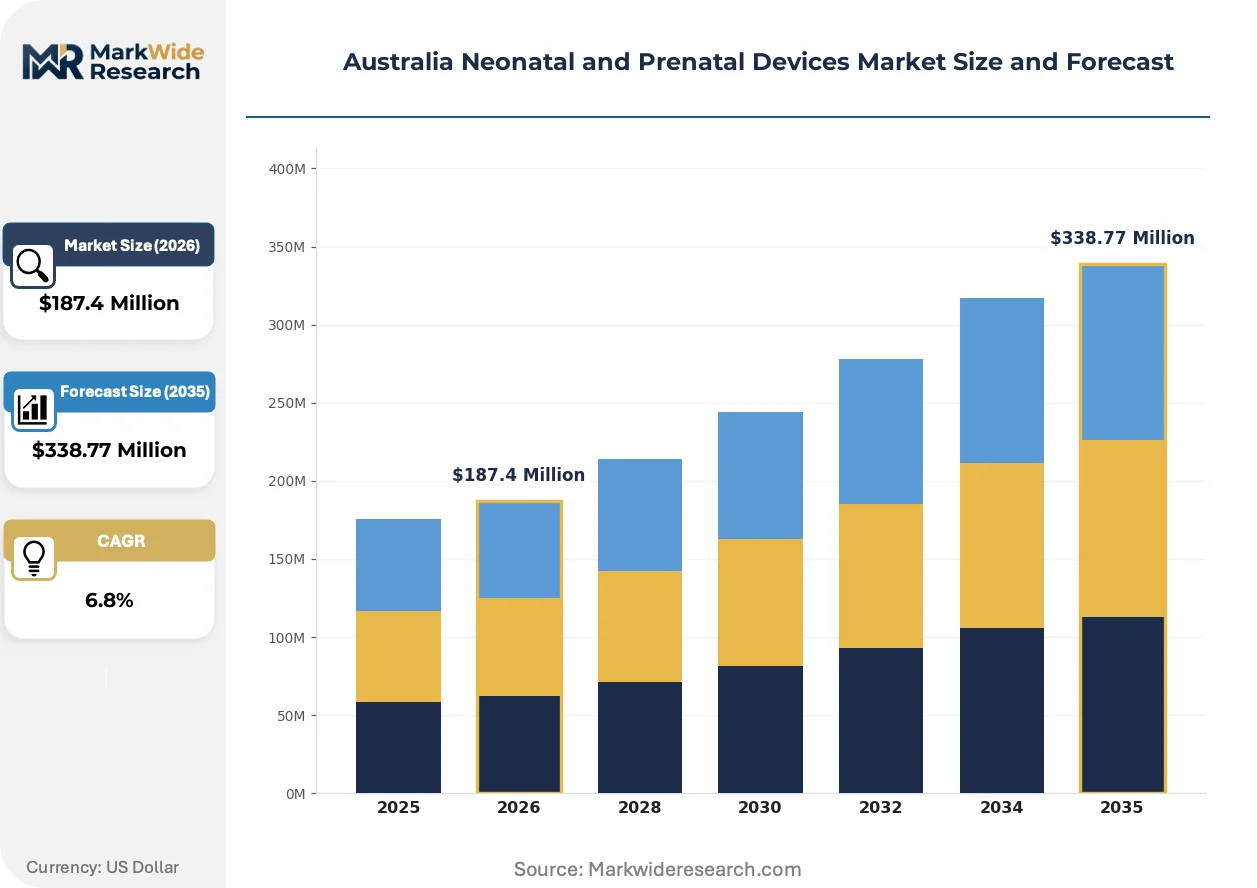
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infant Incubators, Fetal Monitors, Neonatal Ventilators, Phototherapy Devices End User: Hospitals, Clinics, Home Care, Maternity Centers Technology: Digital, Advanced Imaging, Wireless, Integrated Systems Application: Prenatal Monitoring, Neonatal Care, Diagnostic Testing, Surgery |
| Companies Covered | GE Healthcare, Getinge AB, Koninklijke Philips NV, Natus Medical Incorporated, Vyaire Medical, Medtronic PLC, Masimo, Draeger Medical Inc, Fisher & Paykel Healthcare Corporation Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Neonatal and Prenatal Devices Market Strategic Shifts
Technology convergence between continuous monitoring and predictive analytics is restructuring product architectures, while regulatory synchronization and procurement centralization reshape commercial pathways.
Wireless fetal monitoring is bifurcating competitive positioning between integrated platform vendors and specialized point-solution providers. Metropolitan perinatal centers in Sydney and Melbourne are adopting hybrid architectures that layer wireless sensors onto existing infrastructure. This technology trajectory is compressing margins for standalone monitor manufacturers while expanding service contract value pools for integrated system vendors.
TGA's alignment with EU MDR technical documentation standards is intensifying audit preparation requirements for offshore manufacturers. The Therapeutic Goods Act amendments now mandate software lifecycle documentation for connected prenatal devices. Neonatal ventilator and pulse oximetry segments face the steepest compliance burden, with manufacturers restructuring quality teams to manage parallel TGA and European notified body demands.
Hospital network procurement consolidation is displacing individual facility purchasing autonomy across Australian states. New South Wales Health Pathology and Victorian Health Purchasing Victoria are centralizing tender processes for high-value neonatal equipment, compressing vendor negotiation leverage. This behavioral shift concentrates contract awards toward manufacturers with dedicated public sector account infrastructure and documented total cost-of-ownership analytics.
Australia Neonatal and Prenatal Devices Market Segmentation
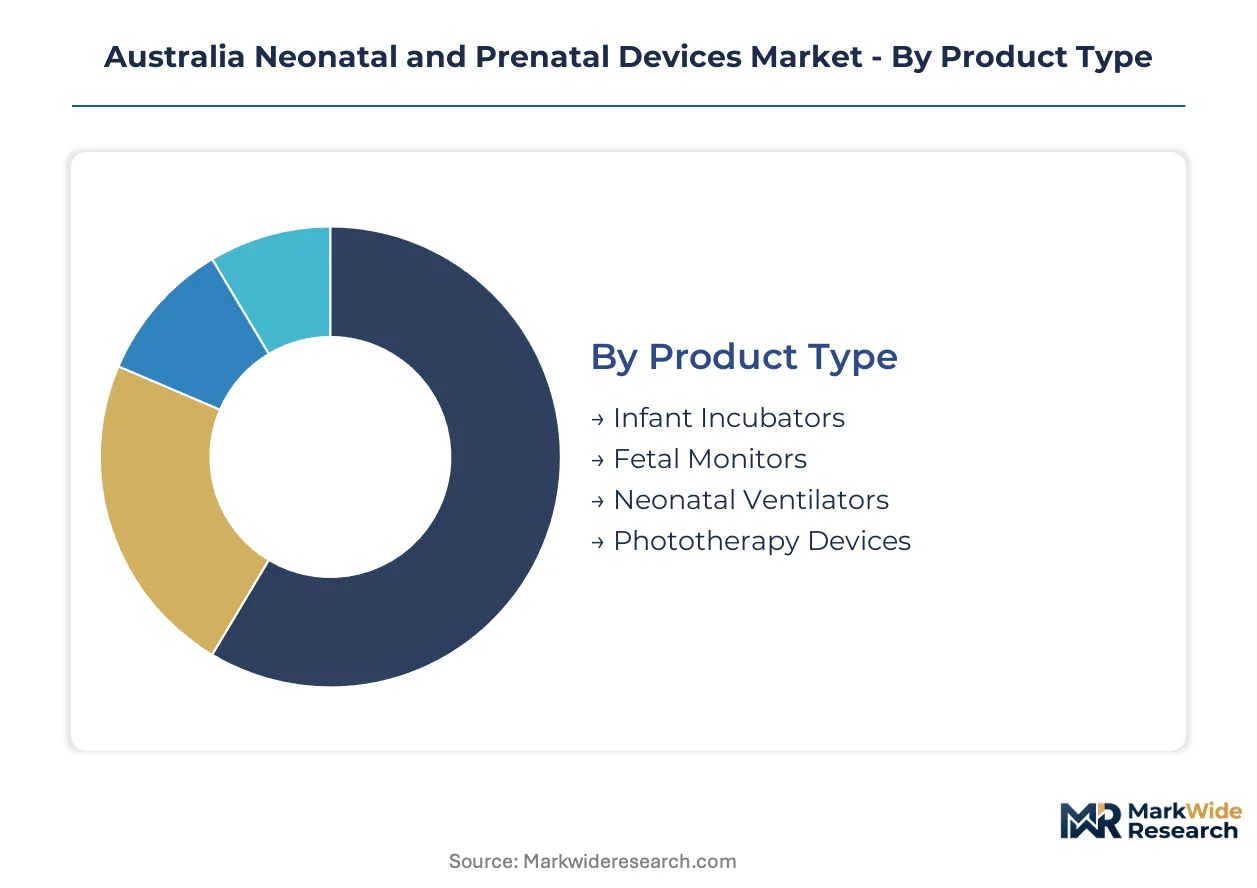
Segmentation in the Australian neonatal and prenatal devices market reveals how procurement centralization and technology transitions are redistributing commercial value across product architectures and care settings.
Product Type:
Mature replacement cycles in public hospital networks anchor margin pools in thermoregulation and traditional monitoring, while wireless-integrated respiratory platforms command premium positioning.
- Infant Incubators:Servo-controlled thermal environments with fractional oxygen precision support preterm infants from twenty-two weeks gestation. Demand concentrates in tertiary perinatal centers across Sydney and Melbourne where high-acuity births are consolidating.
- Fetal Monitors:Wireless and integrated architectures are displacing standalone units as New South Wales and Victoria public maternity hospitals expand decentralized monitoring procurement. This segment is climbing the fastest as maternal mobility during labor becomes a clinical priority.
- Neonatal Ventilators:Class IIb devices face compressed TGA approval timelines.
- Phototherapy Devices:LED-based systems sustain steady replacement demand linked to jaundice incidence.
Infant incubators hold installed capacity. Fetal monitors are rotating up the share rankings.
End User:
Procurement consolidation across state health networks is shifting volume leverage toward centralized hospital purchasing authorities and away from individual facility autonomy.
- Hospitals:Public maternity hospitals in New South Wales and Victoria dominate high-value equipment procurement through centralized tender processes. Tertiary perinatal centers in Brisbane are consolidating demand for advanced respiratory and thermoregulation platforms.
- Maternity Centers:Metropolitan facilities in Sydney and Melbourne are adopting hybrid wireless architectures that layer sensors onto existing infrastructure. This setting is expanding most quickly as decentralized monitoring enables continuous surveillance without restricting maternal mobility.
- Clinics:Diagnostic testing and routine prenatal monitoring occur in outpatient settings.
- Home Care:Remote monitoring applications remain limited in the Australian market.
Hospitals retain procurement volume dominance. Maternity centers are gaining share in wireless platform deployment.
Technology:
Software validation requirements under TGA's Therapeutic Goods Amendment regulations are restructuring competitive viability toward manufacturers with documented lifecycle documentation capabilities.
- Wireless:Decentralized monitoring architectures enable continuous fetal surveillance without maternal mobility restriction. New South Wales and Victoria public hospitals are expanding procurement of these systems as replacement for traditional wired platforms.
- Integrated Systems:Hybrid architectures layering wireless sensors onto existing maternal-infant care platforms are compressing margins for standalone monitor manufacturers. Metropolitan perinatal centers in Sydney and Melbourne favor vendors with documented interoperability and total cost-of-ownership analytics.
- Digital:Software lifecycle documentation is now mandatory for connected prenatal devices.
- Advanced Imaging:Diagnostic capabilities support prenatal assessment and neonatal care planning.
Digital platforms hold legacy installed base. Wireless systems are climbing the technology adoption curve fastest.
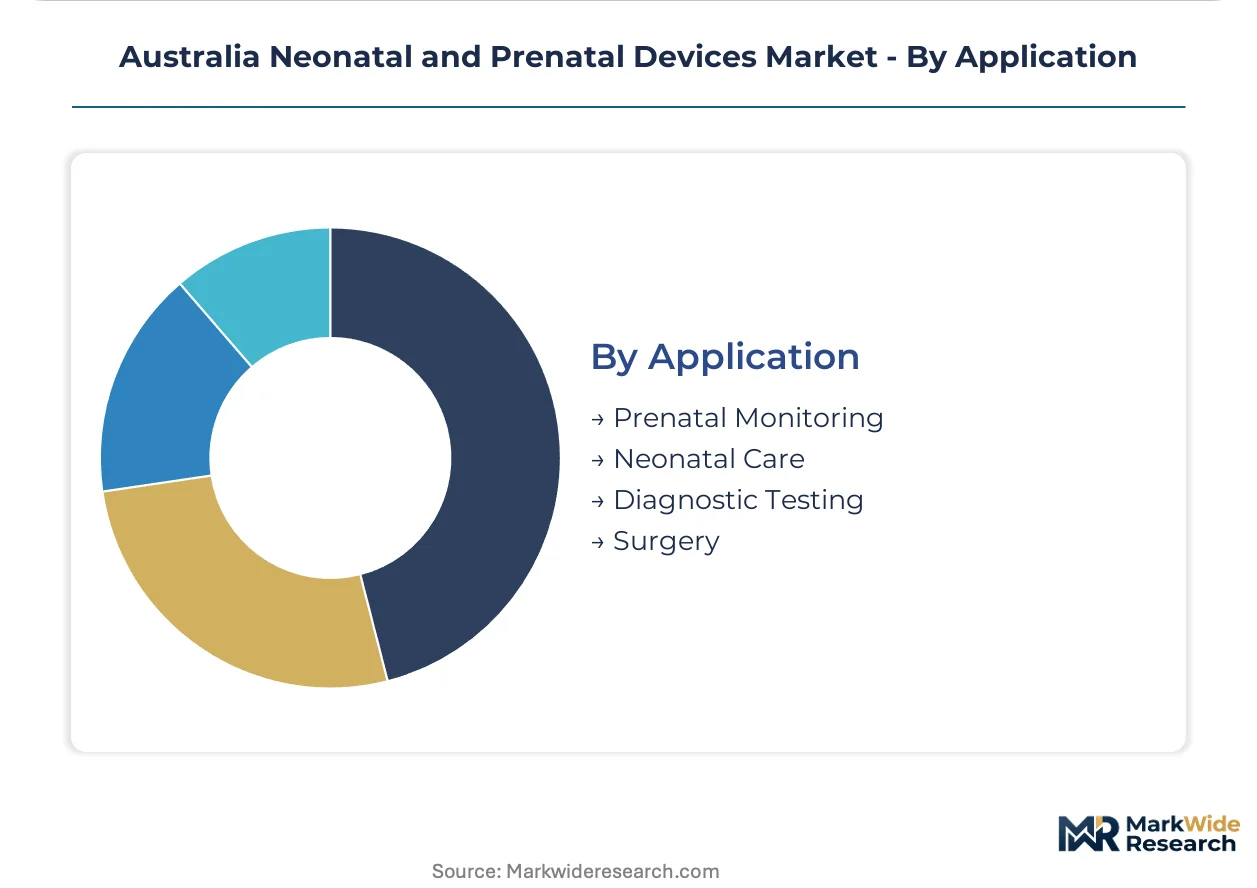
Application:
Clinical workflow integration and predictive analytics convergence are redistributing value from episodic diagnostic testing toward continuous monitoring and early intervention platforms.
- Prenatal Monitoring:Wireless fetal monitoring systems are restructuring competitive positioning between integrated platform vendors and specialized point-solution providers. TGA's compressed conformity assessment timelines favor manufacturers with established Australian regulatory infrastructure.
- Neonatal Care:Thermoregulation, respiratory support, and hemodynamic monitoring equipment serves preterm and low-birth-weight infants in intensive care settings. Demand concentrates in specialized perinatal centers across metropolitan Australia.
- Diagnostic Testing:Laboratory and imaging-based assessment supports clinical decision-making.
- Surgery:Specialized neonatal surgical interventions require dedicated equipment configurations.
Neonatal care holds established clinical volume. Prenatal monitoring is rotating up the priority rankings as wireless platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Public maternity hospitals in New South Wales and Victoria concentrate procurement authority for high-value neonatal equipment, while tertiary perinatal centers across metropolitan Australia drive demand for advanced respiratory and thermoregulation platforms.
New South Wales
New South Wales Health Pathology centralizes tender processes for wireless fetal monitoring systems across public maternity hospitals. TGA's compressed conformity assessment timelines favor manufacturers with established Australian regulatory infrastructure in this state. Sydney's tertiary perinatal centers are consolidating high-acuity births and expanding procurement of decentralized monitoring architectures.
Victoria
Victorian Health Purchasing Victoria directs centralized procurement for neonatal ventilators and infant incubators across Melbourne's hospital networks. The Therapeutic Goods Amendment regulations mandate software validation for connected prenatal devices, accelerating approval pathways for compliant manufacturers. Melbourne metropolitan perinatal centers are adopting hybrid wireless architectures that layer sensors onto existing maternal-infant care platforms.
Queensland
Queensland perinatal centers remain underpenetrated relative to New South Wales and Victoria in wireless monitoring platform deployment. TGA's intensified post-market surveillance obligations compress the viable supplier base for regional hospital networks. Brisbane's tertiary hospitals are consolidating demand for advanced thermoregulation equipment as high-acuity births concentrate in specialized facilities.
Western Australia
Western Australia's perinatal centers present expansion potential for manufacturers with dedicated public sector account infrastructure. ISO 13485 quality management specialization requirements extend supplier qualification timelines for offshore manufacturers without local presence. Perth's metropolitan hospitals are evaluating total cost-of-ownership analytics for integrated system vendors against standalone monitor manufacturers.
Australia Neonatal and Prenatal Devices Market Competitive Environment
Player mix skews toward diversified medical technology conglomerates with maternal-infant care platform portfolios. The market structure concentrates around manufacturers with installed base advantages in Australian tertiary hospitals and documented interoperability capabilities. Three archetypes dominate: integrated platform vendors leveraging comprehensive product ecosystems, specialized point-solution providers competing on technology leadership, and regional quality specialists with regulatory infrastructure depth. Competitive moves center on strategic partnerships for wireless system interoperability and portfolio diversification into predictive analytics.
Among diversified medical technology conglomerates, GE Healthcare, Koninklijke Philips NV, and Medtronic PLC exemplify the integrated platform vendor archetype. These manufacturers occupy positions sustained by installed base relationships across Australian public hospital networks. Specialists in neonatal respiratory and monitoring segments include Getinge AB, Natus Medical Incorporated, Vyaire Medical, Masimo, Draeger Medical Inc, and Fisher & Paykel Healthcare Corporation Ltd, representing point-solution providers competing on technology differentiation. The "Others" category captures emerging and regional participants seeking entry through regulatory compliance and niche specialization.
| Leading Market Players |
|---|
| GE Healthcare |
| Getinge AB |
| Koninklijke Philips NV |
| Natus Medical Incorporated |
| Vyaire Medical |
| Medtronic PLC |
| Masimo |
| Draeger Medical Inc |
| Fisher & Paykel Healthcare Corporation Ltd |
| Others |
Value Chain & Pricing Dynamics
Installed base economies across Australian tertiary hospital networks compress price floors for neonatal ventilators and infant incubators, while concentrated procurement authority in New South Wales Health Pathology and Victorian Health Purchasing Victoria amplifies volume-scale leverage against offshore manufacturers lacking local quality infrastructure.
Pricing Analysis
Cost-plus contracts with indexed component pricing dominate public hospital tenders for Class IIb neonatal devices, with TGA compliance certification tier and installed base interoperability serving as the primary price differentiation drivers. Pricing pressure intensifies in standalone fetal monitor segments as wireless-integrated platforms capture premium positioning through service bundling. Metropolitan perinatal centers exhibit lowest price sensitivity due to clinical workflow integration requirements, while regional Queensland and Western Australia hospitals demonstrate highest sensitivity to total cost-of-ownership analytics.
Supply Chain Analysis
Inbound logistics costs through Port Botany and Port of Melbourne container availability constraints shape landed cost structures for specialized neonatal circuit components sourced from Germany, the United States, and Singapore. Manufacturing of servo-controlled thermal environments and pulse oximetry sensors draws from precision electronics clusters in Malaysia and contract sterilization facilities in Ireland. Single-source vulnerability concentrates in proprietary humidification circuit designs from Fisher & Paykel Healthcare's New Zealand operations. Distribution runs through state health network central warehouses with direct-to-hospital delivery for high-value respiratory platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat environment where TGA regulatory entrenchment and hospital network switching costs protect incumbents with documented post-market surveillance capabilities.
For Market Incumbents: Shield installed base relationships across Sydney and Melbourne tertiary perinatal centers by accelerating software validation documentation for connected prenatal devices under Therapeutic Goods Amendment requirements. Deepen backward integration into specialized neonatal circuit manufacturing to offset supply disruption risks from proprietary component dependencies. Prioritize interoperability certification with Victorian Health Purchasing Victoria centralized procurement platforms to foreclose point-solution vendor access. For New Entrants and Emerging Players: TGA's compressed conformity assessment fast-track for Class IIb devices with established ISO 13485 quality infrastructure creates entry velocity for compliant manufacturers. Queensland perinatal centers present the most penetrable geography given underdeployment of wireless monitoring platforms relative to New South Wales and Victoria. Western Australia's regional hospital networks offer white-space expansion for manufacturers with dedicated public sector account teams and documented total cost-of-ownership analytics. Lead go-to-market through GPO contract participation rather than direct facility sales. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated platform vendors with maternal-infant care ecosystem breadth over standalone monitor manufacturers facing margin compression. Long-term viability across the projection horizon rests on regulatory infrastructure depth and hospital network relationship density rather than pure technology differentiation. Acquisition target archetype: mid-cap specialists with TGA-established quality teams and Queensland/Western Australia geographic footprint. Monitor TGA-EU MDR alignment timeline as inflection signal for parallel audit capability premiums.| Strategic Initiative | Industry Significance |
|---|---|
| TGA Software Validation Pathway | Compressed approval timelines favor manufacturers with lifecycle documentation capabilities under Therapeutic Goods Amendment regulations. |
| Hospital System Partnership | New South Wales Health Pathology centralized tenders require dedicated public sector account infrastructure and interoperability certification. |
| Wireless Platform Integration | Hybrid architectures layering sensors onto existing maternal-infant care platforms capture premium positioning in Melbourne and Sydney. |
| Regional Network Penetration | Queensland and Western Australia perinatal centers remain underpenetrated relative to southeastern state procurement concentration. |
| EU MDR Alignment Preparation | Anticipated TGA convergence with European technical documentation standards creates first-mover advantage for parallel audit capabilities. |
Study Parameters
Operator-level perspectives from biomedical engineers, hospital purchasing committee chairs, GPO contracts managers, and neonatal intensive care unit clinicians anchored the qualitative base for this analysis. Primary field engagement combined with secondary validation through TGA medical device registration databases, state health network procurement disclosure records, hospital capital expenditure filings, and ISO 13485 certification registries. Bottom-up equipment shipment analysis and top-down healthcare expenditure triangulation cross-verified segment-level estimates.
Sensitivity analysis around TGA approval timeline assumptions and wireless adoption curve slopes shaped the forecast framework across the projection horizon. Segmentation dimensions modeled include product type, end-user setting, technology architecture, and application with geographic procurement authority clusters. CAGRs derived from equipment replacement cycle analysis, public hospital capital budget trajectories, and technology diffusion parameters for connected prenatal devices. Forecast inputs incorporated maternity center consolidation patterns and software validation compliance rates.
Decision-makers should treat outputs as directional under base assumptions of sustained TGA framework acceleration and continued metropolitan perinatal center concentration; material deviation in regulatory harmonization timelines or state health network procurement centralization would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neonatal Care
Neonatal Monitoring Equipment Market
Neonatal Care
Global Neonatal Thermoregulation Market
Neonatal Care
North America Fetal and Neonatal Monitoring Market
Neonatal Care
India Neonatal and Prenatal Devices Market
Neonatal Care
Neonatal Ventilators Market
Neonatal Care
Neonatal and Prenatal Devices Market
Neonatal Care
Japan Neonatal and Prenatal Devices Market
Neonatal Care
Infant Resuscitators Market
Neonatal Care
Umbilical Market
Neonatal Care
Preterm Birth Prevention and Management Market
Neonatal Care
Europe Fetal and Neonatal Care Equipment Market
Neonatal Care
Neonatal Intensive Care Market
Neonatal Care
UAE Neonatal and Prenatal Devices Market
Neonatal Care
Neonatal Respiratory Distress Syndrome Treatment Market
Neonatal Care
Global NICU Catheter Market
Neonatal Care
Neonatal Phototherapy Devices Market